
 Rooftop Solar Photovoltaic (PV) Installation Market | 2026-2036
Rooftop Solar Photovoltaic (PV) Installation Market Size, Share, and Industry Trends Forecast 2026-2036
Rooftop Solar Photovoltaic (PV) Installation Market Intelligence
The integration of battery storage and energy management software into standard PV packages is fragmenting the traditional installer-centric service model. This fundamental shift creates new and complex competitive dynamics. Sunrun leverages its significant scale to offer integrated solar-plus-storage solutions as a service. PosiGen specializes in making solar and energy efficiency accessible to low-to-moderate-income families, while Trinity Solar sustains a strong regional presence through its direct sales force.
Rooftop solar photovoltaic installation involves mounting panels, which often use monocrystalline silicon with efficiencies above 20%, onto buildings for decentralized power generation. This process directly reduces grid dependency and lowers energy expenditures for the property owner. While the residential installation segment commands the highest volume of projects, commercial installations typically yield greater margins. Monocrystalline technology is the preferred choice, outperforming thin-film and amorphous silicon options in efficiency.
Regulatory frameworks are critical to market access and project viability. In the United States, federal incentives from the IRA combine with state-level net metering policies to stimulate residential adoption. The EU's Renewable Energy Directive and Australia's Clean Energy Council guidelines set crucial technical standards and installation protocols. Installers must therefore navigate a complex patchwork of local incentives and permitting requirements to sustain profitability.
Market Dynamics
The convergence of decentralized power generation, battery storage, and energy management software is the central structural force shaping the market. This integration transforms simple rooftop panel installations into sophisticated, dispatchable energy assets, fundamentally altering service models and competitive requirements for installers.
Growth Catalysts
- EU Green Deal Mandates:The European Union's Green Deal directly accelerates retrofits by promoting solar installations on existing commercial and public buildings to meet ambitious decarbonization targets, creating a substantial, policy-driven project pipeline.
- Favorable Net Metering Policies:Government incentives, particularly net metering schemes in Australian suburbs, provide direct financial returns for homeowners who export excess solar power to the grid, stimulating high-volume residential demand.
- Monocrystalline Silicon Efficiency:Continuous improvements in monocrystalline silicon cell technology, pushing panel efficiencies above 20%, enhance energy yield per square meter, making rooftop solar viable for a wider range of space-constrained properties.
Market Restraints
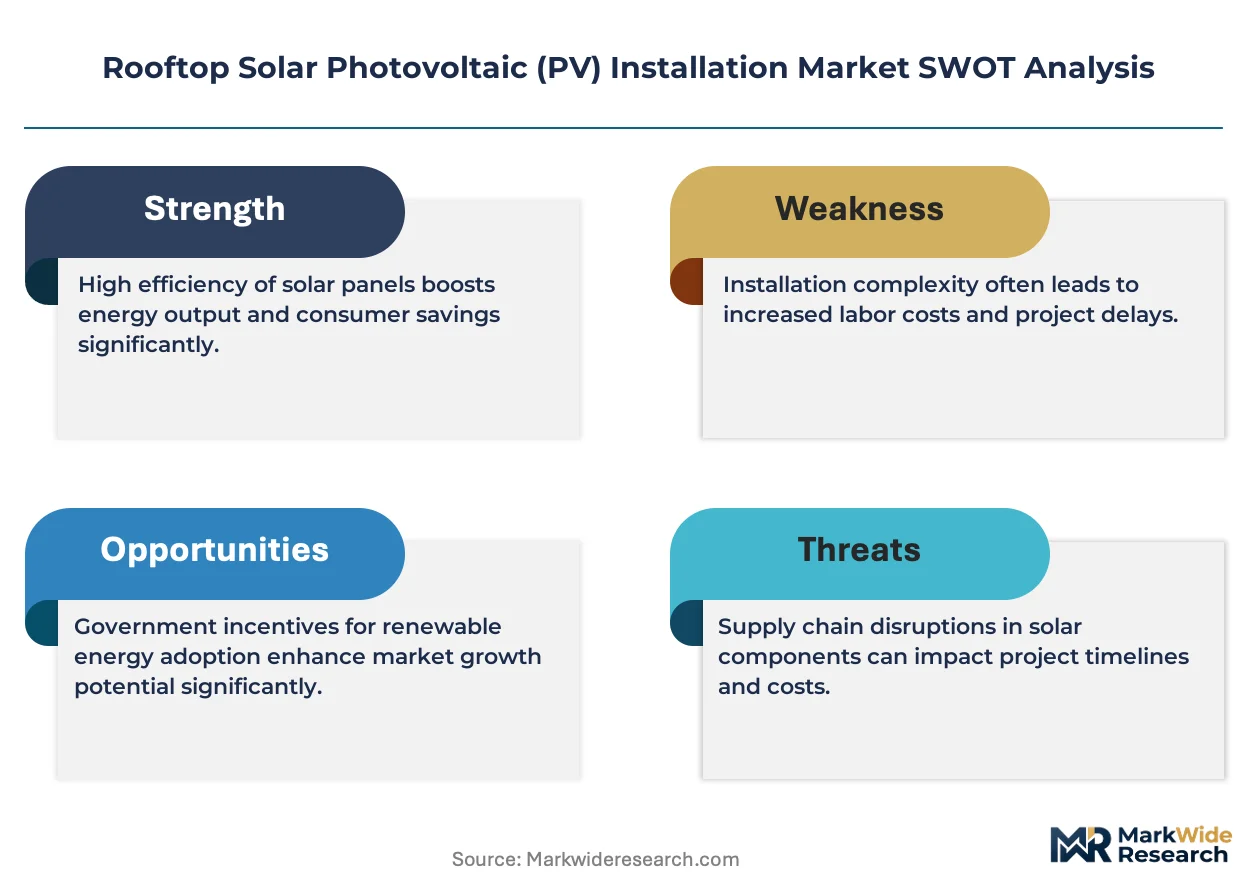
- Supply Chain Concentration:The industry's heavy reliance on a concentrated supply of high-purity polysilicon and monocrystalline wafers, primarily from China, creates significant vulnerability to geopolitical tensions and trade policy shifts.
- Grid Interconnection Bottlenecks:Local utility distribution networks often lack the capacity to handle high levels of intermittent solar generation, leading to lengthy and costly interconnection studies and project delays for new installations.
- Regulatory Patchwork Complexity:Installers face a fragmented landscape of local permitting rules, inspection protocols, and electrical codes that vary by municipality, increasing administrative overhead and hindering scalable, standardized operations.
Strategic Opportunities
- Integrated EV Charging Solutions:The convergence of residential solar with electric vehicle adoption creates an opportunity to bundle home EV chargers with PV and battery systems, offering a unified home energy solution.
- Commercial Sector in Southeast Asia:Underpenetrated commercial and industrial markets in countries like Vietnam and the Philippines present a major growth avenue, driven by high electricity prices and a need for reliable power.
- New Construction Mandates:The expansion of building codes that mandate solar installations on all new residential and commercial constructions, similar to policies in California, offers a predictable, long-term source of demand.
Industry Challenges
- Skilled Labor Shortages:A persistent shortage of electricians and technicians trained in both PV installation and the complex integration of battery storage systems constrains the capacity of installation companies to meet project demand.
- Navigating Technical Standards:Adhering to a diverse and evolving set of technical standards and certification protocols, such as IEC standards and specific national guidelines from bodies like Australia's Clean Energy Council, complicates system design.
- Legacy System Integration:Retrofitting older commercial buildings presents a significant challenge in integrating modern energy management software and PV systems with outdated electrical infrastructure and building management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rooftop Solar Photovoltaic (PV) Installation Market |
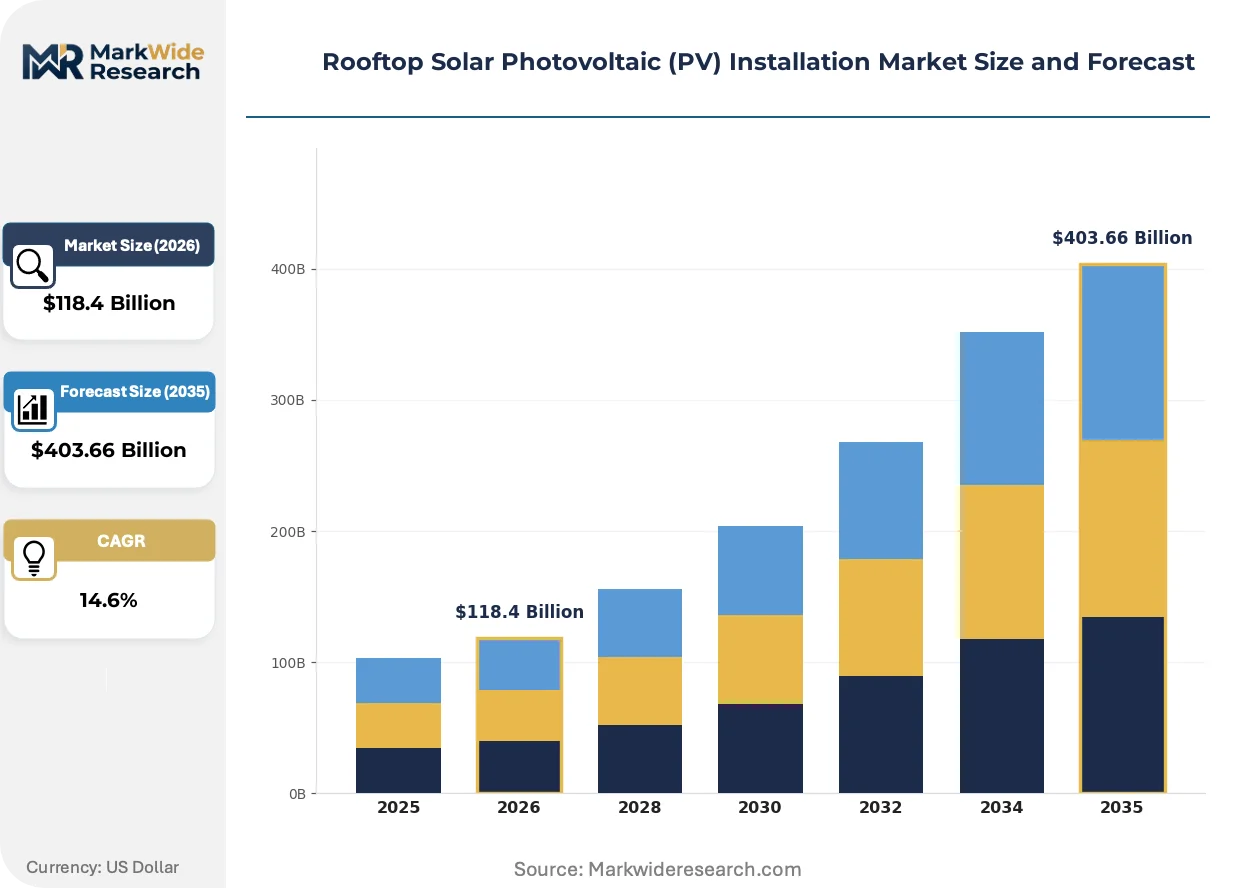
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $403.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Installation Type: Residential, Commercial, Institutional, Agricultural, Recreational Technology: Monocrystalline, Polycrystalline, Thin-Film, Bifacial, Amorphous Silicon End User: Property Owners, Facility Managers, Educational Institutions, Non-Profit Organizations, Hospitality Sector Distribution Channel: Direct Sales, Online Platforms, Retail Dealers, Energy Consultants, Project Developers |
| Companies Covered | Earthlight Technologies, Momentum, Sunrun, Solera Energy, PosiGen, Blue Raven Solar, SolGen Power, Palmetto Solar, Trinity Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rooftop Solar Photovoltaic (PV) Installation Market Strategic Shifts & Innovations
The evolution from standalone hardware sales to integrated service packages is redefining value in the rooftop solar sector. This shift prioritizes software-enabled energy optimization and long-term system management over the simple installation of panels, forcing a change in installer capabilities and business models.
Energy management software (EMS) provides real-time optimization of solar generation, battery storage, and grid interaction. Commercial and industrial property owners are the primary adopters, using EMS to minimize peak demand charges and manage complex energy loads. This software is digitizing the building energy profile, transforming passive solar installations into active, financially optimized assets that can interact intelligently with the grid.
The United States' Inflation Reduction Act (IRA) provides significant, long-term investment tax credits for both solar PV and co-located or standalone battery storage systems. This policy directly incentivizes the bundling of storage with solar from the point of sale. The residential segment is most affected, with installers increasingly positioning solar-plus-storage as the default offering to maximize customer value and system resilience.
A transition from outright equipment ownership to subscription-based service models is gaining traction among residential customers. This trend disrupts the traditional one-time installation sale, favoring service providers who offer solar-as-a-service or power purchase agreements (PPAs) with no upfront cost. This model is most advanced in the United States, where it significantly lowers the barrier to entry for many households.
Rooftop Solar Photovoltaic (PV) Installation Market Segmentation
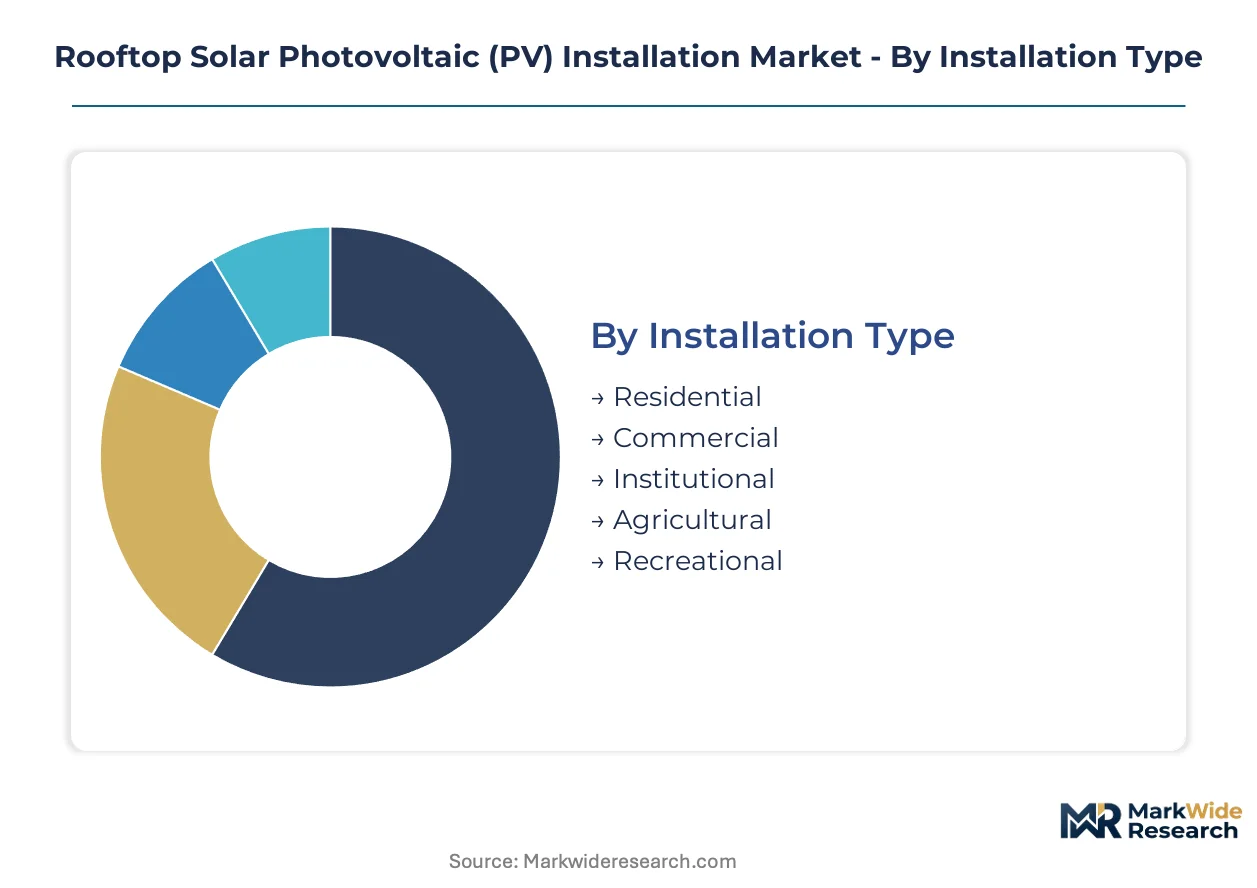
Understanding the distinct segments within the rooftop solar photovoltaic installation market clarifies diverse customer needs and technological preferences. This granular view reveals where specific demand drivers and regulatory incentives create concentrated opportunities for installers. Analyzing these segments helps stakeholders tailor offerings and optimize market penetration strategies across different user groups.
Installation Type:
The market for rooftop solar installations spans a broad use-case spectrum, from individual homes to large commercial facilities, each with unique requirements and economic drivers.
- Residential:Panels are mounted on single-family or multi-family residential buildings, primarily to reduce household electricity bills and enhance energy independence. Demand is particularly high in Australian suburbs, driven by favorable government net metering policies.
- Commercial:These larger-scale installations occur on business premises, often aimed at lowering long-term operational costs and achieving corporate sustainability goals. Strong demand exists within the European Union, propelled by ambitious decarbonization targets.
- Institutional:This segment includes public sector buildings such as schools, universities, and government facilities, often driven by public funding initiatives and mandates for sustainability.
- Agricultural:Solar arrays are deployed on farms for powering irrigation systems, barns, or cold storage, significantly reducing energy expenditures for agricultural operations.
- Recreational:Encompasses installations on leisure facilities like sports complexes, community centers, or campgrounds, improving energy self-sufficiency for these sites.
The dominant share belongs to Residential installations, while Commercial projects are closing the gap fastest due to increasing corporate focus on ESG metrics.
Technology:
Technology choices in rooftop solar are primarily driven by application needs, balancing efficiency, cost, and specific site constraints for optimal energy generation.
- Monocrystalline:This technology uses single-crystal silicon, delivering efficiencies above 20% and a uniform black appearance, making it a preferred choice. Demand is concentrated in space-constrained properties across residential and commercial sectors globally.
- Bifacial:Panels designed to capture sunlight from both their front and rear surfaces, significantly increasing overall energy yield under optimal conditions. Demand is gaining traction in commercial and utility-scale projects where ground reflection can be effectively utilized.
- Polycrystalline:Features multiple silicon crystals, offering a more cost-effective solution with slightly lower efficiency compared to monocrystalline panels.
- Thin-Film:Utilizes thin layers of photovoltaic material, suitable for flexible applications and lightweight installations, though generally less efficient than crystalline silicon.
- Amorphous Silicon:A specific type of thin-film technology, recognized for its performance in low-light conditions but typically exhibiting lower power conversion efficiencies.
Monocrystalline technology holds the largest market share, with bifacial panels demonstrating the steepest expansion trajectory.
End User:
The end-user segmentation highlights distinct customer types, each motivated by specific economic incentives, operational requirements, or environmental objectives when adopting rooftop solar.
- Property Owners:These are individuals or entities directly owning the building where the PV system is installed, seeking to reduce utility bills and increase property value. Residential property owners in the United States are driven by IRA incentives and state-level net metering.
- Facility Managers:Professionals responsible for the operational upkeep and energy efficiency of commercial or institutional buildings, focusing on long-term cost savings and energy reliability. Commercial property owners prioritize operational cost reduction through PV integration into their energy management plans.
- Educational Institutions:Schools and universities install solar to lower utility costs, align with sustainability goals, and provide practical educational examples for students.
- Non-Profit Organizations:Adopting solar solutions to decrease operational expenses and support their environmental missions, often leveraging specific grants and tax benefits.
- Hospitality Sector:Hotels and resorts invest in solar to reduce high energy bills and enhance their brand image by demonstrating a commitment to environmental sustainability.
Property Owners represent the largest segment, with Facility Managers increasingly influencing large-scale deployments.
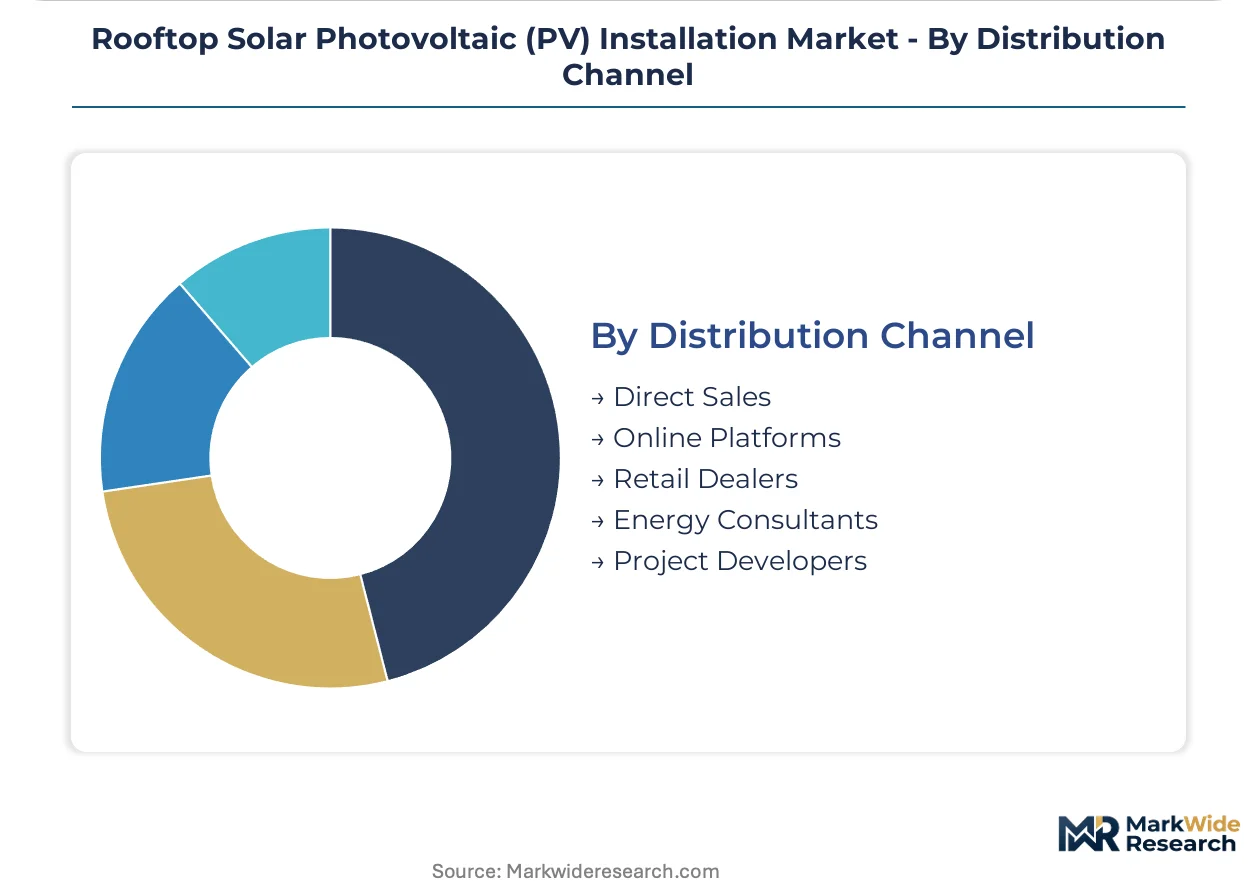
Distribution Channel:
The volume of rooftop solar installations flows through various distribution channels, each optimized to reach specific customer segments and manage project complexities.
- Direct Sales:Installers or manufacturers directly engage with end-users, managing the entire sales, design, and installation process without intermediaries. Trinity Solar sustains a strong regional presence in the United States through its direct sales force.
- Project Developers:Companies that manage the entire solar project lifecycle from initial concept to final commissioning, often for larger commercial or institutional clients. They navigate complex regulatory frameworks and secure financing for significant installations.
- Online Platforms:Digital marketplaces connecting potential customers with solar providers, streamlining the initial inquiry, quotation, and comparison phases of the buying process.
- Retail Dealers:Stores or franchises offering solar solutions alongside other home improvement products, providing localized access and bundled services for residential customers.
- Energy Consultants:Offer specialized advisory services on energy efficiency and solar integration, guiding clients through system selection, financial incentives, and regulatory compliance.
Direct Sales remains a primary channel for customer engagement, while Project Developers drive significant market volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's concentrated supply of high-purity polysilicon and monocrystalline wafers underpins global rooftop solar photovoltaic installation markets. This critical supply chain dynamic influences project viability and cost structures across major consumer regions. Installers worldwide depend on these foundational components for system deployment.
United States
Residential property owners in the United States are driven by the Inflation Reduction Act's long-term investment tax credits. These federal incentives combine with state-level net metering policies to stimulate widespread residential adoption. California's building codes mandate solar installations on all new constructions, ensuring predictable long-term demand.
Germany
Germany's rooftop solar market benefits significantly from the European Union's Green Deal mandates. These policies accelerate retrofits on existing commercial and public buildings to meet ambitious decarbonization targets. Bavaria, a leading state, shows high solar adoption rates, supported by strong regional sustainability initiatives.
Australia
Australian suburbs exhibit high demand for residential rooftop solar installations, stimulated by favorable government net metering policies. These policies provide direct financial returns for homeowners exporting excess power to the grid. The Clean Energy Council guidelines set crucial technical standards for installations across major cities like Sydney and Melbourne.
India
India's commercial and industrial sectors present a major growth avenue for rooftop solar, driven by high electricity prices and energy reliability needs. State-level solar policies and the national PLI scheme encourage domestic manufacturing and deployment. Gujarat is emerging as a significant hub for solar projects and manufacturing facilities.
Vietnam
Vietnam's underpenetrated commercial and industrial markets offer substantial opportunities for rooftop PV, propelled by rising electricity costs. Past Feed-in Tariff policies initially spurred market interest, and current regulations continue to support solar development. Ho Chi Minh City's industrial zones are increasingly adopting solar to manage operational expenditures.
Rooftop Solar Photovoltaic (PV) Installation Market Key Industry Players
Channel-controlling players compete with product-specialist players in the rooftop solar PV installation market, creating complex competitive dynamics. The market structure exhibits a blend of large-scale integrated service providers and numerous regional specialists. Strategic archetypes include full-service installers offering integrated solar-plus-storage, technology integrators focused on software optimization, and localized direct sales networks. Companies frequently pursue geographic expansion or strategic partnerships to broaden their service offerings and market reach.
Within the integrated service provider segment, Sunrun leverages its significant scale to offer integrated solar-plus-storage solutions as a service, addressing diverse customer needs. PosiGen exemplifies a specialist approach, making solar and energy efficiency accessible to low-to-moderate-income families through targeted programs and financial models. Trinity Solar sustains a strong regional presence through its direct sales force, anchoring its operations in specific geographical markets and building customer loyalty. These companies represent distinct strategic models for market penetration and customer engagement within the competitive landscape.
| Leading Market Players |
|---|
| Earthlight Technologies |
| Momentum |
| Sunrun |
| Solera Energy |
| PosiGen |
| Blue Raven Solar |
| SolGen Power |
| Palmetto Solar |
| Trinity Solar |
| Others |
Cost & Logistics Intelligence
Geopolitical tensions and trade policy shifts stemming from China's polysilicon supply concentration determine both pricing tier spreads and the global rooftop solar supply chain shape. This reliance introduces significant market volatility.
Pricing Analysis
The pricing gap between high-efficiency monocrystalline panels and older polycrystalline or thin-film technologies influences installer margins. Project-based pricing dominates for commercial installations, while residential customers increasingly adopt subscription-based solar-as-a-service models. Price differentiation stems from panel efficiency and integrated battery storage solutions. Pricing pressure stems from intense competition among installers and falling hardware costs. Residential customers in regions with strong net metering are generally less price-sensitive than commercial buyers focused on long-term operational cost reduction.
Supply Chain Analysis
Single-source vulnerability in high-purity polysilicon and monocrystalline wafers, primarily from China, underpins the global rooftop solar supply chain. Key dependencies include silicon ingots, cells, and inverters. Geopolitical tensions and trade policies introduce significant structural risk. Distribution runs through a fragmented network of direct sales forces and project developers, particularly in residential and commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rooftop solar PV installation market represents a high-growth disruption, driven by the integration of battery storage and energy management software. This technological inflection transforms passive generation into sophisticated energy assets.
For Market Incumbents: Harden integrated service offerings by bundling PV, battery storage, and EV charging solutions to counter margin pressure from new entrants. Consolidate regional market share through strategic acquisitions of smaller installers, leveraging scale for procurement efficiencies. The threat of commoditization requires a focus on value-added services and long-term customer relationships. Invest in advanced energy management software development as a key lever for differentiation.
For New Entrants and Emerging Players: Establish a beachhead in underpenetrated commercial markets in Southeast Asia, particularly Vietnam, where high electricity prices drive demand. Target the agricultural segment by offering specialized solar solutions for irrigation and cold storage, addressing specific energy expenditure pain points. Focus on subscription-based models and power purchase agreements to lower upfront costs for price-sensitive customers. This go-to-market angle reduces barriers to adoption.
For Investors and Strategic Acquirers: The EU Green Deal mandates and the US Inflation Reduction Act reshape the acquisition landscape, ensuring long-term market viability over the next decade. Target vertically integrated installers with strong regional presences and proprietary energy management software capabilities. These firms offer sticky customer bases and recurring revenue streams. The signal to watch is the increasing rate of new construction mandates for solar installations, which guarantees predictable demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Integrated EV Charging Solutions | Bundles home energy services with electric vehicle adoption, enhancing customer value. |
| Target Commercial Sector in Southeast Asia | Captures growth in high-electricity-price markets with significant unmet demand. |
| Develop Advanced Energy Management Software | Optimizes system performance and grid interaction, differentiating service offerings. |
| Acquire Regional Direct Sales Networks | Strengthens customer acquisition channels and local market penetration. |
| Invest in Skilled Labor Training Programs | Addresses critical shortages of PV and battery integration technicians, scaling capacity. |
Research Approach
Findings reconcile primary fieldwork against secondary review of government renewable energy reports, industry association publications, and company financial disclosures. This approach involved extensive interviews with PV installation executives, energy management software developers, utility grid operators, and policy advisors. Bottom-up data collection from regional markets was triangulated with top-down market sizing for comprehensive validation.
Forecast inputs considered market growth catalysts, regulatory frameworks, and technological advancements across the analysis window. Segmentation dimensions modeled include installation type, technology, end-user, and distribution channel, along with regional policy impacts. Compound Annual Growth Rates were derived from historical trends and projected future demand. Panel efficiency improvements and battery storage integration rates served as key industry-specific forecast inputs.
Sensitivities concentrate around shifts in government incentive programs and the cost trajectory of raw materials like polysilicon. Forecasts reflect assumptions regarding current policy stability and supply chain resilience. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Residential Solar Inverter Market
Solar Power Systems
Denmark Solar Energy Market
Solar Power Systems
Mexico Rooftop Solar Market
Solar Power Systems
Spain Rooftop Solar Market
Solar Power Systems
Full-Cell Solar Module Market
Solar Power Systems
Venezuela Solar Energy Market
Solar Power Systems
Residential Solar Panels Market
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
Residential Solar Market
Solar Power Systems
South Korea Solar Energy Market
Solar Power Systems
Building Applied Photovoltaics (BAPV) Market
Solar Power Systems
Solar Shingles Market
Solar Power Systems
United Kingdom Distributed Solar Power Generation Market
Solar Power Systems
GCC Solar Photovoltaic (PV) Market
Solar Power Systems
Residential Solar Energy Market
Solar Power Systems
US Solar PV Market