
 Solar Cell (Photovoltaic) Module Market | 2026-2036
Solar Cell (Photovoltaic) Module Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Cell (Photovoltaic) Module Market Insights
A shift from outsourced cell sourcing to in-house wafer-to-module production is restructuring supply economics for tier-one manufacturers. LONGi Solar anchors its cost position through captive polysilicon and ingot capacity. JinkoSolar competes by extending vertically into n-type TOPCon cell lines across Southeast Asian plants. First Solar differentiates with thin-film CdTe technology that sidesteps silicon supply volatility entirely.
A solar cell (photovoltaic) module is an interconnected assembly of photovoltaic cells laminated between weatherproof encapsulant layers and framed for mechanical mounting, typically achieving conversion efficiencies from eighteen to twenty-three percent in commercial crystalline products. Its primary purpose is to convert incident solar irradiance into direct-current electricity for integration with inverters, batteries, or grid infrastructure. Monocrystalline modules command premium pricing in residential and commercial rooftop segments where space constraints prioritize watt-per-square-meter performance. Thin-film alternatives sustain niche positions in utility-scale desert installations where temperature coefficients and shading tolerance outweigh efficiency metrics. Bifacial architectures capture growing share in ground-mounted utility projects that exploit albedo reflection from sand, snow, or white gravel surfaces.
China's MIIT enforces updated GB standards for module efficiency and degradation rates that filter subscale domestic producers from state-backed project tenders. India's BIS certification mandate for imported solar modules, paired with the PLI scheme for domestic manufacturing, is redirecting supply chain investments toward Gujarat and Tamil Nadu production corridors. The EU Green Deal and F-Gas Regulation are accelerating module recycling requirements and restricting fluorinated greenhouse gas use in manufacturing processes. Stakeholders must monitor how carbon border adjustment mechanisms and evolving local content rules reshape procurement geography and technology selection.
Market Dynamics
The solar cell module market is experiencing a fundamental restructuring as n-type TOPCon cell technology accelerates its capture of production capacity from legacy p-type PERC lines, compressing capital recovery timelines for manufacturers who delayed technology transitions.
Growth Catalysts
- India's PLI Manufacturing Incentives:Production-linked incentive schemes for domestic cell and module manufacturing are redirecting capital toward Gujarat and Tamil Nadu production corridors, reducing import dependency for utility-scale developers.
- EU F-Gas Regulation Phase-Down:Restrictions on fluorinated greenhouse gases in manufacturing processes are accelerating adoption of fluorine-free encapsulant materials and alternative lamination chemistries across European supply chains.
- Bifacial Module Architecture:Ground-mounted utility projects exploiting albedo reflection from sand, snow, and gravel surfaces are driving procurement specifications toward double-glass framed designs with enhanced rear-side sensitivity.
Market Restraints
- Polysilicon Supply Concentration:Overwhelming concentration of metallurgical-grade silicon purification and polysilicon production in Xinjiang and Inner Mongolia creates geopolitical exposure and forced labor scrutiny risks for module buyers.
- Silver Paste Input Costs:Cell metallization relies on silver paste formulations that track precious metal spot markets, exposing margin structures to commodity volatility that alternative copper-plated approaches have not yet scaled to offset.
- Grid Interconnection Queues:Utility-scale project completion rates face structural delays from transmission upgrade backlogs and interconnection study timelines that extend 24-48 months in key US markets.
Strategic Opportunities
- Agricultural Feeder Separation in India:State-level programs separating agricultural electricity loads from general grids are creating dedicated procurement channels for solar-powered irrigation and rural electrification modules.
- Building-Integrated Photovoltaics:Architectural integration of thin-film and crystalline modules into facades, skylights, and roofing materials opens premium segments where aesthetic and structural performance outweigh efficiency metrics.
- EU Carbon Border Adjustment Mechanism:Embedded carbon accounting for imported modules creates competitive openings for manufacturers with verified low-carbon production footprints and transparent supply chain documentation.
Industry Challenges
- TOPCon Process Engineering Talent:The shift from PERC to tunnel oxide passivated contact cell architectures demands specialized expertise in atomic layer deposition and boron diffusion that remains scarce outside established R&D centers.
- BIS Certification Timelines:India's mandatory Bureau of Indian Standards testing for imported modules creates 12-16 week approval backlogs that disrupt project commissioning schedules for developers with fixed offtake deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Cell (Photovoltaic) Module Market |
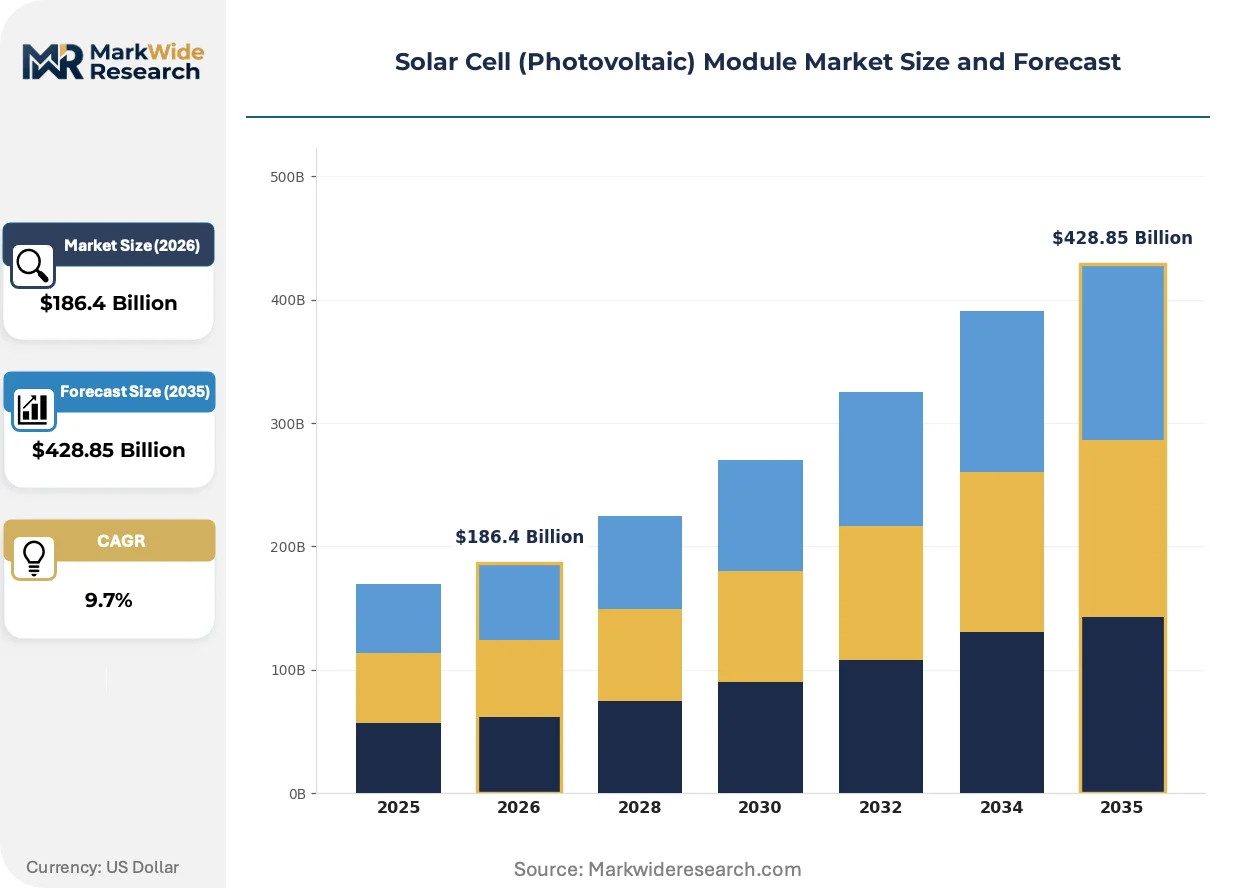
| Market Size in 2026 | $186.4 Billion |
| Market Size in 2035 | $428.85 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Bifacial, Thin-Film Technology: Crystalline Silicon, Cadmium Telluride, CIGS, Organic Photovoltaics End User: Residential, Commercial, Industrial, Utility Scale Installation: Grid-Connected, Off-Grid, Building-Integrated, Ground-Mounted |
| Companies Covered | Trina Solar, JA Solar, LONGi Solar, JinkoSolar, Canadian Solar, First Solar, Hanwha Qcells, Risen Energy, DMEGC Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Cell (Photovoltaic) Module Market Trends and Innovations
N-type cell architectures and heterojunction designs are actively displacing incumbent technologies across manufacturing investment decisions, while regulatory pressure on supply chain transparency and end-of-life recovery is rewriting procurement specifications.
Heterojunction cell technology combines intrinsic thin-layer amorphous silicon deposition with crystalline silicon wafers to achieve superior temperature coefficients and bifaciality ratios. Residential and commercial rooftop installers in Japan and premium European markets are specifying heterojunction modules despite 15-20% cost premiums. This technology is overtaking conventional PERC in new capacity announcements as equipment suppliers report order backlogs stretching through 2026.
China's MIIT has enforced updated GB standards for module efficiency thresholds and annual degradation rate guarantees that filter subscale domestic producers from state-backed tender participation. Manufacturers without in-house cell production or certified testing laboratories face exclusion from centralized procurement auctions. Tier-one producers with captive polysilicon and integrated wafer-to-module operations are consolidating market access as smaller competitors absorb compliance costs.
Utility developers are consolidating module procurement through multi-gigawatt framework agreements that bypass traditional distributor channels and secure multi-year delivery schedules. This direct contracting concentrates volume with vertically integrated manufacturers capable of bankable production guarantees. The pattern is most visible in Middle Eastern markets where sovereign wealth-backed project vehicles negotiate decade-long supply partnerships with Chinese producers.
Solar Cell (Photovoltaic) Module Market Segmentation
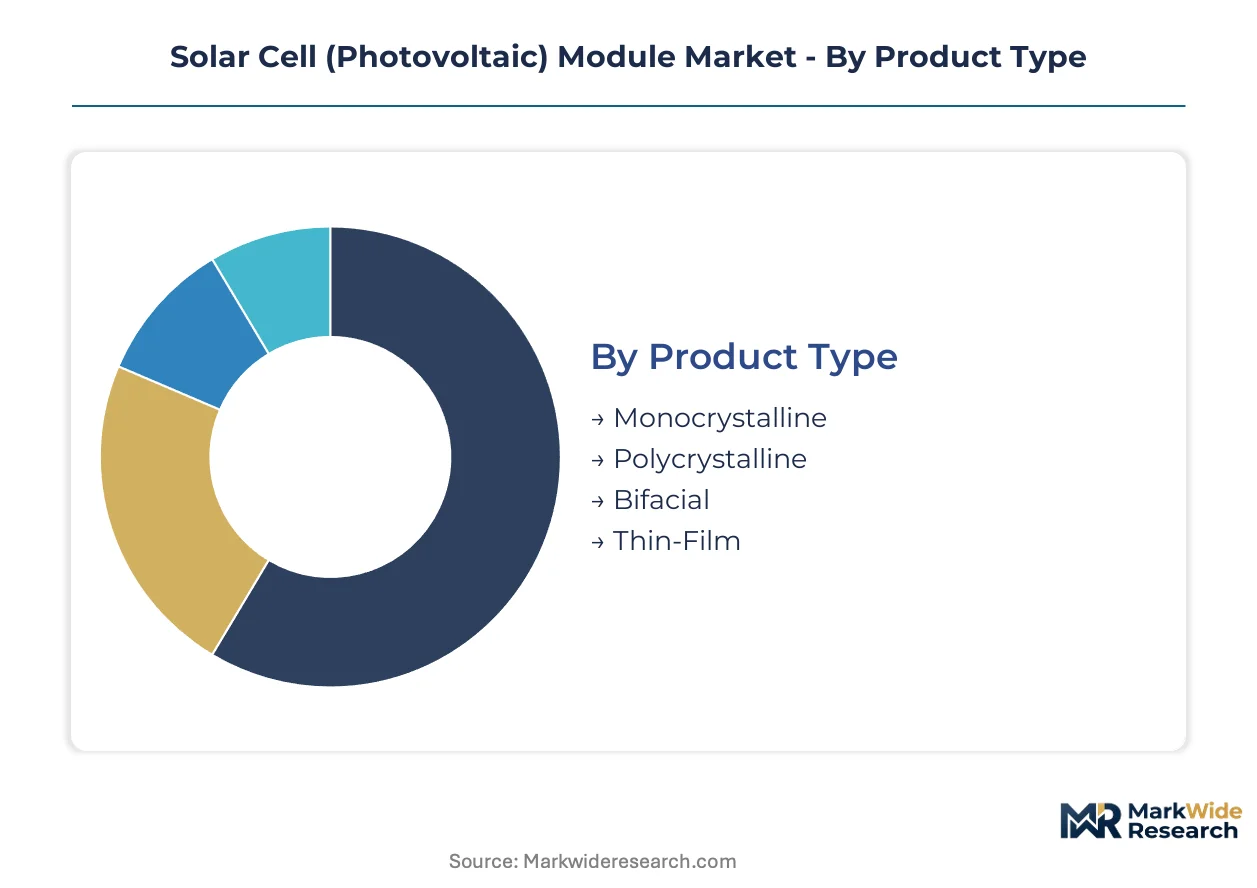
Module segmentation reveals how technology choices lock manufacturers into divergent cost structures and customer relationships. Each category channels capital toward distinct equipment suppliers, certification requirements, and margin profiles that resist easy migration.
Product Type:
Supply concentration in wafer and cell production tilts competitive advantage toward manufacturers with captive upstream capacity.
- Monocrystalline:Single-crystal silicon ingots sliced into wafers deliver the highest commercial conversion efficiencies, typically reaching twenty-one to twenty-three percent. Residential rooftop installers in Germany and Japan specify monocrystalline modules where roof area constraints maximize kilowatt-hour yield per square meter. Premium pricing reflects silicon purity requirements and slower crystal growth rates.
- Bifacial:Double-sided cell architectures capture direct irradiance plus reflected light from ground surfaces, boosting effective output fifteen to thirty percent in high-albedo environments. Utility-scale developers in Saudi Arabia and Chile specify bifacial glass-glass designs for desert installations where sand reflectance amplifies rear-side generation. Procurement contracts increasingly mandate bifacial compatibility for new ground-mounted projects.
- Polycrystalline:Multi-crystal silicon blocks offer lower manufacturing costs at modest efficiency penalties, sustaining presence in price-sensitive distributed generation markets. China's MIIT efficiency thresholds are squeezing polycrystalline share in state-backed tenders.
- Thin-Film:Semiconductor deposition on glass or flexible substrates bypasses silicon supply chains entirely, occupying niche applications where weight and temperature tolerance outweigh efficiency metrics. First Solar's CdTe technology dominates this segment.
Today's leader: Monocrystalline. Tomorrow's challenger: Bifacial.
Technology:
Cost tier separation between established and emerging cell architectures is widening as equipment depreciation schedules lock in technology choices.
- Crystalline Silicon:Dominant commercial technology leveraging decades of process optimization across ingot pulling, wafer slicing, and cell fabrication. PERC lines face accelerated obsolescence as TOPCon and heterojunction capacity expands.
- Cadmium Telluride:Vapor-deposited thin-film technology achieving competitive efficiencies without silicon feedstock exposure. First Solar's vertical manufacturing model insulates against polysilicon price volatility.
- CIGS:Copper-indium-gallium-selenide absorber layers enable flexible substrate applications and building integration where rigid glass modules prove impractical. Manufacturing complexity has limited scale relative to CdTe.
- Organic Photovoltaics:Solution-processed polymer and small-molecule active layers promise ultra-low manufacturing costs and tunable optical properties. Efficiency and stability gaps constrain commercial deployment to experimental building-integrated pilots.
Crystalline silicon commands current volume. Thin-film alternatives carve defensible niches.
End User:
Application-driven specification divergence creates distinct procurement channels with incompatible qualification requirements.
- Utility Scale:Centralized solar parks exceeding fifty megawatts dominate module procurement volume, negotiating multi-gigawatt framework agreements directly with tier-one manufacturers. Saudi Arabia's sovereign wealth-backed project vehicles exemplify this consolidation.
- Residential:Distributed rooftop systems under twenty kilowatts prioritize aesthetic integration, warranty terms, and installer network availability over absolute cost per watt. Japanese households specify heterojunction modules despite substantial premiums.
- Commercial:Mid-scale rooftop and carport installations balance space constraints against energy cost reduction targets, often financing through power purchase agreements.
- Industrial:On-site generation for manufacturing facilities emphasizes reliability and peak demand charge reduction, with procurement decisions integrating into broader energy management strategies.
Utility scale absorbs manufacturing scale. Residential captures margin.
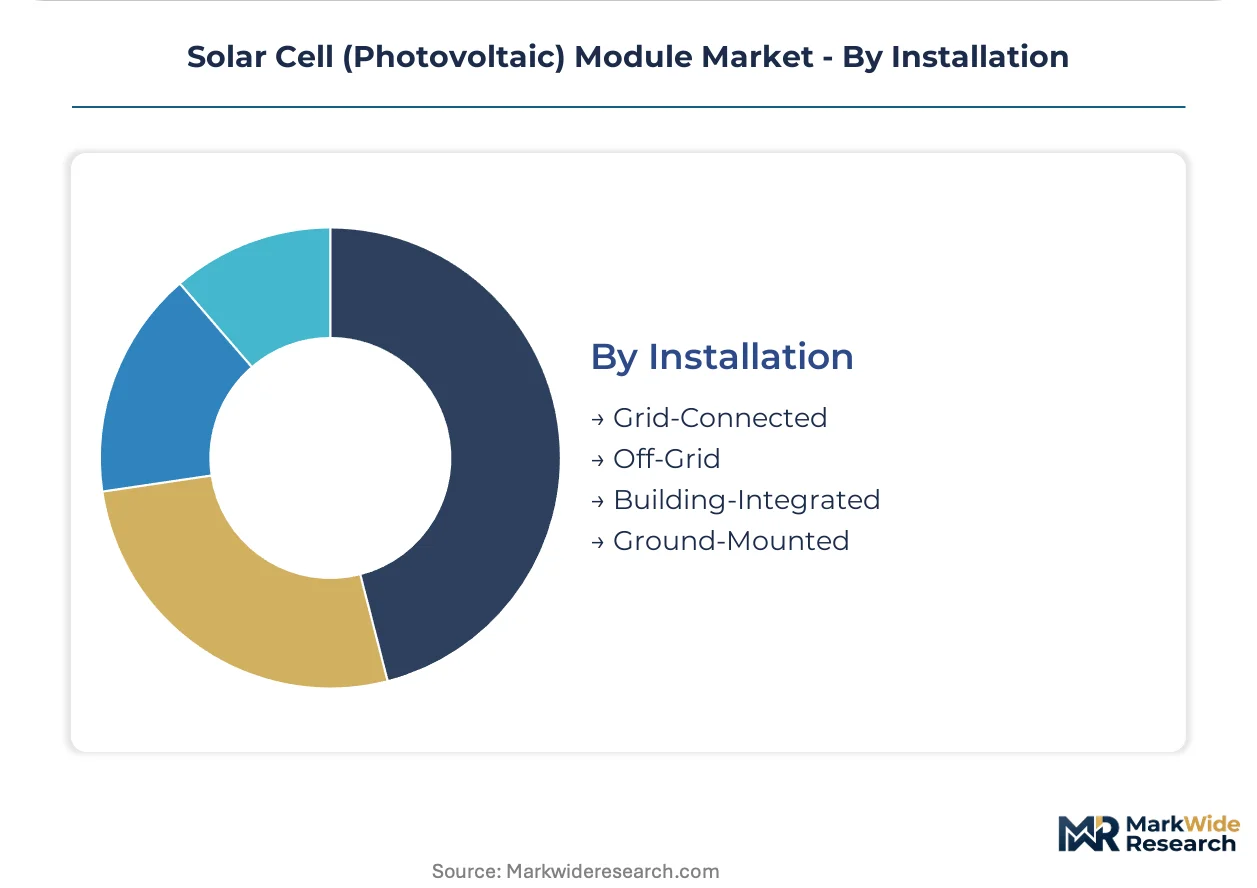
Installation:
Customer type differentiation between grid-dependent and autonomous systems shapes inverter pairing and storage attachment rates.
- Grid-Connected:Systems exporting surplus generation to utility networks constitute the overwhelming majority of installed capacity. India's agricultural feeder separation programs are expanding grid-connected solar irrigation clusters.
- Ground-Mounted:Terrestrial racking systems optimize tilt angles and tracking mechanisms for maximum energy harvest, standard configuration for utility-scale deployment.
- Building-Integrated:Photovoltaic elements replacing conventional construction materials—facade cladding, skylights, roofing membranes—trade efficiency for architectural function. European Green Deal building codes are accelerating specification.
- Off-Grid:Standalone systems with battery storage serve remote locations beyond transmission infrastructure, common in rural electrification and telecommunications applications.
Grid-connected ground-mounted systems anchor volume. Building-integrated segments expand the addressable surface area.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xinjiang and Inner Mongolia anchor global polysilicon purification capacity, concentrating upstream supply in Chinese industrial corridors before module assembly disperses to coastal export zones. India's manufacturing incentives and the EU's carbon border mechanism are redirecting investment flows toward Gujarat, Tamil Nadu, and European low-carbon production clusters.
China
Utility-scale developers in Qinghai and Gansu provinces are accelerating procurement of high-efficiency bifacial modules for desert solar parks. MIIT enforces updated GB standards for module efficiency thresholds that filter subscale producers from state-backed tenders. Xinjiang's polysilicon corridor supplies ingot capacity to LONGi Solar's integrated wafer-to-module operations in Xi'an and Zhejiang.
India
Agricultural feeder separation programs in Maharashtra and Rajasthan are expanding module offtake for solar-powered irrigation clusters. BIS certification mandates for imported modules create 12-16 week approval backlogs that disrupt project commissioning schedules. The PLI scheme redirects capital toward Gujarat and Tamil Nadu production corridors, reducing import dependency for domestic developers.
United States
Utility-scale project completion rates face structural delays from transmission upgrade backlogs and interconnection study timelines extending 24-48 months in ERCOT and PJM markets. FERC grid interconnection reforms aim to accelerate queue processing for solar developers. Ohio hosts First Solar's thin-film CdTe manufacturing that sidesteps silicon supply volatility entirely.
Germany
Residential rooftop installers specify heterojunction modules despite 15-20% cost premiums, prioritizing space-constrained kilowatt-hour yield per square meter. The EU F-Gas Regulation restricts fluorinated greenhouse gases in manufacturing processes, accelerating adoption of fluorine-free encapsulant materials. Saxony-Anhalt hosts emerging module recycling facilities responding to EU Green Deal end-of-life requirements.
Saudi Arabia
Sovereign wealth-backed project vehicles negotiate decade-long supply partnerships directly with tier-one Chinese producers, bypassing traditional distributor channels. The kingdom's renewable energy procurement authority mandates bifacial compatibility for new ground-mounted projects exploiting desert albedo reflection. NEOM's northwest industrial zone anchors gigawatt-scale solar park development with integrated manufacturing zones.
Solar Cell (Photovoltaic) Module Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue building-integrated and agricultural applications where aesthetic and structural performance outweigh efficiency metrics. The market consolidates around vertically integrated manufacturers with captive polysilicon and certified testing laboratories, while subscale competitors absorb compliance costs from tightening efficiency standards. Three archetypes dominate: silicon-integrated giants controlling wafer-to-module production, thin-film specialists bypassing silicon supply chains, and regional assemblers serving protected domestic markets. Capacity expansion and strategic partnerships represent the dominant competitive moves, with manufacturers securing multi-year delivery schedules through direct utility contracting.
Among Chinese-integrated producers, Trina Solar, JA Solar, and LONGi Solar exemplify the silicon-dominant archetype through in-house control of upstream material flows. First Solar occupies a distinct position as a thin-film CdTe specialist with manufacturing insulated from polysilicon price volatility. These four names anchor the competitive structure without exhausting the participant base, as regional specialists in India and Southeast Asia capture protected procurement channels under local content requirements.
| Leading Market Players |
|---|
| Trina Solar |
| JA Solar |
| LONGi Solar |
| JinkoSolar |
| Canadian Solar |
| First Solar |
| Hanwha Qcells |
| Risen Energy |
| DMEGC Solar |
| Others |
Pricing and Supply Chain Analysis
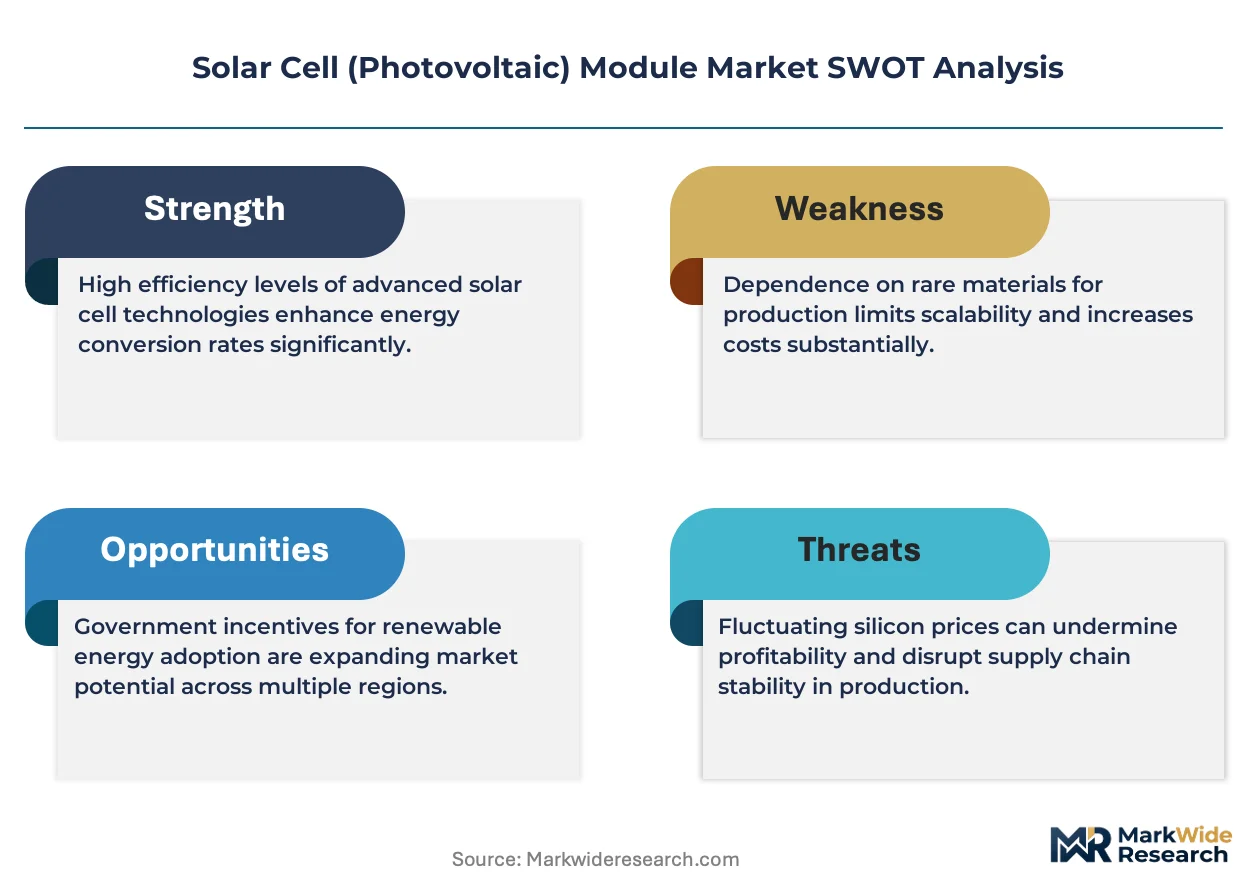
Silver paste metallization formulations track London Metal Exchange spot markets, passing commodity volatility through cell fabrication costs into module pricing tiers before reaching utility-scale developers with multi-gigawatt offtake contracts.
Pricing Analysis
Input-cost pass-through from polysilicon purification and silver paste metallization drives three-tier pricing structure across premium, standard, and economy levels. Premium tiers attach to heterojunction and n-type TOPCon modules with certified low-degradation rates, while standard crystalline products compete on per-watt metrics. Cost compression in economy tiers is intensifying because China's MIIT efficiency thresholds filter subscale producers from state-backed tenders. Utility-scale developers exhibit lowest price sensitivity due to decade-long supply partnerships, whereas distributed residential installers face acute pressure from financing cost fluctuations.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Dubai coordinate hub-and-spoke patterns for module delivery to project sites across Europe, Southeast Asia, and the Middle East. Manufacturing gravity centers on China's Xinjiang and Inner Mongolia polysilicon corridors, with cell and module assembly dispersing to coastal export zones in Jiangsu and Zhejiang. The chain draws from metallurgical-grade silicon, silver paste formulations, and aluminum framing extrusions. Single-source vulnerability concentrates in Xinjiang polysilicon purification exposed to forced labor scrutiny and tariff exposure. Distribution runs through direct manufacturer-to-developer contracting that bypasses traditional wholesaler channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar cell module market functions as a regulatory compounder where India's PLI manufacturing incentives and the EU's carbon border adjustment mechanism are accelerating capital redirection toward compliant production corridors.
For Market Incumbents: Hedge against silver paste cost volatility by accelerating copper-plated metallization R&D partnerships with equipment suppliers. Defend margin position through captive polysilicon capacity in low-carbon production zones, insulating against carbon border accounting penalties that threaten import-dependent competitors.
For New Entrants and Emerging Players: Agricultural irrigation cooperatives in Maharashtra and Rajasthan represent an underserved buyer archetype with dedicated procurement channels under feeder separation programs. Capture this white-space through modular DC solar pumping systems bundled with maintenance service contracts, bypassing grid-interconnection queues that stall utility-scale entrants.
For Investors and Strategic Acquirers: Consolidation pressure builds where BIS certification backlogs and MIIT efficiency thresholds filter subscale competitors from state-backed tenders. Long-term viability favors manufacturers with integrated wafer-to-module operations and verified low-carbon footprints. Watch for inflection when carbon border adjustment mechanisms trigger procurement specification rewrites in European markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Captive Xinjiang-alternative purification capacity insulates against carbon border penalties and forced labor scrutiny. |
| n-type TOPCon Capacity Buildout | Equipment order backlogs through 2026 lock in technology transition ahead of PERC obsolescence. |
| Bifacial Glass-Glass Certification | NEOM and Saudi sovereign procurement mandates bifacial compatibility for desert albedo exploitation. |
| Fluorine-Free Encapsulant Transition | EU F-Gas Regulation phase-down accelerates alternative lamination chemistry adoption across European supply chains. |
| Direct Utility Framework Agreements | Multi-gigawatt decade-long contracts with Middle Eastern project vehicles bypass distributor margin capture. |
Research Methodology
Multiple input streams — executive interviews with tier-one manufacturer strategy heads, primary fieldwork with EPC contractors and utility planning officers, and secondary validation against customs records and FERC interconnection filings — were reconciled through bottom-up and top-down triangulation. Stakeholder roles spanned IPP project developers, grid operators, and module procurement leads at sovereign wealth-backed vehicles. Secondary sources included IEA deployment databases, MIIT GB standard documentation, and BIS certification registries.
Historical capacity expansion patterns were cross-referenced against panel input from equipment suppliers and polysilicon procurement leads. The analytical framework modeled segmentation across cell architecture type, module format, end-use application, and regional regulatory cluster throughout the forecast period. CAGRs were derived from installed capacity buildout trajectories and average selling price compression curves. Industry-specific inputs incorporated silver paste spot price volatility and interconnection queue duration data from ERCOT and PJM markets.
Underlying measurement precision varies by segment; utility-scale procurement channels carry tighter precision than distributed residential estimates due to disclosure requirements in framework agreements. Forecasts reflect documented assumptions around technology transition timelines and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Organic PV Solar Cells Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
Solar Concentrator Market
Solar Power Systems
Global Solar Microinverter Market
Solar Power Systems
Solar Photovoltaic Material Market
Solar Power Systems
Middle East and Africa Solar PV Inverters Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
Venezuela Solar Energy Market
Solar Power Systems
Solar PV Backsheet Market
Solar Power Systems
Distributed Solar Energy Market
Solar Power Systems
Mexico Rooftop Solar Market
Solar Power Systems
Germany Solar Energy Market
Solar Power Systems
Global Ultra Efficient Solar Power Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Skylights Market
Solar Power Systems
Saudi Arabia Solar Energy Market