
 Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market | 2026-2036
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market Foresight
REACH compliance obligations for imported chemical formulations is realigning the cost-of-entry calculus for non-European suppliers serving North African markets. Henkel AG & Co. KGaA leverages its regional formulation centers to sustain localized production advantages across Egypt and Morocco. 3M Company anchors its position through deep channel control in UAE's industrial distribution networks. Avery Dennison Corporation competes on specialty labeling substrates designed for Gulf-state climate extremes.
Pressure sensitive adhesives are viscoelastic materials that bond to surfaces upon light pressure without solvent activation or heat curing, typically formulated with tackifying resins, plasticizers, and elastomer backbones in acrylic, rubber, or silicone chemistries. Their primary commercial purpose is to enable reversible or permanent joining across packaging, automotive, electronics, and construction applications where process speed and substrate versatility outweigh mechanical fastening. Acrylic-based formulations dominate volume in outdoor construction and automotive masking due to UV stability and aging resistance, while water-based technology leads growth as converters retrofit solvent lines to meet tightening MEE and EPA-aligned emission protocols. Hot-melt PSA occupies the premium tier in high-speed labeling lines where instant tack and clean machining reduce downtime.
Saudi Arabia's Standards, Metrology and Quality Organization (SASO) and South Africa's National Regulator for Compulsory Specifications (NRCS) enforce product safety and chemical disclosure standards that shape adhesive import eligibility and local formulation requirements. The UAE's Ministry of Climate Change and Environment implements VOC thresholds for industrial coatings and adhesives that directly influence technology selection in Dubai and Abu Dhabi manufacturing zones. Egypt's Environmental Affairs Agency is developing chemical inventory rules that will extend registration burdens to adhesive importers. Stakeholders must monitor regulatory divergence between Gulf harmonization initiatives and sub-Saharan national frameworks when allocating regional technical service resources.
Market Dynamics
Saudi Arabia's megaproject pipeline and South Africa's VOC enforcement are creating divergent technology requirements across the Middle-East and Africa PSA market. Formulators must now maintain dual-platform capabilities to serve Gulf construction growth alongside sub-Saharan emission compliance.
Growth Catalysts
- Flexible packaging expansion:Gulf Cooperation Council packaging converters are scaling PSA consumption for logistics labeling and food-grade flexible films, driven by e-commerce fulfillment center buildouts.
- MEE-aligned retrofit mandates:Water-based adhesive technology is capturing share as Egyptian and Moroccan converters retrofit solvent coating lines to meet EPA-aligned emission protocols.
- Automotive assembly localization:Saudi Arabia's industrial cities are developing captive adhesive supply chains to support localized vehicle production and component manufacturing.
Market Restraints
- Petrochemical feedstock volatility:Acrylic monomer and tackifying resin costs fluctuate with regional oil price swings, compressing formulation margins for mid-tier producers.
- Import dependency concentration:Specialty silicone PSA and high-performance acrylics remain concentrated in European and Asian supply bases, exposing North African converters to currency and logistics risk.
- REACH compliance friction:Non-European suppliers face elevated cost-of-entry burdens for chemical formulation imports into Morocco and Egypt, favoring incumbents with regional formulation centers.
Strategic Opportunities
- Hot-melt platform penetration:High-speed labeling lines in UAE and Saudi Arabia present white space for hot-melt PSA adoption where instant tack and clean machining reduce converter downtime.
- Construction-grade acrylic expansion:Saudi megaprojects including NEOM and Red Sea developments require UV-stable masking and bonding solutions for extreme climate exposure.
- Egyptian chemical inventory preparation:The Environmental Affairs Agency's developing registration rules will reward early-mover importers with compliant formulation portfolios before mandatory deadlines.
Industry Challenges
- Formulation chemist scarcity:Regional technical talent pools lack depth in water-based polymer synthesis and VOC-compliant additive selection, extending product development cycles.
- Dual-certification burden:Suppliers must simultaneously satisfy SASO product safety standards and NRCS chemical disclosure requirements without unified testing protocols.
- Legacy solvent line stranded assets:South African converters face capex intensity for water-based retrofitting while maintaining production continuity under tightening Air Quality Act enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market |
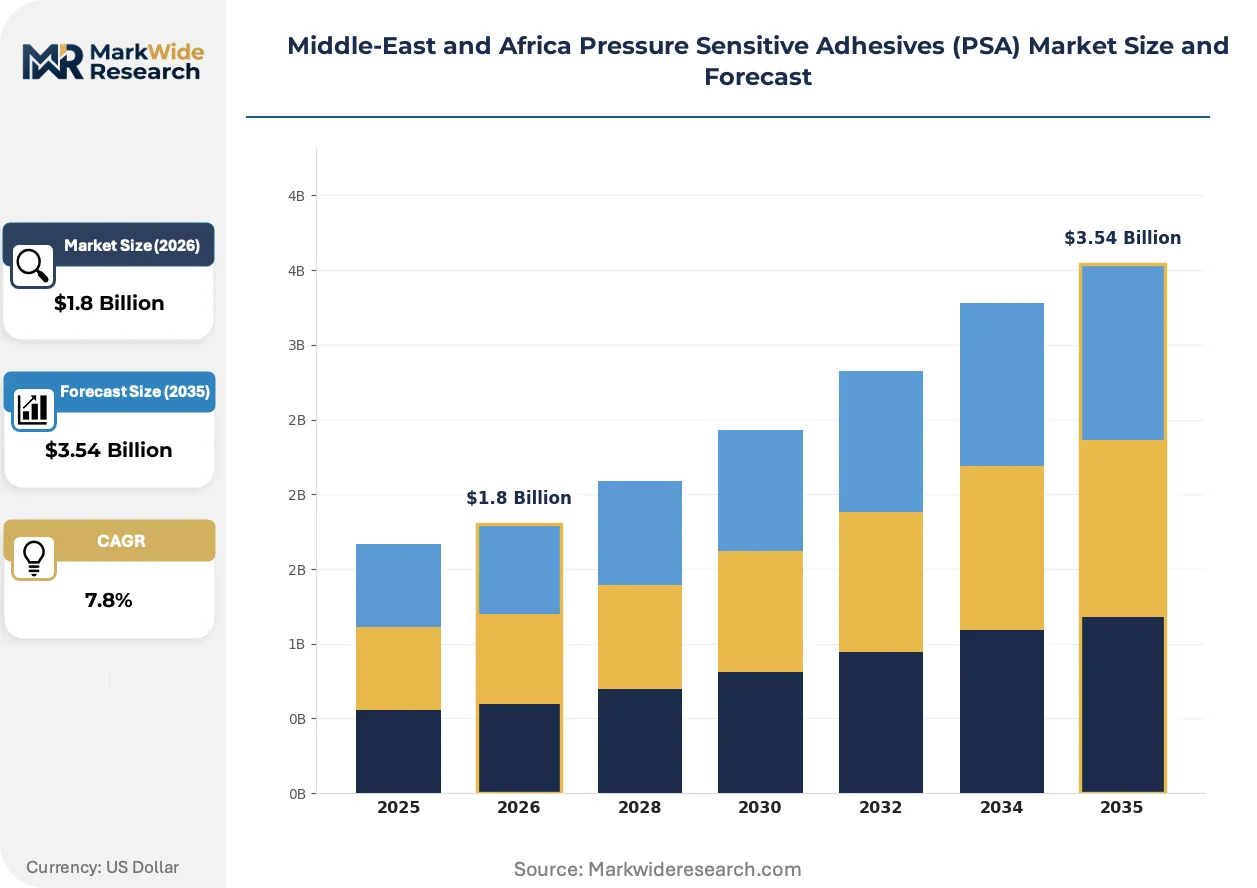
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-Based, Rubber-Based, Silicone-Based, Acrylic-Based End Use Industry: Packaging, Automotive, Construction, Electronics Application: Labeling, Taping, Automotive Assembly, Surface Protection Technology: Hot Melt, Water-Based, Solvent-Based, UV-Curable |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, Avery Dennison Corporation, H.B. Fuller Company, Arkema Group, Sika AG, Dow, Huntsman Corporation, The Industrial Group Ltd., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market Shifts & Advancements
Technology platforms and regulatory enforcement are diverging across the Middle-East and Africa PSA landscape. Formulators are deploying distinct strategies for Gulf construction growth versus sub-Saharan compliance retrofitting.
Hot-melt PSA technology is expanding into high-speed labeling applications across UAE and Saudi Arabian packaging hubs. Major converters are adopting reactive polyurethane and metallocene polyolefin platforms to eliminate solvent handling and reduce changeover downtime. This technology is expanding into premium-tier logistics and consumer goods labeling segments previously dominated by solvent acrylics.
South Africa's Air Quality Act amendments are forcing measurable VOC reductions in industrial adhesive applications. The National Regulator for Compulsory Specifications is tightening disclosure requirements for imported formulations, pushing converters toward water-based and UV-curable alternatives. Automotive masking and construction tape producers in Gauteng and Western Cape manufacturing zones are absorbing the steepest compliance costs.
Buyer consolidation among Gulf packaging groups is compressing supplier negotiation cycles and unbundling technical service from material supply contracts. Major Saudi and UAE converters are centralizing procurement through dedicated adhesive category managers, displacing distributor-led purchasing. This concentration is most visible in Dubai and Jeddah industrial zones where multinational logistics operators have standardized global PSA specifications.
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market Segmentation
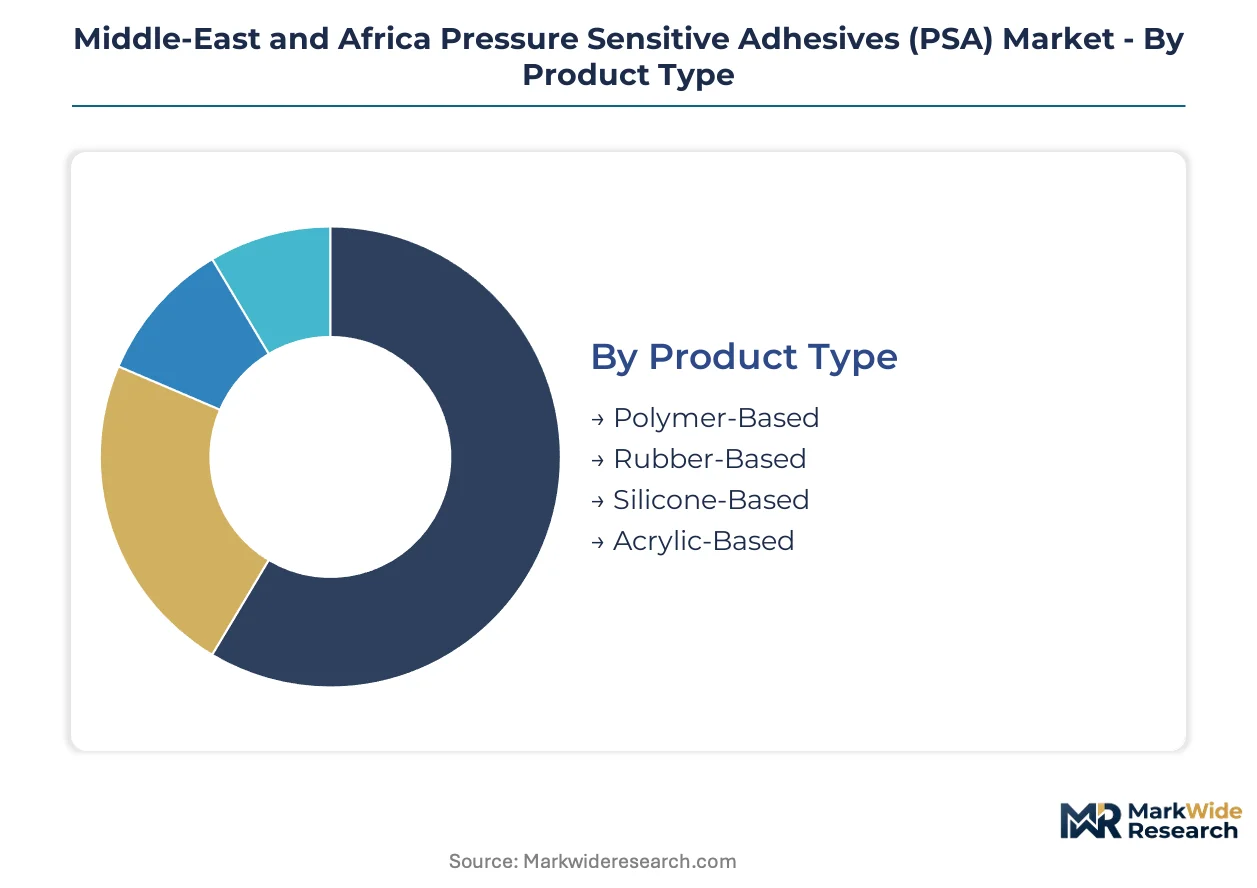
Technology platforms and chemical backbones diverge sharply across Middle-East and Africa PSA applications. Gulf construction megaprojects and South African emission enforcement create distinct upgrade cycles that reshape segment priorities.
Product Type:
Converters are replacing legacy rubber formulations with performance polymers as climate exposure and regulatory scrutiny intensify across Saudi Arabia and South Africa.
- Acrylic-Based:UV-stable copolymers dominate outdoor construction masking and automotive refinishing across Saudi Arabia's NEOM and Red Sea developments. Demand concentrates in Riyadh and Jeddah industrial zones where SASO product safety standards mandate aging resistance documentation.
- Silicone-Based:High-temperature polydimethylsiloxane formulations serve electronics bonding and medical-grade applications. Egyptian and Moroccan importers face REACH compliance friction for specialty silicone imports, favoring regional formulation centers.
- Polymer-Based:Block copolymer and metallocene polyolefin platforms target flexible packaging converters in Dubai and Abu Dhabi logistics hubs.
- Rubber-Based:Natural and synthetic rubber tackified systems persist in low-cost labeling for price-sensitive North African markets.
Volume placements concentrate in Acrylic-Based formulations for Gulf construction; the faster expansion belongs to Silicone-Based grades for electronics localization.
End Use Industry:
Customer procurement patterns split between Gulf packaging consolidation and sub-Saharan automotive compliance retrofitting.
- Packaging:Food-grade flexible films and logistics labeling absorb the majority of PSA tonnage across UAE and Saudi Arabia. E-commerce fulfillment center buildouts in Dubai Industrial City and Jeddah Islamic Port drive specification standardization among multinational logistics operators.
- Construction:Megaproject-driven demand for masking tapes, flooring adhesives, and facade bonding solutions spans Saudi Arabia's giga-developments. UV exposure and sand abrasion requirements favor acrylic and silicone chemistries over rubber alternatives.
- Automotive:Localized vehicle assembly in Saudi industrial cities creates captive adhesive supply chains for interior trim and exterior component bonding.
- Electronics:Thermal management and display bonding applications remain concentrated in UAE free zone manufacturing for re-export markets.
Packaging commands the largest absolute placements; Construction is climbing the fastest on megaproject execution timelines.
Application:
Line speed requirements and climate durability define application-level technology selection across converter segments.
- Labeling:High-speed logistics and consumer goods labeling lines in UAE and Saudi Arabia are displacing solvent acrylics with hot-melt platforms. Instant tack and clean machining reduce changeover downtime for Dubai and Jeddah packaging hubs.
- Taping:Masking and duct tape applications span construction, automotive refinishing, and general industrial maintenance. South African converters absorb steepest compliance costs under Air Quality Act VOC enforcement for solvent-based tape coatings.
- Automotive Assembly:Interior trim, wire harness, and exterior component bonding for localized Saudi vehicle production.
- Surface Protection:Temporary films for glass, metal, and painted surfaces during construction and transportation.
Labeling applications lead current volume; Taping is gaining share fastest on construction sector expansion.
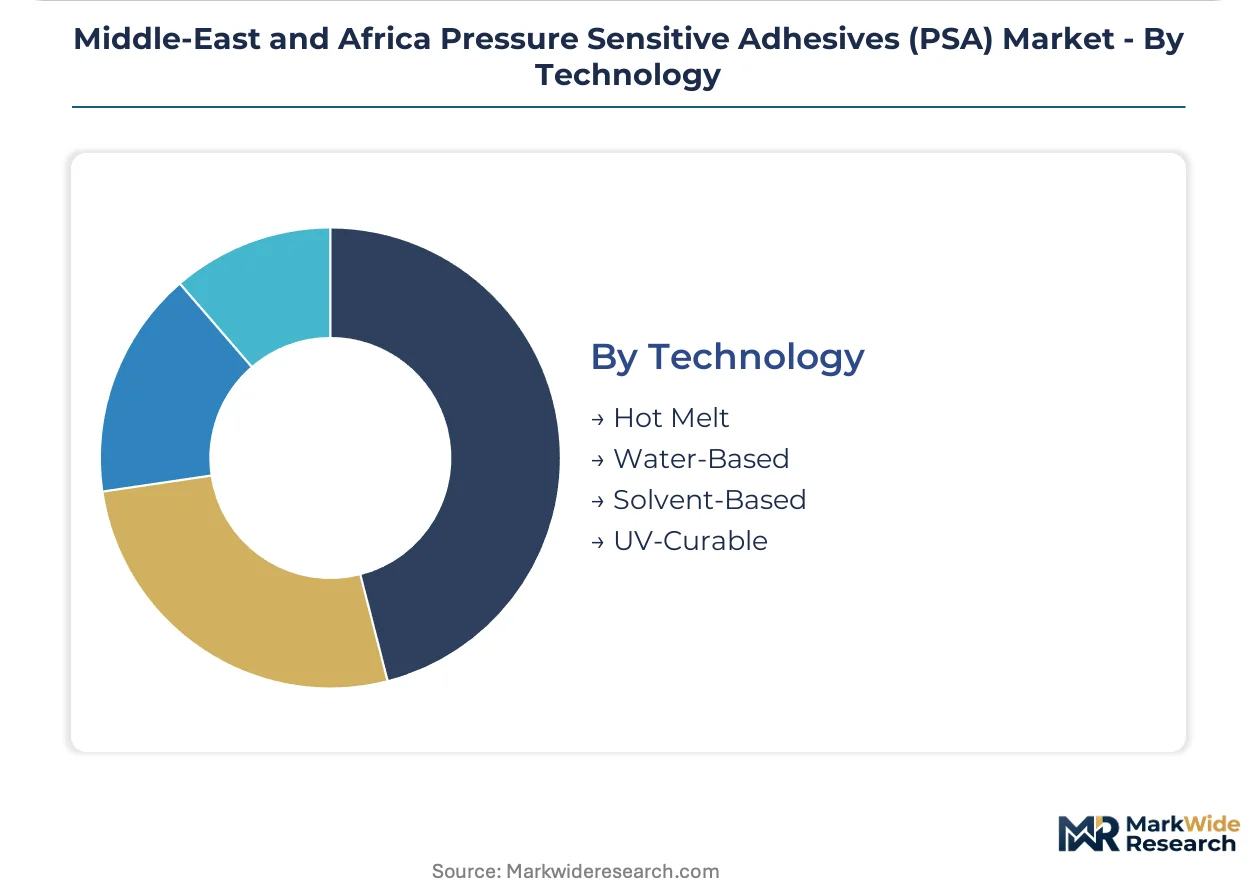
Technology:
Capital expenditure cycles and regulatory enforcement timelines determine technology migration patterns across national markets.
- Water-Based:Acrylic emulsion and polyurethane dispersion platforms capture share as Egyptian and Moroccan converters retrofit solvent coating lines. MEE-aligned emission protocols and EPA-equivalent standards in South Africa accelerate capital deployment toward aqueous systems.
- Hot Melt:Reactive polyurethane and metallocene polyolefin systems eliminate solvent handling entirely. Premium-tier adoption in UAE and Saudi Arabian high-speed labeling lines rewards instant tack performance with reduced downtime economics.
- Solvent-Based:Legacy acrylic and rubber solutions face stranded asset risk under tightening VOC thresholds across South Africa and Gulf harmonization initiatives.
- UV-Curable:Acrylic oligomer formulations target electronics and specialty industrial applications with instant cure and zero emission profiles.
Water-Based technology holds the broadest installed base; Hot Melt is expanding most quickly in premium packaging segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Saudi Arabia's industrial cities and UAE logistics hubs, while regulatory divergence between Gulf harmonization and sub-Saharan frameworks fragments supply chain configuration across the Middle-East and Africa PSA market.
Saudi Arabia
NEOM and Red Sea megaprojects drive construction-grade acrylic consumption for UV-stable masking and facade bonding. SASO enforces product safety and aging resistance documentation for imported formulations. Riyadh and Jeddah industrial zones host localized automotive assembly plants developing captive adhesive supply chains.
United Arab Emirates
Dubai Industrial City and Abu Dhabi manufacturing zones absorb premium hot-melt PSA for high-speed labeling lines serving e-commerce fulfillment. MOHAP implements VOC thresholds influencing technology selection across industrial coatings and adhesives. Multinational logistics operators standardize global PSA specifications through centralized procurement.
South Africa
Gauteng and Western Cape automotive masking tape producers face steep compliance costs under Air Quality Act VOC enforcement. NRCS tightens chemical disclosure requirements for imported formulations. Cape Town manufacturing zones absorb water-based and UV-curable alternatives as converters retrofit solvent coating lines.
Egypt
Packaging converters in Cairo and Alexandria retrofit solvent lines to meet MEE-aligned emission protocols. The Environmental Affairs Agency develops chemical inventory rules extending registration burdens to adhesive importers. Alexandria's free zone manufacturing attracts regional formulation centers seeking early-mover advantage.
Morocco
REACH compliance obligations realign cost-of-entry calculus for non-European suppliers serving North African flexible packaging markets. Egyptian and Moroccan converters accelerate capital deployment toward water-based acrylic emulsion platforms. Casablanca industrial zones concentrate logistics labeling demand from European supply chain reconfiguration.
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market Competitive Landscape
European producers anchor the premium formulation tier; Gulf-based distributors hold channel control in high-volume segments. The market structures around three archetypes: multinational chemical conglomerates with regional formulation centers, specialty adhesive houses with climate-specific portfolios, and industrial distributors with technical service bundling. Competitive moves concentrate on geographic expansion through localized production and portfolio diversification into water-based and hot-melt platforms.
Within the multinational tier, Henkel AG & Co. KGaA, 3M Company, and Avery Dennison Corporation exemplify divergent positioning strategies. Henkel leverages regional formulation centers to sustain localized production advantages. 3M anchors through deep channel control in UAE industrial distribution networks. Avery Dennison occupies a specialty position through labeling substrates engineered for Gulf-state climate extremes. These three represent distinct competitive vectors: formulation proximity, distribution density, and application-specific performance.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| Avery Dennison Corporation |
| H.B. Fuller Company |
| Arkema Group |
| Sika AG |
| Dow |
| Huntsman Corporation |
| The Industrial Group Ltd. |
| Others |
Supply & Pricing Matrix
MEE-aligned emission protocols in Egypt and Morocco gate qualified supply access and premium-tier pricing for water-based adhesive platforms. Converters lacking retrofit capital face exclusion from procurement pools serving multinational packaging accounts, compressing their addressable market to spot solvent-grade transactions at depressed margins.
Pricing Analysis
Lead-time premiums separate contract holders from spot buyers across Saudi and UAE industrial zones. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade against SASO aging resistance standards and volume scale commitments. Cost compression in standard-grade acrylic emulsions is intensifying because Egyptian converters are absorbing stranded asset depreciation from solvent line mothballing. Price-sensitive North African flexible packaging buyers drive the steepest negotiation pressure, while Gulf megaproject contractors show lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Freight cost volatility from European and Asian specialty resin hubs exposes North African converters to margin erosion. Acrylic monomer supply concentrates in Saudi Arabia, South Korea, and Germany; tackifying resin production centers on the US Gulf Coast and Southeast Asia. The regional installed base draws from imported silicone PSA and high-performance acrylics, creating single-source vulnerability for electronics-grade formulations. Distribution runs through UAE-based industrial distributors with technical service bundling, though buyer consolidation is displacing this channel in Jeddah and Dubai logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH obligations and SASO documentation requirements erect barrier-to-entry moats favoring incumbents with regional formulation infrastructure.
For Market Incumbents: Cement localized production advantages by expanding Egyptian and Moroccan formulation centers ahead of Environmental Affairs Agency registration deadlines. Capacity addition in Alexandria's free zone manufacturing clusters captures early-mover positioning while insulating against currency risk on specialty silicone imports. Channel control in UAE industrial distribution networks defends against buyer consolidation pressure from centralized procurement at Saudi packaging groups. For New Entrants and Emerging Players: E-commerce platform direct sales routes bypass distributor markups for mid-tier South African converters retrofitting solvent lines. White-space concentration sits in hot-melt PSA for high-speed labeling lines across Dubai Industrial City and Jeddah Islamic Port, where instant tack performance commands premium positioning. Technical service unbundling from material supply contracts offers the most penetrable go-to-market angle against entrenched multinational bundling. For Investors and Strategic Acquirers: Egyptian Environmental Affairs Agency publication of draft chemical inventory rules is the leading indicator that registration-ready formulation portfolios will command acquisition premiums. Regional formulation centers with water-based polymer synthesis capabilities represent the priority target archetype over pure trading operations. Monitor SASO documentation harmonization announcements as the signal for Gulf market access liberalization or further consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Production | Saudi petrochemical feedstock access secures margin control against oil price volatility. |
| Water-Based Platform Capacity Expansion | Egyptian and Moroccan retrofit demand captures share from stranded solvent assets. |
| Hot-Melt Technology Licensing Agreement | Reactive polyurethane know-how penetrates UAE premium labeling segments. |
| Regional Formulation Center Joint Venture | Alexandria free zone manufacturing localizes supply for North African flexible packaging. |
| Long-Term Supply Agreement with Gulf Packaging Groups | Centralized procurement at Saudi logistics operators locks volume commitments. |
Research Methodology
Independent corroboration across technical directors at PSA formulation centers, procurement leads at GCC packaging converters, and distribution channel partners in UAE industrial zones underwrites the qualitative findings. Secondary validation drew from customs trade data on acrylic monomer and tackifying resin flows, SASO product safety documentation filings, and SEC disclosures from multinational adhesive producers. Bottom-up segment sizing triangulated against top-down market envelope estimates from petrochemical derivative demand modeling.
Comparable-period anchoring to historical capacity utilization and retrofit capital deployment patterns shaped the projection horizon. The analytical framework segmented by technology platform, chemical backbone, end-use industry, and regional regulatory cluster, with cross-elasticity between water-based and hot-melt substitution rates informing technology migration assumptions. CAGRs were derived from installed base turnover timelines and emission compliance enforcement schedules rather than extrapolated trend lines.
The model holds under stable regulatory enforcement timelines and feedstock cost corridors; deviation in Egyptian chemical inventory rule acceleration or Saudi megaproject execution delays would shift volume and value outputs. Forecasts reflect documented assumptions on converter retrofit rates and Gulf buyer consolidation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Correction Fluid and Tape Market
Adhesives & Sealants
Global Bioadhesive Market
Adhesives & Sealants
Metal Bonding Adhesives Market
Adhesives & Sealants
Europe Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
High Temperature Adhesives Market
Adhesives & Sealants
Textile Adhesives Market
Adhesives & Sealants
Soft Skin Adhesives Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
Middle East and Africa Sealants Market
Adhesives & Sealants
Asia-Pacific Automotive Adhesives and Sealants Market
Adhesives & Sealants
Timber Laminating Adhesives Market
Adhesives & Sealants
Corrosion Protection Tapes Market
Adhesives & Sealants
North America Waterborne Adhesives Market
Adhesives & Sealants
Global Epoxy Adhesive Market
Adhesives & Sealants
Polyester Hot Melt Adhesives Market
Adhesives & Sealants
Instant Adhesive Market