
 Global Bioadhesive Market | 2026-2036
Global Bioadhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bioadhesive Market Foresight
Modular patch configurations for transdermal and topical delivery is decoupling traditional one-size-fits-all adhesive procurement. Henkel AG leverages its medical-grade polymer expertise to anchor European supply chains for hospital-grade fixation products. DuPont de Nemours competes through biomaterial R&D intensity, particularly in cellulose-derived platforms for wound closure. H.B. Fuller Company specializes in hot-melt bioadhesive formulations, sustaining North American manufacturing scale for device assembly applications.
Bioadhesives comprise polymeric materials engineered to bond biological tissues or adhere to mucosal surfaces, typically formulated with proteins, polysaccharides, or synthetic biodegradable backbones with tensile adhesion strengths ranging from 0.1 to 10 MPa depending on the target substrate. These materials serve primary functions in sealing surgical incisions, enabling localized drug release, and securing implantable devices without provoking chronic inflammatory responses. Natural polymers command established volume positions due to collagen and chitosan availability, while hydrogel platforms represent the fastest-expanding delivery technology category driven by tunable swelling kinetics and bioresorption rates. Synthetic polymers concentrate margin pools where batch-to-batch consistency meets FDA and EMA sterilization validation requirements for Class III devices.
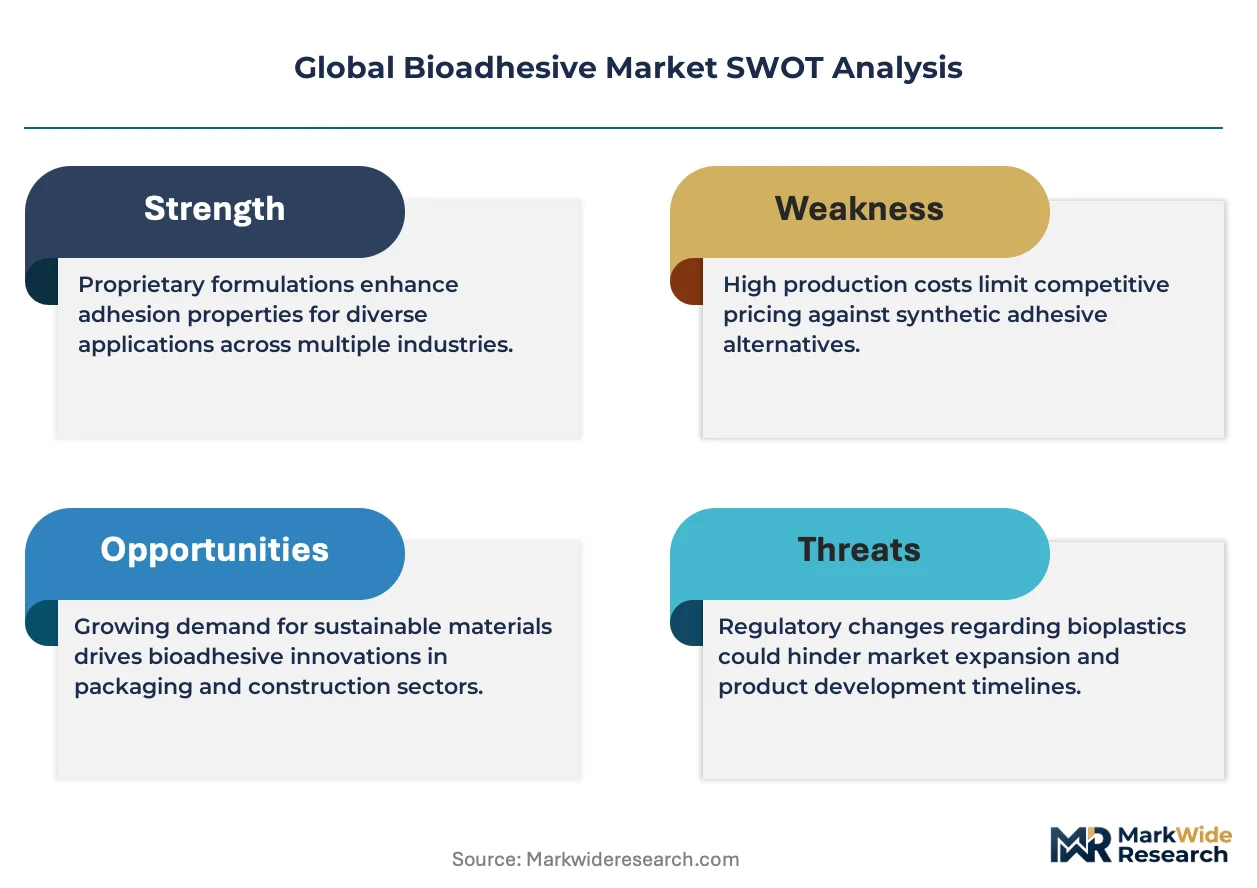
EMA's Medical Device Regulation and the FDA's 510(k) biocompatibility standards shape product development timelines, forcing reformulation investments before market authorization. REACH restrictions on isocyanate-based chemistries and the EU Green Deal's bio-based content mandates are redirecting capital toward fermentation-derived feedstocks and enzymatic polymerization routes. Stakeholders must monitor evolving biodegradability certification protocols from ISO and national regulators, as these standards will determine which formulation platforms qualify for preferred procurement status in public health systems.
Market Dynamics
EU MDR and REACH compliance deadlines are forcing pharmaceutical and medical device manufacturers to abandon petrochemical-derived adhesives before 2027, triggering a wave of reformulation contracts and raw material qualification programs across European supply chains.
Growth Catalysts
- Transdermal drug delivery expansion:Pharmaceutical manufacturers are scaling bioadhesive procurement for patch-based therapeutics targeting chronic conditions, with Class III device approvals accelerating substrate qualification timelines.
- REACH isocyanate restrictions:ECHA's tightening limits on aromatic isocyanates in consumer and medical applications are redirecting formulation R&D toward enzymatic polymerization and fermentation-derived polyols.
- German chemical cluster concentration:Specialized production hubs in Ludwigshafen and Leverkusen anchor medical-grade bioadhesive supply, attracting downstream device assembly investment from Nordic and Benelux markets.
Market Restraints
- Collagen supply volatility:Bovine and porcine-derived collagen prices fluctuate with livestock epidemiology and religious slaughter regulations, compressing margin predictability for natural polymer formulations.
- Batch-to-batch inconsistency:Natural bioadhesives exhibit wider viscosity and adhesion variance than synthetic alternatives, forcing medical device manufacturers to maintain larger safety stocks and quality control overhead.
- Synthetic polymer substitution:Cyanoacrylate and polyurethane platforms retain cost advantages in non-implantable wound closure, limiting bioadhesive penetration in emergency care and consumer first-aid segments.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's accelerating 510(k)-parallel approval pathways for drug-device combinations create entry points for bioadhesive suppliers targeting export-oriented transdermal patch producers in Hyderabad and Ahmedabad.
- Bioresorbable electronics integration:Convergence of transient electronic circuits with hydrogel bioadhesives is opening surgical monitoring applications where adhesion and controlled dissolution must synchronize with tissue healing timelines.
- EU Green Deal bio-based mandates:Public procurement rules requiring minimum renewable content in medical supplies will advantage fermentation-derived polysaccharide platforms over petroleum-based competitors in hospital system tenders.
Industry Challenges
- Sterilization validation complexity:Gamma and electron-beam sterilization protocols alter hydrogel crosslink density and adhesion profiles, forcing iterative FDA 510(k) resubmissions that extend commercialization timelines by 18-24 months.
- Biopolymer processing expertise scarcity:Formulation chemists with simultaneous competence in protein denaturation control, rheology tuning, and biocompatibility testing command premium compensation, constraining scale-up capacity at mid-size manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bioadhesive Market |
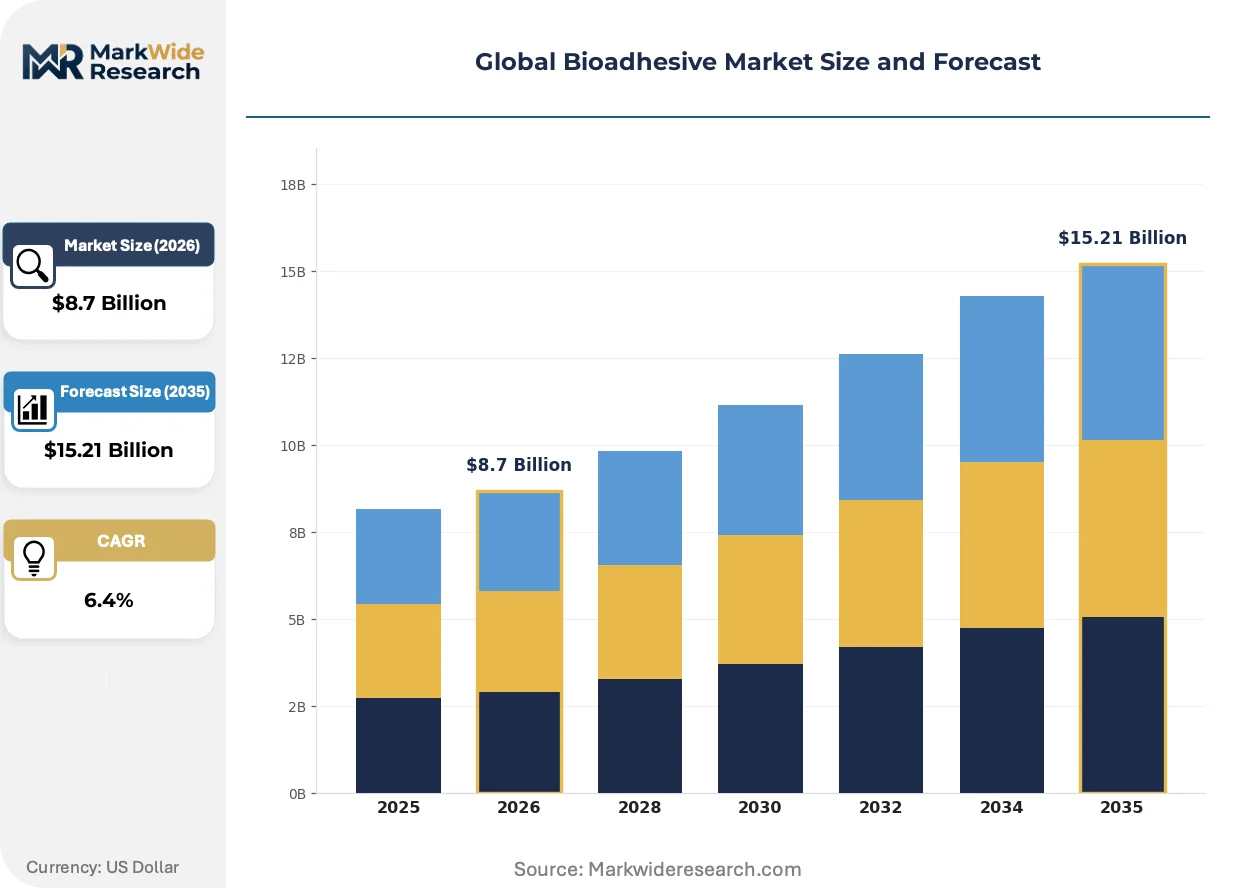
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Polymers, Synthetic Polymers, Semi-Synthetic Polymers, Hybrid Adhesives Application: Wound Closure, Drug Delivery, Medical Device Fixation, Dental Repair, Tissue Engineering End User: Pharmaceutical Manufacturers, Biotech Firms, Medical Device Producers, Research Laboratories Delivery Technology: Patch Systems, Spray Application, Injectable Formulations, Film Coatings, Hydrogel Platforms |
| Companies Covered | Henkel AG, DuPont de Nemours, Arkema, H.B. Fuller Company, Ingredion, Jowat SE, EcoSynthetix, Paramelt, Danimer Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bioadhesive Market Shifts & Advancements
Formulation science is converging with digital manufacturing and synthetic biology to compress development cycles and enable patient-specific adhesion profiles that static petrochemical platforms cannot replicate.
Multifunctional hydrogel platforms is unifying drug delivery, tissue adhesion, and biosensing in single-layer configurations. Wound care divisions at major hospital systems are piloting these materials for post-surgical monitoring. The technology is unifying previously separate procurement categories—dressings, adhesives, and sensors—into integrated contracts that favor vertically integrated bioadhesive suppliers over component specialists.
EMA's Medical Device Regulation recast is mandating Unique Device Identification and enhanced clinical evidence for Class III bioadhesive-containing devices. Manufacturers must now generate post-market surveillance data that validates long-term bioresorption safety. Implantable device segments in Germany and France are responding by consolidating supplier bases to partners with established MDR technical documentation capabilities.
Hospital procurement departments are consolidating annual adhesive contracts into multi-year strategic partnerships with guaranteed volume commitments and joint formulation development clauses. Group purchasing organizations are displacing spot-market purchasing for standard fixation products. This concentration is most visible in US academic medical centers and German hospital networks, where procurement teams now evaluate supplier R&D pipelines alongside unit pricing.
Global Bioadhesive Market Segmentation
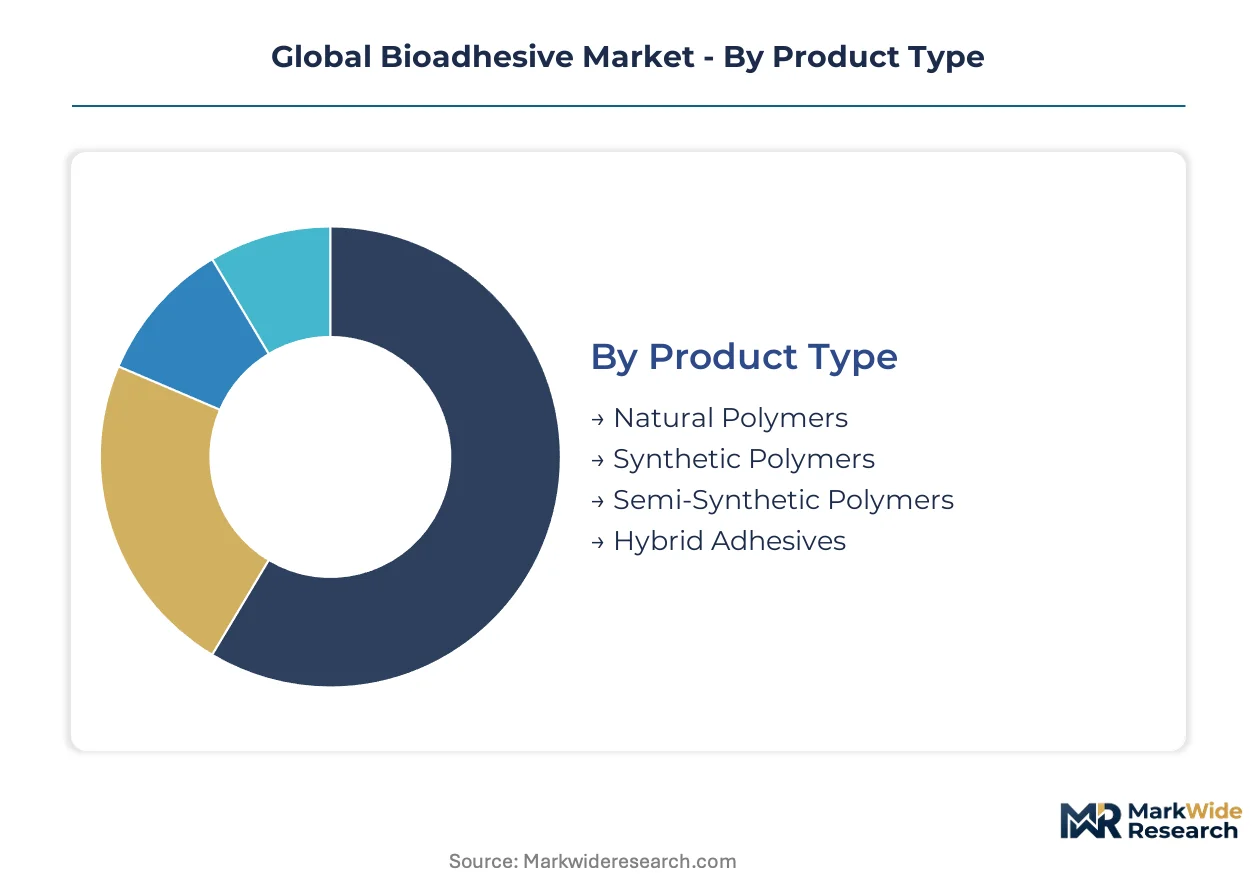
Bioadhesive procurement decisions hinge on sterilization compatibility, bioresorption timelines, and regulatory pathway complexity. Understanding how formulation chemistry, application setting, and delivery mechanism intersect reveals where margin pools concentrate and which technology platforms command premium positioning.
Product Type:
Cost tier determines qualification burden and contract value, with natural polymers anchoring volume and synthetics capturing margin in implantable segments.
- Natural Polymers:Collagen, chitosan, and alginate formulations dominate wound closure and topical applications. German hospital networks and US academic medical centers specify these materials for Class II fixation products where biocompatibility documentation outweighs batch variance concerns.
- Synthetic Polymers:Poly(lactic-co-glycolic acid) and polycaprolactone backbones deliver the controlled degradation kinetics required for Class III implantable devices. FDA 510(k) submissions for synthetic platforms require extensive sterilization validation, concentrating procurement among manufacturers with captive polymerization capabilities.
- Semi-Synthetic Polymers:Modified cellulose and starch derivatives bridge cost and performance gaps in dental repair applications.
- Hybrid Adhesives:Protein-synthetic composites target niche tissue engineering contracts requiring tunable mechanical properties.
Natural polymers lead on scale; synthetic polymers lead on momentum.
Application:
Regulatory classification intensity shapes supplier selection, with Class III device applications demanding deeper technical documentation partnerships.
- Wound Closure:Cyanoacrylate alternatives and fibrin sealants serve emergency departments and surgical suites. REACH isocyanate restrictions are redirecting formulation R&D toward enzymatic polymerization in European procurement.
- Drug Delivery:Transdermal patches and mucosal films require adhesion profiles synchronized with API release kinetics. Pharmaceutical manufacturers in Hyderabad and Ahmedabad are scaling bioadhesive procurement for export-oriented production.
- Medical Device Fixation:Pacemaker leads and catheter securement drive demand for moisture-resistant, long-duration adhesion.
- Dental Repair:Enamel and soft tissue bonding applications favor semi-synthetic platforms for cost-sensitive reimbursement environments.
- Tissue Engineering:Scaffold adhesion and cell encapsulation represent emerging specification territory with evolving ISO standards.
Drug delivery commands the steepest expansion trajectory; wound closure retains the deepest installed base.
End User:
Customer type dictates contract structure, with pharmaceutical manufacturers consolidating multi-year supply agreements and research laboratories driving pilot-scale innovation.
- Pharmaceutical Manufacturers:Transdermal and topical drug delivery specialists in Germany, India, and the United States specify bioadhesives with validated extractables profiles. CDSCO's accelerating 510(k)-parallel approval pathways are expanding procurement volumes for export-oriented producers.
- Biotech Firms:Cell therapy and regenerative medicine developers require small-batch, high-variability formulations with rapid customization turnaround.
- Medical Device Producers:Class III implantable manufacturers concentrate procurement among suppliers with established MDR technical documentation capabilities in Germany and France.
- Research Laboratories:Academic and government research institutions pilot novel hydrogel platforms before commercial scale-up.
Pharmaceutical manufacturers lead on contract value; biotech firms lead on formulation novelty.
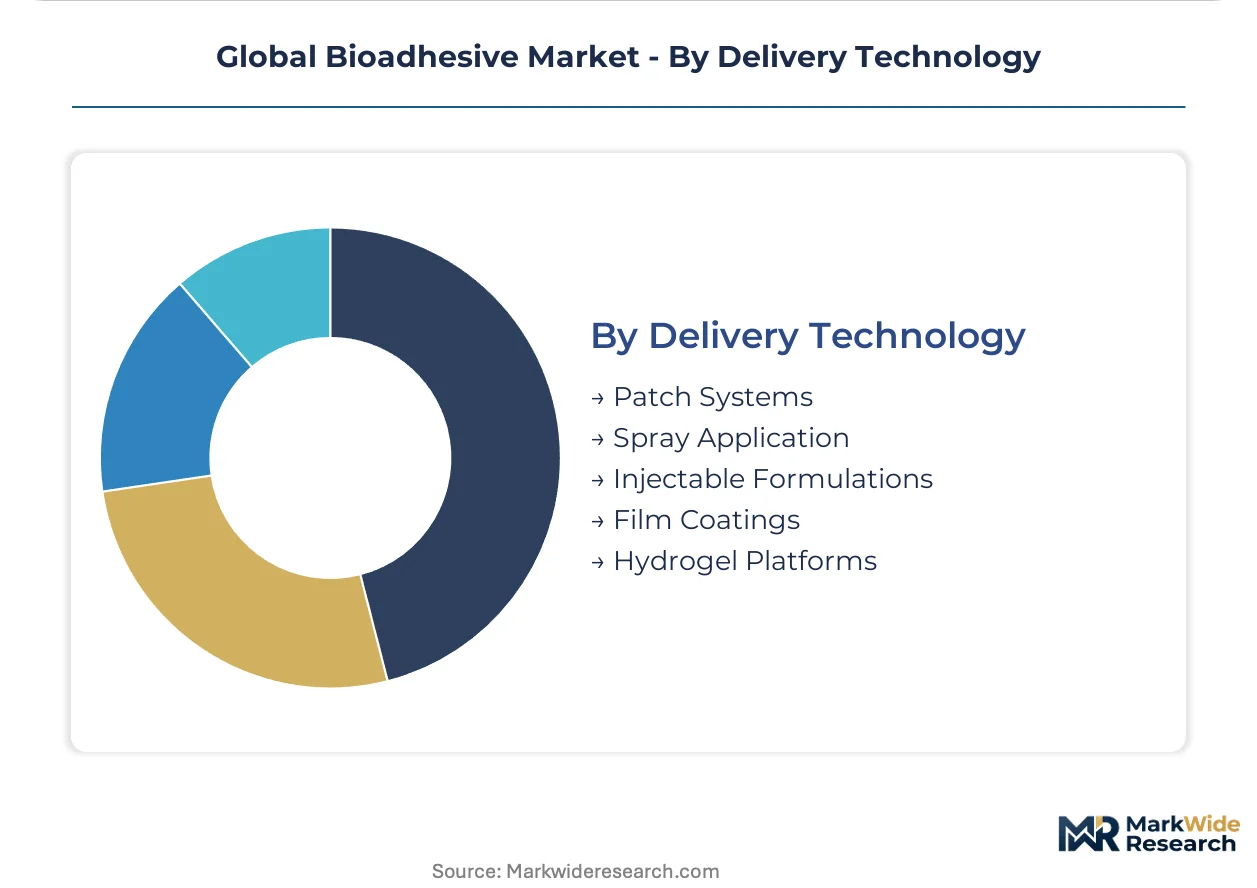
Delivery Technology:
Manufacturing process compatibility determines platform selection, with patch systems and hydrogels diverging on equipment investment and regulatory pathway.
- Patch Systems:Transdermal and topical patches require precise thickness control and backing layer lamination. EU Green Deal bio-based mandates are advantaging fermentation-derived polysaccharide platforms in public hospital tenders.
- Hydrogel Platforms:Tunable swelling kinetics and bioresorption rates enable wound care applications unifying drug delivery, adhesion, and biosensing. Gamma and electron-beam sterilization protocols alter crosslink density, forcing iterative FDA resubmissions.
- Spray Application:Intraoperative and field-deployable settings favor rapid-curing formulations with minimal surface preparation.
- Injectable Formulations:Minimally invasive delivery of in-situ curing bioadhesives targets orthopedic and cardiovascular specialties.
- Film Coatings:Thin-layer mucoadhesive films serve oral and buccal drug delivery with discrete patient compliance advantages.
Patch systems lead on manufacturing scale; hydrogel platforms lead on technology convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade bioadhesive production originated in German chemical clusters during the 1990s, establishing quality benchmarks that shaped FDA and EMA sterilization protocols. Today formulation expertise concentrates in specialized industrial zones across four continents.
Germany
Ludwigshafen and Leverkusen host integrated polymerization facilities serving Class III device manufacturers. REACH isocyanate restrictions are accelerating enzymatic polymerization investments. Bavarian medical technology clusters in Erlangen and Tuttlingen anchor downstream device assembly for Nordic export markets.
United States
Academic medical centers in Boston and the Research Triangle drive specification standards for transdermal patch procurement. FDA 510(k) biocompatibility requirements force sterilization validation partnerships with gamma irradiation facilities. Minnesota's Twin Cities corridor concentrates hot-melt formulation capacity for device fixation applications.
India
Hyderabad and Ahmedabad pharmaceutical manufacturers scale bioadhesive procurement for export-oriented transdermal production. CDSCO's 510(k)-parallel approval pathways compress regulatory timelines for drug-device combinations. Gujarat's specialty chemical zones attract fermentation-derived polysaccharide investments from European suppliers.
China
Yangtze River Delta contract manufacturers integrate bioadhesive lamination into patch production for Japanese and European pharmaceutical clients. NMPA's evolving biocompatibility standards align with ISO 10993 protocols. Shanghai's free-trade zones facilitate import of medical-grade natural polymers for hydrogel formulation.
Japan
Osaka-based medical device producers specify bioadhesives for aging-population wound care and drug delivery systems. PMDA's quality management system requirements exceed ISO 13485 baselines, favoring suppliers with established technical documentation. Kobe's biomedical cluster supports pilot-scale hydrogel customization for regenerative medicine ventures.
Global Bioadhesive Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sterilization validation capabilities and MDR technical documentation depth. The vendor base stratifies into three tiers: integrated chemical conglomerates with captive polymerization, specialized bioadhesive formulators with regional scale, and niche hydrogel innovators serving research markets. Dominant competitive moves include backward integration into fermentation-derived feedstocks and multi-year procurement partnerships with hospital group purchasing organizations.
Within the integrated chemical tier, Henkel AG and DuPont de Nemours occupy positions defined by medical-grade polymer expertise and cellulose-derived platform investments respectively. H.B. Fuller Company exemplifies the North American scale-driven archetype through hot-melt formulation concentration. These three entities represent distinct strategic postures: European regulatory navigation, biomaterial R&D intensity, and manufacturing scale optimization.
| Leading Market Players |
|---|
| Henkel AG |
| DuPont de Nemours |
| Arkema |
| H.B. Fuller Company |
| Ingredion |
| Jowat SE |
| EcoSynthetix |
| Paramelt |
| Danimer Scientific |
| Others |
Supply & Pricing Matrix
REACH isocyanate restrictions and EU MDR compliance deadlines are forcing pharmaceutical manufacturers to requalify adhesive suppliers, compressing procurement timelines and concentrating contract awards among European formulators with established sterilization validation capabilities. This specification tightening transfers pricing power upstream to German chemical clusters while squeezing margin buffers for mid-size manufacturers dependent on spot-market collagen sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Class III implantable-grade synthetics from Class II medical fixation products and commodity wound closure alternatives. Price differentiation rests on FDA 510(k) certification depth and batch-to-batch consistency guarantees, with pharmaceutical manufacturers showing lowest sensitivity and emergency care procurement teams highest. Cost compression in natural polymer tiers is intensifying because bovine collagen supply volatility forces safety stock carrying costs onto formulators without captive fermentation capacity.
Supply Chain Analysis
Single-source vulnerability sits with German polymerization hubs in Ludwigshafen and Leverkusen, where integrated chemical conglomerates anchor medical-grade bioadhesive production for Nordic and Benelux device assemblers. Raw material dependencies draw from Brazilian fermentation-derived polysaccharides, Indian chitosan processors, and domestic cellulose refiners. Tariff exposure on cross-Atlantic natural polymer shipments feeds into formulation cost structures. Distribution runs through hospital group purchasing organizations and pharmaceutical contract manufacturing networks, with spot-market purchasing displaced by multi-year strategic partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between EU MDR documentation requirements and CDSCO's accelerating 510(k)-parallel pathways in India creates cost-advantaged production positioning for suppliers willing to dual-qualify manufacturing sites. This geographic spread captures margin premiums in European tender markets while accessing volume growth in export-oriented pharmaceutical clusters.
For Market Incumbents: Anticipate synthetic polymer substitution pressure in non-implantable wound closure by deepening enzymatic polymerization expertise and securing captive fermentation-derived feedstock contracts. Backward integration into polysaccharide fermentation capacity in Gujarat's specialty chemical zones defends margin position against REACH-driven raw material cost inflation. MDR technical documentation depth remains the priority lever for retaining Class III device manufacturer relationships. For New Entrants and Emerging Players: The premium-to-economy price gap in transdermal patch bioadhesives opens entry space for mid-tier formulators targeting Indian pharmaceutical exporters in Hyderabad and Ahmedabad. CDSCO's streamlined approval pathways reduce qualification timelines versus FDA direct submissions. White-space concentration sits with bioresorbable electronics integration, where hydrogel-biosensor convergence lacks established supplier relationships. A co-development partnership model with regenerative medicine ventures in Japan's Kobe cluster offers the cleanest go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized bioadhesive formulators possessing MDR technical file libraries and gamma sterilization validation partnerships, acquisition targets likely to consolidate as hospital procurement centralization favors scaled documentation capabilities. The five-to-ten year viability window favors platforms with demonstrated FDA 510(k) resubmission management. Fermentation-derived polysaccharide capacity expansion announcements signal inflection points for premium-tier margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstocks | REACH isocyanate restrictions make enzymatic polymerization cost-competitive against petrochemical routes. |
| MDR Technical Documentation Investment | EU hospital procurement centralization favors suppliers with established Class III device filing capabilities. |
| Dual-Site Manufacturing Qualification | CDSCO's parallel approval pathways in India enable geographic arbitrage against European compliance costs. |
| Hydrogel-Biosensor Co-Development Partnerships | Bioresorbable electronics convergence opens surgical monitoring applications with synchronized adhesion-dissolution profiles. |
| Hospital GPO Strategic Partnership | Multi-year procurement contracts with guaranteed volume commitments displace spot-market purchasing for fixation products. |
Research Methodology
Bottom-up pharmaceutical procurement modeling reconciled against top-down chemical production tracking forms the analytical core of this study. Primary interviews with formulation chemists, hospital GPO contracts managers, regulatory affairs directors at medical device manufacturers, and CDSCO submission consultants combined with secondary validation from FDA 510(k) filings, EMA MDR technical documentation databases, EU customs trade records, and Indian pharmaceutical export statistics. Triangulation across these sources calibrated segment-level demand estimates against verified production capacity announcements.
Historical trendline analysis of natural polymer price volatility and synthetic polymer batch consistency metrics established baseline growth assumptions across the projection horizon. The analytical framework modeled segmentation across product chemistry, regulatory classification intensity, delivery technology, and end-user procurement structure. CAGRs derived from fitted trend extrapolation adjusted for REACH reformulation investment cycles and CDSCO approval pathway acceleration. Industry-specific forecast inputs incorporated sterilization validation timeline distributions and collagen supply epidemiology risk curves.
Caveats apply where EMA MDR enforcement intensity or FDA 510(k) biocompatibility standard revisions could materially shift the outlook for Class III device adhesive qualification timelines. Forecasts reflect assumptions about fermentation capacity expansion schedules and livestock disease incidence patterns that remain vulnerable to disruption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Wood Repair Epoxy Market
Adhesives & Sealants
Global Glass Bonding Adhesive Market
Adhesives & Sealants
Global Ethyl Methacrylate (97-63-2) Market
Adhesives & Sealants
Butyl Adhesive Market
Adhesives & Sealants
Germany Adhesives Market
Adhesives & Sealants
Malaysia Adhesives and Sealants Market
Adhesives & Sealants
United Kingdom Sealants Market
Adhesives & Sealants
Glue Pen Market
Adhesives & Sealants
Europe Epoxy Adhesive Market
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
India Waterproofing Solutions Market
Adhesives & Sealants
Solvent-Borne Adhesives Market
Adhesives & Sealants
Polysulfide Sealants Market
Adhesives & Sealants
Europe Sealants Market
Adhesives & Sealants
Mirror Adhesive Market
Adhesives & Sealants
Structural Adhesives Market