
 Corrosion Protection Tapes Market | 2026-2036
Corrosion Protection Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Corrosion Protection Tapes Market Outlook
Polyethylene is decoupling from traditional PVC backing formulations as petrochemical volatility reshapes raw material economics. 3M Company leverages its captive polymer science capabilities to stabilize tape performance across temperature extremes. Nitto Denko Corp anchors its position through precision coating lines that serve Japanese automotive OEMs with exacting thickness tolerances. Berry Global Inc. competes on blown film scale, converting resin into multi-layer backings at throughput rates regional players cannot match.
Corrosion protection tapes are pressure-sensitive adhesive systems laminated to polymer backings, typically 10-50 mils thick, engineered to exclude moisture and electrolytes from metal substrates in buried or submerged environments. The primary purpose is extending asset life for pipelines, structural steel, and marine equipment by blocking the electrochemical reactions that initiate rust. PVC tapes still dominate unit volume in construction and DIY channels where cost sensitivity prevails, though rubber-backed variants command margin premiums in subsea and chemical-processing applications where conformability to irregular surfaces determines performance. Self-adhesive technology leads installation efficiency, while heat-shrinkable systems capture value in field joint protection where factory-applied coatings cannot reach.
EPA guidelines on volatile organic compound emissions from adhesive manufacturing constrain formulation choices for US-based producers, while REACH compliance in Europe mandates disclosure of tape constituent chemicals across extended supply chains. NACE International standards and ISO 21809 for pipeline coatings define performance benchmarks that determine qualification for major energy infrastructure contracts. Buyers must weigh total applied cost against certified service life as project specifications tighten and warranty periods extend.
Market Dynamics
Subsea infrastructure aging is accelerating tape procurement cycles as offshore operators face cascading replacement demand across pipelines installed during the 1980s construction boom. The EU F-Gas Regulation and parallel environmental frameworks are forcing adhesive reformulation investments that reshape competitive economics.
Growth Catalysts
- Subsea Pipeline Rehabilitation:Offshore operators in the United States Gulf Coast petrochemical corridor are expanding maintenance budgets as cathodic protection systems reach end-of-design-life, creating pull-through demand for complementary tape systems.
- REACH Compliance Mandates:European chemical disclosure requirements across extended supply chains are disqualifying solvent-based adhesive producers, consolidating qualified supplier pools and elevating pricing power for compliant manufacturers.
- Butyl Rubber Formulations:Synthetic rubber backing technologies with superior conformability to irregular weld geometries are capturing specification share in chemical processing applications where surface preparation quality varies.
Market Restraints
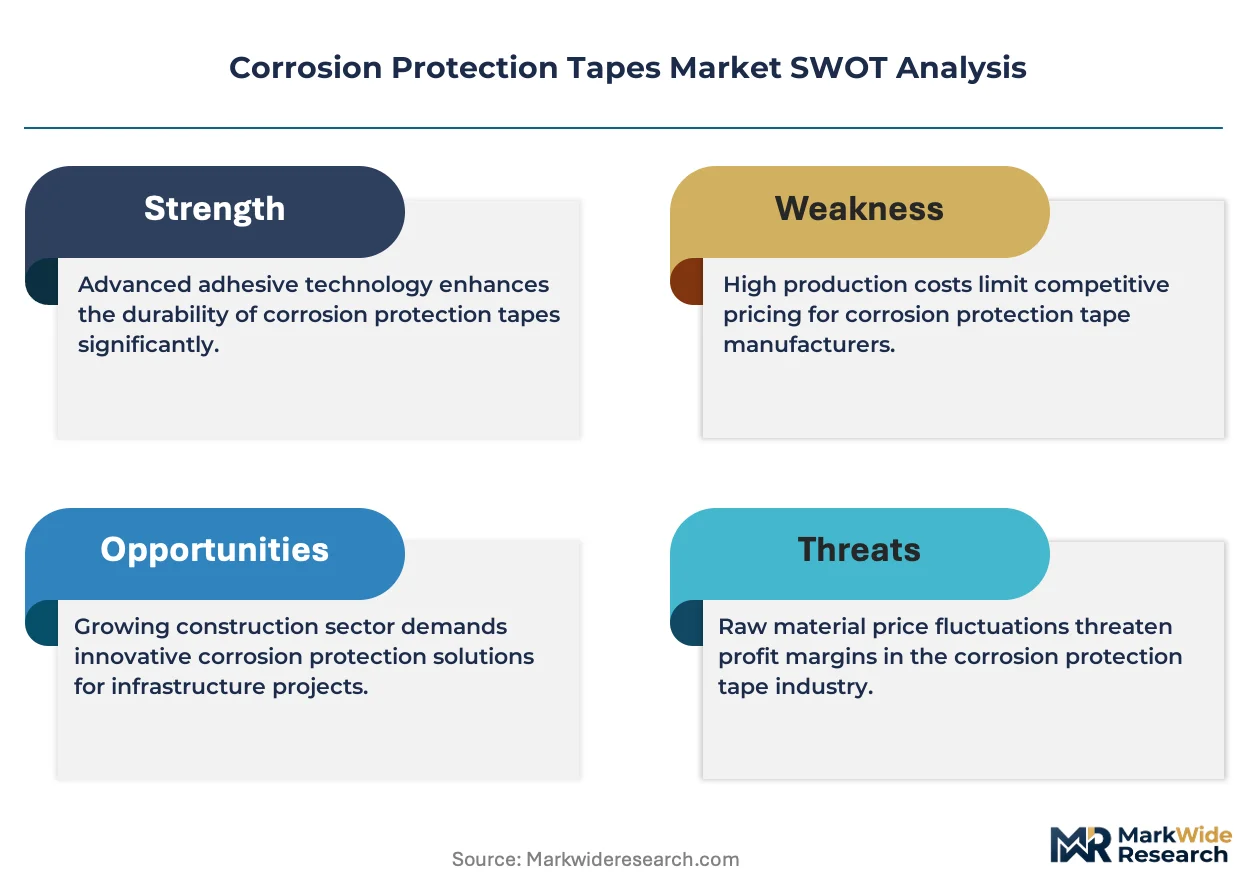
- Ethylene Feedstock Volatility:Polyethylene resin costs fluctuate with crude oil and natural gas liquid pricing, compressing margin predictability for blown film converters serving price-sensitive construction channels.
- Chinese Capacity Concentration:Regional tape backing production clusters in East Asia create supply vulnerability for European and North American tape laminators lacking captive polymer extrusion assets.
- Epoxy Coating Substitution:Fusion-bonded epoxy systems with factory-applied consistency threaten tape market share in new pipeline construction where field application labor costs are less decisive.
Strategic Opportunities
- Indian Infrastructure Buildout:The country's Petroleum and Natural Gas Regulatory Board pipeline expansion mandates are opening specification opportunities for corrosion protection systems in a historically underpenetrated geography.
- Heat-Shrinkable Field Joint Systems:Cross-linked polyethylene sleeve technologies that complement factory-applied mainline coatings represent white space in repair and tie-in applications where tape wrapping remains labor-intensive.
- US EPA VOC Guidelines:Emissions constraints on adhesive manufacturing are creating competitive moats for domestic producers with solvent-free coating capabilities, disadvantaging import-dependent distributors.
Industry Challenges
- NACE SP0169 Certification Timelines:Qualification testing for external corrosion control specialists extends 18-24 months, constraining workforce expansion for field application contractors.
- ISO 21809 Compliance Integration:Pipeline coating standard harmonization across national variants demands redundant testing budgets, particularly for suppliers serving multiple export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrosion Protection Tapes Market |
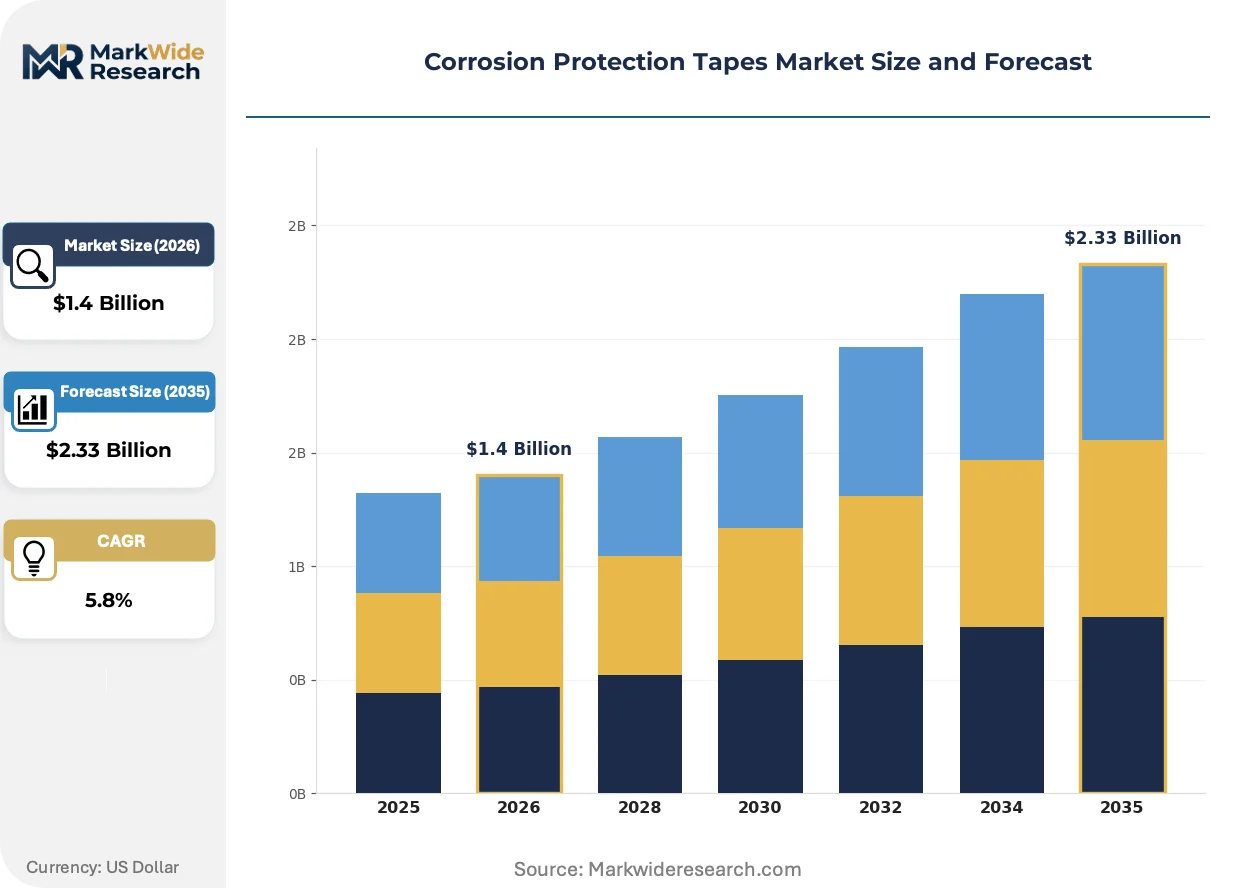
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, PVC, Rubber, Foam Application: Automotive, Marine, Construction, Electronics End User: Manufacturers, Contractors, DIY Consumers, Transportation Technology: Self-adhesive, Coating, Heat Shrinkable, Anti-corrosion |
| Companies Covered | 3M Company, Nitto Denko Corp, Berry Global Inc., Shurtape Technologies, LLC, Coroplast Fritz Müller GmbH & Co. KG, Scapa Group plc, W.W. Grainger Inc, Denso Tape, Polyken, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrosion Protection Tapes Market Strategic Shifts
Adhesive chemistry migration and procurement centralization are restructuring how corrosion protection systems are specified, purchased, and deployed across energy infrastructure value chains.
Butyl rubber adhesive layers are overtaking traditional asphalt-based compounds in subsea and chemical processing specifications. Japanese automotive OEMs with exacting thickness tolerance requirements have validated these formulations for critical sealing applications. The technology is compressing market share for conventional tape systems in high-conformability segments.
REACH mandates from ECHA are forcing constituent chemical disclosure across three-tier supply chains. Tape manufacturers must now document adhesive additive compositions previously treated as proprietary. European energy infrastructure contractors are responding by consolidating supplier panels to reduce audit burden, favoring vertically integrated producers with captive polymer science capabilities.
Integrated service contracting is displacing component-only procurement in major pipeline projects. Engineering-procurement-construction firms now bundle corrosion protection within total installed cost guarantees, compressing direct tape supplier margins while extending warranty liability periods. The United States Gulf Coast petrochemical corridor exhibits this pattern most acutely, where operator risk transfer preferences concentrate purchasing authority with EPC primes.
Corrosion Protection Tapes Market Segmentation
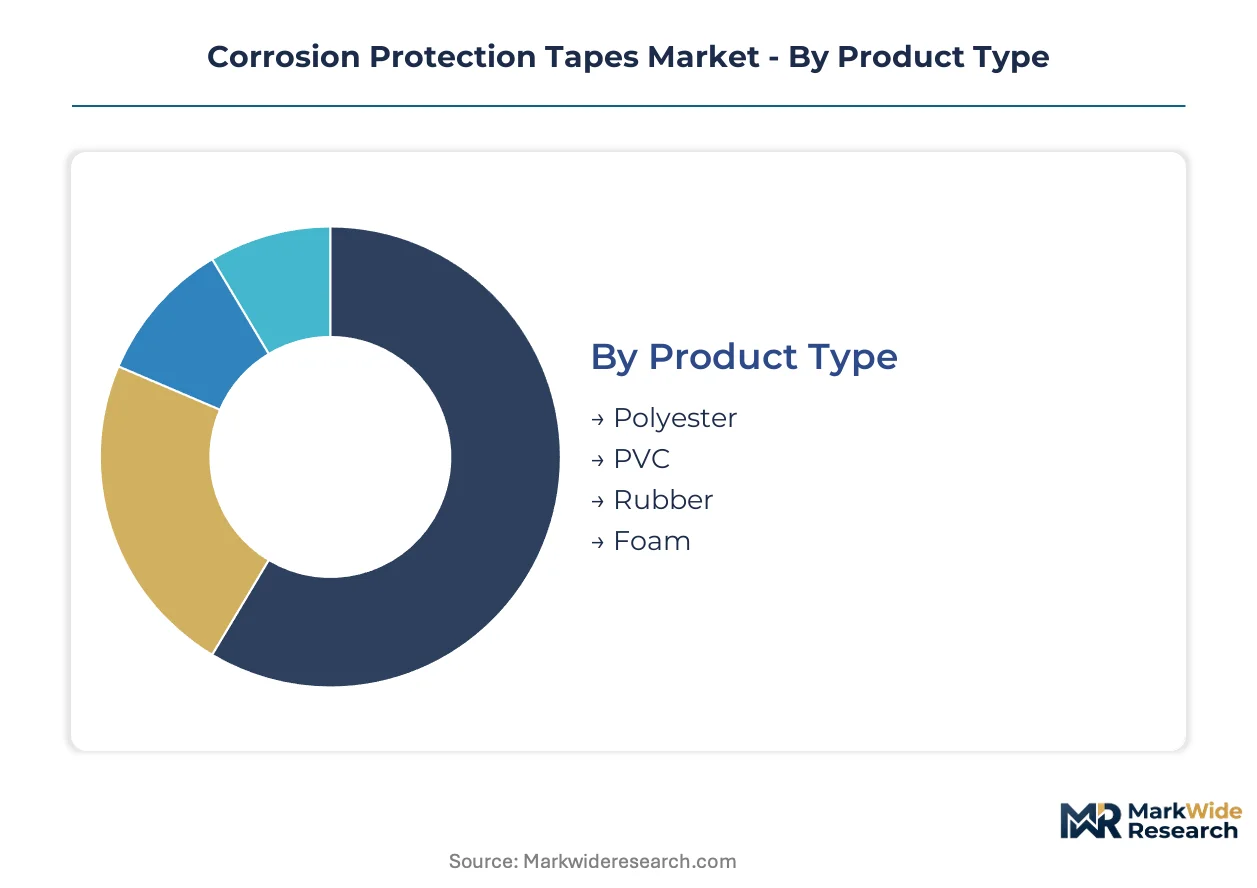
Corrosion protection tapes serve heterogeneous demand pools where specification requirements diverge sharply across substrate types, environmental exposure severity, and installation labor economics. Segmentation reveals where capital deployment concentrates and which technology platforms command sustainable margin premiums.
Product Type:
Polyethylene resin extrusion and adhesive coating line investments range from $2 million for regional blown film capacity to $15 million for multi-layer coextrusion systems serving subsea specifications.
- Polyester:High tensile strength films with dimensional stability under thermal cycling dominate automotive underbody applications where stone chip resistance matters. German automotive OEMs specify polyester backings for chassis protection tapes that must survive salt spray testing regimes.
- PVC:Plasticized vinyl formulations with lower raw material costs capture volume in construction and DIY channels where price sensitivity outweighs performance margins. PVC tape production requires less specialized extrusion equipment, lowering barriers for regional converters serving building trades.
- Rubber:Butyl and EPDM-backed systems with superior conformability to irregular weld geometries command specification share in chemical processing and subsea applications.
- Foam:Closed-cell polyethylene foam tapes with pressure-sensitive adhesive layers fill gap-sealing and vibration-damping roles in marine and transportation equipment.
PVC absorbs the bulk of installed capacity; rubber is expanding most quickly as subsea rehabilitation demand accelerates.
Application:
End-use concentration determines specification stringency and supplier qualification timelines, with marine and automotive applications imposing the most demanding certification requirements.
- Automotive:OEM-directed corrosion protection specifications for underbody coatings, seam sealing, and electrical harness wrapping demand ISO/TS 16949 traceability. Japanese and German manufacturers validate tape systems through 10-year accelerated aging protocols.
- Marine:Subsea pipeline operators and shipbuilders specify tapes meeting NORSOK M-503 and ISO 21809-3 for cathodic protection compatibility. Saltwater immersion resistance and cathodic disbondment thresholds filter supplier pools aggressively.
- Construction:Structural steel protection in commercial and infrastructure projects favors lower-cost PVC and bituminous systems where field application labor dominates total cost.
- Electronics:Thin-gauge polyester and polyimide tapes with controlled outgassing properties serve PCB masking and component protection in high-reliability assemblies.
Construction absorbs the bulk of installed capacity; marine is climbing the fastest as offshore infrastructure ages.
End User:
Procurement authority and technical specification control vary dramatically across buyer types, reshaping go-to-market economics for tape suppliers.
- Manufacturers:Industrial OEMs with captive corrosion protection engineering teams specify tape systems at the design stage, locking in multi-year supply agreements. Automotive and heavy equipment producers qualify suppliers through 18-24 month validation cycles.
- Contractors:Engineering-procurement-construction firms bundle corrosion protection within total installed cost guarantees, compressing direct supplier margins while extending warranty liability periods.
- DIY Consumers:Retail channel buyers prioritize shelf price and immediate availability over certified performance data, concentrating volume with mass-market distributors.
- Transportation:Fleet operators and maintenance depots specify aftermarket corrosion protection for vehicle life extension, particularly in regions with aggressive road salt exposure.
Contractors absorb the bulk of installed capacity; manufacturers are gaining share fastest as OEM specification control tightens.
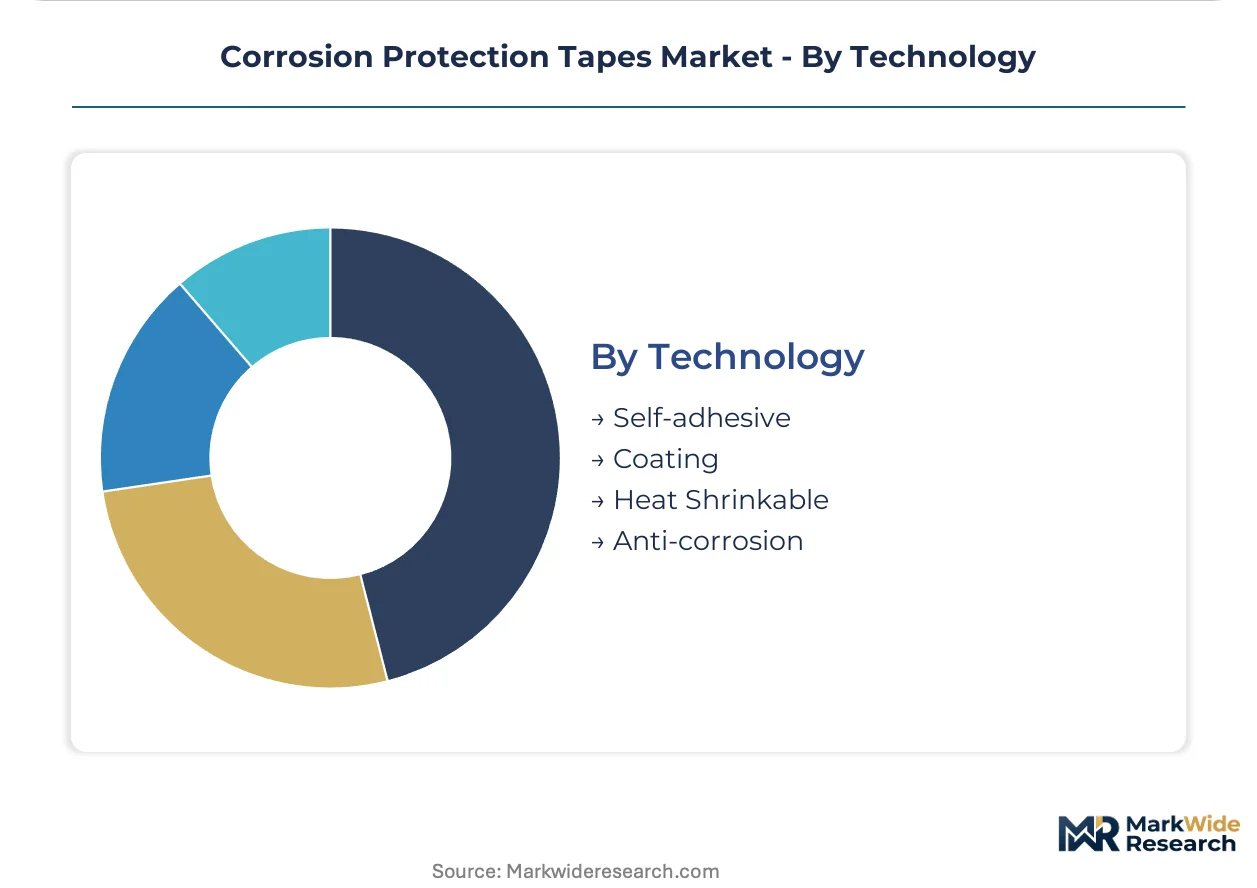
Technology:
Adhesive chemistry and application method determine labor productivity, field reliability, and regulatory compliance exposure across installation environments.
- Self-adhesive:Pressure-sensitive adhesive systems laminated to polymer backings enable rapid installation without curing time, dominating maintenance and repair applications where shutdown windows are constrained.
- Coating:Liquid-applied tape analogues and mastic systems conform to complex geometries but require surface preparation and skilled applicators, limiting use to specialized industrial settings.
- Heat Shrinkable:Cross-linked polyethylene sleeves that shrink-fit to substrate contours capture field joint protection in pipelines where factory-applied mainline coatings terminate.
- Anti-corrosion:VCI-impregnated films and vapor-phase inhibitor tapes protect ferrous metals in transit and storage without direct surface contact.
Self-adhesive absorbs the bulk of installed capacity; heat-shrinkable is expanding most quickly in pipeline rehabilitation applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones along the United States Gulf Coast petrochemical corridor concentrate tape demand through tax-advantaged processing capacity. Offshore pipeline operators in this zone face cascading replacement cycles as subsea infrastructure from the 1980s construction boom reaches end-of-design-life.
United States
EPA guidelines on volatile organic compound emissions from adhesive manufacturing constrain formulation choices for domestic producers. The Gulf Coast petrochemical corridor hosts the densest concentration of offshore pipeline maintenance activity. Houston-area distributors serve subsea rehabilitation contractors with solvent-free coating capabilities that qualify for major energy infrastructure contracts.
Germany
German automotive OEMs specify polyester backings for chassis protection tapes through 10-year accelerated aging protocols. REACH compliance mandates from ECHA force constituent chemical disclosure across three-tier supply chains. The Baden-Württemberg industrial cluster hosts precision coating lines serving exacting thickness tolerance requirements for underbody applications.
Japan
Japanese automotive OEMs validate butyl rubber adhesive formulations for critical sealing applications with exacting specifications. METI industrial standards shape qualification timelines for tape suppliers seeking multi-year supply agreements. The Nagoya-Toyota industrial corridor concentrates validation testing for corrosion protection systems in vehicle manufacturing.
India
The Petroleum and Natural Gas Regulatory Board pipeline expansion mandates open specification opportunities in historically underpenetrated geographies. BIS certification requirements filter supplier pools for infrastructure contractors. The Gujarat industrial corridor attracts blown film converters seeking to serve petrochemical infrastructure buildout with regional production capacity.
United Kingdom
North Sea offshore operators drive demand for cathodic protection compatibility in subsea tape specifications. HSE offshore safety regulations align with NORSOK M-503 standards for saltwater immersion resistance. Aberdeen's energy services cluster hosts field application contractors consolidating procurement authority through integrated service contracting models.
Corrosion Protection Tapes Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with tape backing production showing tighter consolidation than adhesive formulation. The vendor base organizes around three tiers: multinational polymer science conglomerates with captive extrusion assets, regional blown film converters serving price-sensitive construction channels, and niche specialists in subsea-certified systems. Two dominant competitive moves define current positioning: backward integration into resin compounding to secure margin predictability, and qualification-driven consolidation of supplier panels by European energy infrastructure contractors seeking audit burden reduction.
Among diversified industrial conglomerates, 3M Company and Nitto Denko Corp exemplify the polymer science archetype with in-house adhesive chemistry capabilities. Berry Global Inc. represents scale-driven blown film production serving multi-layer backing requirements. These three anchors demonstrate how captive manufacturing assets create competitive moats under tightening environmental compliance regimes.
| Leading Market Players |
|---|
| 3M Company |
| Nitto Denko Corp |
| Berry Global Inc. |
| Shurtape Technologies, LLC |
| Coroplast Fritz Müller GmbH & Co. KG |
| Scapa Group plc |
| W.W. Grainger Inc |
| Denso Tape |
| Polyken |
| Others |
Value Chain & Pricing Dynamics
Ethylene feedstock indices from the United States Gulf Coast petrochemical corridor cascade through blown film converter margins into three distinct pricing tiers for corrosion protection tape procurement. Spot polyethylene resin volatility compresses margin predictability for regional players while integrated producers with captive extrusion assets capture pricing power through supply security guarantees.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations as offshore pipeline operators face unplanned rehabilitation windows. Three-tier pricing structure across premium, standard, and economy levels stratifies by NACE SP0169 certification grade and ISO 21809 compliance depth. Cost compression in PVC-backed construction grades intensifies because Chinese import competition feeds spot inventory discounting. DIY retail channels exhibit highest price sensitivity while subsea contractors prioritize certified performance over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from European energy infrastructure contractors force tape laminators to qualify backup adhesive coating lines across multiple geographies. Supply concentrates in the United States, Germany, and China for blown film backing production. Raw material flows draw from Saudi ethylene crackers, South Korean specialty polymer compounding, and domestic resin extrusion. Single-source vulnerability concentrates around butyl rubber adhesive additives from Japanese chemical producers. Distribution runs through Houston-area distributors serving Gulf Coast petrochemical corridor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Butyl rubber adhesive formulations are displacing legacy asphalt-based compounds across subsea and chemical processing specifications, compressing market share for conventional tape systems. This technology-transition phase rewards producers with precision coating capabilities and captive polymer science assets.
For Market Incumbents: Extend qualification-driven supplier panel consolidation by accelerating REACH-compliant solvent-free coating investments. Defensive positioning requires backward integration into resin compounding to offset ethylene feedstock volatility. Certification depth at NACE International and ISO 21809 standards creates moats against epoxy coating substitution threats.
For New Entrants and Emerging Players: Solvent-free adhesive technology-first wedges open specification opportunities in European energy infrastructure contracting. White-space targets concentrate on Indian Petroleum and Natural Gas Regulatory Board pipeline expansion mandates and heat-shrinkable field joint protection systems. Go-to-market execution partners with engineering-procurement-construction firms bundling corrosion protection within total installed cost guarantees.
For Investors and Strategic Acquirers: Distressed-cycle entries favor precision coating specialists with NORSOK M-503 certification in the United Kingdom North Sea cluster. Long-term viability hinges on subsea infrastructure replacement demand extending across the analysis window. Acquisition screens prioritize adhesive chemistry capabilities and cathodic protection compatibility testing infrastructure. Watch subsea cathodic protection system end-of-design-life announcements as volume inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive ethylene supply secures margin predictability against Gulf Coast feedstock volatility. |
| Solvent-Free Coating Capacity Expansion | EPA VOC guideline compliance creates competitive moats for domestic producers. |
| NACE SP0169 Certification Investment | Qualification timelines filter supplier pools for major energy infrastructure contracts. |
| Heat-Shrinkable Sleeve Technology Licensing | Cross-linked polyethylene systems capture pipeline field joint protection white space. |
| Indian Manufacturing Joint Venture | Regional blown film capacity serves Petroleum and Natural Gas Regulatory Board mandates. |
Study Parameters
Multi-period observation of ethylene feedstock pricing, subsea pipeline maintenance expenditure patterns, and adhesive formulation patent filings anchored the trend analysis, supplemented by interviews with plant managers at blown film converters, procurement leads at downstream petrochemical operators, coating line technical directors, and EPC contractor corrosion protection specialists. Secondary validation drew from EPA VOC emission disclosures, ECHA REACH registration databases, NACE International certification records, and customs trade data for polyethylene resin flows. Bottom-up segment sizing triangulated against top-down energy infrastructure capital expenditure tracking.
Segment-weighting approaches applied differential growth assumptions across product type, application severity, and technology platform dimensions. Modeling incorporated polyethylene resin cost pass-through elasticity, regulatory compliance threshold effects, and subsea infrastructure age distribution curves. CAGRs were derived from installed base replacement cycles and specification migration patterns. Forecast inputs included cathodic protection system end-of-design-life schedules and solvent-free adhesive capacity buildout timelines.
Several conditions sit outside the modeled scope, including fusion-bonded epoxy coating substitution rates beyond pipeline new construction segments and geopolitical disruptions to ethylene feedstock trade flows. Forecasts reflect documented assumptions about REACH enforcement consistency and EPA guideline stability. Deviation in subsea rehabilitation budget allocation or adhesive chemistry innovation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Dimer Acid Market
Adhesives & Sealants
Europe Acrylic Adhesives Market
Adhesives & Sealants
Aviation Adhesives and Sealants Market
Adhesives & Sealants
Cycloaliphatic Epoxy Market
Adhesives & Sealants
Plastic Adhesives Market
Adhesives & Sealants
Thailand Sealants Market
Adhesives & Sealants
Asia-Pacific Laminated Adhesives Market
Adhesives & Sealants
Flock Binder Market
Adhesives & Sealants
Flooring Installation Adhesives Market
Adhesives & Sealants
North America Epoxy Curing Agents Market
Adhesives & Sealants
Global Automotive Adhesive Market
Adhesives & Sealants
Southeast Asia Adhesives and Sealants Market
Adhesives & Sealants
Metal Glue Market
Adhesives & Sealants
Lignin for Adhesives Market
Adhesives & Sealants
Gasket and Seal Material Market
Adhesives & Sealants
Central Reinforced Tape Market