
 Textile Adhesives Market | 2026-2036
Textile Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Adhesives Market Analytics
Specialized polymer chemist availability is unwinding capacity expansion plans across Asian manufacturing hubs. Henkel AG & Co. KGaA leverages its European R&D base to sustain leadership in reactive adhesive systems for automotive interiors. H.B. Fuller Company anchors North American supply through vertical control of hot melt resin sourcing. Sika AG competes in technical textiles by dominating polyurethane dispersion formulations for laminated fabrics.
Textile adhesives are polymeric bonding agents formulated from polyurethane, acrylic, or epoxy chemistries, applied at viscosities ranging from 500 to 50,000 cP depending on substrate porosity and end-use durability requirements. These materials permanently join textile layers without stitching, enabling seam sealing, lamination, and structural reinforcement in products where flexibility and wash resistance are critical. Water-based formulations now lead volume production due to tightened emissions rules, while reactive systems represent the fastest-expanding margin pool as technical textile specifications intensify. Hot melt adhesives occupy the mature, price-sensitive tier of footwear and furniture assembly, where fleece technology applications sustain steady replacement demand across high-volume producers.
EPA regulations in the United States restrict hazardous air pollutant emissions from adhesive coating operations, compelling solvent-based line conversions. ECHA's REACH framework in Europe mandates substance registration and restriction protocols that filter non-compliant imports from Asian suppliers. China's MEE enforces GB standards on VOC content that redirect domestic formulation priorities toward water-based and UV-curable platforms. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with diverging compliance costs and access conditions.
Market Dynamics
REACH compliance deadlines are forcing solvent-based formulation phase-outs across European coating operations, while China's GB standards redirect domestic production toward water-based platforms. This dual regulatory compression is restructuring supplier qualification requirements and regional production footprints simultaneously.
Growth Catalysts
- Automotive lightweighting mandates:German and Chinese OEMs are expanding bonded interior component specifications to reduce vehicle mass. Polyurethane reactive systems capture this specification pull.
- REACH substance restrictions:ECHA's expanding SVHC list filters non-compliant Asian imports, creating qualified-supplier premiums for compliant European manufacturers.
- Technical textile specifications:Medical and protective apparel manufacturers in East Asian clusters demand wash-resistant lamination bonding for multi-layer fabric assemblies.
Market Restraints
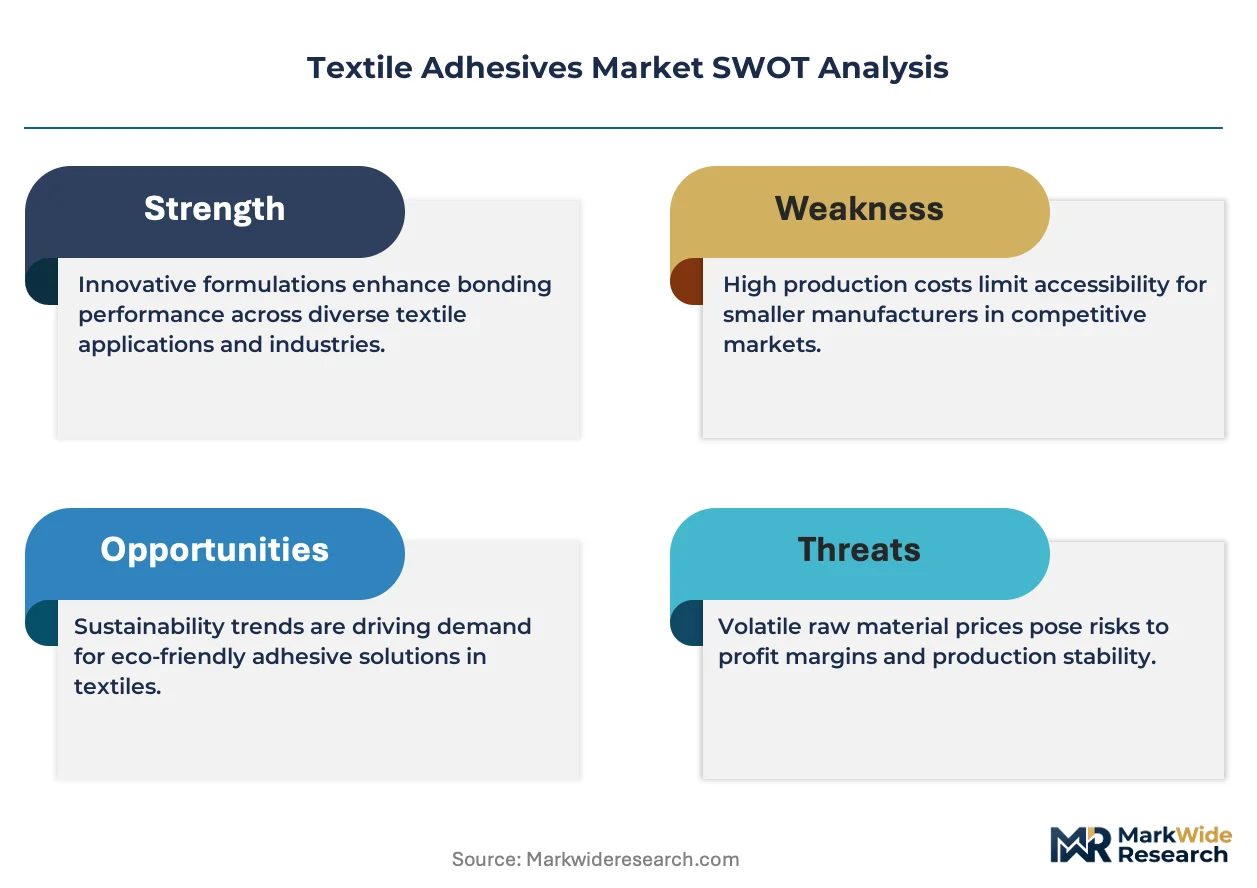
- Specialized polymer chemist scarcity:Formulation expertise concentration in Western Europe limits Asian capacity expansion timelines.
- Isocyanate feedstock volatility:Polyurethane precursor costs fluctuate with crude-linked propylene oxide and MDI pricing.
- Hot melt commoditization:EVA and polyolefin-based footwear adhesives face price compression from Chinese resin oversupply.
Strategic Opportunities
- UV-curable platform expansion:China's MEE enforcement of VOC thresholds creates first-mover advantage for radiation-cured textile coating systems.
- Medical textile lamination:Biocompatible adhesive demand for surgical gowns and drapes outpaces qualified supplier capacity in South Korea and Taiwan.
- Recyclable fabric bonding:EU Green Deal circular economy requirements favor debondable adhesive chemistries for end-of-life textile separation.
Industry Challenges
- Formulation-to-line integration complexity:Water-based viscosity adjustments require recalibration of existing roll-coating and slot-die equipment.
- REACH registration timelines:New substance notifications extend product commercialization cycles by 18-24 months for novel polymer architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Adhesives Market |
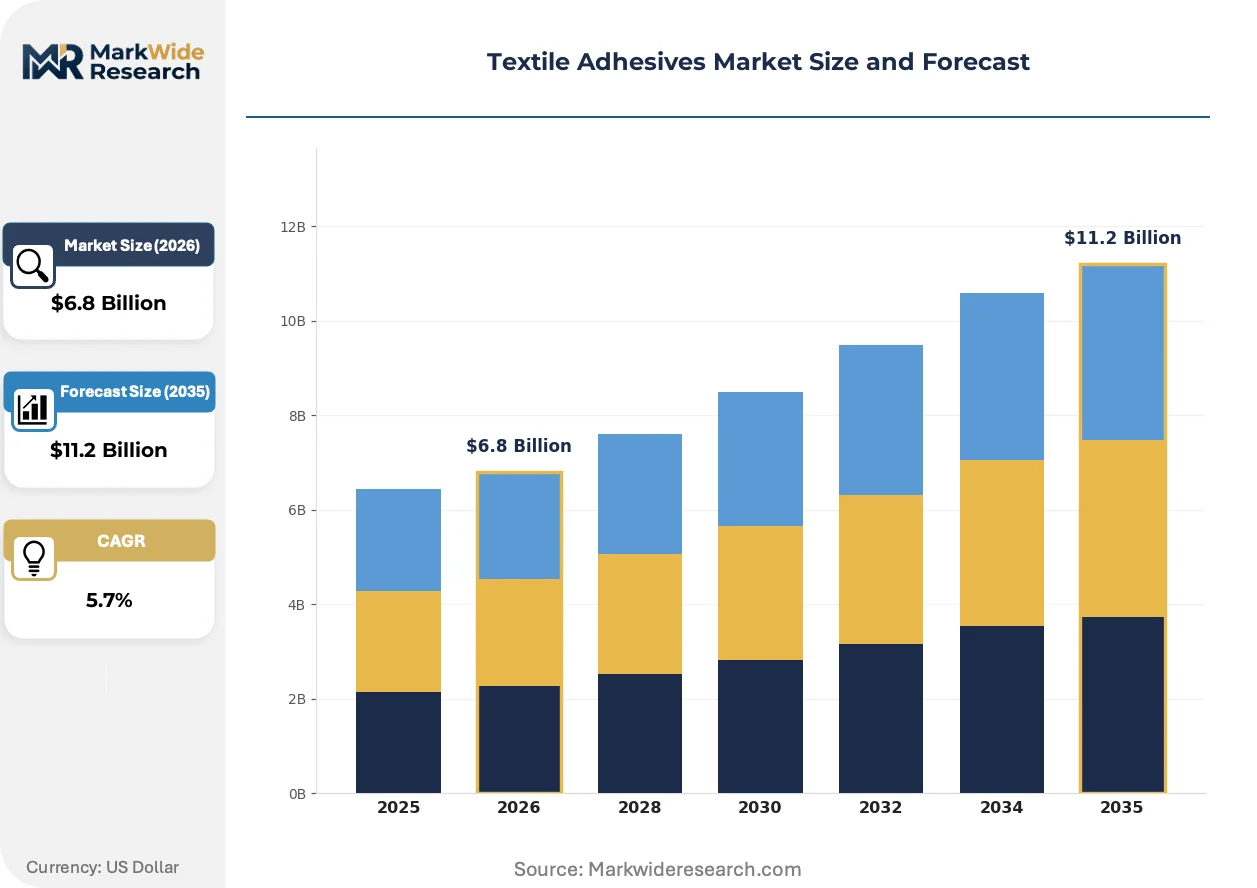
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Reactive Application: Footwear, Automotive Interiors, Upholstery, Technical Textiles End User: Textile Manufacturers, Footwear Producers, Automotive OEMs, Furniture Makers Technology: Fleece Technology, Spray Technology, Roll Coating, Liquid Dispensing |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, Sika AG, Arkema, Bostik, 3M Company, Huntsman Corporation, Avery Dennison Corporation, Pidilite Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Adhesives Market Evolving Landscape
Reactive adhesive platforms are capturing specification share from conventional thermoplastic systems as durability requirements intensify across technical textile end-uses. Three convergent developments are restructuring competitive positioning and investment priorities.
Water-based polyurethane dispersions are supplanting solvent-borne coating systems in automotive interior lamination. Tier-1 seating suppliers in Germany and China specify these platforms to meet OEM sustainability scorecards without sacrificing peel strength. The shift is compressing solvent-based capacity utilization rates while expanding regional formulation tolling demand.
EPA hazardous air pollutant standards for coating operations are compelling US-based textile finishers to convert solvent lines. The rule's MACT compliance deadlines force capital deployment into thermal oxidizers or aqueous system retrofits. Southern US upholstery manufacturing clusters face the steepest reconfiguration costs due to aged facility infrastructure.
Certification-driven supplier consolidation is compressing qualified vendor lists among European protective apparel brands. Buyers now require simultaneous OEKO-TEX Standard 100 and bluesign approval, filtering regional coating houses without dedicated compliance staff. This preference shift favors integrated polymer producers with captive testing laboratories over independent toll coaters.
Textile Adhesives Market Segmentation
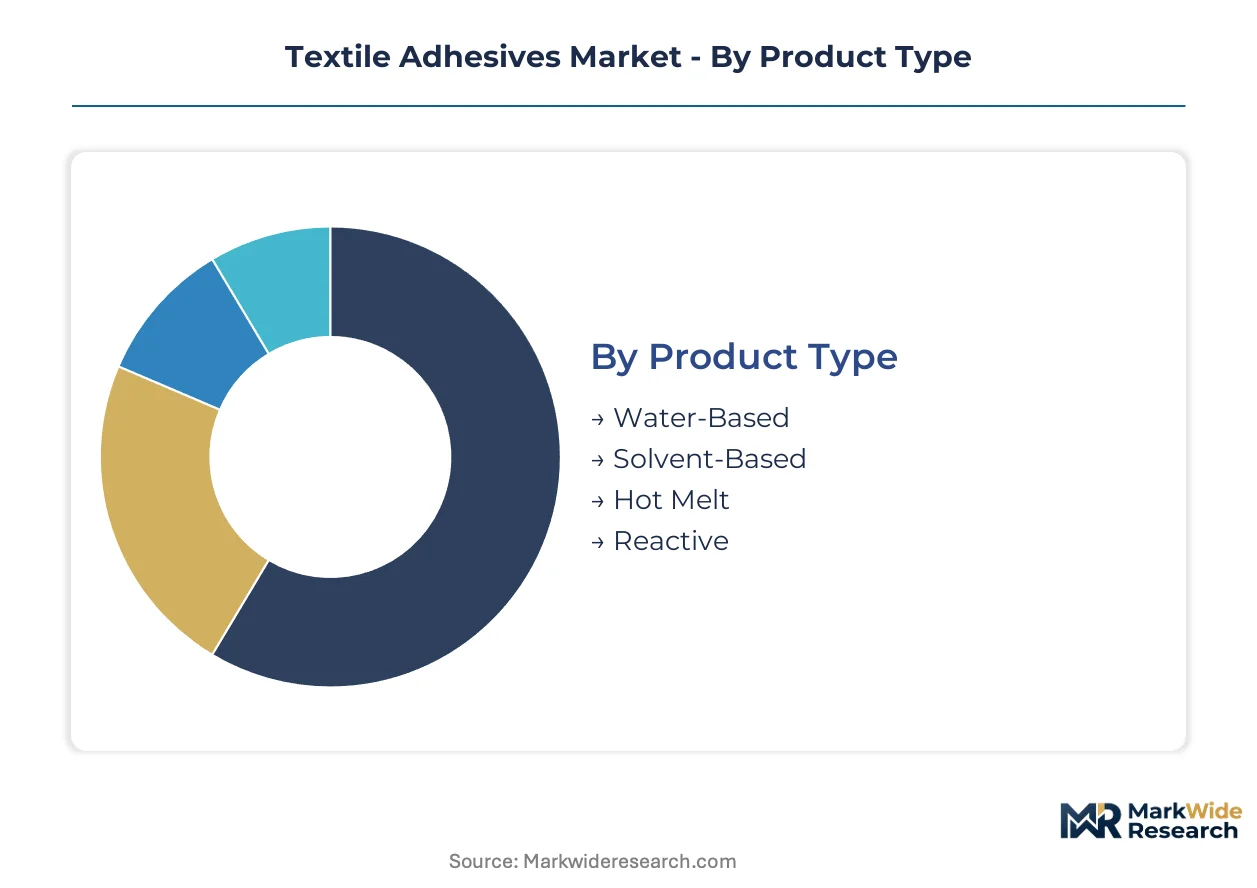
Textile adhesive specifications diverge sharply across end-use durability requirements and regional emissions compliance, forcing suppliers to maintain parallel formulation portfolios. Segmentation clarity enables buyers to match bonding chemistry with substrate porosity, wash cycles, and regulatory jurisdiction.
Product Type:
REACH substance restrictions and China's GB standards are bifurcating formulation investment between aqueous platforms and reactive systems.
- Water-Based:Polyurethane and acrylic dispersions suspended in aqueous carriers, applied at 1,000–15,000 cP for porous textile lamination. German and Chinese automotive seating suppliers specify these systems to meet OEM sustainability scorecards without sacrificing peel strength.
- Reactive:Two-component polyurethane or epoxy systems that cure through chemical crosslinking, delivering superior wash resistance and heat stability. Medical and protective apparel manufacturers in South Korea and Taiwan demand these platforms for multi-layer fabric assemblies subject to sterilization cycles.
- Solvent-Based:Traditional solutions of synthetic rubbers or polyurethanes in organic carriers, now contracting under EPA hazardous air pollutant enforcement and ECHA SVHC filtering.
- Hot Melt:Thermoplastic EVA and polyolefin formulations applied molten for immediate tack, dominating footwear and furniture assembly where price sensitivity overrides durability specifications.
Water-based formulations handle the majority of throughput; reactive systems are climbing the fastest on specification share.
Application:
Cost tier segmentation separates specification-driven automotive and medical applications from volume-driven footwear and furniture markets.
- Automotive Interiors:Bonded headliners, door panels, and seating assemblies requiring fogging resistance and VOC compliance. German OEMs and Chinese joint-venture plants are expanding bonded component specifications to reduce vehicle mass.
- Technical Textiles:Laminated fabrics for surgical gowns, protective suits, and industrial filtration media. East Asian manufacturing clusters in Taiwan and South Korea concentrate demand for wash-resistant multi-layer bonding.
- Footwear:Upper-to-sole attachment and insole lamination, where hot melt and water-based systems compete on production line speed and material cost.
- Upholstery:Residential and contract furniture fabric-to-foam bonding, with Southern US manufacturing clusters facing steep EPA MACT compliance costs for solvent line conversions.
Automotive interiors command the highest formulation premiums; technical textiles are expanding most quickly on qualified-supplier capacity constraints.
End User:
Customer type determines procurement sophistication, with automotive OEMs imposing the most stringent qualification protocols.
- Automotive OEMs:Tier-1 seating and interior component suppliers in Germany and China specify adhesive platforms through approved vendor lists with captive laboratory testing requirements.
- Textile Manufacturers:Lamination houses and coating operations serving apparel and industrial fabric markets, increasingly consolidated under certification-driven supplier filtering.
- Footwear Producers:High-volume assembly operations in Vietnam and Indonesia sourcing hot melt and water-based systems through distributor networks.
- Furniture Makers:Upholstery manufacturers balancing adhesive cost with flame retardancy and emissions compliance for residential and hospitality end markets.
Automotive OEMs drive the most demanding specification evolution; textile manufacturers represent the broadest addressable base.
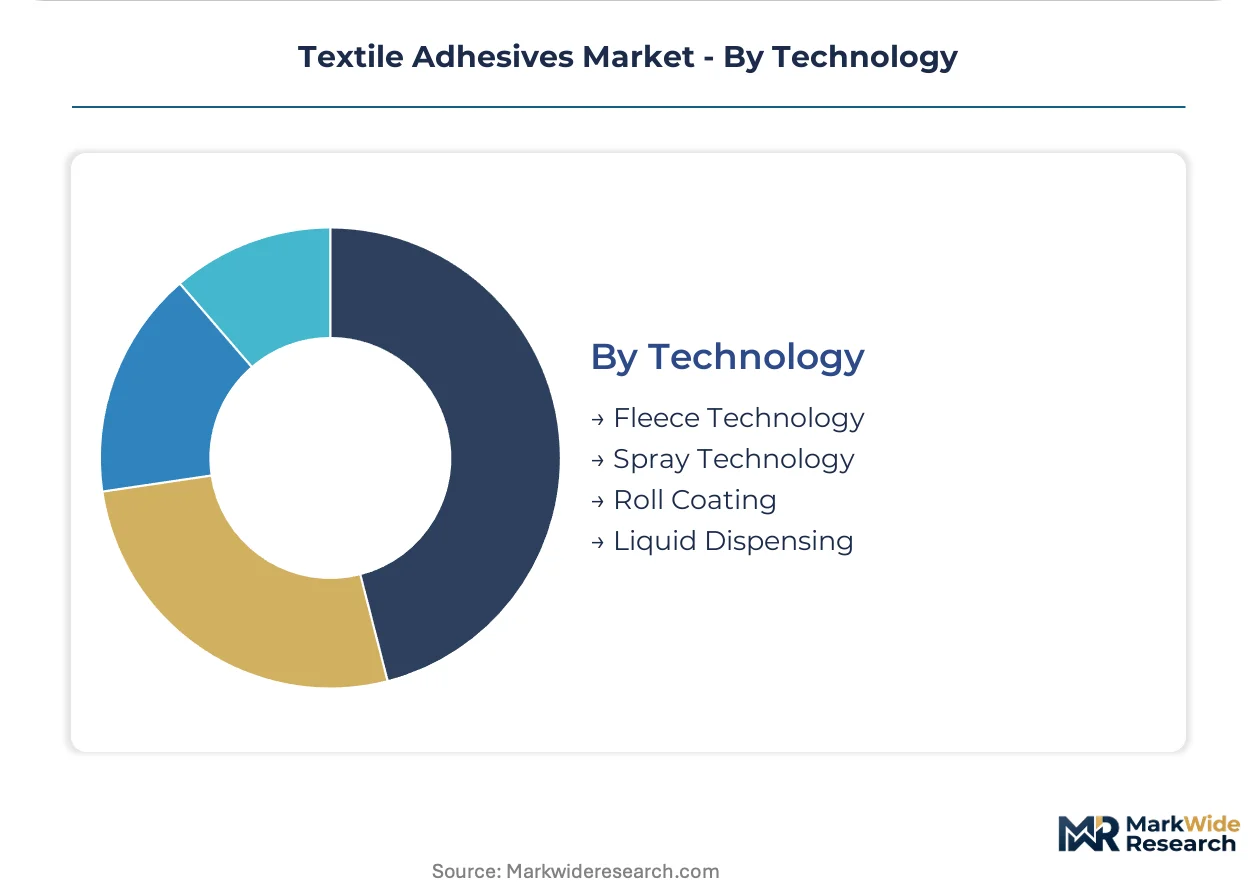
Technology:
Application method selection constrains viscosity range and curing chemistry, with roll coating and spray platforms diverging on capital intensity and throughput.
- Roll Coating:Precision-metered adhesive transfer through engraved cylinders, dominant in automotive interior lamination and technical textile coating where thickness uniformity is critical.
- Spray Technology:Atomized adhesive application for complex three-dimensional substrates, specified in footwear assembly and furniture contour bonding.
- Fleece Technology:Powder or fiber adhesive pre-applied to carrier webs for heat-activated bonding, sustaining steady replacement demand in high-volume footwear and furniture lines.
- Liquid Dispensing:Programmable robotic application of reactive systems for automotive component assembly, requiring integration with curing oven infrastructure.
Roll coating handles the majority of precision lamination volume; liquid dispensing is gaining share fastest on automotive automation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH framework anchors European compliance architecture, filtering non-compliant imports and creating qualified-supplier premiums for compliant manufacturers across the continent.
United States
EPA hazardous air pollutant standards compel solvent-based line conversions across Southern upholstery manufacturing clusters. MACT compliance deadlines force capital deployment into thermal oxidizers or aqueous system retrofits. Aged facility infrastructure in Georgia and North Carolina faces the steepest reconfiguration costs as coating operations modernize.
Germany
Automotive OEMs expand bonded interior component specifications to reduce vehicle mass. Tier-1 seating suppliers specify water-based polyurethane dispersions to meet sustainability scorecards without sacrificing peel strength. Stuttgart and Wolfsburg manufacturing corridors concentrate specification pull for reactive adhesive systems.
China
MEE enforcement of GB standards on VOC content redirects domestic formulation priorities toward water-based and UV-curable platforms. Joint-venture automotive plants in Shanghai and Changchun adopt bonded component specifications aligned with German OEM sustainability protocols. Yangtze River Delta coating houses face compressed solvent-based capacity utilization.
South Korea
Medical and protective apparel manufacturers demand wash-resistant lamination bonding for multi-layer fabric assemblies. MFDS biocompatibility requirements filter adhesive qualification for surgical gown and drape applications. Gyeonggi-do and Daegu-Gyeongbuk clusters concentrate technical textile lamination capacity subject to sterilization cycle specifications.
Taiwan
Certification-driven supplier consolidation compresses qualified vendor lists among protective apparel brands. OEKO-TEX Standard 100 and bluesign approval requirements filter regional coating houses without dedicated compliance staff. Taichung and Tainan manufacturing zones face preference shifts toward integrated polymer producers with captive testing laboratories.
Textile Adhesives Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the textile adhesives market. European chemical conglomerates and North American adhesive specialists dominate premium formulation segments through captive R&D infrastructure and backward integration into resin supply. Three archetypes define competitive positioning: integrated polymer producers with vertical control over feedstock, regional formulation specialists serving toll-coating demand, and diversified chemical houses leveraging cross-sector technology transfer. Capacity expansion and certification-driven supplier consolidation represent the dominant competitive moves reshaping vendor relationships.
Within the integrated polymer tier, Henkel AG & Co. KGaA and H.B. Fuller Company exemplify divergent geographic anchoring strategies. Henkel occupies a position representing European R&D-centric reactive system leadership, while H.B. Fuller anchors North American supply chain resilience through upstream control of hot melt resin sourcing. Sika AG sits within the specialty chemical archetype, dominating polyurethane dispersion formulations for laminated fabrics through technical textile-focused positioning.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Sika AG |
| Arkema |
| Bostik |
| 3M Company |
| Huntsman Corporation |
| Avery Dennison Corporation |
| Pidilite Industries Limited |
| Others |
Value Network & Pricing Analysis
REACH substance restrictions gate both supplier qualification and price differentiation simultaneously, filtering non-compliant Asian imports while creating qualified-supplier premiums for European manufacturers with captive laboratory infrastructure. OEM sustainability scorecards and certification requirements stratify the vendor base into compliance tiers that command divergent formulation premiums.
Pricing Analysis
Geographic price spreads widen between European qualified suppliers and Asian toll coaters, with Stuttgart and Wolfsburg corridors paying premiums for OEKO-TEX and bluesign-certified water-based polyurethane systems. Three-tier pricing structure across premium reactive systems, standard water-based platforms, and economy hot melt grades reflects certification grade and volume scale differentiation. Cost compression in footwear EVA adhesives intensifies because Chinese resin oversupply erodes margins. Furniture makers exhibit highest price sensitivity, while automotive OEMs absorb formulation premiums for VOC compliance.
Supply Chain Analysis
Isocyanate feedstock transit through Rotterdam and Shanghai ports underwrites polyurethane adhesive cost structures across European and Asian manufacturing hubs. Supply concentrates in Germany, China, and South Korea for formulated systems, with propylene oxide and MDI precursors drawing from Gulf Coast and Northeast Asian petrochemical complexes. Single-source vulnerability in specialized polymer chemist talent pools constrains Asian capacity expansion timelines. Distribution runs through Tier-1 seating supplier approved vendor lists with captive laboratory testing requirements, filtering independent toll coaters from automotive specification chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise scarcity in polymer chemistry constrains capacity expansion timelines, with qualified reactive system specialists concentrated in Western European R&D clusters. This capability gap creates structural premiums for incumbents while raising barriers for Asian manufacturing scale-up.
For Market Incumbents: Fortify backward integration into isocyanate and acrylic resin supply to offset propylene oxide volatility. Expand captive testing laboratories in Stuttgart and Wolfsburg corridors to capture OEM specification pull for bonded interior components. Defend against emerging UV-curable specialists by accelerating water-based platform certifications ahead of China's MEE enforcement deadlines. For New Entrants and Emerging Players: Bluesign fast-track approval opens qualified-supplier positioning in European protective apparel markets currently filtered by OEKO-TEX Standard 100 requirements. Target medical textile lamination in South Korea's Gyeonggi-do cluster where MFDS biocompatibility requirements outpace qualified supplier capacity. Lead with UV-curable platform demonstrations for Yangtze River Delta coating houses facing compressed solvent-based utilization. For Investors and Strategic Acquirers: ECHA's expanding SVHC list reshapes the acquisition landscape toward compliant European manufacturers with REACH registration portfolios. Long-term viability favors integrated polymer producers with backward resin control and certification infrastructure over independent toll coaters. Watch for isocyanate feedstock volatility spikes as inflection indicators for margin compression in polyurethane-dependent formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive isocyanate sourcing insulates Henkel and H.B. Fuller from propylene oxide volatility. |
| Certification Laboratory Expansion | In-house OEKO-TEX and bluesign testing accelerates European protective apparel supplier qualification. |
| UV-Curable Platform Development | Radiation-cured systems capture first-mover advantage under China's MEE VOC threshold enforcement. |
| Reactive System Capacity Addition | Two-component polyurethane expansion serves South Korean medical textile sterilization cycle specifications. |
| Joint Venture with Tier-1 Seating Suppliers | Approved vendor list integration locks in German and Chinese automotive interior specification share. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with adhesive formulators, automotive Tier-1 procurement directors, textile coating plant managers, and regulatory compliance officers; and secondary validation through ECHA SVHC registrations, EPA MACT compliance filings, Chinese GB standard updates, and customs trade flows. Primary interviews covered formulation R&D heads at integrated polymer producers and independent toll coating operations across German, Chinese, and South Korean manufacturing clusters. Bottom-up volume estimates from application-level consumption patterns triangulated against top-down chemical industry production data.
Across the analysis window, the forecast framework modeled segmentation dimensions including product chemistry type, end-use durability tier, application method viscosity requirements, and regional regulatory compliance cluster. CAGRs derived from weighted average growth contributions across automotive lightweighting mandates, technical textile specification intensification, and solvent-based formulation phase-out timelines. Industry-specific inputs incorporated isocyanate feedstock price elasticity, REACH registration pipeline status, and automotive OEM bonded component specification adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement, continued automotive lightweighting mandates, or stable crude-linked propylene oxide pricing would require recalibration. Forecasts reflect documented assumptions about regulatory timeline adherence and specification pull-through rates. Practitioners should keep alternative scenarios live as ECHA SVHC list expansion pace and China's MEE inspection intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
High Temperature Sealants Market
Adhesives & Sealants
American Epoxy Adhesives Market
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
Saudi Arabia Sealants Market
Adhesives & Sealants
Adhesives and Sealants for Handheld Devices Market
Adhesives & Sealants
Asia-Pacific Adhesives Market
Adhesives & Sealants
Europe Chemical Anchors Market
Adhesives & Sealants
Moisture Curing Adhesives Market
Adhesives & Sealants
North America Automotive Adhesives and Sealants Market
Adhesives & Sealants
United States Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
South America Adhesives and Sealants Market
Adhesives & Sealants
Lead Encapsulants Market
Adhesives & Sealants
UV-Curable Adhesives Market
Adhesives & Sealants
South America Adhesives Market
Adhesives & Sealants
Leather Glue Market
Adhesives & Sealants
Ocular Sealants and Glues Market