
 Metal Bonding Adhesives Market | 2026-2036
Metal Bonding Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Bonding Adhesives Market Analysis
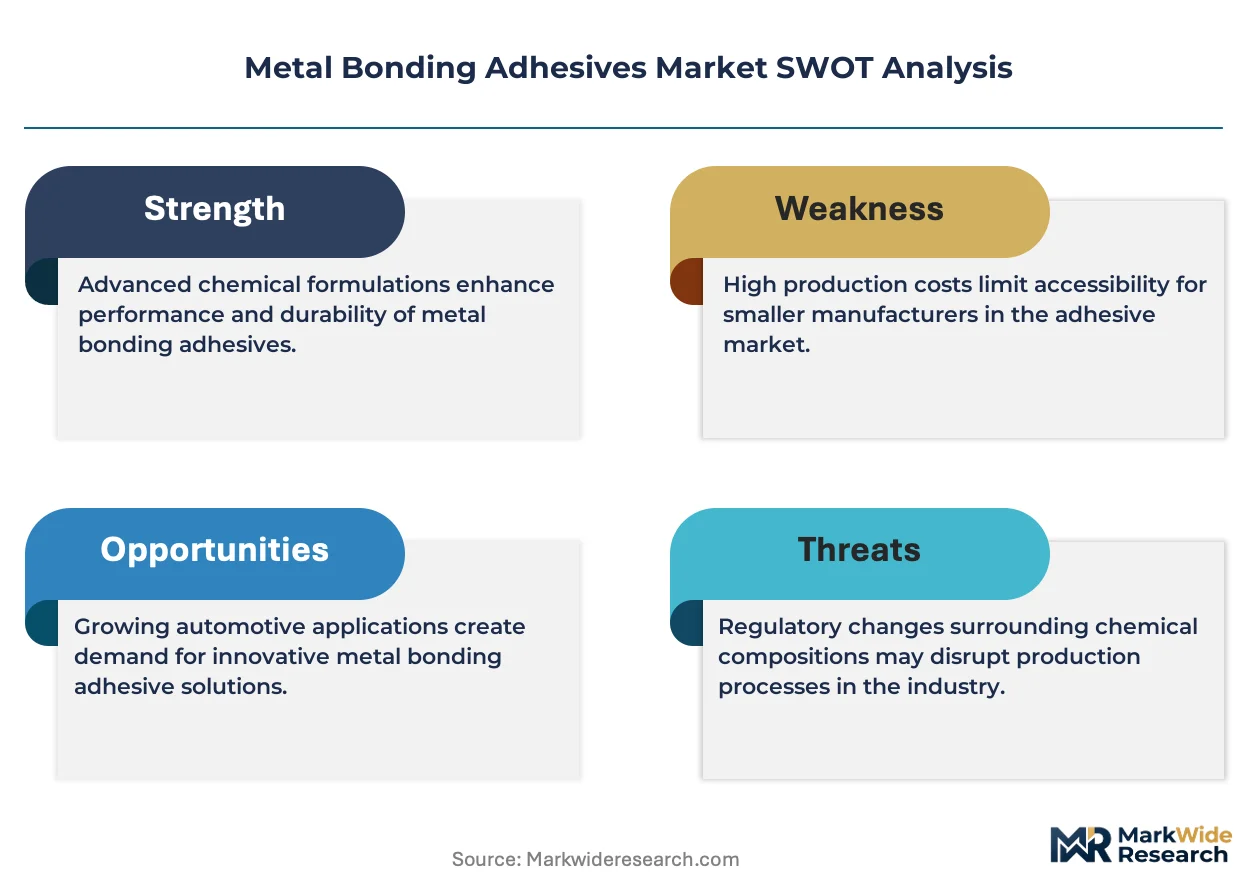
The EU Green Deal is realigning procurement priorities across European metal bonding supply chains, pushing formulators toward low-VOC and bio-based chemistries. Henkel AG & Co. KGaA leverages its European manufacturing footprint to supply REACH-compliant epoxy systems to automotive OEMs. 3M Company sustains technology leadership in acrylic structural tapes for aerospace panel bonding. Sika AG anchors its position through specialized polyurethane formulations for construction metal-to-concrete applications.
Metal bonding adhesives are engineered polymer systems formulated to create structural or semi-structural joints between metallic substrates, typically achieving lap shear strengths exceeding 15 MPa through chemical crosslinking or physical curing mechanisms. These materials replace welding, riveting, and mechanical fastening in applications where thermal distortion, galvanic corrosion, or weight reduction must be avoided. Epoxy resins dominate structural bonding applications where maximum load-bearing capacity and chemical resistance justify longer cure cycles. Polyurethane systems capture growth in assembly operations requiring flexibility and impact resistance across temperature extremes. Water-based technologies are displacing solvent-based alternatives in surface treatment and coating applications as environmental compliance tightens across manufacturing jurisdictions.
REACH in Europe, EPA regulations in the United States, and China's MEE emission standards collectively restrict volatile organic compound content in adhesive formulations, forcing reformulation investments and reshaping competitive access. EMA and FDA scrutiny of chemical constituents in medical and food-contact metal assemblies further narrows approved substance lists for suppliers serving regulated end-uses. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance-driven market exclusion or stranded inventory positions.
Market Dynamics
REACH-compliant epoxy formulations are restructuring European automotive supply chains as OEMs eliminate mechanical fasteners to meet EU Green Deal emissions targets. This regulatory compression is accelerating reformulation investments and redrawing competitive access across metal bonding adhesive markets.
Growth Catalysts
- EU Green Deal mandates:Aerospace manufacturers in Germany and France are expanding adhesive use for lightweight fuselage assembly to reduce fuel consumption and emissions.
- Electric vehicle battery enclosure bonding:Automotive OEMs require structural adhesives for aluminum-intensive battery trays that resist thermal runaway propagation.
- Water-based surface treatment technologies:Environmental compliance tightening across manufacturing jurisdictions is displacing solvent-based alternatives in metal pretreatment applications.
Market Restraints
- Raw material concentration:Specialty epoxy resin supply concentrates in Asian petrochemical complexes, exposing formulators to shipping cost volatility and geopolitical disruption.
- Cure cycle limitations:Heat-cured structural adhesives require capital-intensive oven infrastructure incompatible with just-in-time assembly sequences.
- Substrate preparation complexity:Aluminum oxide layer removal and anodizing protocols add process steps that mechanical fastening avoids entirely.
Strategic Opportunities
- India automotive localization:PLI scheme incentives for domestic electric vehicle manufacturing create demand for localized adhesive formulation capacity.
- Room-temperature curing anaerobics:Convergence of acrylic chemistry with activator systems eliminates thermal processing for small-diameter fastener replacement.
- Medical device metal bonding:FDA and EMA scrutiny of implantable device biocompatibility creates premium positioning for ISO 10993-certified adhesive grades.
Industry Challenges
- Adhesive joining specialist shortage:Industrial engineering programs emphasize welding certification over polymer bonding process design, constraining workforce availability.
- Multi-jurisdictional compliance timelines:Divergent substance restrictions between REACH, EPA, and China's MEE standards force parallel formulation tracks and stranded inventory risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Bonding Adhesives Market |
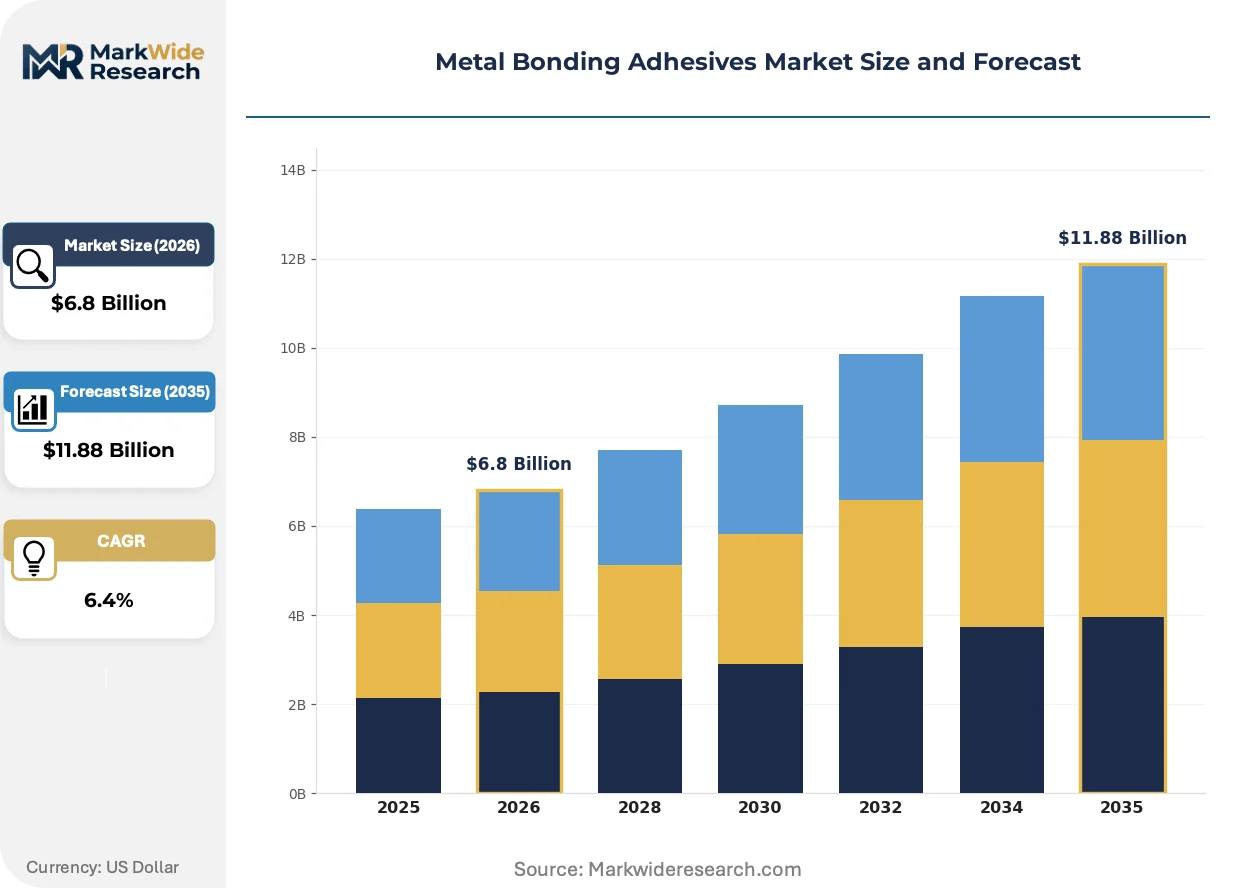
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Silicone End User: Aerospace, Automotive, Electronics, Construction Application: Structural Bonding, Assembly, Surface Treatment, Coating Technology: UV Curing, Heat Curing, Solvent-based, Water-based |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, Sika AG, H.B. Fuller Company, LORD Corporation, Arkema Group, BASF SE, Dow, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Bonding Adhesives Market Emerging Trajectories
Formulation chemistry is pivoting toward bio-based feedstocks and accelerated cure systems as regulatory pressure and assembly throughput requirements intensify simultaneously across metal bonding markets.
Two-part structural acrylic adhesives are overtaking epoxy systems in automotive body-in-white applications where 30-second fixture times enable robotic assembly sequences. Tier 1 suppliers in Germany and the United States are retrofitting production lines for these chemistries. This transition is compressing the viable cure window for conventional heat-cured alternatives.
REACH substance restriction amendments are forcing bisphenol A displacement in food-contact metal packaging adhesives. ECHA evaluations of endocrine-disrupting properties triggered reformulation deadlines in 2024-2025. European can manufacturers are accelerating migration to alternative epoxy novolac systems ahead of authorization sunset dates.
Automotive OEMs are consolidating adhesive specifications to reduce SKU complexity and leverage volume pricing. Tier 2 suppliers face qualification barriers as buyer concentration intensifies. This consolidation is most visible in Germany's automotive supply belt, where Volkswagen Group and BMW AG have reduced approved adhesive vendor lists by 40% since 2022.
Metal Bonding Adhesives Market Segmentation
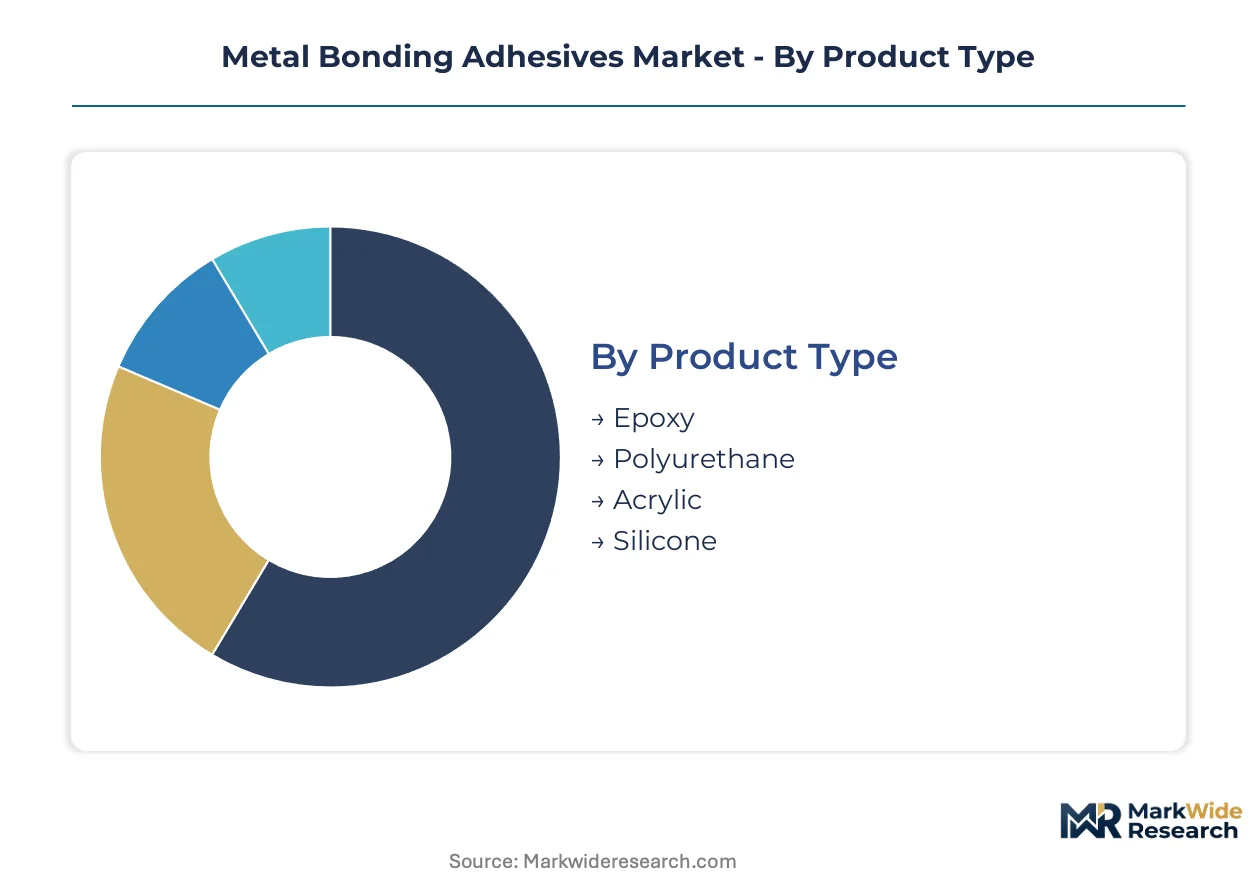
Metal bonding adhesive procurement varies sharply by load-bearing requirements, cure speed demands, and regulatory exposure. Buyers select chemistries based on thermal cycling tolerance, substrate compatibility, and compliance constraints specific to their end-use jurisdiction.
Product Type:
Buyers in this category differentiate primarily by cure cycle length and load-bearing capacity relative to assembly throughput constraints.
- Epoxy:Two-part thermosetting systems achieve lap shear strengths exceeding 25 MPa through covalent crosslinking of epoxide groups with amine hardeners. Automotive OEMs in Germany specify these grades for aluminum battery tray bonding where thermal runaway resistance is mandatory. REACH-compliant bisphenol A alternatives are displacing legacy formulations in European food-contact applications.
- Polyurethane:Isocyanate-terminated prepolymers cure through moisture or polyol reaction to form flexible elastomeric bonds with excellent impact absorption. Construction contractors in France favor these systems for steel-to-concrete facade anchoring where substrate movement tolerance outweighs maximum strength requirements. Cold-weather cure capability extends the application window in Nordic climates.
- Acrylic:Methacrylate ester formulations fixture in 30-90 seconds through radical polymerization initiated by surface activators. Tier 1 automotive suppliers retrofit body-in-white lines for these chemistries.
- Silicone:Room-temperature vulcanizing systems maintain flexibility across temperature extremes from -60°C to 200°C. Electronics manufacturers specify these for thermal management in power module assemblies.
Epoxy leads volumes today; acrylic is gaining share fastest.
End User:
Regulatory stringency and liability exposure create distinct procurement patterns across buyer categories.
- Aerospace:OEMs in France and Germany specify film adhesives and paste syntactics for primary structure bonding per EASA CS-25 certification requirements. EU Green Deal emissions targets drive fuselage lightweighting through adhesive-intensive monocoque designs replacing riveted joints.
- Automotive:Battery enclosure bonding demands structural adhesives with 15+ MPa shear strength and dielectric properties that resist arc propagation during thermal events. OEMs consolidate approved vendor lists to leverage volume pricing.
- Electronics:Miniaturized assemblies require electrically conductive and thermally conductive formulations for EMI shielding and heat dissipation. FDA and EMA scrutiny of implantable devices narrows approved substance lists.
- Construction:Structural glazing and curtain wall anchoring specify high-modulus silicones and hybrid polyurethanes with 50-year durability warranties. German facade engineers prioritize ETAG 002-certified systems.
Automotive commands the largest revenue pool; aerospace is expanding most quickly.
Application:
Process integration requirements and capital equipment intensity separate buyer priorities in this dimension.
- Structural Bonding:Primary load-bearing joints replace welding and mechanical fasteners in safety-critical assemblies. Cure cycle length directly determines line throughput and oven capital requirements.
- Assembly:Secondary joining operations prioritize speed and fixture time over ultimate strength. Two-part acrylics dominate where robotic dispensing enables 30-second handling strength.
- Surface Treatment:Water-based pretreatment chemistries displace solvent-based conversion coatings as EPA and MEE emission standards tighten. Chrome-free formulations are mandatory in EU automotive supply chains.
- Coating:Protective and decorative films require adhesion promoters compatible with powder coat and liquid paint systems. Can manufacturers migrate to bisphenol A-free epoxy novolacs ahead of ECHA authorization deadlines.
Structural bonding generates premium pricing; surface treatment is climbing the fastest.
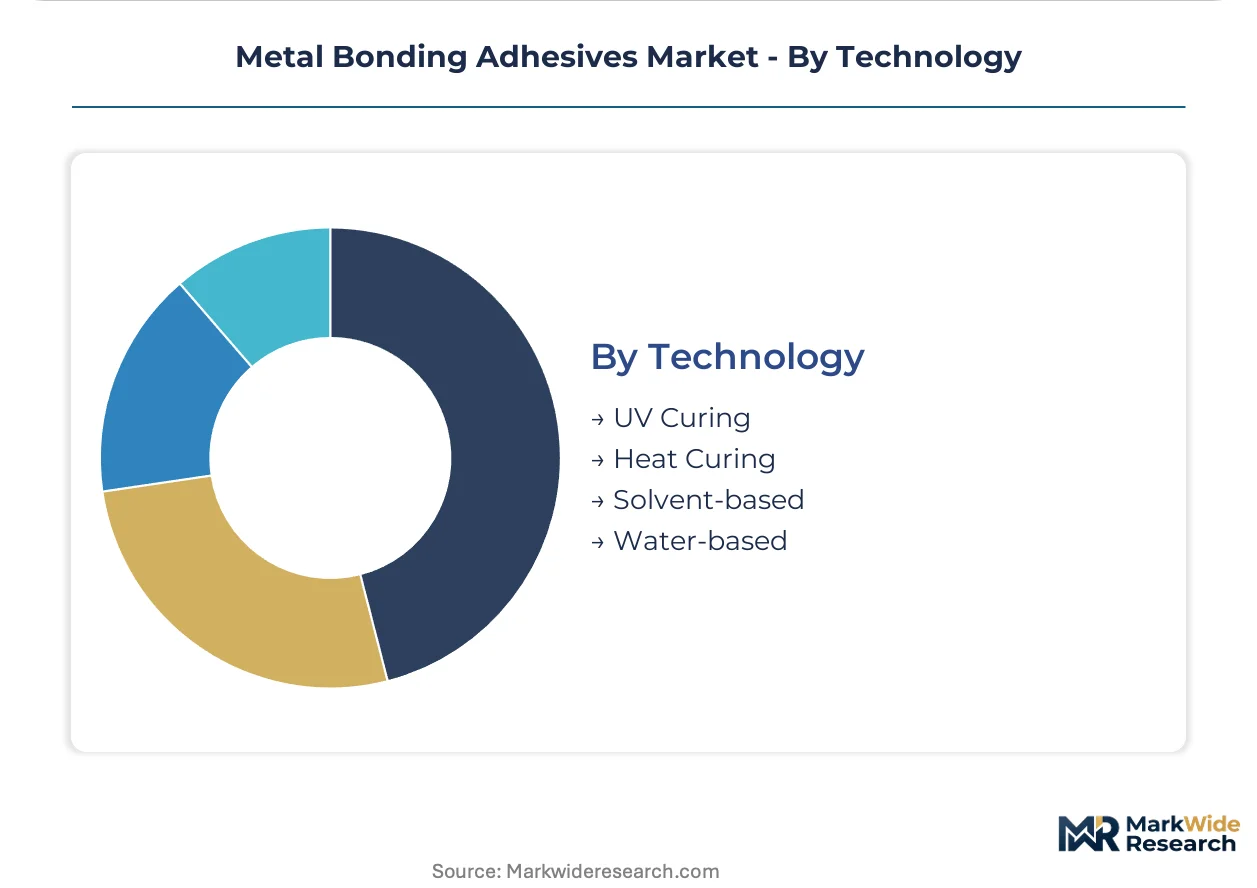
Technology:
Energy consumption and floor space requirements drive technology selection in capital-constrained environments.
- UV Curing:Photoinitiator-activated acrylates polymerize in seconds under 365-405 nm LED arrays. Electronics manufacturers specify these for transparent substrate bonding where line-of-sight cure is feasible.
- Heat Curing:Elevated temperature activation achieves full property development in epoxy and phenolic systems. Automotive battery tray bonding requires 120-180°C cure cycles incompatible with just-in-time sequences.
- Solvent-based:Organic carrier systems enable low-viscosity application and extended open times. REACH and EPA restrictions are forcing reformulation investments and capacity obsolescence.
- Water-based:Aqueous dispersions reduce VOC emissions and fire hazards in high-throughput operations. Surface treatment applications in Germany and the United States accelerate migration to these systems.
Heat curing retains the largest installed base; UV curing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered structural adhesive bonding for automotive lightweighting in the 1980s, establishing technical protocols that now dominate European OEM specifications. This engineering heritage shapes procurement patterns across the continent.
Germany
BMW AG and Volkswagen Group consolidate approved adhesive vendor lists by 40% since 2022, prioritizing REACH-compliant epoxy systems for aluminum battery tray bonding. The KBA enforces strict chemical substance reporting for automotive assemblies. Bavarian suppliers in the Munich-Stuttgart corridor retrofit production lines for two-part acrylic chemistries with 30-second fixture times.
France
Airbus SE expands adhesive-intensive monocoque fuselage designs at Toulouse and Hamburg facilities to meet EU Green Deal emissions targets. EASA CS-25 certification requirements govern primary structure bonding specifications. The Auvergne-Rhône-Alpes cluster hosts specialty film adhesive manufacturing for aerospace panel applications.
United States
Electric vehicle manufacturers demand structural adhesives with dielectric properties resisting thermal runaway propagation in battery enclosures. EPA emission standards accelerate water-based surface treatment migration across automotive supply chains. Michigan-based Tier 1 suppliers qualify new adhesive grades for robotic body-in-white assembly sequences.
China
Domestic electric vehicle production under dual carbon goals drives demand for localized adhesive formulation capacity. MEE emission standards restrict VOC content in manufacturing operations. Yangtze River Delta petrochemical complexes concentrate specialty epoxy resin supply, exposing formulators to shipping cost volatility.
India
PLI scheme incentives for domestic electric vehicle manufacturing create demand for battery enclosure bonding technologies. BIS certification requirements shape adhesive qualification protocols for automotive OEMs. Tamil Nadu and Gujarat automotive clusters attract formulation facility investments from multinational suppliers.
Metal Bonding Adhesives Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across formulation chemistry and application equipment segments. The market structures around three tiers: multinational chemical conglomerates with integrated resin supply, specialized adhesive formulators with deep OEM relationships, and regional compounders serving construction and maintenance markets. Dominant competitive moves include REACH-driven reformulation investments and automotive OEM vendor consolidation programs that compress supplier counts.
Among European-headquartered formulators, Henkel AG & Co. KGaA and Sika AG occupy positions reflecting distinct strategic archetypes. Henkel exemplifies the integrated conglomerate model with captive resin capabilities and broad automotive qualification. Sika represents specialized construction-focused positioning with hybrid polyurethane expertise. 3M Company anchors the technology licensing tier through structural tape intellectual property rather than bulk chemical production.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| Sika AG |
| H.B. Fuller Company |
| LORD Corporation |
| Arkema Group |
| BASF SE |
| Dow |
| Evonik Industries |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap German formulators anchor specialty epoxy production, translating technical heritage into pricing discipline that resists commoditization even as Asian petrochemical feedstock costs fluctuate. Their captive relationships with Bavarian automotive OEMs insulate margin structures from spot-market volatility that pressures asset-light competitors.
Pricing Analysis
Three-tier pricing structure across aerospace-certified, automotive-qualified, and general industrial grades separates buyer segments by compliance burden and performance specification. Price differentiation rests on REACH certification status and ISO 10993 biocompatibility clearance for medical applications. Cost compression in standard epoxy formulations is intensifying because Yangtze River Delta resin supply exposes formulators to shipping volatility. Construction contractors in France prove most price-sensitive, while aerospace OEMs in Toulouse absorb premiums for EASA CS-25 traceability.
Supply Chain Analysis
Reverse-logistics flows for expired adhesive inventory and recalled aerospace batches remain underdeveloped, creating stranded asset risk for formulators holding ECHA-registered substances nearing sunset dates. Specialty epoxy resin production concentrates in China, South Korea, and Germany. Formulation draws from bisphenol A feedstocks, amine hardeners, and photoinitiator packages. Single-source vulnerability in Asian petrochemical complexes threatens just-in-time automotive sequences. Distribution runs through authorized distributor networks with technical service capabilities rather than commodity chemical brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal compliance costs in Germany and France exceed formulation investment requirements in India's PLI-subsidized automotive clusters by a substantial margin.
For Market Incumbents: Lock in REACH-compliant resin supply through backward integration into bio-based feedstock partnerships or long-term offtake agreements with Yangtze River Delta producers. Consolidate technical service capabilities around robotic dispensing integration to defend against acrylic adhesive specialists eroding body-in-white share.
For New Entrants and Emerging Players: REACH authorization timelines in Europe open a window for bisphenol A-free epoxy novolac formulations targeting can manufacturers ahead of ECHA sunset deadlines. India's Tamil Nadu automotive cluster offers the most penetrable geography for localized battery enclosure bonding capacity. Pursue qualification partnerships with domestic EV platforms rather than multinational OEM vendor lists.
For Investors and Strategic Acquirers: Valuations sit cheapest among construction-focused polyurethane formulators with untapped aerospace certification potential. The five-to-ten year viability window favors targets with existing EASA CS-25 or FDA ISO 10993 clearance pathways. Monitor ECHA substance restriction amendment announcements as inflection indicators for reformulation-driven consolidation waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Henkel and Arkema secure supply independence from petrochemical volatility through captive epichlorohydrin production. |
| REACH-Compliant Formulation Investment | Sika AG redirects R&D expenditure toward bisphenol A alternatives ahead of ECHA authorization deadlines. |
| Robotic Dispensing System Partnership | 3M Company embeds acrylic adhesive chemistry into automated body-in-white assembly sequences at BMW Group. |
| India PLI Localization Facility | H.B. Fuller establishes Tamil Nadu compounding capacity to serve Mahindra and Tata Motors battery programs. |
| Aerospace Certification Pathway Expansion | LORD Corporation pursues EASA CS-25 qualification for film adhesives at Airbus SE Hamburg facilities. |
Methodological Framework
Coverage spans Germany, France, the United States, China, and India, with primary inputs from each territory combining structured interviews with adhesive formulators, automotive Tier 1 procurement directors, aerospace materials engineers, and construction specification consultants. Secondary validation draws from ECHA substance restriction databases, EPA emission compliance filings, SEC 10-K chemical segment disclosures, and BIS certification registries. Bottom-up volume modeling triangulates against top-down petrochemical feedstock demand indicators.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions include chemistry type, cure technology, end-use industry, and regional regulatory cluster. CAGRs derive from adhesive consumption intensity per vehicle class, content per square meter in aerospace monocoque designs, and construction square footage coefficients. Industry-specific inputs incorporate EU Green Deal emissions trajectory assumptions and electric vehicle battery enclosure penetration curves.
Revisions become necessary when REACH authorization timelines accelerate, MEE emission standards tighten beyond modeled scenarios, or automotive OEM vendor consolidation programs exceed historical rates. Practitioners should monitor ECHA evaluation reports, Yangtze River Delta shipping cost indices, and India PLI scheme disbursement schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle East and Africa Human Fibrin Glue Market
Adhesives & Sealants
Soft Skin Adhesives Market
Adhesives & Sealants
Europe Acrylic Adhesives Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
Global Construction Adhesive Tapes Market
Adhesives & Sealants
Europe Construction Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Acrylic Adhesives Market
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
Curing Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesives for EV Battery Modules Market
Adhesives & Sealants
Europe, Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Animal Glue Market
Adhesives & Sealants
Asia-Pacific Bone Glue Market
Adhesives & Sealants
Fuel Resistant Sealant Market
Adhesives & Sealants
Middle East & Africa Automotive Adhesives & Sealants Market
Adhesives & Sealants
Craft Glue Market