
 Global Epoxy Adhesive Market | 2026-2036
Global Epoxy Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Global Epoxy Adhesive Market Foresight
China is fragmenting as new specialty chemical plants expand epoxy resin output for adhesive feedstock. Henkel AG & Co. KGaA leverages its European formulation heritage to dominate high-reliability electronics applications. 3M Company sustains technology leadership in film epoxy products for aerospace lamination. Huntsman Corporation anchors its position through backward integration into amine curing agents.
Epoxy adhesive refers to a thermosetting polymer system formed by reacting epoxy resin with a hardener, typically achieving lap shear strengths exceeding 20 MPa and operating temperatures from -40°C to 150°C depending on formulation. These adhesives bond metals, composites, ceramics, and engineered plastics where structural integrity, chemical resistance, and dimensional stability are required. Liquid epoxy formulations command the largest volume share due to their versatility in construction bonding and general industrial assembly. Novolac-based technologies represent the fastest-growing chemistry segment as their elevated thermal resistance addresses under-the-hood automotive and downhole oilfield applications. Film epoxy products capture premium margin pools in aerospace components where precise thickness control and minimal volatile organic compound emissions are mandatory.
EPA regulations in the United States restrict volatile organic compound emissions from adhesive manufacturing and application processes, pushing formulators toward low-emission curing systems. REACH and RoHS frameworks in Europe constrain the use of certain bisphenol derivatives and heavy metal catalysts, directly altering raw material selection for suppliers serving EU electronics and marine end users. China's MEE enforces wastewater and air quality standards that affect epoxy resin production economics. Stakeholders must monitor regulatory divergence across these three jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
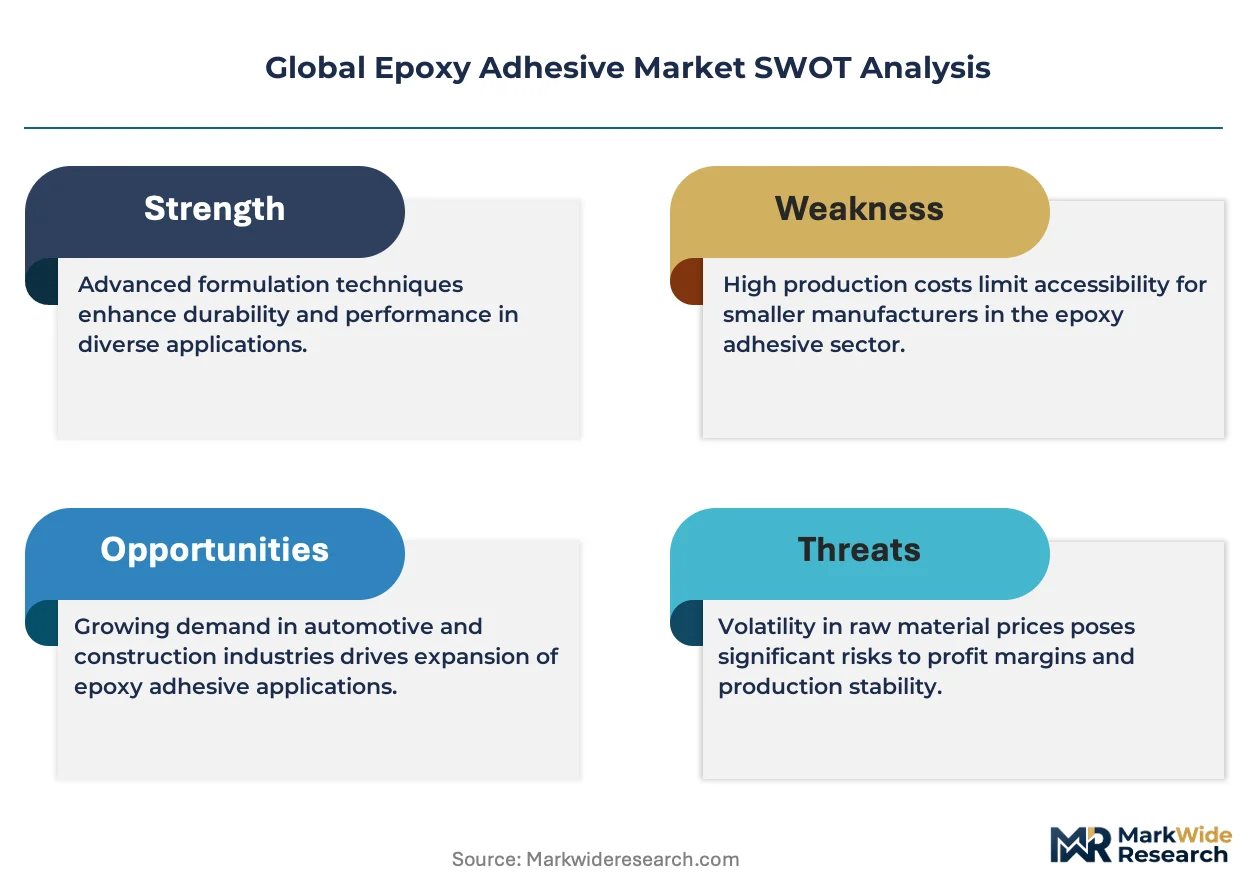
REACH and RoHS compliance requirements in Europe are forcing adhesive formulators to eliminate bisphenol derivatives and heavy metal catalysts from electronics-grade products, triggering costly reformulation cycles and supplier qualification delays across the supply chain.
Growth Catalysts
- Aerospace composite bonding:Aircraft manufacturers are expanding epoxy adhesive procurement for lightweight structural assemblies. Boeing and Airbus production ramps in the United States and France drive specification tightening for film epoxy systems.
- MEE enforcement in China:China's Ministry of Ecology and Environment wastewater standards are consolidating epoxy resin production toward larger, compliant facilities. This concentration improves feedstock quality for domestic adhesive manufacturers serving electronics assembly and shipbuilding.
- Novolac chemistry expansion:Elevated thermal resistance formulations are capturing under-the-hood automotive and downhole oilfield applications. These segments require operating temperatures above 150°C that standard bisphenol-A systems cannot sustain.
Market Restraints
- Amine curing agent concentration:Backward integration by Huntsman and a handful of Asian chemical conglomerates controls critical hardener supply. This oligopoly structure limits pricing leverage for independent formulators in Germany and Japan.
- Bisphenol-A regulatory friction:ECHA hazard classifications and state-level restrictions in California are constraining raw material availability. Formulators face reformulation costs without guaranteed customer acceptance of performance-equivalent alternatives.
- Cyanoacrylate and polyurethane substitution:Fast-curing instant adhesives and flexible polyurethane systems are displacing epoxy in consumer electronics assembly and footwear applications where load-bearing strength is secondary to processing speed.
Strategic Opportunities
- India electronics manufacturing:Production-linked incentive schemes and tariff structures are attracting mobile phone and semiconductor packaging investment. Domestic epoxy adhesive demand for PCB lamination and component underfill remains underpenetrated relative to China and Vietnam.
- Dual carbon goals in China:National carbon neutrality targets are mandating low-VOC curing systems in state-owned enterprise procurement. Waterborne and UV-curable epoxy technologies qualify for preferential treatment in infrastructure tenders.
- Film epoxy-aerospace convergence:Out-of-autoclave processing and automated fiber placement are creating demand for tailored film adhesives with precise rheology control. This specification tier commands margin premiums over liquid formulations.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in epoxy-amine stoichiometry and filler dispersion is retiring faster than universities and technical institutes can replenish pipelines in the United States and Western Europe.
- Qualification timeline compression:Aerospace OEMs are demanding 12-month certification cycles for new adhesive grades against historical 24-36 month windows. This acceleration strains testing laboratory capacity and regulatory submission resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Epoxy Adhesive Market |
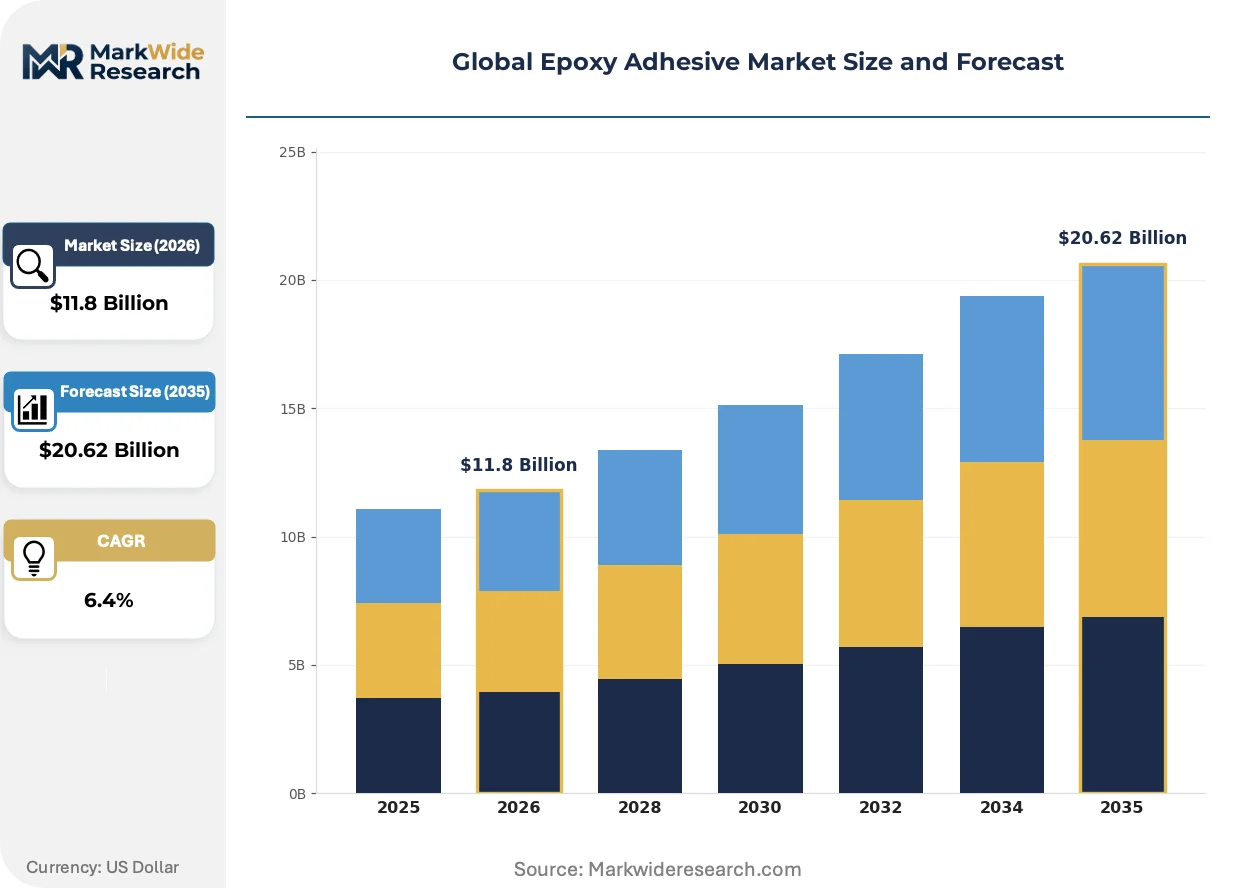
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Epoxy, Paste Epoxy, Solid Epoxy, Film Epoxy Technology: Bisphenol A, Novolac, Aliphatic, Glycidyl Ether Application: Electronics Assembly, Construction Bonding, Aerospace Components, Marine Sealants End User: OEMs, Aerospace Manufacturers, Electronic Device Makers, Shipbuilding Companies |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, H.B. Fuller Company, Sika AG, Dow Inc., Huntsman Corporation, Arkema Group, BASF SE, Ashland Global Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Epoxy Adhesive Market Shifts & Advancements
Epoxy adhesive technology is hybridizing across chemistry platforms and application methods as end-users demand multifunctional performance that single-resin systems cannot deliver alone.
Bio-based epoxy resins derived from lignin and epoxidized vegetable oils are hybridizing with conventional petroleum feedstocks to reduce carbon intensity metrics. Automotive OEMs in Germany and Japan are piloting these formulations for interior trim bonding where structural loads remain moderate. The hybridization is compressing the premium pricing gap between sustainable and conventional adhesives as scale economies emerge.
EPA volatile organic compound regulations under the Clean Air Act are tightening permissible emissions from adhesive manufacturing and application processes. Formulators are responding with low-temperature curing systems and reactive diluents that minimize solvent content. Aerospace laminators in Washington State and California face the steepest compliance costs due to concentration of film epoxy production in these jurisdictions.
Specification-driven procurement is consolidating buyer power among tier-one aerospace and electronics contract manufacturers. Original equipment manufacturers are unbundling adhesive supply from structural component contracts, forcing formulators to qualify directly with Boeing, Airbus, and Apple rather than through tier-two fabricators. This disintermediation is most visible in Shenzhen and Seattle supply corridors where concentration of final assembly creates leverage asymmetries.
Global Epoxy Adhesive Market Segmentation
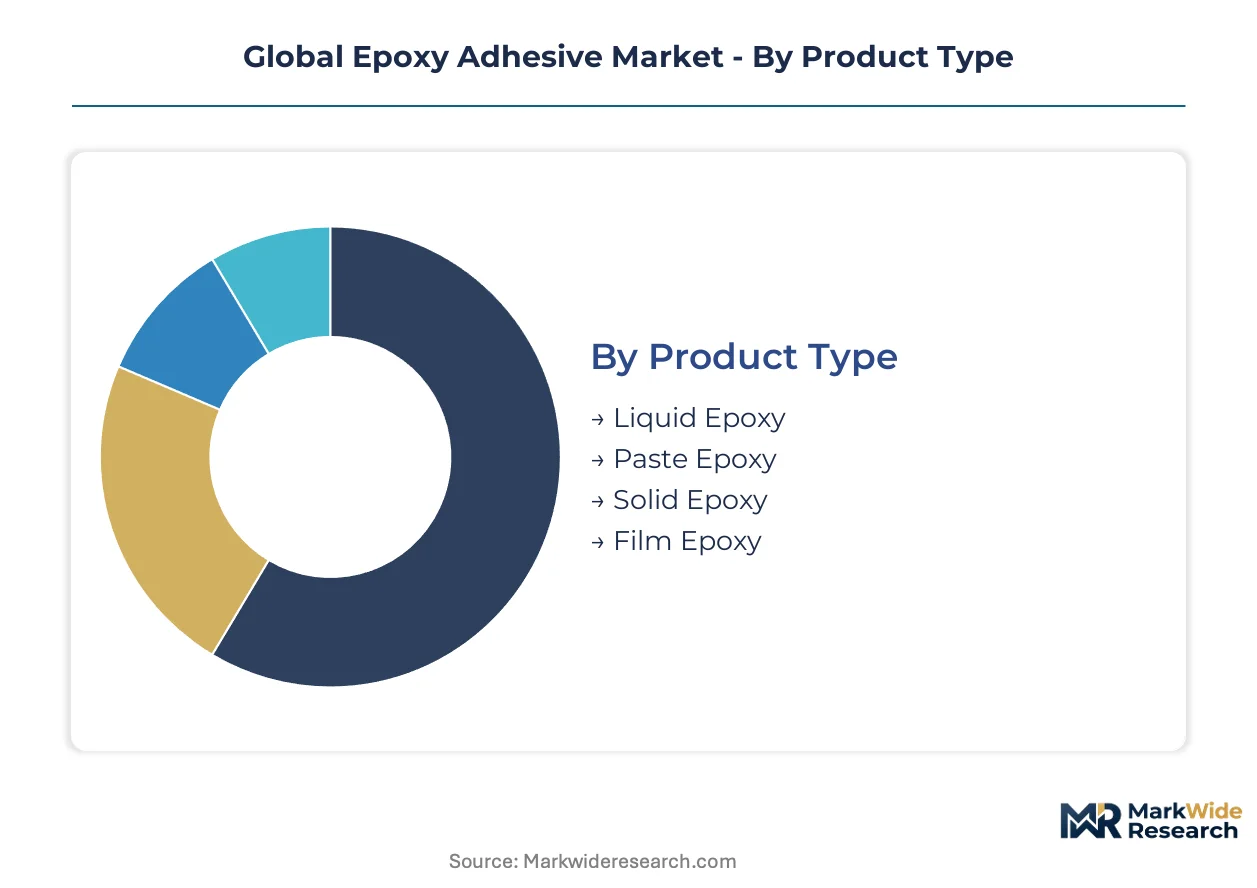
Epoxy adhesive segmentation reveals how formulation chemistry and physical form determine addressable end-use markets. Product viscosity, thermal resistance, and application method create distinct competitive battlegrounds with divergent margin profiles and qualification barriers.
Product Type:
Mature liquid and paste formats dominate volume, while film and solid systems occupy emerging specification niches demanding precision manufacturing.
- Liquid Epoxy:Low-viscosity formulations enable brush, spray, and dispensing applications across construction and general industrial bonding. Construction contractors in Germany and Japan specify these systems for concrete crack injection and metal-to-concrete anchoring where penetration depth matters.
- Film Epoxy:Pre-catalyzed sheets with controlled thickness and minimal volatile content serve aerospace primary structure lamination. Boeing and Airbus qualification requirements in Washington State and Toulouse mandate film products for wing skin and fuselage bonding where out-of-autoclave processing reduces cycle time.
- Paste Epoxy:Thixotropic formulations resist sag on vertical surfaces and gap-filling applications. Marine repair yards in South Korea and Norway specify paste consistency for hull patching and deck sealing.
- Solid Epoxy:Powder and pellet forms support hot-melt compounding and specialty powder coating adhesion. Powder metallurgy and electrical insulation manufacturers in China and Switzerland utilize solid systems for controlled melt flow characteristics.
Liquid epoxy handles the majority of throughput; film epoxy is gaining share fastest on aerospace specification tightening.
Technology:
Cost tiers separate commodity bisphenol chemistry from premium thermal-resistant platforms commanding formulation expertise premiums.
- Bisphenol A:Standard diglycidyl ether of bisphenol-A resins provide baseline mechanical properties and chemical resistance at lowest raw material cost. General industrial assemblers in Mexico and Poland specify bisphenol-A systems for metal bonding and concrete repair where operating temperatures remain below 80°C.
- Novolac:Phenol-formaldehyde derived epoxy resins deliver elevated crosslink density and thermal resistance above 150°C. Automotive under-hood component suppliers in Stuttgart and Detroit specify novolac formulations for engine encapsulation and exhaust system bonding.
- Aliphatic:Flexible backbone structures impart elongation and impact resistance for dynamic load applications. Wind turbine blade manufacturers in Denmark and blade repair services in Texas specify aliphatic-modified systems for root bonding and leading edge erosion protection.
- Glycidyl Ether:Reactive diluents and specialty monomers adjust viscosity and cure kinetics for automated dispensing equipment. Electronics contract manufacturers in Shenzhen and Penang specify glycidyl ether formulations for precise underfill and encapsulation control.
Bisphenol A commands the volume base; novolac climbs the fastest on thermal specification escalation in mobility and energy applications.
Application:
Customer type segmentation separates specification-driven procurement in aerospace and electronics from price-sensitive construction and marine contracting.
- Electronics Assembly:Precision dispensing for PCB lamination, component underfill, and semiconductor packaging demands low ionic content and matched coefficient of thermal expansion. Apple and Samsung contract manufacturers in Vietnam and India enforce sub-50 ppm chloride specifications for mobile device reliability.
- Aerospace Components:Primary and secondary structural bonding requires traceable batch certification and flame-smoke-toxicity compliance. FAA and EASA qualification protocols in Wichita and Hamburg mandate extensive mechanical testing and environmental aging validation.
- Construction Bonding:Structural concrete repair, steel reinforcement anchoring, and composite strengthening utilize field-applied liquid and paste systems. Infrastructure contractors in Australia and Brazil specify epoxy for bridge deck overlays and seismic retrofit of concrete columns.
- Marine Sealants:Hull bonding, deck sealing, and interior joinery require saltwater resistance and flexibility under cyclic loading. Shipbuilders in Shanghai and Ulsan specify marine-grade formulations for container vessel and LNG carrier construction.
Construction bonding moves the highest volume tonnage; aerospace components expand most quickly on composite airframe penetration.
End User:
Supply concentration varies sharply between fragmented construction procurement and consolidated aerospace specification control.
- OEMs:Original equipment manufacturers across automotive, appliance, and industrial machinery sectors specify adhesives for production line efficiency and warranty liability management. Appliance assemblers in Turkey and Mexico balance curing speed with fixture investment constraints.
- Aerospace Manufacturers:Boeing, Airbus, COMAC, and Bombardier control adhesive qualification through approved products lists and source-controlled specifications. Final assembly sites in Charleston, Tianjin, and Montreal dictate formulation requirements that cascade through tiered supplier networks.
- Electronic Device Makers:Smartphone, laptop, and semiconductor packaging houses specify underfill, die attach, and board-level adhesives. Foxconn and Pegatron procurement in Zhengzhou and Chennai concentrate demand for high-purity, low-stress formulations.
- Shipbuilding Companies:Hyundai Heavy Industries, China State Shipbuilding Corporation, and Fincantieri manage adhesive procurement through classification society rules. Korean and Chinese yards specify epoxy systems meeting DNV and Lloyd's Register fire resistance protocols.
OEMs represent the broadest demand base; aerospace manufacturers drive the steepest specification escalation and margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan deep-water port anchors Asia-Pacific epoxy adhesive trade flows, handling resin feedstock imports that supply electronics assemblers across the Yangtze River Delta manufacturing belt.
United States
Boeing's Charleston and Everett assembly lines specify film epoxy systems for 787 and 777X composite fuselage bonding. EPA Clean Air Act enforcement tightens volatile organic compound limits on adhesive manufacturing in Washington State. Aerospace laminators in the Pacific Northwest face compliance cost pressures that favor low-emission curing technologies.
China
MEE wastewater standards are consolidating epoxy resin production toward larger compliant facilities serving domestic electronics and shipbuilding demand. Dual carbon goals mandate low-VOC curing systems in state-owned enterprise procurement tenders. Shenzhen and Zhengzhou concentrate contract manufacturing for Apple and Foxconn requiring high-purity underfill adhesives.
Germany
Automotive OEMs in Stuttgart specify novolac-based formulations for under-hood component bonding above 150°C operating thresholds. REACH and RoHS frameworks constrain bisphenol derivatives and heavy metal catalysts in electronics-grade products. BASF and Henkel formulation heritage dominates high-reliability applications across the Rhine-Ruhr industrial corridor.
Japan
Wind turbine blade manufacturers in Nagoya specify aliphatic-modified systems for root bonding and leading edge erosion protection. METI industrial standards govern adhesive performance certification for infrastructure applications. Osaka-based electronics assemblers enforce sub-50 ppm chloride specifications for semiconductor packaging reliability.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries specify marine-grade epoxy systems for LNG carrier and container vessel construction meeting DNV fire resistance protocols. KOSHA occupational safety regulations govern amine hardener handling in Ulsan and Geoje shipyards. Daegu-Gyeongbuk region concentrates specialty chemical production for adhesive feedstock.
Global Epoxy Adhesive Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream controlling critical curing agent supply. The market structure concentrates around backward-integrated chemical conglomerates and diversified adhesive formulators with formulation heritage advantages. Three archetypes dominate: European heritage formulators with aerospace qualification depth, Asian chemical conglomerates with captive resin supply, and diversified industrials with cross-sector adhesive portfolios. Competitive moves center on backward integration into amine hardeners and direct qualification with tier-one OEMs disintermediating fabricators.
Among European heritage formulators, Henkel AG & Co. KGaA exemplifies the high-reliability electronics specialization archetype, while 3M Company occupies a position representing film adhesive technology leadership for aerospace lamination. Huntsman Corporation anchors the backward-integrated archetype through captive amine curing agent production. These three players collectively illustrate how geographic formulation heritage, technology specialization, and upstream supply control define competitive positioning across specification tiers.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| H.B. Fuller Company |
| Sika AG |
| Dow Inc. |
| Huntsman Corporation |
| Arkema Group |
| BASF SE |
| Ashland Global Holdings |
| Others |
Supply & Pricing Matrix
Single-source dependency on Huntsman Corporation's captive amine curing agent production determines both pricing tier spreads and supply chain shape across the epoxy adhesive landscape. Formulators lacking backward integration into hardener supply face margin compression when aerospace OEMs demand 12-month qualification cycles that strain testing laboratory capacity.
Pricing Analysis
Volume-discount tiering structures separate aerospace film epoxy specifications commanding premium positioning from construction-grade liquid formulations sold on commodity terms. Three-tier pricing stratification across aerospace-certified, industrial-performance, and general-assembly grades reflects divergent qualification burdens and raw material purity requirements. Cost compression in the industrial tier intensifies as Chinese resin capacity expansion feeds independent formulators in Germany and Japan. Construction contractors in Mexico and Poland exhibit highest price sensitivity, while Boeing and Airbus procurement teams prioritize traceable batch certification over unit economics.
Supply Chain Analysis
Upstream feedstock concentration in China, South Korea, and Germany anchors global epoxy resin availability for adhesive manufacturing. Bisphenol-A and epichlorohydrin feedstocks draw from petrochemical complexes along the Yangtze River Delta and the Rhine-Ruhr corridor, with specialty amine hardeners sourcing from Huntsman's US Gulf Coast facilities. Tariff exposure on Chinese resin imports into the United States creates pricing volatility for independent formulators lacking regional manufacturing footprints. Distribution runs through authorized distributor networks serving electronics contract manufacturers in Shenzhen and Penang, with direct qualification channels dominating aerospace supply to Boeing's Charleston assembly line.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive positioning. REACH and RoHS compliance timelines impose 24-36 month supplier qualification windows that protect incumbent formulation expertise from rapid displacement.
For Market Incumbents: Harden supply security through captive amine curing agent production or long-term offtake agreements with Huntsman and Asian chemical conglomerates. Accelerate qualification pipeline investments to compress Boeing and Airbus certification cycles below 18 months, denying independent formulators window opportunities. Prioritize novolac chemistry R&D to capture thermal specification escalation in Stuttgart and Detroit automotive under-hood applications.
For New Entrants and Emerging Players: India's electronics manufacturing corridors offer the most penetrable white-space target, with production-linked incentive schemes attracting Foxconn and Pegatron investment that outpaces domestic adhesive supply development. Waterborne and UV-curable epoxy technologies qualify for preferential procurement treatment under China's dual carbon goals, creating specification entry points without direct confrontation with Henkel's high-reliability electronics dominance. Partner with regional distributors in Chennai and Daegu to bypass direct OEM qualification barriers.
For Investors and Strategic Acquirers: REACH reformulation deadlines reshaping the acquisition landscape toward targets with demonstrated bisphenol-free electronics-grade portfolios. Five-to-ten-year viability hinges on regulatory adaptation speed rather than scale economics alone. Prioritize mid-cap formulators with existing ECHA pre-registration dossiers and qualified aerospace film epoxy positions. Monitor ECHA hazard classification updates on bisphenol derivatives as the critical inflection signal for portfolio revaluation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amine Hardeners | Huntsman's captive supply model demonstrates pricing power leverage over independent German and Japanese formulators. |
| Direct OEM Qualification Bypass | Disintermediating tier-two fabricators captures margin premiums from Boeing, Airbus, and Apple specification control. |
| Novolac Chemistry Capacity Expansion | Stuttgart and Detroit automotive thermal requirements above 150°C exceed standard bisphenol-A system capabilities. |
| India Electronics Manufacturing Partnership | PLI scheme concentration in Zhengzhou and Chennai corridors outpaces domestic adhesive supply infrastructure. |
| Low-VOC Curing System Development | China's MEE enforcement and dual carbon goals mandate waterborne technologies for state-owned enterprise tenders. |
Research Methodology
Operator-level perspectives from adhesive formulators, aerospace procurement managers, electronics contract manufacturing executives, and amine hardener plant managers anchored the qualitative base for this analysis. Primary fieldwork across Washington State, Toulouse, Stuttgart, Shenzhen, and Ulsan supplemented secondary validation through customs trade data, SEC 10-K filings, ECHA registration dossiers, and ACC industry reports. Bottom-up segment sizing triangulated against top-down macroeconomic elasticity assumptions to constrain projection variance.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling spanning product viscosity tier, thermal resistance chemistry, end-use application intensity, and regional production hub concentration. CAGRs derived from elasticity-adjusted demand curves incorporating aerospace build-rate forecasts, electronics assembly capacity expansion in Vietnam and India, and automotive lightweighting penetration assumptions. Novolac chemistry adoption curves and REACH reformulation cost pass-through rates served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Asian chemical conglomerates or accelerated ECHA bisphenol restrictions would shift outcomes beyond modeled ranges. Cross-checking against customs resin import volumes and aerospace OEM approved products list updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market
Adhesives & Sealants
Electric Vehicle Adhesives Market
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
Global Solvent Pressure Sensitive Adhesives Market
Adhesives & Sealants
South America Construction Adhesives Market
Adhesives & Sealants
Construction Repair and Rehabilitation Chemicals Market
Adhesives & Sealants
Middle East and Africa Epoxy Curing Agents Market
Adhesives & Sealants
Applicator Tips Market
Adhesives & Sealants
Global Automotive Adhesive Market
Adhesives & Sealants
Water Based Adhesive Market
Adhesives & Sealants
Flock Binder Market
Adhesives & Sealants
Urea Formaldehyde Concrete Market
Adhesives & Sealants
Global Hygiene Adhesives Market
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market
Adhesives & Sealants
Instant Adhesive Market