
 Asia-Pacific Package Substation Market | 2026-2036
Asia-Pacific Package Substation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Package Substation Market Outlook
Multi-source procurement for transformer cores and switchgear assemblies is pivoting toward captive sourcing as lead times stretch across the Asia-Pacific. Schneider Electric SE leverages its Indian manufacturing footprint to anchor regional supply security. Hitachi Energy Ltd competes through specialized high-voltage compact designs for dense urban deployments. Larsen & Toubro Limited dominates domestic Indian infrastructure tenders with integrated EPC capabilities.
A package substation integrates transformers, switchgear, and protection equipment within a single enclosed or containerized assembly, typically rated from 11 kV to 36 kV for primary distribution networks. These units enable rapid deployment where permanent brick-and-mortar substations prove impractical due to space constraints or emergency restoration timelines. Compact substations lead volume shipments across dense Asian megacities where land scarcity drives vertical infrastructure planning. Smart grid technology represents the fastest-expanding technology segment as utilities deploy remote monitoring and automated fault isolation across fragmented distribution networks. Containerized substations occupy premium positioning for mining and oil-and-gas applications requiring rapid relocation and harsh-environment resilience.
India's Central Electricity Authority mandates standardized substation designs under CEA Technical Standards for Connectivity, while South Korea's KEPCO enforces smart grid interoperability protocols that shape vendor qualification criteria. Australia's state-level electrical safety regulators impose arc-flash and bushfire mitigation standards that filter product eligibility for bushland-adjacent installations. Stakeholders must weigh localization requirements against scale economics as procurement rules tighten across ASEAN member states.
Market Dynamics
Smart grid mandates across South Korea and India's PLI scheme for power infrastructure are forcing synchronous technology transitions, compressing deployment timelines for conventional electromechanical substations while accelerating digital-ready package substation procurement.
Growth Catalysts
- Rural electrification programs:Utilities across Southeast Asia are extending grid connectivity to remote islands and forested regions where containerized substations eliminate civil construction delays.
- CEA Technical Standards for Connectivity:India's Central Electricity Authority mandates standardized substation designs that streamline vendor qualification and accelerate tender approvals for integrated EPC contractors.
- KEPCO smart grid protocols:South Korea's state utility enforces interoperability requirements that pull remote monitoring and automated fault isolation into distribution network upgrades.
Market Restraints
- Grain-oriented electrical steel concentration:Transformer core material sourcing clusters in a narrow supplier base, exposing lead times to geopolitical friction and alloying element volatility.
- Arc-flash mitigation compliance:Australian state-level electrical safety regulators impose bushfire-resistant specifications that filter product eligibility and extend certification cycles for bushland-adjacent installations.
- Permanent brick-and-mortar substitution:Utilities with predictable load growth and available land prefer conventional substations for their lower lifecycle cost and expandable footprint.
Strategic Opportunities
- Indonesia's archipelago electrification:The national utility PLN targets thousands of unelectrified villages across 17,000 islands where marine-transportable containerized units bypass infrastructure gaps.
- Mining automation convergence:Australian iron ore and coal operators are pairing package substations with autonomous haulage systems, creating demand for relocatable power with integrated fiber communications.
- Localization incentives:ASEAN member states are tightening domestic content rules that reward joint ventures with local fabricators and transformer winding facilities.
Industry Challenges
- Commissioning engineer scarcity:Specialized technicians capable of integrating protection relays with SCADA systems are concentrated in metro hubs, constraining deployment velocity in tier-2 industrial corridors.
- Legacy electromechanical interoperability:Utilities with aging distribution networks face protocol translation complexity when grafting IEC 61850-compliant intelligent electronic devices onto existing copper-wire signaling infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Package Substation Market |
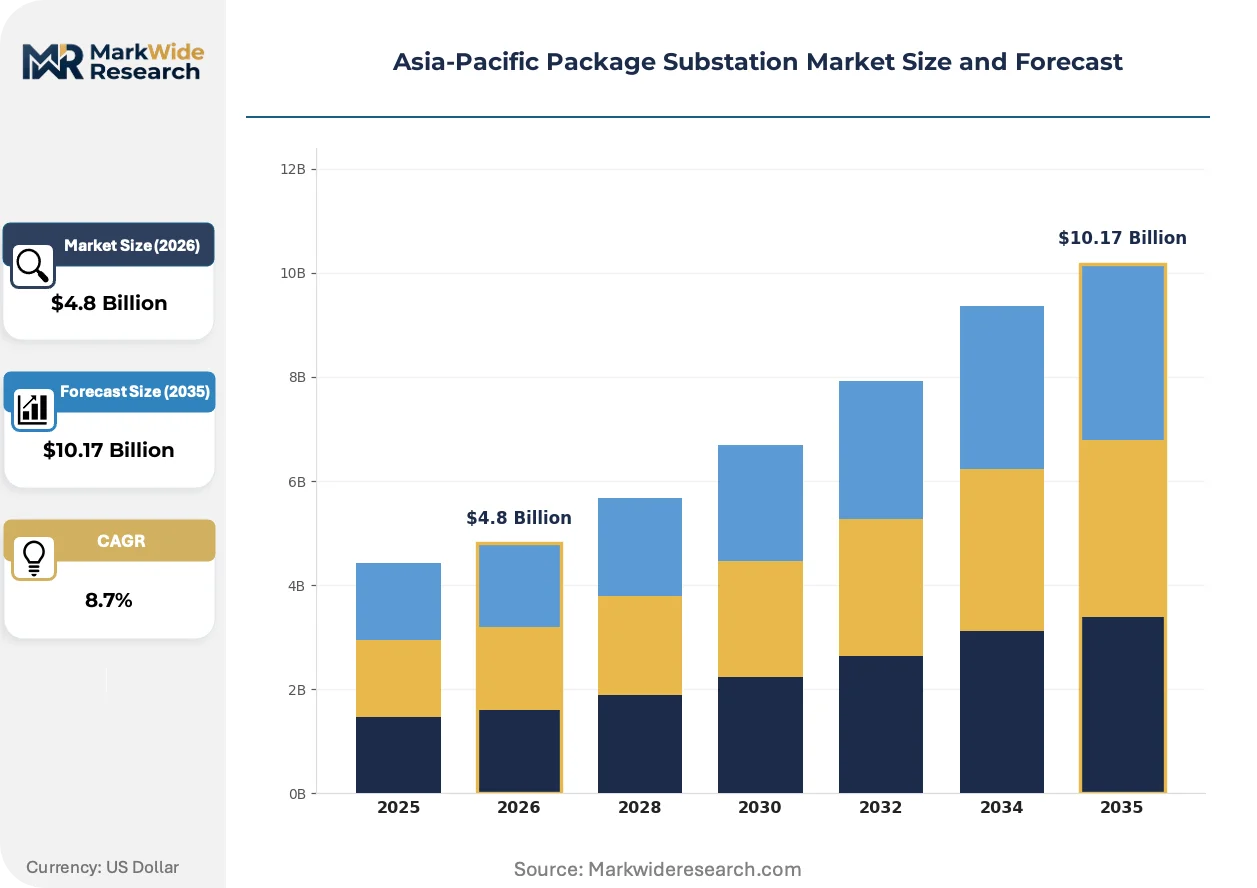
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bay Type, Compact Substation, Modular Substation, Containerized Substation Technology: Smart Grid Technology, Automation Solutions, Conventional Technology, Voltage Regulation End User: Industrial Sector, Commercial Sector, Utilities, Residential Sector Installation: Ground Mounted, Pole Mounted, Underground, Hybrid Systems |
| Companies Covered | Schneider Electric SE, ABB Ltd, Eaton Corporation PLC, Siemens AG, Lucy Group Ltd, General Electric Company, Kirloskar Electric Company Ltd, Hitachi Energy Ltd, Larsen & Toubro Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Package Substation Market Strategic Shifts
Digitalization of distribution infrastructure is compressing the gap between primary equipment and control systems, pulling software-defined protection and edge analytics into what were historically hardware-only procurement categories.
Gas-insulated switchgear technology is expanding into compact package substations rated 36 kV and below, replacing air-insulated designs in dense Asian megacities where footprint constraints dominate site selection. Japanese utilities are specifying SF6 alternatives for coastal installations exposed to salt contamination. The structural consequence is a bifurcation in vendor portfolios between conventional air-insulated specialists and gas-insulated technology licensors.
India's CEA Technical Standards for Connectivity are harmonizing substation design parameters across state distribution companies, reducing engineering customization and enabling modular factory production. The regulation compresses project development timelines from concept to energization. Domestic EPC contractors with pre-approved designs are capturing disproportionate tender share against international competitors requiring design revalidation.
Asset-as-a-service contracting is displacing capital purchase models for mining and oil-and-gas operators seeking to offload obsolescence risk and balance-sheet treatment. Equipment vendors are retaining ownership and charging per-kWh-delivered or fixed monthly availability fees. Western Australia's Pilbara region exhibits the most advanced adoption, with major iron ore producers standardizing on ten-year service agreements with embedded replacement cycles.
Asia-Pacific Package Substation Market Segmentation
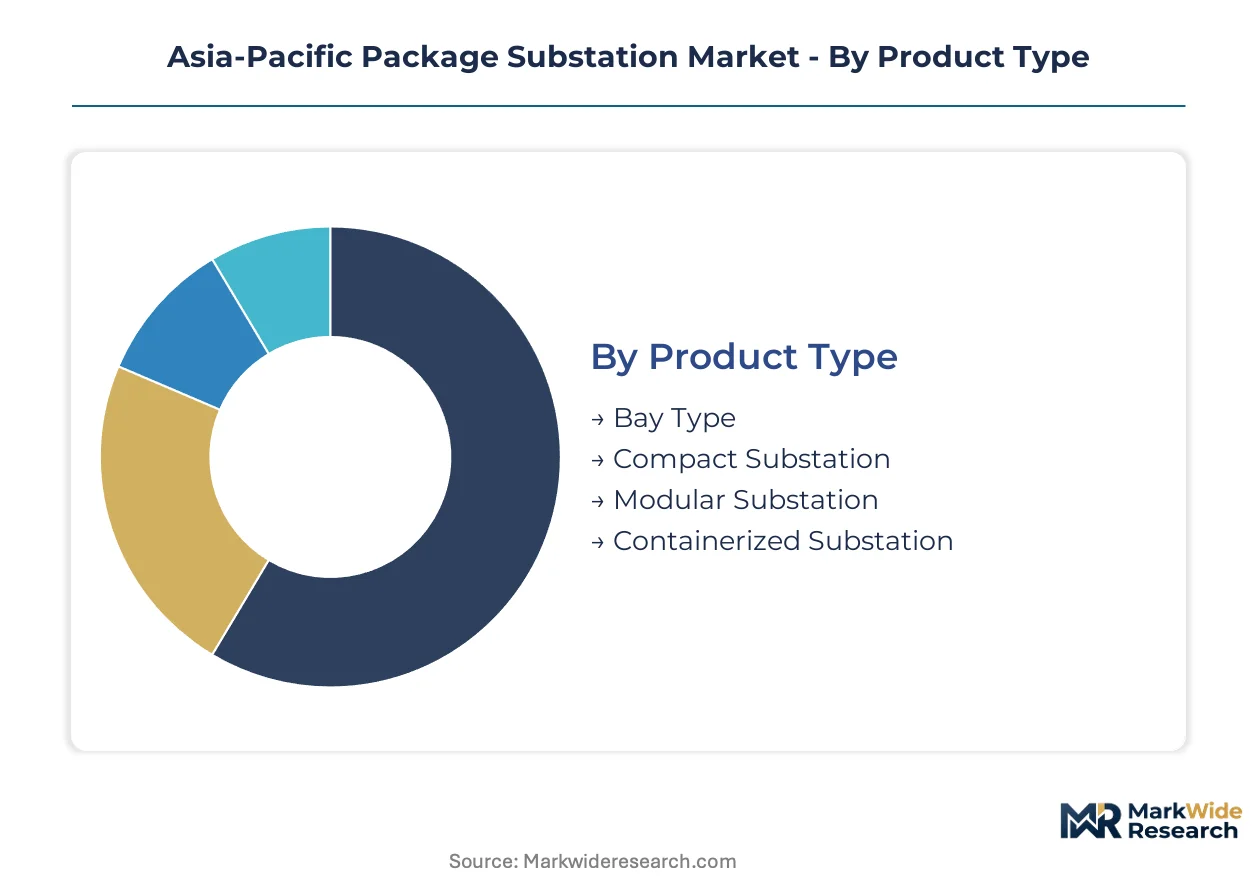
Package substation procurement varies sharply by deployment context. Capital allocation, regulatory compliance, and site constraints reshape vendor selection across each dimension. Understanding segment boundaries clarifies where integrated EPC contracts outperform component sourcing.
Product Type:
Containerized and modular formats demand the highest upfront capital outlays due to transport engineering and enclosure ruggedization. Bay-type and compact variants require lower initial investment but impose civil works costs that shift total project economics.
- Containerized Substation:Fully enclosed steel structures house transformers, switchgear, and protection systems within ISO-standard frames for marine and road transport. Mining operators in Western Australia's Pilbara region specify these for rapid relocation alongside autonomous haulage fleets, with ten-year service agreements replacing capital purchase models.
- Compact Substation:Vertical integration of equipment within minimal footprints serves dense Asian megacities where land scarcity drives infrastructure stacking. Municipal utilities in Seoul and Mumbai deploy these for 11-36 kV distribution networks where permanent brick-and-mortar construction faces right-of-way constraints.
- Modular Substation:Factory-built sections enable phased capacity expansion across Indonesia's archipelago electrification program.
- Bay Type:Open-air arrangements with separate equipment bays suit Indian industrial corridors with available land and predictable load growth.
Most installed capacity flows through Compact Substation formats. Expansion is steepest in Containerized Substation configurations.
Technology:
Smart grid deployments command premium pricing due to embedded communications, edge analytics, and cybersecurity hardening. Conventional electromechanical systems occupy the lowest cost tier but face accelerating replacement timelines under interoperability mandates.
- Smart Grid Technology:Remote monitoring, automated fault isolation, and SCADA integration enable real-time network visibility. South Korea's KEPCO enforces interoperability protocols that pull these capabilities into distribution upgrades, while India's state utilities pilot IEC 61850-compliant intelligent electronic devices under CEA connectivity standards.
- Automation Solutions:Programmable protection relays and load tap changers reduce outage duration through self-healing network logic. Australian distributors in bushfire-prone regions specify arc-flash mitigation and automated sectionalizing to comply with state electrical safety regulations.
- Conventional Technology:Electromechanical relays and manual switching persist in Southeast Asian rural electrification programs where capital constraints dominate procurement.
- Voltage Regulation:On-load tap changers and capacitor banks stabilize fluctuating loads across industrial corridors with heavy motor starting demands.
Conventional Technology retains the largest installed base. Smart Grid Technology is climbing the fastest as utilities modernize aging distribution infrastructure.
End User:
Utility procurement operates at scale with standardized specifications, while industrial buyers prioritize customization and availability guarantees. Commercial and residential segments fragment across smaller unit sizes with higher per-kVA installation costs.
- Industrial Sector:Mining, steel, and petrochemical operators demand relocatable power with integrated fiber communications for automation convergence. Australian iron ore producers standardize on availability-based contracting with embedded replacement cycles.
- Utilities:State distribution companies across India and national utilities in Indonesia drive volume procurement through tender mechanisms. CEA Technical Standards for Connectivity harmonize designs that accelerate approval timelines for pre-qualified EPC contractors.
- Commercial Sector:Data centers and logistics parks in Singapore and Sydney specify compact units for campus distribution with redundancy requirements.
- Residential Sector:High-rise developments in Manila and Bangkok deploy pole-mounted and compact formats for last-mile connection.
Utilities account for the greatest cumulative deployment. Industrial Sector applications are gaining share fastest through mining automation and captive power expansion.
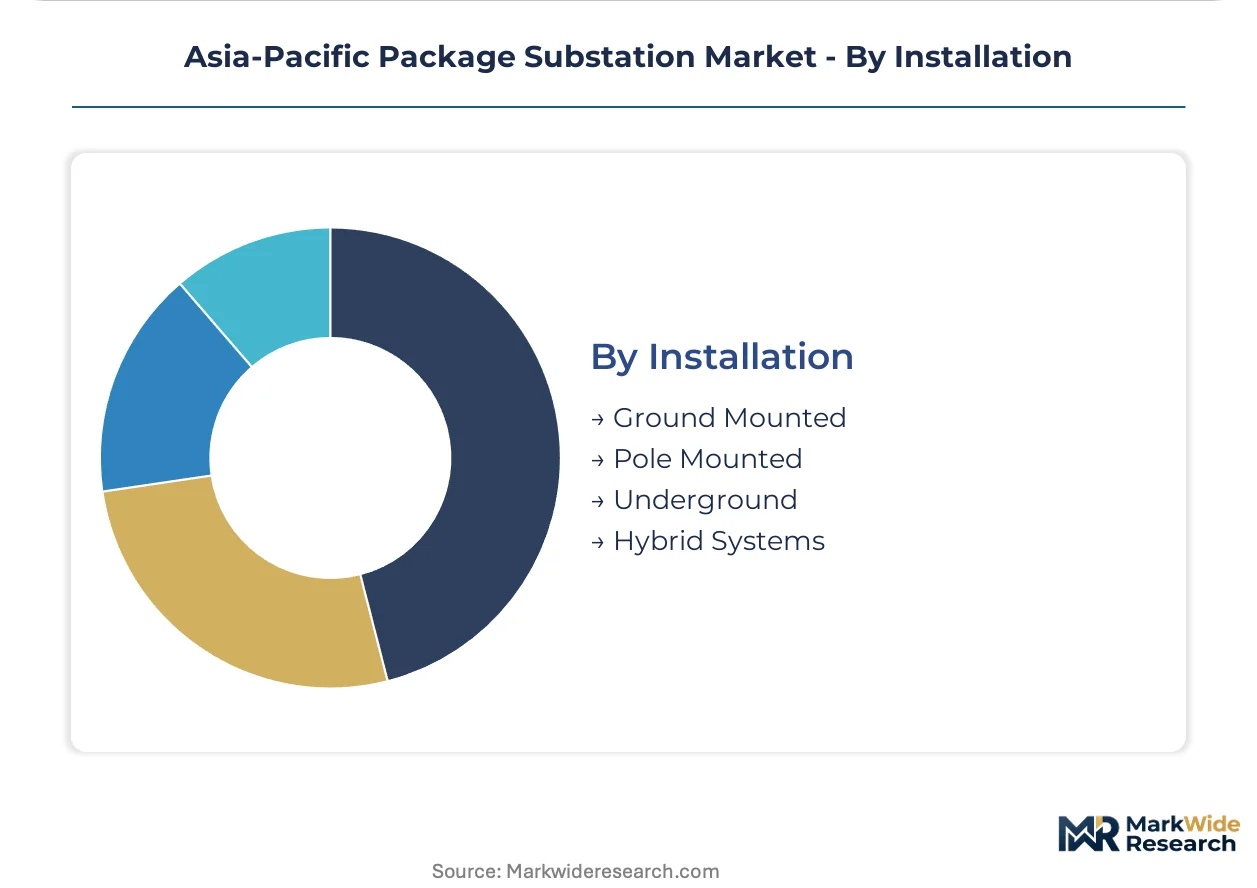
Installation:
Underground and hybrid configurations impose the steepest civil engineering costs but eliminate visual impact and environmental exposure. Ground-mounted and pole-mounted alternatives minimize site preparation while sacrificing space efficiency and flood resilience.
- Ground Mounted:Concrete pad foundations support standard enclosures across Indian industrial townships and Australian mining camps. The format balances accessibility for maintenance with moderate civil works expenditure.
- Underground:Vault or direct-buried installations eliminate surface footprint in Singapore's dense urban core and Tokyo's commercial districts. Salt contamination and water ingress risks drive specification of gas-insulated switchgear alternatives in Japanese coastal zones.
- Pole Mounted:Single-pole structures serve rural distribution lines across the Philippines and Vietnam where terrain limits vehicle access.
- Hybrid Systems:Combinations of surface and buried components adapt to constrained sites in Seoul's vertical infrastructure planning.
Ground Mounted configurations dominate current installations. Underground formats are expanding most quickly in premium urban locations where surface land commands extreme valuations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's industrial corridors command the highest concentration of package substation procurement across the Asia-Pacific, driven by manufacturing expansion and grid modernization mandates. Australia's mining regions and Southeast Asia's island electrification programs create secondary demand poles with distinct technical specifications.
India
State distribution companies in Maharashtra and Gujarat drive tender volumes through CEA Technical Standards for Connectivity compliance. The PLI scheme for power infrastructure accelerates domestic manufacturing capacity expansion. Larsen & Toubro Limited anchors integrated EPC contracts across the Delhi-Mumbai Industrial Corridor with pre-approved standardized designs.
Australia
Iron ore operators in Western Australia's Pilbara region specify containerized units for autonomous haulage fleet power requirements. State-level electrical safety regulators impose arc-flash and bushfire mitigation standards that filter product eligibility. Asset-as-a-service contracting dominates, with ten-year availability agreements replacing capital purchases across major mining camps.
South Korea
KEPCO enforces smart grid interoperability protocols that pull remote monitoring capabilities into distribution network upgrades. Seoul's dense urban core demands compact substation formats for vertical infrastructure planning. Municipal utilities deploy IEC 61850-compliant intelligent electronic devices under national digitalization mandates.
Indonesia
PLN targets thousands of unelectrified villages across 17,000 islands where marine-transportable containerized units bypass infrastructure gaps. Modular factory-built sections enable phased capacity expansion across archipelago electrification programs. Domestic content rules tighten procurement criteria for joint ventures with local fabricators.
Japan
Tokyo's commercial districts specify underground vault installations to eliminate surface footprint constraints. Coastal utilities specify SF6 alternatives for salt contamination exposure in gas-insulated switchgear applications. METI standards shape vendor qualification criteria for distribution infrastructure resilience.
Asia-Pacific Package Substation Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue smart grid integration and service-based contracting models. The vendor base clusters around three strategic archetypes: integrated EPC contractors with domestic regulatory pre-qualification, multinational electrical equipment conglomerates with regional manufacturing footprints, and specialized compact design houses for dense urban deployment. Capacity localization and technology licensing represent the dominant competitive moves as ASEAN domestic content rules tighten.
Among French-origin electrical conglomerates, Schneider Electric SE exemplifies the manufacturing-anchored archetype with supply security positioning across Indian production facilities. Hitachi Energy Ltd occupies the specialized technology tier, representing compact high-voltage design capabilities for space-constrained Asian megacities. Larsen & Toubro Limited anchors the integrated domestic EPC segment, capturing disproportionate tender share through pre-approved CEA-standardized designs.
| Leading Market Players |
|---|
| Schneider Electric SE |
| ABB Ltd |
| Eaton Corporation PLC |
| Siemens AG |
| Lucy Group Ltd |
| General Electric Company |
| Kirloskar Electric Company Ltd |
| Hitachi Energy Ltd |
| Larsen & Toubro Limited |
| Others |
Value Chain & Pricing Dynamics
Australian bushfire-resistance mandates and KEPCO smart grid interoperability protocols gate qualified supply and premium-tier pricing access across the Asia-Pacific package substation market. Buyers seeking arc-flash mitigation certification or IEC 61850 compliance face extended vendor qualification cycles that compress pricing elasticity for standardized designs.
Pricing Analysis
Input-cost pass-through from grain-oriented electrical steel and copper winding materials shapes contract structures across transformer procurement. Three-tier pricing structure across premium smart-grid-integrated, standard compact, and economy conventional electromechanical levels separates buyers by certification burden and remote monitoring capability. Pricing pressure stems from ASEAN domestic content rules forcing joint-venture overhead onto international vendors. State distribution companies in India exhibit highest price sensitivity due to tender-based volume procurement, while Australian mining operators prioritize availability guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for transformer cores and switchgear assemblies are tightening as utilities mandate backup qualification for critical components. Manufacturing concentrates in India, China, and South Korea for core stamping and winding operations, with Japan supplying specialized gas-insulated switchgear technology. Raw material dependencies center on grain-oriented electrical steel, copper rod, and epoxy resin insulation systems. Single-source vulnerability in electrical steel alloying elements exposes lead times to geopolitical friction. Distribution runs through integrated EPC contractors with pre-approved CEA designs in India and direct vendor relationships with mining operators in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific package substation market operates as a regulatory compounder where India's CEA Technical Standards for Connectivity and South Korea's KEPCO smart grid mandates continuously refresh equipment replacement cycles. These frameworks accelerate demand for digital-ready configurations while filtering out non-compliant vendors.
For Market Incumbents: Deploy captive sourcing of transformer core materials to defend margin position against grain-oriented electrical steel price volatility. Schneider Electric SE and Hitachi Energy Ltd should expand Indian manufacturing footprints to satisfy PLI scheme localization thresholds. Larsen & Toubro Limited must deepen protection relay integration capabilities to counter emerging software-defined substation specialists threatening EPC contract margins.
For New Entrants and Emerging Players: Tier-2 Indian industrial corridors with commissioning engineer scarcity present the most penetrable white-space target for specialized service contracting models. Indonesian archipelago electrification programs offer secondary entry through marine-transportable containerized formats underserved by established vendors. A go-to-market angle anchored in ten-year asset-as-a-service availability agreements bypasses capital purchase tender barriers.
For Investors and Strategic Acquirers: Roll-up economics work for regional compact design specialists because CEA standardization reduces engineering customization overhead and enables modular factory production at scale. Long-term viability hinges on software-defined protection and edge analytics integration. The signal to watch is KEPCO interoperability protocol adoption rates across ASEAN national utilities as inflection indicator for smart grid technology pull-through.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Material Supply | Captive electrical steel sourcing insulates Schneider Electric SE and Hitachi Energy Ltd from alloying element volatility. |
| Smart Grid Interoperability Certification | KEPCO protocol compliance opens South Korean municipal utility procurement to qualified vendors. |
| Asset-as-a-Service Contracting Model | Ten-year availability agreements with Australian iron ore producers displace capital purchase cycles. |
| Joint Venture Localization | Domestic content partnerships with Indonesian fabricators satisfy PLN tightening procurement criteria. |
| SF6 Alternative Gas-Insulated Switchgear Development | Japanese coastal utilities specify salt-contamination-resistant designs for underground vault installations. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both procurement volume patterns and vendor qualification dynamics. Primary discussions engaged utility planning officers at state distribution companies, EPC contractor procurement heads, transformer manufacturing plant managers, and mining camp power infrastructure leads. Secondary validation drew from CEA Technical Standards documentation, KEPCO smart grid protocol disclosures, Australian state electrical safety regulator filings, and ASEAN customs trade data. Bottom-up project pipeline aggregation and top-down regional demand estimation were cross-referenced for triangulation.
Segment-weighting approaches distributed value and volume projections across product type, technology tier, end-user vertical, and installation configuration dimensions. The analytical framework modeled growth trajectories across the projection horizon by applying penetration assumptions to utility capital expenditure budgets and industrial captive power expansion plans. CAGRs were derived from segment-level growth rate blending. Forecast inputs incorporated rural electrification program targets from Indonesia's PLN and India's industrial corridor manufacturing expansion timelines.
Underlying measurement precision varies by segment; containerized substation deployments in Australian mining carry tighter precision than modular formats across Indonesia's dispersed archipelago. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and material supply continuity. Deviation in CEA standardization adoption pace or electrical steel export restriction severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
HVDC Capacitor Market
Power
Rotating Phase Converter Market
Power
Electric Arc Furnaces Market
Power
Asia-Pacific Power Market
Power
Water Turbine Market
Power
Sudan Power Market
Power
Wind Turbine Drivetrain Market
Power
Malaysia Power EPC Market
Power
Critical Power Market
Power
Global Marine Power Systems Market
Power
LNG Power Barge Market
Power
Wireless Power Receiver Market
Power
Asia-Pacific Power Purchase Agreement Market
Power
Global Ancillary Services Power Market
Power
Steam Turbine MRO Market
Power
Resonant Power Converters Market