
 Europe Submarine Power Cables Market | 2026-2036
Europe Submarine Power Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Submarine Power Cables Market Foresight
Aftermarket service revenue is reshaping margin distribution across the Europe submarine power cables value chain as project lifespans extend beyond three decades. Prysmian Group leverages integrated installation and maintenance capabilities to capture recurring revenue streams alongside cable supply. NKT A/S anchors its competitive position through in-house manufacturing of high-voltage accessories and jointing systems that reduce third-party dependency.
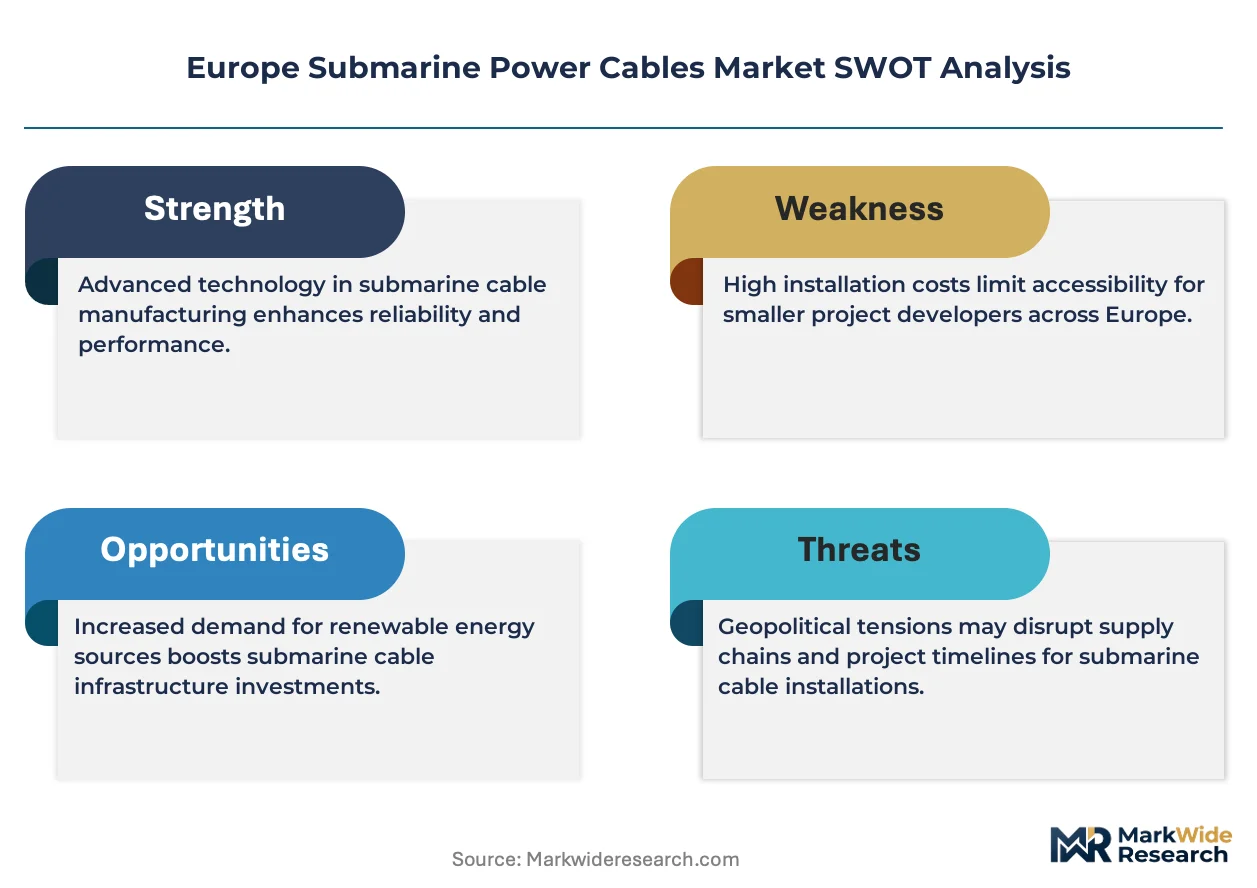
Europe submarine power cables are composite conductors comprising copper or aluminum cores, polymeric insulation layers, and armored protective sheaths engineered for subsea deployment at depths exceeding 1,000 meters, designed to transmit electrical power across marine environments with minimal dielectric loss. Extra high voltage installations dominate capital allocation as offshore wind farms migrate farther from shore and interconnectors span greater distances. XLPE insulation leads technology preference due to superior thermal performance and reduced maintenance requirements versus legacy EPR alternatives.
The EU Green Deal, REPowerEU, and CE marking directives under the EU AI Act's infrastructure provisions are mandating enhanced cable reliability standards and traceable supply chains for critical energy infrastructure. ECHA's REACH regulations constrain halogenated compound use in cable sheathing, pushing manufacturers toward alternative polymer formulations. Stakeholders must monitor interconnector licensing timelines and offshore wind auction schedules to align manufacturing capacity with project commissioning waves.
Market Dynamics
Offshore wind farm siting at distances exceeding 80 kilometers from shore is forcing voltage等级 upgrades across the Europe submarine power cables supply base, compressing delivery timelines and concentrating manufacturing capacity among firms with 525 kV+ qualification records.
Growth Catalysts
- REPowerEU framework:The EU's energy security initiative mandates accelerated interconnector deployment between member states, directly stimulating cross-border cable procurement.
- North Sea offshore wind lease rounds:Germany, Denmark, and the United Kingdom are auctioning seabed rights for multi-gigawatt projects requiring dedicated export cable infrastructure.
- XLPE insulation technology:Superior thermal rating versus EPR alternatives allows higher power transmission density, reducing cable count per gigawatt installed.
Market Restraints
- Copper price volatility:Raw material swings constitute 35-45% of cable manufacturing cost, compressing margin predictability for fixed-price EPC contracts.
- Installation vessel scarcity:Europe maintains fewer than 15 cable-laying ships capable of 1,000-meter depth operations, creating queuing delays.
- ECHA REACH compliance:Restrictions on halogenated flame retardants in cable sheathing force reformulation cycles that extend R&D timelines by 18-24 months.
Strategic Opportunities
- Baltic Sea interconnector mesh:Poland, Lithuania, and Latvia lack sufficient subsea grid links to Nordic synchronous area, representing greenfield project pipelines.
- Floating offshore wind:Dynamic cable systems for tension-leg and semi-submersible platforms require specialized fatigue-resistant designs absent from current product portfolios.
- EU Green Deal hydrogen backbone:Repurposed gas pipelines and new power-to-X interconnectors will demand hybrid electrical cables with integrated fiber monitoring.
Industry Challenges
- High-voltage jointing technician shortage:320 kV and 525 kV splice certification requires multi-year apprenticeship pipelines that outpace current training capacity.
- Type approval timelines:KEMA and DEKRA certification for new cable designs extends 14-18 months, misaligning with offshore wind auction award-to-construction schedules.
- Legacy grid interface compatibility:New HVDC links must synchronize with aging onshore substation infrastructure requiring costly converter station retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Submarine Power Cables Market |
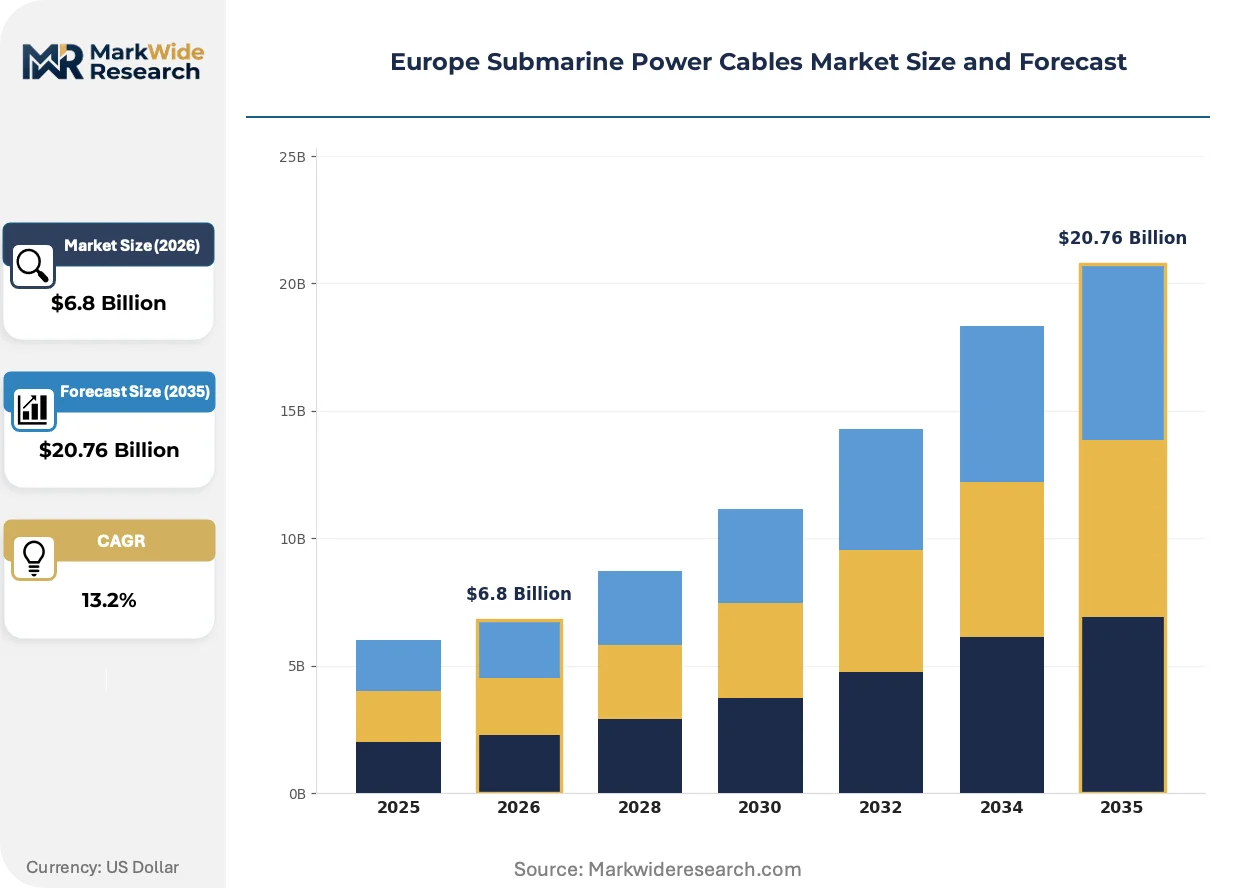
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Offshore Wind Farms, Interconnectors, Oil & Gas Platforms, Coastal Power Supply Insulation Type: XLPE, EPR, PVC, Polypropylene Voltage Level: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage End User: Utility Providers, Renewable Energy Companies, Industrial Plants, Government Agencies |
| Companies Covered | Prysmian Group, Nexans S.A., NKT A/S, Sumitomo Electric Industries, Ltd., Hitachi Energy, Furukawa Electric Co., Ltd., LS Cable & System Ltd., SSG Cable Group, TFKable, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Submarine Power Cables Market Shifts & Advancements
Material science advances and installation methodology refinements are compressing project delivery cycles while extending asset operational lifespans. The competitive frontier shifts toward integrated system performance rather than component specification alone.
Cross-linked polyethylene (XLPE) insulated cables rated to 525 kV are rendering obsolete mass-impregnated paper insulation for offshore wind export applications. Developers in the German Bight and Dogger Bank zones specify XLPE exclusively for projects exceeding 200 MW capacity. The technology is rendering obsolete EPR-based alternatives in the 66-220 kV range due to reduced maintenance windows and higher thermal load capacity.
CE marking directives under the EU AI Act's critical infrastructure provisions now mandate embedded fiber optic monitoring for all new submarine cable installations crossing EU territorial waters. Manufacturers must integrate distributed temperature and strain sensing during extrusion rather than post-installation retrofit. Offshore wind farm operators in Danish and German waters face the steepest compliance ramps as their project pipelines concentrate commissioning between 2027 and 2032.
Utility procurement teams are consolidating cable supply and installation contracts under single-source EPC arrangements rather than split-package tendering. This behavior compresses vendor qualification pools to firms with captive installation assets. The United Kingdom's CfD auction winners and Dutch offshore wind tender recipients demonstrate the strongest migration toward integrated contracting, driven by interface risk allocation concerns and warranty integration requirements.
Europe Submarine Power Cables Market Segmentation
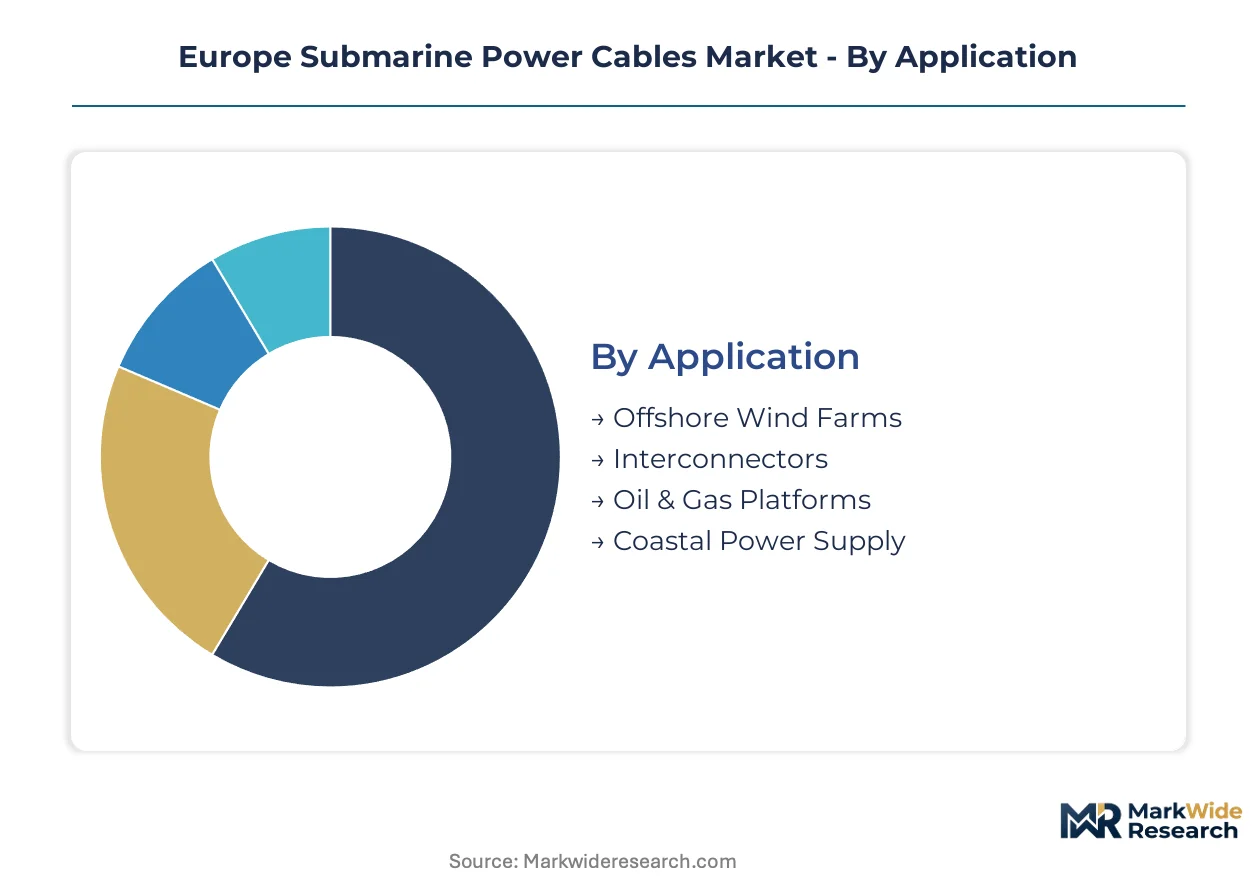
Segmentation of the Europe submarine power cables market reveals how technical specifications and application contexts dictate procurement patterns. Voltage requirements, insulation chemistry, and end-use environments create distinct demand clusters with divergent qualification barriers and margin profiles.
Application:
Mature offshore wind installations coexist with emerging interconnector corridors across the North and Baltic Seas.
- Offshore Wind Farms:Export cables connect turbine arrays to onshore substations across distances exceeding 80 kilometers in the German Bight and Dogger Bank zones. Prysmian and NKT dominate supply for projects above 200 MW capacity where 525 kV XLPE specifications are mandatory.
- Interconnectors:Cross-border links between EU member states synchronize grid frequency and enable renewable energy trading. REPowerEU funding accelerates procurement for Baltic Sea mesh projects linking Poland to Nordic synchronous areas.
- Oil & Gas Platforms:Electrification of North Sea extraction infrastructure replaces offshore diesel generation with subsea power feed from shore.
- Coastal Power Supply:Island interconnection and mainland redundancy projects serve Greek archipelagos and Scottish island clusters.
Offshore wind farms retain volume leadership; interconnectors hold the steepest expansion curve.
Insulation Type:
Cost tiers separate proven extruded compounds from legacy formulations facing regulatory pressure.
- XLPE:Cross-linked polyethylene dominates new procurement with thermal ratings supporting 525 kV transmission and reduced maintenance versus alternatives. Danish and German developers specify XLPE exclusively for projects commissioned through 2032.
- EPR:Ethylene propylene rubber serves lower-voltage distribution links and retrofit applications where installation flexibility outweighs thermal performance. ECHA REACH constraints on halogenated additives accelerate displacement by XLPE in new builds.
- PVC:Limited to shallow-water, low-voltage applications with minimal environmental exposure.
- Polypropylene:Emerging recyclable thermoplastic formulations target circular economy mandates in French and Dutch procurement frameworks.
XLPE commands the premium tier; polypropylene offers the most aggressive substitution trajectory against legacy chemistries.
Voltage Level:
Volume concentrates at utility-scale thresholds while specialized industrial links populate lower tiers.
- Extra High Voltage:Ratings at 320 kV and 525 kV serve offshore wind export and intercontinental interconnectors spanning the North Sea. Manufacturing qualification records concentrate supply among three European cable producers with KEMA-certified test facilities.
- High Voltage:110-220 kV links connect coastal substations and island networks across the Mediterranean basin.
- Medium Voltage:10-35 kV distribution serves oil platform electrification and near-shore wind arrays.
- Low Voltage:Specialized instrumentation and monitoring circuits integrated within composite cable bundles.
Extra high voltage absorbs the dominant capital share; medium voltage maintains the broadest project count across fragmented coastal applications.
End User:
Customer type determines contract structure, with integrated EPC terms favored by the largest procurement entities.
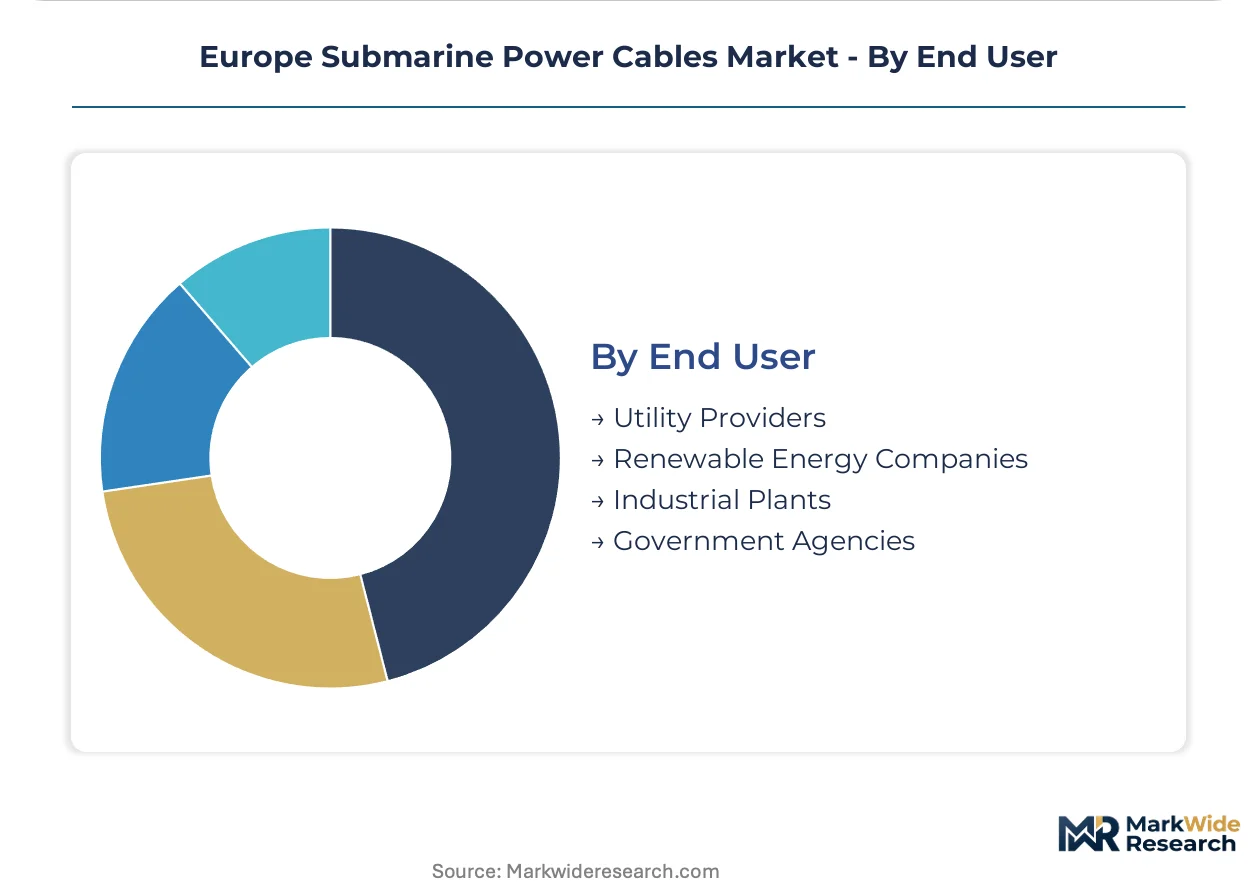
- Utility Providers:Transmission system operators in Germany, the United Kingdom, and Denmark consolidate cable supply with installation under single-source contracts to allocate interface risk.
- Renewable Energy Companies:Offshore wind developers prioritize warranty integration and maintenance service agreements extending across three-decade asset lifespans.
- Industrial Plants:Chemical and data center facilities near coastlines procure private interconnection for grid resilience.
- Government Agencies:Defense and maritime authorities commission hardened cables for naval base electrification and coastal monitoring infrastructure.
Utility providers anchor procurement volume; renewable energy companies drive specification innovation through aggregated offshore auction pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys submarine cables primarily for offshore wind export, whereas the United Kingdom and Denmark concentrate procurement on interconnector corridors. This consumption-mix differential shapes manufacturing qualification requirements across North Sea manufacturing clusters.
Germany
Offshore wind lease rounds in the German Bight drive demand for 525 kV XLPE export cables spanning 80-plus kilometer distances. The Federal Network Agency (Bundesnetzagentur) regulates grid connection timelines under the EnWG energy framework. Manufacturing concentrates in North Rhine-Westphalia where Prysmian and NKT operate high-voltage test facilities serving North Sea projects.
United Kingdom
Interconnector projects linking the UK to Norway, Denmark, and the Netherlands absorb the dominant cable procurement volume. Contracts for Difference (CfD) auctions administered by the Low Carbon Contracts Company mandate integrated EPC contracting for offshore wind developers. Cable-laying operations cluster around Scottish ports and the Humber estuary where installation vessel mobilization accelerates North Sea deployment schedules.
Denmark
Energy Island projects in the North Sea and Baltic Sea require multi-gigawatt transmission infrastructure connecting synthetic energy hubs to continental grids. The Danish Energy Agency coordinates seabed licensing with synchronized REPowerEU funding applications. Esbjerg anchors the national cable supply chain with dedicated offshore service vessel terminals and jointing technician training facilities.
Netherlands
Hollandse Kust offshore wind zones specify dynamic cable systems for floating platform electrification trials. The Netherlands Enterprise Agency (RVO) administers SDE++ subsidy schemes covering subsea grid infrastructure investments. Rotterdam port infrastructure supports cable storage and pre-assembly operations for Dogger Bank consortium projects.
Poland
Baltic Sea interconnector gaps to Sweden and Lithuania represent greenfield procurement opportunities under REPowerEU synchronization mandates. The Polish Energy Regulatory Office (URE) oversees cross-border transmission asset certification. Gdańsk and Szczecin port authorities are expanding heavy-lift quayside capacity to accommodate cable-laying vessel calls for planned Nordic links.
Europe Submarine Power Cables Market Competitive Landscape
Capability concentration sits with cable producers holding 525 kV XLPE qualification records; scale advantage sits with integrated EPC contractors controlling installation vessel fleets. The supply base consolidates around three European manufacturers with KEMA-certified test facilities and captive cable-laying assets. Strategic archetypes separate integrated system suppliers from component specialists and regional installation service providers. Dominant competitive moves include backward integration into high-voltage accessories manufacturing and exclusive vessel chartering agreements locking multi-year installation capacity.
Among Italy-based integrated cable manufacturers, Prysmian Group exemplifies the full-system supplier archetype through combined manufacturing and installation capabilities. Nexans S.A. represents the French engineering conglomerate model with diversified energy infrastructure portfolios. NKT A/S anchors the Nordic specialist position with in-house production of jointing systems and high-voltage termination technologies. These three firms occupy positions defining competitive boundaries for qualification barriers and EPC contracting terms across European offshore wind and interconnector procurement cycles.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans S.A. |
| NKT A/S |
| Sumitomo Electric Industries, Ltd. |
| Hitachi Energy |
| Furukawa Electric Co., Ltd. |
| LS Cable & System Ltd. |
| SSG Cable Group |
| TFKable |
| Others |
Supply & Pricing Matrix
Copper price volatility determines both pricing tier spreads and supply chain shape across the Europe submarine power cables market. Raw material swings constitute the dominant cost component, compressing margin predictability for fixed-price EPC contracts while forcing manufacturers toward long-term offtake arrangements with smelters.
Pricing Analysis
Long-term offtake contracts dominate procurement between cable manufacturers and offshore wind developers, insulating project economics from copper spot market fluctuations. Pricing stratifies across 525 kV XLPE premium tiers, high-voltage EPR mid-tier alternatives, and shallow-water PVC economy specifications. Cost compression in the mid-tier is intensifying because ECHA REACH compliance forces reformulation cycles that extend R&D timelines. Utility providers demonstrate the lowest price sensitivity due to integrated EPC contracting mandates, while industrial plants and coastal power suppliers exhibit higher elasticity.
Supply Chain Analysis
Cable-laying vessel operators in Norway, the Netherlands, and Germany hold concentrated installation capacity critical to project delivery timelines. Raw material feeds draw from Chilean copper cathode, Korean XLPE compound, and Belgian steel wire armoring. Single-source vulnerability sits with the fewer than fifteen European vessels capable of 1,000-meter depth operations. Distribution runs through port-centric pre-assembly hubs at Esbjerg, Rotterdam, and Scottish east coast terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among transmission system operators consolidating cable supply with installation under single-source EPC contracts. This consolidation fragments pricing leverage for component specialists without captive vessel assets.
For Market Incumbents: Pre-empt emerging jointing technician shortages by expanding apprenticeship pipelines at Esbjerg and North Rhine-Westphalia training facilities. Lock multi-year vessel chartering agreements before Baltic Sea interconnector procurement waves accelerate. Backward integration into high-voltage termination manufacturing reduces third-party dependency as KEMA certification timelines extend.
For New Entrants and Emerging Players: Pursue dynamic cable system development for floating offshore wind platforms in Dutch and Norwegian waters, where specialized fatigue-resistant designs remain absent from current portfolios. Target Baltic Sea interconnector gaps between Poland and Nordic synchronous areas as the most penetrable geography. Partner with port authorities at Gdańsk and Szczecin for cable storage and pre-assembly operations.
For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors integrated EPC contractors with captive installation assets and 525 kV XLPE qualification records. Long-term viability hinges on manufacturing scale and vessel access rather than component specialization alone. Monitor interconnector licensing timelines and offshore wind auction award schedules as the primary inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Vessel Chartering Lock-up | Secures scarce installation capacity ahead of Baltic Sea and North Sea commissioning waves. |
| Jointing Technician Apprenticeship Expansion | Addresses 320 kV and 525 kV splice certification gaps at Danish and German training facilities. |
| XLPE Compound Backward Integration | Reduces exposure to Korean and Belgian polymer supply disruptions under ECHA REACH constraints. |
| Fiber Optic Monitoring Integration | Aligns with EU AI Act CE marking mandates for embedded distributed sensing in territorial waters. |
| Baltic Sea Port Partnership | Establishes pre-assembly presence at Gdańsk and Szczecin for planned Poland-Nordic interconnectors. |
Research Methodology
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings across the Europe submarine power cables market. Utility planning officers, offshore wind project developers, EPC contractors, cable-laying vessel operators, and grid interconnection specialists provided forward procurement visibility. Secondary validation drew from Bundesnetzagentur grid connection filings, Danish Energy Agency seabed licensing records, ECHA REACH regulatory updates, and Low Carbon Contracts Company CfD auction documentation. Bottom-up project pipeline aggregation and top-down macro demand modeling were reconciled through iterative calibration.
Calibration against historical commissioning timelines and announced project award schedules shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include voltage level, insulation chemistry, application context, and end-user contract structure. CAGRs were derived from project-level capacity buildout trajectories and interconnector funding authorization patterns. Forecast inputs incorporated REPowerEU disbursement schedules and offshore wind lease round sequencing.
Macroeconomic conditions sit as an overlay; deviation in copper price volatility, installation vessel day-rate inflation, or ECHA regulatory stringency would shift the trajectory. Forecasts reflect documented assumptions regarding project sanctioning rates and cross-border permitting efficiency. Quarterly review of interconnector licensing timelines, offshore wind auction award announcements, and cable-laying vessel chartering activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Asia-Pacific Turbomachinery Control Systems Market
Power
Doubly Fed Induction Generator (DFIG) Market
Power
Global Ancillary Services Power Market
Power
Global Marine Power Systems Market
Power
Distribution Feeder Protection System Market
Power
Modified Sine Wave Home Inverters Market
Power
Flue Gas Desulfurization Unit Market
Power
Steam Turbine MRO Market
Power
Asia-Pacific Alternating Current (AC) Drive Market
Power
Saudi Arabia Power Market
Power
Argentina Power Market
Power
India Uninterruptible Power Supply (UPS) Market
Power
India Power Market
Power
Global Hydraulic Turbine Market
Power
Residential Micro Inverter Market
Power
HVDC Capacitor Market