
 Angola Power EPC Market | 2026-2036
Angola Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Angola Power EPC Market Outlook
Grid-code compliance tier is collapsing the gap between legacy diesel installations and modern hybrid configurations. Siemens leverages its technology leadership in gas turbine integration to anchor large-scale utility projects. AEE Power Corporation sustains geographic dominance across Angola's northern provinces through entrenched government relationships. Elecnor competes on European-standard project execution, differentiating its offering from local competitors.
Angola Power EPC encompasses the integrated design, sourcing, and build-out of generation, transmission, and distribution infrastructure, typically executed under lump-sum turnkey contracts with performance guarantees tied to installed capacity and grid synchronization parameters. The primary purpose is delivering operational energy assets from concept to commissioning without fragmented contractor handoffs. Renewable energy technology is attracting the fastest-growing capital allocation as solar PV and wind hybrid systems displace fuel-import dependency. Conventional energy retains the largest project pipeline value, though margin pools are shifting toward energy storage integration and project management services where technical complexity commands premium pricing.
Angola's national energy regulator, the Ministry of Energy and Water's electricity department, and the country's environmental licensing authority collectively enforce technical standards, environmental impact requirements, and local content rules that shape contractor qualification and equipment sourcing decisions. These frameworks compel foreign EPC firms to partner with domestic entities and source specified shares of labor and materials locally. Stakeholders must monitor how evolving grid interconnection standards and renewable purchase obligations redirect project origination toward hybrid system specialists.
Market Dynamics
Grid-code compliance tier is collapsing the gap between legacy diesel installations and modern hybrid configurations, forcing EPC contractors to reengineer project architectures around synchronous condenser requirements and inverter-based resource integration.
Growth Catalysts
- Rural electrification mandates:Government-backed programs accelerate municipal grid buildouts across Angola's interior provinces, creating sustained demand for distribution infrastructure.
- Hybrid system adoption:Solar PV and wind hybrid configurations displace fuel-import dependency, redirecting capital allocation toward integrated renewable EPC contracts.
- Luanda-Benguela corridor industrialization:Load center clustering in this coastal corridor concentrates demand for transmission upgrades and substation expansion.
Market Restraints
- Local content requirements:Angola's Ministry of Energy and Water mandates specified shares of domestic labor and materials, inflating procurement timelines and compliance costs.
- Equipment import dependency:Critical power electronics and gas turbine components concentrate sourcing with European and Asian suppliers, exposing projects to currency volatility and shipping delays.
- Grid synchronization complexity:Legacy diesel infrastructure lacks modern frequency response capabilities, requiring expensive retrofitting to interconnect with renewable assets.
Strategic Opportunities
- Energy storage integration:Battery hybridization commands premium pricing pools as grid operators seek firm capacity from variable renewable resources.
- Northern province expansion:Underpenetrated markets in Cabinda and Zaire provinces offer first-mover positioning for contractors with established government relationships.
- Project management service unbundling:Technical complexity is driving owner-operators to separate engineering oversight from construction execution, creating specialized advisory revenue streams.
Industry Challenges
- Grid-code certification timelines:Angola's national energy regulator continues tightening technical standards, extending commissioning schedules for interconnected assets.
- Skilled technician scarcity:Specialized inverter commissioning and SCADA integration expertise remains concentrated with expatriate workforces, inflating labor costs.
- Legacy system integration friction:Brownfield substation upgrades require custom protection relay configurations, complicating standardized EPC delivery models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angola Power EPC Market |
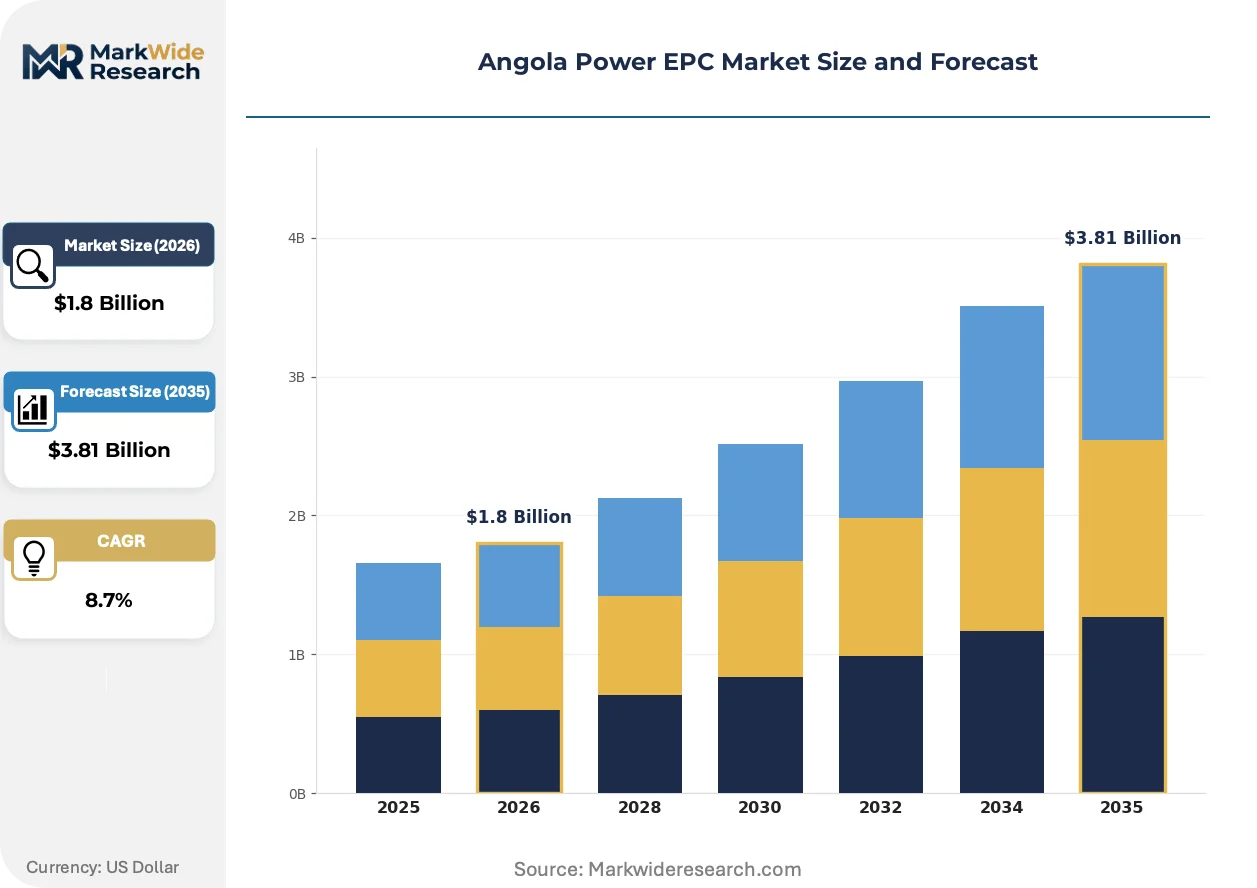
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engineering, Procurement, Construction, Project Management Technology: Renewable Energy, Conventional Energy, Hybrid Systems, Energy Storage End User: Government, Industrial, Commercial, Residential Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | AEE Power Corporation, EDG Angola, Isolux Corsan, Elecnor, Novonor, Gesto-Energia, Siemens, Mecwide, Anglo Belgian Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angola Power EPC Market Strategic Shifts
Containerized power electronics and modular substation architectures are compressing project delivery schedules while enabling phased capacity expansion. These shifts favor contractors with standardized design libraries over bespoke engineering approaches.
Modular inverter platforms are miniaturizing utility-scale solar conversion equipment, reducing footprint requirements for congested substation sites. Industrial offtakers in the Lobito corridor are specifying these systems to accelerate permitting timelines. The technology is miniaturizing balance-of-plant costs and enabling distributed generation clusters without dedicated switchyard construction.
Angola's environmental licensing authority has tightened cumulative impact assessments for watershed-adjacent thermal projects, extending approval timelines for combined-cycle gas turbine installations. This regulatory friction is redirecting developer attention toward solar PV and battery hybrids with streamlined permitting pathways. Northern province projects face heightened scrutiny, compressing margins for conventional EPC proposals.
Turnkey contracting is fragmentating into multi-package delivery models as owner-operators seek to isolate construction risk from equipment performance guarantees. State-owned utilities in the Luanda metropolitan zone now favor split EPC arrangements separating civil works from electromechanical installation. This behavioral shift is visible across Portuguese-speaking African markets where sovereign credit constraints favor milestone-based payment structures over lump-sum commitments.
Angola Power EPC Market Segmentation
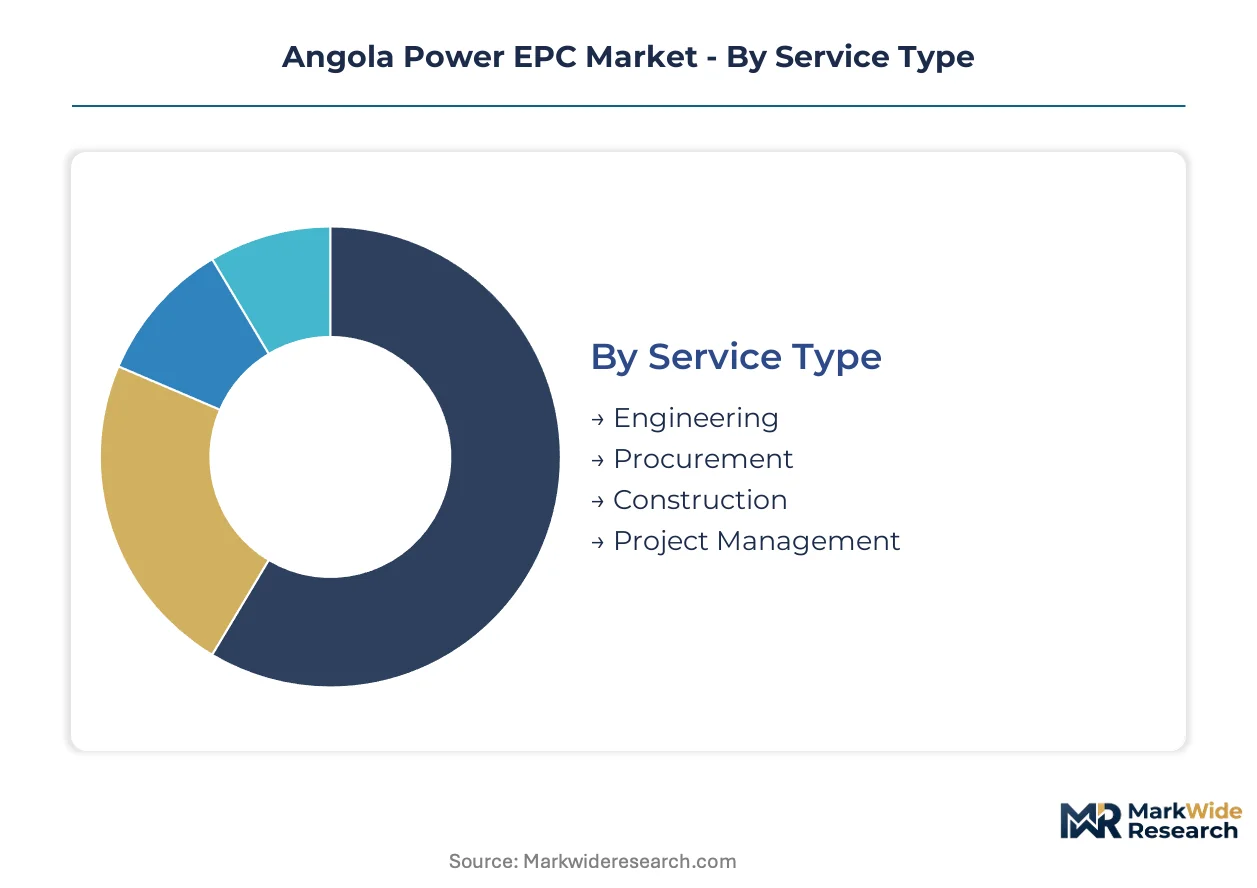
Segmentation in Angola's Power EPC market reveals how contract structures, technology choices, and client profiles redistribute risk and margin across the value chain. Contractors must align capabilities with specific segment requirements to capture premium pricing pools.
Service Type:
Margin pools concentrate in integrated delivery models where performance guarantees command risk premiums.
- Engineering:Front-end design services encompass grid interconnection studies, substation layout optimization, and protection relay configuration for Angola's tightening technical standards. Demand clusters with state-owned utilities in Luanda seeking IEC-compliant documentation for rural electrification tenders.
- Procurement:Equipment sourcing spans gas turbines from European suppliers, containerized inverters from Asian manufacturers, and local content-compliant materials. Currency volatility and shipping delays inflate contingency reserves, compressing margins for fixed-price contracts.
- Construction:Civil works and electromechanical installation face skilled technician scarcity, particularly for SCADA integration and inverter commissioning. Expatriate labor premiums erode profitability on brownfield substation upgrades.
- Project Management:Owner-operators increasingly unbundle oversight from execution, creating specialized advisory revenue streams. Technical complexity around grid synchronization and hybrid system integration supports premium pricing for experienced firms.
The dominant share belongs to Construction, while Project Management is closing the gap fastest as risk isolation reshapes contracting models.
Technology:
Capital allocation patterns reveal a shift from fuel-import dependency toward domestic resource utilization.
- Renewable Energy:Solar PV and wind installations displace diesel generation across Angola's interior provinces. Containerized power electronics and modular architectures compress delivery schedules while enabling phased expansion for municipal grids.
- Conventional Energy:Combined-cycle gas turbine projects retain the largest pipeline value despite tightened environmental licensing for watershed-adjacent thermal plants. Legacy diesel infrastructure requires expensive retrofitting for grid synchronization with renewable assets.
- Hybrid Systems:Solar-diesel and wind-battery configurations anchor rural electrification programs, collapsing the gap between legacy installations and modern grid architectures. Synchronous condenser requirements drive engineering complexity.
- Energy Storage:Battery hybridization commands premium pricing as grid operators seek firm capacity from variable resources. Lithium-ion systems integrate with utility-scale solar in the Luanda-Benguela corridor.
Conventional Energy still captures the dominant share, though Renewable Energy is expanding most quickly as environmental licensing friction redirects developer attention.
End User:
Contractor qualification requirements and payment security vary sharply across client categories.
- Government:State-owned utilities and rural electrification agencies drive infrastructure buildouts through sovereign-backed tenders. Local content mandates from Angola's Ministry of Energy and Water complicate procurement timelines.
- Industrial:Mining and manufacturing offtakers in the Lobito corridor specify modular systems to accelerate permitting. Load center clustering concentrates demand for transmission upgrades and dedicated substations.
- Commercial:Urban developers and retail chains seek distributed generation solutions with streamlined interconnection. C&I solar installations face grid-code certification delays from the national energy regulator.
- Residential:Mini-grid and standalone solar systems serve off-grid populations in Cabinda and Zaire provinces. First-mover contractors with established government relationships capture underpenetrated markets.
Government contracts dominate volume, while Industrial is gaining share fastest as private offtakers pursue energy cost reduction.
Project Size:
Economies of scale in risk underwriting and equipment procurement reshape competitive positioning across scale tiers.
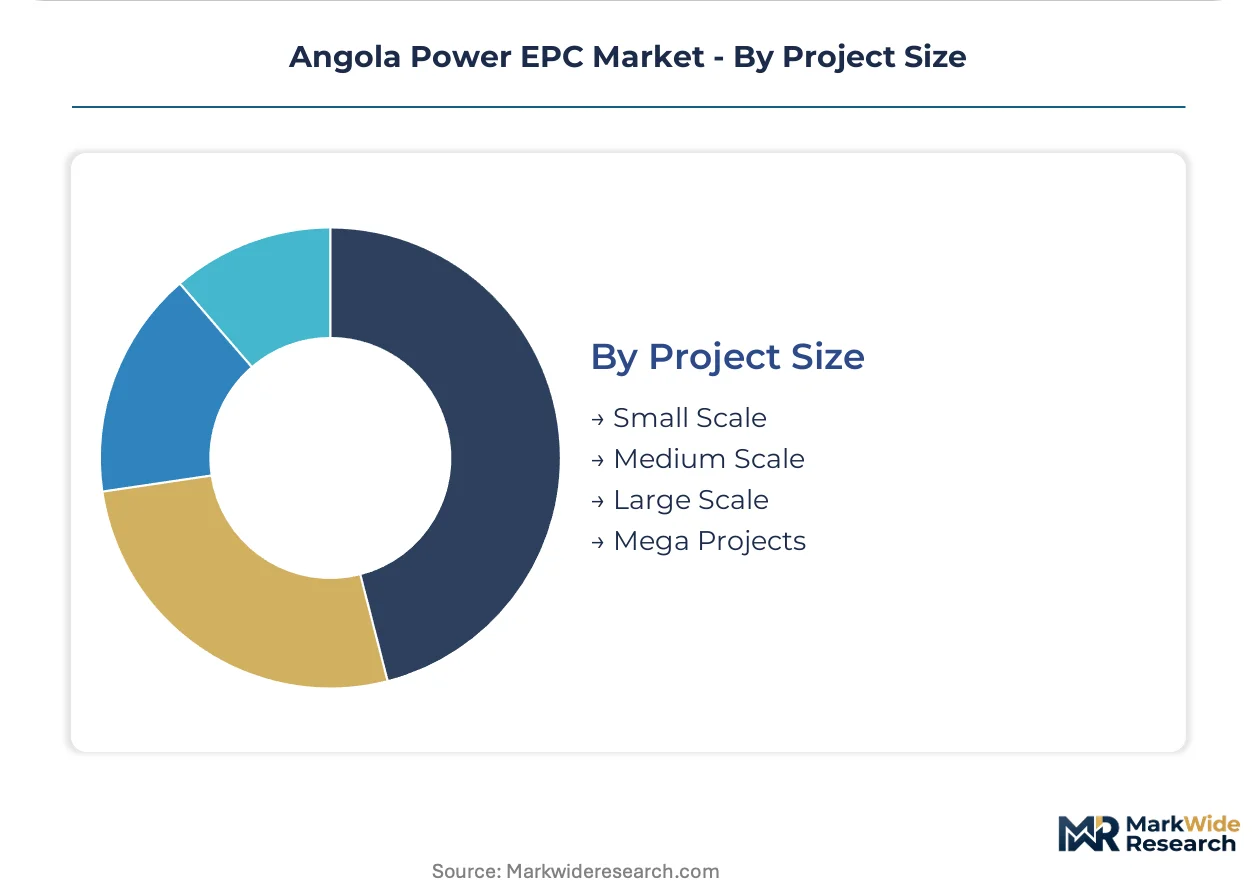
- Small Scale:Distributed solar and diesel generator installations below 10 MW serve commercial and residential microgrids. Standardized design libraries enable rapid deployment with limited customization.
- Medium Scale:Municipal grid extensions and industrial captive plants between 10-50 MW balance standardization with site-specific engineering. Northern province expansion concentrates opportunity here.
- Large Scale:Utility-scale renewable and gas-fired plants above 50 MW require lump-sum turnkey execution with performance guarantees. Siemens anchors this segment through gas turbine integration leadership.
- Mega Projects:National transmission backbone and multi-gigawatt generation complexes demand consortium structures and multilateral financing. Extended commissioning schedules test contractor balance sheet capacity.
Large Scale projects hold the dominant share, while Small Scale is climbing the fastest as modular architectures democratize access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Angola exports electricity infrastructure expertise across the Central African Power Pool, with South Africa and Zambia serving as primary buyer geographies for cross-border transmission consulting and equipment procurement.
Luanda Province
Industrial load centers and state-owned utility headquarters concentrate EPC demand for transmission upgrades and substation expansion. Angola's Ministry of Energy and Water enforces local content mandates that complicate procurement timelines for foreign contractors. The Luanda metropolitan zone anchors national grid synchronization efforts, with Siemens leveraging gas turbine integration capabilities for utility-scale projects.
Benguela Province
Mining and manufacturing offtakers in the Lobito corridor specify modular solar-diesel hybrid systems to reduce fuel-import dependency. The national energy regulator tightens grid-code certification requirements for interconnected assets, extending commissioning schedules. Industrial clustering along the coastal corridor drives demand for dedicated substations and medium-voltage distribution infrastructure.
Northern Provinces (Cabinda and Zaire)
Underpenetrated markets create first-mover positioning for contractors with established government relationships in rural electrification programs. AEE Power Corporation sustains geographic dominance through entrenched institutional connections. Mini-grid and standalone solar deployments serve off-grid populations where municipal grid extension remains economically prohibitive.
Huíla and Huambo Provinces
Interior agricultural processing and small-scale manufacturing generate distributed generation demand for standardized design libraries. The environmental licensing authority applies streamlined permitting pathways for solar PV and battery hybrids versus thermal alternatives. Municipal grid buildouts accelerate across Angola's central highlands as government-backed electrification mandates redirect capital allocation.
Namibe Province
Port infrastructure and logistics hubs require reliable captive power solutions with firm capacity guarantees. Grid synchronization complexity with legacy diesel infrastructure forces expensive retrofitting for renewable interconnection. The coastal location enables wind resource exploitation, attracting hybrid system specialists seeking phased expansion opportunities.
Angola Power EPC Market Competitive Environment
Listed leaders compete with private specialists across technology integration capabilities and government relationship depth. The vendor base organizes around three strategic archetypes: European-standard execution specialists, technology-anchored multinationals, and relationship-driven local champions. Consolidation pressure concentrates in large-scale utility segments where lump-sum turnkey contracts demand balance sheet capacity. Dominant competitive moves include strategic partnerships with domestic entities to satisfy local content requirements and technology licensing arrangements for modular power electronics.
Within the local relationship tier, AEE Power Corporation exemplifies entrenched positioning across Angola's northern provinces. Among European-originated execution specialists, Elecnor represents project delivery differentiation through IEC-compliant documentation and standardized methodologies. At the technology-anchored end, Siemens occupies a position defined by gas turbine integration leadership and synchronous condenser engineering capabilities for hybrid system architectures.
| Leading Market Players |
|---|
| AEE Power Corporation |
| EDG Angola |
| Isolux Corsan |
| Elecnor |
| Novonor |
| Gesto-Energia |
| Siemens |
| Mecwide |
| Anglo Belgian Corporation |
| Others |
Value Chain & Pricing Dynamics
Angola's Ministry of Energy and Water local content mandates gate both contractor qualification and price differentiation, compelling foreign EPC firms to absorb partnership premiums while domestic champions capture margin on labor arbitrage. Grid-code certification tiers from the national energy regulator simultaneously segment pricing across synchronous condenser-equipped hybrids versus legacy diesel retrofits.
Pricing Analysis
Industrial offtakers in the Lobito corridor anchor project-based pricing structures with performance guarantees tied to grid synchronization parameters. Three-tier pricing stratifies across IEC-certified premium execution, standard municipal grid compliance, and economy-tier rural electrification packages. Cost compression in the economy tier intensifies as modular inverter platforms commoditize balance-of-plant engineering. Government-backed rural electrification agencies exhibit highest price sensitivity, while mining operators in the Luanda-Benguela corridor prioritize firm capacity over unit economics.
Supply Chain Analysis
Container availability constraints on the Asia-West Africa trade lane inflate inbound logistics costs for power electronics and gas turbine components. Equipment sourcing concentrates in Germany, China, and South Korea for critical inverters, switchgear, and generation hardware. Raw material dependencies span lithium-ion cells, copper busbars, and specialized magnetic steel. Single-source vulnerability around European gas turbine suppliers exposes projects to extended lead times. Distribution runs through Luanda port consolidation followed by provincial road networks to interior substation sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Angola Power EPC demand follows extractive industry capital cycles, with mining investment recoveries historically preceding utility-scale generation awards by 18-24 months.
For Market Incumbents: Fortify position through backward integration into containerized power electronics assembly within Angola's free trade zones, satisfying local content thresholds while capturing margin currently surrendered to Asian suppliers. Anchor relationships with the Ministry of Energy and Water through dedicated rural electrification program offices in Cabinda and Zaire provinces before competitor entrants replicate AEE Power Corporation's northern province dominance. For New Entrants and Emerging Players: Grid-code certification fast-tracks for solar-diesel hybrid configurations offer the most penetrable entry vector, as Angola's national energy regulator streamlines permitting for inverter-based resources versus thermal alternatives. Target underpenetrated municipal grids in Huíla and Huambo provinces where standardized design libraries enable rapid deployment without entrenched incumbent relationships. Lead with energy storage integration capabilities to command premium pricing pools unavailable to pure-play construction contractors. For Investors and Strategic Acquirers: Tightened environmental licensing for watershed-adjacent thermal projects reshapes the acquisition landscape, redirecting developer pipelines toward solar-battery hybrids with streamlined permitting pathways. Mid-scale EPC specialists with demonstrated grid synchronization expertise and established government relationships represent the most defensible acquisition archetypes over the coming decade. Monitor cumulative impact assessment approval timelines as the inflection signal for capital allocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Local Content Partnership Structuring | Joint ventures with Angolan entities satisfy Ministry mandates while preserving equipment sourcing flexibility. |
| Modular Inverter Platform Deployment | Containerized architectures compress commissioning schedules for congested Luanda-Benguela substation sites. |
| Energy Storage Integration Capability | Battery hybridization commands premium pricing as grid operators seek firm capacity from variable renewables. |
| Northern Province Geographic Expansion | First-mover positioning in Cabinda and Zaire captures rural electrification program flows before incumbent lock-in. |
| Grid-Code Certification Pre-Investment | Early synchronous condenser engineering capabilities accelerate interconnection approvals for hybrid system tenders. |
Study Parameters
Cross-validation between primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators anchors the qualitative findings, supplemented by secondary validation against IEA power sector reports, FERC-equivalent regulatory filings, and project development databases. Bottom-up segmentation modeling triangulates with top-down macroeconomic indicators across the analysis window.
Sensitivity analysis frameworks test demand elasticity across fuel source, generation capacity tier, and project scale dimensions. CAGRs derive from equipment shipment trajectories and contract award patterns rather than single-point estimates. Forecast inputs incorporate grid interconnection queue depths and environmental licensing approval velocity specific to Angola's regulatory environment.
Decision-makers should treat outputs as directional under base assumptions of sustained mining sector recovery and stable currency convertibility; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Europe Power Purchase Agreement Market
Power
Power Rental Market
Power
India Uninterruptible Power Supply (UPS) Market
Power
North America Microturbine Market
Power
Single-Phase Microinverter Market
Power
HVDC Capacitor Market
Power
Wireless Power Receiver Market
Power
Vietnam Power Market
Power
North America Micro CHP Market
Power
Marine Thermal Fluid Heaters Market
Power
Nigeria Power Market
Power
Substation Automation System Market
Power
Kuwait Power Market
Power
Smart Power Market
Power
Japan Uninterrupted Power Supply (UPS) Market
Power
Brazil Power Market