
 India Power Market | 2026-2036
India Power Market Size, Share, and Industry Trends Forecast 2026-2036
India Power Market Outlook
Polysilicon supply diversification away from dominant Chinese sources is recalibrating module economics for Indian solar developers. NTPC Limited sustains the largest thermal-renewable blended portfolio and channels capital into green hydrogen pilots. Tata Power Company Limited anchors distributed solar and EV charging infrastructure across Maharashtra and Delhi. Adani Green Energy Limited dominates utility-scale renewable additions with vertical control from module manufacturing to generation assets.
India Power encompasses electricity generation, transmission, and distribution infrastructure spanning fuel sources from coal and natural gas to solar photovoltaics, wind turbines, and nuclear fission reactors rated by megawatt capacity, grid frequency standards of 50 Hz, and voltage classes from 11 kV distribution to 765 kV transmission corridors. The system delivers commercial and industrial load supply, rural electrification, and grid stabilization services across a geographically fragmented network. Thermal generation occupies the largest installed base though renewable capacity additions now lead annual commissioning trends. Utility-scale solar and wind installations attract the majority of new investment while distributed generation segments gain policy support through rooftop solar mandates and agricultural pump electrification schemes.
The Central Electricity Authority enforces grid codes and renewable purchase obligations that mandate distribution companies procure minimum clean energy shares. BIS certification standards govern solar module efficiency ratings and inverter performance benchmarks that shape equipment procurement decisions. State electricity regulatory commissions set tariffs and approve power purchase agreements that determine project bankability across jurisdictions. Stakeholders must monitor state-level renewable purchase obligation compliance trajectories and interstate transmission corridor auctions to anticipate offtake competition and congestion pricing patterns.
Market Dynamics
Capital reallocation from thermal baseload to solar-wind hybrid portfolios is compressing project development timelines and reshaping lender risk assessments across India's power sector. The Central Electricity Authority's renewable purchase obligations now mandate distribution companies procure escalating clean energy shares, forcing procurement model overhauls.
Growth Catalysts
- Green Hydrogen Mission:The Ministry of New and Renewable Energy's production-linked incentive scheme redirects industrial offtake toward electrolyzer-integrated renewable parks. Steel and cement manufacturers anchor contracted demand.
- Solar-Wind Hybrid Policies:Gujarat and Rajasthan state governments allocate transmission corridor priority to hybrid projects. Land use efficiency gains attract foreign direct investment into these corridors.
- Polysilicon Supply Diversification:Module manufacturers in India source wafers from Southeast Asian and domestic ingot producers. This supply base expansion reduces input cost volatility for developers.
Market Restraints
- Interstate Transmission Congestion:The Western and Southern regional grids face evacuation bottlenecks for Rajasthan solar parks. Central Electricity Regulatory Commission congestion pricing erodes project returns.
- Distribution Company Financial Stress:State electricity boards in Tamil Nadu and Maharashtra accumulate payment delays. Renewable generators bear working capital strain from late offtake settlements.
- Land Acquisition Friction:Solar park development encounters rehabilitation and resettlement disputes in Gujarat. Project commissioning schedules stretch beyond original power purchase agreement tenors.
Strategic Opportunities
- Agricultural Pump Electrification:The KUSUM scheme funds decentralized solar installations across Punjab and Haryana. Rural load growth outpaces urban demand in several state jurisdictions.
- EV Charging Infrastructure:Maharashtra and Delhi regulatory commissions mandate distribution licensees deploy public charging networks. Grid-edge storage integration creates new revenue streams for utilities.
- Rooftop Solar Mandates:Commercial and industrial building codes in Karnataka and Telangana prescribe minimum renewable generation capacity. Engineering procurement construction firms pivot toward distributed project execution.
Industry Challenges
- Grid Code Compliance Complexity:Central Electricity Authority frequency response standards require inverter firmware upgrades. Retrofit timelines compress for operational solar assets.
- Skilled Technician Scarcity:High-voltage substation commissioning and hybrid control system integration outpace vocational training output. Project developers poach talent from thermal plant operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Power Market |
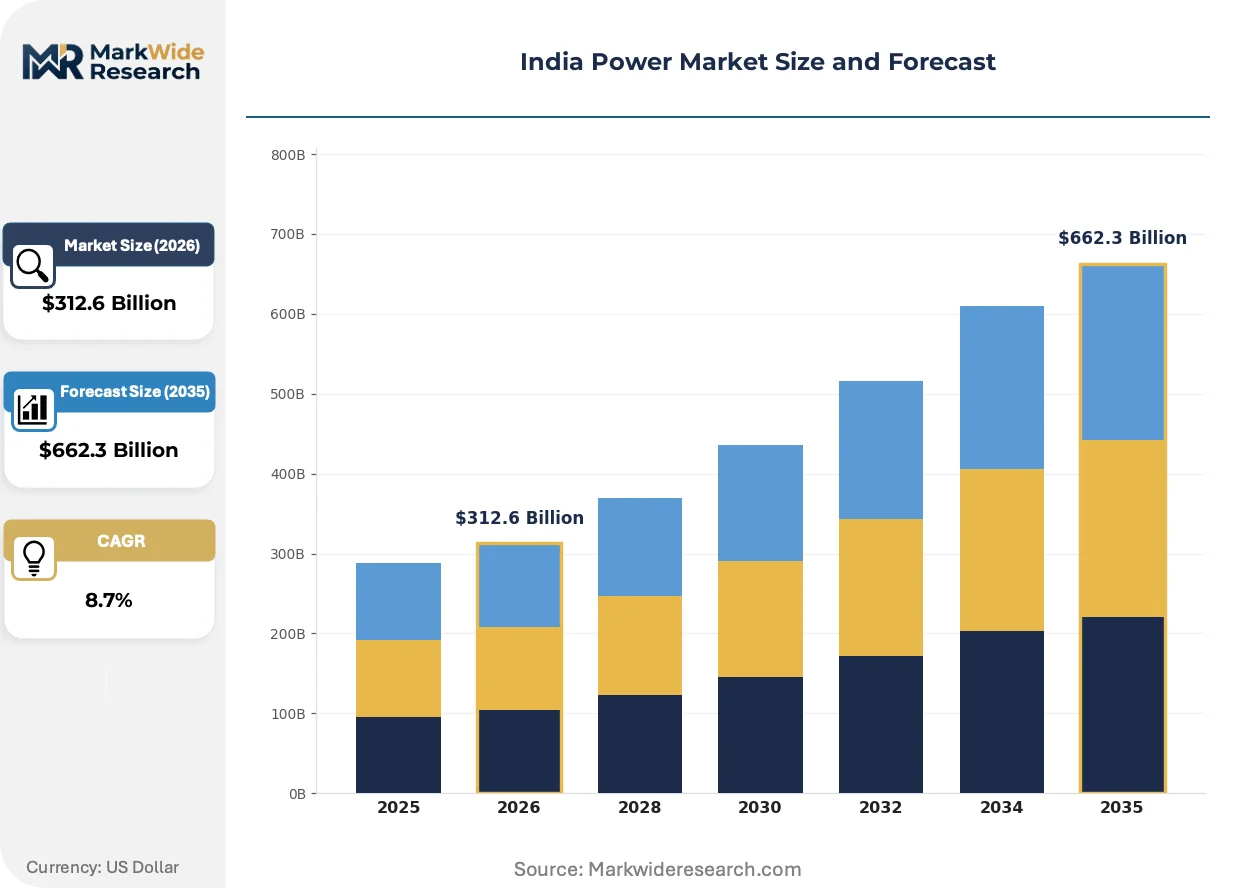
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable, Thermal, Nuclear, Hydropower End User: Residential, Industrial, Commercial, Agricultural Technology: Solar, Wind, Biomass, Geothermal Installation: Utility-Scale, Distributed Generation, Off-Grid, On-Grid |
| Companies Covered | Adani Green Energy Limited, JSW Energy Limited, NTPC Limited, NTPC Green Energy Limited, ReNew Power, Power Grid Corporation of India Limited, Tata Power Company Limited, Suzlon Energy Limited, Adani Power Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Power Market Strategic Shifts
Bifacial module technology and floating solar installations are rewriting project economics for Indian developers. Regulatory mandates on renewable purchase obligations and green hydrogen production are tightening compliance frameworks. Industrial buyers are consolidating procurement through long-term power purchase agreements rather than spot market exposure.
TOPCon cell architecture is rewriting efficiency benchmarks for utility-scale solar plants. NTPC and state gencos specify these modules for new tenders. The technology enables higher DC-AC ratios and reduced land requirements per megawatt, compressing levelized cost trajectories for Rajasthan and Gujarat projects.
The Green Hydrogen Mission production-linked incentive scheme is mandating electrolyzer manufacturing capacity buildout. MNRE guidelines require domestic value addition for subsidy eligibility. Steel and fertilizer sectors in Odisha and Chhattisgarh anchor offtake commitments, though execution timelines remain contingent on electrolyzer cost curves.
Corporate renewable energy procurement is consolidating around group captive structures rather than open access arrangements. Large manufacturing clusters in Maharashtra and Tamil Nadu establish special purpose vehicles with generation assets. This model bypasses distribution company scheduling charges and reduces regulatory exposure for industrial buyers.
India Power Market Segmentation
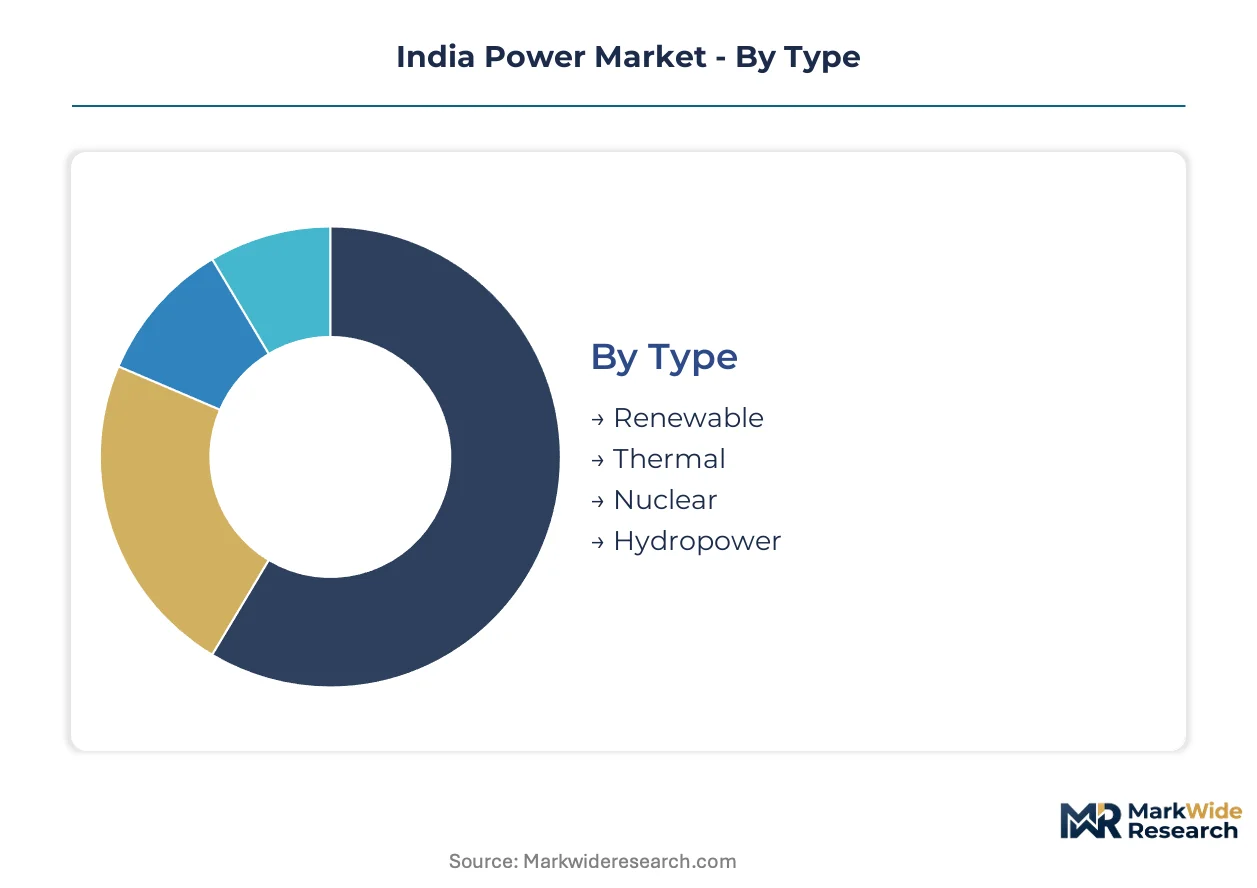
Segmentation in the India Power Market reveals how capital allocation, regulatory mandates, and grid infrastructure constraints shape procurement decisions across generation technologies and customer categories. Understanding these divides allows stakeholders to anticipate where renewable purchase obligations, industrial offtake contracts, and rural electrification schemes will concentrate investment.
Type:
Thermal generation commands the largest installed base while renewable capacity additions now dominate annual commissioning flows. Volume leadership sits with legacy coal assets. Premium growth attaches to clean energy segments.
- Renewable:Solar photovoltaics and wind turbines constitute the fastest-expanding generation category under Central Electricity Authority renewable purchase obligations. Gujarat and Rajasthan solar parks anchor utility-scale additions, though interstate transmission congestion creates evacuation bottlenecks that erode project returns.
- Thermal:Coal-fired plants retain dominant dispatch priority and grid stabilization services despite stagnant capacity growth. NTPC Limited sustains the largest blended thermal-renewable portfolio while channeling capital into green hydrogen pilots that repurposes existing land and transmission access.
- Nuclear:Fission reactors rated at 220 MW and 700 MW unit sizes provide baseload zero-carbon generation concentrated in Tamil Nadu and Gujarat coastal locations. Regulatory approvals and fuel import dependencies constrain expansion timelines.
- Hydropower:Run-of-river and pumped storage installations in Himalayan states supply peaking capacity and grid balancing services. Environmental clearances and geological risks stretch development schedules beyond thermal project timelines.
Today's leader: Thermal. Tomorrow's challenger: Renewable.
End User:
Cost tier differentiation separates price-sensitive agricultural loads from premium industrial offtake that commands firm supply contracts and renewable energy certificates.
- Industrial:Steel and cement manufacturers anchor contracted renewable offtake through group captive structures that bypass distribution company scheduling charges. Maharashtra and Tamil Nadu manufacturing clusters establish special purpose vehicles with dedicated generation assets.
- Commercial:Office complexes and retail chains in Karnataka and Telangana face building code mandates prescribing minimum rooftop solar capacity. Engineering procurement construction firms pivot toward distributed project execution for this segment.
- Residential:Urban households and apartment blocks access subsidized tariffs through state electricity boards that cross-subsidize from industrial ratepayers. Smart meter deployment lags behind commercial and industrial metering penetration.
- Agricultural:The KUSUM scheme funds decentralized solar pump installations across Punjab and Haryana. Rural load growth outpaces urban demand in several state jurisdictions, though payment collection rates trail commercial segments.
Industrial buyers capture premium supply terms. Agricultural electrification scales fastest by unit count.
Technology:
Application-specific performance requirements dictate technology selection across irradiance profiles, wind resource corridors, and biomass feedstock availability.
- Solar:TOPCon cell architecture rewrites efficiency benchmarks for utility-scale plants. Bifacial modules and floating installations compress levelized cost trajectories for Rajasthan and Gujarat projects with high DC-AC ratios.
- Wind:Onshore turbines in Tamil Nadu and Karnataka wind corridors supply capacity factors exceeding solar alternatives. Repowering of aging assets with larger rotor diameters attracts foreign direct investment into these corridors.
- Biomass:Agricultural residue and bagasse-fired plants in sugarcane belts provide distributed baseload and rural employment. Feedstock supply chain reliability constrains capacity scaling beyond captive industrial applications.
- Geothermal:Exploration-stage resources in Ladakh and Himalayan regions await resource confirmation and drilling cost reductions. No commercial capacity operates under current cost structures.
Solar dominates capacity additions. Wind retains capacity factor advantages.
Installation:
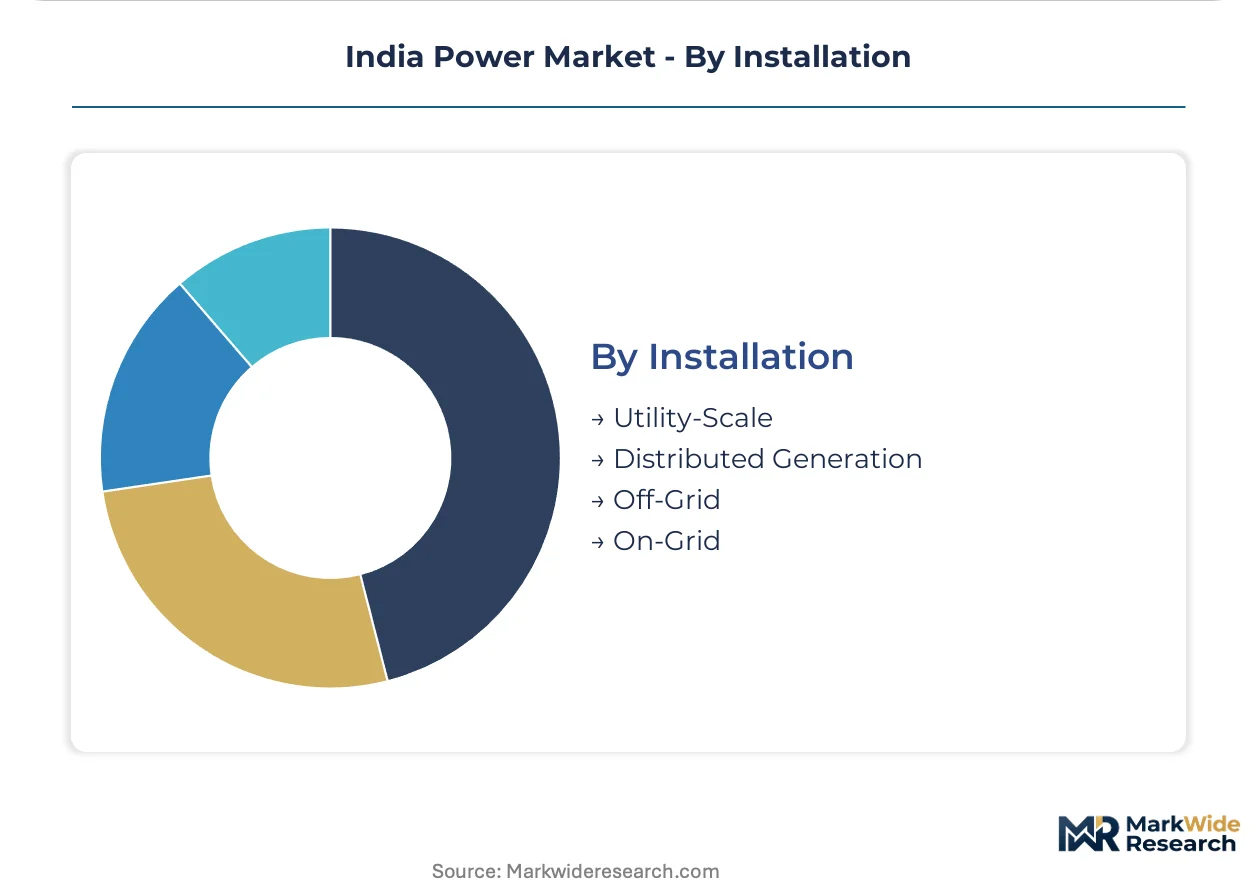
Customer type and grid access determine whether projects pursue centralized utility-scale economics or distributed generation premiums.
- Utility-Scale:Centralized solar parks and wind farms exceeding 50 MW capacity attract the majority of foreign direct investment and domestic institutional capital. Land acquisition friction in Gujarat stretches commissioning schedules beyond original power purchase agreement tenors.
- Distributed Generation:Rooftop solar and agricultural pump electrification gain policy support through mandates and capital subsidies. Maharashtra and Delhi regulatory commissions mandate distribution licensees deploy public charging networks that integrate grid-edge storage.
- On-Grid:Grid-connected installations access renewable purchase obligation compliance credits and net metering tariffs. Central Electricity Authority frequency response standards require inverter firmware upgrades that compress retrofit timelines for operational assets.
- Off-Grid:Remote village electrification and industrial captive plants in transmission-deficit regions rely on diesel hybrid or standalone renewable systems. BIS certification standards govern equipment procurement decisions for these installations.
Utility-scale captures capital flows. Distributed generation gains regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's solar parks and wind corridors anchor the largest capacity additions in India's power sector. State-level renewable purchase obligations and transmission corridor auctions concentrate investment flows across western and southern regions. Interstate grid congestion and distribution company financial stress create divergent risk profiles across state jurisdictions.
Gujarat
Industrial clusters in Mundra and Kutch drive contracted renewable offtake from steel and cement manufacturers. The state's solar-wind hybrid policies allocate transmission priority to integrated projects. Land acquisition friction stretches commissioning schedules beyond original power purchase agreement tenors in several solar parks.
Rajasthan
Utility-scale solar installations in Jodhpur and Bikaner districts attract the majority of foreign direct investment into renewable generation. The Bhadla and Phased solar parks face evacuation bottlenecks as Western regional grid congestion triggers Central Electricity Regulatory Commission pricing penalties. TOPCon module deployments dominate new capacity additions.
Tamil Nadu
Wind corridors in Coimbatore and Tirunelveli supply capacity factors exceeding solar alternatives across the state. State electricity board payment delays accumulate working capital strain for renewable generators. The Kudankulam nuclear complex provides baseload zero-carbon generation alongside coastal wind farms.
Maharashtra
Mumbai-Pune manufacturing clusters establish group captive structures that bypass distribution company scheduling charges. The state regulatory commission mandates public EV charging network deployment with grid-edge storage integration. Rooftop solar mandates for commercial buildings drive engineering procurement construction firm pivot toward distributed execution.
Karnataka
Bengaluru's technology parks and Mysuru industrial zones face building code mandates prescribing minimum renewable generation capacity. The Pavagada solar park anchors utility-scale additions though land use competition with agriculture intensifies. Agricultural pump electrification under KUSUM scheme scales fastest in northern districts.
India Power Market Competitive Environment
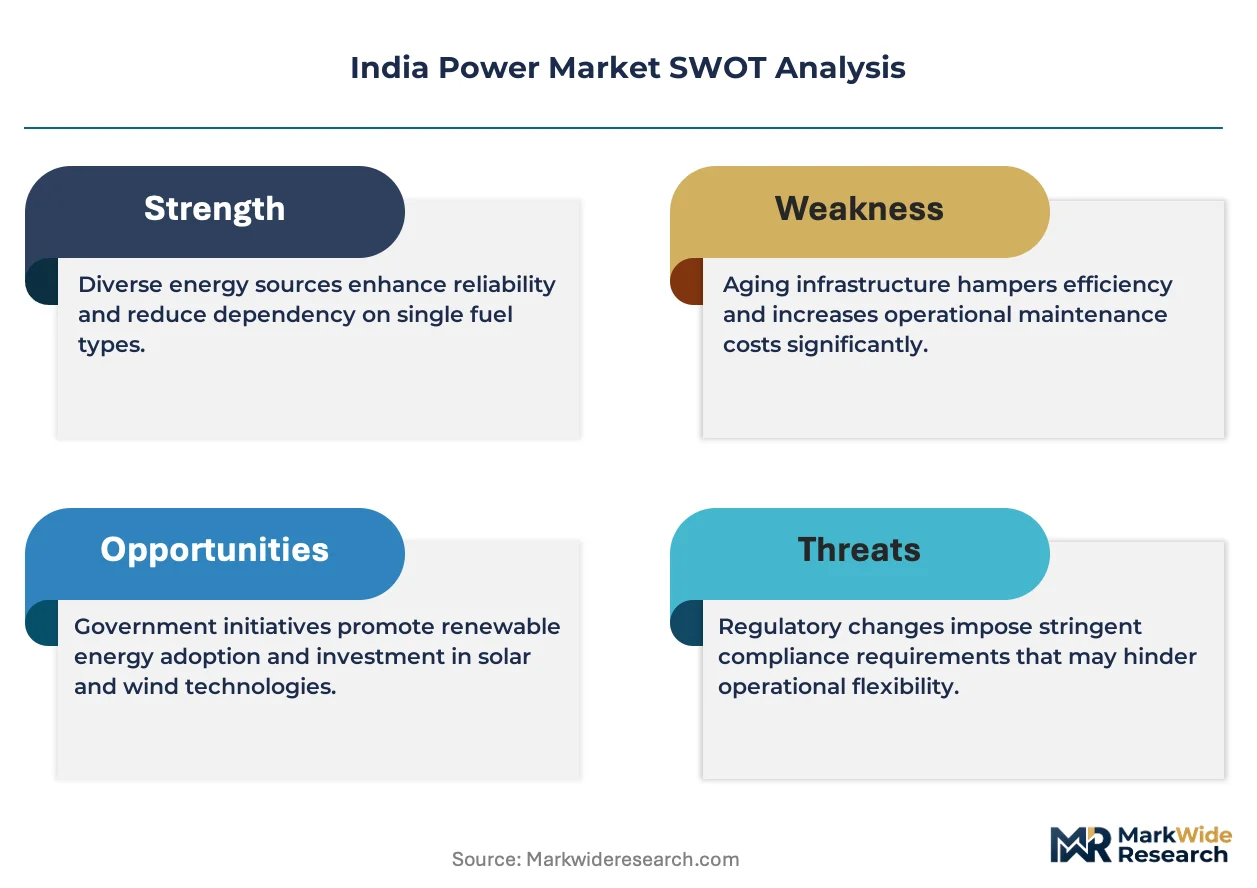
Capacity expansion dominates the current landscape as developers race to secure transmission corridor access and renewable purchase obligation compliance credits. The vendor base organizes around three strategic archetypes: integrated renewable-hydrogen conglomerates, state-owned thermal-to-clean transition utilities, and pure-play wind-solar specialists. Portfolio diversification into electrolyzer manufacturing and EV charging infrastructure represents the primary competitive vector alongside vertical control over module supply chains.
Among integrated renewable developers, Adani Green Energy Limited and ReNew Power exemplify the scale-driven archetype with utility-scale park ownership. NTPC Limited anchors the state-owned tier with thermal-to-renewable transition mandates and green hydrogen pilot deployment. Tata Power Company Limited occupies a distinctive position bridging distributed solar, EV infrastructure, and metropolitan distribution licensing across Maharashtra and Delhi.
| Leading Market Players |
|---|
| Adani Green Energy Limited |
| JSW Energy Limited |
| NTPC Limited |
| NTPC Green Energy Limited |
| ReNew Power |
| Power Grid Corporation of India Limited |
| Tata Power Company Limited |
| Suzlon Energy Limited |
| Adani Power Limited |
| Others |
Value Chain & Pricing Dynamics
Industrial buyers consolidating procurement around group captive structures and long-term power purchase agreements are forcing supply-side reconfiguration toward vertically integrated module manufacturing and electrolyzer assembly, compressing margins for pure-play developers dependent on merchant market exposure.
Pricing Analysis
Polysilicon wafer costs pass through directly to module pricing, with domestic ingot producers and Southeast Asian suppliers competing against legacy Chinese sources. Price differentiation separates BIS-certified premium modules from standard-tier imports, with evacuation risk premiums attaching to Rajasthan solar parks facing Western grid congestion. Pricing pressure stems from distribution company payment delays in Tamil Nadu and Maharashtra that strain working capital for renewable generators. Agricultural offtake under KUSUM exhibits highest price sensitivity, while steel and cement manufacturers absorb premium firm supply terms.
Supply Chain Analysis
Module manufacturing rests on polysilicon feedstock from China, Southeast Asian wafer producers, and emerging domestic ingot capacity in Gujarat and Rajasthan. Inverter electronics draw from Chinese and Taiwanese power semiconductor suppliers, while electrolyzer stacks for green hydrogen pilot projects source from European and Korean engineering firms. Tariff exposure on Chinese solar equipment creates procurement timing risk for developers with compressed commissioning schedules. Distribution runs through state electricity board procurement channels and private open access networks for industrial group captive structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gujarat's solar-wind hybrid transmission priority and Rajasthan's land cost arbitrage against Maharashtra's distribution company financial stress create geographic spreads that reward portfolio diversification across state regulatory jurisdictions.
For Market Incumbents: Hedge merchant market exposure by expanding contracted offtake portfolios with steel and cement manufacturers through group captive structures, while securing backward integration into module manufacturing to offset polysilicon price volatility. Prioritize transmission corridor access in Gujarat and Rajasthan over capacity additions in distribution-stressed markets. For New Entrants and Emerging Players: The MNRE production-linked incentive scheme for green hydrogen and solar-wind hybrid projects opens a window for electrolyzer-integrated renewable park development in Odisha and Chhattisgarh, where steel and fertilizer offtake anchors demand. Target agricultural pump electrification under KUSUM in Punjab and Haryana for fastest-permitting distributed generation entry, leveraging EPC partnerships with established rural electrification contractors. For Investors and Strategic Acquirers: Asymmetric upside sits with developers holding hybrid renewable-hydrogen portfolios and transmission corridor access rights in Gujarat and Rajasthan. Monitor state electricity regulatory commission renewable purchase obligation compliance trajectories as inflection indicator for offtake competition intensity and congestion pricing patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Solar-Wind Hybrid Capacity Buildout | Gujarat and Rajasthan transmission priority allocations accelerate project returns through land use efficiency gains. |
| Electrolyzer Manufacturing Integration | MNRE domestic value addition requirements for PLI eligibility force supply chain localization in hydrogen corridors. |
| Group Captive Structure Expansion | Maharashtra and Tamil Nadu manufacturing clusters bypass distribution company scheduling charges through direct asset ownership. |
| TOPCon Module Technology Deployment | NTPC and state genco tender specifications compress levelized costs for Rajasthan and Gujarat utility-scale parks. |
| EV Charging Infrastructure Mandate Compliance | Maharashtra and Delhi regulatory commission orders create grid-edge storage revenue streams for distribution licensees. |
Study Parameters
Direct dialogue with utility planning officers, IPP project developers, EPC contractors, and state electricity regulatory commission officials anchored qualitative assessment, cross-referenced against Central Electricity Authority generation statistics, MNRE policy circulars, SECI tender documents, and interstate transmission corridor auction records. Bottom-up project pipeline tracking and top-down regulatory mandate analysis provided triangulation across data sources.
Bottom-up capacity addition modeling by fuel source, generation scale, and state jurisdiction fed into top-down renewable purchase obligation compliance trajectory analysis across the projection horizon. CAGRs derived from segmented growth rate aggregation across utility-scale solar, wind repowering, green hydrogen pilot projects, and distributed agricultural electrification schemes, with input from BIS certification timelines and transmission corridor commissioning schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under distribution company financial restructuring timelines and interstate grid congestion pricing regime shifts. Material deviation in state-level renewable purchase obligation enforcement or MNRE green hydrogen subsidy disbursement cadence warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Compact Substation Market
Power
Residential Micro Inverter Market
Power
Germany Solar Inverter Market
Power
Oxy-Hydrogen Generators Market
Power
Electric Power Sports Market
Power
Residential Portable Inverter Generator Market
Power
Colombia Power Market
Power
China Power Market
Power
Vietnam Power Market
Power
Solar UPS Market
Power
Smart Power Market
Power
Power Shelf Market
Power
Gas Freeing Fan Market
Power
Rotating Phase Converter Market
Power
North America Microturbine Market
Power
Middle-East and Africa Power Market