
 Flue Gas Desulfurization Unit Market | 2026-2036
Flue Gas Desulfurization Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Flue Gas Desulfurization Unit Market Insights
A capital-intensity divergence between engineering conglomerates and specialized environmental technology firms is reorganizing competitive dynamics in the flue gas desulfurization unit market. Mitsubishi Heavy Industries leverages integrated EPC capabilities to anchor large-scale power plant projects across Asia. GE Vernova competes through advanced digital monitoring systems bundled with scrubber hardware. Babcock & Wilcox Enterprises sustains its position via deep specialization in high-capacity wet limestone systems for North American utilities.
Flue gas desulfurization units are industrial exhaust treatment systems that chemically neutralize sulfur dioxide from combustion processes, typically achieving removal efficiencies exceeding 95 percent through slurry-based absorption or dry sorbent injection. Their primary purpose is to enable power generation and heavy manufacturing facilities to comply with mandatory emissions ceilings while maintaining operational throughput. Wet scrubbers dominate installed capacity due to mature chemistry and reliable performance on high-sulfur coal, though dry scrubbers gain traction in water-scarce regions where zero-liquid-discharge constraints apply. The 500-1000 MW capacity band captures substantial retrofit demand as mid-sized coal fleets face tightening compliance deadlines without full replacement economics.
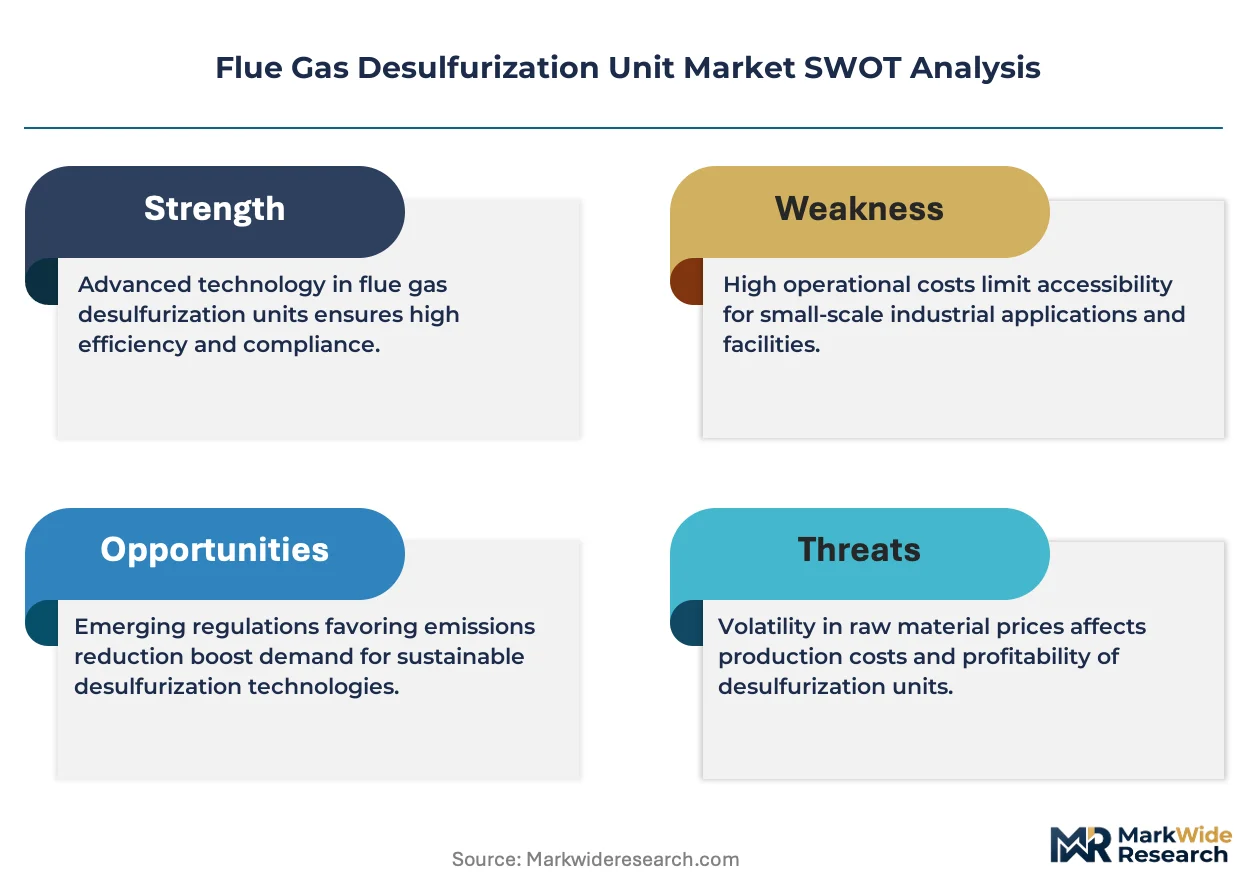
The US EPA enforces sulfur dioxide National Ambient Air Quality Standards that mandate continuous emissions monitoring and penalty structures for non-compliant facilities, directly shaping scrubber procurement cycles. China's MEE administers progressively stricter GB 13223 standards that force provincial power groups into accelerated FGD upgrades. India's CEA implements emissions norms for thermal power plants that require either installation or operational overhaul of desulfurization trains. Stakeholders must track regulatory enforcement variance across jurisdictions to anticipate retrofit waves and align technology portfolios with regional chemistry preferences and water availability constraints.
Market Dynamics
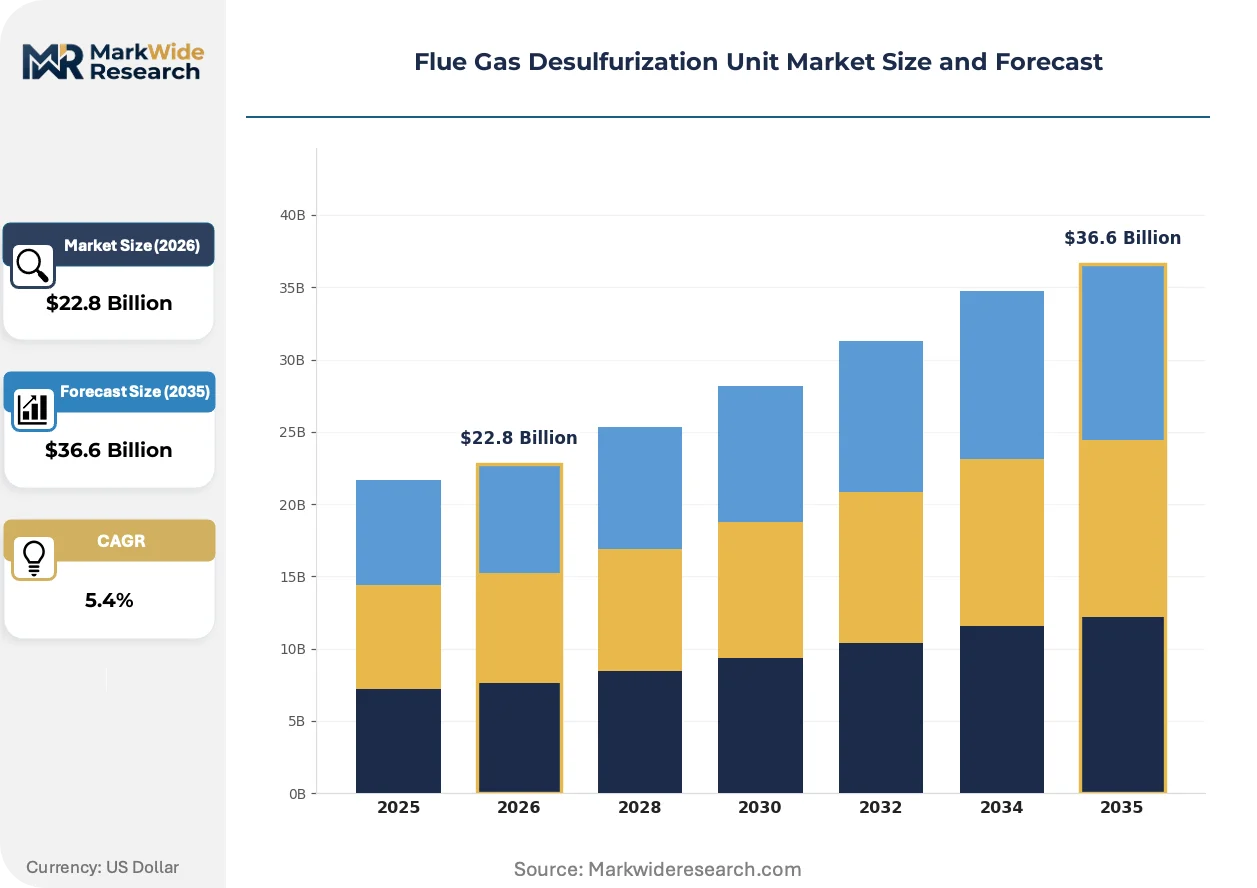
Retrofit cycles in China's coal-fired fleet and Indonesia's utility expansion are compressing procurement timelines while forcing technology suppliers to reconcile wet scrubber chemistry with zero-liquid-discharge constraints in water-scarce provinces.
Growth Catalysts
- GB 13223 Emission Standards:China's MEE mandates compel provincial power groups into accelerated FGD upgrades across the Yangtze River Delta.
- Indonesia's 35,000 MW Program:State utility PLN's coal expansion drives wet limestone scrubber demand for sulfur-rich Kalimantan coal.
- Seawater Scrubbing Chemistry:Coastal plants in Vietnam adopt marine-based absorption to eliminate limestone procurement and sludge disposal.
Market Restraints
- Limestone Supply Concentration:High-purity calcium carbonate deposits cluster in specific Chinese provinces, exposing coastal projects to rail logistics volatility.
- Water Scarcity Constraints:Wet scrubber economics deteriorate in India's Rajasthan and Gujarat where freshwater allocation prioritizes agriculture.
- Forced Outages for Retrofit:India's CEA compliance deadlines require mid-sized plants to schedule 45-60 day shutdowns without reserve margin compensation.
Strategic Opportunities
- Vietnam's Power Development Plan VIII:New coal capacity in Quang Ninh and Thai Binh provinces creates greenfield FGD specification opportunities.
- Dry Sorbent Injection Convergence:Circulating dry scrubbers paired with fabric filters capture emerging demand in Philippine cement kilns.
- Performance-Linked O&M Contracts:Thai independent power producers unbundle long-term service agreements from EPC hardware procurement.
Industry Challenges
- Corrosion Engineering Talent Gap:Specialized alloy specification for chloride-rich flue gas streams exceeds Southeast Asian engineering capacity.
- Legacy Control System Integration:1990s-era DCS platforms in Indonesian Cirebon and Paiton plants resist seamless connectivity with modern emissions monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flue Gas Desulfurization Unit Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $36.6 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Scrubbers, Dry Scrubbers, Semi-Dry Scrubbers, Hybrid Systems Technology: Caustic Soda, Lime, Sodium Bicarbonate, Ammonia End User: Power Plants, Cement Industry, Paper Mills, Metal Processing Capacity: Below 100 MW, 100-500 MW, 500-1000 MW, Above 1000 MW |
| Companies Covered | Mitsubishi Heavy Industries, GE Vernova, Babcock & Wilcox Enterprises, Andritz AG, Valmet Oyj, FLSmidth & Co., Hamon & Cie, Siemens Energy AG, Kawasaki Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flue Gas Desulfurization Unit Market Trends and Innovations
Process intensification and digital instrumentation are compressing scrubber footprints while enabling real-time chemistry optimization that was previously impractical at scale.
Advanced oxidation is bifurcating the oxidation air subsystem market. Power developers in Vietnam's Van Phong and Song Hau complexes specify forced oxidation for gypsum byproduct recovery. This technology is bifurcating equipment procurement between standard air blowers and high-efficiency compressor trains with integrated heat recovery.
China's GB 13223-2011 amendments tightened sulfur dioxide limits for existing units above 600 MW. Provincial environmental protection bureaus now enforce continuous emissions monitoring data submission with 15-minute resolution. Plants in Shandong and Hebei provinces accelerate ammonia-based scrubber trials to meet ultra-low emission targets below 35 mg per cubic meter.
Utility procurement departments in Thailand and the Philippines now unbundle EPC contracts into separate technology supply, civil works, and commissioning packages. This disaggregation exposes specialized scrubber vendors to direct commercial negotiation while compressing margins for integrated conglomerates. The shift is most visible in EGAT's recent Rayong and Krabi tender structures.
Flue Gas Desulfurization Unit Market Segmentation
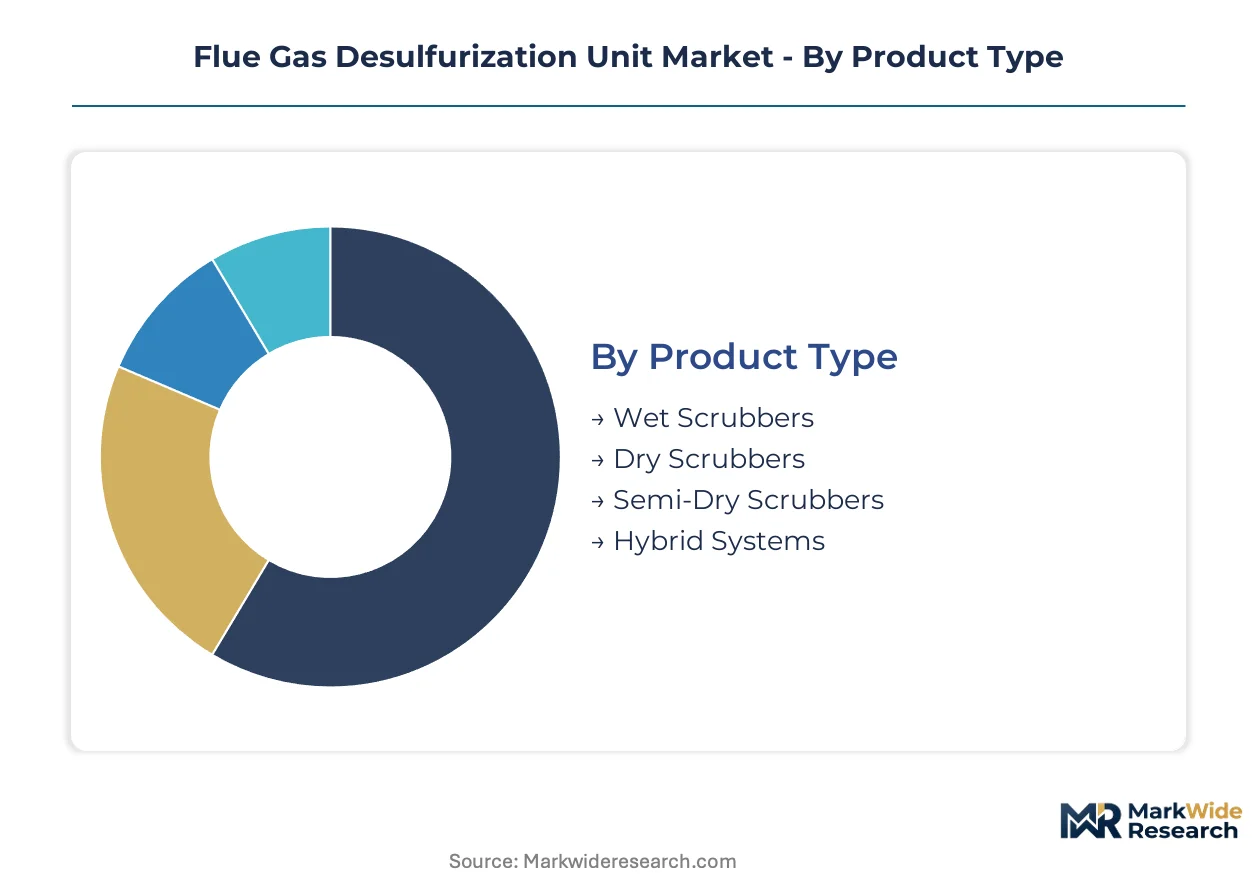
FGD procurement splits along chemistry choices, capacity thresholds, and end-use emission profiles. Each dimension carries distinct regulatory compliance burdens and capital intensity trade-offs that reshape vendor selection criteria.
Product Type:
China's MEE enforces GB 13223 ultra-low emission targets below 35 mg per cubic meter, forcing chemistry-dependent technology choices across provincial power fleets.
- Wet Scrubbers:Limestone-gypsum absorption systems achieve removal efficiencies exceeding 95 percent through slurry-based contact. China's Shandong and Hebei provinces deploy these for retrofits on units above 600 MW facing tightened MEE deadlines. Water consumption and sludge disposal burden operations in inland provinces.
- Dry Scrubbers:Circulating dry scrubbers inject hydrated lime or sodium bicarbonate into flue gas streams without liquid effluent. Rajasthan and Gujarat in India specify these where freshwater allocation prioritizes agricultural use over industrial cooling. Zero-liquid-discharge compliance eliminates wastewater treatment capex.
- Semi-Dry Scrubbers:Spray dryer absorbers atomize lime slurry into hot gas streams, producing dry byproduct for landfill.
- Hybrid Systems:Combined wet-dry configurations optimize for variable sulfur loads and seasonal water availability constraints.
Wet scrubbers handle the majority of throughput; dry scrubbers are gaining share fastest in water-scarce jurisdictions.
Technology:
Reagent cost volatility and byproduct recovery economics drive chemistry selection across divergent regulatory enforcement climates.
- Caustic Soda:Sodium hydroxide absorption delivers rapid reaction kinetics and compact footprint for space-constrained retrofits. Vietnam's coastal plants at Van Phong and Song Hau specify caustic systems where marine logistics reduce reagent transport costs versus inland limestone rail hauls.
- Lime:Hydrated calcium oxide dominates installed base through mature supply chains and gypsum byproduct salability. Indonesia's PLN procurement for Kalimantan coal units anchors demand where high-sulfur content necessitates robust neutralization capacity.
- Sodium Bicarbonate:Dry injection systems target moderate sulfur loads in batch-process industries with intermittent operation profiles.
- Ammonia:Ammonia-based scrubbing trials accelerate in China's Yangtze River Delta provinces pursuing ultra-low emission thresholds below 35 mg per cubic meter.
Lime commands the largest installed base; ammonia is expanding most quickly on ultra-low emission mandates.
End User:
Emission intensity and compliance deadline proximity create divergent procurement urgency across heavy industrial categories.
- Power Plants:Coal-fired generation accounts for the dominant FGD deployment volume. Indonesia's 35,000 MW program and Vietnam's Power Development Plan VIII specify wet limestone trains for new capacity in Quang Ninh and Thai Binh provinces.
- Cement Industry:Kiln exhaust treatment adopts circulating dry scrubbers paired with fabric filters. Philippine cement producers specify these configurations to manage sulfur dioxide from high-sulfur fuels without process water integration.
- Paper Mills:Recovery boiler exhaust requires specialized corrosion-resistant alloys for chloride-rich flue gas streams.
- Metal Processing:Smelter off-gas treatment demands compact footprint systems for retrofit into existing gas cleaning trains.
Power plants absorb the dominant capital allocation; cement kilns are climbing the fastest on dry scrubber adoption.
Capacity:
Retrofit economics versus greenfield specification diverge sharply across unit size thresholds, with mid-sized fleets facing compressed compliance timelines.
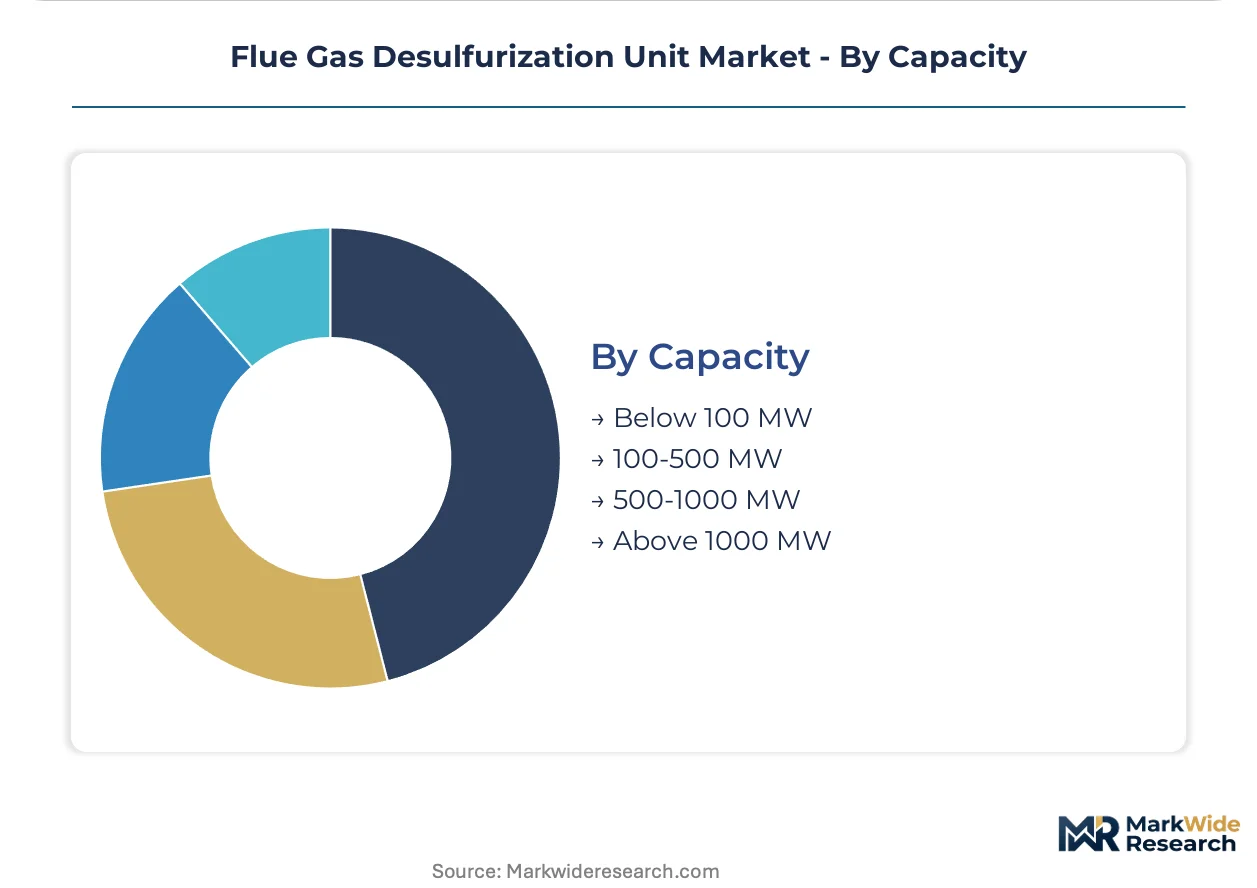
- 500-1000 MW:Mid-sized coal units capture substantial retrofit demand where full replacement economics fail but MEE and CEA deadlines compel scrubber installation. India's CEA mandates 45-60 day shutdowns for these units without reserve margin compensation, compressing procurement timelines.
- Above 1000 MW:Supercritical and ultra-supercritical units specify high-efficiency wet scrubbers with integrated oxidation air subsystems for forced gypsum recovery. China's provincial power groups prioritize these for GB 13223 compliance with continuous emissions monitoring at 15-minute resolution.
- Below 100 MW:Industrial boilers and captive power units face simplified compliance pathways or retirement decisions.
- 100-500 MW:Smaller utility units concentrate in Southeast Asian markets with emerging regulatory frameworks.
Units above 1000 MW concentrate the largest individual project values; the 500-1000 MW band shows steepest retrofit trajectory on compliance deadline compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Chinese coastal provinces where GB 13223 enforcement compels retrofit urgency, while Indian inland utilities face deteriorating wet scrubber economics amid agricultural water priority. Southeast Asian greenfield projects in Vietnam and Indonesia capture premium technology specification margins unavailable in saturated retrofit markets.
China
Shandong and Hebei provinces anchor retrofit demand as MEE enforces continuous emissions monitoring at 15-minute resolution for units above 600 MW. Provincial environmental protection bureaus accelerate ammonia-based scrubber trials to meet ultra-low emission thresholds below 35 mg per cubic meter. The Yangtze River Delta industrial corridor concentrates procurement volume where state power groups bundle FGD upgrades with ultra-supercritical unit modernization.
India
Rajasthan and Gujarat utilities specify circulating dry scrubbers where CEA compliance deadlines intersect with freshwater allocation constraints favoring agricultural use. The CEA mandates 45-60 day forced outages for mid-sized plants without reserve margin compensation, compressing vendor negotiation timelines. Western coastal clusters in Maharashtra pursue seawater scrubbing chemistry to bypass limestone rail logistics from distant deposits.
Indonesia
PLN's 35,000 MW program drives wet limestone demand for high-sulfur Kalimantan coal units in Quang Ninh and Thai Binh provinces. State utility procurement favors integrated EPC contracts bundling scrubber hardware with civil works and commissioning. The Java-Bali grid interconnection creates concentrated specification windows for supercritical capacity additions facing 2025-2027 COD targets.
Vietnam
Power Development Plan VIII specifies new coal capacity in Quang Ninh and Thai Binh provinces with greenfield FGD specification opportunities. Coastal plants at Van Phong and Song Hau adopt caustic soda systems where marine logistics reduce reagent transport costs versus inland limestone hauls. Forced oxidation subsystems dominate equipment procurement for gypsum byproduct recovery in these complexes.
United States
Midwestern utilities face EPA National Ambient Air Quality Standards enforcement that mandates continuous emissions monitoring with penalty structures for non-compliant facilities. The Ohio River Valley coal fleet concentrates retrofit procurement where aging wet limestone systems require corrosion-resistant alloy upgrades for chloride-rich flue gas streams. Texas and Southwestern plants evaluate dry sorbent injection where water scarcity constraints mirror Indian and Chinese inland province economics.
Flue Gas Desulfurization Unit Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated engineering conglomerates commanding premium EPC margins while specialized environmental technology firms capture recurring O&M revenue streams. Market structure tilts toward consolidation at the supercritical unit scale above 1000 MW, where procurement complexity favors bundled solution providers. Three archetypes dominate: full-service EPC integrators with captive fabrication, scrubber technology licensors with regional manufacturing partnerships, and aftermarket service specialists unbundling long-term O&M from initial hardware supply. Dominant competitive moves include geographic expansion through local licensing agreements and vertical integration into reagent supply chains to lock in lifecycle revenue.
Among integrated engineering conglomerates, Mitsubishi Heavy Industries and GE Vernova occupy positions spanning technology supply through commissioning, while Babcock & Wilcox Enterprises exemplifies deep specialization in high-capacity wet limestone configurations. These three represent divergent strategic postures: Japanese and American conglomerates leverage integrated project execution capabilities, while the American specialist anchors competitive position through chemistry-specific engineering depth rather than geographic breadth. Each sits within distinct risk-reward profiles—bundled EPC exposure versus pure-play technology licensing versus aftermarket service dependency.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| GE Vernova |
| Babcock & Wilcox Enterprises |
| Andritz AG |
| Valmet Oyj |
| FLSmidth & Co. |
| Hamon & Cie |
| Siemens Energy AG |
| Kawasaki Heavy Industries |
| Others |
Pricing and Supply Chain Analysis
China's GB 13223 ultra-low emission thresholds gate both supplier qualification and price differentiation simultaneously, forcing scrubber vendors to absorb alloy certification costs while buyers in Shandong and Hebei provinces pay configured-to-order premiums for ammonia-based chemistry packages.
Pricing Analysis
Configured-to-order pricing for wet limestone systems with forced oxidation subsystems commands spreads above standard dry scrubber quotations. Price differentiation rests on corrosion-resistant alloy grades for chloride-rich flue gas and bundled O&M contract duration. Cost compression in standard wet scrubber tiers is intensifying because Indonesian PLN procurement favors unbundled EPC structures. State utility buyers in Southeast Asia exhibit highest price sensitivity; coastal plants in Vietnam with marine logistics advantages show lowest.
Supply Chain Analysis
Inventory lead times for high-nickel alloy pressure vessels stretch procurement cycles for retrofit projects facing CEA-mandated shutdown windows. Manufacturing concentrates in China, Japan, and South Korea for absorber tower fabrication. Raw material sourcing draws from Indonesian nickel laterite, Australian high-purity limestone, and Chinese rare earth catalyst coatings. Single-source vulnerability sits with specialized alloy suppliers qualified for MEE continuous emissions monitoring integration. Distribution runs through EPC prime contractors with captive fabrication or licensed technology partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance-linked O&M contracts are expanding faster than hardware procurement as Thai independent power producers unbundle long-term service agreements from initial EPC supply, creating a service-attach revenue layer with superior margin stability.
For Market Incumbents: Fortify positions by deepening captive supply of high-nickel alloy absorber materials and securing MEE certification for continuous emissions monitoring data integration. Dry scrubber entrants from European cement technology licensors threaten wet limestone margins in water-scarce Indian states. Backward integration into alloy specification engineering defends against corrosion talent gaps in Southeast Asian project execution. For New Entrants and Emerging Players: Lead with circulating dry scrubber configurations targeting Philippine cement kilns where sulfur-rich fuels and zero-liquid-discharge constraints converge. Indonesia's 35,000 MW program offers white-space penetration through ammonia-based chemistry trials for ultra-low emission compliance below 35 mg per cubic meter. Technology licensing with regional fabrication partners accelerates market entry without EPC balance sheet exposure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across dry scrubber subsystems as standardized circulating designs displace custom wet limestone engineering. Long-term viability favors vendors with recurring O&M contract books exceeding hardware revenue concentration. Acquisition targets should display scrubber technology licensing revenue plus regional aftermarket service density. Watch for CEA enforcement variance across Indian states as inflection signal for retrofit wave timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive nickel alloy sourcing insulates margins from Indonesian laterite export volatility. |
| Technology Licensing Partnership | Regional fabrication licensing accelerates MEE compliance without EPC capital deployment. |
| Performance-Linked O&M Contract | Thai IPP unbundling creates recurring revenue streams detached from hardware cyclicality. |
| Dry Scrubber Manufacturing Scale-Up | Zero-liquid-discharge designs capture Rajasthan and Gujarat procurement where agriculture claims freshwater priority. |
| Seawater Scrubbing Chemistry Development | Marine absorption eliminates limestone rail logistics for Vietnam's Van Phong coastal complex. |
Research Methodology
A standing panel of utility planning officers, EPC project managers, plant maintenance directors, and environmental compliance leads provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from EPA enforcement databases, China's MEE emissions monitoring disclosures, PLN procurement bulletins, and IEA power sector investment tracking. Bottom-up project pipeline aggregation and top-down regulatory mandate sizing were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by scrubber chemistry type, capacity tier, end-use emission profile, and regional regulatory enforcement cluster. CAGRs were derived from installed base retirement curves intersecting with compliance deadline schedules. Forecast inputs incorporated limestone reagent cost volatility and alloy specification engineering capacity constraints.
The analysis sits within stated boundaries; outcomes outside sustained GB 13223 enforcement intensity or PLN program continuity would require recalibration. Forecasts reflect assumptions regarding MEE monitoring data submission compliance and CEA deadline adherence. Regulatory enforcement variance, nickel price volatility, or freshwater allocation policy shifts in key provinces could revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Rotating Phase Converter Market
Power
Digital Power Utility Market
Power
Asia-Pacific Power Purchase Agreement Market
Power
North America CHP Market
Power
Denmark Power Market
Power
Europe Submarine Power Cables Market
Power
Uzbekistan Power Market
Power
Middle East and Africa Combined Heat & Power Market
Power
Green UPS Market
Power
Italy Power Market
Power
High Voltage DC Power System Market
Power
Steam Turbine MRO Market
Power
Australia Power Market
Power
Angola Power EPC Market
Power
HVDC Capacitor Market
Power
Wind Turbine Drivetrain Market