
 Middle East and Africa Combined Heat & Power Market | 2026-2036
Middle East and Africa Combined Heat & Power Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Combined Heat & Power Market Insights
Digital twin integration is rewriting how Combined Heat & Power plants are designed, commissioned, and operated across the Middle East and Africa. Siemens Energy leverages remote monitoring platforms to sustain performance guarantees for utility-scale installations in the Gulf. ACWA Power anchors project development through long-term offtake structures that reduce financing risk for independent power producers. General Electric Company competes on aeroderivative turbine configurations optimized for high ambient temperatures prevalent across the region.
Combined Heat & Power denotes the simultaneous generation of usable thermal energy and electrical power from a single fuel source, typically achieving total system efficiencies exceeding 75 percent through heat recovery steam generators and absorption chillers. Gas turbines dominate product type deployment in the Middle East due to fuel availability and scale economics for petrochemical complexes. The industrial end user segment leads absolute capacity additions, while institutional applications in desalination and district cooling represent the fastest-growing margin pool as municipalities seek to reduce grid dependency.
Saudi Arabia's Energy Efficiency Center, South Africa's National Energy Regulator, and the UAE's Emirates Authority for Standardization and Metrology each enforce equipment performance standards and emissions thresholds that shape procurement specifications. Compliance with these frameworks determines market access for original equipment manufacturers and influences technology selection across project pipelines. Stakeholders must monitor regulatory harmonization progress between Gulf standardization bodies and sub-Saharan accreditation systems to anticipate certification requirements for cross-border equipment supply.
Market Dynamics
Industrial efficiency mandates from Saudi Arabia's Energy Efficiency Center and the UAE's distributed generation incentives are compressing payback periods for on-site power investments across the Gulf Cooperation Council states.
Growth Catalysts
- Saudi Arabia's Efficiency Mandates:The Energy Efficiency Center enforces minimum performance standards for industrial facilities above 20 MW thermal capacity, forcing petrochemical complexes toward cogeneration retrofits.
- Absorption Chiller Integration:Heat recovery steam generator configurations paired with lithium bromide absorption systems capture waste thermal energy for district cooling loads in Dubai and Abu Dhabi.
- South Africa's Industrial Belt:KwaZulu-Natal manufacturing corridors face grid reliability constraints that make captive power generation economically viable despite higher upfront capital requirements.
Market Restraints
- Natural Gas Price Volatility:Gulf Cooperation Council spot LNG pricing fluctuations compress project IRRs for independent power producers financing utility-scale installations.
- Equipment Import Concentration:Heavy gas turbine and heat recovery steam generator supply chains concentrate in European and North American manufacturing bases, exposing projects to currency hedging costs and extended lead times.
- Grid Interconnection Standards:Emirates Authority for Standardization and Metrology technical requirements for synchronous connection create certification bottlenecks for modular reciprocating engine packages below 10 MW.
Strategic Opportunities
- Desalination Cogeneration:Multi-effect distillation plants in Saudi Arabia's Eastern Province seek thermal host arrangements that monetize waste heat from adjacent power generation assets.
- Biogas Feedstock Integration:South African sugar milling and pulp processing facilities possess captive biomass streams suitable for anaerobic digestion-to-power configurations with thermal recovery.
- Green Hydrogen Offtake:Electrolyzer projects in Morocco and Egypt require steady renewable power input that hybrid CHP-solar configurations can firm through thermal storage integration.
Industry Challenges
- Commissioning Engineer Scarcity:Heat balance optimization and turbine control system tuning require specialized expertise concentrated in European and East Asian technical service organizations.
- Legacy SCADA Integration:Brownfield industrial facilities in South Africa operate proprietary distributed control systems that resist seamless integration with modern digital twin monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Combined Heat & Power Market |
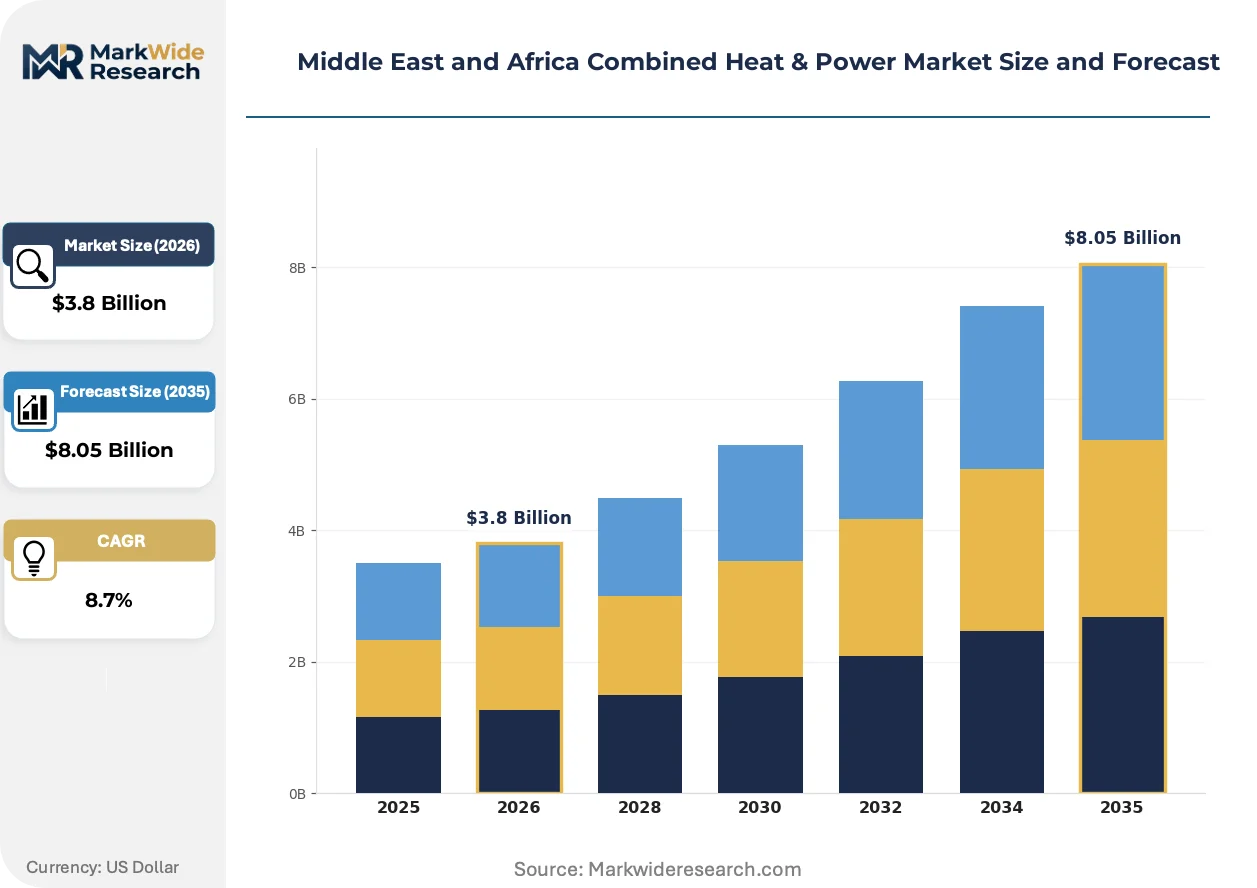
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micro Turbines, Reciprocating Engines, Fuel Cells, Gas Turbines End User: Industrial, Residential, Commercial, Institutional Technology: Internal Combustion Engine, Gasification, Combined Cycle, Organic Rankine Cycle Application: District Heating, Co-Generation, Power Generation, Waste Heat Recovery |
| Companies Covered | General Electric Company, Siemens AG, ABB Ltd, Engie S.A, ACWA Power, Doosan Corp, Samsung C&T Corp, Saudi Electricity Company, Siemens Energy, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Combined Heat & Power Market Trends and Innovations
Digital twin architectures and aeroderivative turbine configurations are compressing the performance gap between utility-scale and distributed generation assets across high-ambient-temperature operating environments.
Advanced heat recovery steam generator designs with once-through Benson boiler technology are rendering obsolete traditional drum-type configurations in combined-cycle applications. Petrochemical complexes in Jubail and Yanbu adopt these compact footprints to reduce civil works costs and shorten construction schedules. The shift eliminates water treatment infrastructure previously required for drum-level control, reducing operational complexity for Saudi Aramco-operated facilities.
Saudi Arabia's Energy Efficiency Center enforcement protocols now mandate third-party verification of actual thermal performance against design guarantees for installations above 50 MW. Industrial offtakers must submit annual efficiency audits to maintain operating licenses. This regulatory compression forces original equipment manufacturers to tighten performance warranties and extend long-term service agreement durations to secure procurement contracts.
Long-term energy service agreements are displacing traditional equipment purchase models for institutional buyers in the UAE's district cooling sector. Emirates Central Cooling Systems Corporation and district cooling operators now contract for guaranteed chilled water output rather than owning generation assets. This performance-based structure transfers operational risk to specialized independent power producers while locking in thermal efficiency benchmarks enforced through Emirates Authority for Standardization and Metrology certification requirements.
Middle East and Africa Combined Heat & Power Market Segmentation
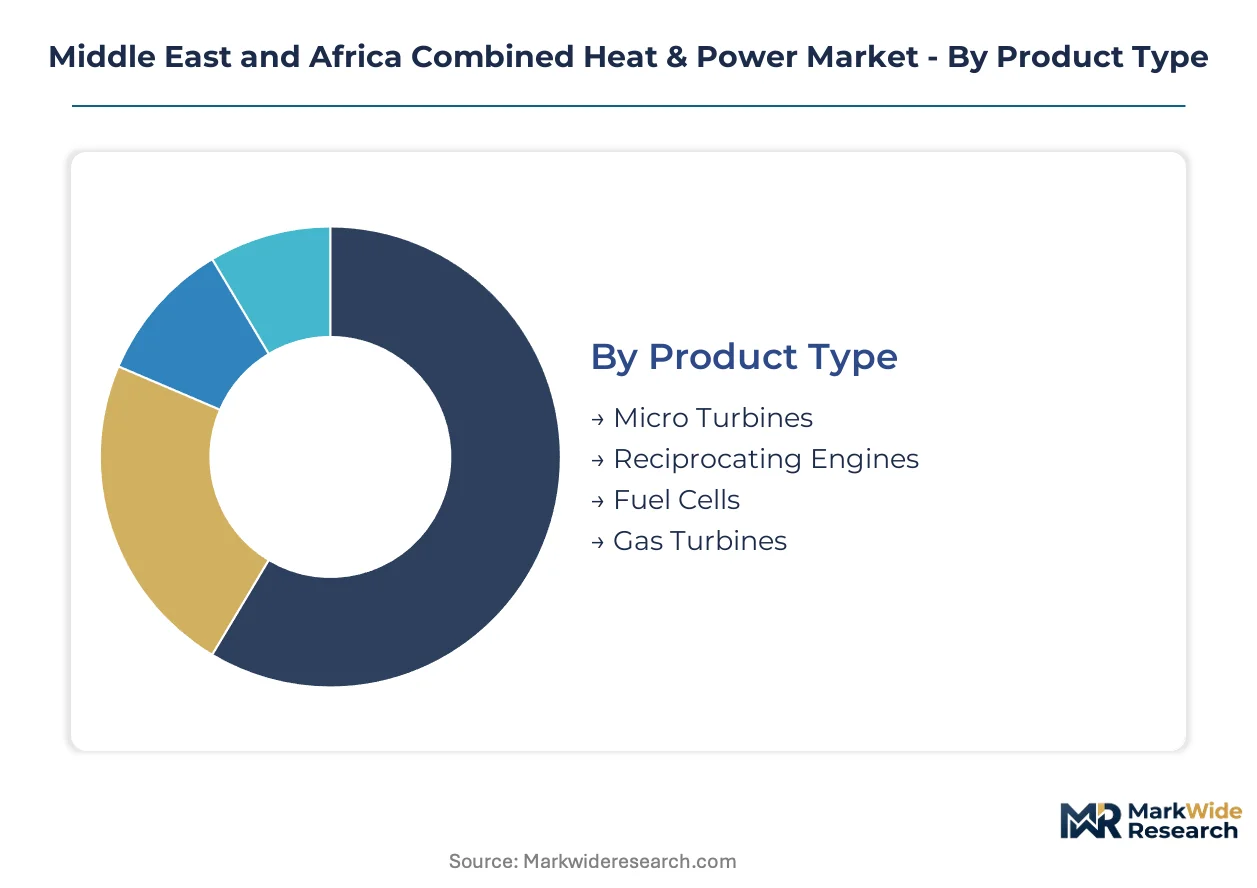
Segmentation in the Middle East and Africa Combined Heat & Power market reveals divergent service intensity profiles across equipment categories. Product type determines spare parts logistics and field engineering density, while end user segmentation shapes contract structures and performance guarantee terms.
Product Type:
After-sales service intensity varies dramatically across product categories, with heavy rotating equipment demanding dedicated technical service teams and predictive maintenance contracts.
- Gas Turbines:Heavy-frame and aeroderivative configurations dominate utility-scale installations across Saudi Arabia's Eastern Province petrochemical corridor. Saudi Aramco-operated facilities in Jubail and Yanbu anchor demand through long-term service agreements tied to efficiency guarantees enforced by the Energy Efficiency Center.
- Reciprocating Engines:Modular reciprocating packages below 10 MW face synchronous connection certification bottlenecks under Emirates Authority for Standardization and Metrology requirements. South Africa's KwaZulu-Natal manufacturing belt favors these units for captive power generation amid grid reliability constraints.
- Micro Turbines:Compact units serve distributed commercial applications in Dubai's district cooling networks with reduced civil works requirements.
- Fuel Cells:Emerging solid oxide configurations target premium institutional installations seeking zero-emission thermal power in UAE healthcare and education facilities.
Gas Turbines holds the largest share; momentum sits with Reciprocating Engines.
End User:
Customer type determines risk allocation structures, with industrial offtakers accepting operational responsibility and institutional buyers preferring performance-based contracting.
- Industrial:Petrochemical complexes, steel mills, and cement plants across the Gulf Cooperation Council states deploy cogeneration to meet Saudi Arabia's Energy Efficiency Center mandates for facilities above 20 MW thermal capacity. These installations require heat recovery steam generator integration with absorption chilling for process steam and district cooling loads.
- Institutional:Desalination plants, district cooling operators, and healthcare facilities represent the fastest-expanding margin pool as Emirates Central Cooling Systems Corporation and similar entities adopt energy service agreements rather than asset ownership. Thermal host arrangements monetize waste heat from adjacent power generation assets.
- Commercial:Hotels, shopping complexes, and office towers in Abu Dhabi and Doha prioritize compact footprints and rapid deployment timelines.
- Residential:Limited penetration concentrated in master-planned communities with centralized thermal infrastructure in Qatar's Lusail development.
Industrial dominates absolute capacity; Institutional climbs the fastest.
Technology:
Technology selection hinges on fuel quality, scale requirements, and integration complexity with existing industrial infrastructure.
- Combined Cycle:Once-through Benson boiler configurations in heat recovery steam generators are displacing drum-type designs across Saudi Aramco facilities, eliminating water treatment infrastructure and reducing civil works costs.
- Internal Combustion Engine:Diesel and dual-fuel reciprocating engines serve backup power and prime power applications in South African industrial corridors facing grid instability.
- Gasification:Biomass and waste-to-energy configurations target South African sugar milling and pulp processing facilities with captive feedstock streams.
- Organic Rankine Cycle:Low-temperature waste heat recovery systems gain traction in geothermal and industrial waste heat applications across East African manufacturing.
Combined Cycle commands the installed base; Organic Rankine Cycle shows steepest expansion trajectory.
Application:
Application segmentation tracks how thermal output is monetized, distinguishing between power-first and heat-first economic models.
- Co-Generation:Simultaneous power and thermal production achieves total system efficiencies exceeding 75 percent through heat recovery steam generators and absorption chillers, anchoring project economics across Gulf petrochemical complexes.
- District Heating:Thermal networks in Dubai and Abu Dhabi distribute recovered heat to commercial and institutional loads, with lithium bromide absorption systems converting waste thermal energy into chilled water output.
- Power Generation:Electricity-first configurations prioritize grid export or captive industrial supply over thermal utilization.
- Waste Heat Recovery:Standalone heat capture from industrial processes feeds thermal hosts or secondary power cycles without primary generation assets.
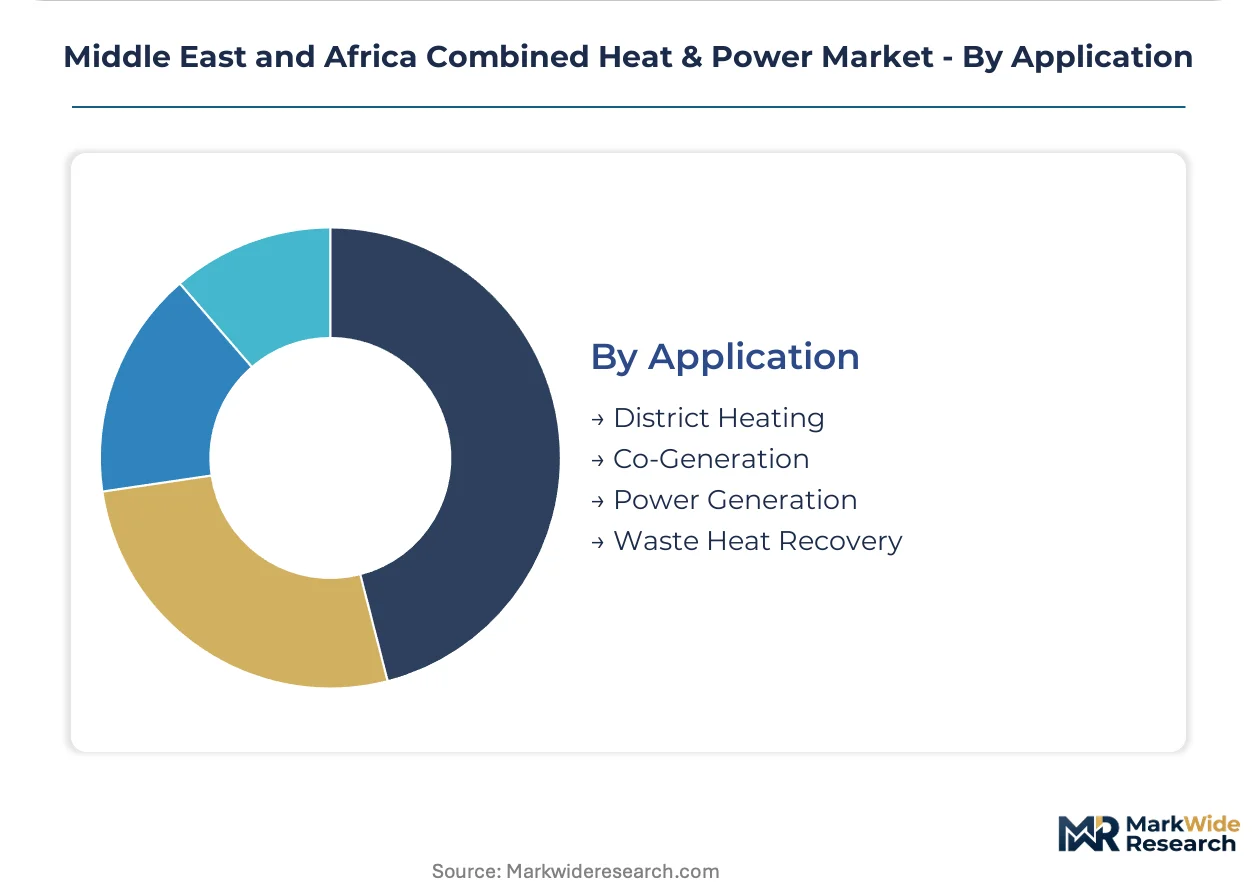
Co-Generation holds the largest share; momentum sits with District Heating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment import dependency shapes regional market dynamics, with European and East Asian manufacturing bases supplying heavy gas turbines and heat recovery steam generators. Currency hedging costs and extended lead times concentrate procurement risk in Gulf Cooperation Council states. Local assembly partnerships are emerging in Saudi Arabia and the UAE to compress delivery timelines.
Saudi Arabia
Petrochemical complexes in Jubail and Yanbu anchor regional demand for utility-scale cogeneration systems. The Energy Efficiency Center enforces mandatory efficiency audits for installations above 50 MW thermal capacity. Eastern Province industrial corridors host Saudi Aramco-operated facilities adopting once-through Benson boiler configurations to eliminate water treatment infrastructure.
United Arab Emirates
District cooling operators in Dubai and Abu Dhabi drive institutional adoption through energy service agreements rather than asset ownership. The Emirates Authority for Standardization and Metrology certifies synchronous connection standards for grid-interconnected systems. Emirates Central Cooling Systems Corporation contracts for guaranteed chilled water output, transferring operational risk to independent power producers.
South Africa
KwaZulu-Natal manufacturing belts face grid reliability constraints that justify captive power generation despite higher capital requirements. The National Energy Regulator oversees interconnection standards for distributed generation assets. Sugar milling and pulp processing facilities in Mpumalanga and KwaZulu-Natal explore biogas feedstock integration for anaerobic digestion-to-power configurations.
Egypt
Electrolyzer projects in the Suez Canal Economic Zone seek hybrid CHP-solar configurations to firm renewable power input for green hydrogen production. The New and Renewable Energy Authority shapes procurement frameworks for industrial offtakers. Thermal power developers in the Delta region evaluate waste heat recovery systems for adjacent desalination infrastructure.
Morocco
Phosphate processing complexes in Khouribga and Youssoufia represent latent demand for high-temperature cogeneration systems. The Moroccan Agency for Energy Efficiency implements industrial audit programs that identify retrofit opportunities. OCP Group facilities evaluate gas turbine integration to reduce grid dependency for energy-intensive fertilizer production.
Middle East and Africa Combined Heat & Power Market Competitive Landscape
On the supply side, the industry is consolidated around a handful of integrated energy conglomerates and specialized power developers. Heavy rotating equipment manufacturing concentrates in European and North American engineering groups with established Middle East service networks. Two strategic archetypes dominate: full-service original equipment manufacturers bundling hardware with long-term service agreements, and independent power developers anchoring project finance through offtake structures. Competitive moves center on technology licensing partnerships and localized assembly joint ventures to compress delivery timelines.
Within the full-service manufacturer tier, General Electric Company and Siemens Energy exemplify archetypes competing on aeroderivative turbine configurations optimized for high ambient temperatures. ACWA Power occupies a distinctive position as a Saudi-based independent power developer structuring long-term offtake arrangements that reduce financing risk for utility-scale installations. Among European-integrated conglomerates, Siemens AG and ABB Ltd represent diversified engineering groups with established regional service networks. Korean construction majors including Doosan Corp and Samsung C&T Corp anchor the engineering-procurement-construction contractor segment, while Engie S.A exemplifies the multinational utility developer archetype pursuing district cooling and desalination cogeneration opportunities across Gulf markets.
| Leading Market Players |
|---|
| General Electric Company |
| Siemens AG |
| ABB Ltd |
| Engie S.A |
| ACWA Power |
| Doosan Corp |
| Samsung C&T Corp |
| Saudi Electricity Company |
| Siemens Energy |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Jeddah container freight corridors transmit European manufacturing cost escalations into Gulf procurement budgets, compressing margins for independent power producers while amplifying price spreads between premium OEM service bundles and standard equipment-only transactions.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers bundle long-term service agreements with efficiency guarantees enforced by Saudi Arabia's Energy Efficiency Center, while standard tiers exclude predictive maintenance contracts. Cost compression in economy tiers intensifies because currency hedging on European turbine imports erodes project IRRs. Petrochemical complexes show least price sensitivity due to regulatory compliance mandates, whereas South African captive power operators exhibit highest sensitivity amid grid reliability-driven urgency.
Supply Chain Analysis
Tariff exposure between Germany and Saudi Arabia dominates procurement risk calculus for heavy-frame gas turbines. Manufacturing concentrates in Germany, Italy, and the United States for heat recovery steam generators and aeroderivative configurations. Supply chains draw from nickel superalloy castings, precision-machined compressor blades, and specialized control system electronics. Single-source vulnerability concentrates in European technical service organizations for commissioning engineering. Distribution runs through engineering-procurement-construction contractors with established Gulf logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from divergent regulatory enforcement timelines across Gulf Cooperation Council standardization bodies, creating niche windows for modular technology providers between utility-scale and distributed generation thresholds.
For Market Incumbents: Insulate service revenue streams by tightening performance warranty terms beyond Energy Efficiency Center minimums, forcing smaller competitors into costly technical service subcontracting. Extend long-term service agreement durations to lock in Saudi Aramco-operated facilities before absorption chiller integration mandates expand. Capacity addition in UAE district cooling corridors captures energy service agreement momentum transferring operational risk from institutional buyers. For New Entrants and Emerging Players: Establish a beachhead in South African sugar milling biogas configurations where captive feedstock eliminates fuel price volatility exposure. Target KwaZulu-Natal manufacturing belts for modular reciprocating engine packages below synchronous connection certification thresholds. Go-to-market through anaerobic digestion engineering partnerships with existing pulp processing technical service providers. For Investors and Strategic Acquirers: Carve-out targets emerge from European conglomerates divesting non-core rotating equipment divisions amid energy transition portfolio rebalancing. Long-term viability hinges on service intensity profiles rather than equipment shipment volumes. Watch for Emirates Authority for Standardization and Metrology harmonization announcements with sub-Saharan accreditation systems as signal for cross-border equipment supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Service Agreement Extension | Locks in Saudi Aramco facilities against emerging Korean EPC competitors. |
| Absorption Chiller Integration Partnership | Captures Emirates Central Cooling Systems Corporation energy service agreement demand. |
| Localized Assembly Joint Venture | Compresses delivery timelines for Saudi Arabia's Eastern Province petrochemical corridor. |
| Biogas Feedstock Engineering Alliance | Opens Mpumalanga sugar milling captive power configurations with thermal recovery. |
| Digital Twin Platform Licensing | Monetizes Siemens Energy-style remote monitoring for mid-scale independent power producers. |
Research Methodology
Cross-validation between regulatory filing databases and equipment procurement records anchors the qualitative findings in this study. Primary interviews with IPP project developers, EPC contractors, utility planning officers, and aftermarket service heads combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Bottom-up installation tracking and top-down energy demand modeling triangulate volume estimates.
Calibration against historical efficiency mandate implementation timelines and currency-adjusted import cost trajectories shapes the analytical framework across the projection horizon. Segmentation dimensions span fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs derive from regression against industrial electricity demand growth and thermal efficiency enforcement intensity. Forecast inputs include Saudi Energy Efficiency Center audit compliance rates and Emirates Authority for Standardization and Metrology certification queue lengths.
Sensitivities concentrate around LNG spot price volatility, grid interconnection standard harmonization delays, and commissioning engineer availability constraints. Forecasts reflect documented assumptions on regulatory enforcement continuity and equipment import tariff stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Japan Uninterrupted Power Supply (UPS) Market
Power
Substation Automation System Market
Power
Japan Power Market
Power
Global Ancillary Services Power Market
Power
Equatorial Guinea Power Market
Power
Steam Turbine MRO Market
Power
Water Turbine Market
Power
Global Power Line Communication (PLC) Systems Market
Power
Telecom Power Rental Market
Power
Angola Power EPC Market
Power
China Power Market
Power
Malaysia Power EPC Market
Power
Mexico Power Market
Power
Global Hydraulic Turbine Market
Power
Power Purchase Agreement Market
Power
Germany Solar Inverter Market