
 Robotic Power Source Market | 2026-2036
Robotic Power Source Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Power Source Market Insights
Multi-source procurement for battery cells and power electronics is decoupling from the traditional single-vendor welding equipment model that dominated robotic power architectures for decades. Panasonic leverages its vertical integration across cell chemistry and welding system integration to sustain pricing leverage in automotive body shops. Lincoln Electric anchors its position through captive supply of inverter-based power sources for automated arc welding cells. Fronius International differentiates via Austrian-engineered charging interfaces that extend cycle life for mobile robot fleets.
A robotic power source converts stored or grid electrical energy into conditioned DC or pulsed outputs that drive servo motors, welding arcs, or locomotion systems in automated equipment, typically operating at voltages from 24 V to 600 V with efficiency targets above 90%. These units integrate battery management systems, thermal regulation, and communication protocols to ensure uninterrupted operation across variable duty cycles in industrial environments. Battery systems dominate installed base owing to lithium-ion energy density improvements, while fuel cell architectures represent the fastest-growing segment for extended-duty logistics robots where refueling speed outweighs capital cost premiums. Industrial automation commands the deepest margin pools as welding and material handling OEMs specify certified power architectures, whereas agriculture applications remain nascent with intermittent duty cycles limiting premium power source deployment.
FDA device safety standards, OSHA electrical workplace regulations, and China's GB/T standards for lithium-ion transport and storage collectively shape product certification requirements and market access conditions for robotic power source suppliers. The EU Battery Regulation and REACH compliance for cell materials are forcing redesigns of pack architectures to enable recycling traceability and restricted substance documentation. Stakeholders must monitor solid-state battery pilot timelines and hydrogen fuel cell cost curves to determine timing for platform transitions in next-generation robotic power architectures.
Market Dynamics
Power density requirements from mobile robot fleets are compressing battery pack design cycles, forcing suppliers to reconcile thermal management architectures with faster certification timelines under tightening safety regimes.
Growth Catalysts
- GB/T 31485 cell testing mandates:China's safety certification protocols are accelerating qualified supplier consolidation, filtering out uncertified pack assemblers and elevating tier-one cell manufacturers in procurement hierarchies.
- Warehouse automation retrofit cycles:E-commerce fulfillment centers are replacing lead-acid traction batteries with lithium-ion systems to support continuous 24-hour picking operations and opportunity charging protocols.
- Fuel cell refueling infrastructure:Hydrogen dispensing stations in logistics corridors are enabling extended-duty autonomous mobile robots to bypass battery swap downtime entirely.
Market Restraints
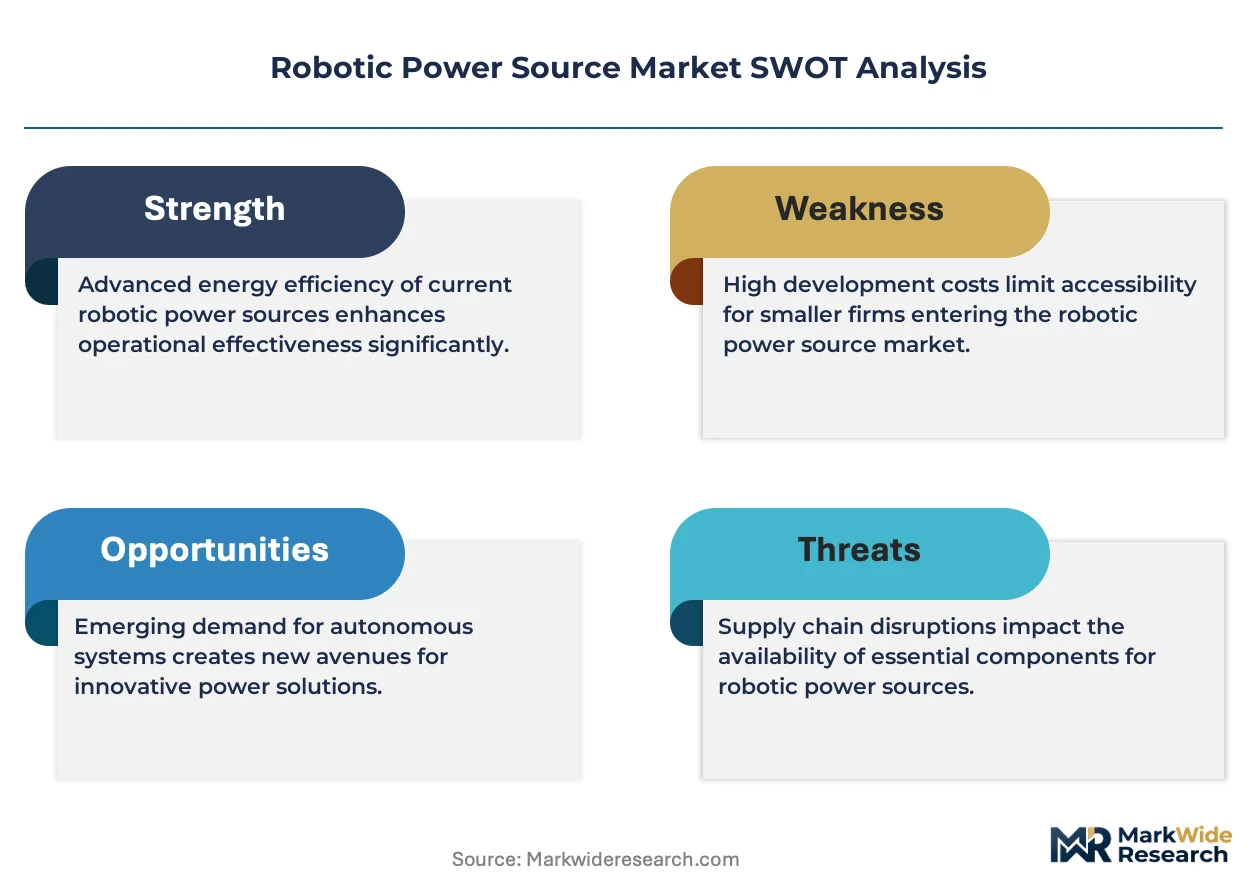
- Lithium carbonate price volatility:Cathode material cost swings compress gross margins for pack integrators unable to pass through input fluctuations under fixed-price OEM contracts.
- East Asian cell supply concentration:Manufacturing of high-NCM cylindrical cells clusters in specific Chinese and Korean production basins, creating single-source exposure for European and North American system builders.
- Solid-state battery timeline uncertainty:Pilot production delays for sulfide-electrolyte architectures are freezing platform roadmaps at incumbent lithium-ion specifications.
Strategic Opportunities
- Indian manufacturing automation:PLI scheme incentives for electronics and automotive production are creating first-mover openings for certified power system suppliers in Pune and Chennai industrial corridors.
- Second-life battery repurposing:End-of-service automotive packs are entering stationary robot charging applications under EU Battery Regulation traceability requirements.
- Wireless inductive charging:Contactless power transfer at automation waypoints is converging with fleet management software to enable fully autonomous continuous operation.
Industry Challenges
- Thermal runaway containment engineering:Pack designers face escalating complexity integrating multi-cell propagation prevention without sacrificing energy density targets.
- Legacy welding power source interoperability:Retrofitting inverter-based supplies into existing robotic work cells requires custom communication gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Power Source Market |
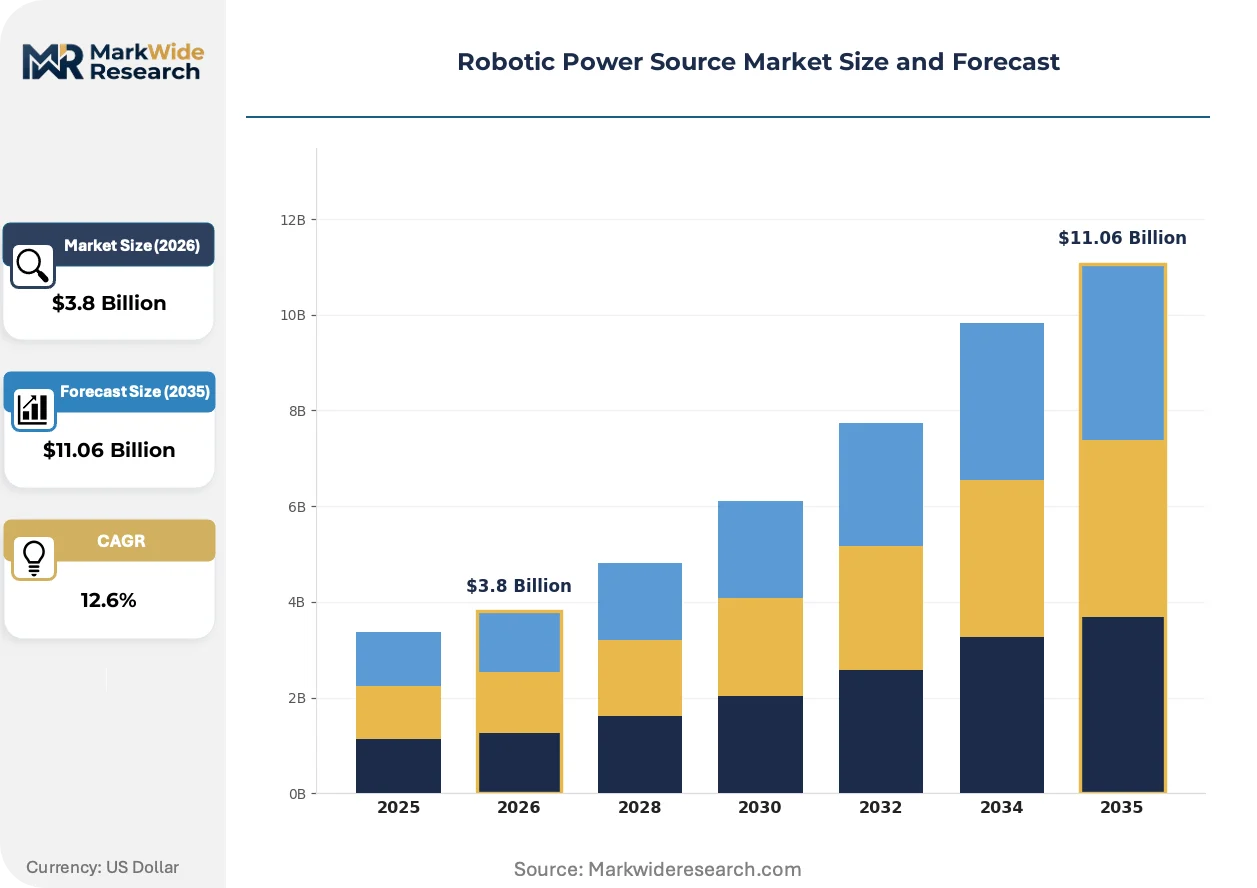
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.06 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery, Fuel Cell, Capacitor, Supercapacitor Application: Industrial Automation, Logistics, Cleaning, Agriculture Technology: Li-ion, Nickel Metal Hydride, Hydrogen Fuel, Solar End User: Manufacturing, Healthcare, Retail, Entertainment |
| Companies Covered | Fronius International, Lincoln Electric, Panasonic, OTC Daihen, Artesyn, KUKA, ABICOR BINZEL, Miller, SKS Welding Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Power Source Market Trends and Innovations
Power architecture decisions are migrating from equipment OEMs to end-user fleet operators, who now specify battery chemistry and charging protocols based on operational uptime requirements rather than defaulting to bundled supplier recommendations.
Solid-state lithium-metal cell technology is decentralizing power system design authority away from traditional welding equipment OEMs toward specialized battery integrators. Automotive-derived cell-to-pack architectures are entering industrial robot applications as tier-one suppliers repurpose EV module designs. This transfer is compressing development timelines and enabling direct procurement relationships between end-users and cell manufacturers.
REACH substance restrictions and EU Battery Regulation recycling mandates are forcing pack redesigns to enable automated disassembly and cathode material recovery. Industrial automation OEMs must now document full material provenance across cell supply chains. Welding robot power systems face the steepest compliance burden due to high cell count configurations and extended service life expectations.
Fleet operators are unbundling power system procurement from robot platform purchases, selecting third-party battery packs and charging infrastructure based on total cost of ownership models. This behavior concentrates buying power among large logistics deployers in German and Japanese automotive supplier parks. Traditional single-source equipment relationships are fragmenting into multi-vendor power architecture integrations.
Robotic Power Source Market Segmentation
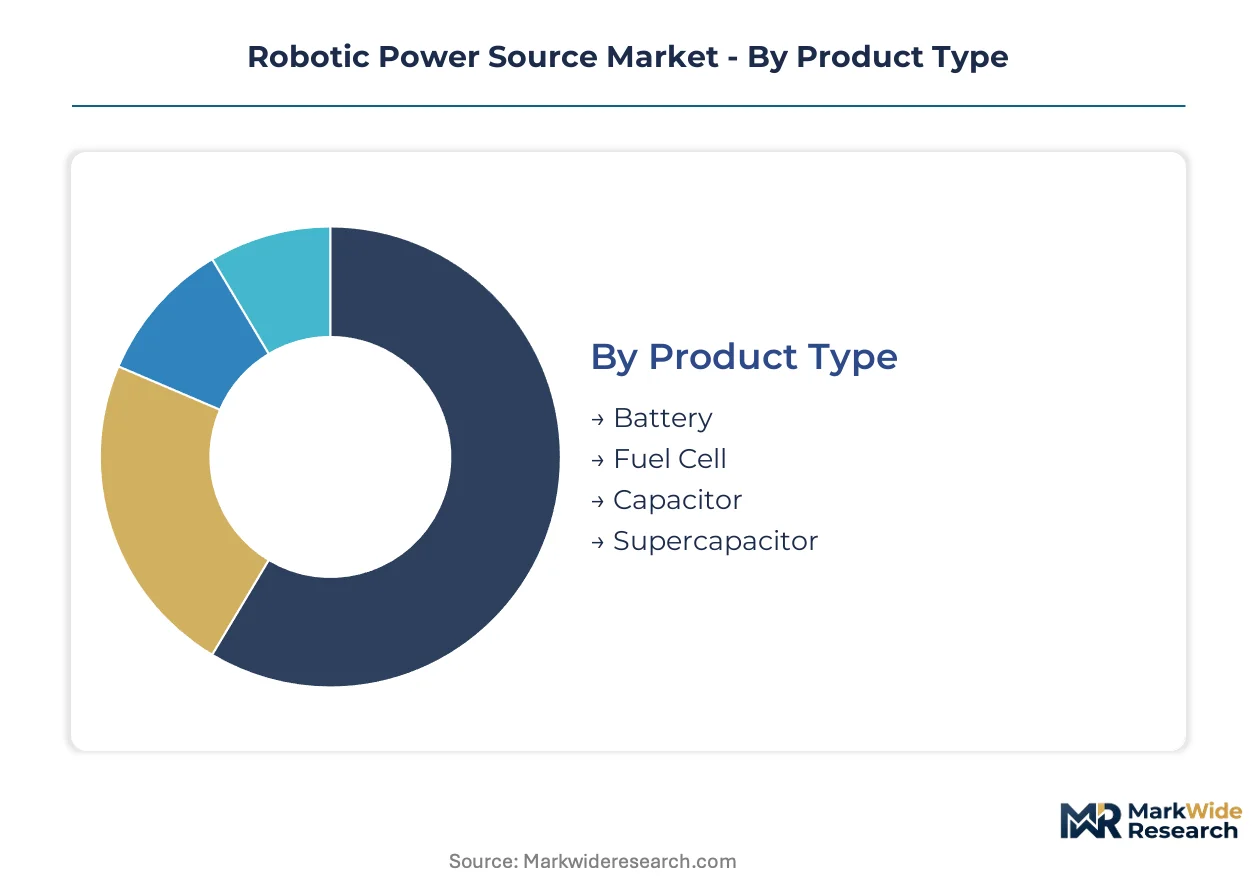
Power source segmentation in robotics reflects divergent certification burdens and duty cycle requirements across deployment environments. Procurement patterns increasingly separate high-reliability industrial specifications from cost-optimized consumer-facing applications.
Product Type:
GB/T 31485 cell testing and EU Battery Regulation traceability requirements impose tiered compliance loads across electrochemical architectures, with thermal runaway containment standards varying by energy density and chemistry class.
- Battery:Lithium-ion packs dominate installed base through energy density improvements above 250 Wh/kg and mature battery management system integration. Demand concentrates in East Asian manufacturing corridors spanning Shenzhen and Nagoya, where continuous welding robot operation requires 24-hour cycle reliability under OSHA electrical workplace regulations.
- Fuel Cell:Proton exchange membrane architectures deliver rapid refueling for extended-duty logistics fleets, bypassing battery swap downtime entirely. Hydrogen dispensing infrastructure in German automotive supplier parks and Japanese logistics corridors enables deployment where capital cost premiums are offset by uptime requirements.
- Capacitor:Electrostatic energy storage supports high-pulse welding applications requiring millisecond discharge rates.
- Supercapacitor:Hybrid configurations bridge power gaps in regenerative braking systems for mobile robot fleets.
Leading the category by volume: Battery. Growing fastest: Fuel Cell.
Application:
Margin structures diverge sharply between continuous-duty industrial specifications and intermittent-use consumer segments, with certification costs amortized over operational hours.
- Industrial Automation:Welding and assembly line power systems operate at 24 V to 600 V with efficiency targets above 90%, integrating thermal regulation and communication protocols for uninterrupted servo motor operation. Automotive body shops in Stuttgart and Toyota City specify certified architectures under JIS standards and CE marking requirements.
- Logistics:Warehouse automation fleets retrofit mobile robots with higher-density battery packs to support 24-hour picking operations. E-commerce fulfillment centers in Leipzig and Osaka deploy opportunity charging protocols under EU Battery Regulation and METI safety guidelines.
- Cleaning:Autonomous scrubber-dryers prioritize water ingress protection over energy density in commercial building deployments.
- Agriculture:Intermittent duty cycles limit premium power source deployment in robotic harvesting and precision spraying equipment.
Industrial Automation commands the steepest margin pool. Logistics is expanding most quickly through fleet retrofit cycles.
Technology:
Cell chemistry selection determines supply chain exposure to East Asian manufacturing concentration and REACH substance restriction compliance scope.
- Li-ion:High-NCM cylindrical cells from Korean and Chinese production basins power the majority of mobile robot fleets, with cathode material provenance documentation required under EU Battery Regulation recycling mandates.
- Nickel Metal Hydride:Legacy chemistry persists in cost-sensitive healthcare robot applications where energy density requirements remain modest.
- Hydrogen Fuel:PEM fuel cell adoption climbs fastest where refueling infrastructure density supports continuous logistics operations.
- Solar:Photovoltaic integration enables off-grid agricultural robot deployments with intermittent duty profiles.
Li-ion retains dominant share. Hydrogen Fuel gains share fastest through logistics corridor infrastructure buildout.
End User:
Procurement authority is migrating from equipment OEMs to fleet operators based on total cost of ownership models, fragmenting traditional single-source relationships.
- Manufacturing:Robotic welding and material handling OEMs specify certified power architectures with full material provenance documentation. Tier-one automotive suppliers in Bavaria and Aichi Prefecture unbundle power system procurement from robot platform purchases.
- Healthcare:FDA device safety standards and ISO 13485 quality management requirements govern power system reliability in surgical and rehabilitation robotics.
- Retail:Inventory scanning and customer service robots prioritize compact form factors over extended cycle life.
- Entertainment:Animatronic and theme park applications tolerate higher downtime tolerance than industrial specifications.
Manufacturing absorbs the deepest certification investment. Healthcare shows steepest expansion trajectory through surgical robot electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate refining capacity clusters in Jiangxi and Qinghai provinces anchor East Asian supply chains for robotic power systems. This feedstock geography shapes procurement patterns across manufacturing corridors in China, Japan, South Korea, Germany, and the United States.
China
Shenzhen and Dongguan manufacturing hubs drive demand for high-density battery packs in welding robot fleets. GB/T 31485 cell testing mandates filter uncertified suppliers from procurement hierarchies. The Yangtze River Delta concentration of pack integrators serves automotive body shop retrofits under MIIT industrial automation directives.
Japan
Nagoya and Toyota City automotive supplier parks specify certified power architectures for continuous welding operations. METI safety guidelines govern opportunity charging protocols in Osaka logistics corridors. JIS standards compliance elevates tier-one cell manufacturers in procurement decisions for robotic assembly lines.
South Korea
Seoul Capital Area battery integrators supply high-NCM cylindrical cells to mobile robot fleets. MFDS-equivalent industrial safety protocols align with EU Battery Regulation traceability requirements. Busan-Ulsan manufacturing clusters concentrate fuel cell power system assembly for extended-duty logistics applications.
Germany
Stuttgart and Bavarian automotive supplier parks unbundle power system procurement from robot platform purchases. EU Battery Regulation recycling mandates force pack redesigns for automated disassembly. Leipzig fulfillment centers deploy opportunity charging under REACH substance restriction compliance frameworks.
United States
Detroit and Southeast Michigan welding equipment OEMs specify inverter-based power sources for automated arc welding cells. OSHA electrical workplace regulations shape certification requirements for continuous-duty industrial specifications. California logistics corridors pilot hydrogen fuel cell refueling infrastructure for autonomous mobile robot fleets.
Robotic Power Source Market Competitive Landscape
Global majors compete with regional champions across power electronics integration and cell chemistry sourcing. The vendor base separates into welding equipment OEMs with captive power source divisions, specialized battery integrators with automotive cell supply relationships, and industrial automation platforms bundling third-party power architectures. Three archetypes dominate: vertically integrated welding system suppliers, independent battery pack specialists, and automation OEMs outsourcing power electronics. Competitive moves concentrate on backward integration into cell procurement and geographic expansion through certified distributor networks.
Within the welding equipment tier, Panasonic and Lincoln Electric exemplify divergent integration strategies. Fronius International occupies a position among European-engineered charging interface specialists. These three anchors represent distinct competitive vectors: Asian cell chemistry control, North American inverter-based power source supply, and Austrian-engineered fleet charging optimization.
| Leading Market Players |
|---|
| Fronius International |
| Lincoln Electric |
| Panasonic |
| OTC Daihen |
| Artesyn |
| KUKA |
| ABICOR BINZEL |
| Miller |
| SKS Welding Systems |
| Others |
Pricing and Supply Chain Analysis
Captive supply of high-NCM cylindrical cells anchors Panasonic's pricing leverage in automotive body shops while forcing competitors toward outsourced procurement models with compressed margin structures. This integration choice simultaneously secures GB/T 31485 certification continuity and defends premium positioning against unbundled battery integrators.
Pricing Analysis
Warranty bundling separates tier-one welding power sources from unbundled third-party battery packs, with Panasonic and Lincoln Electric embedding extended service coverage into capital equipment contracts while fleet operators purchasing standalone power systems absorb aftermarket risk directly. Price differentiation hinges on UL/CE certification tier and volume scale, with automotive OEM procurement pools commanding standard-economy splits and spot buyers facing customization premiums. Cost compression in mid-tier lithium-ion packs is intensifying because cathode material volatility cannot pass through fixed-price welding equipment contracts. Logistics fleet operators exhibit highest price sensitivity as they unbundle procurement from robot platforms, whereas certified automotive body shops prioritize uptime over unit cost.
Supply Chain Analysis
GB/T 31485 cell testing and EU Battery Regulation traceability requirements gate supplier qualification, filtering uncertified pack assemblers from procurement hierarchies and elevating tier-one manufacturers with documented material provenance. Manufacturing of high-NCM cylindrical cells clusters in China, South Korea, and Japan, drawing from lithium carbonate refining capacity concentrated in Jiangxi and Qinghai provinces. Single-source vulnerability runs through East Asian cell supply concentration for European and North American system builders unable to qualify alternative chemistries rapidly. Distribution runs through certified distributor networks anchored by welding equipment OEMs with captive power divisions and independent battery specialists serving unbundled fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU Battery Regulation recycling mandates and China's GB/T 31485 testing protocols erect barrier-to-entry moats favoring incumbents with established certification infrastructure and documented supply chain traceability.
For Market Incumbents: To counter unbundling pressure from logistics fleet operators, welding equipment OEMs should deepen backward integration into cell procurement partnerships with Korean and Chinese tier-one suppliers while accelerating certification investment for solid-state pilot platforms. Channel control through captive distributor networks defends pricing leverage against independent battery integrators eroding traditional single-source relationships. For New Entrants and Emerging Players: Certified distributor partnerships in India's Pune and Chennai industrial corridors offer the most penetrable geographic entry point under PLI scheme incentives for electronics manufacturing. White-space targets include second-life battery repurposing for stationary robot charging and wireless inductive charging infrastructure at automation waypoints, with go-to-market execution hinging on fleet management software integration rather than hardware differentiation alone. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by welding equipment OEMs seeking to backfill power electronics capabilities or automotive cell manufacturers diversifying into industrial automation applications. Long-term viability favors specialists with GB/T and EU Battery Regulation certification infrastructure already operational, as compliance timelines extend beyond typical venture horizons. Solid-state battery pilot production announcements serve as the critical signal to watch for platform transition timing and incumbent vulnerability windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Procurement | Secures GB/T 31485 qualified supply for automotive welding robot fleets under MIIT directives. |
| Second-Life Battery Repurposing | Enables EU Battery Regulation compliant stationary charging using end-of-service automotive packs. |
| Wireless Inductive Charging Deployment | Converges with fleet management software to enable continuous autonomous mobile robot operation. |
| Fuel Cell Infrastructure Partnership | Positions extended-duty logistics fleets in German and Japanese corridors for hydrogen refueling bypass. |
| Solid-State Battery Platform Transition | Captures thermal runaway containment advantages for high-density welding robot power architectures. |
Research Methodology
Multi-period observation of GB/T certification timelines, lithium carbonate price volatility patterns, and fleet operator procurement unbundling rates anchored the trend analysis, supplemented by interviews with welding equipment OEM procurement directors, battery pack integration engineers, logistics fleet operations managers, and industrial automation platform engineers. Secondary validation drew from MIIT industrial automation directives, EU Battery Regulation implementation guidance, SEC filings of listed welding equipment suppliers, and customs data on lithium-ion cell trade flows. Bottom-up unit economics across battery chemistry classes and top-down market sizing through equipment OEM shipment disclosures were triangulated against end-user fleet deployment surveys.
Input-output matrices mapped cell chemistry selection to duty cycle requirements across welding, logistics, and material handling applications, with segmentation dimensions spanning electrochemical architecture, operational voltage tier, certification burden class, and regional regulatory cluster. CAGRs were derived through regression of historical equipment shipment data against e-commerce fulfillment center buildout rates and automotive production forecasts. Industry-specific forecast inputs included hydrogen refueling station deployment density in logistics corridors and solid-state battery pilot production capacity announcements.
Caveats apply where lithium carbonate price volatility, solid-state battery timeline delays, or sudden tightening of REACH substance restrictions could materially shift the outlook for pack architecture redesigns and supplier qualification hierarchies. A model refresh is warranted upon material change in China's dual carbon policy enforcement intensity or EU Battery Regulation recycling mandate implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Digital Power Utility Market
Power
Europe Power Market
Power
Recloser Control Market
Power
Smart Power Market
Power
Smart PV Inverters Market
Power
Global Diesel Power Engine Market
Power
Italy Power EPC Market
Power
Mexico Power EPC Market
Power
India Power Market
Power
Gas Freeing Fan Market
Power
Asia-Pacific Package Substation Market
Power
Australia Power Market
Power
Uzbekistan Power Market
Power
Vietnam Power Market
Power
Global Advanced Marine Power Supply Market
Power
Argentina Power Market