
 Middle-East and Africa Nuclear Power Plant Equipment Market | 2026-2036
Middle-East and Africa Nuclear Power Plant Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Nuclear Power Plant Equipment Market Foresight
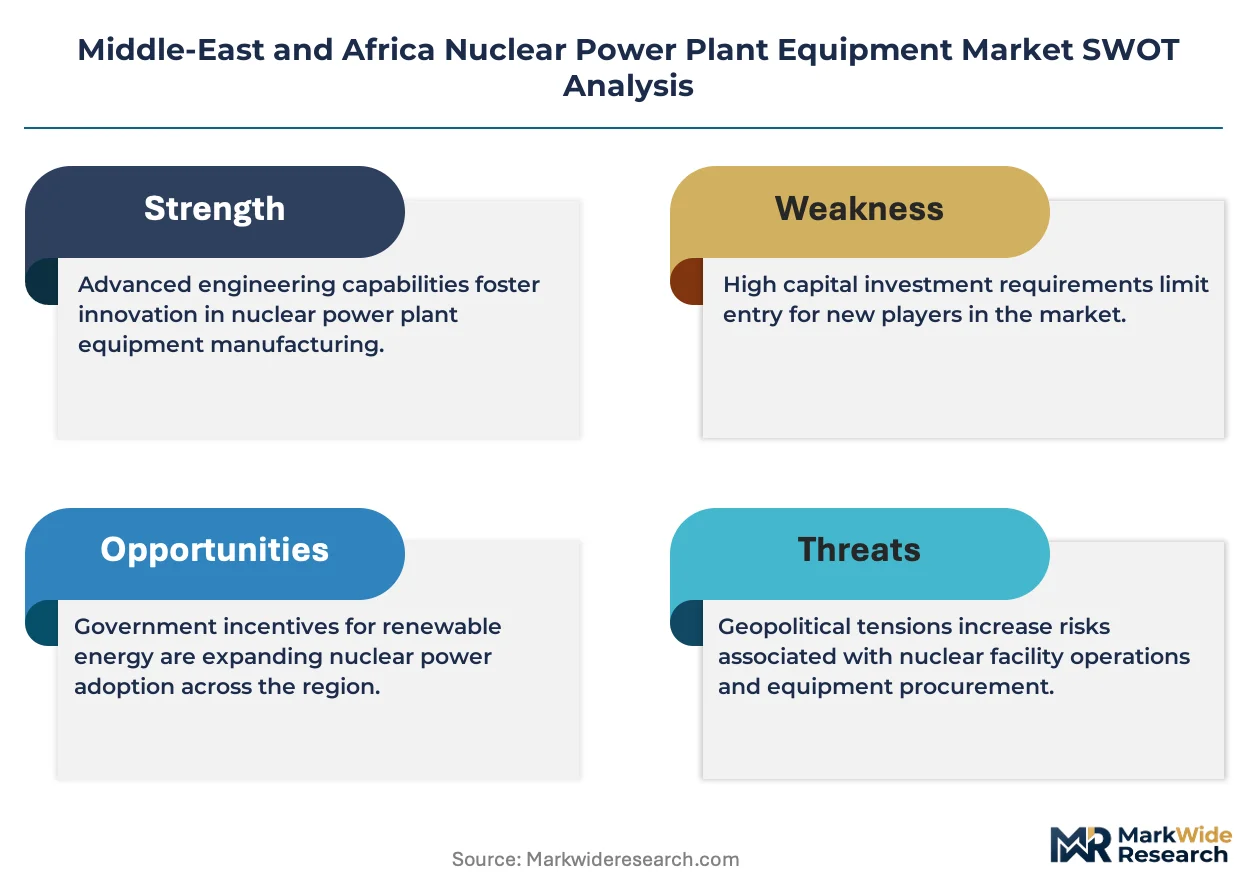
Modular reactor component bundling is hardening as the dominant procurement pattern across Middle-East and Africa nuclear projects. Westinghouse Electric Company LLC leverages its AP1000 design architecture to offer integrated island packages that reduce on-site construction risk. Korea Electric Power Corporation anchors its regional presence through reactor supply agreements tied to operator training and fuel-cycle services. Rosatom State Atomic Energy Corporation competes with build-own-operate structures that shift financing burden from host governments.
Nuclear power plant equipment encompasses engineered systems designed to sustain controlled fission reactions, maintain containment integrity, and convert thermal output to electrical power, with pressure vessels typically forged from SA-508 Grade 3 steel and rated for operating temperatures exceeding 300°C. Reactor Components command the largest value share given forged-vessel lead times and single-source supply constraints. Small Modular Reactor technology represents the fastest-expanding segment as Saudi Arabia and Jordan evaluate sub-300 MWe units for grid-isolated deployment. Control Systems concentrate margin pools where cybersecurity certification and I&C redundancy requirements create vendor stickiness.
The UAE's Federal Authority for Nuclear Regulation and South Africa's National Nuclear Regulator enforce equipment qualification protocols that align with IAEA safety standards, shaping supplier access and product certification timelines. Egypt's nuclear regulator under the Egyptian Atomic Energy Authority applies Russian-origin technical standards for the El Dabaa project, bifurcating procurement specifications across the region. Stakeholders must monitor regulatory harmonization progress between national bodies and assess how divergent certification requirements affect multi-country fleet strategies.
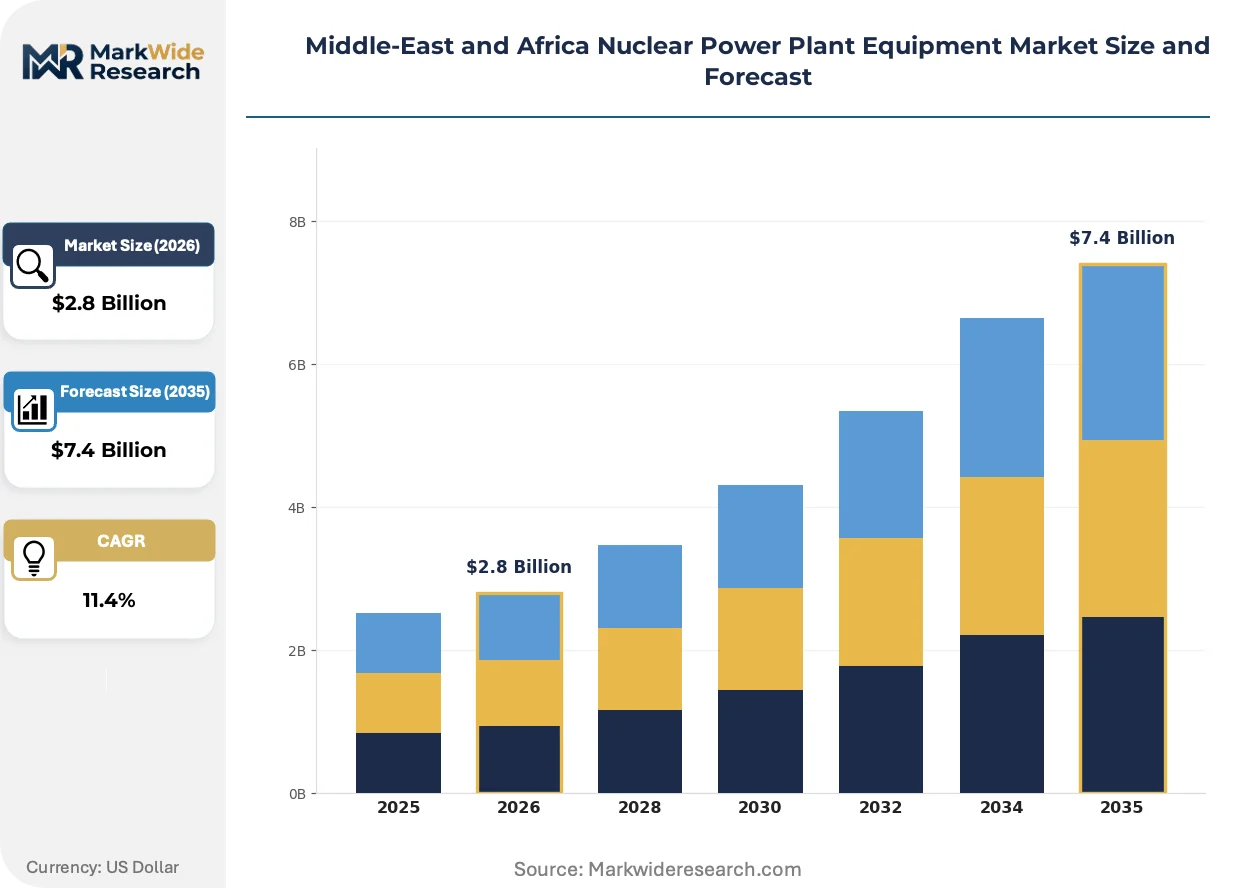
Market Dynamics
Modular reactor procurement is consolidating equipment specifications across the Middle-East and Africa, compressing vendor qualification cycles while fragmenting national regulatory requirements.
Growth Catalysts
- Grid diversification mandates:National utilities in the UAE and Saudi Arabia are expanding baseload nuclear capacity to reduce hydrocarbon dependence for electricity generation.
- FANR certification frameworks:The UAE's Federal Authority for Nuclear Regulation has established equipment qualification protocols that streamline foreign vendor access for reactor component approval.
- Koeberg life-extension programs:Eskom's refurbishment drives replacement orders for control systems and safety equipment across South Africa's sole operational facility.
Market Restraints
- Forged-vessel supply concentration:SA-508 Grade 3 steel pressure vessels face single-source constraints with limited qualified forges capable of meeting 300°C+ operating specifications.
- Divergent national standards:Egypt's El Dabaa project applies Russian-origin technical standards, bifurcating procurement specifications from IAEA-aligned frameworks used elsewhere.
- Extended qualification timelines:Equipment certification under South Africa's National Nuclear Regulator creates multi-year approval cycles for new component suppliers.
Strategic Opportunities
- Small Modular Reactor deployment:Saudi Arabia and Jordan are evaluating sub-300 MWe units for grid-isolated industrial zones and desalination integration.
- Integrated island packaging:Vendors offering bundled reactor and turbine-generator packages reduce on-site construction risk for first-time nuclear operators.
- Operator training tie-ins:Reactor supply agreements bundled with fuel-cycle services and workforce development create multi-decade revenue streams.
Industry Challenges
- Cybersecurity certification gaps:Instrumentation and control systems face evolving FANR and NNR cybersecurity requirements that outpace vendor development cycles.
- Legacy system integration:Life-extension projects at Koeberg require control system retrofits compatible with analog-era safety architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Nuclear Power Plant Equipment Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reactor Components, Control Systems, Safety Equipment, Auxiliary Systems End User: Government Agencies, Utility Companies, Construction Firms, Research Institutions Installation Type: On-Site Installation, Off-Site Assembly, Renovation, Upgrade Technology: Pressurized Water Reactor, Boiling Water Reactor, Small Modular Reactor, Advanced Gas-Cooled Reactor |
| Companies Covered | Westinghouse Electric Company LLC, Doosan Corporation, Rosatom State Atomic Energy Corporation, Mitsubishi Heavy Industries Ltd, Korea Electric Power Corporation, Babcock & Wilcox Company, JSC Atomstroyexport, General Electric, China National Nuclear Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Nuclear Power Plant Equipment Market Shifts & Advancements
Equipment procurement across the Middle-East and Africa is pivoting from component-level transactions toward integrated system architectures that compress construction schedules and transfer operational risk.
Digital instrumentation and control platforms are integrating cybersecurity-hardened architectures into reactor protection systems. Eskom and the Emirates Nuclear Energy Corporation are adopting these platforms for new-build and retrofit applications. This integration is compressing traditional hardware-redundancy approaches while expanding vendor stickiness through proprietary software ecosystems.
The UAE's Federal Authority for Nuclear Regulation and South Africa's National Nuclear Regulator are harmonizing equipment qualification protocols with IAEA safety standards. This alignment is reducing duplicate testing for multi-country fleet operators. Reactor component suppliers are responding by pre-qualifying products against the stricter of overlapping national requirements.
Build-own-operate contracting is displacing traditional engineering-procurement-construction models for new nuclear capacity. Host governments in Egypt and potentially Saudi Arabia are transferring construction risk and financing burden to reactor vendors. This shift is most visible in Russian-origin projects where Rosatom retains equity stakes and operational control through multi-decade power purchase agreements.
Middle-East and Africa Nuclear Power Plant Equipment Market Segmentation
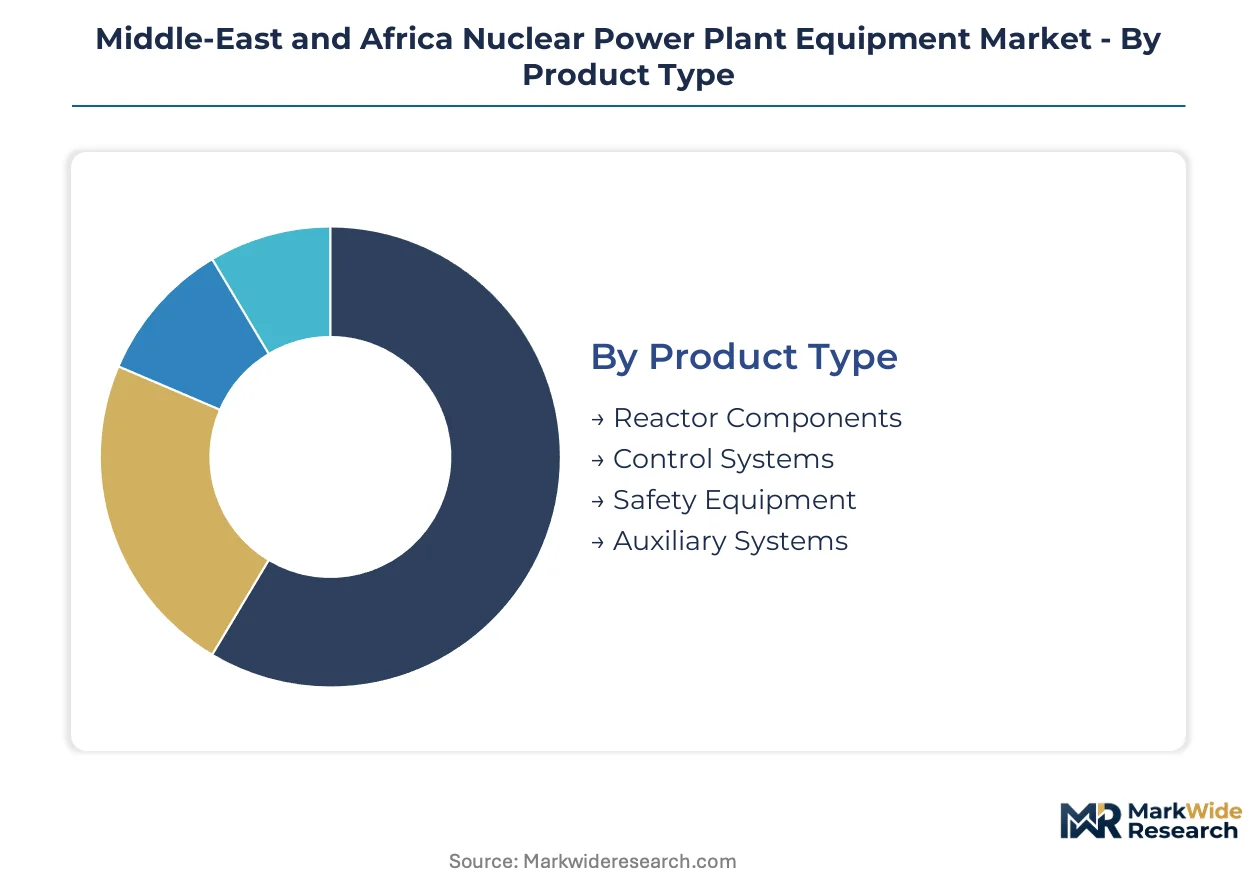
Equipment procurement patterns across Middle-East and Africa nuclear projects diverge sharply by product complexity and regulatory burden. Vendors must calibrate qualification investments against segment-specific margin profiles and certification timelines.
Product Type:
Reactor Components command premium pricing given forging constraints, while Control Systems concentrate recurring revenue through cybersecurity upgrade cycles.
- Reactor Components:Pressure vessels, steam generators, and reactor vessel internals are forged from SA-508 Grade 3 steel with 300°C+ thermal ratings. Demand concentrates in South Africa's Koeberg life-extension programs and Egypt's El Dabaa new-build, where single-source supply constraints extend lead times.
- Control Systems:Digital instrumentation and control platforms integrate cybersecurity-hardened architectures for reactor protection. Procurement is accelerating in the UAE's Barakah facility and Saudi Arabia's planned reactors, where FANR and IAEA-aligned cybersecurity mandates create vendor stickiness through proprietary software ecosystems.
- Safety Equipment:Containment isolation systems and emergency core cooling equipment meet redundant safety architecture requirements.
- Auxiliary Systems:Fuel handling equipment, ventilation systems, and water treatment infrastructure support operational continuity.
Mature deployment sits with Reactor Components. Newer deployment is concentrated in Control Systems.
End User:
Government buyers dominate capital allocation, while Utility Companies drive operational procurement and life-cycle service contracts.
- Government Agencies:National atomic energy authorities and sovereign wealth funds control new-build authorization and vendor selection. Egypt's Nuclear Power Plants Authority and Saudi Arabia's King Abdullah City for Atomic and Renewable Energy shape procurement through state-backed financing structures.
- Utility Companies:Emirates Nuclear Energy Corporation and Eskom execute equipment procurement for operational facilities. These operators are expanding baseload capacity while navigating divergent national regulatory frameworks across the Middle-East and Africa.
- Construction Firms:EPC contractors manage on-site integration and civil works coordination for reactor island construction.
- Research Institutions:Universities and national laboratories procure specialized equipment for reactor physics and materials testing programs.
Capital commitment depth is greatest with Government Agencies. Operational procurement frequency is highest with Utility Companies.
Installation Type:
On-Site Installation absorbs the largest construction risk allocation, while Off-Site Assembly is gaining traction for modular reactor architectures.
- On-Site Installation:Traditional stick-built construction for large-scale reactors requires extended civil works and component integration at the plant location. This approach dominates Egypt's El Dabaa and the UAE's completed Barakah units, where local workforce development and supply chain localization requirements extend project timelines.
- Off-Site Assembly:Factory fabrication of modular reactor components compresses construction schedules and transfers quality control to vendor facilities. Saudi Arabia and Jordan are evaluating this approach for Small Modular Reactor deployment in grid-isolated industrial zones.
- Renovation:Component replacement and system refurbishment for operational facilities approaching design life limits.
- Upgrade:Capacity enhancement and efficiency improvements for existing reactor systems.
Project risk concentration is heaviest with On-Site Installation. Schedule compression potential is strongest with Off-Site Assembly.
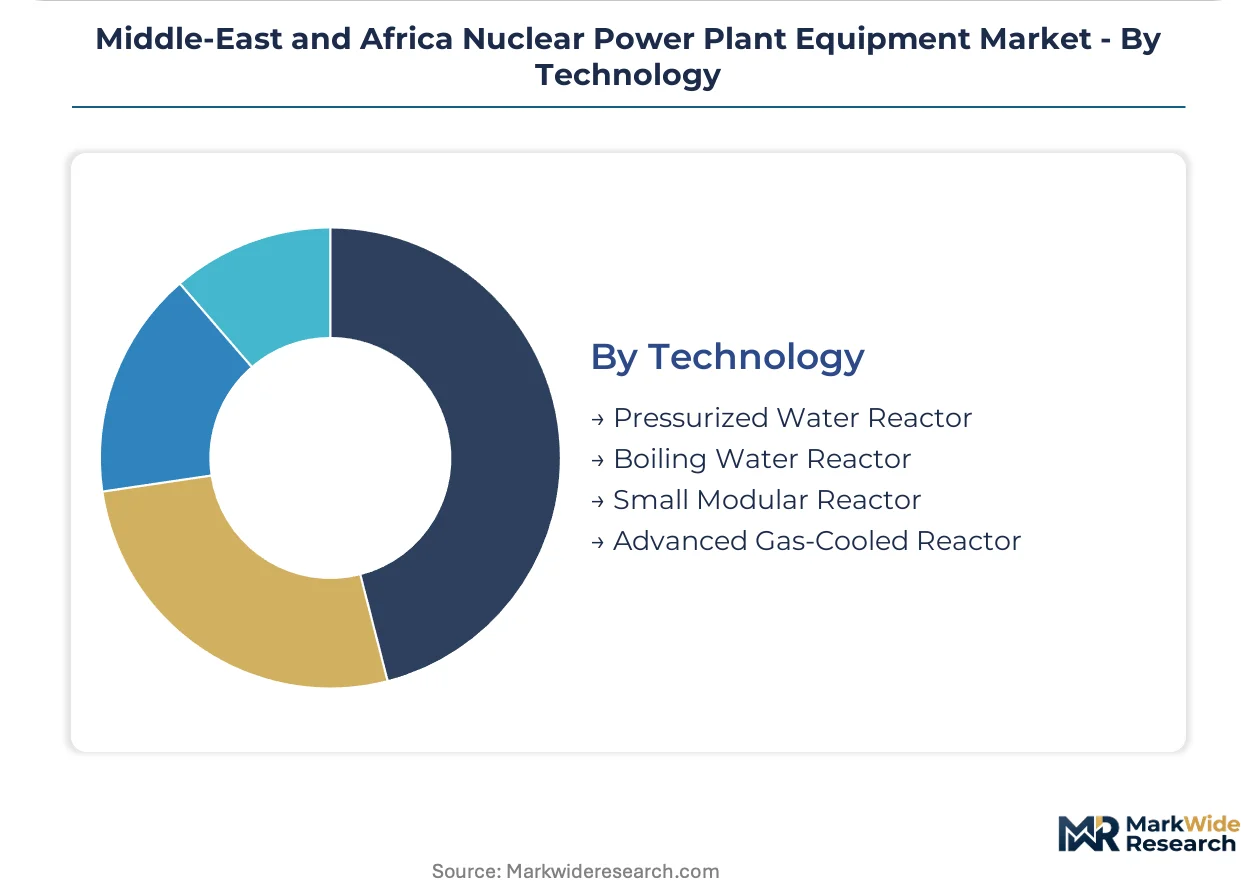
Technology:
Pressurized Water Reactor designs anchor current procurement volumes, while Small Modular Reactor technology is climbing the fastest across evaluation pipelines.
- Pressurized Water Reactor:Light-water cooled and moderated systems with proven operational history dominate current Middle-East and Africa deployment. The UAE's Barakah facility and Egypt's El Dabaa project utilize this technology, with equipment procurement aligned to Korean and Russian vendor supply chains respectively.
- Small Modular Reactor:Sub-300 MWe factory-fabricated units offer scalable baseload for industrial zones and desalination integration. Saudi Arabia's national nuclear program and Jordan's energy diversification strategy are actively evaluating SMR procurement, with vendor qualification timelines shorter than large-reactor equivalents.
- Boiling Water Reactor:Direct-cycle steam generation systems with simplified piping architecture but larger containment requirements.
- Advanced Gas-Cooled Reactor:Graphite-moderated, carbon dioxide-cooled designs with higher thermal efficiency potential.
Operational fleet scale is largest with Pressurized Water Reactor. Pipeline evaluation activity is most intense with Small Modular Reactor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates in countries with active reactor construction or life-extension programs, while prospective markets evaluate modular technologies. Consumption patterns diverge between operational fleet maintenance and new-build specifications.
United Arab Emirates
The Emirates Nuclear Energy Corporation operates the Barakah facility, the region's first commercial nuclear plant. The Federal Authority for Nuclear Regulation enforces equipment qualification protocols aligned with IAEA safety standards. Abu Dhabi hosts the regional procurement center where ENEC coordinates vendor certification for reactor components and digital control systems.
Saudi Arabia
The King Abdullah City for Atomic and Renewable Energy evaluates Small Modular Reactor deployment for industrial zones and desalination integration. The national nuclear program applies international safety standards while developing domestic regulatory capacity. Riyadh anchors policy coordination, with project evaluation concentrating on sub-300 MWe units for grid-isolated applications.
South Africa
Eskom's Koeberg life-extension programs drive replacement orders for control systems and safety equipment at the continent's sole operational nuclear facility. The National Nuclear Regulator enforces multi-year equipment certification cycles for new component suppliers. The Western Cape province hosts Koeberg and surrounding technical infrastructure supporting operational maintenance.
Egypt
The Nuclear Power Plants Authority oversees the El Dabaa project under construction with Russian technology supply. The Egyptian Atomic Energy Authority applies Russian-origin technical standards, bifurcating procurement specifications from IAEA-aligned frameworks elsewhere. The Mediterranean coastal site concentrates construction activity and equipment staging for the four-reactor complex.
Jordan
The Jordan Atomic Energy Commission evaluates Small Modular Reactor options for energy diversification and water desalination. National regulators develop certification frameworks for first-time nuclear deployment. Amman coordinates regional cooperation initiatives and vendor qualification for sub-300 MWe unit evaluation.
Middle-East and Africa Nuclear Power Plant Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across reactor component supply. The vendor base clusters around three strategic archetypes: integrated island packagers offering bundled reactor and turbine-generator systems, state-backed entities providing build-own-operate financing structures, and component specialists concentrating on forged vessels or digital control platforms. Dominant competitive moves include technology licensing agreements that transfer reactor designs to emerging markets, and strategic partnerships bundling operator training with equipment supply.
Among state-backed atomic energy corporations, Rosatom State Atomic Energy Corporation and Korea Electric Power Corporation exemplify divergent market approaches. Westinghouse Electric Company LLC occupies a position within the integrated technology tier. These entities anchor competitive positioning through distinct contracting models: equity-retaining build-own-operate structures, comprehensive fuel-cycle service agreements, and design-licensing arrangements for AP1000 reactor architectures.
| Leading Market Players |
|---|
| Westinghouse Electric Company LLC |
| Doosan Corporation |
| Rosatom State Atomic Energy Corporation |
| Mitsubishi Heavy Industries Ltd |
| Korea Electric Power Corporation |
| Babcock & Wilcox Company |
| JSC Atomstroyexport |
| General Electric |
| China National Nuclear Corporation |
| Others |
Supply & Pricing Matrix
SA-508 Grade 3 steel ingots flow from a handful of qualified forges through tiered equipment qualification protocols, with FANR-certified reactor components commanding substantial premiums over standard pressure-vessel grades while uncertified alternatives face exclusion from UAE and South African procurement pools.
Pricing Analysis
Margin tightening in reactor component supply traces to single-source forging constraints and extended IAEA-aligned certification timelines. Three-tier pricing structure separates FANR/NNR-certified premium grades from standard industrial pressure-vessel specifications and uncertified economy alternatives. Price differentiation hinges on cybersecurity certification tier for digital I&C platforms and forged-vessel thermal rating. Cost compression accelerates in auxiliary systems as modular reactor bundling standardizes specifications. Government agencies exhibit lowest price sensitivity given sovereign financing structures, while construction firms face acute margin pressure on fixed-price EPC contracts.
Supply Chain Analysis
Forged reactor vessel supply rests on qualified facilities in Japan, France, and Russia, with SA-508 Grade 3 steel sourcing concentrated in North American and European specialty mills. Control system hardware draws from South Korean and German automation specialists, while digital I&C software ecosystems anchor in vendor-proprietary architectures. Single-source vulnerability concentrates in 300°C+ rated pressure vessels where alternative qualification pathways require multi-year FANR or NNR cycles. Distribution runs through national atomic energy authorities and utility procurement centers rather than open merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forged-vessel fabrication capacity constraints prop equipment pricing across the Middle-East and Africa, with qualified supplier scarcity insulating incumbent margins from commoditization pressure.
For Market Incumbents: Acquire cybersecurity certification capabilities to harden digital I&C platforms against evolving FANR and NNR requirements. Lock in long-term fuel-cycle service agreements with Saudi Arabia and Jordan to secure recurring revenue streams as SMR evaluation advances. Defend against Rosatom's build-own-operate encroachment by bundling operator training with reactor component supply. For New Entrants and Emerging Players: Capture white-space in Small Modular Reactor auxiliary systems where vendor qualification timelines compress versus large-reactor equivalents. Target Jordan's grid-isolated industrial zones and Egypt's El Dabaa localization requirements for first-mover positioning. Enter through cybersecurity-hardened control system retrofits compatible with Koeberg's analog-era safety architectures. For Investors and Strategic Acquirers: Saudi Arabia's SMR site selection announcement is the leading indicator that sub-300 MWe procurement will accelerate across the region. Long-term viability favors suppliers with FANR pre-qualification and forge partnerships capable of SA-508 Grade 3 output. Watch for Egyptian regulatory harmonization signals with IAEA standards as a trigger for specification convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Forge Partnership Consolidation | Secures SA-508 Grade 3 capacity for Koeberg and El Dabaa replacement cycles. |
| Cybersecurity Certification Investment | Aligns digital I&C platforms with FANR and NNR evolving requirements. |
| SMR Auxiliary System Development | Positions vendors for Saudi Arabia and Jordan sub-300 MWe evaluations. |
| Operator Training Bundling | Creates multi-decade revenue streams tied to ENEC and emerging national programs. |
| Localization Joint Venture | Satisfies Egyptian and South African domestic content mandates for new-build and retrofit. |
Research Methodology
Multi-period observation of reactor component order flows, regulatory certification timelines, and utility capital expenditure patterns anchored the trend analysis, supplemented by interviews with nuclear procurement officers at Emirates Nuclear Energy Corporation and Eskom, FANR and NNR regulatory affairs leads, EPC project managers, and forged-vessel supply specialists. Secondary validation drew from IAEA safety standards documentation, national nuclear regulator filings, reactor vendor technical disclosures, and utility integrated resource plans. Bottom-up equipment procurement tracking triangulated against top-down national nuclear program capacity targets.
Input-output matrices mapped reactor component demand across pressure vessel, steam generator, and I&C categories against forge capacity, certification throughput, and installation schedules over the projection horizon. Segmentation dimensions spanned product complexity tier, end-user procurement authority, installation risk allocation, and reactor technology type. CAGRs derived from equipment replacement cycles at Koeberg, new-build progress at El Dabaa, and SMR evaluation milestones in Saudi Arabia and Jordan.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory harmonization progress between FANR, NNR, and Egyptian Atomic Energy Authority standards. Forecasts reflect assumptions regarding SMR commercialization timelines, forge capacity expansion, and geopolitical stability affecting Russian-origin supply chains. A small set of triggers—Saudi SMR site selection, Egyptian regulatory alignment signals, and Koeberg life-extension authorization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Germany Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Steam Generator Market
Nuclear Energy
Nuclear Fuel Fabrication Market
Nuclear Energy
North America Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Small Modular Reactor (SMR) Market
Nuclear Energy
Europe Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Power Market
Nuclear Energy
Global Thorium Reactor Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
China Nuclear Power Plant Equipment Market
Nuclear Energy
North America Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Power Pump Market
Nuclear Energy
Thorium Market
Nuclear Energy
Industrial Radioactive Source Market
Nuclear Energy
North America Nuclear Power Plant and Equipment Market
Nuclear Energy
Europe Nuclear Reactor Decommissioning Market