
 North America and Europe Electric Boilers Market | 2026-2036
North America and Europe Electric Boilers Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Electric Boilers Market Analysis
The capability gap between integrated European boiler specialists and North American assembly-focused competitors is collapsing as modular manufacturing platforms standardize across both regions. Bosch Thermotechnology leverages its captive heat-pump component supply to sustain margin leadership in high-capacity electric thermal boilers. Viessmann Climate Solutions anchors its position through deep backward integration into control systems and connected-home platforms. Cleaver-Brooks competes in the industrial segment with heavy-gauge pressure-vessel fabrication expertise that few rivals replicate at scale.
North America and Europe electric boilers are closed-vessel electromechanical systems that convert electrical energy into thermal energy through resistive or electrode heating elements, typically operating at pressures up to 30 bar and temperatures reaching 200°C for steam generation in commercial and industrial settings. Electric steam boilers serve sterilization and humidification loads in pharmaceutical and food-processing facilities where combustion-free heat eliminates stack emissions and simplifies permitting. Electric water boilers dominate residential and light-commercial retrofits across the European Union, where product-type segmentation shows wall-mounted compact units leading volume while floor-standing modular systems capture the highest margin pools in institutional applications. Power-rating segmentation reveals medium-capacity models as the fastest-growing tier, driven by commercial building electrification mandates in France, Germany, and the Netherlands.
The EU Green Deal and F-Gas Regulation are accelerating fossil-fuel heating phaseouts, while the EPA in the United States enforces tightened emissions standards that push commercial building operators toward electric alternatives. CE marking under the Ecodesign Directive and forthcoming EU AI Act requirements for connected heating controls are reshaping product development roadmaps and market access conditions. Stakeholders must monitor how national building codes in Germany, France, and select US states integrate heat-pump compatibility requirements that could either expand or constrain electric boiler deployment in hybrid systems.
Market Dynamics
Electrification mandates in Germany and France are forcing building operators to replace fossil-fuel heating infrastructure faster than supply chains can scale, compressing installation timelines and amplifying procurement bottlenecks for medium-capacity systems.
Growth Catalysts
- EU Green Deal:The framework's building renovation targets mandate fossil-fuel phaseouts in residential and commercial structures, creating immediate replacement demand across member states with binding enforcement timelines.
- Pharmaceutical sterilization loads:Electric steam boilers eliminate stack emissions and simplify EPA permitting for facilities in the United States, accelerating adoption in FDA-regulated manufacturing environments.
- Netherlands district heating:Municipal networks in Amsterdam and Rotterdam are integrating electric thermal storage systems to balance grid loads and reduce natural gas dependency in dense urban cores.
Market Restraints
- Copper and silicon steel volatility:Resistive heating elements and transformer cores face input cost swings that erode manufacturer margins and destabilize project quoting for institutional buyers.
- Nordic supply concentration:Pressure-vessel fabrication for high-capacity systems clusters in specialized Swedish and Finnish foundries, creating single-source vulnerability for North American project developers.
- Heat pump substitution:EU member state incentives increasingly favor air-source and geothermal heat pumps for residential retrofits, diverting capital from pure electric boiler installations in sub-50kW segments.
Strategic Opportunities
- Polish residential market:Coal heating bans in Silesia and Malopolska create immediate retrofit demand where district heating infrastructure remains underdeveloped and electric boilers offer faster deployment than heat pump retrofits.
- Connected-home convergence:Integration of electric boilers with demand-response platforms and residential battery storage enables participation in grid-balancing markets across Germany and the Netherlands.
- US Inflation Reduction Act:Commercial building electrification tax credits reduce effective installed costs for electric thermal systems in multi-family housing and institutional projects.
Industry Challenges
- CE marking timeline compression:Ecodesign Directive updates and impending EU AI Act requirements for connected controls are forcing manufacturers to accelerate certification cycles while maintaining legacy product lines.
- Electrode boiler technician scarcity:High-voltage electrode systems require specialized commissioning expertise that training programs in France and Germany have not scaled to match installation volume growth.
- Legacy hydronic integration:Retrofit projects in older European building stock face compatibility failures between modern electric boiler control logic and existing radiator valve systems, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Electric Boilers Market |
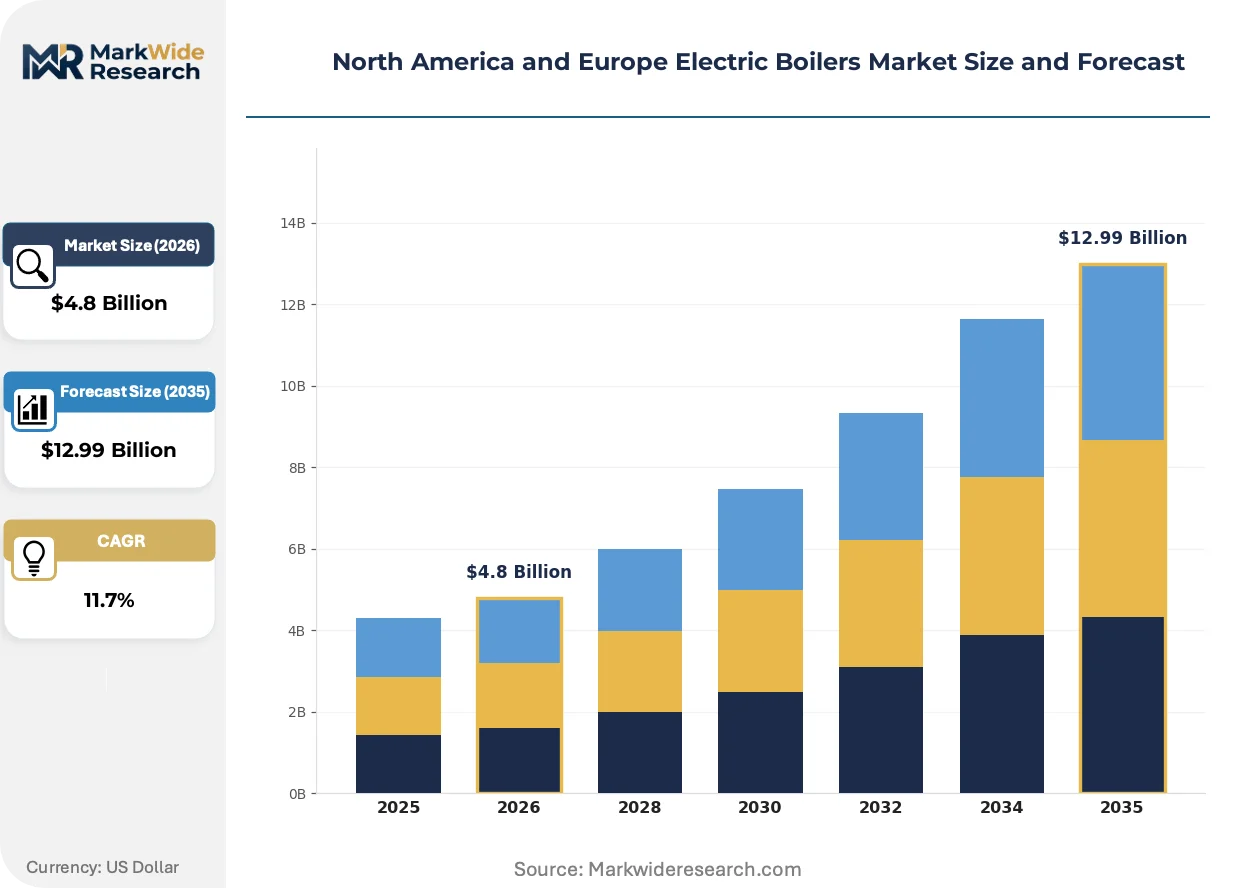
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Water Boilers, Electric Steam Boilers, Electric Thermal Boilers, Compact Electric Boilers End User: Residential, Commercial, Institutional, Industrial Installation Type: Wall-Mounted, Floor-Standing, Portable, Modular Power Rating: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity |
| Companies Covered | Bosch Thermotechnology, Viessmann Climate Solutions, Cleaver-Brooks, Lochinvar, Vaillant Group, Ariston Holding, Stiebel Eltron, Carrier, Chromalox, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Electric Boilers Market Emerging Trajectories
Modular thermal storage and smart grid integration are redefining product architecture, shifting competitive advantage from pure hardware efficiency toward system-level energy management capabilities.
Electrode steam generation technology is supplanting traditional resistive elements in commercial applications above 1MW. Food-processing facilities in the Netherlands and pharmaceutical plants in Ireland are adopting these systems for their superior ramp rates and reduced mineral scaling. The shift is compressing maintenance intervals and enabling participation in intraday power markets through rapid load modulation.
The F-Gas Regulation's phase-down schedule is accelerating refrigerant-based heat pump restrictions in commercial buildings across Germany and France. This regulatory pressure is redirecting capital toward electric thermal alternatives in applications where heat pump efficiency degrades. District heating operators in Copenhagen and Stockholm are responding by specifying electric peak-load boilers for sub-zero temperature periods.
Building operators are unbundling equipment procurement from long-term service contracts, forcing manufacturers to compete on upfront capital cost rather than lifecycle performance. This pattern is most visible in French multi-family housing associations and US university campus projects. Traditional integrated suppliers are responding with transparent component pricing and third-party maintenance certification programs.
North America and Europe Electric Boilers Market Segmentation
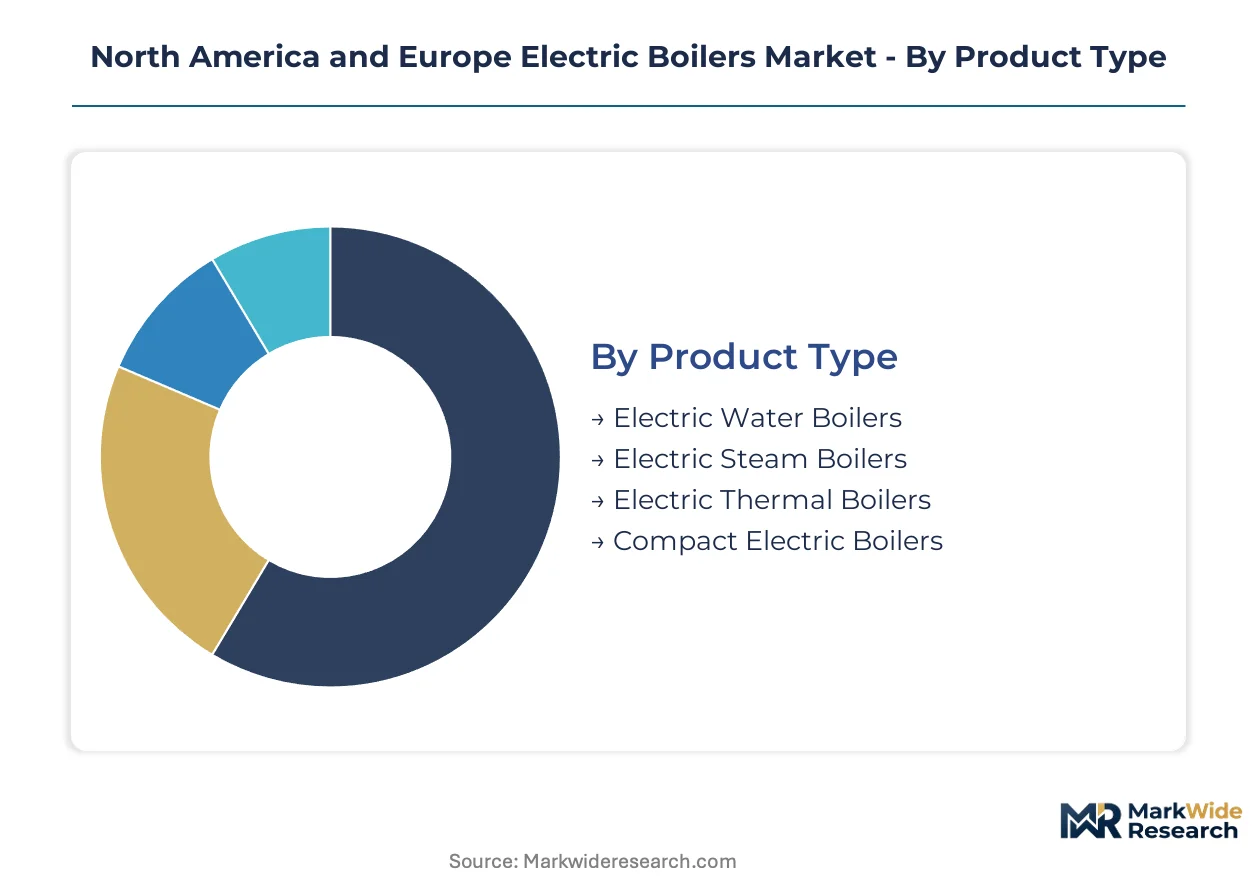
Segmentation in the North America and Europe electric boilers market reveals how regulatory pressure and retrofit economics reshape procurement patterns across jurisdictions. Product architecture and power classification determine compliance pathways under the EU Ecodesign Directive and EPA emissions frameworks.
Product Type:
CE marking requirements under the Ecodesign Directive create divergent compliance burdens across product architectures, with steam generation systems facing stricter pressure-vessel certification than hydronic units.
- Electric Water Boilers:Closed-vessel systems generating hot water up to 110°C through resistive immersion elements, dominating residential retrofits in Germany and France where the EU Green Deal mandates fossil-fuel phaseouts in existing building stock.
- Electric Steam Boilers:Pressure-rated vessels producing saturated steam for sterilization and process heat, concentrating demand in pharmaceutical manufacturing facilities across Ireland and the Netherlands where FDA and EMA regulations prohibit combustion emissions near cleanroom environments.
- Electric Thermal Boilers:High-mass systems designed for district heating integration and thermal storage applications.
- Compact Electric Boilers:Reduced-footprint units targeting apartment retrofits and light commercial spaces with constrained mechanical rooms.
Established volume favors electric water boilers; emerging adoption favors electric steam boilers.
End User:
Cost tier differentiation separates premium-specified institutional projects from price-sensitive residential retrofits, with procurement authority fragmenting across housing associations, facility managers, and municipal operators.
- Residential:Single-family and multi-family dwelling applications where wall-mounted compact units replace gas-fired combi boilers, with German KfW subsidies and French MaPrimeRenov incentives accelerating deployment timelines in coal-dependent regions like Silesia.
- Commercial:Office buildings, retail, and hospitality requiring medium-capacity modular systems, with Dutch commercial electrification mandates in Amsterdam and Rotterdam driving specification of grid-responsive thermal storage configurations.
- Institutional:Universities, hospitals, and government facilities with extended capital planning cycles and lifecycle cost evaluation frameworks.
- Industrial:Process heat and sterilization loads in FDA-regulated manufacturing where combustion-free heat simplifies EPA Title V permitting.
Residential captures highest unit volume; industrial commands highest margin per installation.
Installation Type:
Application context dictates physical configuration, with urban density constraints in Nordic and Benelux cities favoring wall-mounted solutions while campus and district heating projects specify floor-standing modular arrays.
- Wall-Mounted:Compact enclosures designed for utility room or kitchen installation, dominating French and German residential retrofits where existing gas boiler footprints constrain replacement options.
- Floor-Standing:Heavy-gauge pressure vessels on structural skids, specified for institutional and district heating projects in Copenhagen and Stockholm where electric peak-load boilers supplement heat pump networks during sub-zero periods.
- Portable:Temporary or supplemental heating units with quick-connect utility interfaces.
- Modular:Scalable arrays of standardized boiler modules enabling incremental capacity expansion and redundancy for critical process loads.
Floor-standing systems anchor project value; wall-mounted units drive replacement volume.
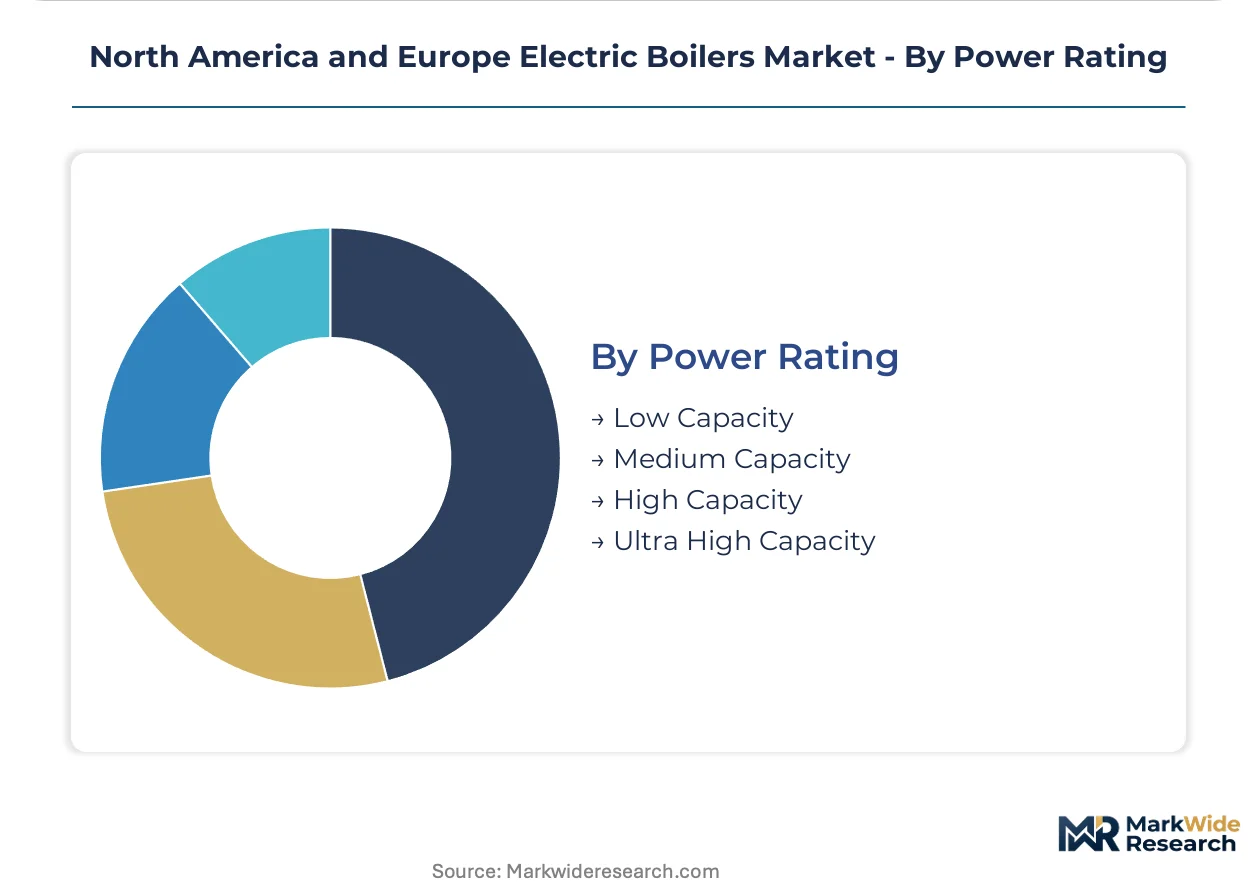
Power Rating:
Supply concentration in Swedish and Finnish foundries for high-capacity pressure vessels creates procurement bottlenecks that favor medium-capacity standardized platforms with shorter lead times.
- Low Capacity:Sub-15kW units for single-family dwellings, facing substitution pressure from air-source heat pumps in German and French incentive structures that favor refrigerant-based systems below this threshold.
- Medium Capacity:15-150kW systems capturing commercial building electrification mandates, with French tertiary sector regulations and Dutch gas connection bans accelerating specification in office and retail retrofits.
- High Capacity:150kW-1MW systems for institutional and light industrial process heat.
- Ultra High Capacity:Above-1MW electrode steam systems requiring specialized high-voltage infrastructure and commissioning expertise.
Medium capacity is climbing the fastest; ultra high capacity faces technician scarcity constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish residential buyers exhibit the sharpest price sensitivity as coal heating bans force rapid retrofits on constrained budgets, while Dutch district heating authorities prioritize lifecycle performance over capital cost in electric thermal storage procurement.
Germany
Residential retrofits in former coal-dependent regions of North Rhine-Westphalia and Brandenburg are accelerating electric water boiler deployment. The KfW subsidy program and federal Building Energy Act mandate fossil-fuel phaseouts in existing stock. Munich and Stuttgart engineering clusters are developing grid-responsive control systems for medium-capacity commercial installations.
France
Multi-family housing associations in Île-de-France are unbundling equipment procurement from service contracts, compressing upfront pricing. The MaPrimeRenov incentive scheme and tertiary sector electrification regulations drive specification timelines. Lyon and Grenoble industrial zones are integrating electric steam boilers into pharmaceutical manufacturing facilities under ANSM cleanroom requirements.
Netherlands
Amsterdam and Rotterdam municipal networks are deploying electric peak-load boilers to balance district heating loads during sub-zero periods. National gas connection bans in new construction redirect capital toward thermal storage configurations. The Ecodesign Directive and forthcoming EU AI Act requirements are reshaping connected-control product roadmaps for Dutch system integrators.
United States
Pharmaceutical sterilization loads in FDA-regulated manufacturing are concentrating demand for electric steam boilers that eliminate EPA Title V permitting complexity. The Inflation Reduction Act's commercial building electrification tax credits reduce effective installed costs in multi-family housing projects. Boston and Seattle metropolitan areas are specifying medium-capacity modular systems for institutional retrofits.
Sweden
Pressure-vessel fabrication for high-capacity systems clusters in specialized foundries around Stockholm and Gothenburg, creating procurement bottlenecks for North American project developers. National building codes integrate heat-pump compatibility requirements that expand electric boiler deployment in hybrid district heating networks. Nordic supply concentration is forcing manufacturers to extend lead times for ultra-high-capacity electrode systems.
North America and Europe Electric Boilers Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated European specialists sustaining margin advantages through captive component supply while North American assembly-focused competitors compete on standardized platform pricing. The vendor base fragments across three strategic tiers: premium integrated systems providers, mid-scale modular fabricators, and regional installation specialists. Dominant competitive moves include backward integration into control electronics and strategic partnerships with district heating operators for long-term service contracts.
Among German-origin integrated specialists, Bosch Thermotechnology and Viessmann Climate Solutions exemplify the premium-tier archetype through upstream control over heat-pump component supply and connected-home platform development. Cleaver-Brooks occupies a position within the heavy-gauge pressure-vessel fabrication segment that few rivals replicate at scale for industrial process heat applications.
| Leading Market Players |
|---|
| Bosch Thermotechnology |
| Viessmann Climate Solutions |
| Cleaver-Brooks |
| Lochinvar |
| Vaillant Group |
| Ariston Holding |
| Stiebel Eltron |
| Carrier |
| Chromalox |
| Others |
Supply Flow & Price Mechanics
Sixteen-week lead times for Swedish pressure-vessel foundries concentrate pricing power among European integrated specialists while compressing margins for North American assembly-focused competitors dependent on cross-Atlantic sourcing. This supply bottleneck amplifies cost pass-through to institutional buyers in district heating and pharmaceutical sterilization segments.
Pricing Analysis
After-sales service contracts and spare-parts revenue now exceed hardware margins over a ten-year ownership cycle for medium-capacity commercial installations. Three-tier pricing structure across premium integrated systems, standard modular platforms, and economy compact units separates German-origin specialists with captive control-system supply from North American fabricators competing on upfront capital cost. Pricing pressure stems from copper and silicon steel volatility eroding manufacturer margins on resistive heating elements. Polish residential buyers exhibit sharpest price sensitivity amid coal heating bans, while Dutch municipal operators prioritize lifecycle performance over capital outlay.
Supply Chain Analysis
Sweden and Finland anchor high-capacity pressure-vessel fabrication for electrode steam systems above 1MW, with Germany supplying control electronics and connected-home platforms. Raw material dependencies center on copper for resistive elements, silicon steel for transformer cores, and nickel alloys for corrosion-resistant vessels. Single-source vulnerability concentrates in Nordic foundries serving North American project developers. Distribution runs through authorized system integrators in the Netherlands and Germany, direct OEM sales for institutional projects, and wholesale channels for residential retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-term service contracts and demand-response platform subscriptions are expanding faster than hardware sales as Dutch and German grid operators monetize thermal storage flexibility. This recurring-revenue layer now commands higher valuation multiples than equipment manufacturing.
For Market Incumbents: Compound defensive positioning through backward integration into control electronics and captive heat-pump component supply to sustain margin leadership against North American price competition. Prioritize certification investment under impending EU AI Act requirements for connected heating controls. Extend capacity buffers in Swedish pressure-vessel partnerships to insulate against procurement bottlenecks threatening project timelines. For New Entrants and Emerging Players: Anchor in Polish residential retrofits where district heating infrastructure remains underdeveloped and coal heating bans create immediate replacement demand faster than heat-pump deployment. Target Silesia and Malopolska regions with compact electric water boilers positioned as faster-install alternatives to refrigerant-based systems. Pursue third-party maintenance certification to participate in unbundled service contracts that French housing associations now favor. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EU Green Deal enforcement timelines and F-Gas Regulation phase-downs create irreversible replacement demand across member states. Target acquisition profiles should emphasize integrated specialists with in-house control-system development and established district heating operator relationships. Watch electrode boiler technician training program scaling in France and Germany as inflection indicator for ultra-high-capacity segment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Control Electronics | Captive supply of connected-home platforms secures margin pools under EU AI Act compliance requirements. |
| Electrode Steam Technology Licensing | Superior ramp rates enable participation in German and Dutch intraday power markets through rapid load modulation. |
| Polish Distribution Channel Expansion | Coal heating bans in Silesia and Malopolska create immediate retrofit demand with limited heat-pump competition. |
| Demand-Response Platform Partnership | Grid-balancing revenue streams in Amsterdam and Rotterdam municipal networks diversify beyond hardware sales. |
| Third-Party Maintenance Certification | Unbundled service contracts in French multi-family housing require transparent component pricing and independent support. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and district heating operators across Germany, France, the Netherlands, and the United States; and secondary validation through customs and trade data, SEC filings, Ecodesign Directive compliance databases, and national building code registries. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product architecture, power rating tier, end-use application, and installation type alongside regional regulatory cluster variations. CAGRs were derived from fitted growth curves incorporating electrification mandate enforcement timelines, subsidy program renewal patterns, and heat-pump substitution elasticity in residential retrofits. Forecast inputs included copper price volatility indices and Nordic foundry capacity utilization rates.
Material uncertainties — copper and silicon steel commodity swings, CE marking timeline compression under Ecodesign updates, and technician training program scaling for high-voltage electrode systems — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and district heating capital allocation priorities. Recalibration cycles align with material shifts in EU Green Deal implementation pace and national building code revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Boiler System Market
Boilers
Industrial and Residential Heating Market
Boilers
Superheater Tubes Market
Boilers
Europe Residential Boiler Market
Boilers
Boiler Combustion Chamber Market
Boilers
Utility Boiler Market
Boilers
Asia-Pacific Power Plant Boiler Market
Boilers
Germany Combined Heat and Power Market
Boilers
Superheater Market
Boilers
Gas Fired Boilers Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
Coal-Saving Combustion-Supporting Agent Market
Boilers
Steam Boiler Market
Boilers
Watertube Boilers Market
Boilers
Boiler Control Market
Boilers
Marine Boiler Burner Market