
 Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market | 2026-2036
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market Foresight
Automotive interior assembly is consolidating as the dominant demand vertical for polyurethane hot-melt adhesives across the Middle-East and Africa, displacing traditional solvent-based bonding in dashboard lamination and seat fabrication. Henkel AG & Co. KGaA leverages its regional technical service network to anchor OEM supply relationships in Morocco and South Africa. BASF SE competes through localized production of moisture-cure reactive hot-melt grades tailored to high-temperature desert operating conditions. Huntsman International LLC specializes in rapid-setting formulations that sustain throughput rates in automated furniture and footwear assembly lines serving export markets.
Middle-East and Africa polyurethane hot-melt adhesives are thermoplastic or reactive polyurethane systems applied in molten state that solidify upon cooling or moisture exposure to form durable elastomeric bonds, with typical open times of 30-120 seconds and tensile shear strengths exceeding 8 MPa on polar substrates. Their primary commercial purpose centers on replacing mechanical fasteners and solvent cements in manufacturing environments where VOC emissions face tightening constraints. Single component reactive systems dominate current volume flows due to simpler dispensing infrastructure and lower capital requirements for mid-scale converters. Multi-component formulations represent the fastest-growing product category as Egyptian and Turkish manufacturers invest in precision metering equipment for construction panel and insulated glass applications. The flexural formulation segment occupies the deepest margin pool, commanding premium positioning in automotive structural bonding where crash-performance certification creates qualification barriers for commodity suppliers.
Saudi Arabia's Saudi Standards, Metrology and Quality Organization and South Africa's National Regulator for Compulsory Specifications shape product compliance pathways, with both jurisdictions tightening VOC emission thresholds for interior-grade adhesives used in enclosed spaces. Egypt's Ministry of Trade and Industry enforces import inspection protocols that favor suppliers with ISO 9001 and ISO 14001 certification, effectively filtering market access for European and Asian producers. Stakeholders must monitor divergence between Gulf harmonization initiatives and national standards regimes, as regulatory fragmentation threatens to complicate pan-regional distribution strategies and formulation portfolio rationalization.
Market Dynamics
Saudi Arabia's SABIC-aligned industrial localization mandates and Egypt's updated building codes for green construction materials are forcing specification shifts toward low-VOC polyurethane hot-melt formulations across manufacturing and construction value chains.
Growth Catalysts
- Automotive Interior Bonding:Dashboard lamination and seat fabrication in Morocco and South Africa are displacing solvent-based adhesives as OEMs pursue enclosed-cabin air quality targets.
- SASO VOC Thresholds:Saudi Standards, Metrology and Quality Organization mandates for interior-grade adhesives are accelerating reactive hot-melt qualification in enclosed-space applications.
- Modular Housing Mega-Projects:Gulf Cooperation Council transportation infrastructure and prefabricated construction pipelines are reshaping procurement patterns for structural adhesive systems.
Market Restraints
- Isocyanate Input Volatility:MDI and polyol feedstock prices fluctuate with crude oil benchmarks, compressing converter margins in Egypt and Turkey.
- European Supplier Concentration:Specialty-grade resin supply concentrates among German and Belgian producers, exposing African converters to currency and logistics risk.
- Moisture-Cure Limitations:Desert aridity in Saudi Arabia and UAE extends cure cycles for reactive systems, constraining throughput in high-speed automated lines.
Strategic Opportunities
- Turkish Precision Metering Adoption:Egyptian and Turkish manufacturers investing in multi-component dispensing equipment for construction panel bonding represent untapped equipment-adjacent revenue.
- SFDA Medical Device Pathway:Saudi Food and Drug Authority regulations for wearable device assembly create qualification demand for skin-contact-grade reactive hot-melts.
- Digital Distribution Platforms:B2B procurement portals are disintermediating traditional distributor networks in South Africa's furniture manufacturing corridor.
Industry Challenges
- Formulation Chemist Scarcity:Reactive polyurethane R&D expertise concentrates in European and Asian technical centers, constraining Middle-East and Africa product development.
- Crash-Performance Certification Timelines:Automotive structural bonding approvals require 18-24 month validation cycles, locking out commodity suppliers from premium positioning.
- Legacy Solvent System Integration:Converters maintaining hybrid adhesive inventories face workflow complexity and cross-contamination risk during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market |
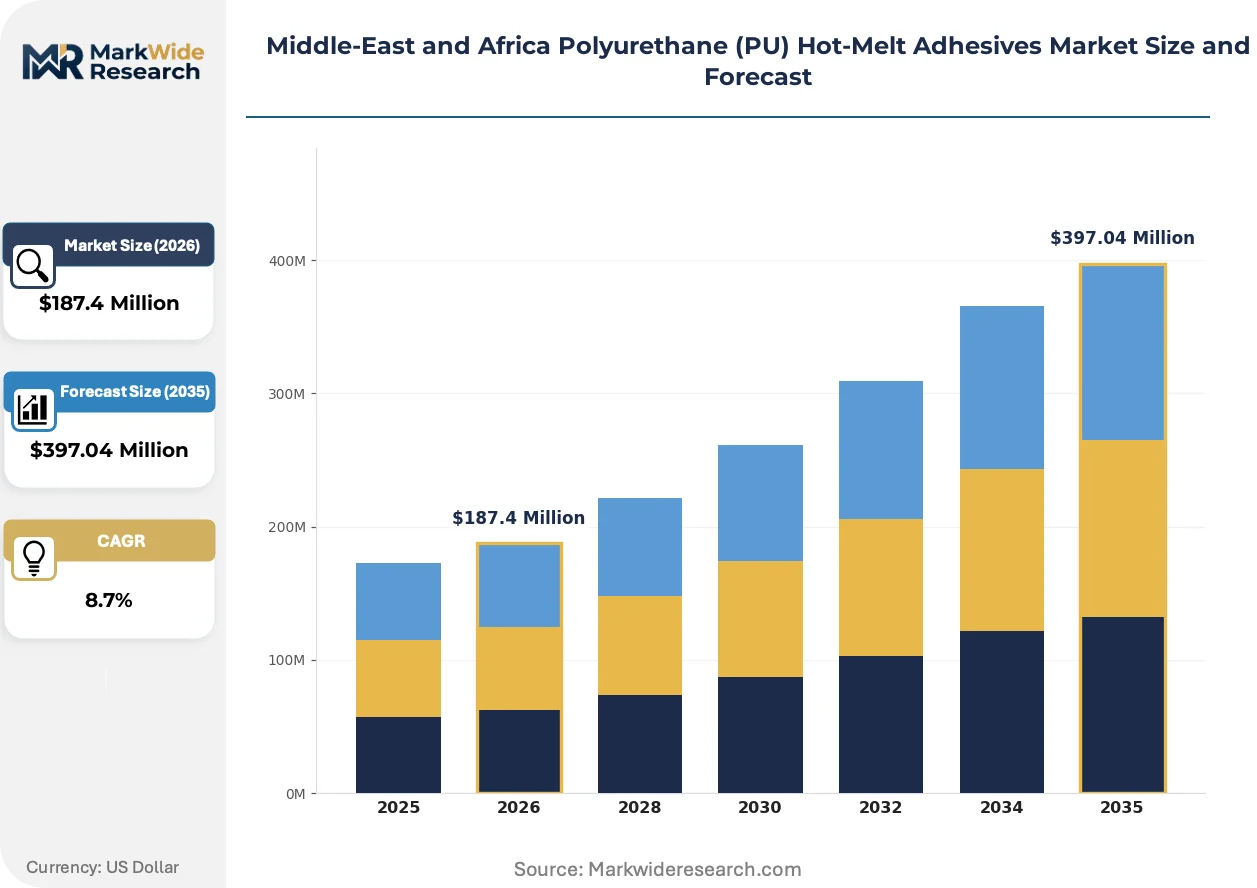
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Component, Multi-Component, Solvent-Based, Water-Based End User Industry: Automotive, Packaging, Woodworking, Textile Application: Furniture Assembly, Footwear Production, Electronics Assembly, Construction Formulation: Flexural, Rigid, Semi-Rigid, Elastomeric |
| Companies Covered | Arkema Group, H.B. Fuller Company, Henkel AG & Co. KGaA, Sika AG, Jowat SE, 3M, BASF SE, Huntsman International LLC, Pidilite Industries Ltd, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market Shifts & Advancements
Moisture-cure reactive technology, regulatory tightening on enclosed-space emissions, and procurement digitization are rewriting competitive positioning across the Middle-East and Africa polyurethane hot-melt adhesives landscape.
Hybrid polyurethane-polyolefin reactive hot-melt formulations is rewriting bonding performance benchmarks for high-temperature desert operating conditions. Saudi Arabian automotive tier-1 suppliers are adopting these grades at accelerated qualification pace. The technology is compressing open-time windows while maintaining tensile shear strength above 8 MPa, enabling faster automated assembly without climate-controlled environments.
Egypt's Ministry of Trade and Industry import inspection protocols now enforce ISO 9001 and ISO 14001 documentation as mandatory market access filters. European and Asian producers without certified quality management systems face effective exclusion from Egyptian procurement channels. Construction panel manufacturers in Cairo and Alexandria are consolidating supplier relationships around pre-qualified certification holders to avoid customs delays.
Consolidated buying consortia among UAE modular housing developers are displacing fragmented project-by-project adhesive sourcing. Tier-1 contractors now negotiate master supply agreements covering multi-year mega-project pipelines. This concentration is most visible in Dubai and Riyadh, where procurement teams are unbundling technical service from material supply to drive unit cost compression.
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market Segmentation
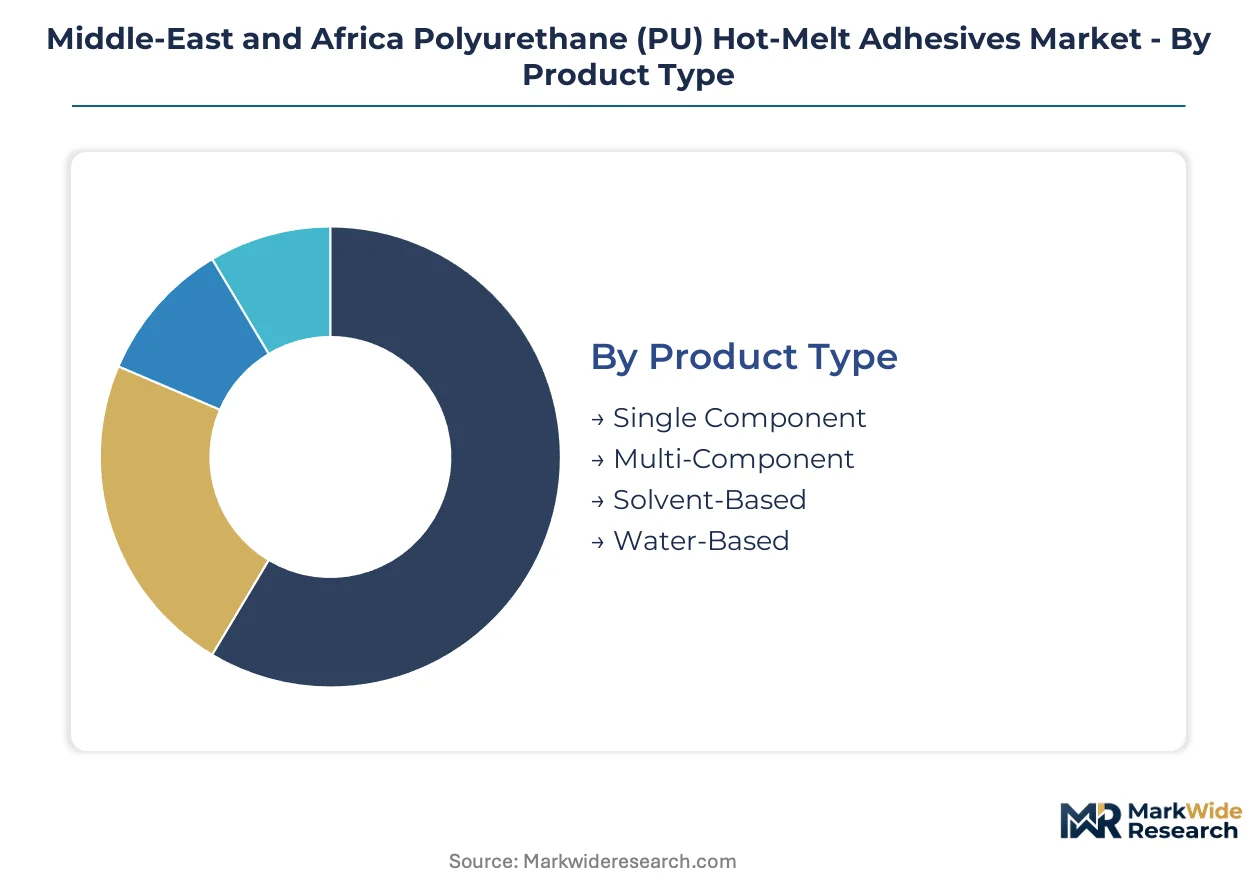
Polyurethane hot-melt adhesive purchasing in the Middle-East and Africa fragments across four distinct category axes. Product type and formulation chemistry determine capital equipment requirements and per-unit economics, while end-use industry and application dictate performance specifications and regulatory compliance burdens.
Product Type:
Single component systems dominate current volume flows due to lower dispensing infrastructure costs, while multi-component formulations capture expanding share among precision manufacturers.
- Single Component:Thermoplastic or moisture-cure reactive systems requiring only heating and dispensing equipment dominate mid-scale converter operations across Egypt and Turkey. Saudi Arabian furniture manufacturers favor these grades for simplified workflow integration and reduced technical training requirements.
- Multi-Component:Meter-mixed reactive systems combining isocyanate and polyol streams at point of application deliver superior bond durability for structural applications. Egyptian construction panel producers and Turkish insulated glass manufacturers are investing in precision dispensing equipment to access these higher-performance grades.
- Solvent-Based:Legacy formulations declining amid VOC regulatory pressure but maintaining residual presence in price-sensitive woodworking segments.
- Water-Based:Emerging alternative for textile lamination applications where moisture-cure chemistry faces humidity variability constraints.
Today's leader: Single Component. Tomorrow's challenger: Multi-Component.
End User Industry:
Automotive specification requirements pull the most demanding technical performance, while packaging volume offers scale economies for regional producers.
- Automotive:Dashboard lamination, seat fabrication, and interior trim bonding in Morocco and South Africa require crash-performance certification and enclosed-cabin air quality compliance. OEMs are consolidating supplier relationships around reactive hot-melt specialists with localized technical service networks.
- Packaging:High-speed case and carton sealing operations across Gulf Cooperation Council logistics hubs demand rapid-setting formulations with consistent open times. Volume concentration in UAE and Saudi Arabian distribution centers supports dedicated production lines.
- Woodworking:Edge banding and veneer applications in South African furniture manufacturing corridors favor cost-optimized thermoplastic grades.
- Textile:Sportswear and automotive upholstery lamination in Turkish export zones drives demand for soft-hand elastomeric formulations.
Automotive commands premium positioning. Packaging delivers volume scale.
Application:
Construction and electronics assembly applications are climbing the fastest as modular housing mega-projects and wearable device manufacturing expand regional demand.
- Furniture Assembly:Edge banding, frame construction, and decorative lamination across South African and Egyptian manufacturing corridors. Thermoplastic grades dominate for cost-sensitive residential furniture, while reactive systems penetrate high-end export-oriented production.
- Footwear Production:Upper-to-sole bonding and insole lamination in Moroccan and Ethiopian export zones require rapid-setting formulations sustaining automated line speeds. Moisture-cure limitations in desert climates constrain reactive system adoption.
- Electronics Assembly:Wearable device and consumer electronics bonding for Saudi Arabian and UAE assembly operations. SFDA skin-contact regulations create qualification barriers favoring certified reactive hot-melt suppliers.
- Construction:Structural panel bonding, insulated glass edge sealing, and flooring installation across Gulf mega-project pipelines. Multi-component systems gain share as Egyptian and Turkish contractors invest in precision metering infrastructure.
Construction applications are expanding most quickly. Furniture maintains volume foundation.
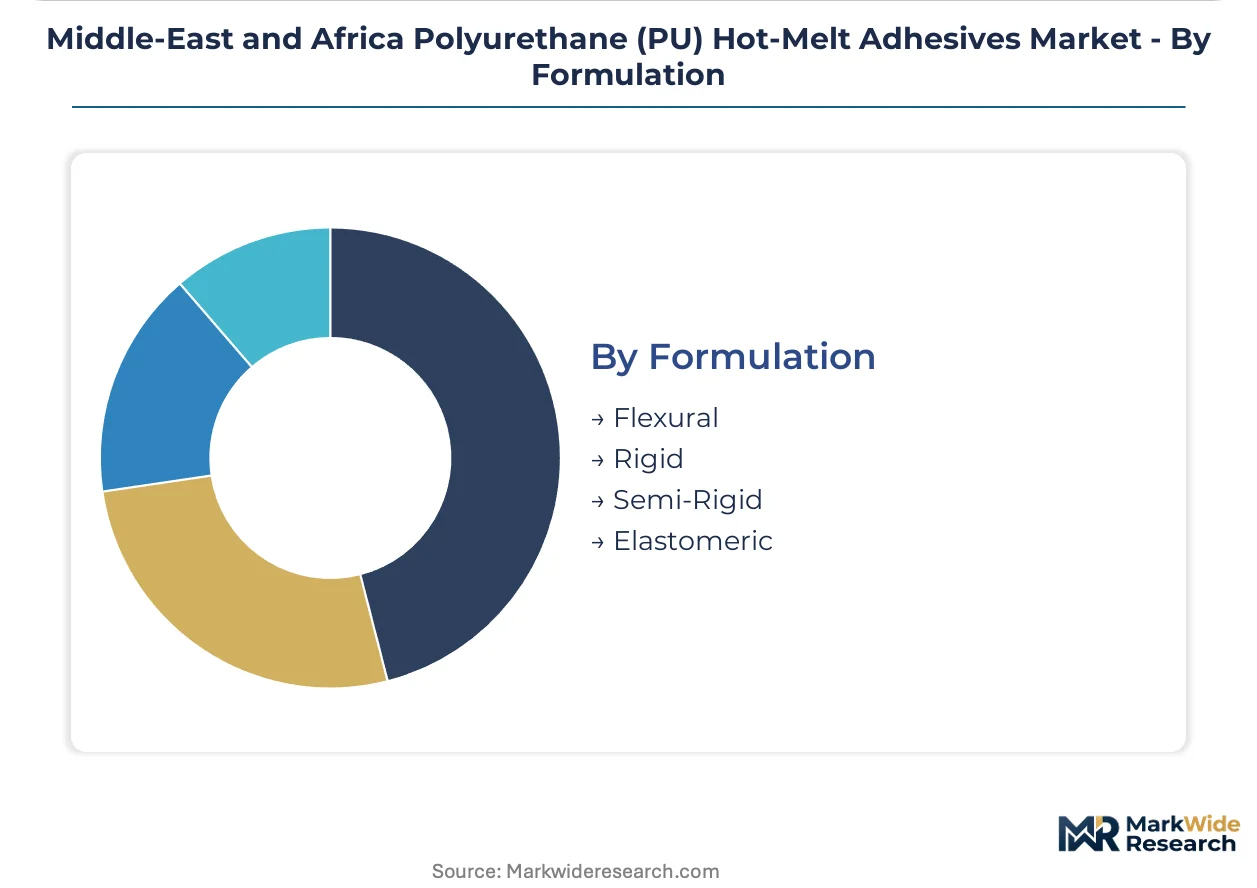
Formulation:
Flexural grades occupy the deepest margin pool through automotive structural bonding certification barriers, while rigid formulations serve cost-optimized construction segments.
- Flexural:High-modulus elastomeric systems engineered for energy absorption and crash-performance compliance. Saudi Arabian and South African automotive tier-1 suppliers pay substantial premiums for qualified grades with 18-24 month validation timelines.
- Rigid:High-crosslink density formulations for structural load-bearing applications in construction panel and insulated glass assembly. Egyptian manufacturers favor these grades for dimensional stability in high-temperature operating environments.
- Semi-Rigid:Intermediate modulus systems balancing flexibility and strength for furniture and packaging applications.
- Elastomeric:Soft, low-modulus formulations for textile lamination and flexible electronics bonding where substrate conformability is critical.
Flexural formulations capture premium positioning. Elastomeric grades gain share in wearable device assembly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting polyurethane hot-melt adhesive procurement toward Gulf Cooperation Council jurisdictions where VOC compliance costs remain below European benchmarks. Manufacturers are relocating formulation facilities to exploit this cost-of-compliance gap while maintaining access to mega-project demand pipelines.
Saudi Arabia
Automotive interior bonding and modular housing construction are absorbing reactive hot-melt volumes at accelerated pace. SASO mandates for interior-grade adhesives in enclosed spaces are disqualifying legacy solvent-based suppliers from state-backed procurement channels. Riyadh-based tier-1 automotive suppliers are consolidating master service agreements around qualified reactive system providers.
United Arab Emirates
Packaging logistics hubs in Dubai and Abu Dhabi are driving rapid-setting formulation demand for high-speed case sealing operations. MOHAP pharmaceutical packaging regulations are creating qualification pathways for medical-grade adhesive suppliers. Consolidated buying consortia among modular housing developers are displacing fragmented project-by-project sourcing in the Northern Emirates corridor.
Egypt
Construction panel manufacturing in Cairo and Alexandria is pivoting toward multi-component polyurethane systems for structural bonding applications. The Ministry of Trade and Industry's ISO 9001 and ISO 14001 documentation requirements are filtering market access for uncertified European and Asian producers. Green building code updates are accelerating specification shifts toward low-VOC formulations in public infrastructure tenders.
South Africa
Furniture manufacturing corridors in Gauteng and Western Cape are sustaining thermoplastic grade consumption for edge-banding and veneer applications. The National Regulator for Compulsory Specifications is tightening VOC emission thresholds for interior-grade adhesives used in enclosed spaces. Automotive seat fabrication plants in Eastern Cape are qualifying reactive hot-melt suppliers for export-oriented OEM contracts.
Turkey
Insulated glass and construction panel producers in Istanbul and Izmir are investing in precision metering equipment for multi-component reactive systems. Turkish manufacturers are capturing equipment-adjacent revenue streams as Egyptian contractors source dispensing infrastructure through cross-border supply relationships. Textile lamination operations in Bursa export zones are driving soft-hand elastomeric formulation demand.
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation ownership concentrating among European-headquartered resin suppliers while regional converters handle toll manufacturing. The vendor base organizes into three tiers: global adhesive houses with localized technical service networks, regional distributors holding inventory positions in Gulf logistics hubs, and specialty chemical producers supplying certified grades for automotive and medical applications. Competitive moves center on strategic partnerships with mega-project contractors and backward integration into isocyanate feedstock sourcing.
Within the global adhesive house tier, Henkel AG & Co. KGaA and H.B. Fuller Company exemplify archetypes anchored by regional technical service infrastructure. BASF SE represents the specialty chemical producer model with localized moisture-cure reactive production. Arkema Group occupies a position bridging formulation ownership and distribution reach across North African markets.
| Leading Market Players |
|---|
| Arkema Group |
| H.B. Fuller Company |
| Henkel AG & Co. KGaA |
| Sika AG |
| Jowat SE |
| 3M |
| BASF SE |
| Huntsman International LLC |
| Pidilite Industries Ltd |
| Others |
Supply & Pricing Matrix
Moisture-cure reactive technology adoption in Saudi Arabian automotive plants simultaneously compresses per-unit adhesive costs and concentrates procurement leverage among qualified suppliers holding SASO certification. This production-method transition rewards converters with ISO 14001 documentation while squeezing uncertified competitors from state-backed mega-project channels.
Pricing Analysis
Distributor margin layers in Gulf Cooperation Council corridors stratify pricing across three performance tiers. Certification-grade reactive systems command premium positioning against commodity thermoplastic grades, with price differentiation driven by crash-performance validation timelines and ISO 14001 compliance documentation. Cost compression in standard-grade segments intensifies as Turkish manufacturers scale multi-component dispensing capacity. Small-scale Egyptian furniture converters exhibit highest price sensitivity, while Saudi Arabian tier-1 automotive suppliers prioritize technical service bundling over unit cost.
Supply Chain Analysis
Saudi Arabia's SABIC-aligned domestic-content mandates are redirecting raw material sourcing toward localized isocyanate and polyol production. Supply concentration rests on Germany, Belgium, and Saudi Arabia for specialty-grade resin inputs. MDI feedstock volatility and European supplier concentration expose African converters to currency and logistics risk. Distribution runs through Dubai and Jebel Ali logistics hubs serving pan-regional converter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through premium-tier qualification barriers and equipment-adjacent revenue capture in precision metering adoption.
For Market Incumbents: Anticipate consolidation pressure from hybrid polyurethane-polyolefin formulations displacing legacy reactive grades in desert climate applications. Defensive positioning requires backward integration into isocyanate feedstock sourcing and expanded technical service networks in Moroccan automotive corridors. SASO VOC threshold tightening threatens commodity suppliers lacking certification infrastructure. For New Entrants and Emerging Players: Rapid-setting formulation technology for high-speed automated footwear lines in Ethiopian export zones offers penetrable white-space entry. Egyptian construction panel manufacturers investing in multi-component equipment represent underserved equipment-adjacent demand. Go-to-market execution should anchor on cross-border Turkish dispensing infrastructure partnerships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors holding ISO 9001 certification but lacking reactive formulation R&D capabilities. Long-term viability over the mid-decade window favors acquisition targets with captive supply relationships to SABIC-aligned feedstock producers. The signal to monitor is Saudi Arabian modular housing procurement consolidation into master service agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Feedstock | Captive MDI supply secures margin stability against crude-linked volatility in Egyptian and Turkish markets. |
| SASO Certification Investment | Qualification for interior-grade adhesive supply unlocks state-backed automotive and housing procurement channels. |
| Precision Metering Equipment Partnership | Equipment-adjacent revenue capture in Egyptian construction panel manufacturing deepens customer switching costs. |
| Hybrid Formulation R&D Program | Polyurethane-polyolefin reactive grades address moisture-cure limitations in Saudi Arabian desert operating conditions. |
| Cross-Border Technical Service Expansion | Localized support networks in Morocco and South Africa anchor OEM supplier consolidation trends. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with adhesive plant managers, procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors with secondary validation against customs and trade data, SEC filings of listed chemical producers, and SABIC industrial localization disclosures. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Segment-weighting approaches modeled product type, formulation chemistry, end-use industry, and application dimensions across the analysis window. CAGRs derived from historical trajectory analysis and demand elasticity modeling against automotive production forecasts, modular housing pipeline disclosures, and VOC regulatory implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to isocyanate feedstock volatility, regulatory harmonization divergence between Gulf and national standards regimes, and moisture-cure technology adoption rates in desert climate applications. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Stone and Tile Adhesives and Sealants Market
Adhesives & Sealants
Glass Adhesive Market
Adhesives & Sealants
Malaysia Adhesives and Sealants Market
Adhesives & Sealants
United States Construction Adhesives and Sealants Market
Adhesives & Sealants
North America Automotive Adhesives and Sealants Market
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Global Non-Woven Adhesives Market
Adhesives & Sealants
North America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Middle-East and Africa Acrylic Adhesives Market
Adhesives & Sealants
Wearable Adhesives Market
Adhesives & Sealants
Elastomeric Adhesive Market
Adhesives & Sealants
Construction Repair and Rehabilitation Chemicals Market
Adhesives & Sealants
Global Bioadhesive Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market
Adhesives & Sealants
Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Structural Sealants Market