
 Global Hybrid Adhesives and Sealants Market | 2026-2036
Global Hybrid Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hybrid Adhesives and Sealants Market Foresight
Automotive OEMs is rotating demand away from conventional mechanical fasteners toward hybrid bonding systems in electric vehicle platforms. Henkel AG & Co. KGaA leverages its R&D intensity in silane-modified polymer platforms to capture platform engineering contracts. Sika AG anchors its position through geographic dominance in European automotive assembly plants. Dow competes on manufacturing scale, supplying two-component hybrid systems to industrial equipment builders across multiple continents.
Hybrid adhesives and sealants combine organic polymer backbones with inorganic silane crosslinkers to deliver elastic bonding with primerless adhesion to metals, plastics, and composites, typically curing through ambient moisture or UV exposure to form durable thermoset networks. Their primary purpose is to replace mechanical fastening and traditional sealants in assemblies requiring simultaneous structural strength, environmental sealing, and vibration damping. Silane Modified Polymers lead product type demand due to their balance of elasticity and paintability in automotive and construction applications, while UV Cure technology represents the fastest-growing segment as electronics assembly lines demand rapid, energy-efficient processing without thermal damage to sensitive components. Epoxy Hybrids command premium margins in aerospace supplier applications where outgassing control and thermal cycling resistance are non-negotiable.
REACH registration requirements in Europe, EPA VOC regulations in the United States, and China's GB standards for construction adhesives collectively restrict solvent-containing formulations and mandate disclosure of hazardous substance content. These frameworks push manufacturers toward solvent-free and moisture-cure platforms while creating compliance barriers for smaller regional suppliers. Stakeholders must monitor evolving chemical hazard classifications across ECHA, EPA, and SAMR jurisdictions to anticipate reformulation costs and certification timelines that will determine competitive access in high-growth end-use sectors.
Market Dynamics
Automotive OEMs are consolidating bonding operations around silane-modified polymer platforms that eliminate primer steps and reduce assembly line footprint, compressing traditional mechanical fastening supply chains into single-source adhesive contracts.
Growth Catalysts
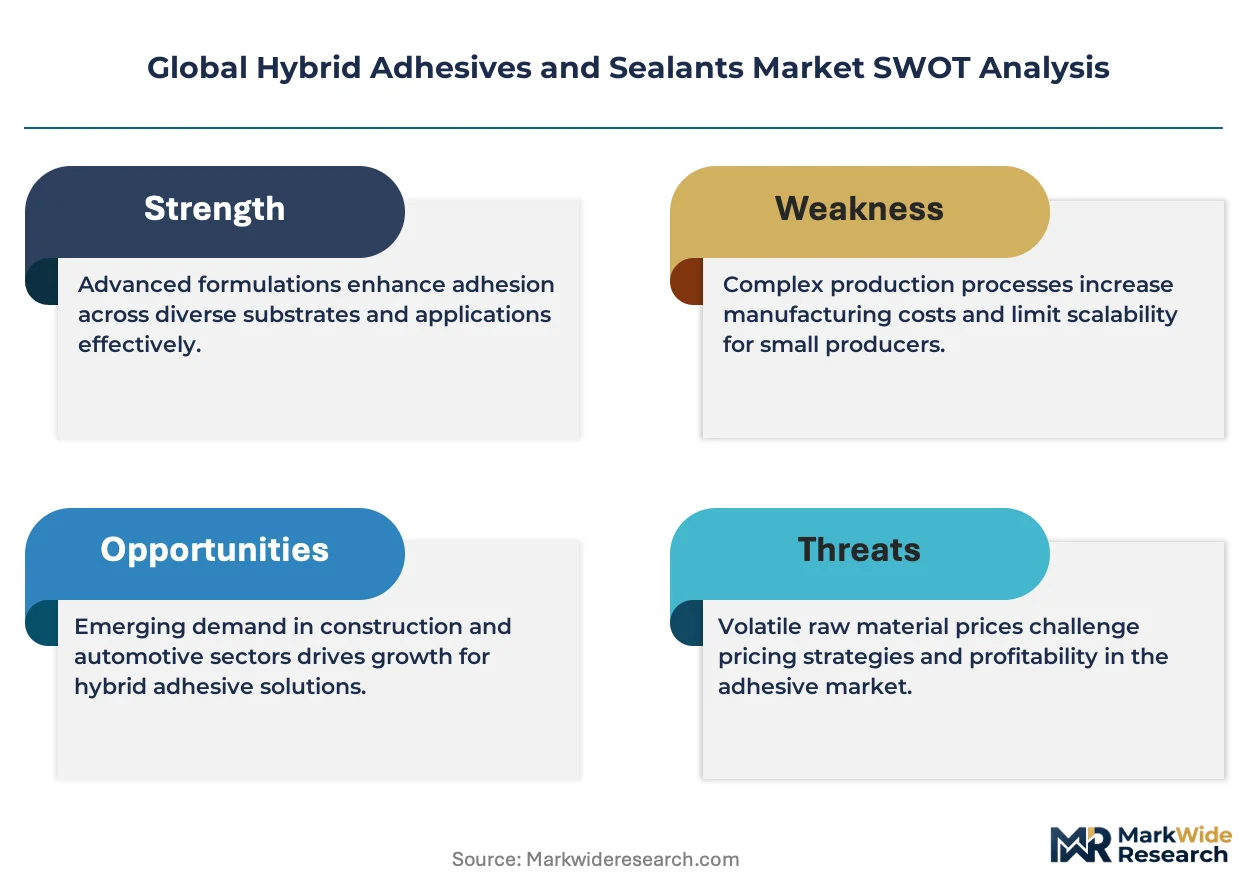
- EU Green Deal compliance mandates:REACH restrictions on solvent-based formulations push formulators toward moisture-cure hybrid systems in German and French automotive plants.
- Electric vehicle platform engineering:Battery enclosure sealing requirements drive specification of epoxy-polyurethane hybrids for thermal runaway protection in Chinese and US assembly facilities.
- Wind turbine blade manufacturing:Offshore wind installations in Denmark and the United Kingdom specify UV-cure hybrid sealants for rapid field repairs and reduced cure-cycle downtime.
Market Restraints
- Petrochemical feedstock volatility:Silane crosslinker prices fluctuate with natural gas derivatives, compressing margins for moisture-cure platform producers.
- Specialized equipment concentration:High-shear mixing and precision dispensing systems for two-component hybrids concentrate among German and Japanese machinery suppliers, creating procurement bottlenecks.
- Epoxy hybrid processing limitations:Rigid pot-life constraints restrict use in high-throughput automated lines, confining these materials to low-volume aerospace and medical device applications.
Strategic Opportunities
- Indian construction adhesives penetration:BIS certification alignment with GB standards opens pathways for hybrid sealant adoption in Mumbai and Delhi green building projects.
- Medical device miniaturization:UV-cure hybrid platforms enable catheter and wearable sensor assembly without thermal damage to electronics.
- Brazilian bio-based feedstock integration:ANVISA pathways for renewable polyol certification create first-mover positioning for sugarcane-derived hybrid formulations.
Industry Challenges
- Formulation chemist scarcity:Silane chemistry expertise concentrates among aging specialists in European and Japanese R&D centers, constraining new product development velocity.
- Multi-jurisdiction certification lag:Simultaneous EPA VOC, REACH SVHC, and SAMR GB standard approvals extend time-to-market by 18-24 months for novel hybrid platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hybrid Adhesives and Sealants Market |
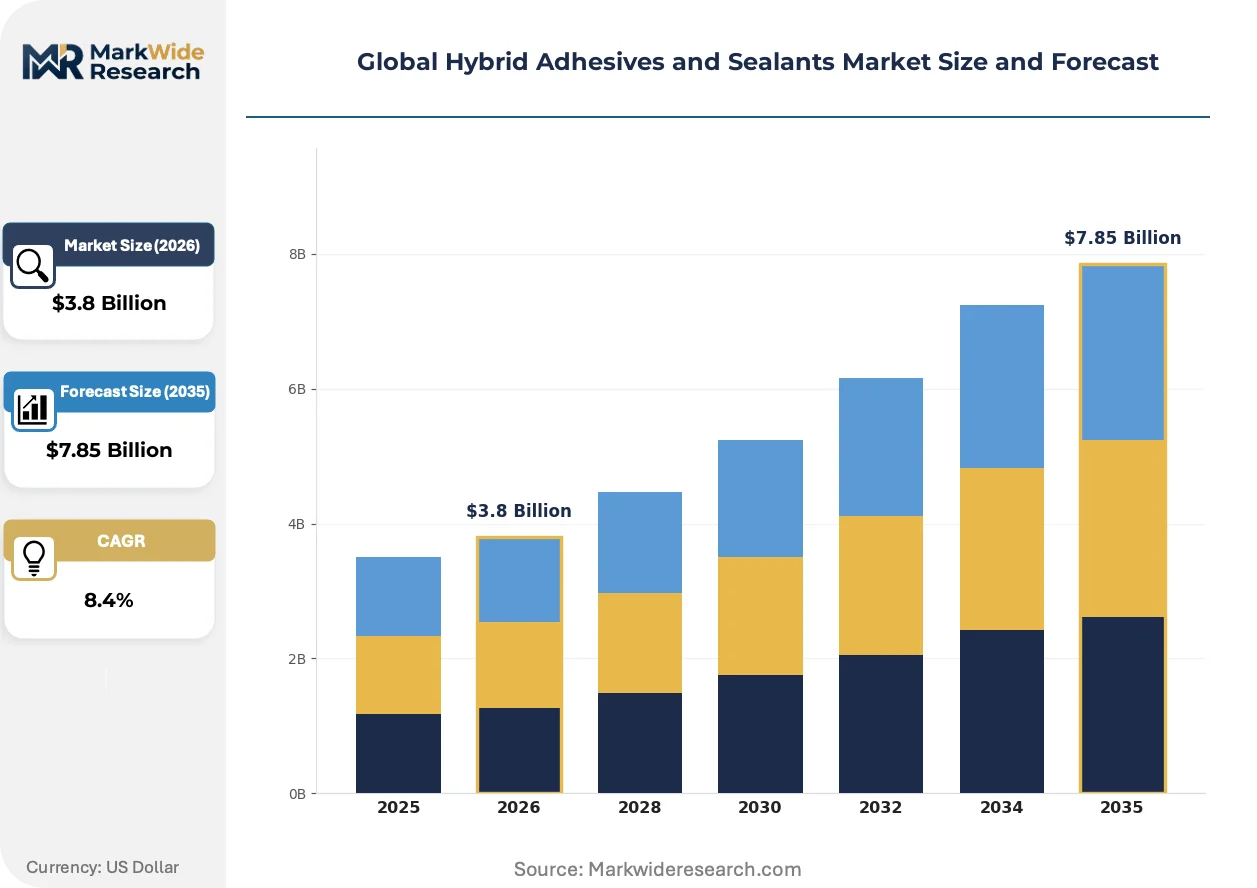
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
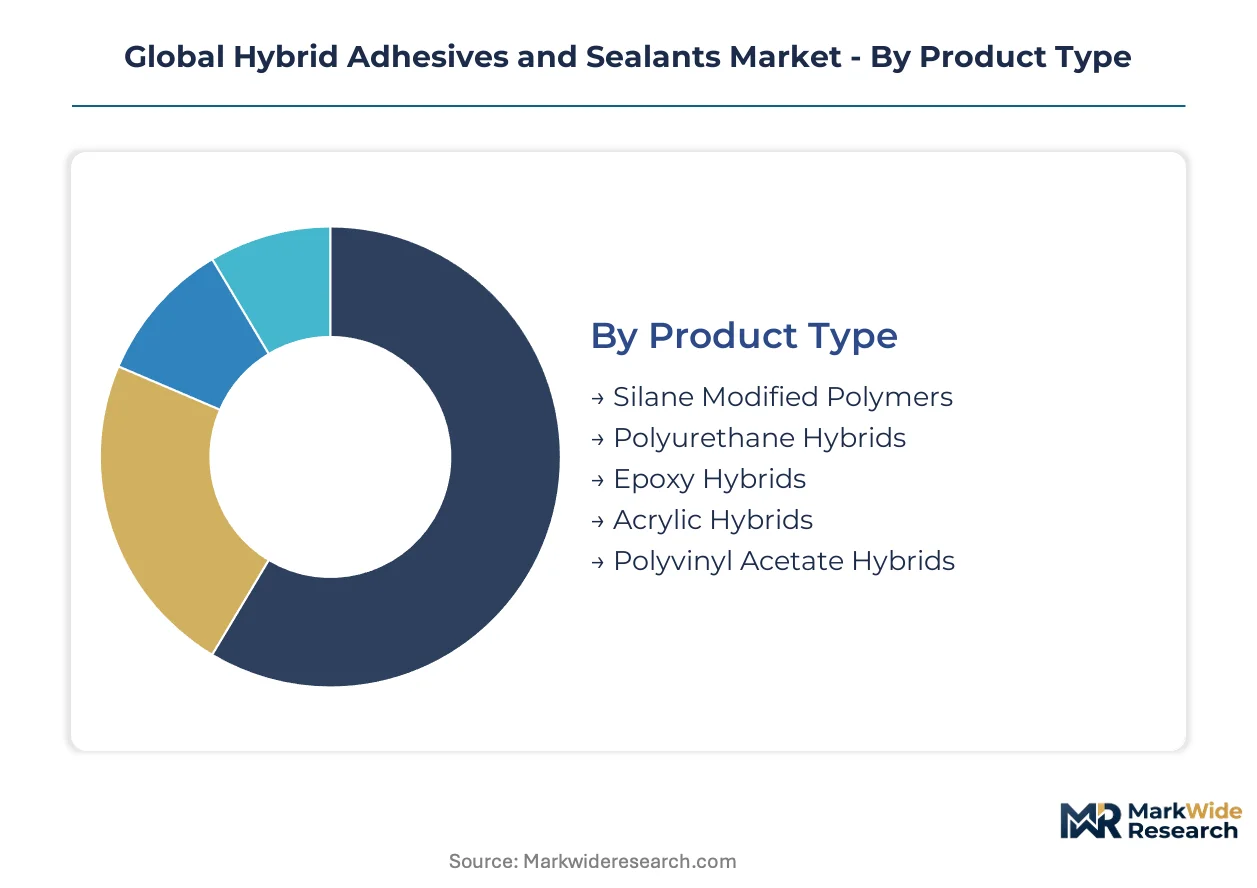
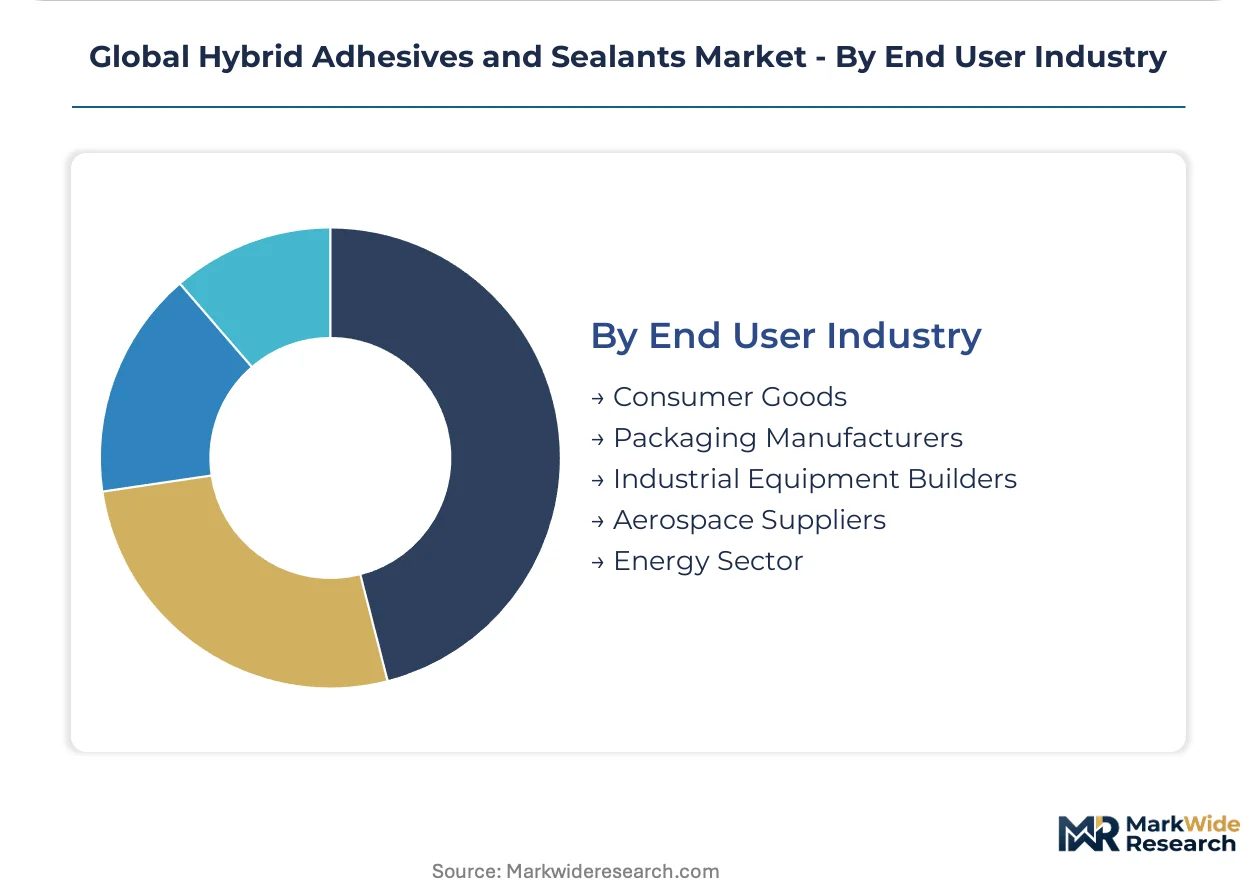
| Segmentation | Product Type: Silane Modified Polymers, Polyurethane Hybrids, Epoxy Hybrids, Acrylic Hybrids, Polyvinyl Acetate Hybrids Technology: Moisture Cure, Two-Component, Solvent-Free, UV Cure, Hot Melt Application: Building & Construction, Electronics Assembly, Footwear Manufacturing, Woodworking, Marine Assembly End User Industry: Consumer Goods, Packaging Manufacturers, Industrial Equipment Builders, Aerospace Suppliers, Energy Sector |
| Companies Covered | Henkel AG & Co. KGaA, Sika AG, 3M, H.B. Fuller, Bostik, Wacker Chemie AG, Dow, Arkema, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hybrid Adhesives and Sealants Market Shifts & Advancements
Formulation science is converging with processing automation to redefine how hybrid adhesives are specified, purchased, and deployed across industrial assembly environments.
Silane-terminated polyurethane technology is supplanting conventional silyl-modified polyether systems in automotive glazing and body-in-white applications. German and Chinese OEMs now specify these materials for 90-second handling strength in robotic dispensing cells. The shift is compressing supplier qualification timelines and eliminating secondary primer operations from paint shop workflows.
REACH SVHC candidate list expansions are forcing disclosure of residual isocyanate content in polyurethane-containing hybrids. Formulators serving European construction and transportation markets are accelerating aldehyde-free catalyst development and migrating toward blocked isocyanate architectures. German adhesive producers bear the highest compliance burden, with reformulation costs concentrated in flooring and marine sealing product lines.
Specification authority is migrating from plant engineers to centralized corporate procurement functions with sustainability mandates. Tier-one suppliers now bundle adhesive supply with dispensing equipment and VOC reporting documentation, displacing traditional distributor relationships in US and European automotive supply chains. This consolidation is most visible in Detroit and Stuttgart, where platform engineering contracts increasingly specify single-source hybrid platforms with decade-long supply agreements.
Global Hybrid Adhesives and Sealants Market Segmentation
Hybrid adhesives compete against mechanical fasteners, welding, and conventional sealants across every industrial assembly environment. Segment boundaries blur as formulators engineer multi-platform systems that satisfy divergent end-use specifications. Procurement decisions increasingly hinge on regulatory compliance breadth rather than unit cost alone.
Product Type:
Substitution pressure from mechanical fastening varies sharply by backbone chemistry, with elastic systems facing the strongest threat from clip-and-bolt assemblies in high-vibration automotive applications.
- Silane Modified Polymers:These systems combine silyl-terminated backbones with ambient moisture cure mechanisms to deliver primerless adhesion across painted metals and engineering plastics. German automotive OEMs specify these materials for body-in-white bonding to eliminate corrosion-prone weld points and reduce paint shop complexity.
- Epoxy Hybrids:Rigid thermoset networks formed from epoxy-silane or epoxy-urethane combinations provide structural strength with controlled flexibility for thermal cycling resistance. Aerospace suppliers in the United States and France demand these formulations for satellite component bonding where outgassing specifications from ESA and NASA constrain material selection.
- Polyurethane Hybrids:Blocked isocyanate architectures enable one-component packaging with extended shelf stability for construction sealant applications.
- Acrylic Hybrids:UV-accelerated cure platforms serve electronics assembly lines requiring rapid handling strength without thermal damage to sensitive substrates.
- Polyvinyl Acetate Hybrids:Moisture-cure modifications of traditional PVA chemistry penetrate woodworking applications in emerging manufacturing economies.
Silane Modified Polymers retain volume leadership; Epoxy Hybrids hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium two-component systems from commodity moisture-cure platforms, with equipment requirements driving total cost of ownership divergence.
- Moisture Cure:Single-component formulations cure through atmospheric humidity to form elastic thermosets without mixing equipment. Chinese construction adhesive producers dominate this segment through simplified logistics and reduced application training requirements for field installation crews.
- UV Cure:Photoinitiator-activated polymerization delivers sub-second handling strength under LED or mercury arc exposure. Electronics assembly lines in South Korea and Japan specify these systems for smartphone display bonding where thermal cure would damage OLED substrates.
- Two-Component:Meter-mix-dispense systems combine resin and hardener at point of application for controlled cure profiles and superior mechanical properties.
- Solvent-Free:Zero-VOC formulations satisfy REACH and EPA regulations for indoor air quality in European and North American building products.
- Hot Melt:Thermoplastic hybrid formulations enable rapid assembly with reversible thermal processing for rework applications.
Moisture Cure commands the widest installed base; UV Cure is gaining share fastest in precision assembly segments.
Application:
Application concentration tracks manufacturing cluster geography, with specification authority migrating toward centralized procurement functions in multinational OEMs.
- Building & Construction:Structural glazing, flooring installation, and waterproofing membranes consume hybrid sealants for elastic movement accommodation across thermal expansion cycles. German and French green building certification systems specify solvent-free systems for public infrastructure projects.
- Electronics Assembly:Miniaturized device manufacturing demands precise dispensing and rapid cure without thermal damage to populated circuit boards. Chinese and Vietnamese contract manufacturers drive specification of UV-cure platforms for wearable device production.
- Footwear Manufacturing:Outsole bonding and upper assembly utilize moisture-cure hybrids for flexible, water-resistant joints in athletic and safety footwear.
- Woodworking:Panel lamination and furniture assembly employ PVAc hybrids for cost-sensitive applications with moderate durability requirements.
- Marine Assembly:Hull sealing and deck bonding in yacht and commercial vessel construction specify epoxy hybrids for saltwater resistance and structural load bearing.
Building & Construction anchors volume demand; Electronics Assembly shows the most rapid specification growth.
End User Industry:
Customer type differentiation separates specification-driven aerospace procurement from price-sensitive packaging converters, with certification burden concentrating in regulated sectors.
- Industrial Equipment Builders:Agricultural machinery, machine tool, and material handling equipment manufacturers specify hybrid adhesives for cab assembly, panel bonding, and vibration damping. German and Japanese machinery OEMs consolidate adhesive supply through decade-long platform contracts with integrated dispensing system provision.
- Aerospace Suppliers:Tier-one aerostructures and avionics manufacturers demand traceable material certification with lot-specific test data for FAA and EASA compliance. French and United States prime contractors maintain approved supplier lists with 18-24 month qualification timelines for new hybrid platforms.
- Energy Sector:Wind turbine blade manufacturing and solar panel assembly specify UV-cure hybrids for rapid field repair and reduced cure-cycle downtime in Danish and United Kingdom offshore installations.
- Consumer Goods:Appliance and furniture manufacturers prioritize cost-optimized moisture-cure systems for high-volume assembly lines.
- Packaging Manufacturers:Folding carton and flexible packaging converters employ hot-melt hybrids for rapid bonding with food-contact compliance requirements.
Industrial Equipment Builders maintain the largest procurement volumes; Aerospace Suppliers drive the highest margin segment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German adhesive formulators export silane-modified polymer systems to Chinese electric vehicle battery plants, establishing the dominant trade-flow corridor in this market. This bilateral supply relationship channels formulation expertise eastward while Chinese manufacturing scale absorbs premium European chemistry.
United States
EPA VOC regulations under the Clean Air Act push construction adhesive producers toward solvent-free hybrid platforms. Detroit-area automotive OEMs consolidate adhesive procurement through single-source contracts spanning decade-long platform lifecycles. Michigan and Ohio assembly plants now specify moisture-cure hybrids for body-in-white bonding to eliminate corrosion-prone weld points.
Germany
REACH SVHC disclosure mandates force reformulation of polyurethane-containing hybrids across flooring and marine sealing lines. Stuttgart and Wolfsburg automotive clusters drive specification of silane-terminated polyurethane technology for 90-second handling strength in robotic dispensing cells. German machinery OEMs bundle adhesive supply with precision dispensing equipment, displacing traditional distributor channels.
China
SAMR GB standards for construction adhesives restrict solvent-containing formulations in public infrastructure projects. Yangtze River Delta battery manufacturers specify epoxy-polyurethane hybrids for thermal runaway protection in electric vehicle enclosures. Shenzhen and Shanghai electronics assemblers drive UV-cure hybrid adoption for smartphone display bonding without thermal damage to OLED substrates.
Japan
METI energy efficiency guidelines favor rapid-cure adhesive systems that reduce assembly line energy consumption. Nagoya and Tokyo Bay industrial corridors concentrate demand for two-component hybrid systems in precision machinery manufacturing. Japanese R&D centers retain concentrated expertise in silane chemistry, constraining new product development velocity for competitors lacking comparable technical depth.
India
BIS certification alignment with GB standards opens pathways for hybrid sealant adoption in green building projects. Mumbai and Delhi construction markets specify solvent-free systems for public infrastructure certification compliance. Domestic adhesive producers leverage simplified logistics and reduced application training requirements to penetrate cost-sensitive field installation segments.
Global Hybrid Adhesives and Sealants Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with adhesive divisions nested within broader material science portfolios. Tier-one suppliers compete through integrated dispensing system provision rather than chemistry alone. Three archetypes dominate: European automotive specialists, North American industrial scale players, and Asian electronics-focused formulators. Competitive moves concentrate on strategic partnerships with machinery suppliers and geographic expansion through regional formulation facilities.
Among European specialists, Henkel AG & Co. KGaA and Sika AG exemplify the automotive-anchored archetype, occupying positions defined by proximity to German OEM engineering centers and long-term platform contracts. Dow represents the scale-driven North American model, with manufacturing footprint spanning multiple continents to serve industrial equipment builders. These three companies anchor the competitive structure, with their relative positioning shaped by R&D intensity versus manufacturing breadth rather than discrete product differentiation.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Sika AG |
| 3M |
| H.B. Fuller |
| Bostik |
| Wacker Chemie AG |
| Dow |
| Arkema |
| DuPont |
| Others |
Supply & Pricing Matrix
REACH SVHC disclosure mandates gate both supplier qualification timelines and price differentiation across European adhesive markets. Formulators bearing compliance certification costs extract premiums from automotive OEMs while uncertified competitors face exclusion from platform engineering contracts in Stuttgart and Wolfsburg.
Pricing Analysis
Moisture-cure platforms command commodity margins against UV-cure systems priced at premium tiers for electronics assembly. Pricing stratifies across aerospace-grade epoxy hybrids, automotive silane-modified polymers, and construction-grade polyurethane systems based on certification burden and raw material purity. Cost compression in silane crosslinker feedstocks is intensifying because natural gas derivative volatility squeezes moisture-cure platform producers. Packaging manufacturers and woodworking operations show highest price sensitivity; aerospace suppliers and medical device assemblers demonstrate lowest.
Supply Chain Analysis
Strategic stockpiling of silane crosslinkers dominates German and Japanese formulator procurement against just-in-time preferences among Chinese construction adhesive distributors. Manufacturing gravity centers on Germany, China, and the United States for hybrid adhesive production. Formulation draws from petrochemical-derived polyols, silane coupling agents, and epoxy resins as core inputs. Single-source vulnerability concentrates in German and Japanese precision dispensing equipment suppliers. Distribution runs through integrated direct contracts with automotive OEMs rather than traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive positioning as adhesive supply bundles with dispensing equipment and compliance documentation. Interoperability between formulation chemistry and robotic dispensing systems determines supplier selection authority.
For Market Incumbents: Fortify platform engineering relationships through captive dispensing equipment provision and decade-long supply agreements. Invest in backward integration into silane crosslinker production to offset petrochemical feedstock volatility. Consolidate certification documentation services to defend against emerging Asian formulators with lower compliance overhead. For New Entrants and Emerging Players: BIS certification fast-track alignment with Chinese GB standards opens construction adhesive penetration in Mumbai and Delhi green building projects. Target UV-cure hybrid platforms for medical device miniaturization applications where thermal damage constraints exclude incumbent chemistries. Pursue joint development agreements with Shenzhen electronics assemblers lacking qualified domestic adhesive suppliers. For Investors and Strategic Acquirers: REACH SVHC expansion milestones reshape the acquisition landscape toward formulators with blocked isocyanate architectures and aldehyde-free catalyst pipelines. Long-term viability favors specialists with dual EPA and ECHA certification breadth over regional commodity producers. Monitor SAMR GB standard harmonization progress as inflection signal for Chinese market access premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Crosslinkers | Captive supply of natural gas derivatives insulates margins from feedstock volatility in German manufacturing. |
| Blocked Isocyanate Architecture Migration | Aldehyde-free catalyst development satisfies REACH SVHC disclosure mandates for European construction markets. |
| Integrated Dispensing System Provision | Equipment-adhesive bundles displace distributor channels in Detroit and Stuttgart automotive procurement. |
| UV-Cure Platform Expansion | Sub-second cure technology penetrates Shenzhen smartphone display bonding without OLED thermal damage. |
| BIS-GB Certification Harmonization | Standards alignment unlocks Mumbai and Delhi green building project specifications for solvent-free sealants. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade association filings, customs data, and regulatory disclosure databases. Interview program engaged adhesive formulator R&D directors, automotive OEM platform engineers, Tier 1 supplier procurement leads, construction contractor operations managers, and precision dispensing equipment manufacturers. Secondary validation drew from ECHA REACH registrations, EPA VOC compliance filings, SAMR GB standard publications, and chemical industry trade flow data. Bottom-up demand modeling triangulated against top-down production capacity estimates.
Segmentation dimensions modeled span product type chemistry, cure technology mechanism, application end-use, and end-user industry vertical across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating electric vehicle platform penetration rates, green building certification adoption, and electronics miniaturization trends. Forecast inputs included silane crosslinker price indices, REACH SVHC candidate list expansion schedules, and regional automotive production cluster shifts.
Decision-makers should treat outputs as directional under stable regulatory enforcement and petrochemical feedstock availability assumptions; material deviation would warrant model refresh. Forecasts incorporate disclosed compliance timelines and announced capacity investments without projecting unannounced regulatory accelerations or technology substitutions. Revision becomes warranted when REACH SVHC reclassification or SAMR GB standard enforcement crosses thresholds altering qualification economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Human Fibrin Glue Market
Adhesives & Sealants
Isobornyl Acrylate Market
Adhesives & Sealants
Electrical Insulation Tape Market
Adhesives & Sealants
North America Epoxy Curing Agents Market
Adhesives & Sealants
Applicator Tips Market
Adhesives & Sealants
Ethylene Butyl Acrylate Market
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
Tissue Adhesives Market
Adhesives & Sealants
Global Isononyl Acrylate Market
Adhesives & Sealants
Dibutyl Maleate (DBM) Market
Adhesives & Sealants
Mexico Adhesives Market
Adhesives & Sealants
Lignin for Adhesives Market
Adhesives & Sealants
North America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Melamine Formaldehyde (MF) Market
Adhesives & Sealants
Saudi Arabia Adhesives Market
Adhesives & Sealants
Glass Adhesive Market