
 North America Cyanoacrylate Adhesives Market | 2026-2036
North America Cyanoacrylate Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cyanoacrylate Adhesives Market Analytics
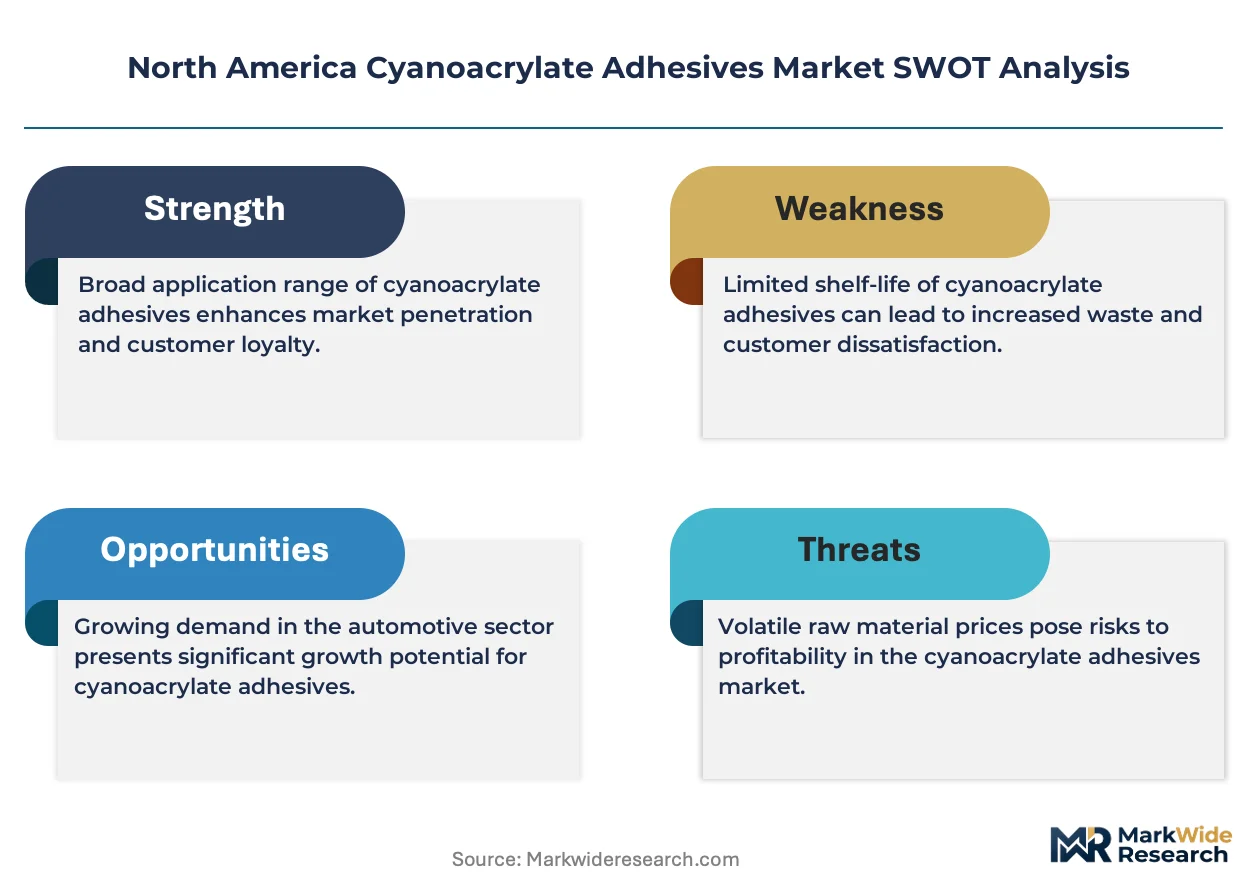
The North America cyanoacrylate adhesives market is recalibrating around a widening split between medical-grade premium formulations and commodity industrial grades. Illinois Tool Works leverages its diversified industrial portfolio to sustain pricing power across automotive assembly lines. Henkel AG & Co. KGaA anchors its position through specialized medical adhesive portfolios that command formulation premiums.
Cyanoacrylate adhesives are single-component thermoplastic resins that polymerize rapidly on contact with trace moisture, typically achieving handling strength within seconds at room temperature without catalysts. Their primary commercial purpose centers on instant bonding of rubber, metal, plastic, and biological tissue across manufacturing and clinical settings. Ethyl cyanoacrylate dominates volume production due to its versatile adhesion profile and established supply chains, while specialty cyanoacrylates capture disproportionate margin pools through medical-grade purity certifications and customized rheology. Fast cure technology leads adoption in electronics assembly, where cycle time compression directly correlates with throughput economics.
EPA oversight of volatile methyl methacrylate emissions and FDA biocompatibility requirements under ISO 10993 constrain formulation choices for medical applications, effectively raising barriers for uncertified suppliers. OSHA workplace exposure limits for cyanoacrylate vapors further shape industrial application protocols and ventilation infrastructure investments. Stakeholders must monitor evolving state-level chemical disclosure laws in California and New York, as these jurisdictions typically prefigure broader North American regulatory trajectories.
Market Dynamics
The North America cyanoacrylate adhesives market is bifurcating around FDA ISO 10993 biocompatibility certification, which partitions suppliers into medical-grade premium tiers and commodity industrial grades with divergent margin structures.
Growth Catalysts
- EPA methyl methacrylate emission controls:Tightening volatile organic compound limits in Ohio and Michigan automotive corridors are accelerating solvent-free adhesive conversions. Manufacturers are retrofitting assembly lines with cyanoacrylate systems to maintain throughput under compliance deadlines.
- Wound closure surgical applications:Medical device manufacturers in Illinois and Minnesota are expanding tissue adhesive portfolios beyond sutures. FDA 510(k) clearance pathways for topical skin adhesives are shortening commercialization timelines for certified formulators.
- Electronics miniaturization:Smartphone and wearable assembly plants in Texas and California are adopting fast-cure cyanoacrylates for micro-component bonding. Cycle time compression in surface-mount technology lines directly correlates with throughput economics.
Market Restraints
- Ethyl cyanoacrylate feedstock concentration:Bulk monomer supply concentrates among a limited set of Gulf Coast chemical producers. Price volatility in acetic acid and cyanide precursors transmits directly to formulation costs.
- OSHA workplace exposure infrastructure:Eight-hour time-weighted average limits for cyanoacrylate vapors mandate capital-intensive ventilation and monitoring systems. Small-scale industrial users face disproportionate compliance burdens relative to large automotive assemblers.
- UV-curable epoxy substitution:Electronics manufacturers are selectively displacing cyanoacrylates in display bonding applications where optical clarity and thermal stability requirements exceed cyanoacrylate performance envelopes.
Strategic Opportunities
- Canadian medical device expansion:Health Canada regulatory harmonization with FDA biocompatibility standards is opening export pathways for US-certified formulators. Ontario and Quebec surgical supply clusters present underpenetrated demand.
- Flexible electronics convergence:Stretchable circuit assemblies for wearable health monitors require modified rheology cyanoacrylates. Formulators combining low-modulus polymers with moisture-triggered cure kinetics are capturing prototype-to-production contracts.
- California Proposition 65 disclosure acceleration:Advance warning requirements for chemical exposure are creating first-mover advantages for suppliers with transparent ingredient documentation. Premium positioning through preemptive compliance is displacing commodity competition in consumer-facing applications.
Industry Challenges
- ISO 10993-5 cytotoxicity testing timelines:Medical-grade certification requires six-to-twelve-month biocompatibility validation cycles. Formulators face working capital strain during qualification periods without offsetting revenue.
- Legacy methyl methacrylate adhesive integration:Automotive assembly lines running solvent-based legacy systems require line-stop conversions to cyanoacrylate chemistry. Production managers resist downtime risks despite long-term efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cyanoacrylate Adhesives Market |
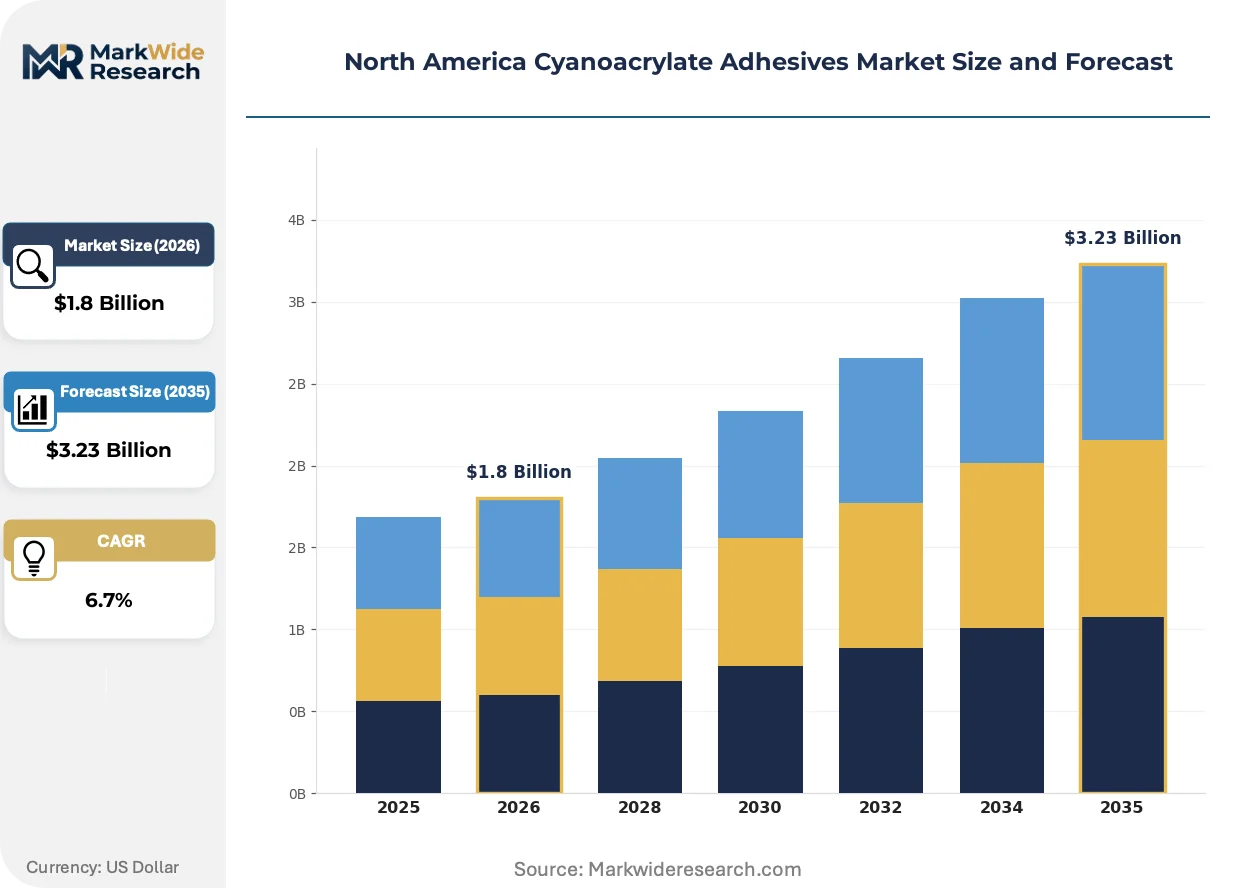
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethyl Cyanoacrylate, Methyl Cyanoacrylate, Butyl Cyanoacrylate, Specialty Cyanoacrylates End User: Automotive, Electronics, Medical, Crafts Application: Bonding, Sealing, Coating, Repair Technology: Fast Cure, Low Viscosity, High Viscosity, Anaerobic |
| Companies Covered | Arkema, Illinois Tool Works, 3M, Permabond, Soudal, Henkel AG & Co. KGaA, Sika AG, Dow, H.B. Fuller Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cyanoacrylate Adhesives Market Evolving Landscape
Formulation chemistry and regulatory disclosure requirements are compressing product development cycles while elevating documentation standards across medical and industrial segments.
Toughened cyanoacrylate formulations incorporating rubber-toughening agents are integrating into automotive structural bonding applications previously dominated by two-part epoxies. Tier 1 suppliers in Michigan and Ohio are qualifying these systems for interior trim and lighting assembly where impact resistance requirements have tightened. The technology is integrating impact-modified chemistry into high-vibration environments without sacrificing the speed advantages that define cyanoacrylate value propositions.
California's Safer Consumer Products regulations are forcing reformulation of cyanoacrylate stabilizer packages to eliminate bisphenol A and phthalate plasticizers from consumer-accessible products. Industrial adhesive suppliers serving retail channels through hardware distributors are redesigning stabilizer chemistries to maintain shelf stability without flagged substances. Medical-grade suppliers with existing ISO 10993 documentation are extending compliant formulations into consumer segments with minimal incremental qualification burden.
Automotive procurement departments are consolidating adhesive specifications across multi-plant networks to leverage volume pricing and reduce supplier management overhead. Tier 1 interior suppliers serving Detroit Three manufacturers are responding with platform-level adhesive standardization programs. This concentration is most visible in the Midwest manufacturing corridor where single-source cyanoacrylate contracts now span Ohio, Michigan, and Illinois assembly facilities under unified technical service agreements.
North America Cyanoacrylate Adhesives Market Segmentation
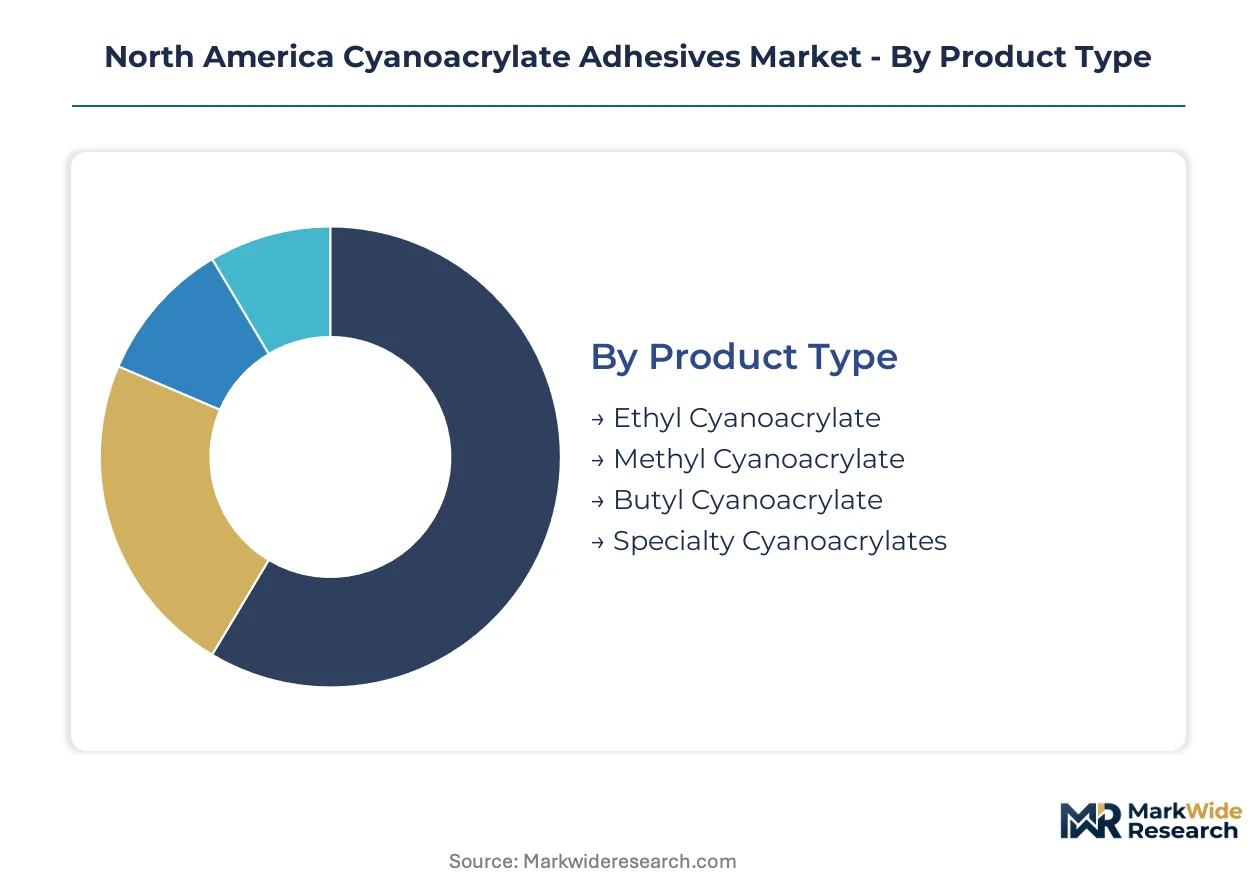
Cyanoacrylate adhesive buyers select formulations through divergent technical filters. Medical procurement teams prioritize biocompatibility certifications, while automotive engineers optimize for cure speed on high-volume assembly lines.
Product Type:
Cost tiers separate commodity monomer buyers from premium formulation purchasers seeking specialized certifications.
- Ethyl Cyanoacrylate:The dominant commercial monomer balances rapid polymerization with versatile substrate adhesion. Midwest automotive corridors in Ohio and Michigan consume bulk volumes for interior trim bonding where eight-second fixture times compress cycle economics. EPA volatile organic compound limits are accelerating solvent-to-cyanoacrylate conversions in these manufacturing clusters.
- Specialty Cyanoacrylates:Medical-grade purity variants command formulation premiums through ISO 10993 biocompatibility documentation. Minnesota and Illinois surgical device manufacturers specify these grades for topical skin adhesives and internal wound closure applications where cytotoxicity testing validates patient safety.
- Methyl Cyanoacrylate:Higher bond strength on metal substrates suits industrial maintenance applications in Texas oilfield equipment repair.
- Butyl Cyanoacrylate:Flexible polymer chains accommodate rubber and elastomer bonding in Michigan tire manufacturing plants.
Ethyl cyanoacrylate leads volumes today; specialty cyanoacrylates are gaining share fastest.
End User:
Application environments dictate formulation specifications across divergent performance requirements.
- Automotive:Tier 1 suppliers in the Detroit Three network specify toughened formulations for interior structural bonding. Impact-modified cyanoacrylates are displacing two-part epoxies in lighting assembly and dashboard modules where vibration resistance requirements have tightened without sacrificing speed advantages.
- Medical:Device manufacturers in Illinois and Minnesota are expanding tissue adhesive portfolios beyond traditional sutures. FDA 510(k) clearance pathways for topical skin adhesives are shortening commercialization timelines for certified formulators serving surgical supply chains.
- Electronics:Smartphone assembly plants in Texas and California adopt fast-cure systems for micro-component surface-mount technology.
- Crafts:California Proposition 65 disclosure requirements are filtering retail-channel formulations toward bisphenol A-free stabilizer packages.
Automotive procurement dominates volume; medical end use is expanding most quickly.
Application:
Functional purpose determines rheology specifications and cure kinetics selection.
- Bonding:The core commercial function leverages moisture-triggered anionic polymerization for instant mechanical fixation. Electronics miniaturization in California and Texas is driving demand for precision-dispensed low-viscosity grades that wick into micro-scale component gaps without overflow.
- Sealing:Gap-filling formulations with thixotropic properties prevent leakage in automotive fluid system assemblies. Michigan powertrain suppliers specify high-viscosity grades for transmission case sealing where thermal cycling resistance matters.
- Coating:Thin-film applications in medical device manufacturing protect sensitive electronic components from moisture ingress.
- Repair:Field maintenance crews in Ohio manufacturing plants keep rapid-fix kits for emergency equipment restoration.
Bonding commands the largest application share; sealing is climbing the fastest.
Technology:
Cure speed and flow characteristics segment buyers by production line constraints.
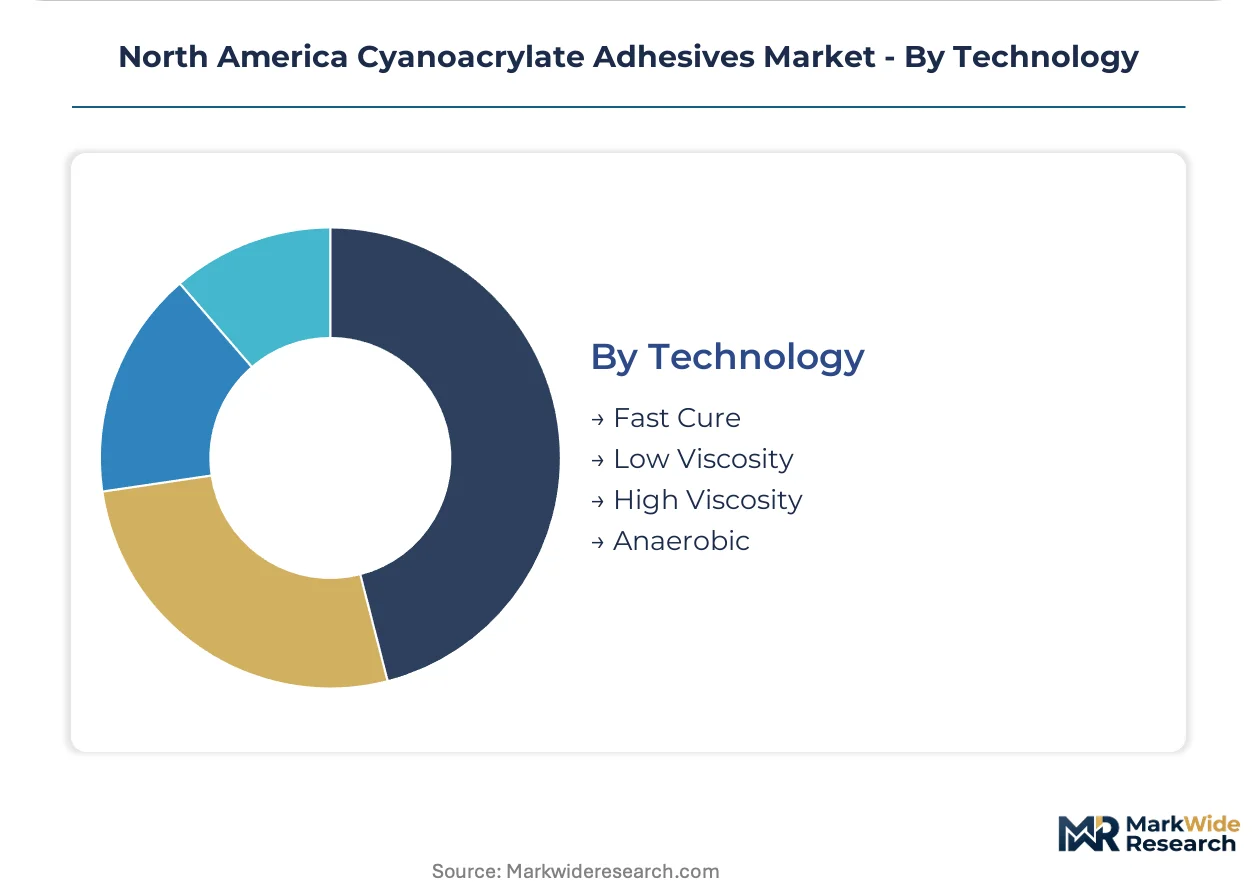
- Fast Cure:Sub-five-second handling strength defines value in high-throughput electronics assembly. Texas smartphone manufacturing plants correlate cure speed directly with line throughput economics, making this technology non-negotiable for surface-mount operations.
- Low Viscosity:Capillary-grade flow characteristics penetrate tight clearances in medical device micro-assembly. Minnesota catheter manufacturers specify these grades for bonding components where mechanical fasteners are impossible.
- High Viscosity:Non-sag formulations suit vertical automotive assembly applications in Michigan trim plants.
- Anaerobic:Metal-to-metal bonding without surface moisture activation serves Ohio industrial maintenance applications.
Fast cure technology leads adoption; low viscosity grades show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists and polymer engineers concentrate in the Great Lakes manufacturing belt, anchoring North American cyanoacrylate adhesive development. FDA and EPA regulatory expertise clusters in Washington DC corridors and Midwest state capitals. Cross-border supply chains integrate Canadian raw material flows with US formulation and Mexican assembly demand.
United States
Automotive assembly plants in Ohio, Michigan, and Illinois drive bulk consumption of toughened ethyl cyanoacrylate grades for interior structural bonding. EPA volatile organic compound limits in these manufacturing corridors accelerate solvent-to-cyanoacrylate line conversions. Minnesota and Illinois surgical device clusters specify ISO 10993-certified medical grades for topical skin adhesives and internal wound closure applications.
Canada
Health Canada regulatory harmonization with FDA biocompatibility standards opens export pathways for US-certified formulators serving Ontario and Quebec surgical supply chains. Ontario medical device manufacturers import specialty cyanoacrylates for catheter and wound closure product assembly. Quebec's aerospace maintenance sector maintains rapid-fix adhesive inventories for emergency equipment restoration.
Mexico
Automotive assembly expansion in Nuevo León and the Bajío Region generates demand for fast-cure industrial grades in tier supplier plants serving US OEMs. Mexican environmental regulators align volatile organic compound standards with EPA frameworks, facilitating cross-border formulation approvals. Northern border states integrate into just-in-time supply chains delivering adhesives to Texas electronics assembly plants.
North America Cyanoacrylate Adhesives Market Competitive Landscape
Top-tier vendors anchor medical-grade premium positioning, while commodity industrial specialists compete on throughput scale and automotive procurement integration. The market structures around ISO 10993 certification barriers that partition suppliers into divergent margin tiers. Three archetypes dominate: diversified industrial conglomerates with adhesive portfolios, pure-play medical adhesive specialists, and regional formulation houses serving automotive corridors. Competitive moves center on platform-level adhesive standardization programs across multi-plant automotive networks and preemptive California Proposition 65 compliance documentation.
Among diversified industrial conglomerates, Illinois Tool Works and 3M occupy positions spanning automotive assembly and medical device supply chains. Henkel AG & Co. KGaA exemplifies the medical-grade specialist archetype through its ISO 10993-certified formulation portfolios. These three anchors represent distinct competitive vectors: industrial scale, medical certification depth, and cross-segment diversification.
| Leading Market Players |
|---|
| Arkema |
| Illinois Tool Works |
| 3M |
| Permabond |
| Soudal |
| Henkel AG & Co. KGaA |
| Sika AG |
| Dow |
| H.B. Fuller Company |
| Others |
Value Network & Pricing Analysis
Tier 1 automotive suppliers in the Detroit Three network command unbundled material pricing with technical service agreements billed separately, while medical device manufacturers absorb bundled formulation-plus-certification packages. This split concentrates pricing power among ISO 10993-certified formulators serving Illinois and Minnesota surgical clusters, where regulatory documentation carries discrete premiums. Commodity ethyl cyanoacrylate volumes in Ohio and Michigan automotive corridors trade on spot-indexed monomer costs with thin margins.
Pricing Analysis
Bundled certification-plus-formulation packages dominate medical procurement, while unbundled material-and-service contracts prevail in automotive. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified medical grades from industrial toughened formulations and commodity bulk monomers. Cost compression in standard industrial tiers is intensifying because automotive procurement consolidation demands volume discounts across multi-plant networks. Medical device manufacturers show least price sensitivity due to regulatory switching costs, while small-scale industrial users face acute margin pressure from OSHA compliance infrastructure requirements.
Supply Chain Analysis
Specialized polymer chemists and formulation engineers concentrate in the Great Lakes manufacturing belt, creating workforce-availability bottlenecks for new production capacity. Bulk monomer supply draws from Gulf Coast petrochemical complexes and select Canadian specialty chemical producers, with critical dependencies on acetic acid, cyanide precursors, and sulfuric acid catalysts. Single-source vulnerability in ethyl cyanoacrylate monomer production exposes formulators to feedstock price volatility. Distribution runs through direct technical sales forces for medical and automotive accounts, with retail hardware channels handling consumer-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America cyanoacrylate adhesives market functions as a regulatory compounder, where each FDA ISO 10993 certification milestone and EPA emission control tightening expands the addressable premium tier. Health Canada harmonization with FDA standards now extends this dynamic across the full North American footprint.
For Market Incumbents: Anticipate UV-curable epoxy substitution in electronics display bonding by accelerating toughened formulation R&D for automotive structural applications. Backward integration into captive monomer supply buffers Gulf Coast feedstock volatility. Defensive patent filings around low-modulus flexible electronics chemistries will pre-empt entrant disruption in wearable health monitor assemblies. For New Entrants and Emerging Players: Launch via Health Canada-aligned export pathways into Ontario and Quebec surgical supply chains, where US-certified formulators remain underrepresented. Canadian medical device expansion offers the most penetrable geography. Target flexible electronics convergence segments with modified rheology prototypes, leveraging prototype-to-production contract structures to bypass incumbent certification timelines. For Investors and Strategic Acquirers: Diversified industrial conglomerates with adhesive portfolios are the most active acquirers in this space, seeking ISO 10993 certification capabilities to bridge medical-industrial segments. Long-term viability centers on regulatory documentation depth rather than commodity scale. Watch for California Proposition 65 disclosure acceleration as inflection signal—suppliers with preemptive compliant formulations will capture consumer-facing channel share from lagging competitors.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993-5 Certification Investment | Medical-grade purity documentation unlocks FDA 510(k) pathways and formulation premiums in Illinois surgical clusters. |
| Backward Integration into Monomer Supply | Gulf Coast feedstock volatility mitigation secures cost stability for Ohio and Michigan automotive contract volumes. |
| Platform-Level Adhesive Standardization | Detroit Three procurement consolidation rewards single-source suppliers spanning multi-state assembly networks. |
| Prop 65-Compliant Stabilizer Reformulation | Bisphenol A-free packages preempt disclosure requirements in California retail channels. |
| Flexible Electronics Rheology Development | Stretchable circuit assemblies for Minnesota wearable health monitors capture prototype-to-production contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged adhesive formulation chemists, Tier 1 automotive procurement directors, medical device regulatory affairs leads, and hospital supply chain managers across the Midwest manufacturing corridor. Secondary validation drew from EPA emission control filings, FDA 510(k) clearance databases, SEC 10-K chemical segment disclosures, and Health Canada medical device establishment licenses. Bottom-up demand modeling triangulated against top-down market sizing from trade flow analysis.
Historical reference periods anchored volume and value projections across the modeling period, with CAGR derivation reflecting segment-specific adoption curves and regulatory milestone timing. Segmentation dimensions spanned product type, end-use industry, application function, and cure technology. Forecast inputs incorporated automotive production schedules at Ohio, Michigan, and Illinois assembly plants, plus medical device approval velocity through FDA and Health Canada pathways.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPA methyl methacrylate emission standard revisions or OSHA workplace exposure limit tightening. Material deviation in Health Canada-FDA harmonization pace or automotive platform standardization program cancellations warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America & Europe Adhesives and Sealants Market
Adhesives & Sealants
Middle East & Africa Automotive Adhesives & Sealants Market
Adhesives & Sealants
Europe Electronics Adhesives Market
Adhesives & Sealants
Optically Clear Adhesives Market
Adhesives & Sealants
Textile Adhesives Market
Adhesives & Sealants
Asia-Pacific Flock Adhesives Market
Adhesives & Sealants
South America Acrylic Adhesives Market
Adhesives & Sealants
Indonesia Adhesives and Sealants Market
Adhesives & Sealants
South America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Global Epoxy Adhesive Market
Adhesives & Sealants
North America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Tissue Adhesives Market
Adhesives & Sealants
Water Based Adhesive Market
Adhesives & Sealants
South Korea Sealants Market
Adhesives & Sealants
UV Cured Adhesives Market
Adhesives & Sealants
Wood Glue Market