
 United States Construction Adhesives and Sealants Market | 2026-2036
United States Construction Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
United States Construction Adhesives and Sealants Market Analytics
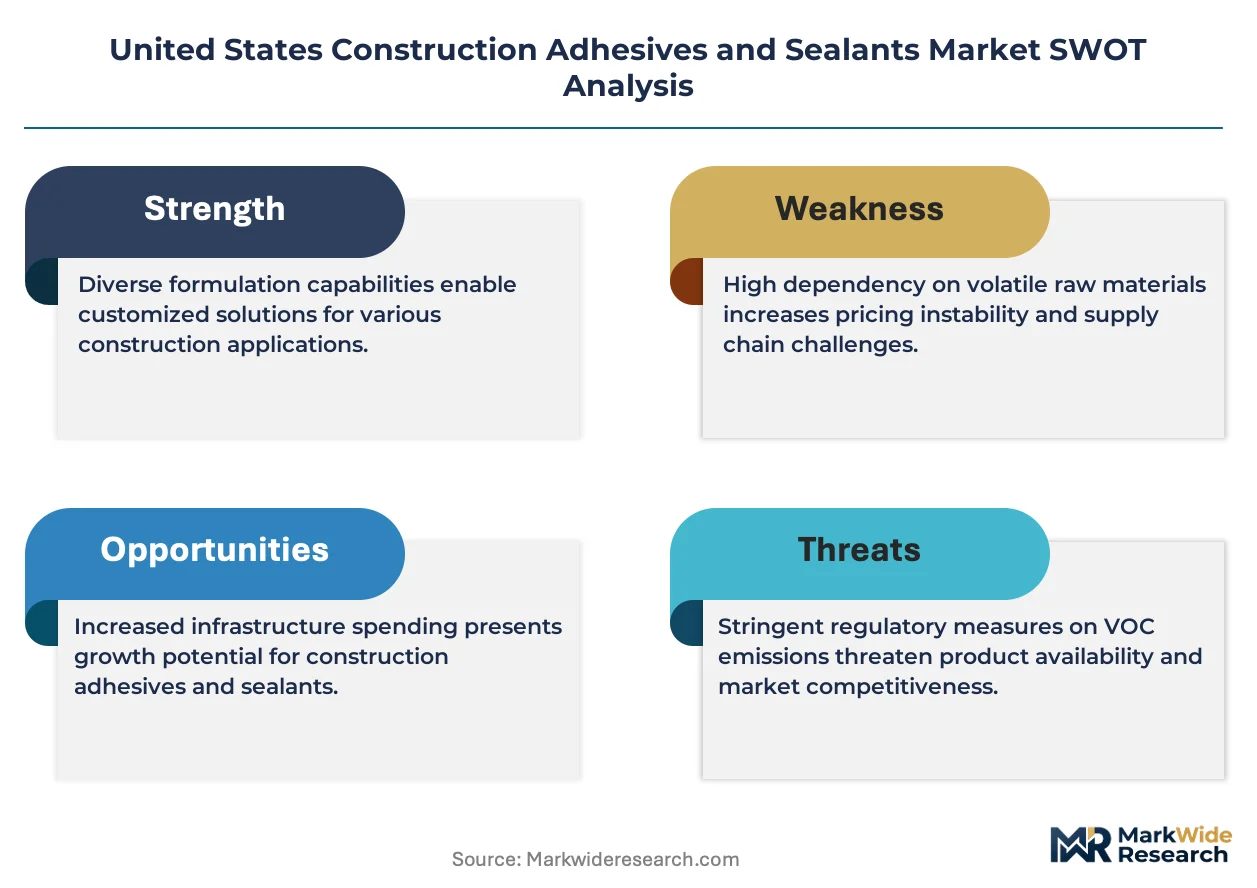
EPA VOC regulations under the Clean Air Act is pivoting the cost-of-entry calculus for adhesive formulators, forcing capital-intensive scrubber installations and low-solvent R&D commitments. H.B. Fuller Company anchors its position through captive resin synthesis and deep contractor channel relationships. Sika AG competes by leveraging its structural glazing expertise and specification-grade product lines. Dow differentiates through silicone chemistry leadership and direct supply to large-scale commercial envelope projects.
Construction adhesives and sealants comprise formulated polymer systems—typically polyurethane, silicone, acrylic, or butyl bases—engineered to bond dissimilar substrates and create impermeable barriers against moisture, air, and thermal transfer in built structures. These products cure through moisture reaction, solvent evaporation, or UV activation to achieve specified peel strengths and elongation properties critical to building envelope integrity. Polyurethane dominates volume owing to its structural bonding capacity and gap-filling performance in residential framing applications. Water-based technology is displacing solvent systems fastest, driven by OSHA workplace exposure limits and LEED v4.1 material ingredient reporting requirements that penalize high-VOC formulations.
FDA maintains indirect influence through food-contact adhesive standards applicable to commercial kitchen and food-processing facility construction. EPA and OSHA jointly shape permissible exposure thresholds and hazard communication mandates that determine product labeling, worker training burdens, and liability exposure for contractors. NHTSA's unrelated regulatory prominence in federal rulemaking illustrates how cross-agency precedent can accelerate chemical safety reviews. Stakeholders must monitor state-level adoptions of California's CARB standards, as these propagate through the Interstate Ozone Transport Rule and preempt federal minimums in practice.
Market Dynamics
EPA VOC regulations under the Clean Air Act are compressing formulation cycles and forcing capital redeployment toward low-emission chemistry platforms across the United States construction adhesives and sealants market.
Growth Catalysts
- Sun Belt construction volume:Texas, Florida, and Arizona residential starts are accelerating sealant consumption as humidity-driven degradation shortens replacement cycles in these high-growth corridors.
- LEED v4.1 material reporting:The US Green Building Council's ingredient disclosure requirements are pulling water-based adhesive adoption ahead of solvent systems in commercial envelope specifications.
- Residential retrofit wave:Aging building envelope replacements across the Northeast and Midwest are generating pull-through demand for structural bonding and air-sealing products.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane precursor costs fluctuate with propylene and MDI contract pricing, compressing margin stability for formulators without backward integration.
- Specialty resin supply concentration:Captive silicone monomer production concentrates among three domestic suppliers, creating bottleneck risk for sealant manufacturers.
- OSHA exposure threshold tightening:Reduced permissible isocyanate limits are forcing engineering controls and respiratory protection investments that elevate installed cost.
Strategic Opportunities
- Mass timber construction codes:The International Building Council's expanded Type IV construction allowances are opening structural adhesive applications in multi-story wood buildings.
- Offsite modular assembly:Factory-built wall and roof panel manufacturers need fast-cure, high-strength bonding systems that tolerate transport stress.
- CARB SCM 2007 propagation:California's low-VOC adhesive standards are spreading through the Ozone Transport Region, creating preemptive compliance demand in upwind states.
Industry Challenges
- Formulation chemist scarcity:The pipeline of polymer scientists trained in moisture-cure and UV-activated systems is narrowing relative to R&D program expansion.
- Scrubber retrofit capex:Solvent-based production lines require vapor recovery installations that strain mid-capitalization formulator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Construction Adhesives and Sealants Market |
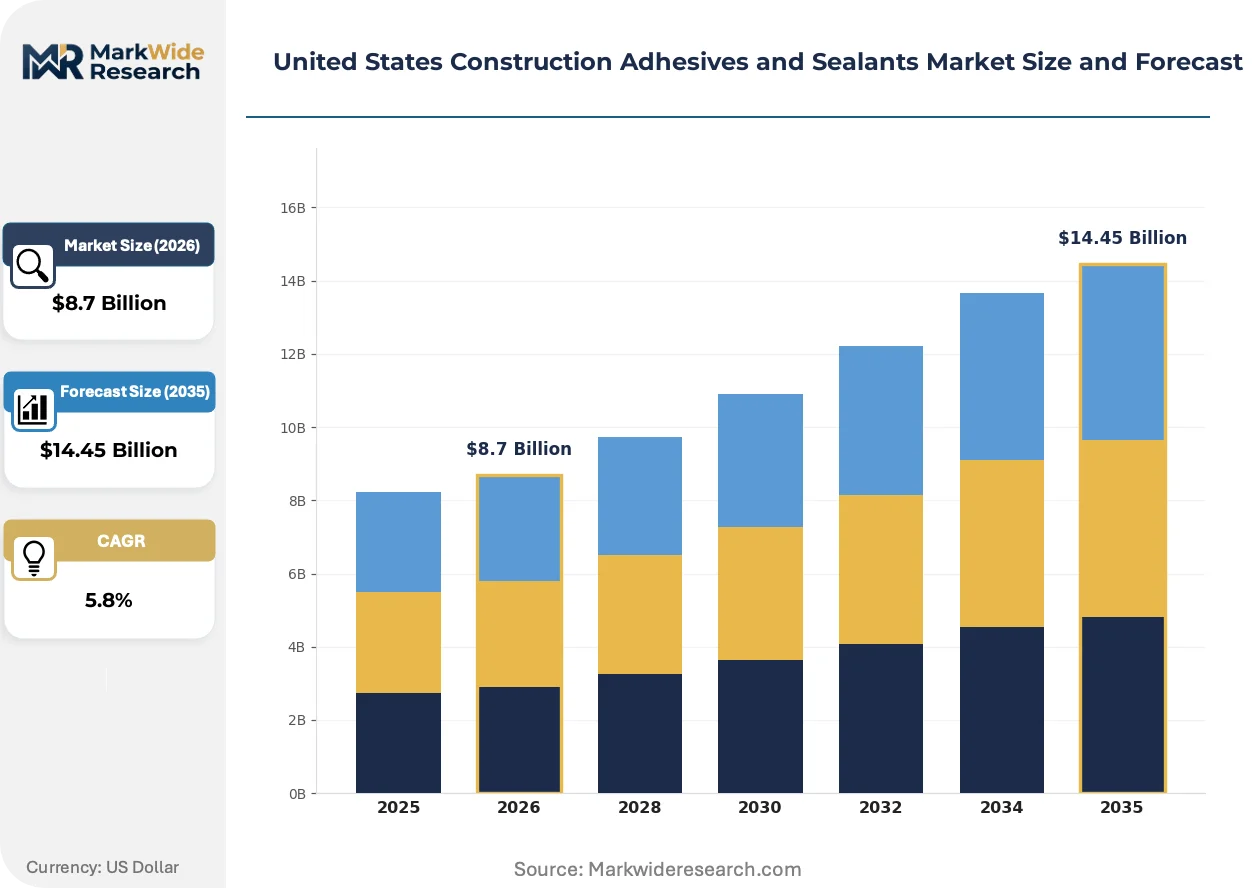
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Silicone, Acrylic, Butyl Application: Commercial Construction, Residential Construction, Industrial Applications, DIY Projects Technology: Water-Based, Solvent-Based, Hot Melt, Reactive End User: Contractors, Builders, Architects, Homeowners |
| Companies Covered | 3M, H.B. Fuller Company, Henkel AG & Co. KGaA, Sika AG, Dow, Huntsman Corporation, Arkema, RPM International, MAPEI, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Construction Adhesives and Sealants Market Evolving Landscape
Modular construction methods and factory-based assembly are rewiring how adhesives are specified, purchased, and applied across the United States building sector.
Hybrid polyurethane-silane (STPE) technology is modularizing specification workflows by combining structural adhesion with sealant elasticity in single-product platforms. Offsite panel manufacturers and modular builders are specifying these systems to reduce SKU complexity and inventory carrying costs. The convergence is compressing traditional product category boundaries between structural adhesives and weatherseal grades.
OSHA's expanded hazard communication standard is forcing reformulation transparency through Safety Data Sheet disclosure requirements. Manufacturers must now document isocyanate content, residual solvent levels, and cure byproduct chemistry in granular detail. Commercial contractors in California, New York, and Washington are responding by pre-qualifying suppliers based on complete toxicological dossiers.
Direct procurement relationships between adhesive formulators and national homebuilders are displacing traditional two-step distribution through regional construction supply houses. Lennar, D.R. Horton, and PulteGroup are negotiating volume commitments and technical service embedding that bypass local distributor margins. This channel compression is most visible in the Sun Belt, where production homebuilding concentration enables scale-based procurement restructuring.
United States Construction Adhesives and Sealants Market Segmentation
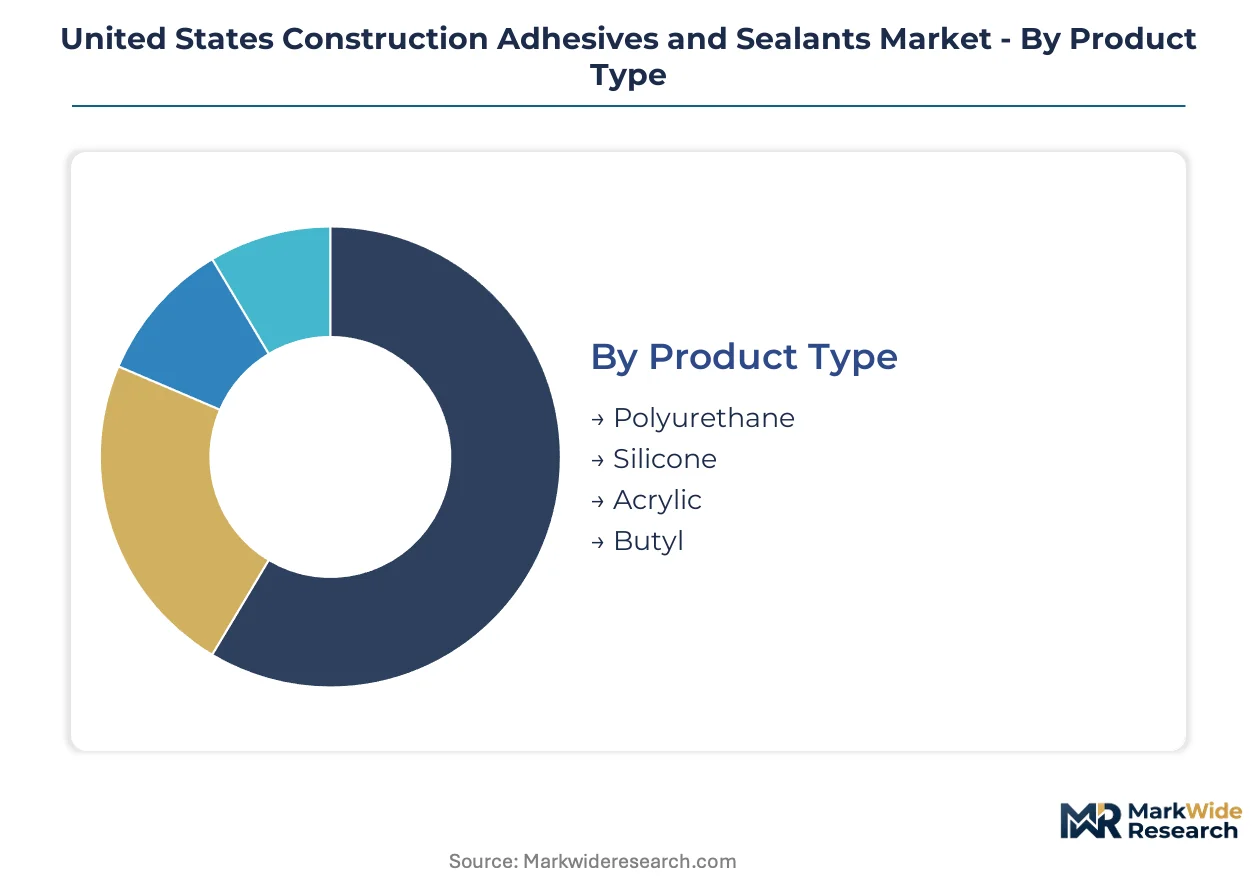
Segmentation reveals how replacement cycles and specification pressures fragment demand across chemistries and customer types. Upgrade timelines vary dramatically between residential envelope retrofits and commercial new-build projects.
Product Type:
Replacement frequency differs sharply by chemistry, with humidity exposure and UV degradation dictating upgrade schedules across climate zones.
- Polyurethane:Moisture-cure systems deliver structural bonding capacity and gap-filling performance in residential framing and subfloor applications. Demand concentrates in Sun Belt states where new construction volume and humidity-driven reapplication cycles accelerate consumption.
- Silicone:UV-stable formulations provide superior elongation and thermal cycling resistance for curtain wall and roofing applications. Specification-grade projects in coastal metros drive premium placements, though captive monomer supply concentration creates procurement risk for formulators.
- Acrylic:Water-based systems serve interior finishing and low-stress bonding where rapid tack and paint compatibility matter. Cost-sensitive residential retrofits favor these formulations.
- Butyl:Preformed tapes and sealants deliver vapor barrier performance in metal building envelopes and window flanging. Industrial metal construction specifications sustain niche demand.
Volume placements concentrate in Polyurethane; the faster expansion belongs to Silicone.
Application:
Customer procurement patterns split between specification-driven commercial workflows and price-sensitive residential channels.
- Commercial Construction:Envelope integrity specifications and LEED v4.1 material reporting requirements pull water-based and low-VOC systems into curtain wall, roofing, and air barrier assemblies. Direct formulator relationships with national contractors bypass traditional distribution.
- Residential Construction:Production homebuilders in Texas, Florida, and Arizona negotiate volume commitments for subfloor adhesive and window sealant. Fast-cure polyurethane dominates new-start applications.
- Industrial Applications:Metal building, cold storage, and food-processing facility construction require FDA-compliant and chemical-resistant formulations. Specification complexity favors established supplier relationships.
- DIY Projects:Big-box retail channels and contractor-grade product availability drive homeowner purchases for repair and small-scale renovation. Price transparency compresses margin.
Revenue concentration sits with Commercial Construction; Residential Construction is climbing the fastest.
Technology:
Regulatory pressure and workplace exposure limits are compressing the viable technology mix toward lower-emission platforms.
- Water-Based:Acrylic and polyurethane dispersions eliminate solvent exposure concerns and satisfy LEED v4.1 ingredient disclosure mandates. OSHA workplace limits and EPA VOC regulations accelerate displacement of solvent alternatives.
- Solvent-Based:High-solids neoprene and SBC formulations persist in specialty roofing and cold-weather applications where water-based cure failure risks exist. Scrubber retrofit capital requirements strain mid-tier formulator balance sheets.
- Hot Melt:EVA and polyolefin systems serve factory-built component assembly where rapid green strength and automation compatibility matter. Modular construction growth expands addressable demand.
- Reactive:Two-component epoxies and hybrid silane-terminated polyethers deliver structural performance in mass timber and engineered wood applications. IBC Type IV code expansion opens multi-story wood building specifications.
Installed base remains weighted toward Solvent-Based; Water-Based platforms are gaining share fastest.
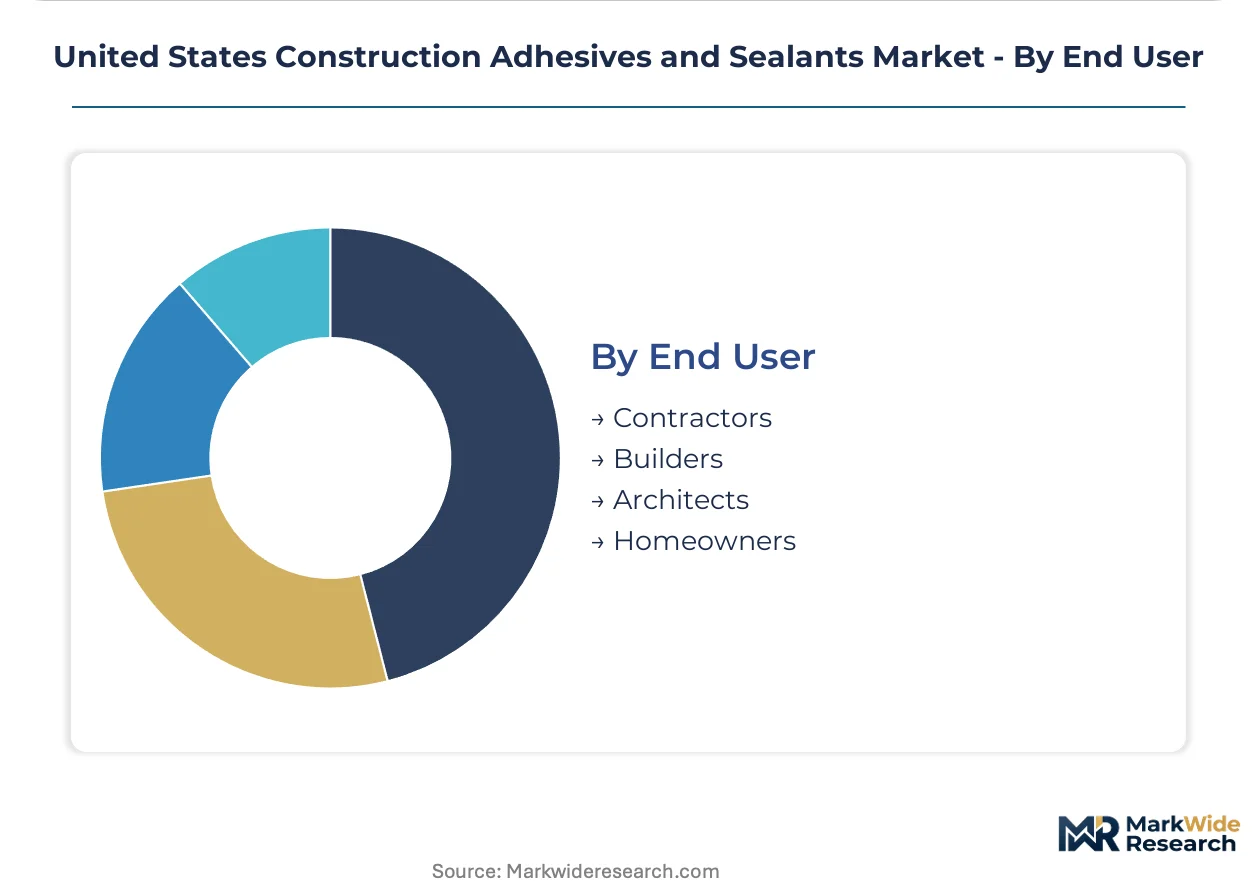
End User:
Purchasing authority and technical specification involvement vary sharply across the value chain, determining channel strategy and service intensity.
- Contractors:Trade specialists in envelope, flooring, and glazing drive product selection through performance verification and warranty terms. Technical service embedding and jobsite support cement supplier relationships.
- Builders:National production homebuilders leverage procurement scale to negotiate direct formulator contracts and private-label arrangements. Lennar, D.R. Horton, and PulteGroup bypass regional distribution in Sun Belt markets.
- Architects:Specification writers influence commercial project adhesive selection through master specification and approved product lists. CSI MasterFormat integration and LEED documentation support matter.
- Homeowners:End consumers purchase through retail channels for repair and renovation, with brand recognition and shelf placement driving selection. Price sensitivity limits premium product uptake.
Transaction volume clusters with Contractors; specification influence and margin expansion track with Architects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the Sun Belt states, where humidity-driven sealant degradation and new construction volume create replacement-intensive markets. Texas, Florida, and Arizona anchor volume consumption, while California and the Northeast drive specification-grade commercial demand through stringent environmental standards.
Texas
Residential construction volume in Dallas-Fort Worth and Houston metro areas accelerates polyurethane adhesive consumption for subfloor and framing applications. The Texas Commission on Environmental Quality enforces VOC standards aligned with federal EPA baselines, though with streamlined permitting for low-emission formulations. Production homebuilders in Austin and San Antonio negotiate direct supply contracts that bypass traditional distribution channels.
Florida
Coastal humidity and hurricane-resistant building codes shorten sealant replacement cycles in Miami, Tampa, and Orlando markets. The Florida Building Commission mandates high-performance envelope standards that favor silicone and hybrid STPE chemistries for wind-uplift resistance. Window and door manufacturers in the I-4 corridor cluster specify premium sealant grades for coastal exposure zones.
California
CARB SCM 2007 standards propagate through the Ozone Transport Region, forcing preemptive compliance in upwind states before federal mandates arrive. The California Air Resources Board's adhesive regulations exceed EPA Clean Air Act minimums, creating a de facto national standard for formulators serving multi-state contractors. Los Angeles and San Francisco commercial envelope specifications drive water-based technology adoption ahead of national trends.
Arizona
Extreme thermal cycling and UV exposure in Phoenix and Tucson metro areas accelerate silicone sealant degradation in roofing and glazing applications. The Arizona Department of Environmental Quality coordinates with EPA Region 9 on VOC enforcement priorities that target architectural coatings and adhesives. Modular construction factories in Mesa and Tempe specify fast-cure hot melt systems for panel assembly lines.
Northeast Corridor
Aging building stock in New York, Massachusetts, and Pennsylvania generates retrofit-driven demand for air-sealing and structural bonding products. State-level adoptions of California CARB standards through the Interstate Ozone Transport Rule preempt federal minimums in practice. Boston and New York City commercial projects specify LEED v4.1-compliant formulations that satisfy material ingredient reporting requirements.
United States Construction Adhesives and Sealants Market Competitive Landscape
Midwestern and Northeastern producers anchor one tier; European-headquartered specialists hold specification-grade positions through structural glazing expertise. The vendor base splits between diversified chemical conglomerates with captive resin synthesis and mid-cap formulators serving regional contractor channels. Three archetypes dominate: backward-integrated resin producers, specification-driven envelope specialists, and distribution-embedded regional suppliers. Competitive moves concentrate on M&A for technology access and direct procurement relationships with national homebuilders that displace two-step distribution.
Among diversified chemical conglomerates, 3M, Dow, and Huntsman Corporation exemplify scale-driven positions with integrated material science capabilities. H.B. Fuller Company and Sika AG occupy distinct specification-tier roles, with the former representing North American-focused adhesive specialists and the latter embodying European-engineered structural systems expertise. Henkel AG & Co. KGaA sits within the industrial adhesives archetype, while RPM International and MAPEI represent construction-focused regional specialists with distribution-embedded service models. Arkema exemplifies the specialty chemical player with advanced materials positioning.
| Leading Market Players |
|---|
| 3M |
| H.B. Fuller Company |
| Henkel AG & Co. KGaA |
| Sika AG |
| Dow |
| Huntsman Corporation |
| Arkema |
| RPM International |
| MAPEI |
| Others |
Value Network & Pricing Analysis
Polymer formulation chemists concentrated in the Midwest and Northeast command wage premiums that widen pricing-tier spreads between specification-grade and commodity adhesive products. Labor-cost differentials between these technical centers and Sun Belt manufacturing zones translate directly into margin structures that separate premium structural systems from economy-grade residential formulations.
Pricing Analysis
Volume placements cluster in commodity polyurethane construction adhesives where thin margins reward scale; specification-grade silicone and hybrid STPE systems capture value through LEED certification tiers and wind-uplift performance ratings. Price differentiation hinges on VOC compliance grade and contractor technical service embedding, with CARB-compliant formulations commanding placement premiums in California and Ozone Transport Region states. Cost compression in solvent-based tiers is intensifying because scrubber retrofit capex burdens mid-tier formulators without backward integration. Production homebuilders in Texas and Florida exhibit lowest price sensitivity through direct procurement contracts; DIY retail channels show highest elasticity to shelf-price positioning.
Supply Chain Analysis
Dual-sourcing requirements from national homebuilders and envelope contractors mandate multi-supplier qualification for silicone monomer, MDI, and acrylic resin inputs. Geographic supply concentration centers on domestic captive production of silicone monomers by three suppliers, with MDI and propylene oxide derivatives drawing from integrated petrochemical complexes along the Gulf Coast. Raw material dependencies rest on propylene, methylene diphenyl diisocyanate, and silane coupling agents. Single-source vulnerability concentrates in specialty hybrid STPE intermediates where patent-protected synthesis limits qualified suppliers. Distribution runs through direct formulator relationships with national builders in Sun Belt markets, supplemented by regional construction supply houses serving contractor trade specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States construction adhesives and sealants market sits in a technology-transition phase as water-based and hybrid STPE platforms displace legacy solvent systems under EPA and OSHA regulatory compression.
For Market Incumbents: To counter channel compression from direct procurement relationships, secure captive resin synthesis capacity or long-term supply agreements with Gulf Coast petrochemical producers. Deepen technical service embedding with national homebuilders through jobsite support teams in Texas and Florida production corridors. Prioritize LEED v4.1 documentation infrastructure to maintain specification-tier positioning in California and Northeast commercial markets. For New Entrants and Emerging Players: Capture modular construction factory demand in Arizona and Sun Belt states where fast-cure hot melt and reactive adhesive specifications remain undersupplied by incumbent distributors. Target mass timber construction code expansion in multi-story wood building applications where structural adhesive qualification lists remain open. Pursue white-label arrangements with regional panel manufacturers seeking SKU consolidation. For Investors and Strategic Acquirers: The window for entry favors mid-cap formulators with captive silicone monomer access or established CARB-compliant water-based technology platforms. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale. Watch EPA Region-level VOC enforcement acceleration as the inflection indicator for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive MDI or silicone monomer production insulates margin from propylene contract volatility and supply interruption. |
| Direct Procurement Relationship Expansion | Bypassing regional distribution with Lennar or D.R. Horton secures volume commitments and technical service embedding. |
| LEED v4.1 Documentation Infrastructure | Material ingredient reporting compliance opens specification-grade commercial envelope projects in California and Northeast metros. |
| Modular Construction Factory Partnership | Fast-cure adhesive qualification with Arizona panel manufacturers addresses offsite assembly growth in Sun Belt corridors. |
| Hybrid STPE Technology Acquisition | Structural adhesion plus sealant elasticity in single-product platforms reduces SKU complexity for national homebuilder procurement. |
Research Methodology
Independent corroboration across adhesive formulator R&D directors, national homebuilder procurement officers, and envelope contractor trade specialists underwrites the qualitative findings in this study. Primary fieldwork included structured interviews with technical service managers at polyurethane and silicone production facilities, supplemented by secondary validation through EPA enforcement action databases, TCEQ and CARB regulatory filings, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up demand modeling from construction start data and top-down triangulation against chemical industry production statistics anchored volume estimates.
Rate-of-change decomposition across the projection horizon separates volume growth from mix-shift effects as water-based technology displaces solvent systems. The analytical framework models segmentation dimensions including chemistry type, application category, technology platform, and end-user purchasing authority, with regional construction permitting data and humidity-driven replacement cycle frequencies serving as industry-specific forecast inputs. CAGRs were derived from trend extrapolation moderated by regulatory phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA regional enforcement acceleration and petrochemical feedstock contract volatility. Deviation in CARB SCM 2007 propagation speed through the Ozone Transport Region would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
North America Waterborne Adhesives Market
Adhesives & Sealants
High Temperature Sealants Market
Adhesives & Sealants
North America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Global Adhesives Market
Adhesives & Sealants
North America Reactive Adhesives Market
Adhesives & Sealants
South America Sealants Market
Adhesives & Sealants
Indonesia Sealants Market
Adhesives & Sealants
Global Stone and Tile Adhesives and Sealants Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
Dibutyl Maleate (DBM) Market
Adhesives & Sealants
Butyl Adhesive Market
Adhesives & Sealants
Australia Sealants Market
Adhesives & Sealants
Automotive Adhesives and Sealants Market
Adhesives & Sealants
Structural Adhesives Market
Adhesives & Sealants
Nigeria Tile Adhesive Market