
 Europe, Middle-East and Africa Hot-Melt Adhesives Market | 2026-2036
Europe, Middle-East and Africa Hot-Melt Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe, Middle-East and Africa Hot-Melt Adhesives Market Insights
EU REACH regulation is decoupling legacy formulations from profitable market access. Henkel AG & Co. KGaA leverages its integrated resin capabilities to preempt compliance costs. H.B. Fuller Company anchors its EMEA position through dedicated plants in Egypt and Germany. Arkema Group differentiates via high-performance polyamide grades for electronics bonding.
Hot-melt adhesives are thermoplastic polymers applied in molten state that solidify on cooling to form bonds, typically operating between 120°C and 180°C and formulated from ethylene vinyl acetate, polyolefin, or polyamide base resins. These adhesives serve industrial joining where solvent-free, fast-setting attachment is required across porous and non-porous substrates. Ethylene vinyl acetate formulations dominate volume in packaging applications where cost and processing speed determine procurement decisions. Polyamide adhesives command premium positioning in automotive and electronics segments demanding thermal resistance above 150°C and chemical inertness. Styrenic block copolymers sustain growth in pressure-sensitive hygiene and medical tape applications across European healthcare end users.
EMA and ECHA frameworks govern chemical safety and biocompatibility for adhesives used in medical devices and food-contact packaging across European markets. Saudi Arabia's national standardization body and South Africa's chemical regulator enforce import testing protocols that extend product registration timelines for non-regional suppliers. Stakeholders must monitor divergence between EU Green Deal chemical restrictions and Gulf state industrialization incentives when allocating formulation R&D budgets.
Market Dynamics
REACH compliance deadlines in the European Union are forcing formulators to abandon legacy petroleum-based feedstocks before 2030, redirecting R&D budgets toward bio-based polyolefin development and supplier qualification programs.
Growth Catalysts
- E-commerce packaging scale-up:Gulf Cooperation Council states are expanding automated fulfillment centers that demand high-speed case sealing adhesives. Saudi Arabia and UAE logistics hubs drive procurement volumes for pressure-sensitive hot-melt formulations.
- REACH chemical restrictions:EU Green Deal mandates on carbon-intensive inputs are accelerating bio-based polyolefin adoption. Formulators securing ECHA pre-registration gain preferential access to automotive OEM qualification lists.
- Automotive lightweighting:German and Turkish assembly plants are substituting mechanical fasteners with structural bonding in electric vehicle battery enclosures. Polyamide hot-melt grades enable thermal management above 150°C.
Market Restraints
- Crude oil derivative volatility:Ethylene and propylene feedstock costs swing with naphtha cracking economics. EVA formulation margins compress when olefin spreads widen unpredictably.
- Specialty resin supply concentration:High-performance polyamide and reactive polyurethane precursor production clusters in Belgium and Netherlands. Disruption at Antwerp-Rotterdam hub propagates through EMEA medical device supply chains.
- UV-curable substitute threat:Electronics manufacturers in Czech Republic and Hungary are piloting radiation-cured acrylics for display bonding. These alternatives eliminate thermal exposure risks for heat-sensitive substrates.
Strategic Opportunities
- South African pharmaceutical packaging:Local converters serving Sub-Saharan HIV/AIDS drug distribution lack qualified hot-melt suppliers for tropical climate stability. First-mover registration with SAHPRA unlocks regional exclusivity.
- EU CSRD disclosure mandates:Scope 3 emissions reporting requirements push brand owners toward certified bio-based adhesives. Suppliers with ISCC PLUS chain-of-custody documentation capture sustainability-premium pricing.
- Digital dispensing integration:Industrial IoT sensor networks enable predictive maintenance for melt tank operations. Adhesive producers offering cloud-connected equipment leases differentiate against commodity competitors.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise in reactive hot-melt chemistry concentrates at aging technical centers in Germany. Gulf state universities lack graduate programs in pressure-sensitive adhesive design.
- Multi-jurisdiction registration timelines:Medical device adhesives require separate biocompatibility dossiers for EMA, Saudi SFDA, and South African regulators. Parallel track submissions extend time-to-revenue by 18-24 months.
- Legacy equipment retrofit costs:Bio-based polyolefins exhibit different melt viscosity profiles versus conventional EVA. Converters must recalibrate gear pumps and nozzle geometries, requiring production line downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe, Middle-East and Africa Hot-Melt Adhesives Market |
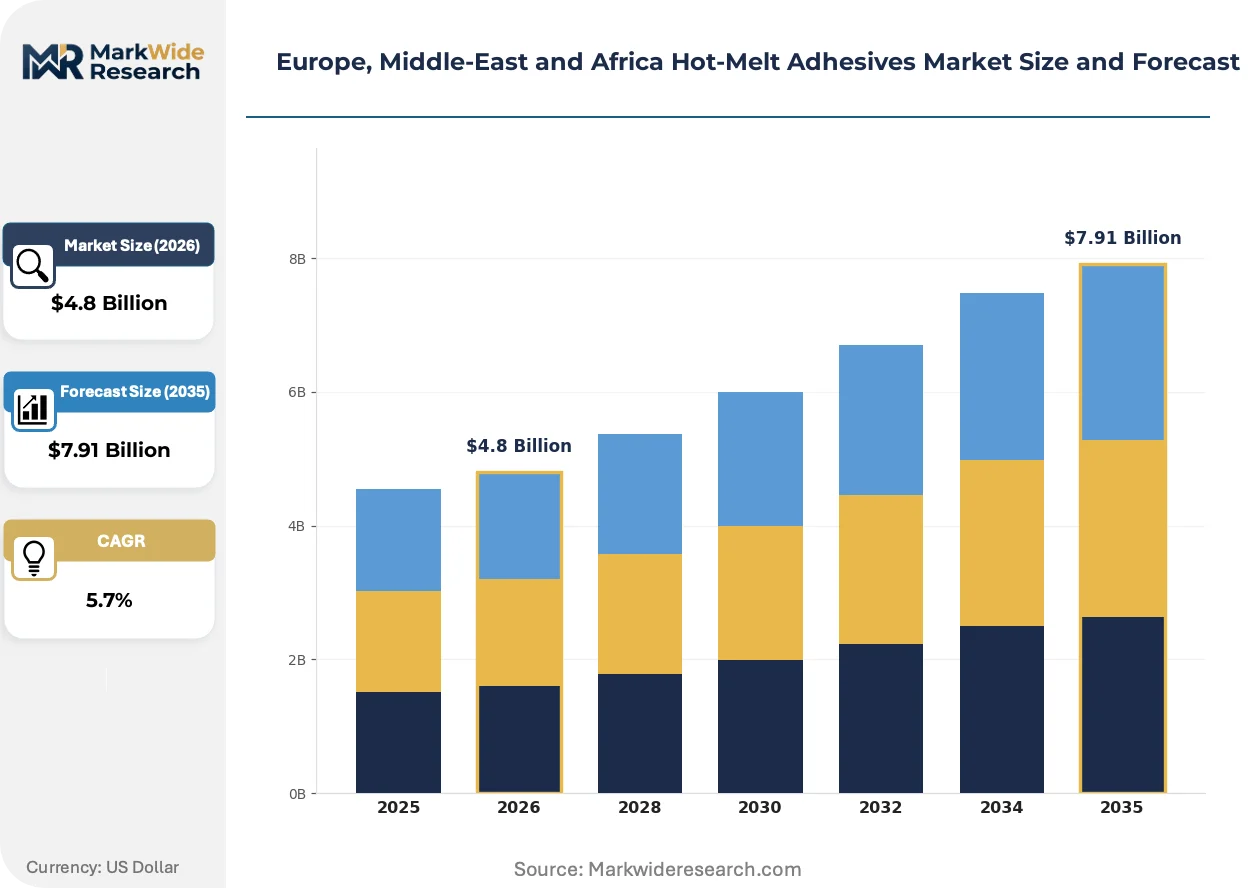
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyolefin, Styrenic Block, Ethylene Vinyl Acetate, Polyamide Application: Packaging, Furniture, Automotive, Electronics End User: Consumer Goods, Construction, Manufacturing, Healthcare Distribution Channel: Direct Sales, Retail, Distributors, E-commerce |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, Arkema Group, Jowat SE, Sika AG, Dow Inc., 3M Company, Hexcel Corporation, Beardow Adams, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe, Middle-East and Africa Hot-Melt Adhesives Market Trends and Innovations
Bio-based feedstock substitution and digital process integration are restructuring how adhesive value is captured across formulation, application equipment, and compliance documentation layers.
Reactive polyurethane hot-melt technology is modularizing plant floor configurations. Automotive Tier 1 suppliers in Stuttgart and Bursa are deploying compact dispensing cells that integrate moisture-curing chemistry with robotic path programming. This modularization collapses the traditional separation between adhesive supplier and systems integrator, compressing equipment procurement cycles from months to weeks.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon propellants in aerosol-dispensed contact adhesives. Industrial maintenance applications in food processing facilities must transition to pumpable hot-melt alternatives. German packaging machinery OEMs are responding with heated hose retrofit kits for existing pneumatic dispensing stations.
Consolidated buying by pan-European packaging groups is compressing supplier rosters. Three multinational converters now control over half of corrugated case sealing volume in Benelux and Northern France. These buyers are unbundling adhesive supply from equipment service contracts, forcing formulators to compete on per-kilogram pricing without captive maintenance revenue.
Europe, Middle-East and Africa Hot-Melt Adhesives Market Segmentation
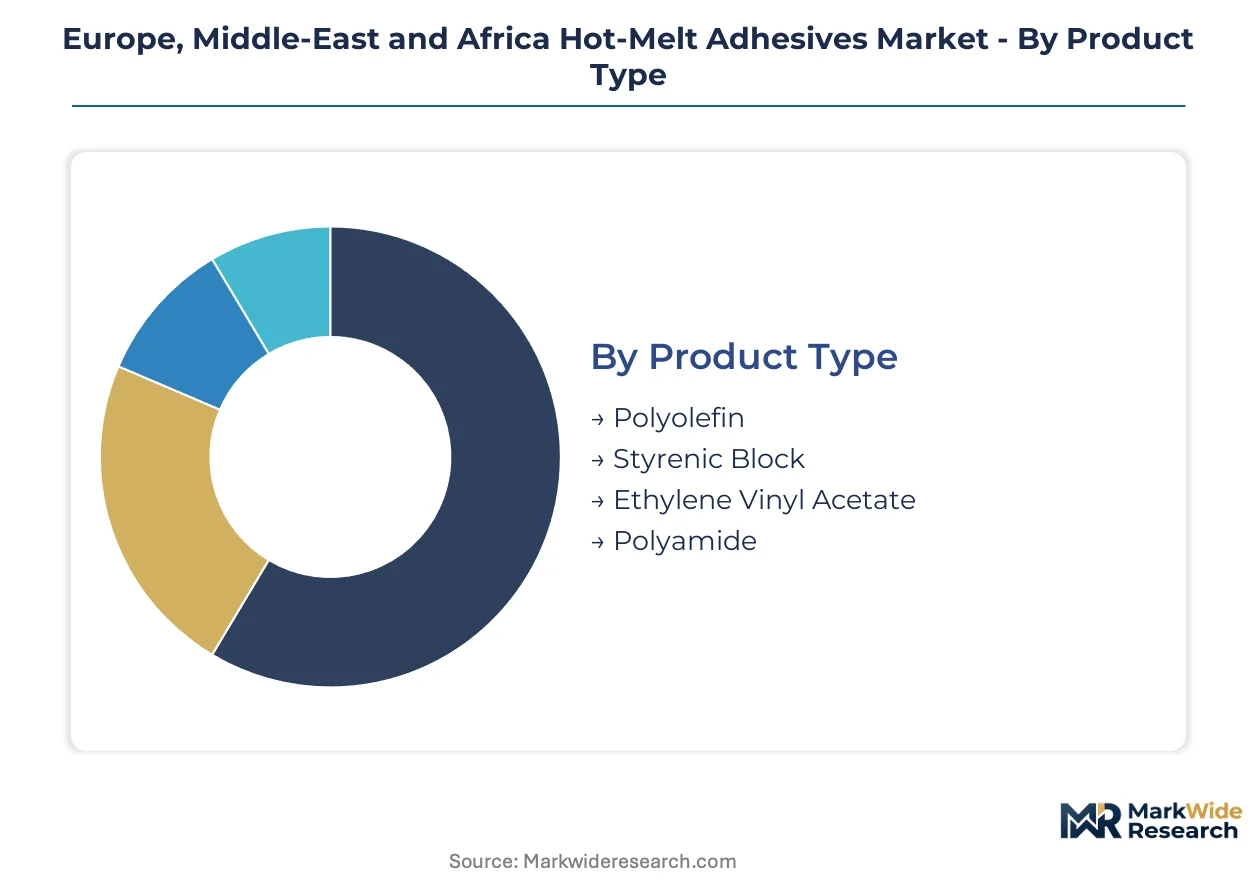
Hot-melt adhesive procurement decisions diverge sharply across end-use requirements, with thermal resistance specifications and regulatory compliance driving category selection. Formulators align product architectures to distinct performance thresholds rather than pursuing universal solutions.
Product Type:
Cost tier separates commodity volume buyers from premium specification seekers in resin selection.
- Ethylene Vinyl Acetate:Copolymer formulations balance tack strength and open time for high-speed packaging lines. German corrugated converters in the Ruhr Valley specify EVA grades for automated case sealing at throughput rates exceeding 200 units per minute.
- Polyamide:High-melting-point thermoplastics deliver thermal stability above 150°C for under-hood automotive bonding. Turkish electric vehicle battery pack assemblers in Bursa specify polyamide hot-melts for enclosure sealing where mechanical fasteners fail under thermal cycling stress.
- Polyolefin:Bio-based feedstock variants address EU Green Deal compliance mandates for Scope 3 emissions reduction.
- Styrenic Block:Pressure-sensitive formulations serve hygiene product lamination across European healthcare supply chains.
Volume sits with Ethylene Vinyl Acetate; growth tilts toward Polyamide.
Application:
Application maturity determines whether procurement prioritizes processing speed or structural performance.
- Packaging:Case and carton sealing consumes the majority of EMEA hot-melt tonnage. Saudi Arabian e-commerce fulfillment centers in Riyadh and Jeddah drive procurement of low-viscosity formulations compatible with high-speed applicator nozzles.
- Automotive:Structural bonding displaces welding and riveting in lightweight vehicle architectures. German OEMs in Stuttgart specify reactive polyurethane hot-melts for composite body-in-white assembly where dissimilar materials require compliant joint interfaces.
- Electronics:Display lamination and component potting demand ultra-pure grades with ionic contamination below 10 ppm.
- Furniture:Edgebanding and veneer lamination utilize standard EVA formulations with moderate heat resistance requirements.
Revenue concentrates in Packaging; margin expansion favors Automotive.
End User:
End-user regulatory exposure shapes certification requirements and supplier qualification timelines.
- Consumer Goods:Food-contact packaging adhesives require EFSA compliance and migration testing. UAE-based converters serving Gulf retail chains prioritize odor-free formulations meeting strict organoleptic standards for edible product enclosures.
- Healthcare:Medical device bonding demands EMA biocompatibility dossiers and ISO 10993 testing. South African pharmaceutical packaging for Sub-Saharan HIV/AIDS drug distribution requires tropical climate stability validation.
- Manufacturing:General industrial assembly tolerates wider specification ranges with emphasis on cost per bonded unit.
- Construction:Flooring and insulation applications specify moisture-curing reactive grades for structural integrity.
Procurement scale favors Manufacturing; compliance premiums peak in Healthcare.
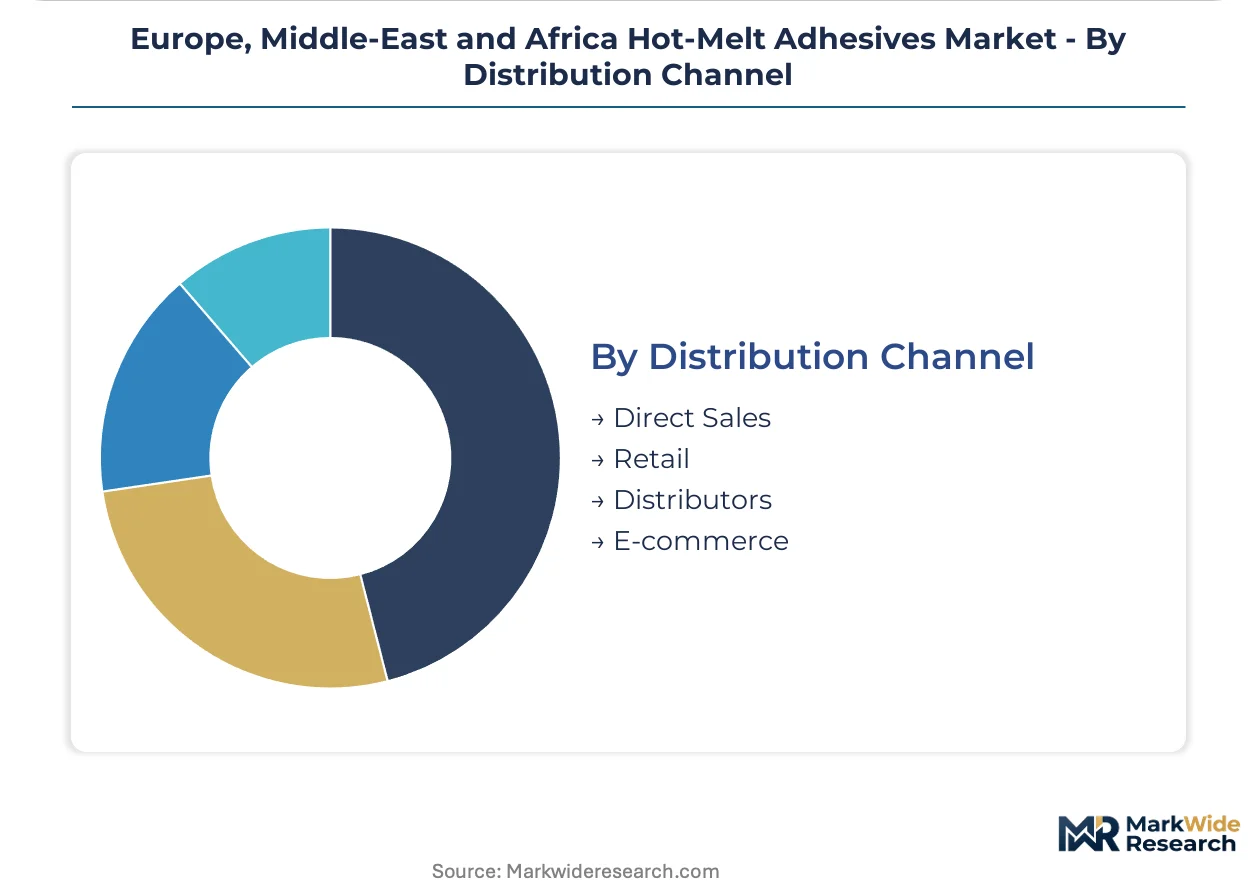
Distribution Channel:
Channel selection reflects buyer technical sophistication and volume scale.
- Direct Sales:Large-volume automotive and packaging converters negotiate formulation customization and technical service integration. Henkel and H.B. Fuller maintain dedicated account teams for German Tier 1 suppliers requiring just-in-time adhesive delivery synchronized to assembly line takt times.
- Distributors:Regional stocking points serve mid-tier converters with standardized grades and localized technical support.
- E-commerce:Small-batch procurement for maintenance and repair operations gains traction among independent furniture manufacturers.
- Retail:Consumer-grade hot-melt sticks and glue guns represent minimal revenue share in professional markets.
Relationship intensity peaks with Direct Sales; geographic coverage expands through Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for hot-melt adhesives concentrates in Germany's automotive corridors and the Gulf Cooperation Council's e-commerce logistics hubs. ECHA compliance deadlines and Saudi industrialization incentives create divergent procurement priorities across the region. Turkey and South Africa emerge as secondary growth poles with distinct regulatory pathways.
Germany
Stuttgart and Munich automotive clusters drive structural bonding demand for electric vehicle battery enclosures. REACH chemical restrictions force formulators to abandon petroleum-based feedstocks before 2030. Henkel and H.B. Fuller maintain dedicated technical service teams for Ruhr Valley corrugated converters operating case sealing lines above 200 units per minute.
Saudi Arabia
Riyadh and Jeddah fulfillment centers scale automated packaging infrastructure for regional e-commerce distribution. SFDA import testing protocols extend registration timelines for non-regional adhesive suppliers. Local converters prioritize low-viscosity formulations compatible with high-speed applicator nozzles in desert climate conditions.
Turkey
Bursa electric vehicle battery pack assemblers specify polyamide hot-melts for thermal management above 150°C. The country's national standardization body enforces product registration requirements that favor established regional suppliers. Istanbul-based packaging machinery OEMs develop heated hose retrofit kits for pneumatic dispensing stations transitioning from aerosol contact adhesives.
South Africa
Pharmaceutical packaging converters serving Sub-Saharan HIV/AIDS drug distribution lack qualified suppliers for tropical climate stability. SAHPRA registration requirements create first-mover exclusivity opportunities for compliant adhesive producers. Cape Town and Johannesburg industrial zones concentrate demand for pressure-sensitive hygiene product lamination.
United Arab Emirates
Dubai and Abu Dhabi logistics hubs anchor Gulf e-commerce procurement volumes for pressure-sensitive formulations. MOHAP enforces strict organoleptic standards for food-contact packaging adhesives serving retail chains. Local converters prioritize odor-free grades meeting EFSA-equivalent migration testing for edible product enclosures.
Europe, Middle-East and Africa Hot-Melt Adhesives Market Competitive Landscape
German producers anchor one tier; Gulf state specialists hold regional distribution advantages. The vendor base separates into consolidated multinationals with integrated resin capabilities and mid-tier formulators serving niche compliance requirements. Three strategic archetypes dominate: integrated chemical conglomerates, regional application specialists, and bio-based feedstock innovators. Capacity expansion and supplier qualification programs constitute the dominant competitive moves as REACH deadlines approach.
Among integrated chemical conglomerates, Henkel AG & Co. KGaA and Arkema Group exemplify the premium-tier positioning. H.B. Fuller Company occupies a position within the regional application specialist archetype. These three anchors represent distinct strategic postures: integrated resin capabilities, high-performance polyamide differentiation, and dedicated EMEA plant networks respectively.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Arkema Group |
| Jowat SE |
| Sika AG |
| Dow Inc. |
| 3M Company |
| Hexcel Corporation |
| Beardow Adams |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon-intensity mandates are forcing formulators to abandon petroleum-based EVA feedstocks and absorb bio-based polyolefin qualification costs. This specification shift compresses margins on legacy formulations while creating premium capture opportunities for ISCC PLUS-certified suppliers.
Pricing Analysis
Volume concentrates in commodity EVA grades where per-kilogram pricing dominates procurement decisions. Three-tier pricing structure across premium, standard, and economy levels separates ISCC PLUS bio-based polyolefins from conventional petroleum grades and unbranded regional imports. Pricing pressure stems from consolidated buying by pan-European packaging groups unbundling adhesive supply from equipment service contracts. Consumer goods converters exhibit highest price sensitivity; healthcare and automotive OEMs prioritize thermal resistance and biocompatibility certification over unit cost.
Supply Chain Analysis
Saudi Arabia's local-content rules and Turkey's national standardization requirements are reshaping sourcing patterns for non-regional suppliers. High-performance polyamide and reactive polyurethane precursor production clusters in Belgium and the Netherlands. Feedstock supply draws from naphtha cracking economics in Northwest Europe and polyolefin resin imports from Gulf state petrochemical complexes. Single-source vulnerability concentrates at the Antwerp-Rotterdam hub where disruption propagates through EMEA medical device supply chains. Distribution runs through direct sales for automotive Tier 1 suppliers and regional distributors serving mid-tier packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-based polyolefin technology is displacing legacy petroleum-based EVA formulations as REACH compliance deadlines approach. This transition phase rewards suppliers with integrated resin capabilities and certified sustainable supply chains.
For Market Incumbents: Lock in automotive OEM qualification lists by securing ECHA pre-registration for bio-based formulations before 2030 compliance deadlines. Backward integration into captive bio-polyolefin production defends margin position against feedstock cost volatility. Prioritize technical service team expansion in Bursa and Stuttgart battery assembly corridors where polyamide specification expertise commands premium pricing. For New Entrants and Emerging Players: The price-point gap between premium ISCC PLUS-certified grades and economy-tier unbranded imports creates white-space opportunity in South African pharmaceutical packaging. Target SAHPRA registration for tropical climate stability formulations serving Sub-Saharan HIV/AIDS drug distribution. Pursue first-mover exclusivity through parallel-track biocompatibility dossiers with EMA and SAHPRA. Lead with digital dispensing integration and cloud-connected equipment leases to differentiate against commodity competitors. For Investors and Strategic Acquirers: The window for entry favors bio-based feedstock innovators with ISCC PLUS chain-of-custody documentation and established Gulf state distributor relationships. Long-term viability centers on suppliers capable of serving divergent EU chemical restrictions and Saudi industrialization incentives simultaneously. Watch for consolidation signals when REACH compliance costs force mid-tier formulators to exit or seek acquisition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Captures margin from petroleum volatility while securing ISCC PLUS certification for EU Green Deal compliance. |
| SAHPRA Registration for Tropical Climate Stability | Unlocks first-mover exclusivity in South African pharmaceutical packaging for Sub-Saharan drug distribution. |
| Digital Dispensing Integration with IoT Sensors | Enables predictive maintenance contracts that differentiate adhesive producers from commodity competitors. |
| Joint Venture with Gulf State Distributors | Accelerates SFDA registration timelines and local-content compliance for Saudi e-commerce fulfillment demand. |
| Reactive Polyurethane Modular Cell Deployment | Collapses equipment procurement cycles for Stuttgart and Bursa automotive Tier 1 suppliers. |
Research Methodology
Multi-period observation of formulation substitution rates, REACH compliance expenditure patterns, and automotive OEM qualification timelines anchored the trend analysis, supplemented by interviews with adhesive plant managers, procurement leads at German corrugated converters, Turkish battery pack assemblers, and Gulf state distribution channel partners. Secondary validation drew from ECHA registration databases, EU customs trade data, SEC 10-K filings of listed chemical conglomerates, and Saudi SFDA import testing protocols. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the EMEA region.
Input-output matrices modeled demand across resin type, application maturity, end-user regulatory exposure, and channel relationship intensity. The projection horizon spans bio-based feedstock adoption curves, automotive lightweighting penetration, and e-commerce packaging infrastructure buildout. CAGRs derived from segment-level growth differentials applied to baseline consumption volumes. Industry-specific forecast inputs included naphtha-ethylene spread volatility and EMA biocompatibility dossier approval timelines.
Underlying measurement precision varies by segment; commodity EVA packaging volumes carry tighter precision than emerging bio-based polyolefin adoption rates. Forecasts reflect assumptions about REACH enforcement consistency and Gulf state industrialization policy continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
2K Epoxy Adhesives Market
Adhesives & Sealants
Europe Acrylic Adhesives Market
Adhesives & Sealants
Glue Pen Market
Adhesives & Sealants
Global Bone Cement and Glue Market
Adhesives & Sealants
Middle East & Africa Automotive Adhesives & Sealants Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
Brazil Adhesives Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Saudi Arabia Adhesives Market
Adhesives & Sealants
Adhesive Equipment Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
Wood Adhesives Market
Adhesives & Sealants
North America Waterborne Adhesives Market
Adhesives & Sealants
North America & Europe Adhesives and Sealants Market
Adhesives & Sealants
Global Contact Adhesives Market