
 Middle East and Africa Plant-Derived and Synthetic Sugar Market | 2026-2036
Middle East and Africa Plant-Derived and Synthetic Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Plant-Derived and Synthetic Sugar Market Foresight
Single-serve and portion-controlled packaging is pivoting how foodservice and retail buyers evaluate sweetener procurement. Cargill Incorporated leverages its regional ingredient supply infrastructure to anchor bulk stevia and erythritol distribution across North African processing hubs. Tate and Lyle Plc differentiates through specialized reformulation services that help beverage manufacturers reduce sugar without compromising sensory profiles. Archer Daniels Midland Company sustains competitive positioning via backward integration into corn-based polyol production, securing cost advantages in synthetic sugar alcohol supply.
The Middle East and Africa Plant-Derived and Synthetic Sugar category encompasses caloric and non-caloric sweetening agents extracted from botanical sources or manufactured through chemical and enzymatic processes, typically achieving sweetness intensities ranging from 0.7 to 600 times that of sucrose with specified particle sizes and purity grades for industrial blending. These inputs serve primarily to reduce caloric content, extend shelf stability, and manage glycemic response in processed foods and beverages. Natural Sweeteners and Stevia segments command premium positioning as clean-label demand from Gulf retail channels reshapes supplier priorities, while Sugar Alcohols occupies the fastest-expanding functional niche in sugar-free confectionery and oral care applications across Egyptian and Moroccan manufacturing zones. Artificial Sweeteners retains volume dominance in mass-market carbonated soft drinks where cost thresholds override label preference, though margin compression from input volatility limits supplier flexibility.
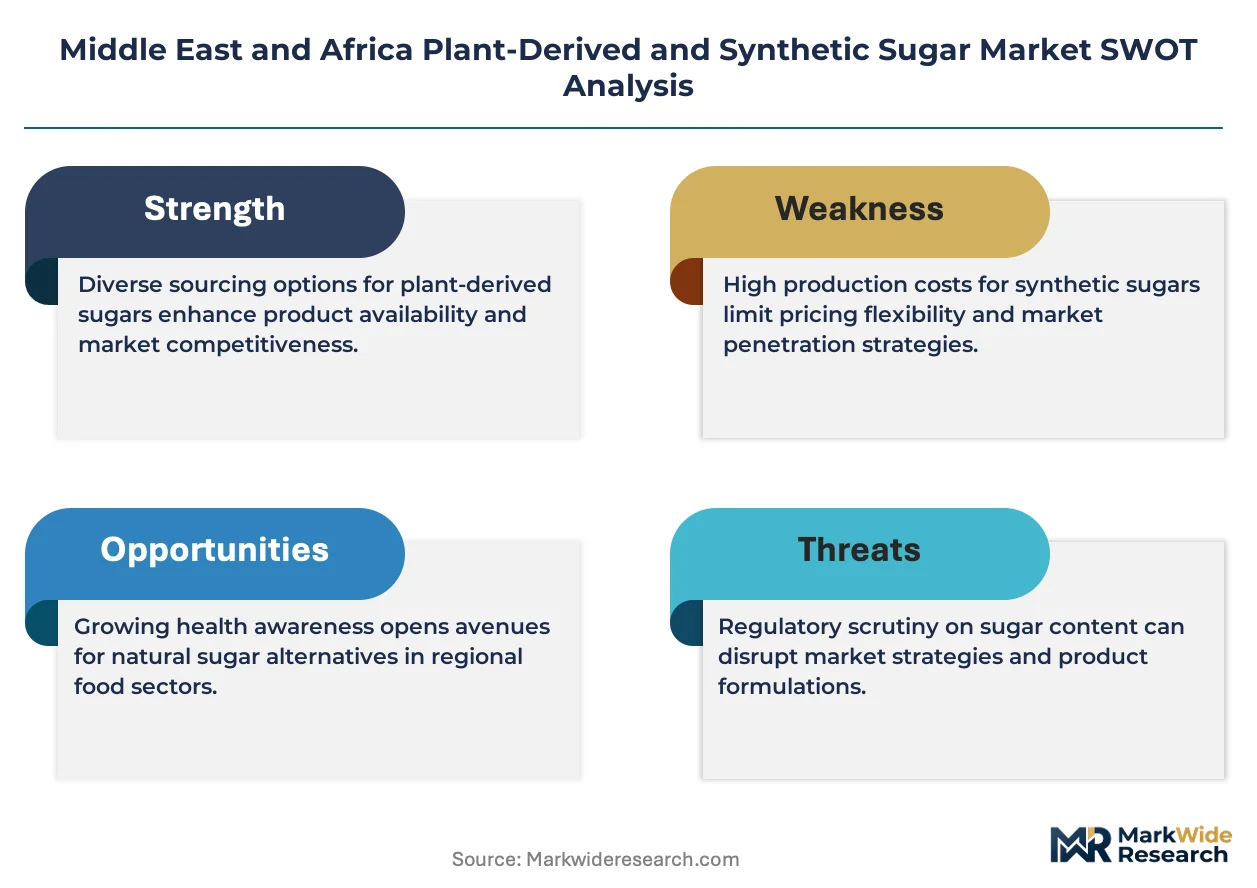
South Africa's National Treasury sugar tax framework, Egypt's food additive standards administered by the national food safety authority, and Gulf Standardization Organization sweetener specifications collectively determine product registration timelines and reformulation requirements across the regional trade corridor. Compliance with these overlapping regimes necessitates dedicated regulatory affairs capacity and localized stability testing protocols. Stakeholders must monitor evolving excise structures and halal certification requirements for enzymatic processing methods to anticipate which sweetener platforms will retain formulation access in priority markets.
Market Dynamics
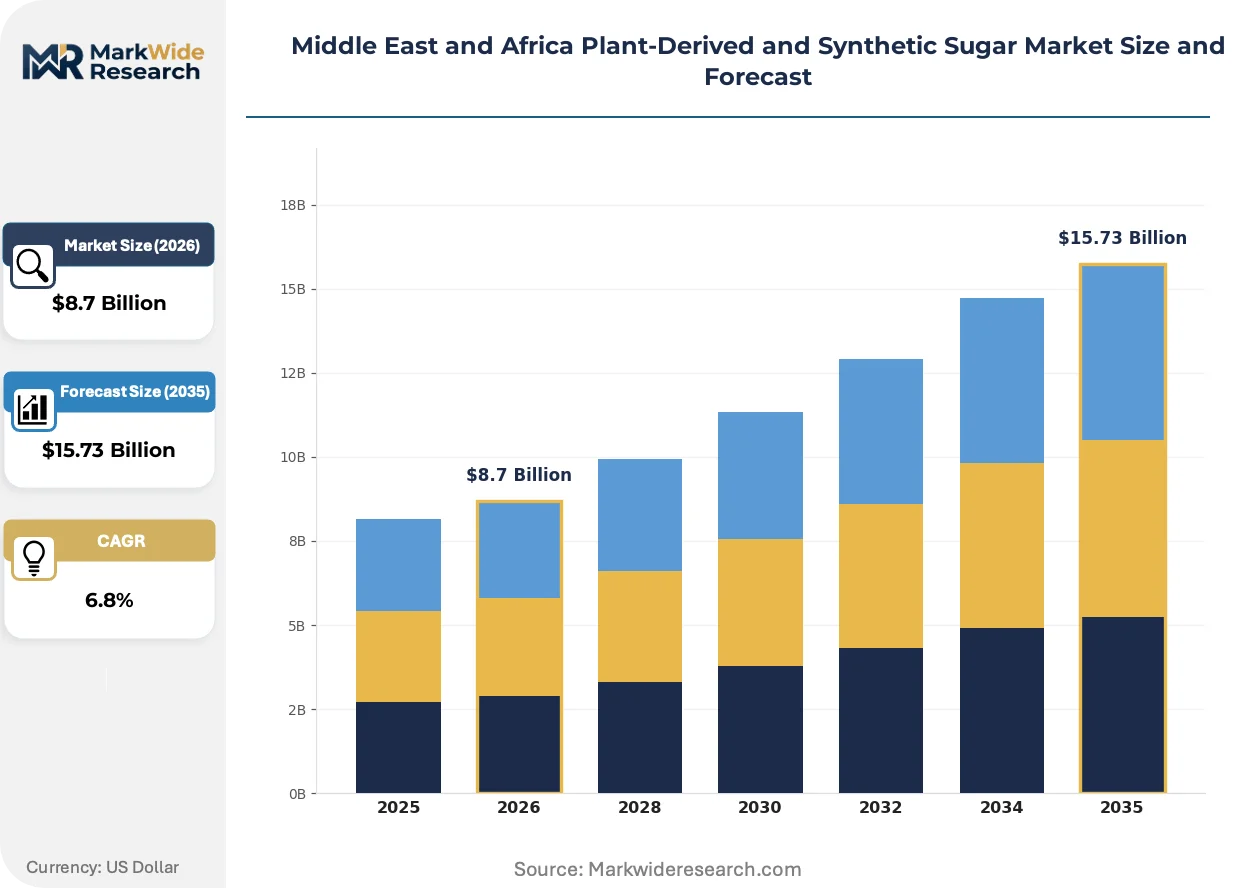
South Africa's sugar-sweetened beverage levy and Egypt's expanding food processing clusters are redirecting procurement toward plant-derived alternatives, compressing synthetic sugar alcohol margins while elevating stevia and erythritol formulation volumes across North African beverage operations.
Growth Catalysts
- South Africa's National Treasury sugar tax framework:Beverage manufacturers across Johannesburg and Cape Town are accelerating reformulation timelines to avoid excise penalties, expanding stevia and sucralose blending capacity in regional bottling plants.
- Gulf Cooperation Council confectionery demand:Clean-label positioning in Saudi and UAE retail channels is displacing artificial sweeteners in premium chocolate and gum categories, with halal-certified enzymatic processing methods gaining formulation preference.
- Egyptian food additive standards:The national food safety authority's streamlined registration protocols for plant-derived sweeteners are attracting ingredient distributors to Cairo and Alexandria processing zones, shortening time-to-market for erythritol and monk fruit extracts.
Market Restraints
- Corn price volatility:Archer Daniels Midland's captive sorbitol and maltitol production faces margin pressure from feedstock cost swings, limiting synthetic sugar alcohol pricing flexibility in mass-market applications.
- Stevia leaf supply concentration:Raw material sourcing clusters in China's Fujian and Yunnan provinces create geographic single-point vulnerability for Middle East and Africa blenders dependent on imported Reb-A extracts.
- Technical formulation barriers:Bitterness masking in high-intensity stevia applications requires proprietary taste-modulation systems that smaller Egyptian and Nigerian beverage manufacturers lack in-house capability to develop.
Strategic Opportunities
- Moroccan oral care manufacturing:Sugar-free toothpaste and mouthwash production in Casablanca's industrial zones represents underpenetrated demand for xylitol and sorbitol, with European export qualification standards driving ingredient quality premiums.
- Nigerian soft drink sector expansion:Lagos and Kano bottling operations are piloting allulose-sweetened carbonated variants targeting diabetic consumer segments, creating first-mover positioning for suppliers with local blending infrastructure.
- Gulf Standardization Organization halal certification:Streamlined enzymatic processing verification for polyol production is reducing compliance friction for UAE and Saudi food additive registrations, accelerating market access for compliant suppliers.
Industry Challenges
- Reformulation technical talent scarcity:Beverage manufacturers in Cairo and Johannesburg struggle to recruit food scientists with specialized expertise in sweetness modulation and sensory profiling for reduced-sugar systems.
- Stability testing protocol fragmentation:Divergent shelf-life validation requirements between South Africa's national treasury framework and Egypt's food safety authority create redundant certification costs for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Plant-Derived and Synthetic Sugar Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Sweeteners, Artificial Sweeteners, Sugar Alcohols, Stevia Application: Beverages, Bakery, Confectionery, Dairy End User: Food Industry, Beverage Manufacturers, Pharmaceutical, Cosmetics Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Food Stores |
| Companies Covered | Tate and Lyle Plc, Cargill Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Roquette, Tereos S.A, CJ CheilJedang, Celanese, DuPont Nutrition and Health, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Plant-Derived and Synthetic Sugar Market Shifts & Advancements
Enzymatic bioconversion platforms and precision fermentation are compressing production economics for rare sugars, while regulatory harmonization pressures and clean-label retail positioning are forcing simultaneous reformulation across multiple sweetener categories.
Enzymatic stevia glycoside conversion is consolidating cost structures for Reb-M and Reb-D production, which deliver superior taste profiles without bitter aftertaste. Egyptian and UAE beverage formulators are adopting these second-generation extracts at accelerating rates for premium positioning. The technology is consolidating supplier margins around bioconversion capability, disadvantaging simple leaf-extraction operations.
South Africa's National Treasury sugar tax framework is tightening excise thresholds annually, compelling Johannesburg bottlers to accelerate zero-sugar line extensions. The policy is compressing artificial sweetener tolerance in mainstream carbonated drinks, with aspartame and acesulfame-K formulations losing shelf space to stevia-sucralose blends. Nigerian and Kenyan manufacturers are monitoring this regulatory trajectory for anticipatory reformulation.
Foodservice operators across Dubai and Riyadh are unbundling sweetener specification from bundled ingredient procurement, demanding discrete stevia and erythritol SKUs for in-house beverage preparation. This disintermediation is compressing distributor margins while elevating direct supplier relationships with hotel chains and quick-service restaurant groups. The pattern is most visible in Gulf Cooperation Council hospitality procurement, where procurement teams now specify sweetness intensity and particle size independently.
Middle East and Africa Plant-Derived and Synthetic Sugar Market Segmentation
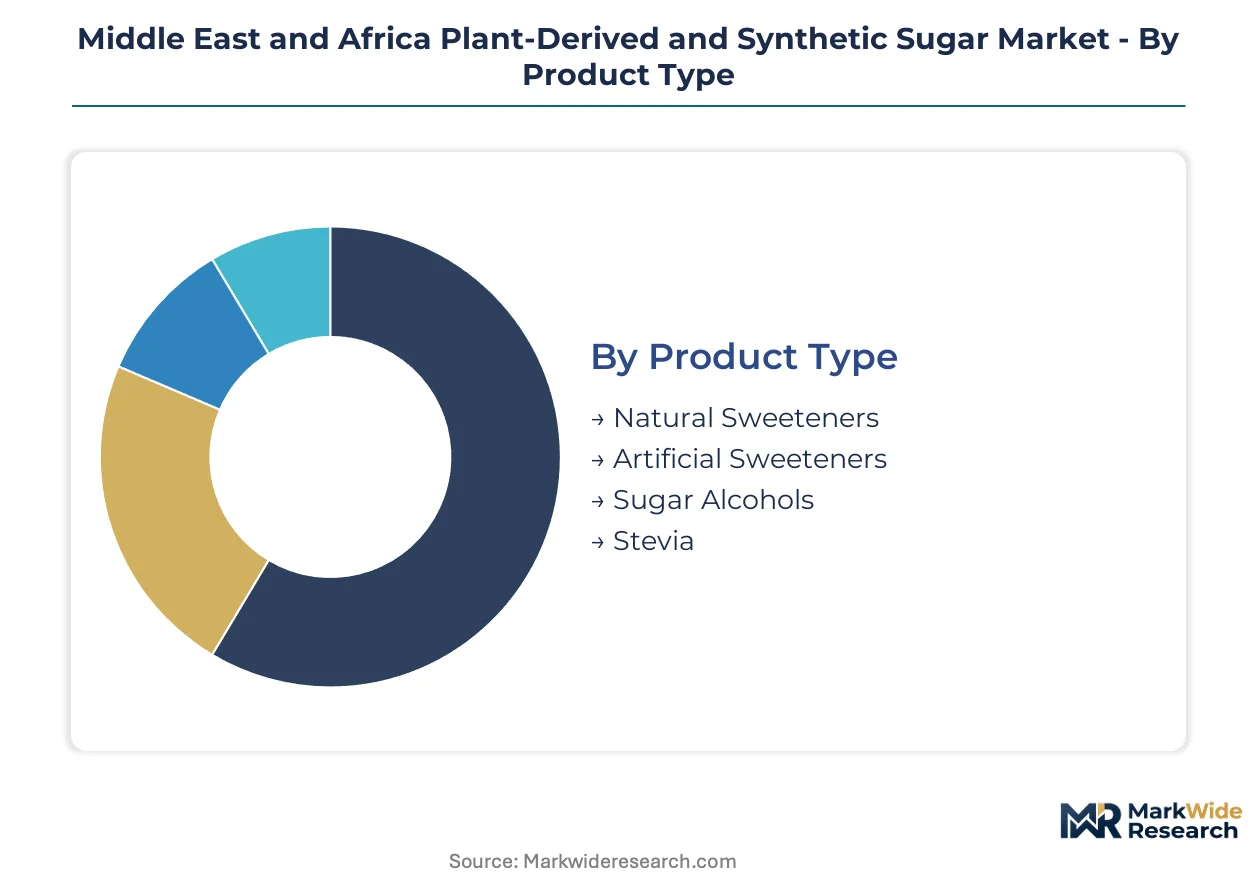
Plant-derived and synthetic sugar procurement across the Middle East and Africa varies sharply by whether sweeteners enter as standalone ingredients or embedded within finished formulations. Beverage manufacturers in Johannesburg and Cairo prioritize discrete high-intensity extracts for in-house blending, while Gulf retail channels increasingly demand pre-formulated clean-label systems.
Product Type:
Stevia and sugar alcohols function predominantly as standalone inputs requiring technical formulation support, whereas artificial sweeteners embed more readily into turnkey beverage concentrates supplied by regional distributors.
- Natural Sweeteners:Monk fruit and thaumatin extracts deliver 150-300x sucrose sweetness with minimal caloric contribution. Egyptian dairy processors in Alexandria are integrating these into reduced-sugar yogurt lines to meet Gulf Standardization Organization export requirements for clean-label positioning.
- Artificial Sweeteners:Aspartame, acesulfame-K, and sucralose dominate mass-market carbonated soft drinks through cost-optimized blending protocols. Lagos bottling operations rely on these for price-competitive cola variants targeting Nigeria's value-conscious retail sector.
- Sugar Alcohols:Xylitol, erythritol, and maltitol provide bulk sweetness with reduced glycemic impact in sugar-free confectionery. Moroccan oral care manufacturers in Casablanca source pharmaceutical-grade sorbitol for European-export toothpaste production.
- Stevia:Reb-A and enzymatically converted Reb-M glycosides command premium positioning in Gulf Cooperation Council retail channels. Saudi chocolate and gum producers specify halal-certified enzymatic processing methods to satisfy clean-label demand.
Artificial sweeteners lead volumes today; stevia is gaining share fastest.
Application:
Cost tier stratification separates commodity beverage formulations from premium bakery and confectionery segments where ingredient specification drives margin capture.
- Beverages:Carbonated soft drinks, flavored waters, and juice concentrates represent the dominant volume outlet. South Africa's National Treasury sugar tax framework compels Johannesburg bottlers to accelerate reformulation toward stevia-sucralose blends.
- Bakery:Reduced-sugar breads and pastries require bulking agents to maintain moisture and texture profiles. Egyptian industrial bakeries in Cairo are piloting erythritol-maltitol combinations for diabetic-friendly product lines.
- Confectionery:Sugar-free chocolates, chewing gums, and hard candies depend on precise sweetness modulation and cooling-effect management. UAE retail channels are displacing artificial sweeteners in premium chocolate categories.
- Dairy:Yogurt, ice cream, and flavored milk applications demand heat-stable sweetening systems. Nigerian dairy processors in Kano are testing allulose for reduced-calorie cultured milk variants.
Beverages command the largest volume footprint; confectionery offers the steepest margin expansion trajectory.
End User:
Customer type determines whether procurement flows through technical ingredient distributors or direct supplier relationships with formulation support.
- Food Industry:Industrial bakeries, snack manufacturers, and prepared food processors source bulk polyols and high-intensity sweeteners through regional distributors. Moroccan and Egyptian food processing clusters are consolidating procurement around stevia and erythritol.
- Beverage Manufacturers:Bottling operations in Lagos, Johannesburg, and Riyadh demand discrete SKU specifications for sweetness intensity and particle size. Gulf hospitality procurement teams are unbundling sweetener specification from bundled ingredient sourcing.
- Pharmaceutical:Excipient-grade sugar alcohols for syrups, chewable tablets, and lozenges require pharmacopeia compliance. Casablanca's industrial zones are expanding xylitol and sorbitol capacity for European export qualification.
- Cosmetics:Oral care and personal care applications utilize sugar alcohols for humectant and sweetening functions. Dubai-based personal care manufacturers specify halal-certified polyol supply chains.
Beverage manufacturers dominate current procurement volumes; pharmaceutical applications are climbing the fastest.
Distribution Channel:
Supply concentration in import-dependent markets creates divergent channel economics between bulk industrial procurement and fragmented retail access.
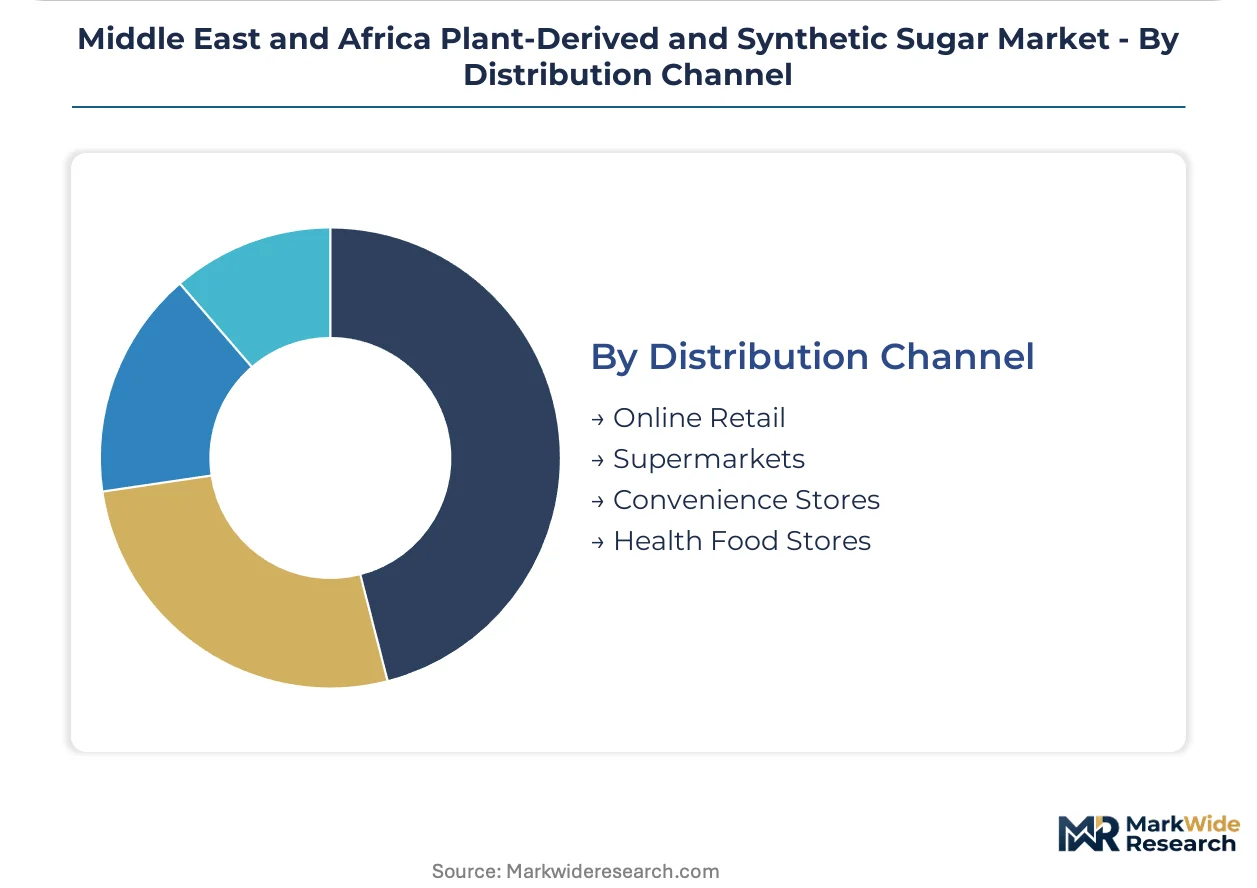
- Online Retail:E-commerce platforms serve small-scale foodservice operators and health-conscious consumers with packaged stevia and monk fruit extracts. UAE and Saudi digital grocery expansion is accelerating direct-to-kitchen sweetener sales.
- Supermarkets:Hypermarket chains across the Gulf Cooperation Council stock consumer-packaged sugar alternatives alongside conventional sweeteners. Clean-label positioning is displacing artificial sweeteners from premium shelf placements.
- Convenience Stores:Small-format retail in Nigeria and Kenya distributes single-serve sachets for immediate consumption. Price compression limits penetration of premium plant-derived options in this channel.
- Health Food Stores:Specialty retailers in South Africa and UAE cater to diabetic and ketogenic consumer segments with curated natural sweetener assortments. Johannesburg's independent health food sector is expanding stevia and allulose SKUs.
Supermarkets anchor volume distribution today; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial sugar cultivation and early industrial sweetener processing in the Middle East and Africa trace to colonial-era cane estates in South Africa and Egypt's Nile Delta, establishing infrastructure that now pivots toward enzymatic bioconversion and plant-derived extraction.
South Africa
Johannesburg bottlers drive stevia-sucralose blending capacity expansion to comply with the National Treasury's escalating sugar-sweetened beverage levy. The country's food safety authority coordinates stability testing protocols with excise enforcement timelines. Cape Town's food processing corridor attracts regional distributors seeking localized reformulation support.
Egypt
Alexandria dairy processors integrate monk fruit extracts into reduced-sugar yogurt lines for Gulf Standardization Organization export qualification. The national food safety authority streamlined plant-derived sweetener registration to shorten Cairo ingredient distributors' time-to-market. Industrial bakeries in Cairo pilot erythritol-maltitol combinations for diabetic-friendly product development.
United Arab Emirates
Dubai hospitality procurement teams unbundle sweetener specification from bundled ingredient sourcing, demanding discrete stevia SKUs with defined particle sizes. The Ministry of Health and Prevention administers halal certification for enzymatic processing methods. Riyadh-adjacent suppliers leverage UAE logistics hubs for Saudi confectionery market access.
Saudi Arabia
Saudi chocolate and gum producers specify halal-certified enzymatic Reb-M glycosides to satisfy clean-label retail positioning. The Saudi Food and Drug Authority enforces Gulf Standardization Organization sweetener specifications across domestic manufacturing. Jeddah's industrial zones concentrate sugar-free confectionery capacity targeting premium domestic consumption.
Nigeria
Lagos bottling operations pilot allulose-sweetened carbonated variants for diabetic consumer segments in Africa's largest soft drink market. The national food safety regulator maintains additive standards that lag regional counterparts, creating first-mover positioning for suppliers with local blending infrastructure. Kano dairy processors test reduced-calorie cultured milk applications.
Middle East and Africa Plant-Derived and Synthetic Sugar Market Competitive Landscape
Premium-margin players sit above commodity-margin players across enzymatic bioconversion capability and halal-certified supply chain verification. The vendor base stratifies between multinational ingredient conglomerates with captive raw material sourcing and regional distributors dependent on imported extracts. Three archetypes dominate: backward-integrated polyol producers, specialized reformulation service providers, and commodity traders with logistics infrastructure. Competitive moves concentrate on strategic partnerships with Gulf hospitality procurement teams and capacity expansion in Egyptian processing zones.
Within the multinational conglomerate tier, Tate and Lyle Plc and Cargill Incorporated exemplify divergent positioning strategies. Tate and Lyle Plc occupies a position emphasizing specialized reformulation services that help beverage manufacturers reduce sugar without compromising sensory profiles. Cargill Incorporated anchors bulk stevia and erythritol distribution through regional ingredient supply infrastructure across North African processing hubs. Archer Daniels Midland Company represents the backward-integrated archetype, sustaining competitive positioning via in-house production of corn-based polyols.
| Leading Market Players |
|---|
| Tate and Lyle Plc |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Roquette |
| Tereos S.A |
| CJ CheilJedang |
| Celanese |
| DuPont Nutrition and Health |
| Others |
Supply & Pricing Matrix
Halal certification for enzymatic processing methods gates both qualified supply and premium-tier pricing access across Middle East and Africa sweetener markets, with Saudi Food and Drug Authority and Gulf Standardization Organization standards separating compliant suppliers from commodity traders. Manufacturers lacking verified bioconversion capabilities face exclusion from Gulf Cooperation Council retail channels while certificate holders command 15-25% price premiums on Reb-M glycosides and pharmaceutical-grade polyols.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by enzymatic conversion capability and certification grade. Premium tiers capture halal-certified Reb-M and pharmaceutical-grade erythritol for Saudi chocolate and UAE oral care applications, while standard tiers serve Egyptian industrial bakeries with conventional Reb-A extracts. Cost compression in synthetic sugar alcohols is intensifying because Archer Daniels Midland's captive corn-based production faces feedstock volatility. Mass-market carbonated bottlers in Lagos exhibit highest price sensitivity, whereas Dubai hospitality procurement teams prioritize sensory performance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for enzymatic processing verification certificates and halal audit documentation create compliance documentation loops between Chinese extraction facilities and Gulf destination markets. Raw material sourcing clusters in China's Fujian and Yunnan provinces, combined with Egyptian redistributor consolidation in Cairo and Alexandria, tether finished sweetener supply to Asian leaf supply concentration. Single-source vulnerability in stevia leaf procurement exposes Middle East and Africa blenders to geographic concentration risk. Distribution runs through regional ingredient distributors with localized reformulation support rather than direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Gulf retail channel clean-label positioning is forcing simultaneous premium specification upgrades across stevia and sugar alcohol categories.
For Market Incumbents: To counter margin compression from corn price volatility and Chinese leaf supply concentration, Tate and Lyle Plc and Cargill Incorporated should deepen backward integration into enzymatic bioconversion capabilities and secure captive halal-certified production capacity in Egyptian processing zones. Channel control through direct relationships with Dubai hospitality procurement teams offers defensive positioning against distributor disintermediation. For New Entrants and Emerging Players: Small-scale Nigerian beverage manufacturers lacking in-house bitterness masking expertise represent the most penetrable buyer archetype for specialized reformulation service providers. Moroccan oral care manufacturing in Casablanca's industrial zones offers white-space demand for pharmaceutical-grade xylitol suppliers with European export qualification capabilities. A technical service-led go-to-market approach differentiates against commodity traders. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors dependent on imported extracts without enzymatic processing verification or halal certification infrastructure. Long-term viability over the next decade hinges on bioconversion capability ownership rather than simple trading relationships. The signal to watch is accelerating Gulf Standardization Organization harmonization of enzymatic processing standards, which will consolidate supplier margins around compliant operations.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Investment | Gulf Standardization Organization compliance unlocks Saudi and UAE retail channel access for enzymatic Reb-M glycosides. |
| Enzymatic Bioconversion Capacity Expansion | Second-generation stevia extracts with superior taste profiles command premium positioning in Egyptian and Gulf beverage operations. |
| Backward Integration into Corn-Based Polyol Production | Captive sorbitol and maltitol supply insulates against feedstock cost volatility in North African mass-market applications. |
| Direct Hospitality Procurement Relationships | Dubai and Riyadh hotel chains now specify discrete sweetener SKUs, bypassing traditional distributor bundling. |
| Pharmaceutical-Grade Polyol Qualification | European export standards for Casablanca oral care manufacturing drive xylitol and sorbitol quality premiums. |
Research Methodology
Multiple input streams — regulatory filing analysis, customs and trade flow data, and primary field engagement — were reconciled to construct segment-level demand estimates across the Middle East and Africa Plant-Derived and Synthetic Sugar Market. Beverage formulation directors at Johannesburg and Lagos bottling operations, Egyptian dairy processors in Alexandria, and procurement leads at Saudi confectionery manufacturers provided operational validation. Secondary sources included Gulf Standardization Organization sweetener specifications, South Africa National Treasury excise enforcement documentation, Egyptian food safety authority registration protocols, and regional ingredient distributor financial disclosures. Bottom-up volume builds by application and end-user category were cross-checked against top-down market sizing from trade flow analysis.
Data-stream reconciliation across primary interview transcripts and secondary validation sources anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled encompassed product type (natural sweeteners, artificial sweeteners, sugar alcohols, stevia), application (beverages, bakery, confectionery, dairy), end-user category (food industry, beverage manufacturers, pharmaceutical, cosmetics), and distribution channel (online retail, supermarkets, convenience stores, health food stores). CAGRs were derived from trend extrapolation of excise policy trajectories and clean-label retail penetration curves, with enzymatic bioconversion adoption rates and halal certification compliance timelines serving as industry-specific forecast inputs.
Underlying measurement precision varies by segment; beverage applications and Gulf Cooperation Council geographies carry tighter precision than pharmaceutical cosmetics crossovers or fragmented Nigerian retail channels. Forecasts reflect assumptions around regulatory harmonization pace and enzymatic processing cost reduction trajectories that could shift materially with Chinese leaf supply disruptions or accelerated South African sugar tax escalation. Practitioners should monitor Gulf Standardization Organization halal certification protocol updates and South African National Treasury excise threshold announcements for early signals of supplier consolidation or reformulation acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Natural Stevia Market
Sweeteners
Oligofructose Market
Sweeteners
Mexico Food Sweetener Market
Sweeteners
Asia-Pacific Starch Sweetener Market
Sweeteners
Glucose-Fructose Syrup (GFS) Market
Sweeteners
Caramelized Sugars Market
Sweeteners
Stevia Mints Market
Sweeteners
Clarified Rice Syrup Market
Sweeteners
Global Plant-Derived and Synthetic Sugar Market
Sweeteners
Fructose Market
Sweeteners
Raw Beetroot Sugar Market
Sweeteners
Compressible Sugar Market
Sweeteners
Plant-Derived Sweetener Market
Sweeteners
Erythritol Market
Sweeteners
Nutritive Sweeteners Market
Sweeteners
Europe Sugar Substitute Market