
 Asia-Pacific Starch Sweetener Market | 2026-2036
Asia-Pacific Starch Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Starch Sweetener Market Outlook
ISO 22000 certification is unwinding competitive access across the Asia-Pacific starch sweetener supply base, filtering out smaller domestic refiners lacking hazard-analysis documentation. Cargill Incorporated leverages its integrated corn-milling footprint across Thailand and Australia to sustain bulk dextrose supply to regional beverage bottlers. Tate & Lyle PLC anchors specialty maltodextrin output for sports-nutrition brands, while Matsutani Chemical Industry Co., Ltd dominates reduced-calorie syrup formulations through its polyol-starch hybrid R&D pipeline in Japan.
Starch sweeteners comprise enzymatically or acid-hydrolyzed carbohydrate derivatives—typically glucose equivalency ratings from 20 to 100—serving as bulk sweetening, bulking, and moisture-retention agents in processed foods. High fructose corn syrup retains volume leadership across beverage applications, though margin compression in carbonated soft drinks is pushing refiners toward higher-value dextrose crystalline grades for pharmaceutical excipient use. Maltodextrin competes aggressively within confectionery and dairy powder systems where low hygroscopicity and clean flavor profiles command price premiums over conventional glucose syrups.
FSSAI in India, China's SAMR, and Japan's Ministry of Health, Labour and Welfare collectively enforce tightening purity specifications and added-sugar disclosure rules that reshape formulation procurement across the region. These frameworks elevate demand for certified-low-DE maltodextrin and non-GMO corn-derived dextrose as manufacturers preempt compliance costs. Stakeholders must monitor divergence between national sweetener labeling regimes to avoid stranded inventory in cross-border food-manufacturing networks.
Market Dynamics
ISO 22000 certification requirements are filtering Asia-Pacific starch sweetener supply chains, systematically excluding smaller domestic refiners lacking documented hazard-analysis protocols and consolidating procurement around certified integrated millers.
Growth Catalysts
- India's FSSAI mandatory labeling:Added-sugar disclosure rules force reformulation trials, accelerating clean-label maltodextrin and dextrose adoption across processed food manufacturers.
- Sports-nutrition powder systems:Low-DE maltodextrin demand concentrates in Japan and Australia as brands prioritize clean flavor profiles and moisture stability in protein formulations.
- Enzymatic hydrolysis advances:Next-generation glucoamylase processes improve glucose equivalency precision, enabling pharmaceutical-grade crystalline dextrose output from corn wet-milling operations.
Market Restraints
- Corn input cost volatility:Feedstock price swings in Thailand and Australia compress refiner margins, particularly for bulk high-fructose corn syrup producers serving carbonated beverage bottlers.
- Supply concentration in Java-Sumatra corridor:Indonesia's processed food manufacturers face single-source dependency risks as regional refining capacity clusters on specific islands.
- Technical ceiling in polyol-starch hybrids:Reduced-calorie syrup formulations encounter sensory limitations at higher replacement ratios, constraining clean-label sugar reduction claims.
Strategic Opportunities
- Vietnam's underpenetrated confectionery sector:Dairy powder and candy manufacturers present untapped demand for low-hygroscopicity maltodextrin as production scales toward export markets.
- China's SAMR purity specification tightening:Non-GMO corn-derived dextrose certification creates premium positioning for refiners preempting compliance cost escalation.
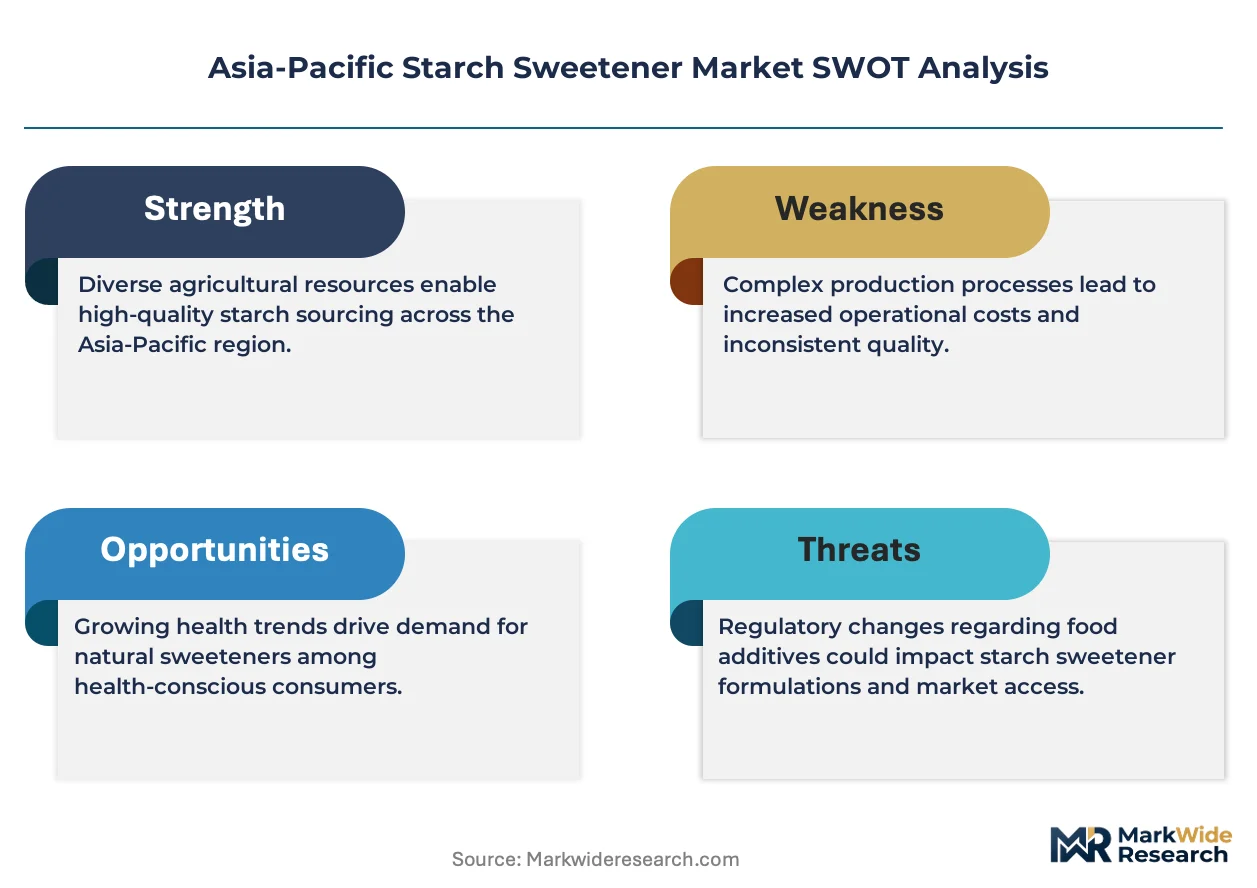
- E-commerce ingredient procurement platforms:Direct-to-manufacturer channels disintermediate traditional distributor networks, enabling smaller food tech startups to source certified sweeteners at reduced minimum order thresholds.
Industry Challenges
- ISO 22000 documentation burden:Hazard-analysis critical control point systems require 12-18 month implementation timelines, straining mid-scale refiners without dedicated quality assurance infrastructure.
- Legacy glucose syrup tank infrastructure:Existing storage and transport systems designed for high-fructose formulations demand capital-intensive retrofitting to handle crystalline dextrose slurries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Starch Sweetener Market |
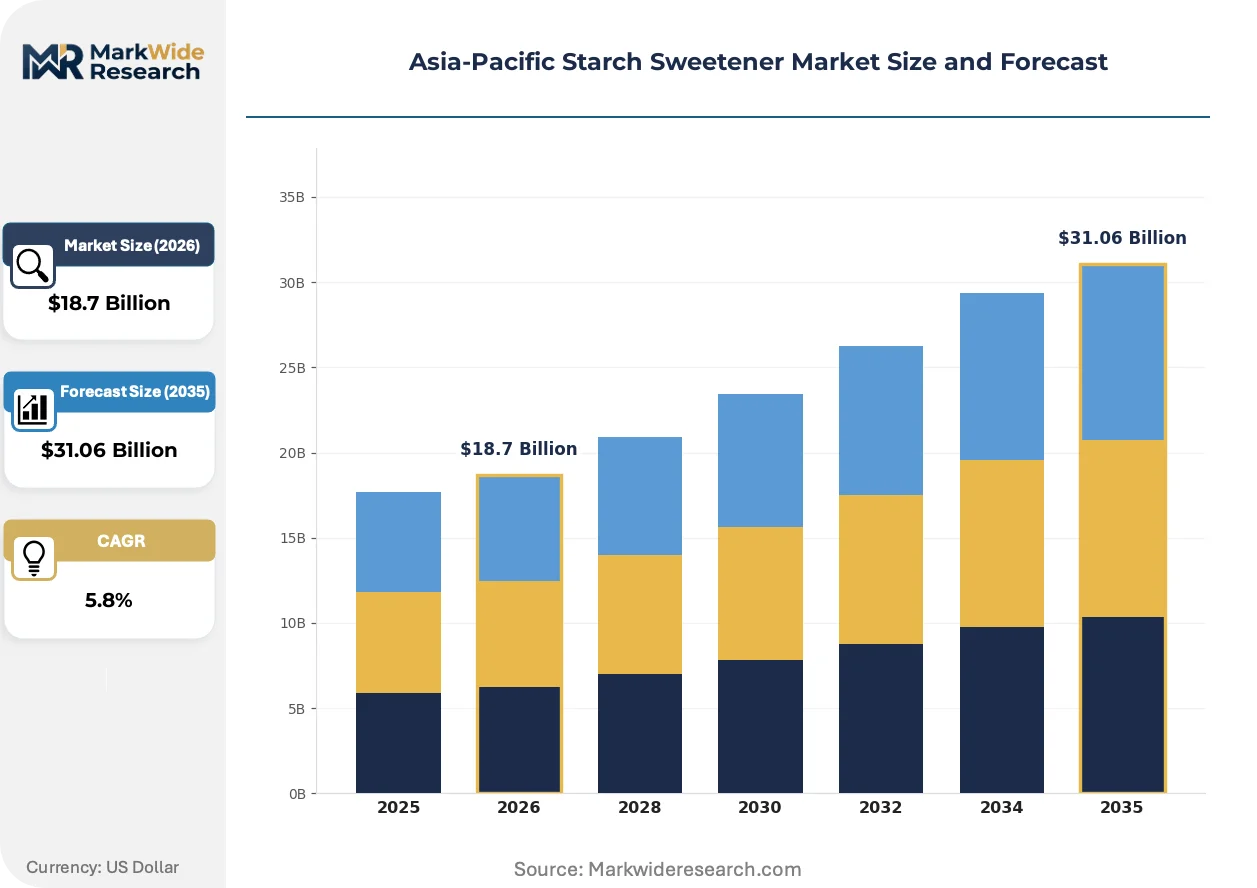
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Fructose Corn Syrup, Maltodextrin, Dextrose, Cellulose Application: Beverages, Confectionery, Bakery, Dairy End User: Food Manufacturers, Beverage Companies, Nutraceuticals, Pharmaceutical Firms Distribution Channel: Online Retail, Wholesale, Supermarkets, Direct Sales |
| Companies Covered | Ingredion Inc., Roquette Frères, Cargill Incorporated, Matsutani Chemical Industry Co., Ltd, E. I. du Pont de Nemours and Company, The Archer Daniels Midland Company, Tate & Lyle PLC, Sukhjit Starch & Chemicals Ltd., Tereos SA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Starch Sweetener Market Strategic Shifts
Enzyme engineering and regulatory disclosure mandates are compressing formulation cycles across Asia-Pacific food manufacturing, forcing simultaneous adaptation in production technology and procurement protocols.
Immobilized enzyme reactor technology is miniaturizing starch hydrolysis unit operations, enabling modular refinery deployments that reduce capital intensity for mid-scale producers. Indonesian and Vietnamese food ingredient manufacturers are piloting containerized enzymatic systems to localize dextrose production near confectionery clusters. This distributed processing architecture is compressing logistics costs and inventory carrying requirements for regional sweetener supply chains.
FSSAI's added-sugar labeling mandate in India is compelling reformulation documentation that traces sweetener provenance through supply chain tiers. Food manufacturers must now maintain batch-level certification records linking corn origin to final glucose equivalency ratings. Confectionery and dairy powder segments are responding by consolidating supplier bases around integrated millers with captive traceability systems.
Direct procurement from certified refiners is displacing layered distributor networks across Southeast Asia's processed food corridor. Large beverage bottlers in Thailand and Indonesia are negotiating volume commitments with corn wet-millers, extracting price transparency previously obscured by intermediary markups. This channel compression is most visible in Java's industrial zones, where manufacturer-refiner partnerships now govern bulk dextrose supply scheduling.
Asia-Pacific Starch Sweetener Market Segmentation
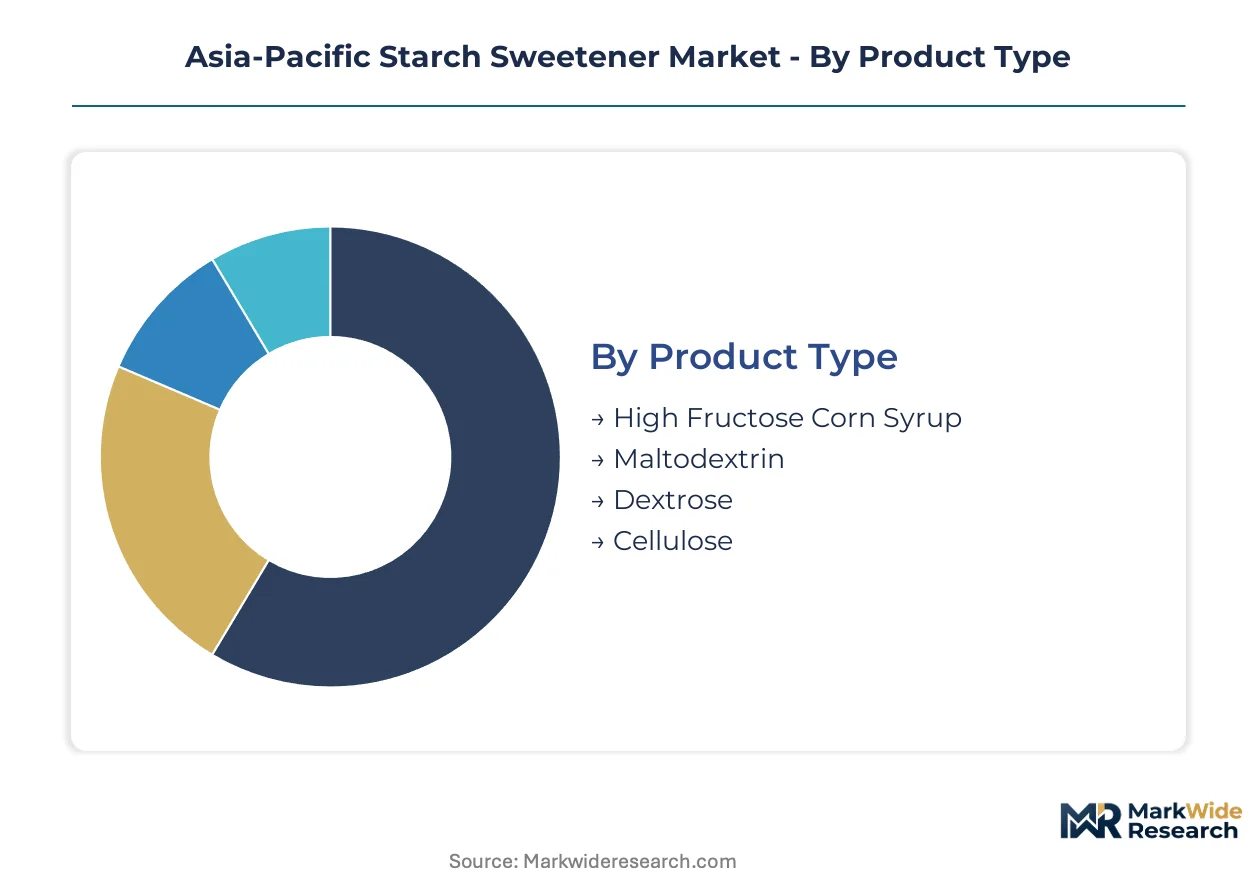
Starch sweetener procurement patterns diverge sharply across product chemistry and end-use specifications. Manufacturers configure supply contracts around glucose equivalency ratings, moisture sensitivity thresholds, and regulatory certification tiers rather than commodity pricing alone.
Product Type:
Margin pools concentrate in specialty carbohydrate derivatives where enzymatic precision commands technical premiums over bulk syrup formulations.
- High Fructose Corn Syrup:Fructose-glucose blends with 42% to 55% fructose content serve as the primary sweetening agent in carbonated beverages. Thai and Indonesian bottlers anchor volume offtake, though reformulation pressures are compressing per-unit margins as manufacturers reduce added-sugar declarations.
- Maltodextrin:Low-dextrose-equivalency polysaccharides (DE 10-20) deliver clean flavor profiles and moisture stability critical to sports-nutrition powders. Japanese and Australian brands drive specification tightening for pharmaceutical-grade material with batch-level corn provenance documentation.
- Dextrose:Crystalline glucose monohydrate and anhydrous grades function as pharmaceutical excipients and confectionery bulking agents. India's FSSAI labeling mandates are accelerating clean-label dextrose trials across Mumbai and Delhi processed food corridors.
- Cellulose:Microcrystalline and powdered cellulose variants provide non-caloric fiber fortification and textural modification in reduced-sugar bakery applications.
High fructose corn syrup holds installed capacity. Maltodextrin is rotating up the share rankings.
Application:
End-use concentration patterns reflect divergent technical requirements for moisture retention, browning control, and sweetness intensity modulation.
- Beverages:Liquid syrup systems dominate carbonated soft drinks and ready-to-drink tea formulations. Thailand's integrated bottling clusters sustain bulk dextrose offtake, though sugar reduction targets are forcing partial reformulation toward lower-calorie alternatives.
- Confectionery:Hard candy, gummies, and chocolate coatings demand precise glucose-fructose ratios for crystallization control and humectancy. Vietnam's expanding candy export sector presents untapped specification demand for low-hygroscopicity maltodextrin.
- Bakery:Bread and pastry applications leverage reducing sugar content for Maillard browning and crumb moisture retention. Indonesia's Java-based industrial bakeries cluster procurement around certified non-GMO corn derivatives.
- Dairy:Ice cream and yogurt systems utilize maltodextrin for freezing point depression and mouthfeel enhancement without excessive sweetness. Australian dairy powder exporters specify low-DE grades for clean-label positioning in Asian markets.
Beverages retain volume leadership. Confectionery is climbing the fastest.
End User:
Procurement sophistication varies with scale and regulatory exposure, fragmenting supplier relationship models across customer tiers.
- Food Manufacturers:Processed food conglomerates in Indonesia and Thailand negotiate long-term dextrose supply agreements with integrated corn millers, extracting price transparency through direct refiner partnerships.
- Beverage Companies:Carbonated and non-carbonated drink bottlers face margin compression from cane sugar price volatility and reformulation costs, consolidating supplier bases around ISO 22000-certified refiners.
- Nutraceuticals:Sports-nutrition and dietary supplement brands in Japan and Australia specify pharmaceutical-grade maltodextrin with documented enzymatic hydrolysis parameters and heavy metal testing protocols.
- Pharmaceutical Firms:Excipient-grade crystalline dextrose demand concentrates in Indian and Chinese generic drug manufacturing, where USP-NF compliance and microbial specification tightening elevate procurement scrutiny.
Food manufacturers command contract scale. Nutraceuticals is gaining share fastest.
Distribution Channel:
Channel economics reflect order minimum thresholds, certification documentation requirements, and inventory velocity constraints.
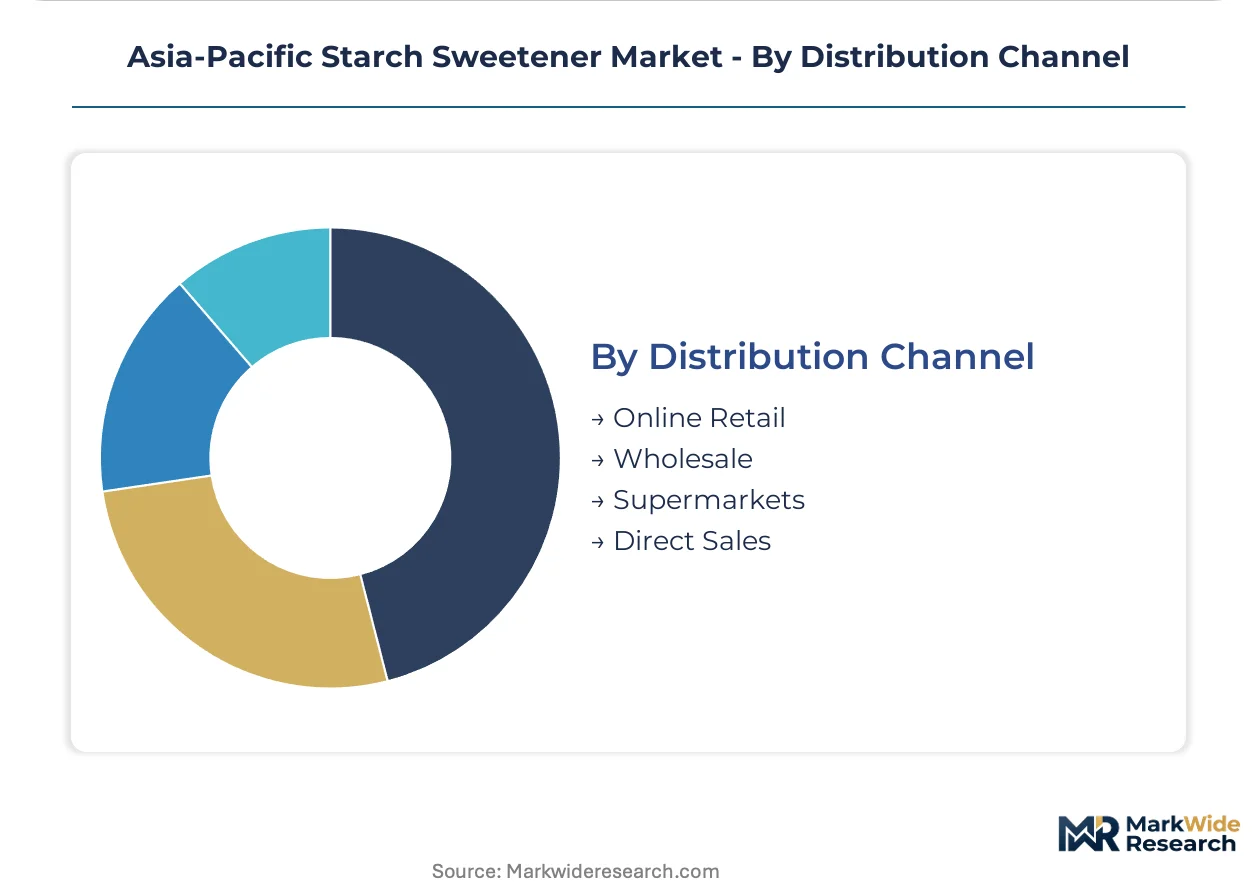
- Online Retail:E-commerce ingredient platforms are disintermediating traditional distributor networks, enabling smaller food tech startups to source certified sweeteners at reduced minimum order quantities.
- Wholesale:Regional distributors maintain bulk syrup storage infrastructure and tanker logistics for beverage bottlers lacking captive wet-milling capacity.
- Supermarkets:Retail-packaged specialty sweeteners for home baking and small commercial kitchens occupy niche shelf space in urban centers.
- Direct Sales:Large-volume food and beverage manufacturers negotiate manufacturer-refiner partnerships governing bulk dextrose supply scheduling, particularly visible across Java's industrial zones.
Wholesale holds legacy infrastructure. Direct sales is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale beverage bottlers and processed food conglomerates dominate procurement across the Asia-Pacific starch sweetener market, consolidating supply relationships around integrated corn millers with ISO 22000 certification and captive traceability systems.
China
Carbonated beverage reformulation and sports-nutrition powder expansion drive maltodextrin demand in Jiangsu and Shandong provinces. SAMR purity specification tightening for non-GMO corn-derived ingredients elevates procurement scrutiny across domestic wet-milling operations. Yangtze River Delta food manufacturers consolidate supplier bases to preempt compliance cost escalation.
India
Clean-label dextrose trials accelerate across Mumbai and Delhi processed food corridors following FSSAI mandatory added-sugar labeling requirements. Pharmaceutical excipient-grade crystalline glucose demand concentrates in Gujarat and Maharashtra generic drug manufacturing clusters. Integrated millers with batch-level corn provenance documentation capture premium positioning.
Japan
Reduced-calorie syrup formulations and sports-nutrition applications anchor demand for low-DE maltodextrin with documented enzymatic hydrolysis parameters. Ministry of Health, Labour and Welfare disclosure rules reshape formulation procurement protocols for confectionery exporters. Kanto region industrial bakeries specify pharmaceutical-grade material for clean-label positioning.
Thailand
Integrated corn-milling operations sustain bulk dextrose supply to regional beverage bottlers facing margin compression from cane sugar price volatility. Cargill Incorporated leverages its captive wet-milling footprint to extract price transparency through direct manufacturer partnerships. Bangkok metropolitan area bottling clusters negotiate volume commitments bypassing traditional distributor networks.
Indonesia
Processed food manufacturers across Java and Sumatra face single-source dependency risks as regional refining capacity concentrates on specific islands. Reformulation programs to reduce cane sugar content expand across confectionery and dairy powder segments. Surabaya industrial zones witness manufacturer-refiner partnerships governing bulk sweetener supply scheduling.
Asia-Pacific Starch Sweetener Market Competitive Environment
Player mix skews toward integrated agricultural processors with captive corn wet-milling infrastructure and specialized carbohydrate derivative refiners focused on pharmaceutical-grade certifications. Market structure exhibits tiered consolidation, with bulk syrup supply concentrating around multinational millers while specialty maltodextrin and crystalline dextrose segments retain niche specialist participation. Strategic archetypes include backward-integrated agribusiness conglomerates, enzymatic technology licensors, and regionally focused clean-label ingredient formulators. Competitive dynamics center on certification-driven supplier consolidation and direct procurement channel compression eliminating intermediary markups.
Among North American-based agribusiness conglomerates, Cargill Incorporated and Archer Daniels Midland Company represent the integrated milling archetype with regional Asia-Pacific infrastructure. Tate & Lyle PLC exemplifies the specialty carbohydrate refiner positioning, while Matsutani Chemical Industry Co., Ltd anchors Japanese domestic reduced-calorie formulation expertise. Ingredion Inc. and Roquette Frères occupy positions spanning bulk and specialty segments across multiple Asia-Pacific markets. Sukhjit Starch & Chemicals Ltd represents the emerging regional specialist archetype with India-focused operations. These entities collectively illustrate the competitive spectrum from scale-driven commodity supply to precision-engineered ingredient systems.
| Leading Market Players |
|---|
| Ingredion Inc. |
| Roquette Frères |
| Cargill Incorporated |
| Matsutani Chemical Industry Co., Ltd |
| E. I. du Pont de Nemours and Company |
| The Archer Daniels Midland Company |
| Tate & Lyle PLC |
| Sukhjit Starch & Chemicals Ltd. |
| Tereos SA |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day inventory cycles across Thai corn wet-milling operations concentrate pricing power with integrated millers possessing captive storage infrastructure, while Indonesian bottlers absorb margin volatility through long-term offtake commitments indexed to feedstock benchmarks.
Pricing Analysis
Cost-plus contracts with Bangkok corn price indexation dominate bulk dextrose procurement between Thai millers and Indonesian beverage bottlers. Price differentiation rests on ISO 22000 certification tier and volume scale, with pharmaceutical-grade maltodextrin commanding technical premiums over standard beverage syrup grades. Pricing pressure stems from cane sugar price volatility compressing reformulation budgets across Southeast Asian processed food manufacturers. Small-scale confectionery producers in Vietnam exhibit highest price sensitivity, while Japanese sports-nutrition brands prioritize batch-level provenance documentation over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites raw corn import flows into Thai and Indonesian wet-milling clusters, creating logistics chokepoint exposure for regional dextrose supply. Manufacturing concentrates in Thailand, Indonesia, and Australia, with feedstock sourcing anchored in Ukrainian and Brazilian corn exports. Supply chain risk centers on single-source dependency within Java-Sumatra refining corridors. Distribution runs through direct manufacturer-refiner partnerships displacing traditional wholesale networks across Southeast Asia's processed food belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific starch sweetener demand sits in early-cycle expansion as FSSAI labeling mandates and clean-label reformulation programs accelerate adoption beyond legacy beverage applications.
For Market Incumbents: Consolidate supplier relationships around integrated millers with captive traceability systems to preempt compliance cost escalation from India's FSSAI and China's SAMR disclosure tightening. Defend margin position through backward integration into enzymatic hydrolysis technology licensing rather than commodity volume expansion. Channel control through direct procurement partnerships with Java-based industrial bakeries offers defensive positioning against distributor disintermediation. For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade certification and batch-level corn provenance documentation to penetrate Japanese sports-nutrition and Australian dairy powder export segments. Vietnam's underpenetrated confectionery sector presents the most accessible white-space target, with low-hygroscopicity maltodextrin specifications still consolidating around first-mover suppliers. Containerized enzymatic processing systems enable localized production near Surabaya candy clusters without capital-intensive wet-milling infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because mandatory added-sugar labeling regimes across India, China, and Japan structurally elevate demand for certified-low-DE alternatives. Acquisition targets should display integrated corn-milling infrastructure with ISO 22000 documentation systems already deployed. The signal to watch is divergence between national sweetener labeling regimes triggering cross-border inventory stranding.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22000 Certification Investment | FSSAI and SAMR tightening elevates hazard-analysis documentation to competitive entry barrier. |
| Direct Manufacturer-Refiner Partnerships | Java industrial zones witness channel compression eliminating distributor markup layers. |
| Containerized Enzymatic Processing Deployment | Indonesian and Vietnamese pilots localize dextrose production near confectionery demand clusters. |
| Pharmaceutical-Grade Maltodextrin Capacity Addition | Japanese Ministry of Health disclosure rules reshape procurement protocols for excipient-grade material. |
| Non-GMO Corn Provenance Traceability Systems | Batch-level certification records capture premium positioning ahead of China's SAMR purity specification escalation. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant managers at Thai and Indonesian wet-milling facilities, procurement leads at Mumbai and Delhi processed food conglomerates, technical R&D directors at Japanese sports-nutrition formulators, and distribution channel partners across Southeast Asia's wholesale syrup networks. Secondary validation drew from FSSAI regulatory filings, SAMR purity specification drafts, customs and trade data on corn import flows, and SEC 10-K disclosures from listed agribusiness conglomerates. Bottom-up volume modeling triangulated against top-down value estimates across product chemistry and end-use segments.
Across the analysis window, the forecasting framework modeled demand trajectories by glucose equivalency rating, application specification, certification tier, and regional regulatory cluster. CAGRs were derived from trend extrapolation of enzymatic hydrolysis capacity expansion, reformulation trial documentation from major food manufacturers, and historical elasticity patterns between cane sugar and starch-derived alternatives. Industry-specific inputs included pharmaceutical excipient-grade demand from Indian generic drug manufacturing clusters and sports-nutrition powder system specifications from Australian export-oriented dairy processors.
Material uncertainties — corn input cost volatility, divergence between national labeling regimes, and enzymatic technology licensing access — sit outside the modeled envelope and could compress or extend projected adoption curves. Practitioners should keep alternative scenarios live as FSSAI enforcement intensity and SAMR implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sour Sugar Market
Sweeteners
Sorbitol Market
Sweeteners
Isomaltulose Market
Sweeteners
Glucose Syrup Market
Sweeteners
Europe Low-Calorie Sweeteners Market
Sweeteners
Sugar Substitutes Market
Sweeteners
Corn Sweeteners Market
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
Corn Syrup Market
Sweeteners
Sucrose Esters Market
Sweeteners
Sugar Syrups Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Palm Sugar Market
Sweeteners
Invert Sugar Market
Sweeteners
Resistant Maltodextrin Market
Sweeteners
Organic Palm Sugar Market