
 Caramelized Sugars Market | 2026-2036
Caramelized Sugars Market Size, Share, and Industry Trends Forecast 2026-2036
Caramelized Sugars Market Outlook
Multi-source procurement of caramelized sugar intermediates is expanding as food manufacturers diversify away from single-origin supply contracts. Cargill leverages its integrated corn-sweetener infrastructure to sustain cost-advantaged caramel production across North American processing hubs. Sethness-Roquette specializes in liquid caramel colorants and competes on application-specific formulations for beverage clients. Royal Buisman anchors European supply through controlled Maillard reaction expertise and dominates heritage-style caramel profiles for artisan food brands.
Caramelized sugars are carbohydrate derivatives produced through controlled thermal degradation of reducing sugars, typically operating between 120°C and 180°C to develop color, flavor, and antioxidant functionality through Maillard and caramelization pathways. These ingredients serve primarily as natural colorants, flavor modifiers, and shelf-life extendants across packaged foods and foodservice channels. The product type landscape tilts toward brown sugar and amber sugar variants, where margin pools concentrate in bakery and confectionery applications requiring consistent hue intensity and clean-label positioning. Dark caramel grades are accelerating fastest in sauces and beverages, driven by formulation shifts toward visually intense, bitter-sweet profiles in barbecue sauces, cola formulations, and craft brewing adjuncts.
The FDA governs caramel colorant classifications through 21 CFR 73.85, distinguishing four process-defined classes with varying sulfite and ammonium compound limits that directly dictate permissible applications and labeling requirements. EFSA and the EU Food Improvement Agents Package enforce maximum 4-MeI concentration thresholds in Class III and IV caramels, compelling reformulation investments among European suppliers. Stakeholders must monitor evolving clean-label thresholds and regional purity divergences to align capital allocation with the stricter compliance trajectory shaping market access conditions.
Market Dynamics
Clean-label reformulation mandates from EFSA and the FDA are forcing caramelized sugar suppliers to reengineer Maillard reaction pathways, eliminating ammonium catalysts while preserving color stability in Class III and IV caramels for beverage applications.
Growth Catalysts
- EU F-Gas Regulation:Tightened purity standards for food-grade caramel products are accelerating investment in closed-system thermal processing equipment across German and Dutch production facilities.
- Artificial colorant replacement:Bakery and confectionery manufacturers in France and Italy are converting formulation lines to caramelized sugar colorants to meet retailer clean-label requirements.
- Maillard reaction optimization:Advanced temperature-control technologies are enabling precise hue modulation in dark caramel grades for craft brewing and premium sauce segments.
Market Restraints
- Feedstock volatility:Beet sugar and corn syrup input costs fluctuate with agricultural commodity cycles, compressing margin predictability for European caramel producers.
- Supplier concentration:Heritage-style caramel expertise concentrates in Netherlands-based controlled-reaction specialists, creating single-source vulnerability for artisan food brands.
- 4-MeI threshold compliance:EFSA maximum concentration limits for Class III and IV caramels necessitate costly reformulation and extended safety testing timelines.
Strategic Opportunities
- Saudi Arabia foodservice expansion:MOHAP food additive approvals for caramel colorants are opening institutional catering and quick-service restaurant supply contracts in Gulf Cooperation Council markets.
- Plant-based dairy analogues:Oat and almond milk manufacturers require visually intense caramel profiles to mimic traditional dairy browning in barista formulations.
- Carbon labeling alignment:EU Green Deal corporate sustainability reporting obligations create preference for regionally produced caramel with verified supply chain emissions data.
Industry Challenges
- Maillard reaction engineering expertise:Shortage of food chemists with specialized knowledge in controlled thermal degradation pathways limits production scale-up for mid-tier suppliers.
- Legacy equipment retrofitting:Converting open-kettle caramelization systems to closed-loop processing requires capital expenditure that strains privately held manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caramelized Sugars Market |
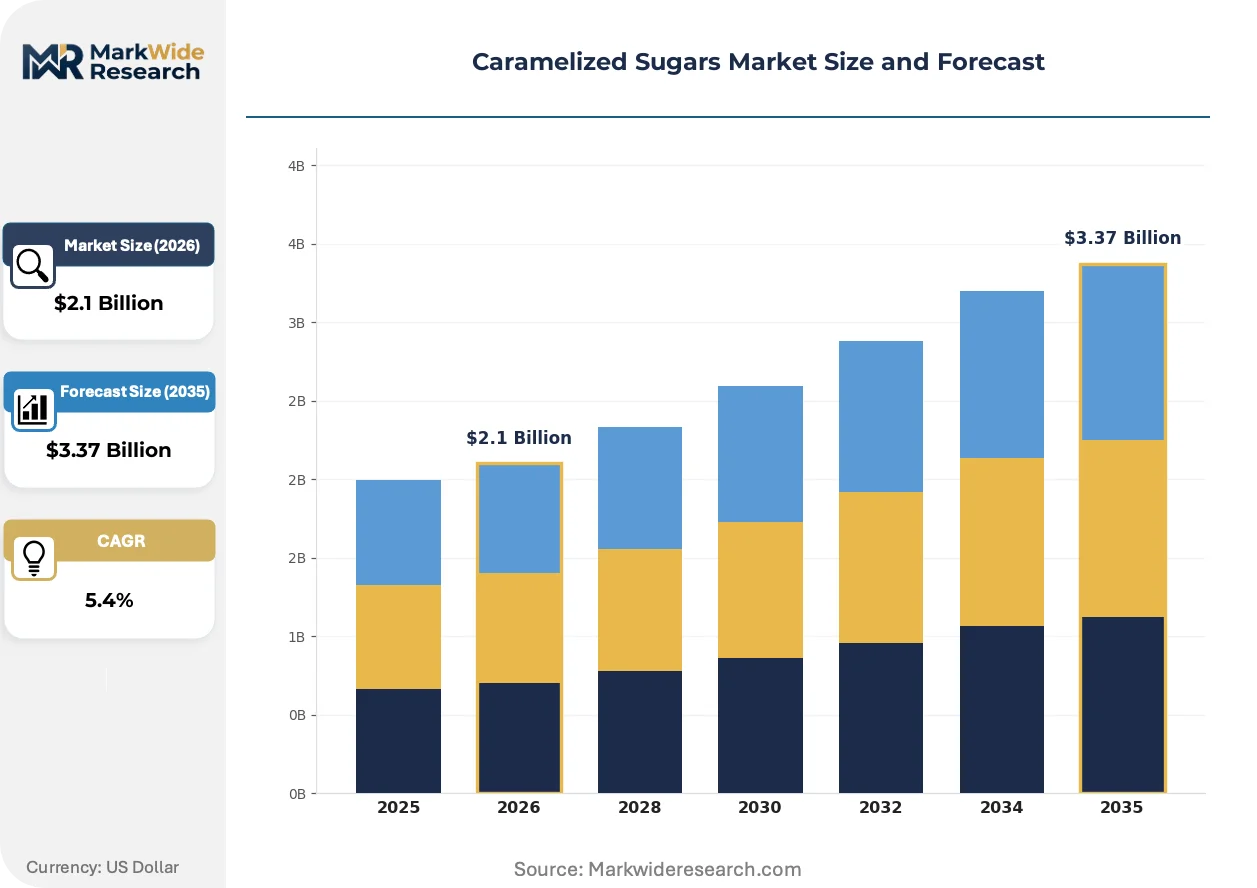
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brown Sugar, Amber Sugar, Dark Caramel, Glazed Sugar Application: Baking, Confectionery, Sauces, Beverages End User: Food Manufacturers, Restaurants, Bakeries, Catering Services Distribution Channel: Wholesale, Retail, Online, Direct |
| Companies Covered | Cargill, Ingredion Incorporated, Kerry Group, Sethness-Roquette, Nigay, Royal Buisman, Secna Group, Tate & Lyle, Martin Mundo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caramelized Sugars Market Strategic Shifts
Precision thermal processing and regulatory chemistry are converging to redefine how caramelized sugars achieve color intensity without compromising clean-label positioning or crossing contaminant thresholds.
Continuous-flow reactor technology is absorbing the batch-to-batch variability that has historically plagued caramel color production. Industrial sauce manufacturers in the United States are retrofitting lines with these systems to achieve lot-to-lot consistency in barbecue and Worcestershire applications. The technology is absorbing quality-control overhead while compressing the rejection rates that previously eroded margin in high-volume contracts.
REACH compliance frameworks in Europe are mandating granular substance registration for caramel colorant intermediates, compelling suppliers to document reaction byproducts across the full Maillard pathway. This regulatory pressure is redirecting R&D investment toward catalyst-free thermal processes. German beverage formulators are responding by consolidating supplier relationships with processors holding full ECHA dossier coverage.
Direct-procurement contracts between industrial bakeries and caramel specialists are displacing traditional ingredient distributor intermediation in France and Belgium. Large-scale croissant and pastry manufacturers now negotiate volume commitments with controlled-reaction processors to secure hue specification guarantees. This channel compression is most visible in northern France, where industrial bakery clusters have established captive supply arrangements with Maillard reaction specialists.
Caramelized Sugars Market Segmentation
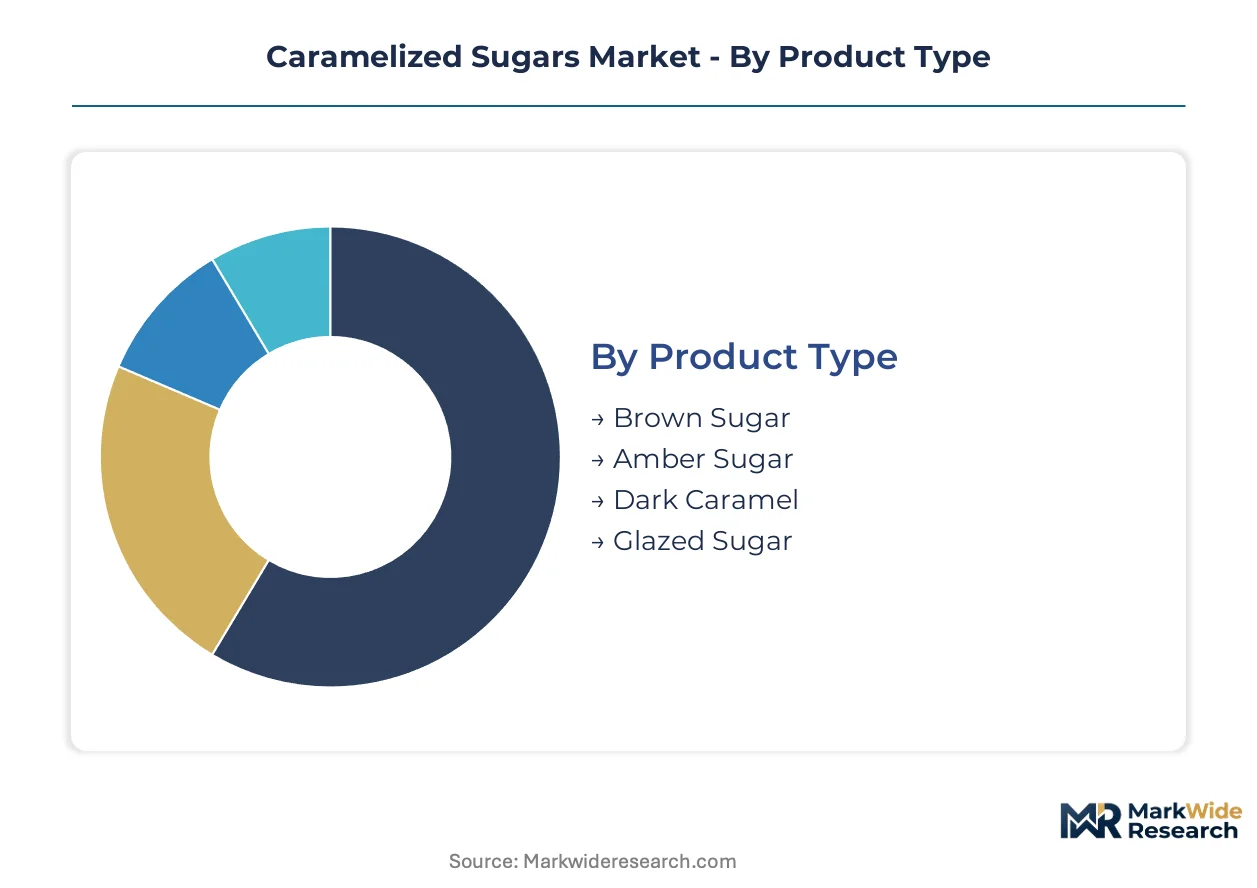
Caramelized sugar specifications diverge sharply across thermal processing intensity and reducing sugar composition, creating distinct margin pools and regulatory exposure profiles. Manufacturers align procurement decisions with Maillard reaction control capabilities and end-use colorant classification requirements.
Product Type:
Thermal degradation pathways and hue intensity specifications define competitive positioning across caramelized sugar grades.
- Brown Sugar:Partially refined sucrose retains molasses coating for mild caramel notes and moisture retention in cookie and cake formulations. Industrial bakeries in Germany anchor volume procurement for consistent crumb color in laminated dough applications.
- Amber Sugar:Intermediate Maillard reaction products deliver golden-brown chromaticity with balanced sweetness. French sauce manufacturers concentrate demand for visually appealing béchamel and dessert sauce bases requiring clean-label positioning.
- Dark Caramel:Extended thermal processing generates intense bitter-sweet profiles and maximum color density. Craft brewing and premium barbecue sauce segments in the United States drive formulation adoption.
- Glazed Sugar:Surface-crystallized variants provide decorative sheen and textural contrast. Specialty confectionery applications in Belgium and the Netherlands utilize controlled glazing for praline finishing.
Mature deployment sits with brown sugar in high-volume bakery contracts. Newer deployment is concentrated in dark caramel grades for beverage and brewing applications.
Application:
End-use processing conditions and visual performance requirements segment demand across food manufacturing channels.
- Baking:Laminated dough and pastry applications require thermally stable caramelized sugars that resist color degradation through extended oven exposure. Northern French industrial croissant manufacturers specify tight hue tolerance bands.
- Confectionery:Hard candy and caramel center formulations demand precise moisture content and crystallization control. Italian nougat producers prioritize amber grades for traditional torrone production.
- Sauces:Acidic and high-temperature processing environments necessitate sulfite-stabilized Class III caramels. Barbecue and Worcestershire manufacturers in the United States retrofit continuous-flow reactors for lot consistency.
- Beverages:Cola formulations and craft brewing adjuncts require maximum color intensity with minimal flavor contribution. EFSA 4-MeI thresholds compel catalyst-free process investments for European supply.
Volume concentration remains in baking applications. Steepest expansion trajectory appears in beverages as clean-label cola reformulations accelerate.
End User:
Scale and specification complexity separate procurement patterns across foodservice and manufacturing verticals.
- Food Manufacturers:Packaged goods producers negotiate annual volume contracts with hue specification guarantees. Direct procurement arrangements with Maillard reaction specialists are displacing distributor intermediation in France.
- Restaurants:Foodservice operators prioritize cost-efficient liquid caramel colorants for sauce and dessert plating consistency.
- Bakeries:Artisan and industrial segments diverge on heritage-style versus precision-controlled caramel profiles.
- Catering Services:Institutional buyers emphasize shelf-stable concentrates for large-batch sauce preparation.
Specification intensity concentrates with food manufacturers. Price sensitivity dominates catering procurement decisions.
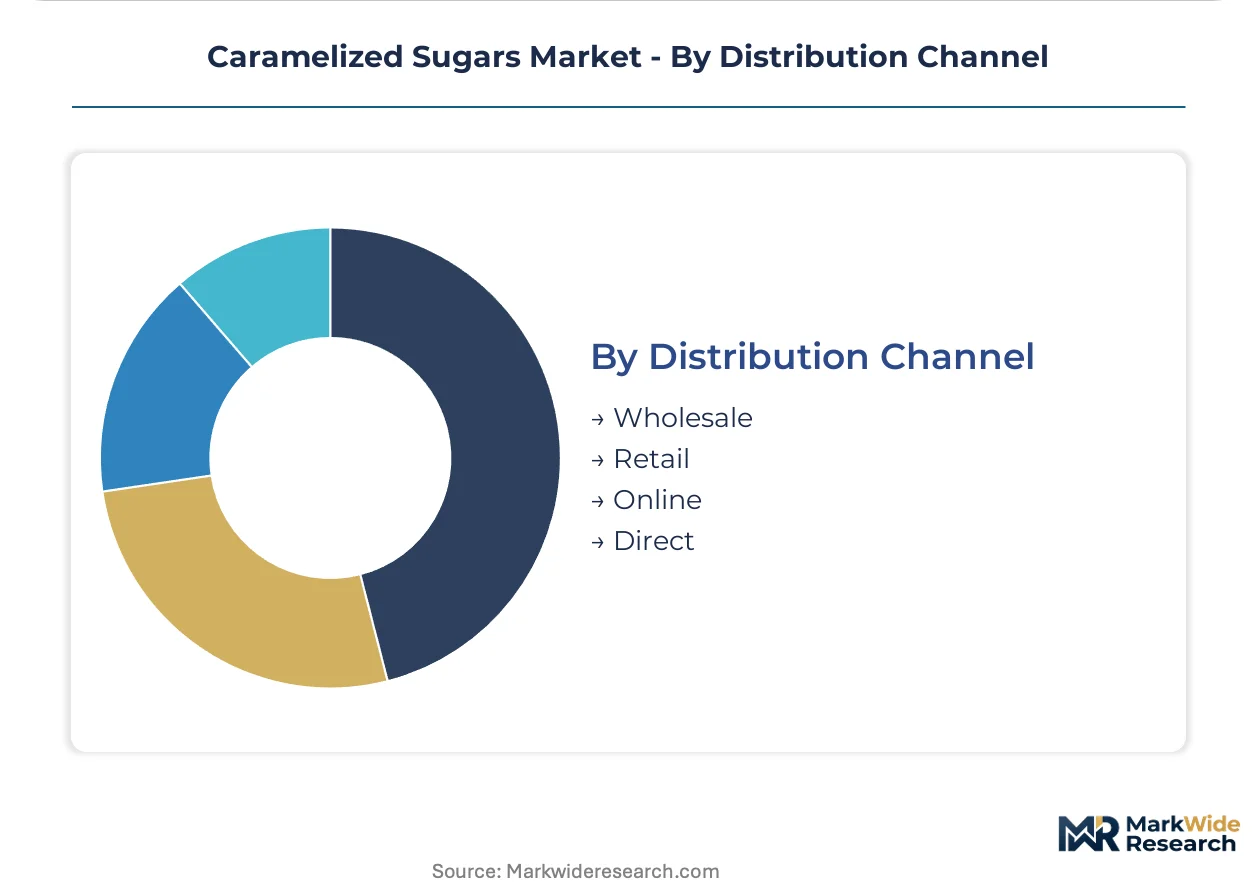
Distribution Channel:
Supply chain configuration reflects order scale, technical service requirements, and geographic proximity to production assets.
- Wholesale:Ingredient distributors aggregate fragmented bakery demand and provide technical formulation support. Channel share is compressing as direct contracts expand.
- Retail:Small-scale specialty sugar sales serve artisan producers and test kitchen applications.
- Online:Digital procurement platforms facilitate spot purchasing for mid-tier manufacturers seeking alternative suppliers.
- Direct:Large-volume food manufacturers establish captive supply relationships with controlled-reaction processors for hue guarantee security.
Longstanding volume flows through wholesale networks. Direct channel expansion is accelerating among tier-one food manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beet sugar cultivation in northern France and corn syrup processing in the United States Midwest anchor the feedstock geography for caramelized sugar production. Regional demand patterns diverge sharply between European clean-label reformulation pressures and North American beverage industry volume requirements. Asian markets are emerging as formulation testing grounds for catalyst-free thermal processes.
United States
Midwest corn syrup processors supply cost-advantaged feedstock to caramel colorant manufacturers serving cola and craft brewing segments. FDA 21 CFR 73.85 classifications dictate four process-defined caramel grades with varying sulfite and ammonium limits. Chicago-area industrial sauce producers are retrofitting continuous-flow reactors to achieve lot consistency in barbecue and Worcestershire applications.
Germany
Industrial bakeries in Lower Saxony and Bavaria anchor European volume procurement for laminated dough applications requiring consistent crumb color. EU F-Gas Regulation compliance is accelerating investment in closed-system thermal processing equipment across German production facilities. Hamburg-controlled Maillard reaction specialists dominate heritage-style caramel profiles for artisan food brands.
France
Northern French sugar beet cooperatives supply premium feedstock for amber and dark caramel grades targeting sauce and confectionery applications. EFSA maximum 4-MeI concentration thresholds for Class III and IV caramels are compelling reformulation investments among suppliers. Industrial croissant manufacturers in Île-de-France are establishing direct procurement contracts with controlled-reaction processors for hue specification guarantees.
Netherlands
Rotterdam-area port infrastructure facilitates import of diverse reducing sugar feedstocks for specialty caramel production. REACH compliance frameworks mandate granular substance registration for caramel colorant intermediates, compelling full ECHA dossier coverage. Royal Buisman in the Netherlands anchors European supply through controlled Maillard reaction expertise.
Saudi Arabia
Gulf Cooperation Council foodservice expansion is creating institutional catering and quick-service restaurant demand for shelf-stable caramel concentrates. MOHAP food additive approvals for caramel colorants are opening supply contracts in institutional channels. Riyadh-based distributors are consolidating procurement relationships with European processors holding full regulatory documentation.
Caramelized Sugars Market Competitive Environment
Capacity expansion dominates the current landscape as suppliers retrofit open-kettle systems to closed-loop processing to meet tightening purity standards. The vendor base concentrates around three strategic tiers: integrated agricultural processors with captive feedstock infrastructure, specialized Maillard reaction houses with formulation expertise, and regional distributors aggregating fragmented bakery demand. Competitive intensity is escalating through direct-procurement contracts displacing traditional distributor intermediation, and through technology licensing agreements transferring continuous-flow reactor designs across manufacturing networks.
Among integrated agricultural processors, Cargill and Tate & Lyle exemplify the scale-driven archetype through their corn-sweetener infrastructure positions. Sethness-Roquette occupies a position within the specialized formulation tier, representing application-specific expertise for liquid caramel colorants. Royal Buisman anchors the heritage-style segment, exemplifying controlled-reaction capabilities that dominate European artisan brand supply relationships.
| Leading Market Players |
|---|
| Cargill |
| Ingredion Incorporated |
| Kerry Group |
| Sethness-Roquette |
| Nigay |
| Royal Buisman |
| Secna Group |
| Tate & Lyle |
| Martin Mundo |
| Others |
Value Chain & Pricing Dynamics
Industrial bakery procurement clusters in northern France and Lower Saxony negotiate annual volume contracts with hue specification guarantees, anchoring a contract-based long-term offtake model that compresses spot-market participation for mid-tier buyers.
Pricing Analysis
Warranty-backed hue consistency and technical formulation support are bundled into premium tier contracts, while standard tiers strip out application-specific customization. Three-tier pricing structure across premium, standard, and economy levels separates heritage-style Maillard reaction expertise from commodity brown sugar grades. Pricing pressure stems from feedstock volatility in beet sugar and corn syrup markets, squeezing margin predictability for European producers. Catering services and institutional buyers exhibit highest price sensitivity, whereas premium sauce manufacturers and craft brewers absorb cost premiums for color stability.
Supply Chain Analysis
EU Green Deal corporate sustainability reporting obligations and REACH substance registration requirements are reshaping sourcing toward regionally verified supply chains with documented emissions data. Production gravity centers on Germany, France, and the Netherlands, with Rotterdam port infrastructure facilitating diverse reducing sugar feedstock imports. The supply chain draws from beet sugar cooperatives in northern France, corn syrup processors in the United States Midwest, and specialty glucose refiners in the Netherlands. Single-source vulnerability concentrates in Netherlands-based controlled-reaction specialists holding heritage-style caramel expertise. Distribution runs through wholesale ingredient networks aggregating fragmented bakery demand, though direct procurement contracts are compressing channel intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around processors capable of funding closed-loop thermal system retrofits, with REACH compliance investments forcing weaker open-kettle operators toward exit or acquisition.
For Market Incumbents: Anchor defensive positioning through backward integration into captive corn-sweetener or beet sugar feedstock infrastructure, insulating margin from agricultural commodity cycles. Prioritize ECHA dossier coverage for full caramel colorant intermediate registration, locking out mid-tier competitors from European beverage supply contracts. Cargill and Tate & Lyle exemplify this scale-driven consolidation archetype.
For New Entrants and Emerging Players: Begin with catalyst-free thermal process licensing in Gulf Cooperation Council markets, where MOHAP approvals create lower regulatory barriers than EFSA thresholds. Target Saudi Arabia foodservice expansion and plant-based dairy analogue formulations as penetrable white-space segments. Pursue direct-procurement relationships with oat and almond milk manufacturers seeking visually intense caramel profiles for barista applications.
For Investors and Strategic Acquirers: The window for entry favors specialized Maillard reaction houses with controlled thermal degradation expertise and full regulatory documentation coverage. Over the medium-term horizon, acquisition value concentrates in Netherlands-based and German processors holding heritage-style caramel capabilities and ECHA dossier completeness. Monitor EFSA 4-MeI threshold enforcement actions as the inflection signal indicating accelerated reformulation investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Thermal Processing Retrofit | EU F-Gas Regulation compliance mandates equipment upgrades across German and Dutch production facilities. |
| Catalyst-Free Process Development | EFSA 4-MeI thresholds compel R&D redirection toward ammonium-free Maillard reaction pathways. |
| Direct Procurement Contracting | Northern French industrial bakeries bypass distributors to secure hue guarantees from reaction specialists. |
| Heritage-Style Capability Acquisition | Royal Buisman anchors European artisan brand supply through controlled-reaction expertise concentration. |
| Gulf Market Regulatory Entry | MOHAP approvals unlock institutional catering and quick-service restaurant supply contracts in Saudi Arabia. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with caramel colorant plant managers, procurement leads at industrial bakeries, beverage formulation directors, and Maillard reaction R&D specialists. Bottom-up triangulation combined production capacity assessments across German, French, and Dutch processing facilities with top-down validation against EU sweetener consumption statistics and FDA 21 CFR 73.85 classification frameworks. ECHA REACH registration databases and EFSA scientific opinions provided regulatory boundary conditions.
Granularity extended to product type thermal processing intensity, application-specific colorant classification requirements, and end-user procurement scale tiers across the analysis window. CAGRs were derived from segmented volume trajectories calibrated to clean-label reformulation adoption curves and beverage industry catalyst-free process migration timelines. Feedstock price elasticity models incorporated beet sugar and corn syrup agricultural commodity cycle patterns.
Underlying measurement precision varies by segment; dark caramel grades for craft brewing carry tighter precision than commodity brown sugar bakery applications due to formulation specification intensity. Forecasts reflect assumptions around EFSA enforcement continuity and EU Green Deal sustainability reporting phase-in. Regulatory timeline acceleration or feedstock supply disruption could revise trajectory boundaries. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Aspartame Market
Sweeteners
Tagatose Market
Sweeteners
Natural Malt Sweeteners Market
Sweeteners
Agave Syrup Market
Sweeteners
Granulated Sugar Market
Sweeteners
Maltodextrin Market
Sweeteners
Asia Pacific Food Sweetener Market
Sweeteners
Japan Food Sweetener Market
Sweeteners
Canada Food Sweetener Market
Sweeteners
Sugar Market
Sweeteners
Gluten-Free Sugar Syrup Market
Sweeteners
Dextrose Syrup Market
Sweeteners
Corn Syrup Market
Sweeteners
North America High-Intensity Sweeteners Market
Sweeteners
Sorbitol Market
Sweeteners
United States Food Sweetener Market