
 Global Plant-Derived and Synthetic Sugar Market | 2026-2036
Global Plant-Derived and Synthetic Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plant-Derived and Synthetic Sugar Market Foresight
Subscription-based formulation services is rebalancing how sweetener suppliers monetize technical relationships beyond commodity tonnage. Cargill leverages its global agricultural origination network to sustain integrated supply security from Brazilian cane fields to North American refineries. Tate & Lyle differentiates through specialty starch and sweetener innovation, while Südzucker AG anchors European beet sugar processing with captive agricultural operations across Germany and Eastern Europe.
Plant-derived and synthetic sugar encompasses carbohydrate-based sweetening agents extracted from vegetative biomass or manufactured through catalytic and microbial conversion processes, with purity grades ranging from raw syrups to crystalline saccharides exceeding 99.5% concentration. These inputs serve as functional ingredients that provide sweetness, browning, preservation, and bulk in formulated consumer and industrial products. Cane sugar and beet sugar occupy mature volume positions with thin margin profiles, while synthetic sweeteners and agave syrup capture expanding premium pools from clean-label and reduced-calorie formulation trends. Enzymatic hydrolysis leads extraction technology adoption for its specificity and lower thermal degradation, though membrane separation is gaining share in high-purity pharmaceutical and cosmetic applications.
The U.S. FDA governs sweetener safety through GRAS determinations and added-sugar disclosure mandates, while the EU EFSA enforces novel food approvals and F-Gas Regulation compliance for processing refrigerants. Brazil's ANVISA and India's FSSAI impose parallel purity and labeling standards that shape export market access for multinational suppliers. Stakeholders must monitor regulatory divergence between permissive synthetic sweetener regimes and restrictive natural-sugar thresholds when allocating R&D and regional production capacity.
Market Dynamics
Enzymatic extraction technology is compressing processing costs for plant-derived sweeteners while regulatory labeling mandates force simultaneous portfolio reformulation across beverage and packaged food manufacturers.
Growth Catalysts
- Enzymatic Hydrolysis:Beverage producers deploy cellulase and amylase systems to extract fermentable sugars with higher yield specificity than acid hydrolysis, reducing thermal degradation losses in cane and beet processing.
- FDA Added-Sugar Disclosure:The U.S. FDA's updated Nutrition Facts panel mandates gram-level disclosure of added sugars, compelling manufacturers to reformulate with lower-glycemic plant alternatives that require less label attribution.
- Brazilian Infrastructure Concentration:Integrated cane processors leverage existing bioethanol co-production assets to achieve structural cost advantages in crystalline sugar and molasses derivatives.
Market Restraints
- Input Cost Volatility:Natural gas and electricity price spikes directly inflate evaporation and crystallization costs for beet sugar processors in the EU and North America.
- Supply Concentration Risk:Brazilian cane harvest variability and port logistics bottlenecks create systemic exposure for multinational buyers dependent on Santos terminal throughput.
- Synthetic Sweetener Substitution:Aspartame, sucralose, and steviol glycosides capture formulation share in reduced-calorie segments, pressuring bulk sucrose volume in carbonated soft drinks.
Strategic Opportunities
- Indian Regulatory Tailwind:FSSAI's proposed reduction in permissible added-sugar thresholds for packaged foods creates white space for monk fruit and erythritol blends in domestic and export formulations.
- Cosmetic-Grade Purification:Membrane separation technology enables pharmaceutical and personal care manufacturers to source 99.9% purity saccharides for humectant and preservative applications.
- Direct-to-Manufacturer Platforms:Digital procurement channels bypass traditional commodity broker networks, allowing mid-size food tech startups to secure certified organic cane sugar with full traceability documentation.
Industry Challenges
- Enzyme Engineering Talent Gap:Protein optimization for thermostable cellulases requires specialized biochemists, with competition intensifying from adjacent biofuel and bioplastic sectors.
- GRAS Certification Timelines:Novel plant-derived sweeteners face multi-year FDA safety review cycles, delaying commercialization of emerging extracts from underutilized botanical sources.
- Legacy Refinery Retrofit Costs:Converting thermal evaporation trains to membrane-enzyme hybrid systems demands capital outlays that strain thin-margin commodity sugar operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plant-Derived and Synthetic Sugar Market |
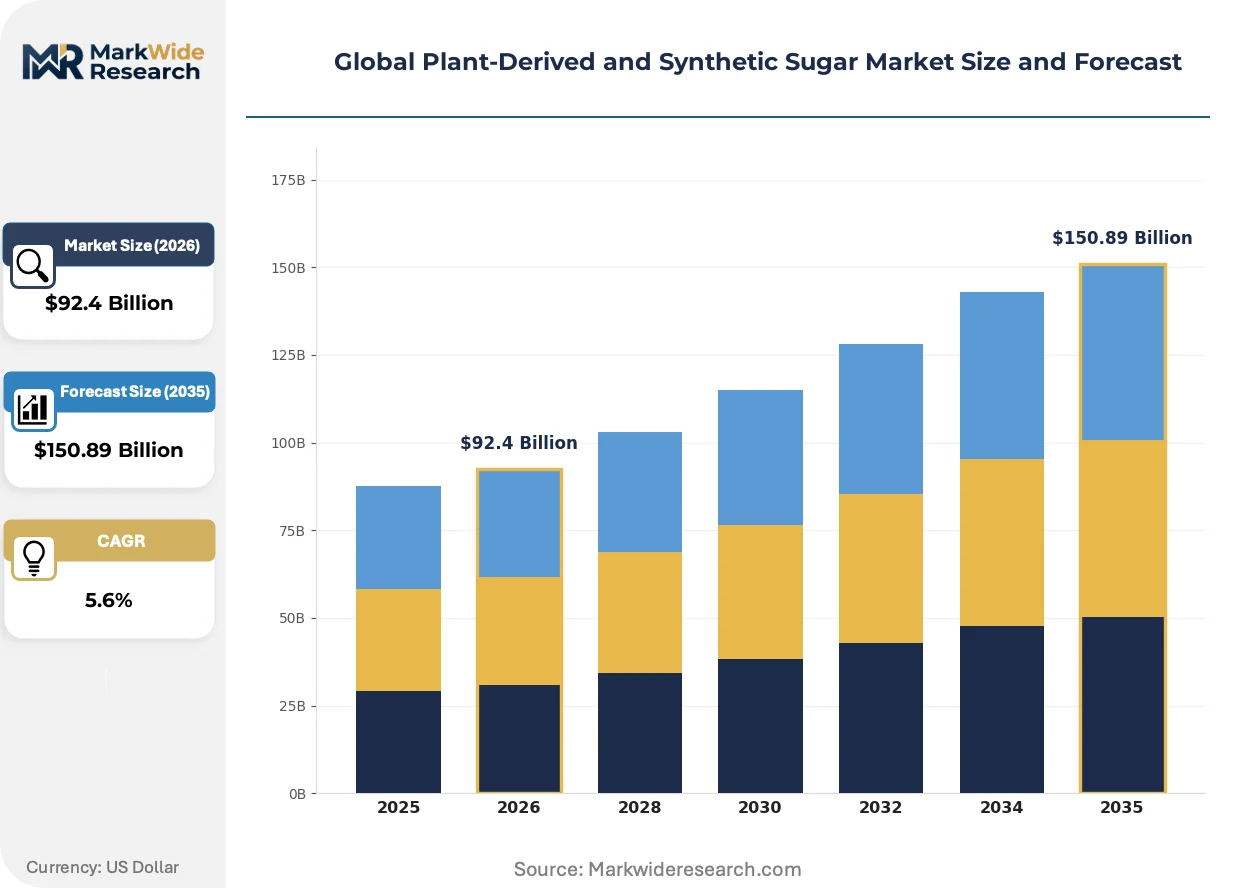
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $150.89 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cane Sugar, Beet Sugar, High Fructose Corn Syrup, Synthetic Sweeteners, Agave Syrup Application: Beverage Manufacturing, Confectionery Production, Pharmaceutical Formulations, Cosmetics, Bakery Items End User: Food Processors, Pharmaceutical Companies, Cosmetic Manufacturers, Beverage Producers, Nutraceutical Firms Extraction Technology: Enzymatic Hydrolysis, Chemical Catalysis, Fermentation, Membrane Separation, Crystallization |
| Companies Covered | ADM, Cargill, Ingredion, Ajinomoto Co., Inc., BENEO, DuPont, Roquette Frères, Tate & Lyle, Südzucker AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plant-Derived and Synthetic Sugar Market Shifts & Advancements
Continuous fermentation and cell-free enzymatic systems are displacing batch processing, while regulatory divergence between permissive synthetic regimes and restrictive natural-sugar jurisdictions forces dual-track formulation strategies.
Precision fermentation of rare sugars is electrifying supply economics for allulose and tagatose. Biotech startups deploy engineered yeast strains to convert corn dextrose into low-calorie epimers at scale previously constrained by botanical extraction. Beverage formulators in North America and East Asia are adopting these inputs at accelerating rates, compressing the premium gap between synthetic and plant-derived alternatives.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in beet sugar crystallization plants. Processors must retrofit cooling systems with ammonia or CO2 alternatives, adding compliance capex that disadvantages smaller Eastern European facilities. German and Polish operators are consolidating processing capacity to amortize upgrade costs across larger throughput bases.
Clean-label procurement criteria now mandate third-party certification for non-GMO and organic cane provenance. Mid-size confectionery brands bypass commodity exchanges to contract directly with Brazilian and Paraguayan cooperatives, replacing spot-market purchasing with multi-year offtake agreements. This disintermediation is most visible in premium chocolate and craft beverage segments across Scandinavia and the Pacific Northwest.
Global Plant-Derived and Synthetic Sugar Market Segmentation
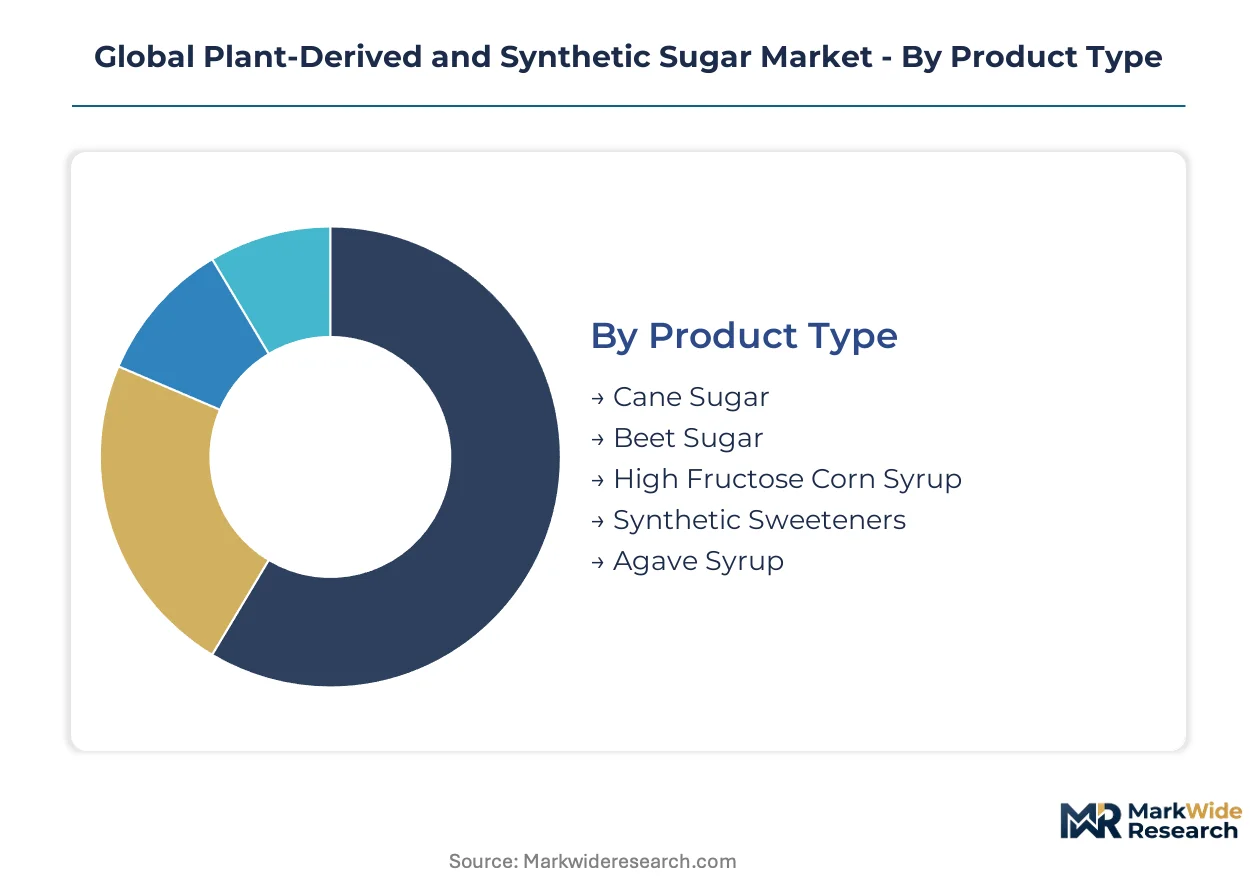
Sweetener procurement strategies diverge sharply across product categories and end-use specifications. Manufacturers must align extraction technology investments with regulatory thresholds in target markets while balancing reformulation costs against label-positioning advantages.
Product Type:
Supply concentration in Brazilian cane fields and EU beet belts creates divergent margin structures across botanical and synthetic alternatives.
- Cane Sugar:Crystalline sucrose extracted from Saccharum officinarum dominates bulk sweetener procurement, with Brazilian mills supplying integrated refiners across North America and Asia. Santos port throughput constraints periodically disrupt just-in-time delivery schedules for multinational beverage formulators.
- Synthetic Sweeteners:Catalytically manufactured aspartame, sucralose, and acesulfame potassium deliver high-intensity sweetness at micro-dosage levels. FDA GRAS determinations and permissive daily intake thresholds in the US sustain formulation share in reduced-calorie carbonated drinks despite clean-label headwinds.
- Beet Sugar:Beta vulgaris-derived crystalline sucrose from EU and North American processing facilities carries non-GMO certification advantages for European confectionery applications.
- High Fructose Corn Syrup:Enzymatically isomerized glucose-fructose blends from US corn wet milling operations serve cost-sensitive beverage and bakery segments.
- Agave Syrup:Fructose-rich nectar from Mexican blue agave plants captures premium positioning in organic and low-glycemic formulations across North American natural products channels.
Today's leader: Cane Sugar. Tomorrow's challenger: Synthetic Sweeteners.
Application:
End-use specifications create tiered purity requirements that reshape processor technology selection and certification investments.
- Beverage Manufacturing:Liquid and dry sweetener inputs must meet microbial load specifications below 1000 CFU/g for aseptic filling compatibility. Brazilian cane processors and US corn refiners compete on delivered cost to Coca-Cola and PepsiCo formulation centers, with enzymatic extraction yield differentials determining contract awards.
- Pharmaceutical Formulations:USP-grade excipient saccharides require 99.5%+ purity with heavy metal content below 10 ppm for tablet binding and syrup vehicles. Membrane separation technology enables Indian and Chinese suppliers to meet EP and USP monograph standards for export to regulated markets.
- Confectionery Production:Sucrose and glucose syrups provide crystallization control and texture modulation in chocolate and hard candy manufacturing.
- Cosmetics:Humectant-grade glycerol and sorbitol from plant-derived feedstocks serve moisturizing and preservative functions in personal care formulations.
- Bakery Items:Invert syrups and maltodextrins control moisture retention and Maillard browning in industrial bread and pastry production.
Volume concentrates in Beverage Manufacturing. Value accumulates in Pharmaceutical Formulations.
End User:
Procurement scale and specification stringency separate commodity buyers from specialty purchasers across the demand base.
- Food Processors:Industrial bakeries, sauce manufacturers, and prepared meal producers purchase bulk sweeteners through annual contracts indexed to ICE sugar futures. Nestlé and Unilever procurement teams negotiate multi-origin supply agreements to hedge against Brazilian harvest variability.
- Beverage Producers:Carbonated soft drink and juice manufacturers operate the largest single-site sweetener consumption, with tanker-truck delivery of liquid sucrose and HFCS directly to production facilities.
- Pharmaceutical Companies:Pfizer, Novartis, and generic manufacturers source excipient-grade sugars through qualified supplier audits and certificate-of-analysis documentation.
- Cosmetic Manufacturers:L'Oréal and Estée Lauder procurement teams specify non-GMO and RSPO-certified feedstocks for sustainability-aligned product lines.
- Nutraceutical Firms:Sports nutrition and dietary supplement producers blend erythritol, allulose, and stevia extracts for reduced-calorie protein and energy products.
Scale belongs to Beverage Producers. Margin capture sits with Nutraceutical Firms.
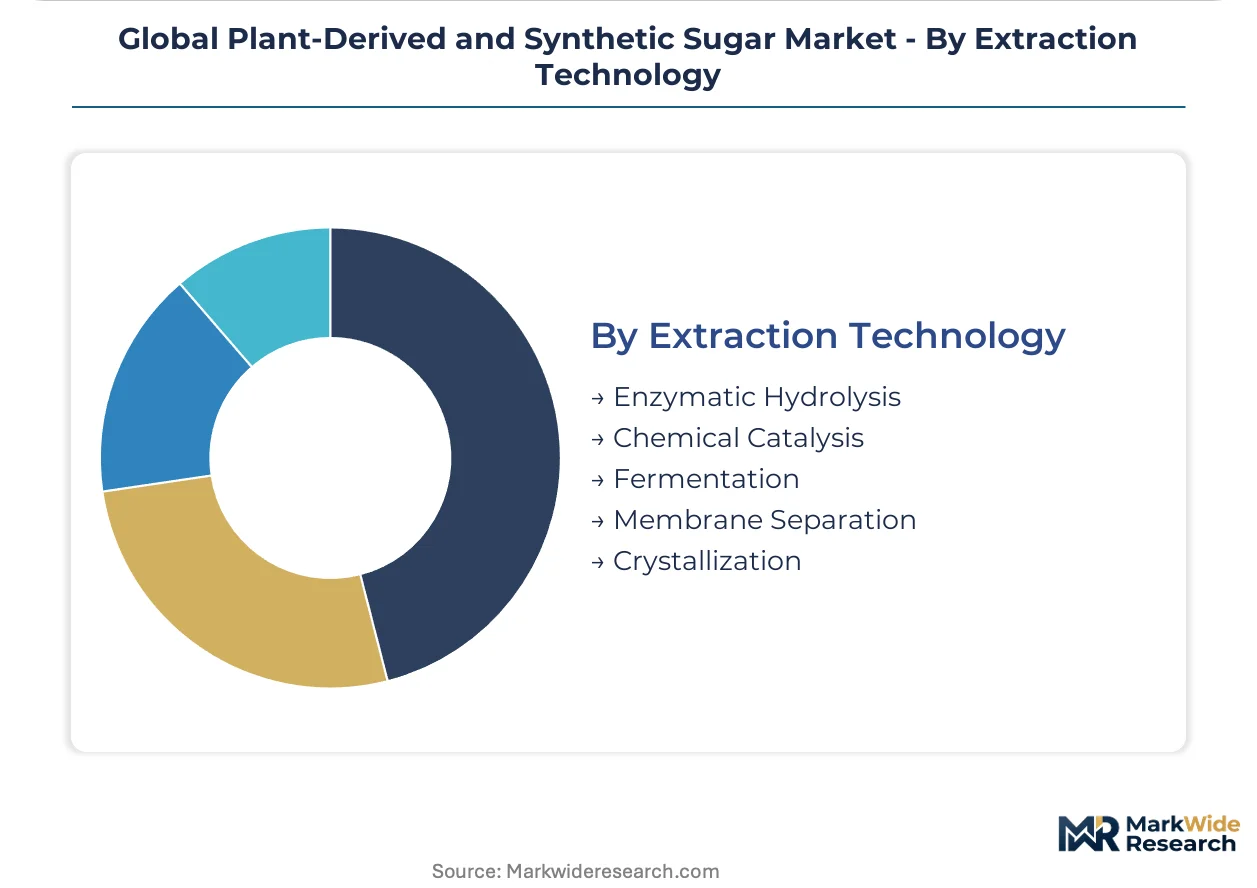
Extraction Technology:
Capital intensity and yield specificity separate batch processing legacy systems from continuous enzymatic and membrane-based alternatives.
- Enzymatic Hydrolysis:Cellulase and amylase systems operate at 50-60°C with pH 4.5-5.5 optima, converting starch and cellulosic biomass to fermentable sugars with 95%+ theoretical yield. Novozymes and DuPont supply immobilized enzyme preparations to Brazilian mills and US corn processors seeking to reduce thermal degradation losses.
- Membrane Separation:Nanofiltration and reverse osmosis systems achieve 99.9% purity saccharides without thermal stress, serving pharmaceutical and cosmetic specifications that command 3-5x commodity premiums.
- Chemical Catalysis:Acid hydrolysis of lignocellulosic feedstocks persists in legacy facilities despite corrosion maintenance costs and lower selectivity.
- Fermentation:Precision yeast and bacterial strains convert glucose to rare sugars including allulose and tagatose for low-calorie applications.
- Crystallization:Vacuum pan evaporation and centrifugal separation produce crystalline sucrose from clarified juice, consuming 300-400 kWh per ton of sugar.
Adoption accelerates fastest in Enzymatic Hydrolysis. Premium capture concentrates in Membrane Separation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian cane processors command structural cost advantages that North American corn refiners struggle to replicate, while Indian regulatory shifts and European sustainability mandates reshape procurement geography for multinational buyers.
Brazil
Santos port throughput constraints and bioethanol co-production economics anchor global cane sugar supply. ANVISA purity standards and labeling mandates shape export documentation requirements for integrated mills. São Paulo state processing clusters concentrate enzymatic extraction capacity serving Coca-Cola and PepsiCo formulation centers.
United States
FDA added-sugar disclosure rules drive beverage reformulation toward lower-glycemic alternatives. Corn wet milling operations in Illinois and Iowa supply high-fructose syrup to carbonated soft drink manufacturers. Chicago commodity exchanges price domestic sweetener contracts against Brazilian ICE futures.
India
FSSAI proposed reductions in permissible added-sugar thresholds create formulation white space for monk fruit and erythritol blends. Uttar Pradesh and Maharashtra cane belts sustain domestic crystalline sugar production. Gujarat processing hubs export pharmaceutical-grade saccharides to regulated European and North American markets.
Germany
EU F-Gas Regulation phase-down forces beet sugar crystallization plant retrofits toward ammonia cooling systems. Südzucker AG captive agricultural operations across Saxony-Anhalt and Brandenburg consolidate processing capacity. Eastern European facility closures redirect supply toward larger Polish and German throughput bases.
China
Guangxi and Yunnan cane provinces supply domestic beverage manufacturing while corn refiners in Jilin produce crystalline glucose for pharmaceutical excipients. NMPA excipient-grade standards and GB food additive regulations shape import substitution strategies. Yangtze River Delta formulation centers source membrane-purified saccharides for cosmetic humectant applications.
Global Plant-Derived and Synthetic Sugar Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated agricultural processors dominating bulk commodity flows while biotech innovators capture premium rare-sugar formulations. The vendor base concentrates around three strategic archetypes: cane-to-refinery integrators with captive origination networks, enzymatic technology licensors, and precision fermentation startups. Consolidation pressures favor M&A between regional beet processors and capacity expansion toward membrane-purification systems serving pharmaceutical specifications.
Within the integrated processor tier, Cargill and Südzucker AG exemplify divergent geographic anchoring strategies, with the former leveraging Brazilian field-to-refinery control and the latter consolidating European beet supply security. Tate & Lyle occupies a specialty innovation position, representing the enzymatic extraction technology licensor archetype without the agricultural origination overhead of commodity rivals. ADM and Ingredion sit within the North American corn-refiner cluster, their scale-driven operations serving cost-sensitive beverage and bakery segments through established wet-milling infrastructure.
| Leading Market Players |
|---|
| ADM |
| Cargill |
| Ingredion |
| Ajinomoto Co., Inc. |
| BENEO |
| DuPont |
| Roquette Frères |
| Tate & Lyle |
| Südzucker AG |
| Others |
Supply & Pricing Matrix
Enzymatic extraction technology is simultaneously compressing processing costs and concentrating supply power among Brazilian integrated mills capable of deploying cellulase systems at scale. This dual transformation rewards processors with captive agricultural networks while squeezing independent refiners dependent on spot-market cane supply.
Pricing Analysis
Capacity additions in Brazil are reshaping price floors for crystalline sucrose as São Paulo state mills expand enzymatic throughput. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade purity levels reflects membrane separation investment differentials. Cost compression in standard-grade beet sugar is intensifying because EU natural gas price volatility inflates crystallization energy costs. Beverage manufacturers exhibit highest price sensitivity due to bulk volume procurement, while pharmaceutical formulators accept premiums for USP-grade excipient documentation.
Supply Chain Analysis
Dual-sourcing qualification mandates from Nestlé and Unilever procurement teams require multinational buyers to maintain approved supplier lists across Brazil, India, and Thailand cane belts. Raw material flows draw from Saccharum officinarum harvests, corn wet milling dextrose, and blue agave nectar extraction. Single-source vulnerability concentrates around Santos port logistics chokepoints disrupting just-in-time delivery schedules. Distribution runs through integrated processor direct-tanker networks for beverage producers and commodity broker channels for mid-size food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as clean-label procurement criteria shift demand toward certified organic and non-GMO cane provenance. Premium specification requirements now dominate contract awards in confectionery and nutraceutical segments.
For Market Incumbents: Cement supply security through backward integration into Brazilian cane field operations or long-term offtake agreements with São Paulo cooperatives. Invest in membrane separation capacity to capture pharmaceutical-grade premiums before specialty chemical entrants scale competing purification assets. Synthetic sweetener substitution in carbonated soft drinks threatens bulk sucrose volume.
For New Entrants and Emerging Players: Mid-size craft beverage brands in Scandinavia and the Pacific Northwest represent an underserved buyer archetype seeking full-traceability documentation bypassing commodity exchanges. Precision fermentation capabilities for allulose and tagatose production target the fastest-expanding reduced-calorie formulation segment. Direct-to-manufacturer digital procurement platforms offer channel control without legacy broker network investments.
For Investors and Strategic Acquirers: Valuations sit cheapest among Eastern European beet processors facing EU F-Gas Regulation retrofit compliance burdens. Long-term viability hinges on consolidation plays capturing membrane-purification technology and pharmaceutical certification assets. Watch Indian FSSAI added-sugar threshold implementation as inflection indicator for monk fruit and erythritol blend demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Capacity Expansion | Brazilian mills deploying Novozymes cellulase systems achieve yield advantages over acid hydrolysis competitors. |
| Backward Integration into Cane Origination | Captive agricultural operations in São Paulo state secure supply continuity through harvest variability cycles. |
| Membrane Separation Technology Investment | Nanofiltration systems enable 99.9% purity saccharides commanding pharmaceutical and cosmetic grade premiums. |
| Precision Fermentation Scale-Up | Engineered yeast strains convert corn dextrose into rare sugars for low-calorie beverage formulations. |
| Direct-to-Manufacturer Platform Launch | Digital procurement channels bypass commodity brokers serving mid-size food tech startups with certification documentation. |
Research Methodology
Coverage spans Brazil, the United States, India, Germany, and China, with primary inputs from each market informing demand and supply assessments. Primary interviews with beverage formulation directors, pharmaceutical excipient procurement managers, cane mill operations heads, and enzymatic technology licensors combined with secondary validation from FDA GRAS determinations, ANVISA export documentation, FSSAI regulatory filings, and EU F-Gas Regulation compliance records. Bottom-up volume modeling and top-down value triangulation cross-validated segment estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, application specification, end-user procurement scale, and extraction technology capital intensity. CAGRs derived from historical trajectory analysis and elasticity-adjusted demand projections incorporate Brazilian bioethanol co-production economics and Indian regulatory threshold proposals as industry-specific forecast inputs.
Underlying measurement precision varies by segment; pharmaceutical-grade and cosmetic-grade saccharides carry tighter precision than commodity bulk sucrose due to certification documentation availability. Forecasts reflect documented assumptions regarding enzymatic yield improvement rates and regulatory implementation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
White Sugar Market
Sweeteners
Corn Syrup Market
Sweeteners
Palm Sugar Market
Sweeteners
Sanding Sugar Market
Sweeteners
Steviol Glycoside Market
Sweeteners
Dry Sweeteners Market
Sweeteners
Dextrose Syrup Market
Sweeteners
Canada Food Sweetener Market
Sweeteners
Rice Syrup Market
Sweeteners
Starch Glucose Syrup Market
Sweeteners
Natural Sweeteners Market
Sweeteners
Vietnam Food Sweetener Market
Sweeteners
Maltodextrin Market
Sweeteners
Maltitol Market
Sweeteners
Cassava Syrup Market
Sweeteners
Clarified Rice Syrup Market