
 Europe Sugar Substitute Market | 2026-2036
Europe Sugar Substitute Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sugar Substitute Market Foresight
The EU Green Deal and its Farm to Fork Strategy is rebalancing the cost-of-entry calculus for new sugar substitute suppliers by tightening environmental disclosure requirements across ingredient supply chains. Cargill leverages its European stevia extraction network to sustain volume leadership in plant-based sweeteners. Tate & Lyle anchors its position through specialized texturant systems that pair with reduced-sugar formulations. Südzucker AG competes via backward integration into beet-derived polyol production, controlling raw material flows across Central European processing plants.
Europe sugar substitutes encompass high-intensity sweeteners, bulk sweeteners, and natural extracts engineered to replicate sucrose's sensory profile while delivering reduced caloric content or glycemic response; stevia glycosides typically achieve 200-350x sucrose sweetness equivalence at extraction purities exceeding 95% rebaudioside A, serving industrial food manufacturers seeking clean-label positioning without sacrificing product viscosity or browning characteristics. Stevia dominates ingredient R&D investment as beverage formulators chase front-of-pack scoring advantages, while erythritol occupies the fastest-growing position in bakery applications where crystallization behavior and cooling effects prove functionally critical. Aspartame retains volume significance in confectionery despite ongoing EFSA safety reassessments, though margin pools are migrating toward natural-positioned alternatives with traceable supply chains.
EFSA's continuous sweetener safety evaluations and the EU's Nutri-Score front-of-pack labeling system collectively reshape product development priorities by penalizing added sugar content while demanding exhaustive toxicological documentation for novel ingredients. REACH compliance and the EU Green Deal's carbon border adjustments further filter market access, favoring suppliers with verified lifecycle data and regional manufacturing footprints. Stakeholders must monitor EFSA's pending opinions on stevia glycoside expansion and calibrate formulation investments against shifting member-state adoption of Nutri-Score variants.
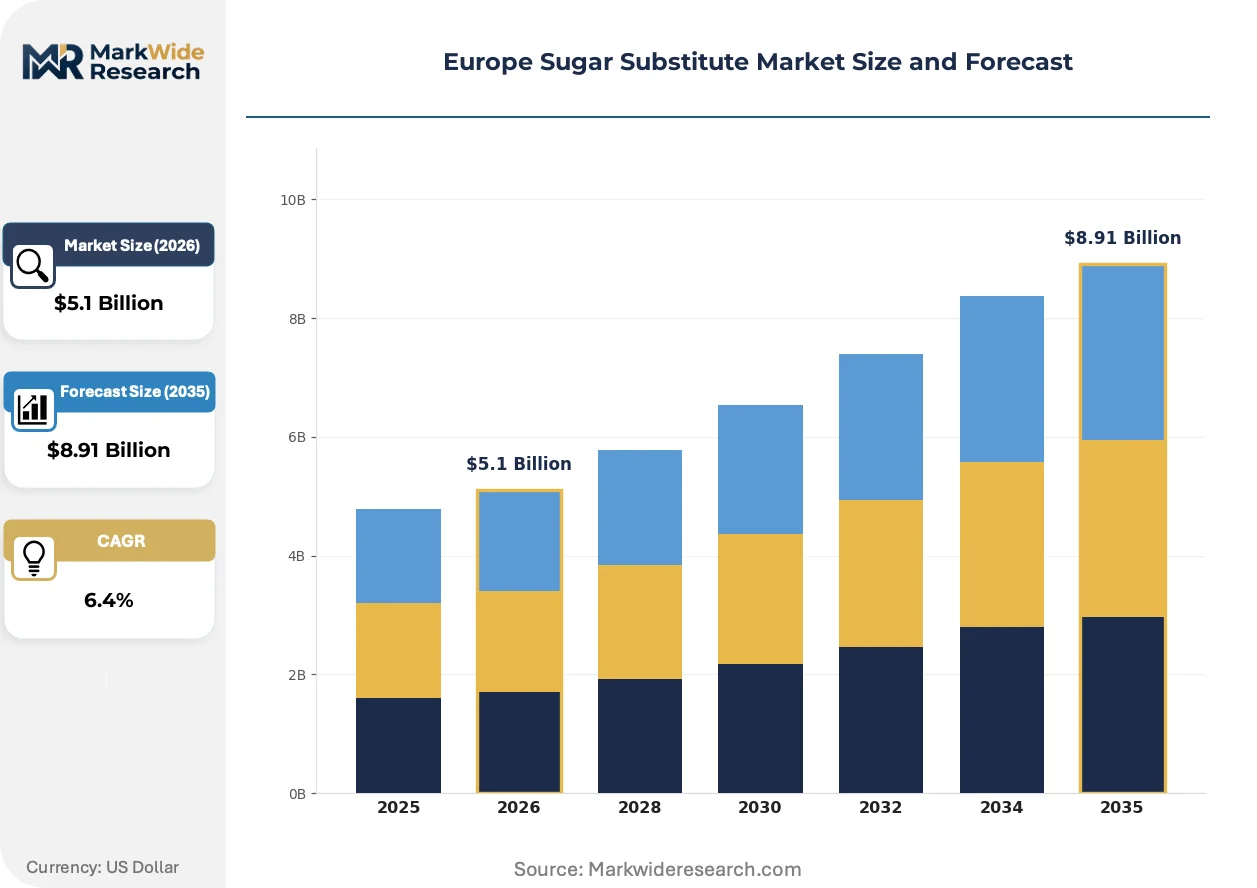
Market Dynamics
EFSA's pending stevia glycoside expansion opinions and the EU Green Deal's carbon border adjustments are compressing formulation timelines and redirecting procurement toward verified low-carbon supply chains.
Growth Catalysts
- Nutri-Score labeling:France's mandatory front-of-pack scoring penalizes added sugar, forcing beverage reformulation toward plant-based sweeteners with traceable origins.
- Stevia extraction efficiency gains:Industrial bioprocessing advances now yield rebaudioside A purities exceeding 95%, cutting unit costs for food manufacturers.
- Paris-Milan processing hub concentration:Western European food clusters aggregate demand for bulk polyols and high-intensity sweeteners, creating procurement density.
Market Restraints
- Beet sugar price volatility:Central European sucrose fluctuations compress margins for polyol producers dependent on beet-derived feedstocks.
- EFSA safety reassessment backlog:Pending toxicological opinions on novel glycosides freeze formulation investments and extend product launch timelines.
- Natural extract supply concentration:Stevia leaf sourcing concentrates in specific equatorial growing regions, exposing processors to climate and logistics risk.
Strategic Opportunities
- Eastern European penetration gap:Poland and Romania food manufacturers lag Western counterparts in clean-label adoption, creating first-mover positioning for suppliers with verified supply chains.
- Bakery erythritol expansion:Crystallization behavior and cooling effects in reduced-sugar baked goods open formulation partnerships with industrial bakeries.
- CSRD disclosure mandates:The EU's Corporate Sustainability Reporting Directive creates competitive advantage for sweetener suppliers with lifecycle carbon data and regional manufacturing footprints.
Industry Challenges
- REACH registration complexity:Novel sweetener molecules face extended chemical safety dossier preparation, delaying market access by 18-36 months.
- Reformulation skill scarcity:Food technologists capable of balancing sensory profiles with clean-label positioning command premium compensation and extended recruitment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sugar Substitute Market |
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $8.91 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevia, Aspartame, Saccharin, Erythritol Application: Beverages, Bakery, Dairy, Confectionery End User: Food Manufacturers, Beverage Companies, Healthcare Providers, Consumers Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Cargill, Tate & Lyle, Ingredion, Archer Daniels Midland Company, Roquette Frères, Ajinomoto Co., Inc., Südzucker AG, Kerry Group plc, DSM-Firmenich AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sugar Substitute Market Shifts & Advancements
Bioprocessing advances and regulatory disclosure mandates are redrawing competitive boundaries between synthetic and plant-derived sweetener categories.
Enzymatic stevia conversion is decentralizing extraction economics by enabling regional processing facilities to compete with centralized tropical operations. German and Dutch ingredient houses now deploy cell-culture bioreactors to produce glycosides without leaf dependency. This technology is decentralizing supply chain risk and compressing the premium previously commanded by vertically integrated stevia processors.
REACH compliance and the EU Green Deal's carbon border adjustments are tightening environmental documentation requirements across ingredient supply chains. Industrial buyers now mandate lifecycle carbon disclosures from sweetener suppliers, filtering market access toward those with verified regional manufacturing footprints. EFSA's pending opinions on stevia glycoside expansion are accelerating pre-submission data preparation among novel ingredient developers.
Clean-label procurement now dominates beverage manufacturer RFP criteria, displacing cost-per-unit as the primary vendor selection metric. Paris and Milan-based food processors specify traceable plant-derived sweeteners with front-of-pack scoring advantages. This preference shift concentrates volume among suppliers with certified sustainable sourcing and regional extraction capabilities.
Europe Sugar Substitute Market Segmentation
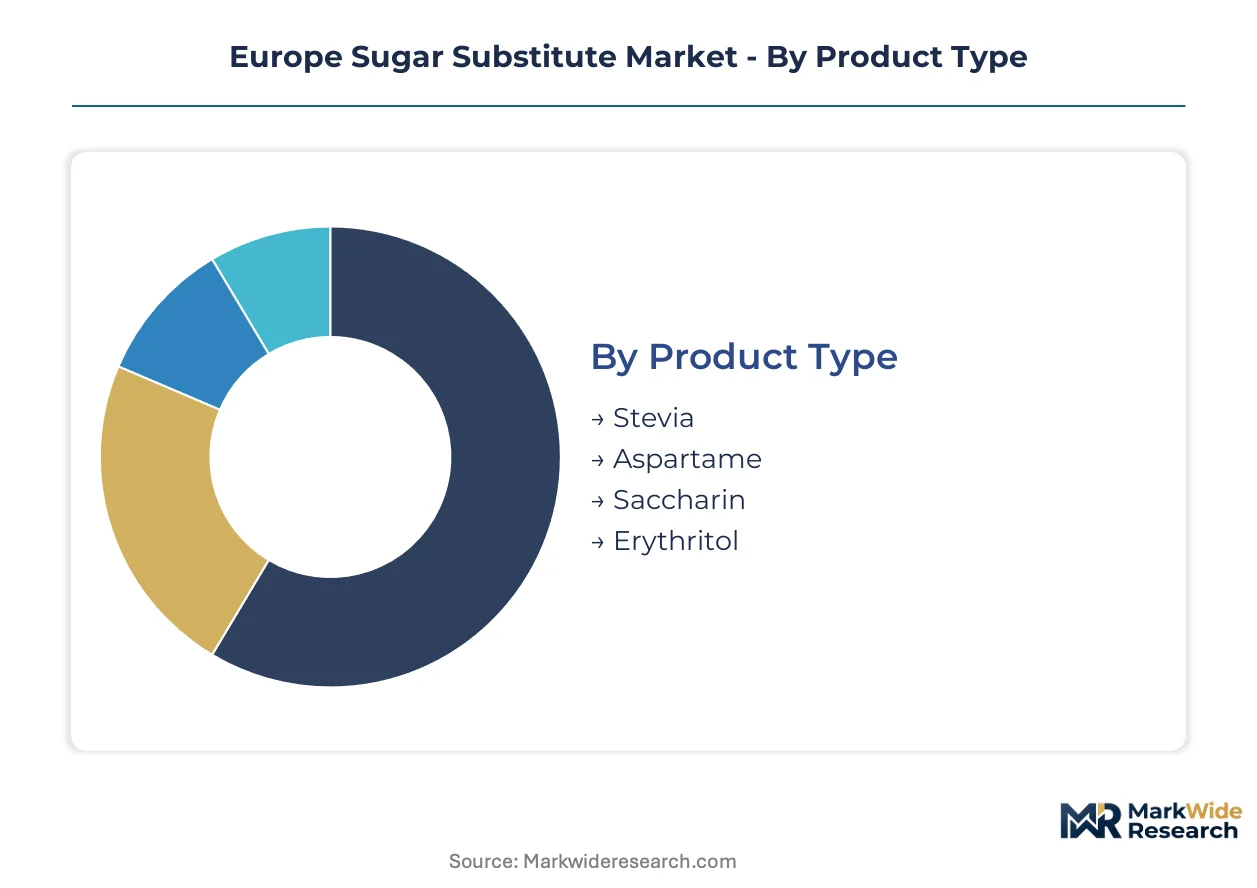
Sugar substitute procurement in Europe follows distinct technical and commercial logics that reshape supplier relationships. Formulators select sweetener categories based on front-of-pack scoring implications, functional performance in specific matrices, and traceability documentation requirements.
Product Type:
Buyers prioritize sweetness equivalence ratios, glycemic impact, and clean-label positioning when selecting among high-intensity and bulk alternatives.
- Stevia:Glycoside extracts achieve 200-350x sucrose sweetness at rebaudioside A purities exceeding 95%. French and German beverage manufacturers concentrate procurement here to secure Nutri-Score advantages and front-of-pack label improvements.
- Erythritol:A sugar alcohol with 60-70% sucrose sweetness and negligible caloric content, prized for crystallization behavior and cooling effects. Milan-based industrial bakeries drive demand expansion for reduced-sugar formulations requiring specific textural properties.
- Aspartame:Synthetic dipeptide delivering 200x sweetness equivalence; retains volume in confectionery despite EFSA safety reassessments and clean-label headwinds.
- Saccharin:Oldest high-intensity synthetic option at 300-400x sweetness; limited to specific tabletop and pharmaceutical applications with established tolerance profiles.
Volume sits with aspartame in legacy applications; growth tilts toward stevia as extraction efficiency gains compress unit economics.
Application:
Functional requirements vary sharply across matrices, determining sweetener selection based on heat stability, browning behavior, and viscosity contribution.
- Beverages:Liquid applications demand complete solubility and stability across pH ranges. Paris-based formulators lead reformulation pipelines targeting Nutri-Score upgrades through plant-derived high-intensity options.
- Bakery:Maillard reaction participation and moisture retention dictate bulk sweetener choices. Erythritol's crystallization properties address specific cooling and texture requirements in reduced-sugar cakes and pastries.
- Dairy:Fermentation compatibility and freeze-thaw stability filter options for yogurt and ice cream applications.
- Confectionery:Hard candy and chewing gum formulations prioritize heat stability and sustained release profiles.
Reformulation intensity runs highest in beverages; bakery applications show steepest expansion trajectory as erythritol supply scales.
End User:
Procurement scale and technical capability separate industrial buyers from retail-channel purchasers.
- Food Manufacturers:Industrial processors across Germany, France, and Italy aggregate bulk polyol and high-intensity volumes, specifying certified sustainable sourcing and lifecycle carbon disclosures under CSRD mandates.
- Beverage Companies:Dedicated R&D functions and reformulation pipelines concentrate in Western European hubs, prioritizing front-of-pack scoring optimization.
- Healthcare Providers:Clinical nutrition and diabetes management applications require glycemic response documentation and medical-grade purity certifications.
- Consumers:Retail tabletop and home-baking purchases flow through supermarket and online channels, price-sensitive and brand-driven.
Margin capture concentrates with food manufacturers; healthcare channels are gaining share fastest as clinical nutrition protocols expand.
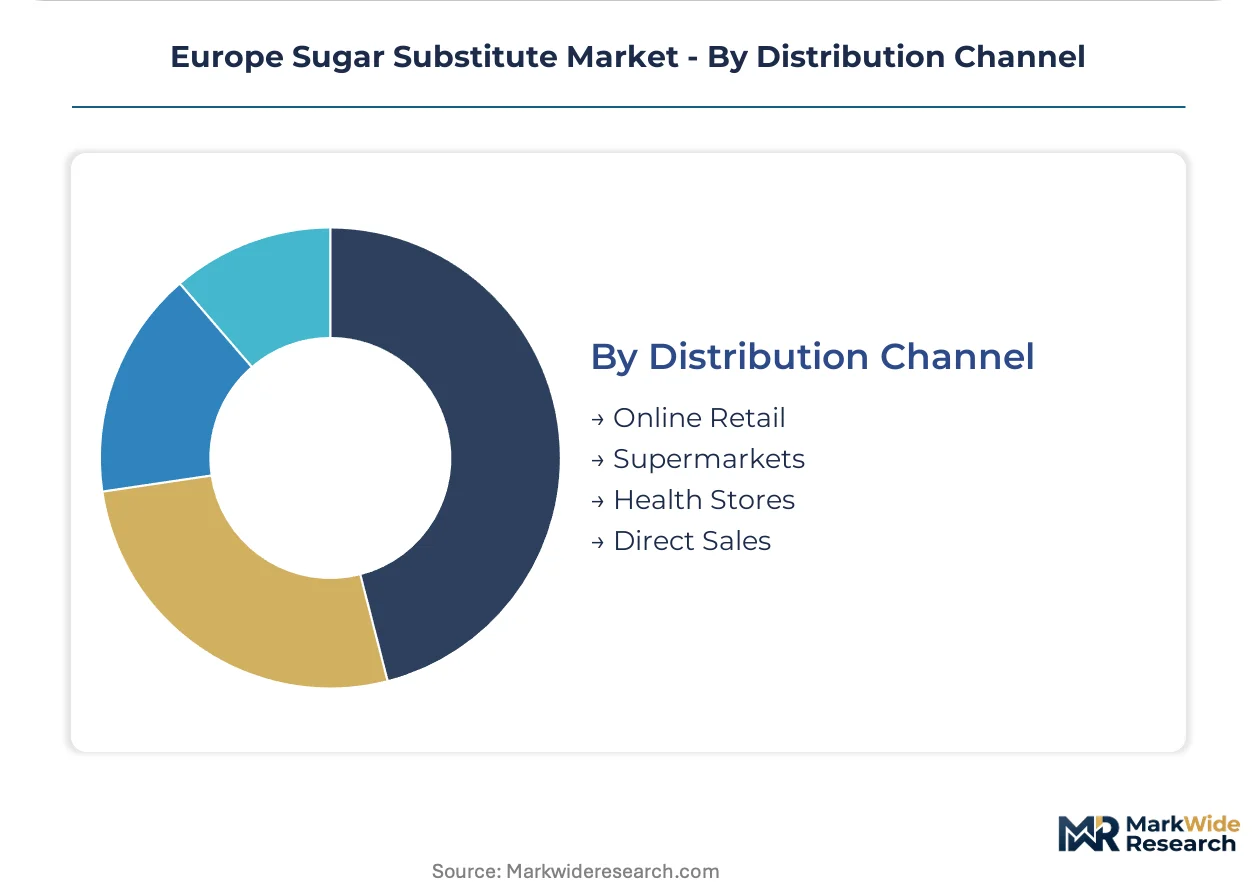
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and traceability documentation needs.
- Direct Sales:Bulk industrial volumes move through supplier-manufacturer relationships with embedded technical support and joint formulation development.
- Supermarkets:Retail tabletop sweeteners and consumer-packaged goods reach mass-market penetration through established grocery networks.
- Online Retail:Direct-to-consumer and small-business procurement channels expand for specialty and certified-organic variants.
- Health Stores:Premium-positioned natural extracts and functional sweeteners target wellness-focused consumers.
Direct sales anchor industrial volume; online retail is climbing the fastest as procurement digitization accelerates among mid-tier food processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's Parc d'Activités de Rungis and Germany's Bioeconomy Cluster Mitteldeutschland anchor European sugar substitute production through tax-advantaged zones that concentrate extraction and formulation infrastructure. These designated areas attract multinational ingredient houses seeking proximity to Paris-Milan food processing corridors.
Germany
Beverage reformulation pipelines at Düsseldorf and Hamburg headquarters drive stevia glycoside procurement from regional extraction networks. EFSA's pending safety opinions on novel sweeteners shape R&D timelines for domestic formulators. The Bioeconomy Cluster Mitteldeutschland aggregates bioprocessing facilities that convert agricultural feedstocks into polyol intermediates.
France
Mandatory Nutri-Score labeling forces Paris-based beverage manufacturers toward plant-derived high-intensity alternatives with traceable supply chains. ANSM coordinates with EFSA on novel food ingredient assessments, extending pre-market approval durations. The Parc d'Activités de Rungis outside Paris concentrates flavor houses and sweetener distributors serving reformulation demand.
Italy
Milan industrial bakeries specify erythritol volumes for reduced-sugar formulations requiring specific crystallization behavior. REACH compliance documentation filters supplier access to northern Italian food processing clusters. The Emilia-Romagna corridor hosts polyol distributors warehousing bulk sweeteners for pan-European redistribution.
Netherlands
Rotterdam port infrastructure enables stevia leaf importation and extraction feedstock distribution across Rhine-Ruhr manufacturing zones. ECHA administers REACH registration requirements that delay novel molecule market entry by chemical safety dossier preparation. Amsterdam headquarters of multinational ingredient traders coordinate procurement from certified sustainable sourcing programs.
Poland
Warsaw and Krakow food manufacturers lag Western European counterparts in clean-label adoption, creating positioning opportunities for suppliers with verified supply chains. EU Green Deal carbon border adjustments redirect procurement toward regional manufacturing footprints with lifecycle documentation. The Łódź special economic zone attracts sweetener distributors targeting underpenetrated Central European bakery and confectionery channels.
Europe Sugar Substitute Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation partnerships and extraction technology licensing. The vendor base organizes into three tiers: multinational agribusinesses with integrated supply chains, mid-cap ingredient houses with specialized texturant capabilities, and regional bioprocessors leveraging enzymatic conversion advances. Consolidation pressure runs highest among stevia extractors facing carbon disclosure mandates. Dominant competitive moves include backward integration into beet-derived feedstocks and joint formulation development with beverage manufacturers.
Within the diversified agribusiness tier, Cargill leverages its European stevia extraction network to anchor volume positions, while Tate & Lyle occupies a specialized texturant niche pairing reduced-sugar formulations with functional ingredient systems. Südzucker AG represents the backward-integrated archetype through captive beet polyol production across Central European processing plants.
| Leading Market Players |
|---|
| Cargill |
| Tate & Lyle |
| Ingredion |
| Archer Daniels Midland Company |
| Roquette Frères |
| Ajinomoto Co., Inc. |
| Südzucker AG |
| Kerry Group plc |
| DSM-Firmenich AG |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap stevia processors across Germany and France anchor regional supply networks through generational capital structures that resist short-term margin compression. Their patient financing enables sustained investment in enzymatic conversion capacity, creating pricing discipline that spot-market traders cannot match.
Pricing Analysis
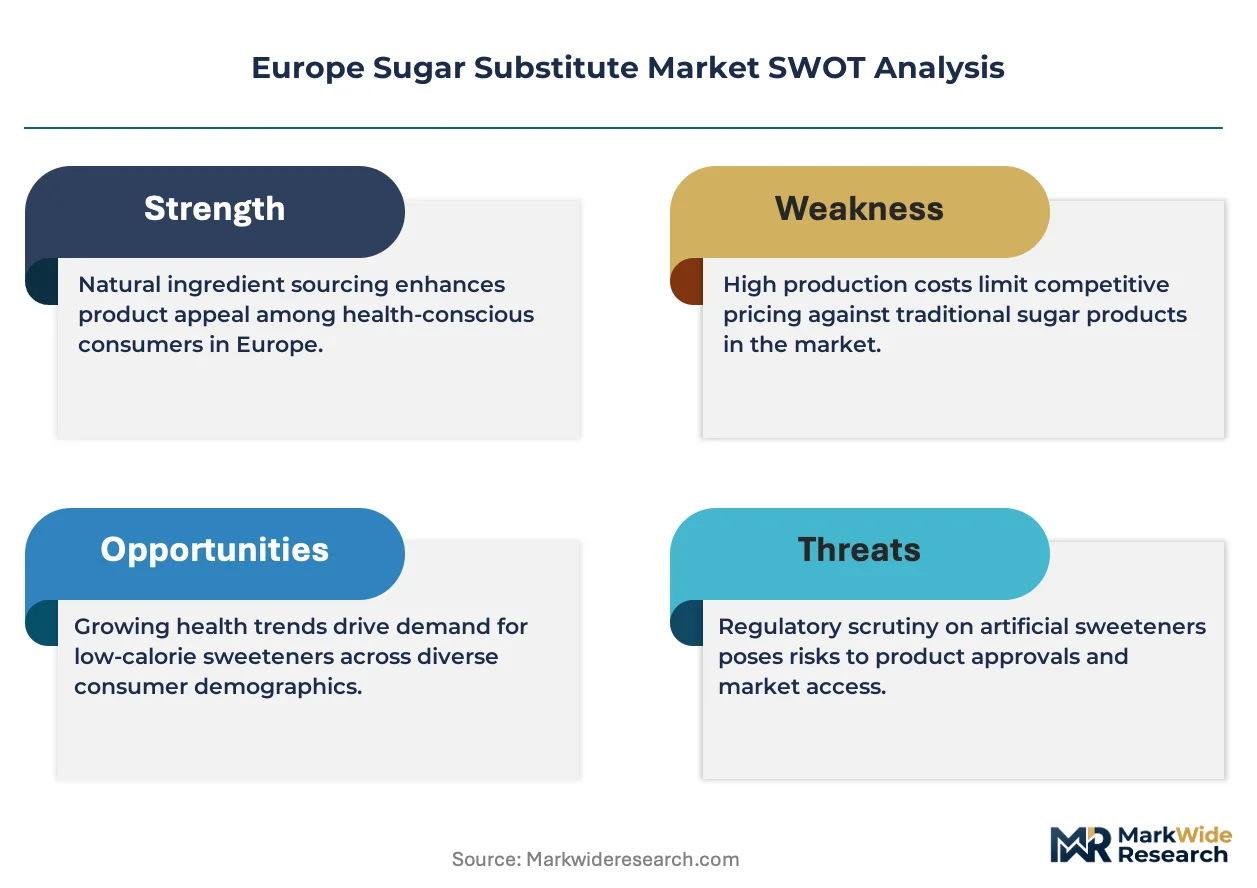
Premium pricing attaches to rebaudioside A extracts delivered within compressed lead times, while spot inventory of lower-purity glycosides trades at meaningful discounts. Three-tier pricing structure across premium, standard, and economy levels separates certified-organic stevia from conventional extracts and commodity-grade polyols. Pricing pressure stems from beet sugar price volatility compressing polyol margins. Industrial food manufacturers show lowest price sensitivity due to reformulation lock-in costs, while retail tabletop purchasers remain highly elastic.
Supply Chain Analysis
Freight costs from equatorial stevia growing regions to Rotterdam and Hamburg ports represent a structural cost layer that regional bioprocessors are eliminating through cell-culture production. Supply concentrates in Paraguay, Kenya, and China for leaf-derived glycosides, while Germany, France, and the Netherlands host extraction and formulation infrastructure. Raw material flows depend on stevia leaf harvests, beet sugar feedstocks, and fermentation substrates. Single-source vulnerability runs through concentrated equatorial leaf sourcing. Distribution runs through direct supplier-manufacturer relationships with embedded technical service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic bioreactor capacity constraints in Western Europe prop pricing power for incumbents with operational assets, creating a supply-constrained market structure that favors established processors.
For Market Incumbents: Cement volume positions through captive beet polyol production across Central European processing plants and accelerated certification investment for CSRD-compliant lifecycle documentation. Emerging cell-culture competitors from Dutch and German biotech clusters threaten extraction-based margin pools. Backward integration into regional fermentation capacity is the priority lever. For New Entrants and Emerging Players: The price-point gap between premium certified-organic stevia and economy-grade aspartame creates entry space for mid-tier positioning. Poland and Romania food manufacturers lag in clean-label adoption, offering first-mover positioning. Bakery erythritol partnerships with Milan industrial bakeries provide the most penetrable application wedge. A technical service-heavy direct sales model accelerates credibility building. For Investors and Strategic Acquirers: EFSA's pending stevia glycoside expansion opinions are the leading indicator that regulatory clearance timelines will compress competitive windows. The five-to-ten-year viability frame favors processors with diversified extraction technology portfolios over single-source leaf-dependent operators. Acquisition targets should show enzymatic conversion capabilities or established CSRD documentation systems. Watch EFSA publication schedules for inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beet Polyol Production | Südzucker AG's captive feedstock control insulates margin pools from sucrose price swings. |
| Enzymatic Stevia Conversion Deployment | German and Dutch bioreactor facilities decentralize supply risk from equatorial leaf concentration. |
| CSRD Lifecycle Documentation Investment | Verified carbon data filters procurement access under EU Green Deal disclosure mandates. |
| Joint Formulation Development Partnerships | Tate & Lyle's texturant pairings lock in beverage manufacturer R&D pipelines. |
| Eastern European Distribution Expansion | Łódź special economic zone positioning captures underpenetrated Polish and Romanian bakery demand. |
Research Methodology
EFSA safety opinion archives, EU customs trade databases, and CSRD disclosure filings formed the secondary backbone of this analysis. Primary interviews with beverage formulation directors, sweetener procurement leads at industrial food processors, stevia extraction plant managers, and EFSA regulatory affairs specialists validated segment assumptions. Bottom-up volume estimates from application-level consumption patterns were triangulated against top-down macroeconomic indicators across the European food manufacturing sector.
Historical trendline analysis of sweetener substitution rates in beverage and bakery applications established baseline growth trajectories. The analytical framework modeled volume and value across product type, application matrix, end-user scale, and distribution channel dimensions throughout the forecast period. CAGRs were derived from regression analysis of segment-specific adoption curves, incorporating Nutri-Score regulatory diffusion rates and enzymatic extraction cost decline trajectories as key inputs.
Inputs from EFSA pre-submission databases and EU member-state Nutri-Score adoption records were available through the study window; gaps in proprietary extraction cost data from private stevia processors introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions about regulatory timeline acceleration and clean-label procurement preference shifts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sanding Sugar Market
Sweeteners
South Africa Food Sweetener Market
Sweeteners
Low-Calorie Sweetener Market
Sweeteners
Specialty Sweeteners Market
Sweeteners
Floral Nectar Market
Sweeteners
High-Intensity Sweeteners Market
Sweeteners
Fructose Market
Sweeteners
Crystalline Fructose Market
Sweeteners
Argentina Food Sweetener Market
Sweeteners
China Allulose Market
Sweeteners
Palm Sugar Market
Sweeteners
Natural Malt Sweeteners Market
Sweeteners
North America Low-Calorie Sweeteners Market
Sweeteners
Saudi Arabia Allulose Market
Sweeteners
Sour Sugar Market
Sweeteners
Compressible Sugar Market