
 Plant-Based Natural Flavor Market | 2026-2036
Plant-Based Natural Flavor Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Natural Flavor Market Insights
Vanillin derived from petrochemical feedstock is consolidating toward ferulic acid and rice bran oil bioconversion pathways as enzymatic processing cuts production costs. Givaudan leverages captive biotechnology platforms to secure fermentation-derived vanillin supply chains. Symrise AG anchors European extraction capacity through specialized botanical sourcing networks in Madagascar and Southeast Asia. Kerry Group competes on integrated taste-and-nutrition systems that bind flavor delivery with plant protein masking technology.
Plant-based natural flavors comprise volatile and non-volatile aromatic compounds extracted from fruits, vegetables, herbs, spices, and botanicals through steam distillation, solvent extraction, or microbial fermentation, typically standardized at specific fold concentrations for batch consistency in industrial food production. Their primary commercial purpose is to impart or enhance taste and aroma profiles in finished consumer goods while satisfying clean-label and non-GMO positioning requirements. Essences and extracts dominate current volume flows due to established beverage industry demand, whereas spray-dried powders capture expanding margin pools in shelf-stable snack and dairy alternative applications where thermal stability and extended release properties command formulation premiums. Liquid formats retain the largest share of food manufacturer procurement, though granular forms are gaining traction in bakery segment trials for dusting and dry-mix compatibility.
FDA GRAS self-determination and EU Flavouring Regulation (EC) No 1334/2008 govern substance authorization and labeling thresholds, while EFSA safety evaluations for novel botanical extracts extend compliance timelines for new market entrants. BIS certification requirements in India and China's GB standards for food flavorings add layered conformity costs for suppliers targeting Asia-Pacific expansion. Stakeholders must monitor evolving national positive lists for permitted extraction solvents and maximum residue limits as regulatory divergence between major economies intensifies qualification burdens.
Market Dynamics
Enzymatic bioconversion of ferulic acid into vanillin is compressing synthetic flavor production economics, forcing incumbent chemical manufacturers to retool toward fermentation-derived pathways or exit aromatic compound segments entirely.
Growth Catalysts
- EU Flavouring Regulation (EC) No 1334/2008:Mandatory additive disclosure thresholds are accelerating clean-label procurement across German and French beverage manufacturing, expanding contract volumes for botanical extraction houses.
- Carbonated soft drinks:Formulators in North American bottling operations are specifying standardized fold concentrations of citrus and spice essences to maintain batch consistency at industrial scale.
- Rice bran oil feedstock:Southeast Asian agricultural processing clusters are supplying refined ferulic acid precursors to enzymatic bioconversion facilities, anchoring regional supply security.
Market Restraints
- Madagascar vanilla orchid concentration:Cyclone exposure and political instability in primary growing regions creates supply interruption risk for natural vanillin extraction.
- EFSA novel extract evaluations:Extended safety assessment timelines for new botanical sources delay product launches by 18-36 months, freezing formulation pipelines.
- Petrochemical-derived synthetic vanillin:Mature production infrastructure and residual cost advantages in Asian chemical manufacturing maintain price pressure on biobased alternatives.
Strategic Opportunities
- India BIS certification pathway:Harmonized flavoring standards under Bureau of Indian Safety protocols are opening procurement channels for compliant European and North American suppliers.
- Spray-dried thermal stability:Powder formats with extended-release properties are penetrating shelf-stable snack and plant-based dairy alternative applications where liquid essences fail.
- GB standards alignment:China's national food flavoring safety frameworks are converging with CODEX Alimentarius, reducing dual-compliance burdens for exporters targeting domestic distribution.
Industry Challenges
- Cross-regulatory solvent residue limits:Divergent maximum permissible thresholds for hexane and ethanol extraction across FDA, EFSA, and BIS jurisdictions force redundant testing protocols.
- Botanical authentication expertise:Shortage of analytical chemists trained in isotope ratio mass spectrometry and DNA barcoding for natural-origin verification creates quality control bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Natural Flavor Market |
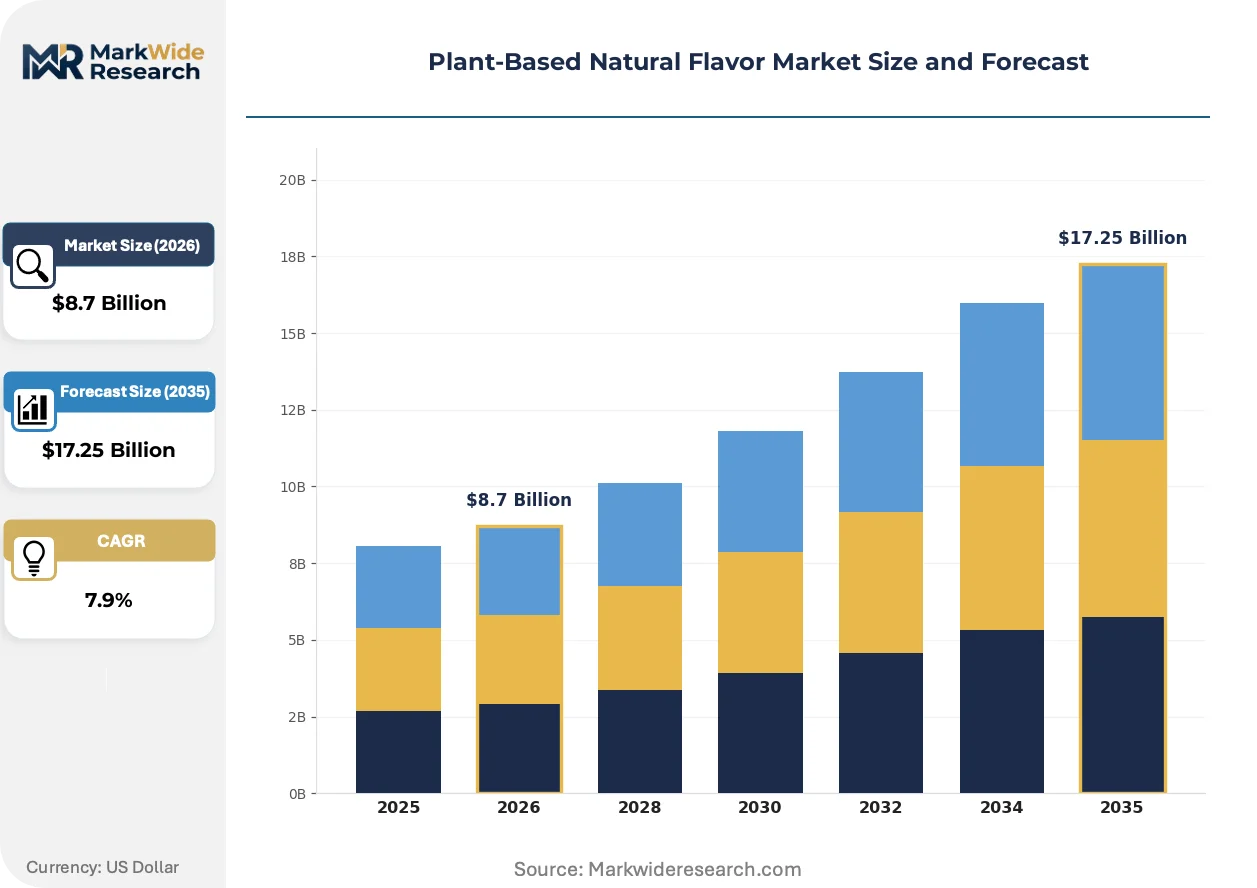
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.25 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essences, Extracts, Concentrates, Powders Application: Beverages, Bakery, Snacks, Dairy Alternatives Form: Liquid, Solid, Granular, Spray-Dried Customer Type: Food Manufacturers, Beverage Producers, Retailers, Food Service |
| Companies Covered | Givaudan, International Flavors & Fragrances Inc., Symrise AG, Firmenich, Kerry Group, Sensient Technologies Corporation, Takasago International Corporation, dsm-firmenich, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Natural Flavor Market Trends and Innovations
Biotechnology platforms are fragmenting traditional extraction economics, enabling precision fermentation to compete with field-grown botanicals on cost and consistency metrics previously unattainable.
Precision fermentation of aromatic compounds is modularizing flavor manufacturing infrastructure. Mid-scale bioreactor installations in food ingredient parks are allowing regional producers to bypass concentrated extraction hubs. This distributed production architecture is compressing logistics costs and shortening lead times for beverage manufacturers requiring just-in-time flavor delivery.
REACH registration requirements for novel extraction solvents are tightening substance authorization protocols. Industrial consequence includes accelerated phase-out of petroleum-derived carriers in favor of GRAS-listed alternatives. German flavor houses are responding by retrofitting solvent recovery systems to meet tightened volatile organic compound emission thresholds.
Direct procurement contracts between beverage formulators and biotechnology platforms are displacing traditional flavor house intermediation. Large North American bottling groups are establishing captive supply agreements with fermentation-derived aromatic producers. This channel restructuring is most visible in carbonated soft drink and flavored water segments where volume commitments justify dedicated production capacity.
Plant-Based Natural Flavor Market Segmentation
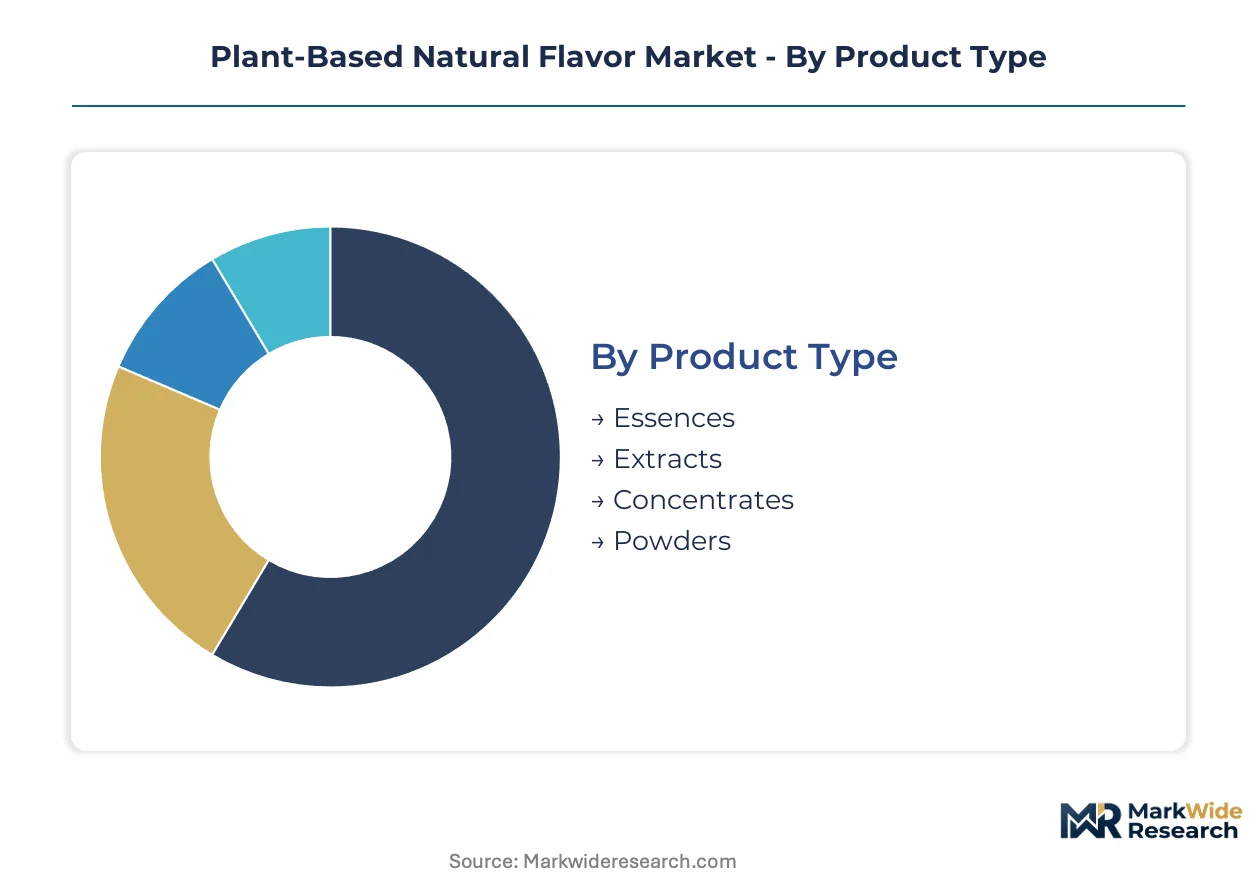
Segmentation in plant-based natural flavors reveals how technical specifications, end-use requirements, and supply chain configurations create distinct value pools. Formulators select product types and formats based on thermal stability needs, label positioning, and procurement scale.
Product Type:
Essences and extracts command the volume base, while concentrates and powders capture premium margins through concentration efficiency and shelf stability.
- Essences:Volatile aromatic compounds recovered through steam distillation, typically standardized at 5-10 fold concentration for batch consistency in high-volume beverage production. North American carbonated soft drink bottlers specify essences for citrus and spice profiles where cost-per-liter dominates procurement decisions.
- Extracts:Solvent-derived concentrated solutions from botanical maceration, offering deeper flavor intensity than essences for premium applications. German formulators source vanilla and cocoa extracts for clean-label positioning under tightened EU Flavouring Regulation disclosure thresholds.
- Concentrates:High-potency reduced-volume formats enabling logistics efficiency.
- Powders:Spray-dried or encapsulated carriers for dry-mix compatibility and extended shelf life.
Today's leader: Essences. Tomorrow's challenger: Powders.
Application:
Beverage procurement scales largest by volume, though dairy alternatives and snacks are climbing the fastest as plant-based positioning expands.
- Beverages:Carbonated soft drinks, flavored waters, and functional drinks requiring consistent dosing across billion-unit production runs. Citrus, berry, and botanical essences dominate procurement from extraction houses serving North American and European bottling operations.
- Bakery:Heat-stable vanillin and spice extracts for cookies, cakes, and pastries where Maillard reaction compatibility matters. French and German industrial bakeries specify encapsulated formats to prevent volatile loss during oven exposure.
- Snacks:Savory and sweet profiles for extruded and coated products demanding thermal resilience.
- Dairy Alternatives:Masking systems for off-notes in oat, almond, and soy bases, binding flavor delivery with protein stabilization.
Beverages anchor current procurement volumes; dairy alternatives are expanding most quickly as formulation complexity intensifies.
Form:
Liquid formats retain manufacturing integration advantages, though solid and spray-dried forms are gaining formulation share where powder handling simplifies dry-mix operations.
- Liquid:Standardized solutions and suspensions for direct dosing into batch tanks and continuous processing lines. Food manufacturers prefer liquids for ease of metering and immediate dispersion in aqueous systems.
- Solid:Compressed or crystalline formats for controlled-release applications in confectionery and chewing gum.
- Granular:Free-flowing particles for dusting and topical application in bakery finishing operations.
- Spray-Dried:Encapsulated aromatic compounds in maltodextrin or gum arabic matrices, providing thermal protection and extended release for shelf-stable snacks and plant-based dairy alternatives where liquid essences degrade.
Liquid forms dominate current procurement; spray-dried formats are gaining share fastest in shelf-stable and plant-based segments.
Customer Type:
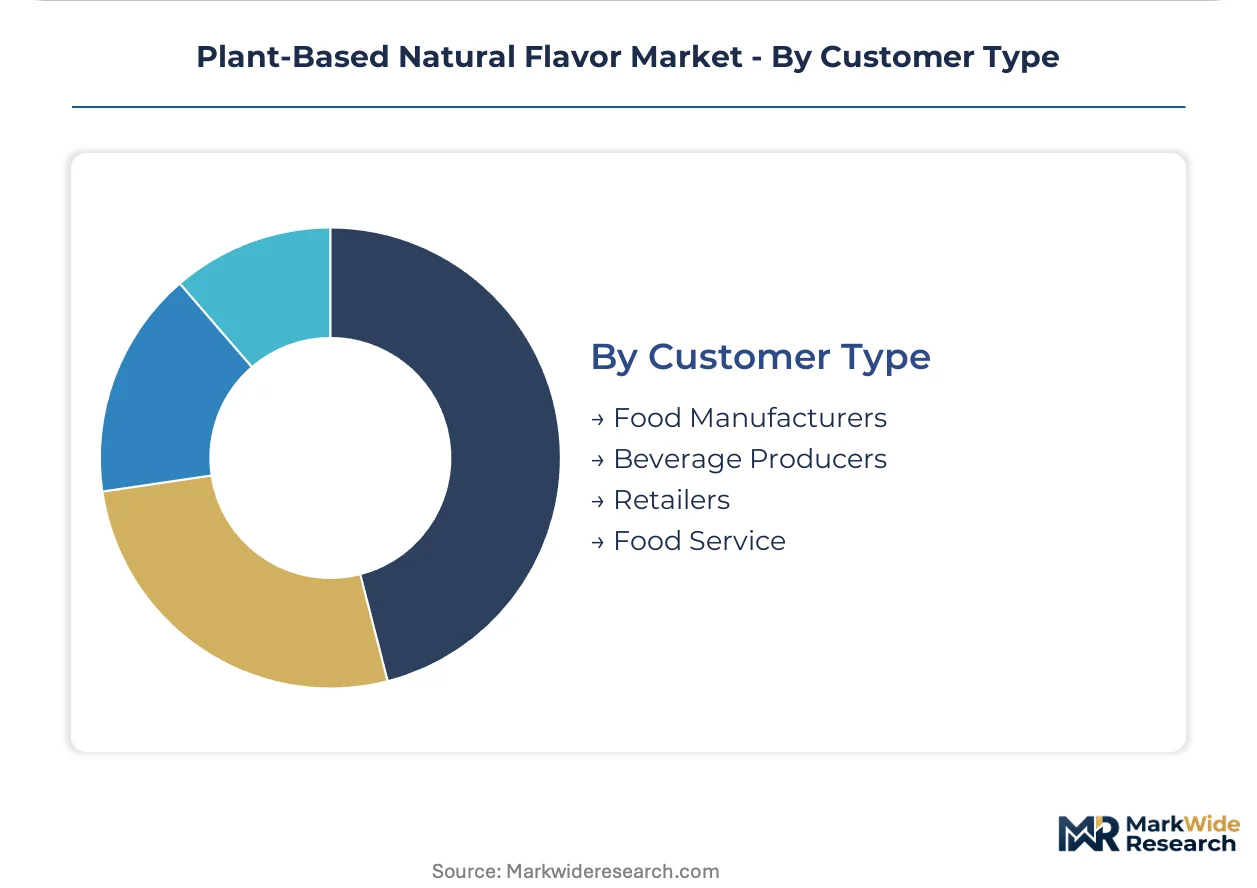
Food manufacturers and beverage producers drive contract volumes, while retailers and food service operators are consolidating direct sourcing to control label positioning.
- Food Manufacturers:Industrial-scale buyers of standardized flavor systems for baked goods, confectionery, and processed foods. Procurement emphasizes batch consistency, regulatory documentation, and long-term supply security.
- Beverage Producers:Bottling groups and co-packers specifying essences and extracts for carbonated and still drinks. North American operations are establishing direct contracts with fermentation-derived aromatic suppliers to bypass traditional flavor house intermediation.
- Retailers:Private-label brands sourcing clean-label flavors for store-brand positioning.
- Food Service:Restaurant chains and institutional caterers procuring concentrated formats for fountain and kitchen applications.
Food manufacturers hold current volume leadership; beverage producers are restructuring procurement fastest through captive biotechnology agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Botanical extraction clusters in Madagascar anchor vanilla supply chains for European formulators. German beverage manufacturers drive procurement volumes for clean-label essences. Southeast Asian rice bran processing feeds enzymatic bioconversion facilities.
Germany
Carbonated soft drink and flavored water formulators specify standardized citrus and spice essences for batch consistency. EU Flavouring Regulation (EC) No 1334/2008 mandates additive disclosure thresholds that accelerate clean-label procurement. The Cologne-Düsseldorf industrial corridor hosts extraction houses serving German and French bottling operations.
United States
North American bottling groups establish direct contracts with fermentation-derived aromatic suppliers to bypass traditional intermediaries. FDA GRAS self-determination governs substance authorization for novel botanical extracts. Midwestern agricultural processing clusters supply refined ferulic acid precursors to enzymatic bioconversion facilities.
China
Domestic flavor houses align GB standards with CODEX Alimentarius to reduce dual-compliance burdens for exporters. SAMR and MEE oversight tightens volatile organic compound emission thresholds for extraction operations. Yangtze River Delta bioreactor installations enable regional producers to bypass concentrated extraction hubs.
India
Food manufacturers procure standardized flavor systems emphasizing batch consistency and regulatory documentation. BIS certification requirements under harmonized flavoring standards open procurement channels for compliant European suppliers. Maharashtra and Gujarat processing clusters supply botanical extracts for beverage and bakery applications.
Madagascar
Vanilla orchid cultivation faces cyclone exposure and political instability creating supply interruption risk for natural vanillin extraction. No single regulator dominates export-oriented agricultural processing. The Sava region maintains concentrated vanilla curing and extraction operations serving European and North American flavor houses.
Plant-Based Natural Flavor Market Competitive Landscape
Capacity expansion dominates the current landscape as biotechnology platforms fragment traditional extraction economics. The vendor base concentrates around integrated taste-and-nutrition systems specialists and fermentation-derived aromatic producers. Three strategic archetypes emerge: captive biotechnology platforms, specialized botanical sourcing networks, and integrated taste-and-nutrition systems providers. M&A activity and direct procurement contract restructuring represent the dominant competitive moves reshaping channel relationships.
Among European extraction specialists, Symrise AG and Givaudan exemplify divergent platform strategies. Symrise anchors European capacity through specialized botanical sourcing networks. Givaudan leverages captive biotechnology platforms to secure fermentation-derived supply chains. Kerry Group occupies a position binding flavor delivery with plant protein masking technology for dairy alternative applications.
| Leading Market Players |
|---|
| Givaudan |
| International Flavors & Fragrances Inc. |
| Symrise AG |
| Firmenich |
| Kerry Group |
| Sensient Technologies Corporation |
| Takasago International Corporation |
| dsm-firmenich |
| Cargill Incorporated |
| Others |
Pricing and Supply Chain Analysis
Ferulic acid spot pricing from Southeast Asian rice bran processors cascades through enzymatic bioconversion facilities into three distinct procurement tiers for beverage formulators, with fermentation-derived vanillin commanding premium positioning against petrochemical-sourced alternatives.
Pricing Analysis
Input-cost pass-through from Madagascar vanilla orchid volatility and rice bran oil feedstock fluctuations stratifies pricing across premium, standard, and economy tiers. Certification under EU Flavouring Regulation (EC) No 1334/2008 and FDA GRAS self-determination tiers create price differentiation between compliant and non-compliant suppliers. Pricing pressure stems from residual cost advantages in Asian synthetic vanillin manufacturing. Large North American bottling groups exhibit lowest price sensitivity due to volume commitments, while regional snack producers face acute margin compression.
Supply Chain Analysis
Direct-to-beverage-manufacturer channels handle hyperscale demand from North American bottling groups, displacing traditional flavor house intermediation. Raw material sourcing concentrates in Madagascar for vanilla orchids, Southeast Asia for rice bran oil feedstock, and Germany for botanical extraction capacity. Supply chains draw from ferulic acid precursors, cured vanilla beans, and citrus peel biomass. Single-source vulnerability in Madagascar's Sava region creates structural interruption risk from cyclone exposure. Distribution runs through fermentation facility networks, extraction houses, and direct biotechnology platform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU Flavouring Regulation (EC) No 1334/2008 additive disclosure mandates accelerate clean-label procurement cycles across German and French beverage manufacturing.
For Market Incumbents: Hedge against biotechnology platform disruption by securing captive fermentation-derived aromatic supply chains through backward integration into enzymatic bioconversion facilities. Anchor extraction capacity in Southeast Asian rice bran processing clusters to lock in ferulic acid precursor security against agricultural commodity volatility. For New Entrants and Emerging Players: Begin with spray-dried thermal stability formats for shelf-stable snack and plant-based dairy alternative applications, where incumbent liquid essence portfolios underperform. Target India's BIS certification pathway for harmonized flavoring standards compliance. Pursue direct procurement contracts with mid-scale beverage co-packers seeking just-in-time flavor delivery alternatives. For Investors and Strategic Acquirers: Asymmetric upside sits with biotechnology platforms possessing modular bioreactor installations in food ingredient parks. Long-term viability centers on precision fermentation capabilities that bypass field-grown botanical constraints. Monitor EFSA novel extract evaluation timelines as inflection signals for formulation pipeline acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive bioconversion facilities secure vanillin supply chains against Madagascar orchid volatility. |
| Spray-Dried Format Expansion | Thermal stability properties penetrate shelf-stable snack applications where liquid essences degrade. |
| BIS Certification Investment | Harmonized Indian standards open procurement channels for EU-compliant extraction houses. |
| Direct Biotechnology Platform Contracts | North American bottlers bypass traditional flavor intermediaries through captive supply agreements. |
| Botanical Authentication Infrastructure | Isotope ratio mass spectrometry capabilities address quality control bottlenecks in natural-origin verification. |
Research Methodology
Direct dialogue with flavor house procurement directors, beverage formulator R&D leads, extraction facility plant managers, and biotechnology platform technical directors grounded the qualitative foundation. Secondary validation drew from EU Flavouring Regulation filings, FDA GRAS determination notices, EFSA safety evaluation databases, and Bureau of Indian Standards certification records. Bottom-up and top-down triangulation cross-checked facility capacity data against end-use procurement volumes.
Segment-level outputs across the projection horizon reflect modeled interactions between product type, application, and form dimensions. CAGRs were derived from regression analysis against historical procurement patterns and regulatory implementation timelines. Industry-specific forecast inputs incorporated enzymatic bioconversion yield improvements and EU disclosure threshold enforcement schedules.
Several conditions sit outside the modeled scope, including unscheduled EFSA novel extract evaluation accelerations, Madagascar political instability scenarios beyond historical cyclone patterns, and breakthrough synthetic biology pathways displacing current fermentation economics. Forecasts reflect documented assumptions regarding regulatory harmonization trajectories and feedstock price continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Food Ingredients Market
Plant Based Food
Plant-Based Shrimp Market
Plant Based Food
Vegan Gelatin Market
Plant Based Food
Italy Plant Protein Market
Plant Based Food
Europe Rice Protein Market
Plant Based Food
Europe Plant-Based Meal Kit Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
Plant Based Eggs Market
Plant Based Food
Plant-Based Chorizo Market
Plant Based Food
Middle East and Africa Plant-Based Egg Market
Plant Based Food
New Jersey Vegan Products Market
Plant Based Food
Vegan Pastry Market
Plant Based Food
Meatless Meat Market
Plant Based Food
India Plant Based Meat Alternatives Market
Plant Based Food
Plant Based Breads Market
Plant Based Food
Vegan Alternatives Market