
 Plant Based Pasta Market | 2026-2036
Plant Based Pasta Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Pasta Market Analytics
Supermarket shelf space allocation between conventional and alternative pasta is narrowing as category managers recalibrate planograms for higher-margin SKUs. Barilla Group leverages its milling infrastructure to secure consistent semolina-alternative supply chains across Mediterranean sourcing zones. Banza LLC differentiates through chickpea-protein formulation expertise that commands premium placement in US natural channel sets. Nestlé sustains multi-brand portfolio breadth spanning mass-market penetration and specialty health positioning.
Plant based pasta denotes durum-wheat-free noodle products manufactured from legume, pseudocereal, or tuber flours, typically requiring extrusion temperatures below 55°C to preserve protein integrity and achieve al dente texture comparable to semolina benchmarks. The ingredient base segment anchors current revenue, with lentil and chickpea varieties occupying the deepest retail distribution and brown rice formulations competing on allergen-free positioning. Packaging type stratification reveals margin concentration in pouch formats targeting single-serve convenience, while bulk channels serve foodservice accounts with lower per-unit logistics overhead.
USDA organic certification and FDA food-labeling standards govern composition claims and allergen declarations in the American market, while EU REACH frameworks and EFSA novel food assessments shape ingredient approval timelines for European manufacturers. The EU Green Deal's farm-to-fork targets indirectly accelerate pulse-crop subsidies that feed raw material pipelines. Stakeholders must monitor evolving protein-content thresholds that regulators embed in standard-of-identity discussions, as these thresholds will determine which formulations qualify for pasta nomenclature versus alternative classification.
Market Dynamics
Extrusion temperature control below 55°C is virtualizing traditional pasta manufacturing economics by preserving protein integrity in legume flours while achieving semolina-comparable texture, forcing legacy wheat-dominant processors to retool thermal systems or cede premium shelf space.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Pulse-crop subsidies in Italy and Spain expand raw material pipelines for Mediterranean processors, lowering input cost volatility for chickpea and lentil formulations.
- University foodservice procurement:Corporate and campus dining programs in the United States accelerate volume pull-through via contracted annual volume commitments with specialty distributors.
- Low-temperature extrusion:This thermal processing technology preserves protein functionality in brown rice and pseudocereal blends, enabling allergen-free positioning without texture compromise.
Market Restraints
- Pulse flour supply concentration:Canadian and Australian lentil processors control over 60% of exportable protein-grade supply, exposing manufacturers to harvest volatility and freight cost spikes.
- Standard-of-identity thresholds:FDA and EFSA protein-content minimums for pasta nomenclature create regulatory friction for formulations below 12% protein, forcing reclassification to "noodle alternative" with reduced retail placement.
- Semolina price anchoring:Conventional durum wheat pasta maintains 40-60% cost advantage at shelf, limiting price elasticity for plant-based alternatives in mass-market channels.
Strategic Opportunities
- Single-serve pouch formats:Convenience-oriented packaging in Japanese convenience stores and US meal-kit channels commands 35-50% margin premiums over bulk formats.
- EFSA novel food approval acceleration:Simplified assessment pathways for traditional pulse ingredients reduce time-to-market for European innovators, compressing competitive response windows.
- Foodservice direct distribution:Bypassing retail slotting fees through institutional procurement contracts with hospital and airline catering operations rebuilds margin structure.
Industry Challenges
- Extrusion technician scarcity:Specialized knowledge of low-temperature screw profiles and die design for protein-rich doughs concentrates among Italian equipment manufacturers, creating hiring bottlenecks for new market entrants.
- Organic certification timelines:USDA and EU organic accreditation requires 18-36 months of supply chain documentation, delaying premium positioning for vertically integrated startups.
- Legacy wheat infrastructure lock-in:Conventional millers face stranded asset risk when retrofitting semolina lines for pulse processing, requiring parallel capital deployment rather than conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Pasta Market |
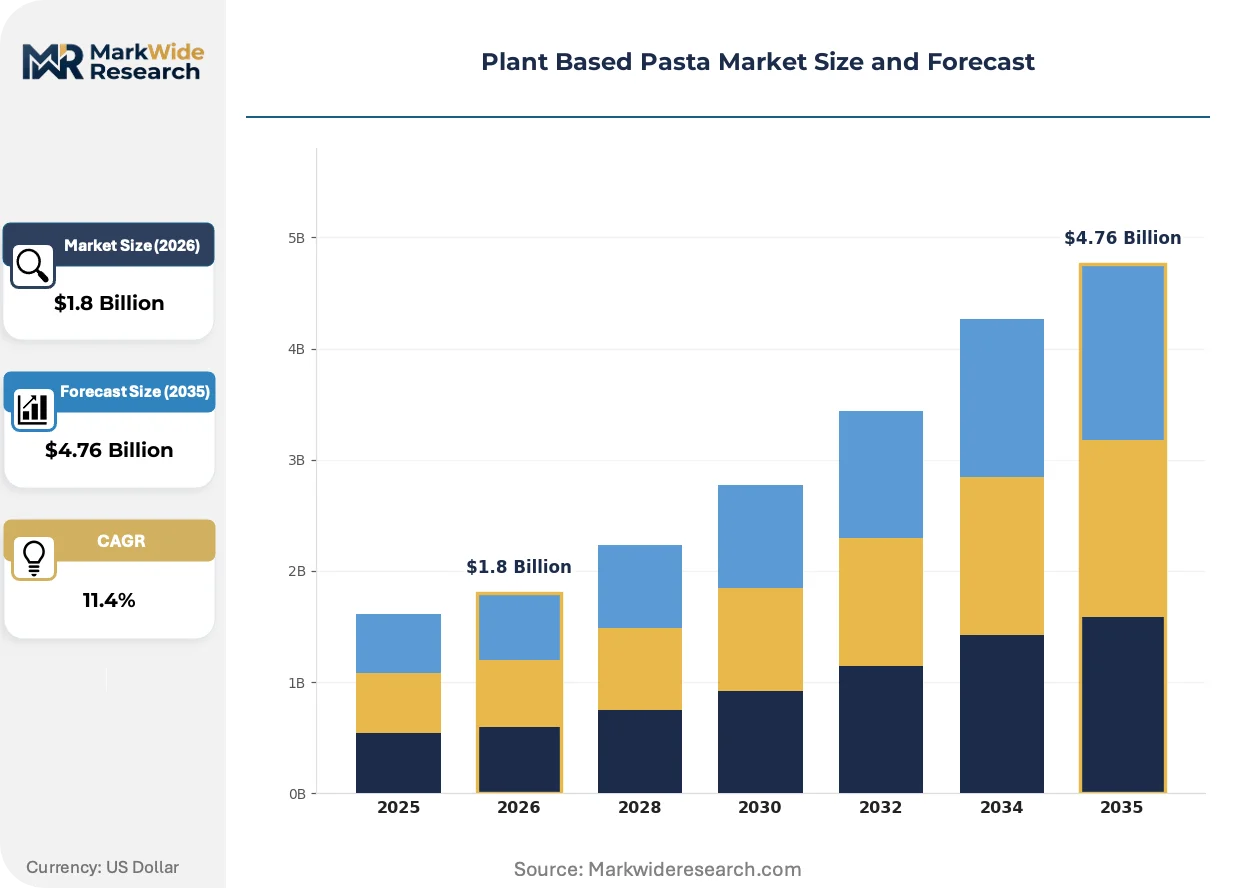
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spaghetti, Penne, Fusilli, Lasagna Ingredient Base: Lentil, Chickpea, Quinoa, Brown Rice Packaging Type: Box, Bag, Pouch, Bulk Distribution Channel: Online, Supermarkets, Health Stores, Specialty Retailers |
| Companies Covered | Rummo, General Mills, Inc, Barilla Group, Garofalo, Nestlé, De Cecco, Banza LLC, The Only Bean, Bionaturae LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Pasta Market Evolving Landscape
Digital twin modeling of extrusion parameters is compressing product development cycles while regulatory clarity on protein claims is reshaping formulation priorities across manufacturing bases.
Low-temperature twin-screw extrusion is virtualizing the boundary between traditional pasta texture and plant-protein functionality by enabling precise control of starch gelatinization and protein denaturation zones. Italian equipment suppliers are deploying these systems to brown rice and fava bean processors seeking al dente benchmarks. The technology is virtualizing quality differentiation, allowing mid-scale manufacturers to achieve texture parity with semolina without vertical integration into durum wheat milling.
EFSA's updated guidance on novel food assessments for traditional pulse varieties is compressing approval timelines from 24 months to 9-12 months for ingredients with documented consumption history. This regulatory shift enables faster SKU rotation for European manufacturers competing with North American imports. Brown rice and chickpea formulations receive the greatest benefit, as these ingredients already carry substantial safety dossiers.
Planogram recalibration by US and Italian supermarket category managers is displacing conventional pasta facings with higher-margin alternative SKUs, particularly in perimeter fresh sections and natural channel sets. Retail buyers now negotiate annual volume guarantees rather than slotting fee structures, transferring inventory risk upstream to manufacturers. This behavioral shift concentrates most visibly in Whole Foods Market and Eataly locations, where plant-based pasta occupies 15-20% of linear shelf space versus 3-5% in conventional grocers.
Plant Based Pasta Market Segmentation
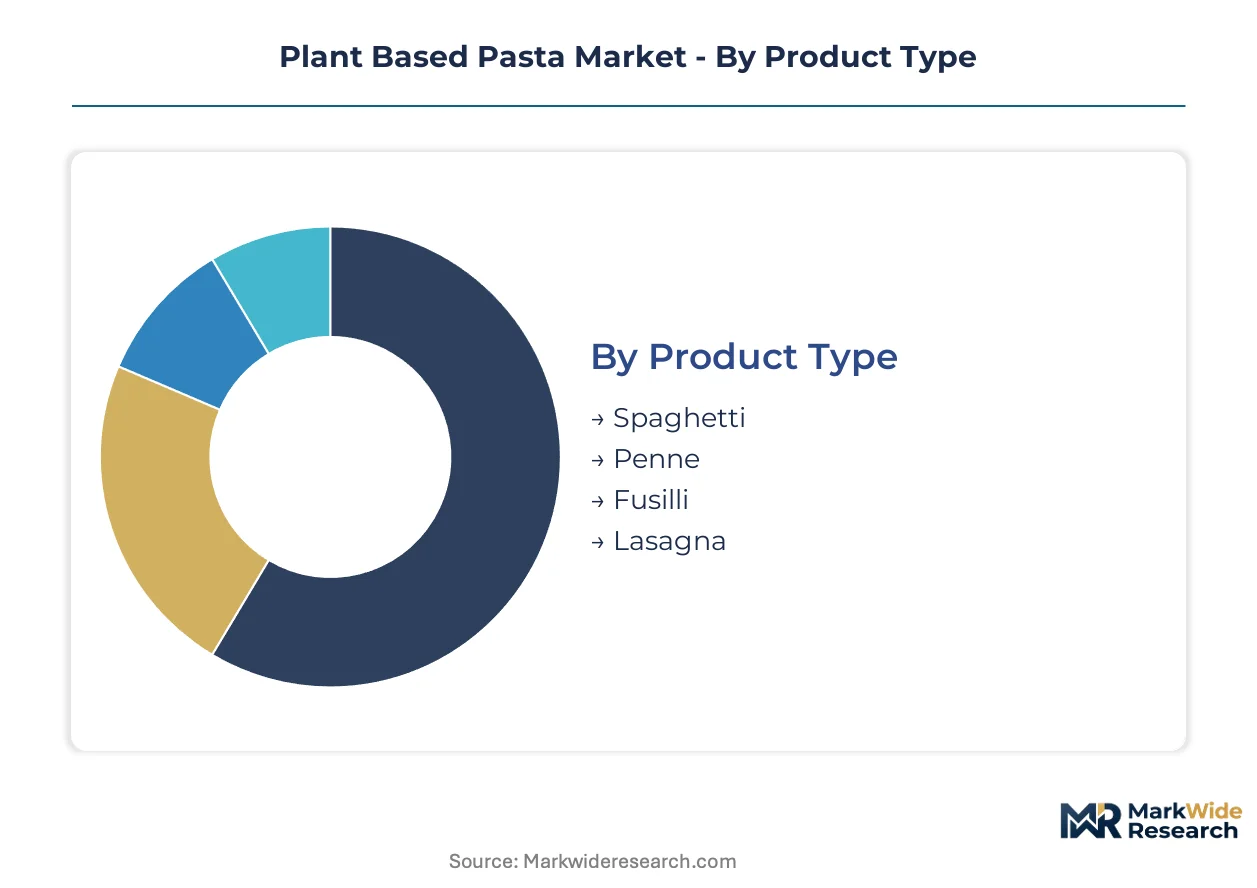
Segmentation in plant based pasta reveals how formulation choices and packaging formats create distinct margin profiles and channel access. Each dimension carries different capital intensity and after-sales service requirements, from extrusion equipment maintenance to cold-chain logistics for fresh formats.
Product Type:
After-sales service intensity varies sharply across pasta shapes, with long-cut formats demanding more precise die calibration and shorter replacement cycles than short-cut alternatives.
- Spaghetti:Long-cut extrusion requires specialized cooling tunnels and precision cutting blades that demand frequent technician service. Italian manufacturers dominate this segment through legacy equipment expertise, while US foodservice buyers specify spaghetti for university dining contracts requiring consistent cook times.
- Penne:Ridged tubular shapes achieve premium placement in US natural channel sets due to sauce-retention properties that justify higher price points. The bronze die extrusion process creates surface texture but accelerates equipment wear, driving annual maintenance contracts.
- Fusilli:Corkscrew geometry demands complex helical die designs with limited supplier base concentrated in Italian equipment manufacturers.
- Lasagna:Sheet formats require flatbed drying systems with higher capital footprint and specialized humidity control servicing.
By volume, spaghetti leads. By growth pace, penne is ahead.
Ingredient Base:
Cost tier stratification separates commodity pulse flours from premium pseudocereal positioning, with protein content thresholds determining regulatory classification and retail placement.
- Lentil:High-protein red and green lentil flours anchor the deepest retail distribution in North American mass-market channels. Canadian processors control exportable supply, exposing manufacturers to Prairie harvest volatility and rail freight spikes.
- Chickpea:Neutral flavor profile and established supply chains from Mediterranean sourcing zones command premium placement. Barilla Group leverages Italian pulse processing infrastructure to secure consistent semolina-alternative feedstock.
- Quinoa:Andean sourcing constraints and organic certification requirements position this base at the premium tier with limited volume scale.
- Brown Rice:Allergen-free positioning captures specialty diet consumers, though lower protein content risks FDA reclassification below pasta nomenclature thresholds.
By volume, lentil dominates shelf presence. By margin expansion, chickpea is climbing the fastest.
Packaging Type:
Volume throughput and per-unit logistics economics separate single-serve convenience formats from institutional bulk channels with divergent margin structures.
- Pouch:Single-serve flexible packaging commands 35-50% margin premiums in Japanese convenience stores and US meal-kit channels. The format requires nitrogen flushing equipment and specialized film sealing maintenance contracts.
- Box:Standard retail carton formats balance shelf stability with established recycling infrastructure across European and North American markets.
- Bag:Value-tier positioning in club stores and discount channels sacrifices margin for volume throughput and reduced packaging cost.
- Bulk:Foodservice accounts including hospital and airline catering operations bypass retail slotting fees through direct distribution contracts with lower per-unit logistics overhead.
By revenue contribution, pouch formats lead. By volume tonnage, bulk channels are expanding most quickly.
Distribution Channel:
Customer type concentration separates convenience-oriented digital buyers from planned pantry-stockers, with procurement patterns dictating inventory risk allocation between manufacturers and retailers.
- Supermarkets:Category managers at Whole Foods Market and Eataly now negotiate annual volume guarantees rather than slotting fee structures, transferring inventory risk upstream. Planogram recalibration has expanded plant-based pasta to 15-20% of linear shelf space in perimeter fresh sections.
- Online:Direct-to-consumer subscription models and meal-kit integrations capture repeat purchase data but require cold-chain logistics investment for fresh pasta variants.
- Health Stores:Natural channel sets prioritize USDA organic certification and non-GMO verification, with 18-36 month accreditation timelines delaying new entrant access.
- Specialty Retailers:Italian gourmet importers and regional pasta shops sustain premium pricing through provenance storytelling and limited-batch positioning.
By transaction volume, supermarkets lead. By customer acquisition efficiency, online channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal farm-to-fork targets pulse-crop subsidies across Mediterranean sourcing zones, lowering input cost volatility for chickpea and lentil processors. Italian equipment manufacturers concentrate low-temperature extrusion expertise, while US foodservice procurement accelerates volume pull-through via university dining contracts.
Italy
Traditional pasta heritage intersects with ingredient innovation from local pulse processors in Emilia-Romagna and Lombardy. EU REACH frameworks and EFSA novel food assessments shape ingredient approval timelines for Mediterranean manufacturers. Barilla Group leverages milling infrastructure across Piedmont and Veneto to secure consistent semolina-alternative supply chains.
United States
University and corporate dining programs accelerate volume pull-through via contracted annual commitments with specialty distributors. FDA updated guidance on plant protein labeling standards clarifies composition claims for domestic manufacturers. Banza LLC commands premium placement in natural channel sets through chickpea-protein formulation expertise developed in the US market.
Canada
Prairie lentil processors control over 60% of exportable protein-grade supply, anchoring raw material pipelines for North American manufacturers. Canadian harvest volatility and rail freight spikes expose manufacturers to input cost pressure. Saskatchewan and Alberta pulse processing clusters feed brown rice and lentil formulation supply chains.
Germany
EU organic certification requirements and EFSA protein-content thresholds create regulatory friction for formulations below 12% protein minimums. German supermarket category managers recalibrate planograms for higher-margin alternative SKUs in perimeter fresh sections. Bavaria and North Rhine-Westphalia host equipment distributors servicing low-temperature extrusion retrofit demand.
Australia
Lentil export supply concentration exposes Asia-Pacific manufacturers to harvest volatility and freight cost spikes from Australian processors. EFSA simplified assessment pathways for traditional pulse ingredients compress approval timelines for European market entry. Victoria and New South Wales pulse processing infrastructure supports regional formulation development.
Plant Based Pasta Market Competitive Landscape
On the supply side, the industry is consolidating around legacy wheat processors retooling for pulse extrusion and specialist legume formulators with captive ingredient sourcing. The vendor base stratifies across three archetypes: diversified food conglomerates with multi-brand portfolios, regional pasta specialists leveraging heritage equipment expertise, and venture-backed legume pure-plays with formulation IP. Dominant competitive moves include M&A for Mediterranean pulse processing assets and strategic partnerships with university foodservice procurement channels.
Within the heritage equipment tier, Barilla Group and De Cecco exemplify regional specialists with legacy milling infrastructure adaptable to semolina-alternative feedstocks. Among diversified conglomerates, General Mills, Inc. and Nestlé occupy positions spanning mass-market penetration and specialty health positioning. At the venture-backed formulation end, Banza LLC represents the legume-pure-play archetype with chickpea-protein expertise commanding premium retail placement.
| Leading Market Players |
|---|
| Rummo |
| General Mills, Inc |
| Barilla Group |
| Garofalo |
| Nestlé |
| De Cecco |
| Banza LLC |
| The Only Bean |
| Bionaturae LLC |
| Others |
Value Network & Pricing Analysis
Emilia-Romagna's pulse processing clusters in northern Italy concentrate lentil and chickpea milling capacity, translating harvest volatility into downstream pricing power for Mediterranean manufacturers negotiating annual feedstock contracts. This geographic concentration forces North American brands to absorb freight cost spikes or cede margin to secure protein-grade flour allocations.
Pricing Analysis
Certification level (USDA organic versus conventional) creates the primary spread between mass-market and premium shelf placement. Three-tier pricing structure across organic premium, standard natural, and economy club-store tiers anchors contract structures. Cost compression in the economy tier is intensifying because semolina maintains persistent cost advantage. Foodservice procurement managers exhibit lowest price sensitivity, while mass-market retail buyers negotiate hardest on per-unit landed cost.
Supply Chain Analysis
Tariff exposure between Canadian Prairie provinces and US Great Lakes processing hubs dominates supply chain risk calculus for lentil-dependent manufacturers. Raw material pipelines draw from Saskatchewan pulse processors, Mediterranean chickpea cooperatives, and Andean quinoa collectives. Single-source vulnerability concentrates in protein-grade lentil flour where Prairie harvest volatility feeds directly into input cost pressure. Distribution runs through specialty distributors serving university dining contracts and direct institutional procurement for hospital catering operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated foodservice procurement offices at major university systems and corporate dining operators, fragmenting manufacturer leverage across smaller account portfolios.
For Market Incumbents: Harden formulation IP protection around low-temperature extrusion parameters as Italian equipment manufacturers license proprietary screw profiles to emerging competitors. Defend shelf position by securing multi-year volume guarantees with Whole Foods Market and Eataly category managers before planogram recalibration cycles complete. Priority lever rests on backward integration into Mediterranean pulse processing assets. For New Entrants and Emerging Players: Pursue white-space positioning in Japanese convenience store single-serve pouches where domestic incumbents lack chickpea-protein formulation expertise. Target hospital and airline catering direct distribution channels that bypass retail slotting fee structures entirely. Go-to-market angle centers on EFSA novel food approval acceleration for traditional pulse ingredients with documented consumption history. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors venture-backed legume pure-plays with captive ingredient sourcing and established natural channel placement. Five-to-ten year viability hinges on standard-of-identity threshold outcomes at FDA and EFSA. Acquisition target archetype combines formulation IP with existing foodservice procurement relationships. Signal to monitor is protein-content regulatory reclassification that would force "noodle alternative" labeling.| Strategic Initiative | Industry Significance |
|---|---|
| Mediterranean Pulse Processing Acquisition | Secures captive lentil and chickpea feedstock supply for North American manufacturers facing Prairie harvest volatility. |
| Low-Temperature Extrusion Patent Portfolio | Locks in texture parity advantages as Italian equipment suppliers license proprietary thermal control systems. |
| University Foodservice Direct Contracting | Bypasses retail slotting fees through institutional procurement relationships with consolidated dining operators. |
| EFSA Novel Food Approval Fast-Track | Compresses European market entry timelines for brown rice and traditional pulse formulations with safety dossiers. |
| Single-Serve Pouch Format Expansion | Captures 35-50% margin premiums in Japanese convenience stores and US meal-kit subscription channels. |
Research Methodology
Operator-level perspectives from extrusion technicians at Italian equipment manufacturers, procurement directors at university dining consortiums, and category managers at natural channel retailers anchored the qualitative base. Secondary validation drew from FDA food-labeling guidance documents, EFSA novel food assessment registers, USDA organic certification databases, and trade flow data from Canadian Prairie pulse export terminals. Bottom-up volume modeling triangulated against top-down category spend estimates.
Scenario-bracketing around EU Green Deal subsidy trajectories, FDA protein-content threshold outcomes, and semolina price anchoring shaped the analytical framework across the analysis window. Segmentation dimensions modeled include ingredient base, packaging format, distribution channel, and extrusion temperature technology tier. CAGRs derived from regression against historical volume pull-through in university foodservice and natural channel velocity indices.
Sensitivities concentrate around EFSA regulatory timeline compression, Prairie harvest yield variance, and planogram recalibration speed at perimeter fresh sections. Forecasts reflect documented assumptions about low-temperature extrusion adoption curves and pulse-crop subsidy durability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Global Plant Based Milk Market
Plant Based Food
Vegan Noodles Market
Plant Based Food
Europe Tofu Market
Plant Based Food
Germany Soy Protein Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Middle East and Africa Plant-Based Meat and Dairy Products Market
Plant Based Food
Organic Pea Protein Market
Plant Based Food
Plant Derived Proteins Market
Plant Based Food
Smart Plant Based Food Packaging Market
Plant Based Food
Vegan Dessert Market
Plant Based Food
China Plant Protein Market
Plant Based Food
Enzyme-Based Plant Protein Market
Plant Based Food
Plant-Based Burger Market
Plant Based Food
Plant-Based Wellness Foods Market
Plant Based Food
Hemp-Based Food Market
Plant Based Food
India Plant Protein Market