
 Plant-Based Beef Market | 2026-2036
Plant-Based Beef Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Beef Market Outlook
Premium clean-label formulations is rotating consumer preference toward shorter ingredient decks and recognizable protein sources. Beyond Meat leverages its proprietary extrusion platform to replicate muscle fiber texture at commercial scale. Impossible Foods anchors its position through heme-based flavor chemistry that narrows the sensory gap with conventional beef. Maple Leaf Foods controls integrated supply chains from pea protein sourcing through retail distribution in North America.
Plant-based beef comprises textured vegetable proteins, legume isolates, and fat analogs formulated to replicate the organoleptic properties of conventional beef, typically achieving protein contents between fifteen and twenty grams per serving through high-moisture extrusion or shear-cell processing. Its primary commercial purpose is to substitute animal-derived beef in applications ranging from raw crumble formats to fully formed center-of-plate items without requiring modified cooking equipment. Burger patties currently dominate refrigerated case space in North American supermarkets, while ground meat formats capture the fastest expansion in foodservice procurement due to operational versatility across tacos, Bolognese, and chili applications. The flexitarian consumer segment generates the deepest margin pools, as these buyers accept modest price premiums while requiring less stringent certification than committed vegan purchasers.
The USDA oversees labeling standards that distinguish plant-based products from meat through enforceable identity standards, while the FDA governs ingredient safety and novel protein approvals such as soy leghemoglobin. The EU Green Deal and F-Gas Regulation indirectly shape demand by embedding carbon accounting into public procurement criteria for institutional foodservice. REACH compliance in Europe adds formulation complexity for imported fat analogs and flavor systems. Stakeholders must monitor evolving nomenclature restrictions, as regulatory definitions of "meat" and "beef" remain contested across multiple jurisdictions and could force packaging and marketing revisions.
Market Dynamics
High-moisture extrusion and shear-cell processing are compressing cost curves for texture replication, while the EU Green Deal's carbon-accounting mandates force reformulation of fat analogs and protein sourcing across European supply chains.
Growth Catalysts
- EU Green Deal procurement criteria:Institutional foodservice contracts in Germany, France, and the Netherlands now embed lifecycle carbon thresholds that favor plant-based alternatives over conventional beef in school and hospital cafeterias.
- Quick-service restaurant operational versatility:Ground crumble formats allow single SKUs to cover tacos, chili, and pasta sauces without kitchen equipment changes, accelerating menu expansion across North American chains.
- Pea protein isolate supply maturation:Dedicated processing capacity in Canada and northern Europe has stabilized input costs for mid-tier formulations targeting flexitarian households.
Market Restraints
- Soy leghemoglobin regulatory lag:FDA novel protein approval timelines for heme-based flavor systems create multi-year gaps between formulation readiness and commercial launch in the United States.
- Yellow pea concentrate geographic concentration:Prairie province processing in Canada dominates global supply, exposing margins to single-region weather volatility and rail logistics bottlenecks.
- Coconut oil fat analog cost structure:Tropical supply sensitivity to shipping rates and harvest cycles prevents price parity with beef tallow in commodity ground applications.
Strategic Opportunities
- Chilled retail case expansion in Germany:Discounter chains Aldi and Lidl have tripled refrigerated plant-based shelf space since 2023, creating entry points for regional brands without frozen logistics infrastructure.
- Precision fermentation lipid convergence:Combined with high-moisture extrusion, microbially derived fats promise authentic marbling without tropical supply exposure or hydrogenation processing.
- USDA school lunch program flexibilities:Updated nutrition standards allow plant-based proteins to qualify for meal pattern requirements, opening procurement channels in K-12 foodservice.
Industry Challenges
- Extrusion technician skill scarcity:Operating high-moisture extrusion lines requires calibrated moisture-protein-temperature control that outpaces vocational training pipeline output in Midwestern processing hubs.
- REACH compliance timeline compression:European flavor system and color additive registrations now require 18-24 month safety dossier preparation, delaying reformulation cycles for clean-label positioning.
- Legacy meatpacking equipment incompatibility:Cold-chain infrastructure built for animal protein handling lacks humidity controls needed for plant-based texture stability, forcing parallel capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Beef Market |
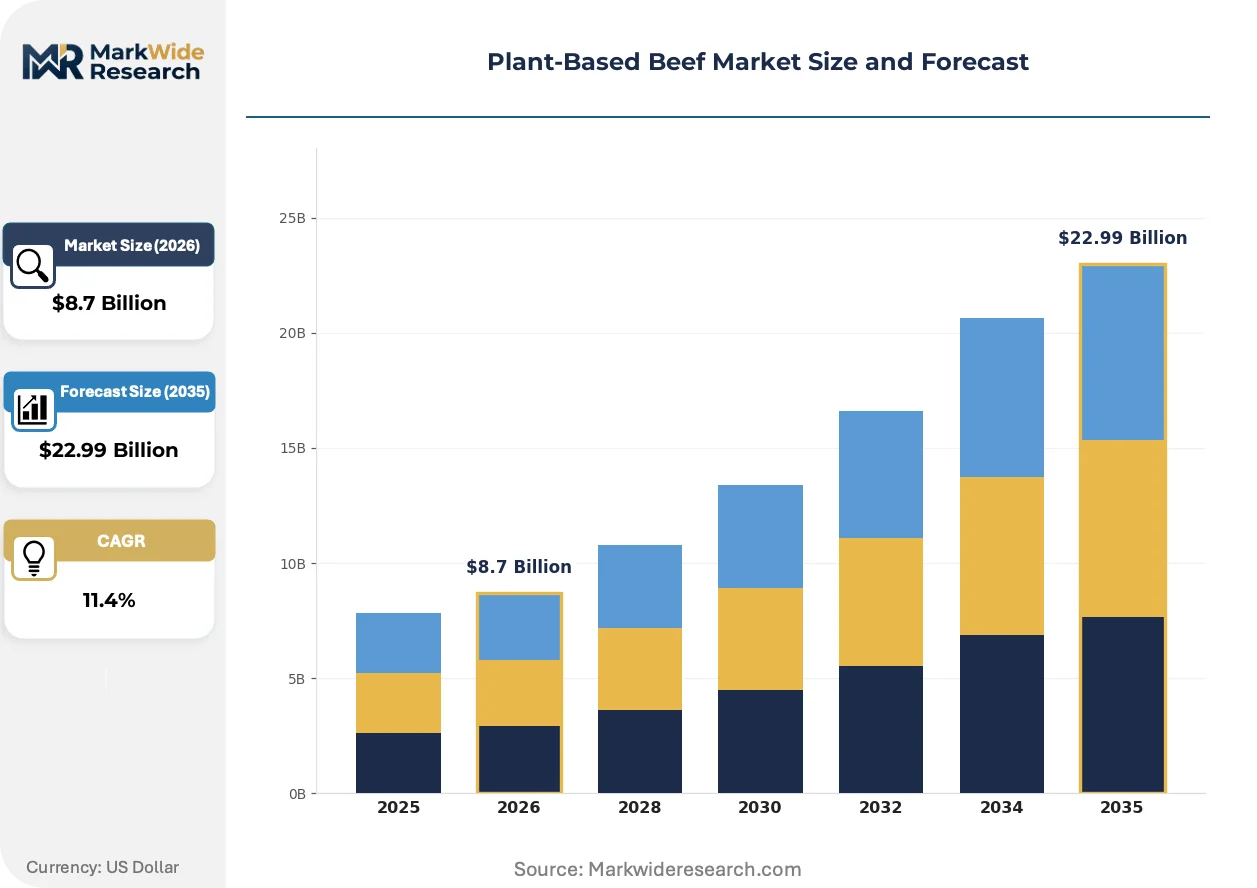
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Meat, Burger Patties, Sausages, Meatballs Consumer Segment: Flexitarians, Vegetarians, Vegans, Meat Reducers Distribution Channel: Supermarkets, Online Retailers, Restaurants, Convenience Stores Packaging Type: Ready-to-Cook, Frozen, Chilled, Shelf-Stable |
| Companies Covered | Beyond Meat, Impossible Foods, Conagra Brands, Maple Leaf Foods, The Vegetarian Butcher, Kellanova, Quorn Foods, Tofurky, Amy's Kitchen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Beef Market Strategic Shifts
Clean-label ingredient decks and carbon-accounting transparency are redefining competitive differentiation, with texture science and regulatory compliance emerging as the twin battlegrounds for formulation leadership.
Shear-cell processing is decomposing the capital barrier between artisanal texture quality and industrial scale. This mechanical texturization method eliminates the thermal degradation associated with traditional extrusion, allowing European equipment suppliers to target mid-cap producers with smaller footprint installations. Foodservice distributors in the United Kingdom are piloting these systems for co-manufactured private-label programs.
REACH authorization requirements for imported fat analogs are forcing reformulation toward European-sourced lipid systems. ECHA's updated substance evaluation criteria now classify several palm-derived and coconut-based emulsifiers as requiring extended safety data, compelling manufacturers to accelerate microbial oil and domestically processed rapeseed alternatives. German retailers are responding by tightening supplier qualification protocols ahead of 2026 reauthorization deadlines.
Flexitarian purchasing patterns are fragmenting the traditional vegan-vegetarian binary that structured early category development. German and Dutch supermarkets now merchandise plant-based beef adjacent to conventional meat rather than in segregated alternative sections, normalizing substitution behavior among weekly shoppers. This spatial repositioning compresses trial barriers for households that previously avoided dedicated plant-based aisles.
Plant-Based Beef Market Segmentation
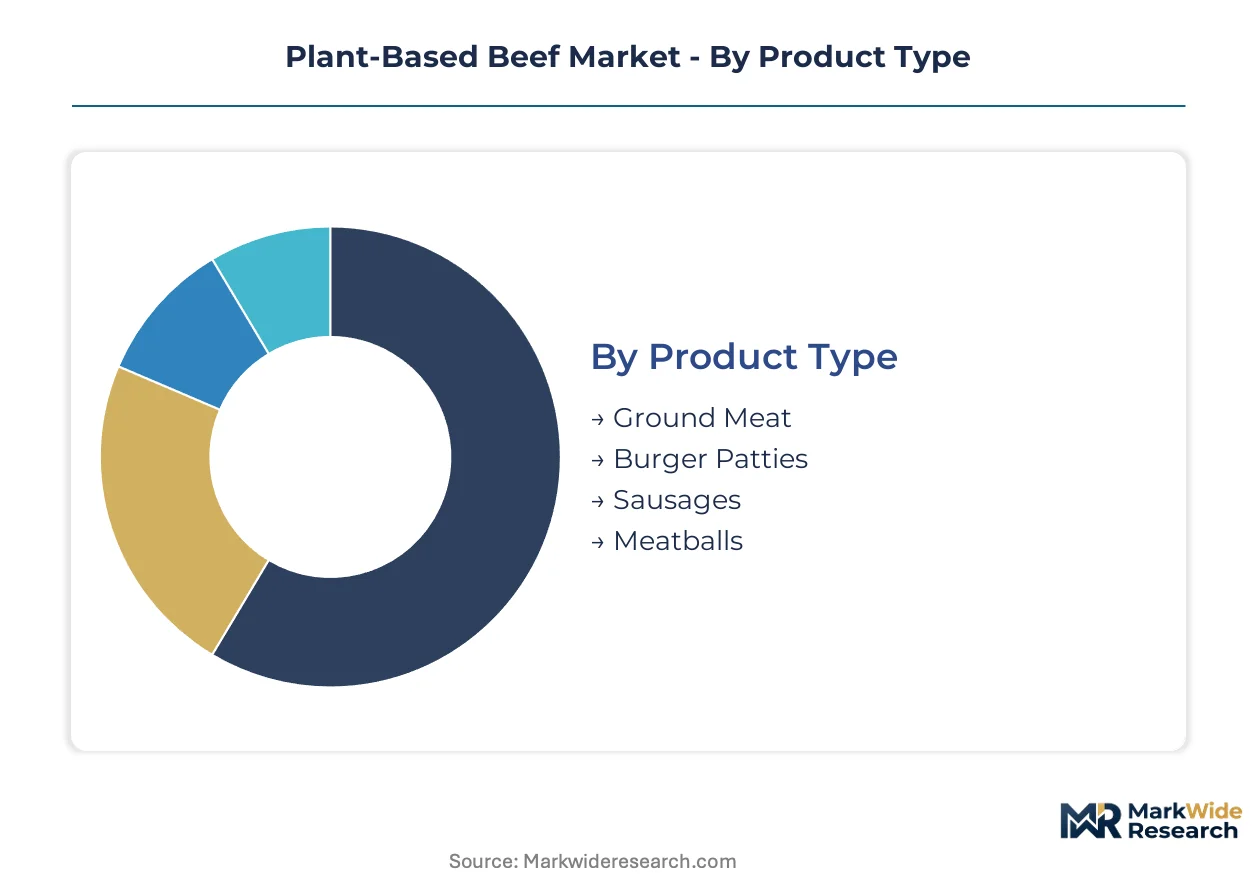
Segmentation in plant-based beef reveals divergent channel economics and formulation requirements. Product format dictates equipment compatibility for foodservice buyers, while packaging temperature band determines retail placement and margin structure.
Product Type:
Channel mix splits sharply between foodservice procurement and retail case placement, with format versatility driving operational adoption.
- Ground Meat:Crumble format achieves protein contents between fifteen and twenty grams per serving through high-moisture extrusion. Demand concentrates in North American quick-service restaurant chains where single SKUs cover tacos, chili, and pasta sauces without kitchen equipment changes.
- Burger Patties:Fully formed center-of-plate items replicate conventional beef thickness and cook-out behavior. Refrigerated case space in US and German supermarkets has deepened significantly as discounter chains tripled shelf allocation.
- Sausages:Cased formats require modified casing materials and smoke-flavor systems to achieve snap and bite resistance.
- Meatballs:Pre-formed spheres target foodservice prep reduction and home-meal assembly convenience.
Ground meat dominates installed base. Burger patties are where expansion concentrates.
Consumer Segment:
Margin tiering separates price-acceptant flexitarian households from certification-demanding committed vegan purchasers.
- Flexitarians:Weekly meat consumers accepting modest price premiums for partial substitution. This segment generates the deepest margin pools across German and Dutch retail markets where plant-based beef now merchandises adjacent to conventional meat.
- Meat Reducers:Health-motivated buyers reducing animal protein frequency without eliminating it entirely. Demand clusters in UK and US coastal metropolitan areas with strong wellness positioning.
- Vegetarians:Long-term abstainers from animal flesh seeking familiar formats and cooking rituals.
- Vegans:Strict animal-product avoiders requiring stringent certification and cross-contamination controls.
Flexitarians anchor volume throughput. Meat reducers are climbing the fastest.
Distribution Channel:
Supply concentration varies by cold-chain infrastructure maturity and buyer procurement scale.
- Supermarkets:Chilled retail cases in Germany and North America carry the bulk of branded and private-label SKUs. Aldi and Lidl expansion has created entry points for regional brands without frozen logistics infrastructure.
- Restaurants:Foodservice procurement favors ground crumble formats for operational versatility across menu applications. USDA school lunch program flexibilities now allow plant-based proteins to qualify for meal pattern requirements.
- Online Retailers:Direct-to-consumer frozen shipments bypass retail slotting fees but face last-mile cold-chain cost pressures.
- Convenience Stores:Shelf-stable and frozen grab-and-go formats target immediate consumption occasions with limited preparation.
Supermarkets hold the deepest SKU breadth. Restaurants are gaining share fastest.
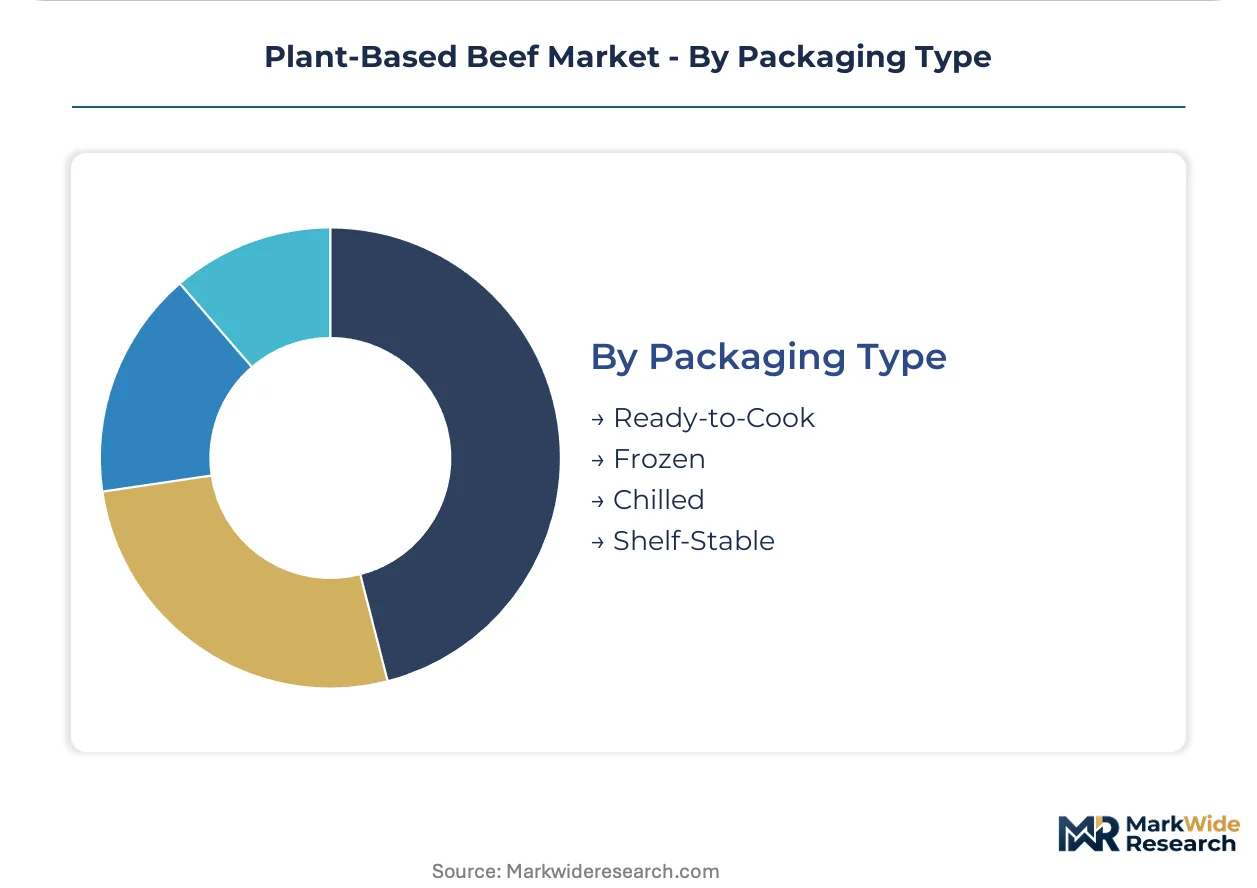
Packaging Type:
Capital deployment requirements and inventory velocity separate temperature-band strategies.
- Chilled:Refrigerated distribution demands parallel cold-chain infrastructure with humidity controls for texture stability. German discounter expansion has prioritized this format for weekly shopper frequency.
- Frozen:Extended shelf life enables national distribution but carries energy-intensive storage costs and texture degradation risks from ice crystal formation.
- Ready-to-Cook:Pre-seasoned and marinated formats reduce home preparation friction for time-constrained households.
- Shelf-Stable:Retort and aseptic processing extends distribution reach to convenience and emergency stockpiling channels.
Frozen commands the widest geographic reach. Chilled is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in plant-based beef concentrate manufacturing capacity in North America and Europe while Asian markets absorb growing import volumes. Export-oriented producers in Canada and the Netherlands supply ingredient isolates to formulation facilities across multiple continents. Germany and the United States function as the primary demand anchors, with divergent regulatory frameworks shaping local production economics.
United States
Quick-service restaurant chains drive procurement volumes for ground crumble formats across the Southwest and Midwest. The USDA governs labeling standards that distinguish plant-based products from conventional meat through enforceable identity standards. Chicago anchors foodservice distribution networks where distributors pilot shear-cell processing systems for co-manufactured private-label programs.
Germany
Discounter chains Aldi and Lidl have tripled refrigerated plant-based shelf space since 2023, concentrating demand in the Rhine-Ruhr and Bavarian metropolitan clusters. The EU Green Deal embeds lifecycle carbon thresholds into public procurement criteria for institutional foodservice contracts. Berlin-Brandenburg hosts reformulation laboratories accelerating microbial oil alternatives ahead of 2026 REACH reauthorization deadlines.
Canada
Prairie province processing dominates global yellow pea concentrate supply, exposing margins to single-region weather volatility and rail logistics bottlenecks. Health Canada oversees novel protein approvals with timelines that create gaps between formulation readiness and commercial launch. Alberta and Saskatchewan house dedicated pea protein isolate processing capacity that stabilizes input costs for North American mid-tier formulations.
Netherlands
Foodservice distributors pilot precision fermentation lipid convergence alongside high-moisture extrusion for authentic marbling without tropical supply exposure. ECHA's updated substance evaluation criteria classify several palm-derived emulsifiers as requiring extended safety data. The Eindhoven Region and Randstad corridor concentrate equipment suppliers targeting mid-cap producers with smaller footprint shear-cell installations.
United Kingdom
Wellness-positioned meat reducers cluster in London and coastal metropolitan areas, accepting modest price premiums for partial substitution. The FSA governs ingredient safety with protocols that influence formulation decisions across Commonwealth export markets. The Midlands hosts extrusion technician training programs attempting to close skill scarcity gaps in high-moisture extrusion line operation.
Plant-Based Beef Market Competitive Environment
Listed leaders compete with private specialists across capital access and speed-to-market dimensions, producing a tiered structure where scale advantages coexist with niche positioning. The vendor base separates into three strategic archetypes: integrated protein processors controlling supply chains from raw material through retail, technology licensors monetizing proprietary extrusion platforms, and regional formulators exploiting chilled distribution proximity. Dominant competitive moves include backward integration into pea protein sourcing and strategic partnerships with quick-service restaurant chains for menu placement.
Within the technology-licensor tier, Beyond Meat and Impossible Foods exemplify divergent approaches to sensory replication, with the former representing proprietary extrusion-based texture science and the latter occupying a position anchored in heme-based flavor chemistry. Maple Leaf Foods sits within the integrated processor archetype, demonstrating captive supply chain control from raw material sourcing through retail distribution. These three entities collectively illustrate how competitive positioning in plant-based beef depends on securing either manufacturing technology differentiation or supply chain verticality.
| Leading Market Players |
|---|
| Beyond Meat |
| Impossible Foods |
| Conagra Brands |
| Maple Leaf Foods |
| The Vegetarian Butcher |
| Kellanova |
| Quorn Foods |
| Tofurky |
| Amy's Kitchen |
| Others |
Value Chain & Pricing Dynamics
EU REACH authorization requirements for imported fat analogs and flavor systems gate both supplier qualification timelines and tiered pricing separation between compliant and non-compliant formulations. Certification investment creates cost pass-through capacity for established processors while compressing margins for reformulation-lagged competitors.
Pricing Analysis
Quick-service restaurant procurement teams anchor contract-based long-term offtake structures across North American ground crumble supply. Three-tier pricing structure across premium clean-label, standard extruded, and economy textured vegetable protein levels separates flexitarian-acceptant households from certification-demanding vegan purchasers. Cost compression in mid-tier formulations is intensifying because prairie province pea protein concentrate supply exposes margins to single-region weather volatility. Foodservice distributors exhibit lowest price sensitivity due to operational versatility premiums, while retail private-label buyers drive hardest bargain terms.
Supply Chain Analysis
Inventory velocity differentials between chilled and frozen temperature bands create lead-time fragmentation across German discounter expansion zones. Prairie province processing in Canada, northern European isolate facilities, and tropical coconut oil sourcing centers concentrate upstream supply. Yellow pea concentrate, heme-based flavor precursors, and palm-derived emulsifiers draw from geographically dispersed extraction and fermentation bases. Single-source vulnerability in Canadian rail logistics threatens input cost stability. Distribution runs through foodservice redistribution centers in Chicago and cold-chain retail hubs in the Rhine-Ruhr corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-moisture extrusion technician scarcity constrains capacity expansion velocity faster than capital deployment, creating bottleneck premiums for qualified equipment operators. This capability gap reshapes competitive timelines more fundamentally than raw material access.
For Market Incumbents: Compound captive supply chain control through backward integration into prairie province pea protein sourcing and shear-cell processing capacity additions in the Eindhoven Region. Precision fermentation lipid convergence represents a substitution threat to tropical fat analog dependencies. Certification investment ahead of 2026 REACH reauthorization deadlines secures pricing power retention. For New Entrants and Emerging Players: USDA school lunch program flexibilities offer a certification fast-track into institutional foodservice procurement channels previously gated by commodity beef contracts. Chilled retail case expansion in German discounter chains presents the most penetrable geography for regional brands lacking frozen logistics infrastructure. Direct partnerships with Aldi and Lidl category managers bypass slotting fee barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across shear-cell processing equipment as European suppliers target mid-cap producers with smaller footprint installations. Long-term viability over the projection horizon favors technology licensors with proprietary extrusion platforms over commodity formulators. Watch precision fermentation lipid cost curves as inflection indicator for fat analog sourcing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Protein Sourcing | Maple Leaf Foods demonstrates captive supply chain control from prairie province processing through retail distribution. |
| Shear-Cell Processing Capacity Expansion | Mid-cap producers in the Netherlands access artisanal texture quality without traditional extrusion thermal degradation. |
| REACH-Compliant Flavor System Reformulation | Berlin-Brandenburg laboratories accelerate microbial oil alternatives ahead of ECHA reauthorization deadlines. |
| Quick-Service Restaurant Menu Placement Partnerships | Beyond Meat leverages proprietary extrusion platform for operational versatility across taco and chili applications. |
| Precision Fermentation Lipid Convergence | Impossible Foods anchors heme-based flavor chemistry position while microbial fat alternatives promise authentic marbling. |
Study Parameters
Operator-level perspectives from high-moisture extrusion line technicians, quick-service restaurant procurement directors, German discounter category managers, and ECHA regulatory affairs specialists anchored the qualitative base. Secondary validation drew from USDA labeling guidance documents, FDA novel protein approval filings, EU Green Deal procurement criteria, and trade flow databases tracking prairie province pea concentrate exports. Bottom-up capacity modeling triangulated against top-down demand segmentation across the analysis window.
Sensitivity analysis tested forecast robustness across alternative scenarios for REACH compliance timeline compression and precision fermentation lipid cost convergence. Segmentation dimensions modeled include product format, consumer segment, distribution channel, packaging temperature band, and regional regulatory cluster. CAGRs were derived from installed base growth rates and replacement demand patterns. Industry-specific inputs incorporated extrusion equipment depreciation schedules and school lunch program procurement volume elasticities.
Decision-makers should treat outputs as directional under sustained flexitarian acceptance of modest price premiums and stable prairie province agricultural yields; material deviation in either assumption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Pasta Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Packed Vegan Foods Market
Plant Based Food
Global Isolate Organic Soy Protein Market
Plant Based Food
Soy Protein Market
Plant Based Food
United States Meat Substitutes Market
Plant Based Food
Plant-Based Butter Market
Plant Based Food
Pea Protein Isolate Market
Plant Based Food
Plant-Based Food and Beverages Market
Plant Based Food
Europe Plant-Based Meal Kit Market
Plant Based Food
Plant-Based Flour Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Singapore Plant-Based Food and Beverages Market
Plant Based Food
Plant Based Protein Market
Plant Based Food
US Plant-Based Meat Market
Plant Based Food
Plant-Based Bacon Market