
 Plant-Based Nuggets Market | 2026-2036
Plant-Based Nuggets Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Nuggets Market Analytics
Quick-service restaurant procurement is realigning toward flexitarian menu strategies as chains reduce reliance on conventional chicken offerings. Beyond Meat leverages its food-service partnerships to secure freezer placement in national burger chains. Impossible Foods competes through proprietary heme technology that replicates meat texture in nugget formats. MorningStar Farms sustains retail dominance through decades of frozen-vegetable-protein brand recognition and broad supermarket distribution.
Plant-based nuggets comprise extruded or formed protein matrices, typically using pea, soy, or wheat isolates bound with starches and oils, then breaded and par-fried for rethermalization. These products serve commercial kitchens and home consumers seeking animal-protein alternatives with familiar bite-size formats and crunch profiles. Pea protein nuggets lead product type expansion due to allergen-friendly positioning against soy-dominant legacy lines. Food service channels capture the fastest-growing distribution share as institutional buyers seek operational simplicity in batch-prepared meals. Flexitarian end users now represent the deepest demand pool, outnumbering strict vegan households and driving repeat purchase frequency.
The FDA governs ingredient safety and nutrition labeling for plant-based nuggets sold in U.S. interstate commerce, while USDA-FSIS oversight applies when products mimic poultry closely enough to trigger meat inspection parallels. The EU EFSA and EMA frameworks influence export-bound manufacturers through novel protein approval pathways and clean-label expectations. Stakeholders must monitor evolving protein-isolate import tariffs and front-of-pack labeling mandates that will determine which formulations achieve cost-competitive shelf placement.
Market Dynamics
Quick-service restaurant chains are consolidating plant-based nugget procurement through centralized category management, compressing supplier margins while demanding formulation consistency across thousands of locations.
Growth Catalysts
- USDA-FSIS Labeling Clarity:Updated poultry-mimic inspection guidelines reduce compliance uncertainty for manufacturers, accelerating retail shelf placement.
- Pea Protein Isolate Supply Expansion:North American processing capacity additions lower input costs for allergen-friendly formulations targeting school food service.
- Flexitarian Household Penetration:Dual-protein pantries now outnumber strict vegan homes, creating repeat purchase velocity in frozen retail channels.
Market Restraints
- Canola and Sunflower Oil Price Volatility:Breaded coating formulations depend on commodity oil inputs with weather-linked supply swings.
- Soy Isolate Supply Concentration:Three Midwest processors control domestic soy protein concentrate output, creating single-source vulnerability.
- Texture Replication Ceiling:Current extrusion technology cannot match whole-muscle chicken fiber alignment in bite-size formats.
Strategic Opportunities
- EU EFSA Novel Protein Pathway:Fermentation-derived mycelium nuggets qualify for expedited approval, opening export channels for US manufacturers.
- Airport and Stadium Concession Channels:Captive-audience food service seeks plant-based options with extended hold times and minimal prep labor.
- Precision Fermentation Convergence:Combining heme protein with extruded matrices enables next-generation juiciness without animal inputs.
Industry Challenges
- Food Technologist Talent Scarcity:Formulation chemists with both protein chemistry and sensory science expertise command premium compensation.
- Co-Manufacturer Certification Lag:USDA-FSIS facility approvals for meat-mimic products extend production timelines by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Nuggets Market |
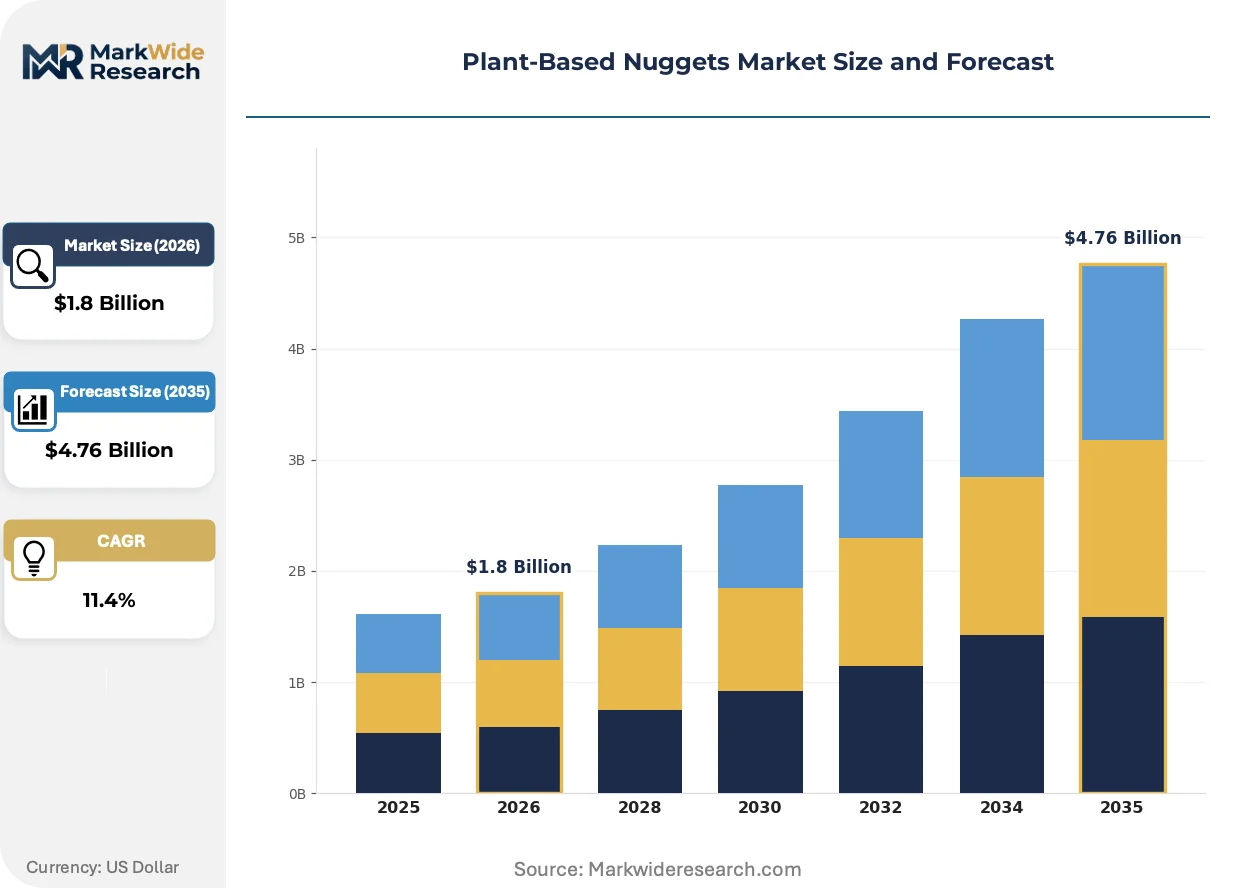
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chickpea Nuggets, Lentil Nuggets, Pea Protein Nuggets, Soy Nugget Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service End User: Vegetarians, Vegans, Health-Conscious Consumers, Flexitarians Packaging Type: Plastic Tray, Vacuum Pack, Carton Box, Resealable Bag |
| Companies Covered | Gardein, Alpha Foods, Beyond Meat, Field Roast, Rebellyous Foods, Impossible Foods, MorningStar Farms, VFC Foods, Quorn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Nuggets Market Evolving Landscape
Extrusion and forming technologies are converging with precision fermentation to close the sensory gap between plant-based nuggets and conventional chicken, while regulatory frameworks on both sides of the Atlantic codify what can be labeled as meat.
High-moisture extrusion is automating the continuous production of fibrous protein matrices that previously required batch processing. Food service manufacturers with national quick-service contracts are retrofitting lines to handle twin-screw extruders running at moisture levels above 60%. This automation is compressing unit costs and enabling real-time texture adjustment through inline shear control.
EU EFSA novel food approvals for fermented ingredients are creating a regulatory fast lane for mycoprotein nuggets entering European retail. Manufacturers must submit full toxicology dossiers, but streamlined equivalence pathways for established strains reduce review cycles. German and Dutch supermarket chains are prioritizing shelf placement for products carrying these designations.
Institutional buyers are unbundling protein procurement from full-menu contracts, creating direct sourcing relationships with plant-based nugget suppliers. K-12 school districts and university food service operators now run separate RFPs for meat alternatives, bypassing broadline distributors. This shift is most visible in California and New York state systems with mandated plant-based meal ratios.
Plant-Based Nuggets Market Segmentation
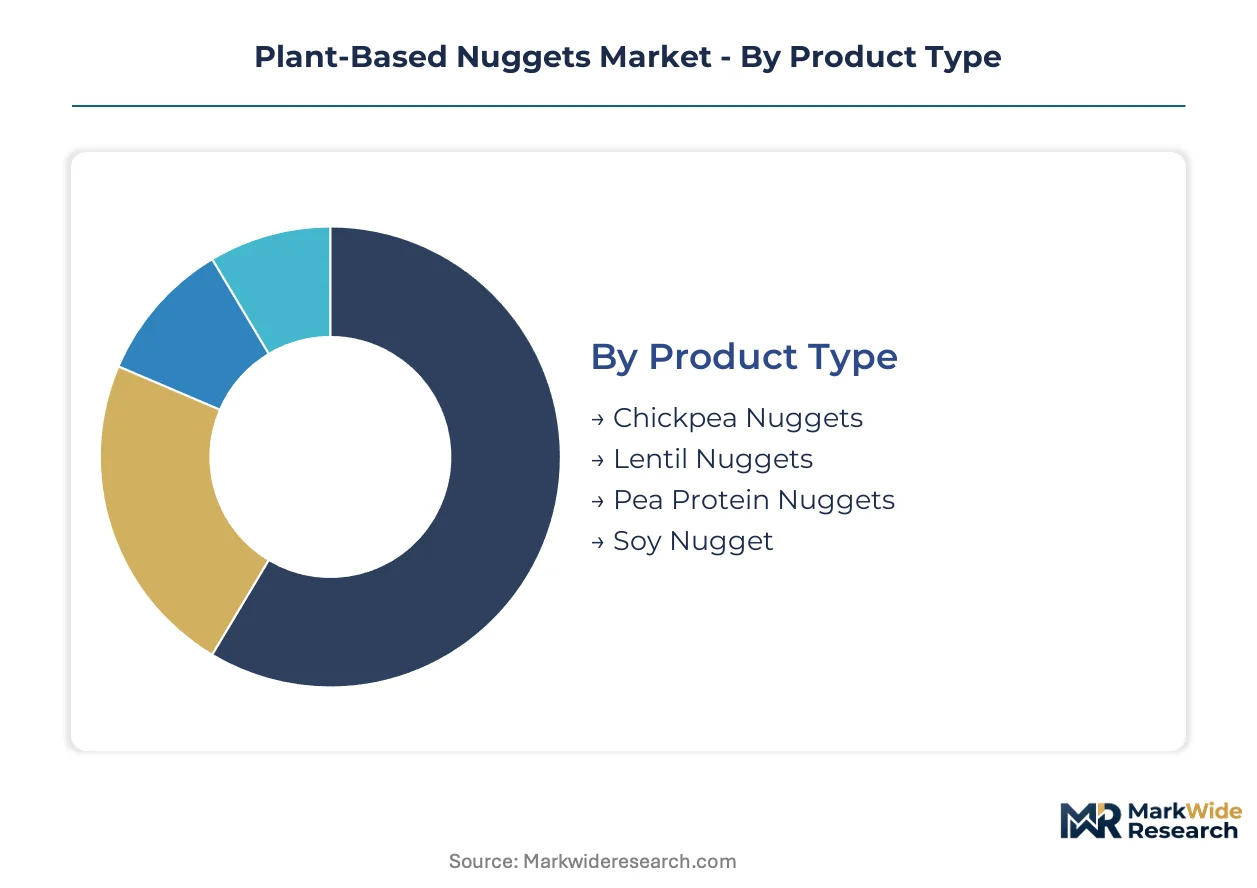
Segmentation in plant-based nuggets reveals how protein source, purchase channel, and dietary identity shape formulation priorities and margin structures. Manufacturers must align extrusion capabilities with the specific texture and price-point expectations of each slice.
Product Type:
Pea protein and soy isolates operate as embedded protein systems within broader ingredient matrices, while chickpea and lentil formats function as more standalone, whole-food-positioned offerings with visible particle integrity.
- Pea Protein Nuggets:Isolates from yellow split peas create neutral-flavor bases that accept seasoning and breading without beany off-notes. Allergen-free positioning drives adoption in K-12 school districts across California and New York with mandated plant-based meal ratios.
- Soy Nugget:Decades of processing infrastructure and established supply chains keep soy-dominant lines cost-competitive in broadline food service. Texture replication remains superior through high-moisture extrusion, though GMO and allergen concerns constrain retail expansion in premium channels.
- Chickpea Nuggets:Whole pulse formulations appeal to clean-label seekers with visible fiber and minimal ingredient lists. Mediterranean and Middle Eastern flavor profiles dominate this niche.
- Lentil Nuggets:Earthy flavor signatures and higher fiber content target health-positioned retail shelves. Limited extrusion scalability keeps volumes constrained relative to isolate-based alternatives.
Volume placements concentrate in soy nuggets; the faster expansion belongs to pea protein nuggets.
Distribution Channel:
Channel selection determines freezer logistics, rethermalization requirements, and the degree of consumer education required at point of purchase.
- Food Service:National quick-service chains and institutional buyers drive batch-scale procurement with standardized prep protocols. USDA-FSIS labeling clarity has accelerated placement in burger chain freezers seeking operational simplicity.
- Supermarkets:Frozen aisle placement demands competitive slotting fees and sustained promotional support. MorningStar Farms and private-label lines dominate shelf space through decades of brand recognition.
- Online Retail:Direct-to-consumer subscriptions and frozen delivery services capture trial-oriented flexitarians. Cold-chain shipping costs limit repeat purchase economics outside dense urban corridors.
- Specialty Stores:Natural grocers and co-ops stock premium-positioned mycoprotein and fermentation-derived lines. EFSA novel food approvals enable European import placement in these channels.
Food service captures the deepest volume; online retail is climbing the fastest as cold-chain infrastructure matures.
End User:
Dietary identity segments diverge sharply on price sensitivity, texture fidelity demands, and frequency of animal-protein substitution.
- Flexitarians:Dual-protein households now outnumber strict vegan homes, creating repeat purchase velocity in frozen retail. This segment accepts price premiums only when sensory gaps versus chicken narrow visibly.
- Health-Conscious Consumers:Protein-per-calorie ratios and sodium content drive selection more than ethical positioning. Front-of-pack labeling transparency determines trial conversion.
- Vegetarians:Longstanding category participants with established brand loyalties and lower texture-fidelity requirements. Price elasticity exceeds that of newer flexitarian entrants.
- Vegans:Strict exclusion standards demand certified supply chains and absence of cross-contamination protocols. Smaller addressable base with higher per-unit willingness to pay.
Flexitarians dominate absolute volume; health-conscious consumers are gaining share fastest as nutritional credentialing improves.
Packaging Type:
Packaging format signals freshness positioning, portion control, and sustainability commitments while governing freezer burn protection and reseal functionality.
- Resealable Bag:Multi-serve formats with zip-lock closures dominate club store and family-size retail placements. Material innovations in recyclable films respond to E.U. packaging waste directives.
- Plastic Tray:Rigid bases with film overwrap enable vertical stacking and portion visibility in supermarket freezers. Higher material costs pressure margins in value-tier lines.
- Carton Box:Paperboard exteriors with inner film barriers signal sustainability positioning for premium and specialty channels. California and New York state procurement guidelines increasingly favor fiber-based packaging.
- Vacuum Pack:Extended shelf-life formats target food service and export markets where cold-chain reliability varies. Compression reduces shipping cube but limits breading integrity.
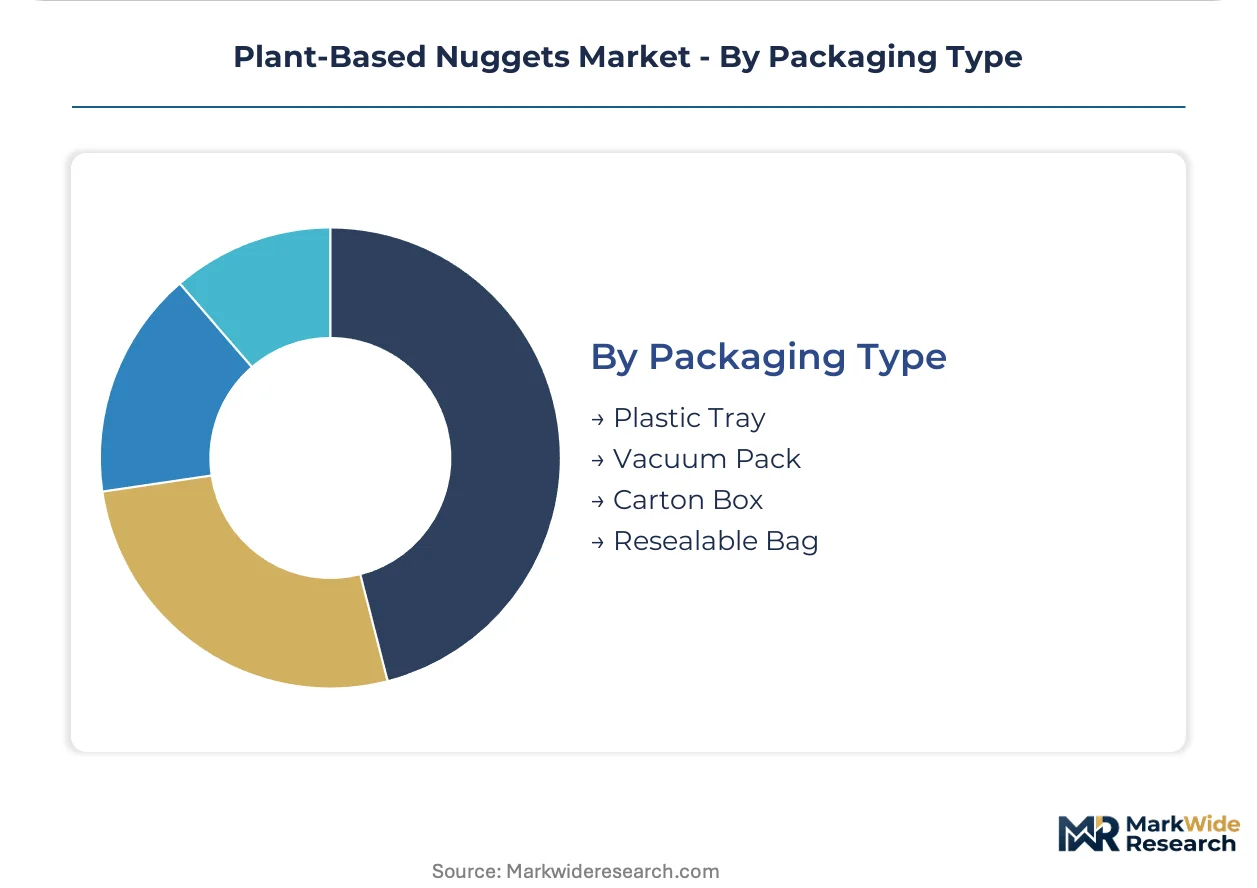
Resealable bags hold the volume concentration; carton boxes are expanding most quickly under regulatory packaging pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity for plant-based nuggets concentrates in North American and European processing hubs, while consumption growth accelerates across Asia-Pacific food service channels. Raw material sourcing for pea and soy isolates spans multiple continents, creating trade dependencies that shape regional competitive positioning.
United States
Flexitarian household penetration drives frozen retail velocity in suburban supermarkets and quick-service chain procurement. FDA and USDA-FSIS labeling clarity reduces compliance friction for poultry-mimic formulations. California and New York state school districts mandate plant-based meal ratios, creating institutional demand clusters in Los Angeles and New York City metro areas.
Germany
Clean-label expectations and novel protein acceptance position German retail as an early adopter for mycoprotein and fermentation-derived formats. EFSA novel food approval pathways streamline entry for US and Asian manufacturers seeking European shelf placement. The Emsland region hosts pea protein processing infrastructure serving Central European food service networks.
United Kingdom
Vegan population density and meat-free January campaigns sustain year-round trial rates in frozen and chilled retail segments. EFSA regulatory alignment post-Brexit maintains streamlined novel protein assessments for domestic manufacturers. Greater London food service operators lead plant-based nugget placement in pub chains and stadium concessions.
China
Domestic soy processing dominance supplies cost-competitive isolate feedstock for regional manufacturers and export markets. SAMR food safety standards govern protein additive labeling and import clearance for foreign brands. Yangtze River Delta metropolitan clusters test quick-service plant-based menu integration ahead of national rollout.
Netherlands
Precision fermentation research clusters and mycoprotein heritage create technology export capabilities for next-generation nugget formulations. EU Green Deal packaging waste directives accelerate fiber-based carton adoption in retail channels. The Randstad logistics hub enables cold-chain distribution efficiency across Benelux and Northern European markets.
Plant-Based Nuggets Market Competitive Landscape
Top-tier vendors anchor branded retail and national food service contracts, while mid-tier specialists and private-label suppliers fill price-sensitive channels and regional markets. The competitive structure reflects dual consolidation pressures: scale requirements for extrusion equipment investment and formulation expertise scarcity for texture replication. Three archetypes dominate—established frozen protein brands with decades of retail presence, venture-backed technology innovators with proprietary heme or fermentation platforms, and co-manufacturing specialists serving private-label supermarket lines. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players seek to secure pea protein supply commitments and co-packer certification for USDA-FSIS-compliant facilities.
Among venture-backed technology innovators, Beyond Meat and Impossible Foods exemplify the heme-protein and extrusion-convergence archetype, while MorningStar Farms represents legacy frozen-vegetable-protein brand equity sustained through broad supermarket distribution. These three occupy positions spanning the premium technology tier and mass-market retail penetration, illustrating how competitive positioning stratifies across price points and channel access rather than converging on a single dominant model.
| Leading Market Players |
|---|
| Gardein |
| Alpha Foods |
| Beyond Meat |
| Field Roast |
| Rebellyous Foods |
| Impossible Foods |
| MorningStar Farms |
| VFC Foods |
| Quorn |
| Others |
Value Network & Pricing Analysis
High-moisture extrusion line retrofits across North American co-manufacturing facilities simultaneously compress unit production costs and consolidate processing capacity among fewer USDA-FSIS-certified operators. This automation wave concentrates supply-side leverage while flexitarian demand growth intensifies price competition at retail.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as quick-service chains demand just-in-time freezer replenishment for promotional menu cycles. Three-tier pricing structure across premium heme-enhanced, standard isolate-based, and economy private-label tiers separates sensory fidelity expectations. Cost compression in the standard tier intensifies as pea protein isolate capacity additions in Canada and the U.S. Midwest expand supply availability. Flexitarian households in suburban supermarket channels exhibit highest price sensitivity, while institutional buyers in K-12 districts prioritize formulation consistency over per-unit cost.
Supply Chain Analysis
Pea protein isolate supply rests on processing facilities concentrated in Canada, the U.S. Midwest, and the Emsland region of Germany. Raw material dependencies span yellow split pea sourcing from the Northern Plains, canola and sunflower oil for breading formulations, and modified starches for binding matrices. Single-source vulnerability persists in domestic soy protein concentrate output controlled by three Midwest processors. Distribution runs through national broadline food service networks, direct sourcing relationships with quick-service chains, and frozen retail logistics hubs serving supermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation convergence with extrusion matrices marks a technology-transition phase displacing legacy batch-processed protein formulations. Manufacturers must align capital deployment with this capability shift to maintain competitive positioning.
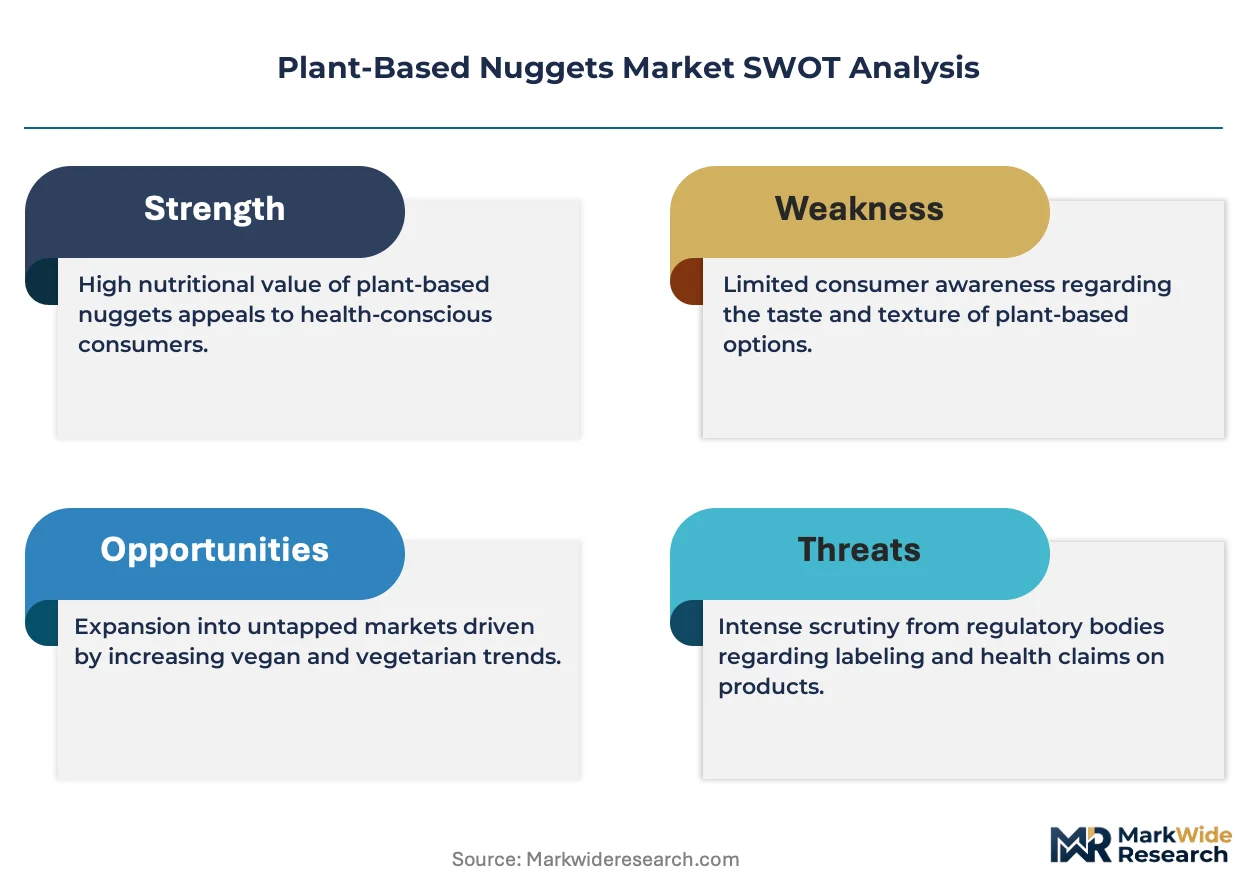
For Market Incumbents: Hedge against texture-replication ceiling risks by securing captive heme protein supply through precision fermentation partnerships or backward integration into mycoprotein processing. Add extrusion capacity in USDA-FSIS-certified facilities before certification queue lengths extend further. Defend supermarket freezer placement through sustained slotting fee commitments as private-label pressure intensifies. For New Entrants and Emerging Players: USDA-FSIS labeling clarity in the United States opens a window for poultry-mimic formulations to bypass protracted compliance uncertainty that previously deterred market entry. Target airport and stadium concession channels where captive-audience food service seeks extended hold-time products with minimal prep labor. Pursue direct RFP relationships with California and New York state school districts that have unbundled protein procurement from broadline contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by legacy frozen protein brands seeking precision fermentation capabilities. Five-to-ten-year viability hinges on securing defensible positions in heme-enhanced formulation IP or mycoprotein supply chains. Watch for inflection signals in EU EFSA novel protein approval timelines that would unlock European export channels for U.S. fermentation-derived nugget manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Enables heme protein integration into extruded matrices for next-generation juiciness without animal inputs. |
| USDA-FSIS Facility Certification Investment | Accelerates production timelines for poultry-mimic products facing eight-to-fourteen-month approval queues. |
| Pea Protein Supply Agreement | Locks in allergen-friendly isolate feedstock as North American processing capacity expands. |
| Direct School District Procurement Relationship | Bypasses broadline distributors in California and New York systems with mandated plant-based meal ratios. |
| EU EFSA Novel Food Approval Pathway | Opens streamlined export channels for fermentation-derived mycoprotein nuggets entering German and Dutch retail. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with plant-based protein R&D directors, quick-service chain procurement managers, co-manufacturing facility operators, and school food service directors. FDA guidance documents, USDA-FSIS inspection protocols, EU EFSA novel food submission dossiers, and frozen food industry association production statistics provided foundational secondary validation. Bottom-up volume modeling across protein source, distribution channel, and end-user segments triangulated against top-down market sizing from retail audit data and food service procurement databases.
Data-stream reconciliation connected production capacity announcements, extrusion equipment installation records, and pea protein processing facility expansion timelines with demand-side indicators from quick-service menu placement tracking and institutional procurement RFP activity. Segmentation dimensions modeled include protein source technology, distribution channel logistics requirements, end-user dietary identity, and packaging format sustainability positioning. CAGRs were derived from slope analysis of historical volume trajectories adjusted for technology adoption inflection points and regulatory approval pathway accelerations.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation scale-up would alter the outlook if capital deployment lags or consumer acceptance of mycoprotein formats stalls. Forecasts reflect assumptions about flexitarian household penetration rates, pea protein isolate cost curves, and USDA-FSIS certification queue resolution. Regulatory timeline slippage, commodity oil price volatility, and food technologist talent scarcity represent specific revision risks. A small set of triggers—EFSA approval velocity, quick-service chain promotional frequency, and school district mandate expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Black Rice Protein Market
Plant Based Food
Plant-Based Shrimp Market
Plant Based Food
Hemp-Based Food Market
Plant Based Food
Vegan Meat Alternatives Market
Plant Based Food
Chicory Roots Market
Plant Based Food
Vegan Diet Market
Plant Based Food
Smart Plant Based Food Packaging Market
Plant Based Food
Brazil Soy Beverages Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
India Plant Protein Market
Plant Based Food
Extruded Soy Products Market
Plant Based Food
Plant Based Tuna Market
Plant Based Food
Yellow Pea Protein Market
Plant Based Food
Fermented Plant-Based Food Market
Plant Based Food
Plant-Based Protein Food Market
Plant Based Food
Oat-Based Cereals Market