
 Cardiopulmonary Disease Diagnostics and Treatment Market | 2026-2036
Cardiopulmonary Disease Diagnostics and Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiopulmonary Disease Diagnostics and Treatment Market Intelligence
The substitution of traditional metallic components with advanced biocompatible polymers is restructuring product economics for implantable cardiac monitors. This shift allows for smaller, MRI-compatible devices with improved patient comfort. Medtronic plc leverages its materials science expertise to lead in this area of innovation. Boston Scientific Corporation competes by focusing on next-generation materials for its ventilator and cardiac rhythm management portfolio.
Cardiopulmonary disease diagnostics and treatment encompasses medical devices and procedures used to identify and manage disorders of the heart and lungs. These systems, such as ECG machines with 12-lead configurations, measure physiological parameters to detect conditions like arrhythmia. Among product types, imaging devices hold a dominant share, while home care devices represent a high-growth category. Within therapy areas, chronic obstructive pulmonary disorder and heart failure constitute mature segments with substantial patient populations.
Device approval pathways are governed by stringent regulations from bodies like the US FDA and the European Union's MDR. In China, the NMPA sets standards for both imported and domestically produced medical equipment. These frameworks mandate extensive clinical data for market access. Navigating the varied data requirements for telemedicine solutions across different jurisdictions remains a key strategic challenge for device manufacturers.
Market Dynamics
The integration of artificial intelligence into diagnostic workflows, particularly for imaging and physiological monitoring, is the central force shaping the market. This is driven by healthcare systems in countries like China seeking to improve diagnostic efficiency for aging populations.
Growth Catalysts
- AI-Enhanced Diagnostics:The integration of AI algorithms into ECG and imaging systems accelerates the detection of conditions like arrhythmia, improving diagnostic accuracy and throughput in specialized clinics.
- Healthcare Infrastructure Expansion:Government initiatives in countries like China to build out healthcare capacity for managing chronic diseases in aging populations create sustained demand for diagnostic and therapeutic equipment.
- Rising Chronic Disease Burden:A growing global prevalence of chronic obstructive pulmonary disorder and heart failure expands the patient pool requiring long-term monitoring, sustaining demand for both clinical and home care devices.
Market Restraints
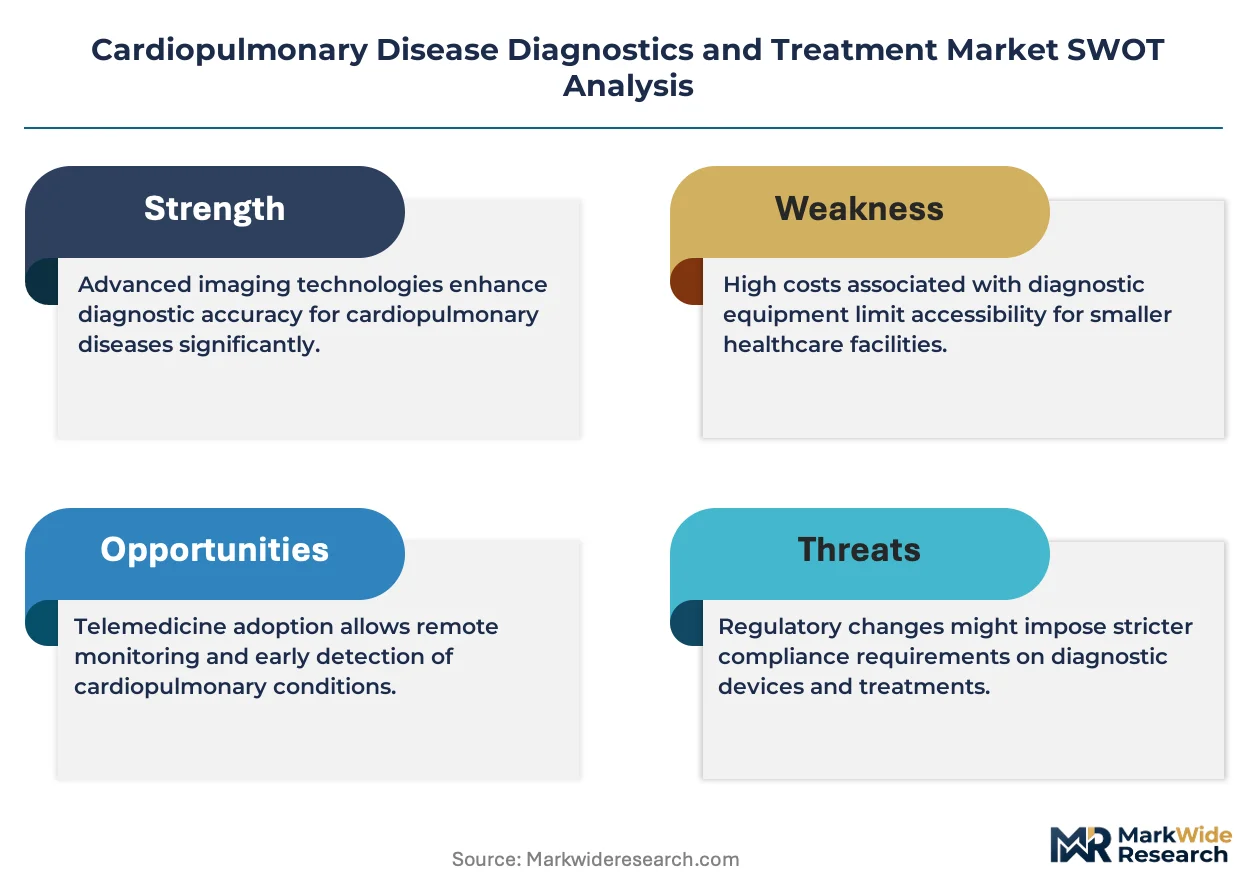
- High Device Cost:The significant capital expenditure required for advanced imaging systems, such as 12-lead ECG machines and MRI-compatible monitors, limits adoption in smaller clinics and healthcare systems with constrained budgets.
- Regulatory Fragmentation:Navigating disparate data privacy and device approval requirements from the US FDA, the EU's MDR, and China's NMPA creates significant compliance overhead and delays market access for new technologies.
- Biocompatible Polymer Scarcity:Supply chain dependencies on a limited number of suppliers for advanced biocompatible polymers create input cost volatility and production risks for manufacturers of next-generation implantable cardiac monitors.
Strategic Opportunities
- Home Care in Emerging Markets:Expanding telemedicine infrastructure in Southeast Asian and Latin American countries provides a channel for introducing portable, user-friendly home care monitoring devices for conditions like pulmonary hypertension.
- Wearable Sensor Integration:The convergence of consumer-grade wearables with clinical-grade diagnostic algorithms offers an opportunity to develop continuous monitoring solutions for early-stage disease detection and post-procedural patient management.
- Favorable Reimbursement Policies:Evolving reimbursement frameworks that incentivize remote patient monitoring create a pull for connected diagnostic devices that can demonstrate improved patient outcomes and reduced hospitalizations.
Industry Challenges
- Data Science Skill Gaps:A shortage of clinical data scientists capable of developing, validating, and implementing AI-powered diagnostic algorithms within regulatory frameworks like the EU AI Act slows down innovation cycles.
- Legacy System Interoperability:Integrating new diagnostic platforms with existing hospital electronic health record systems presents significant technical and data security challenges, hindering seamless workflow adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiopulmonary Disease Diagnostics and Treatment Market |
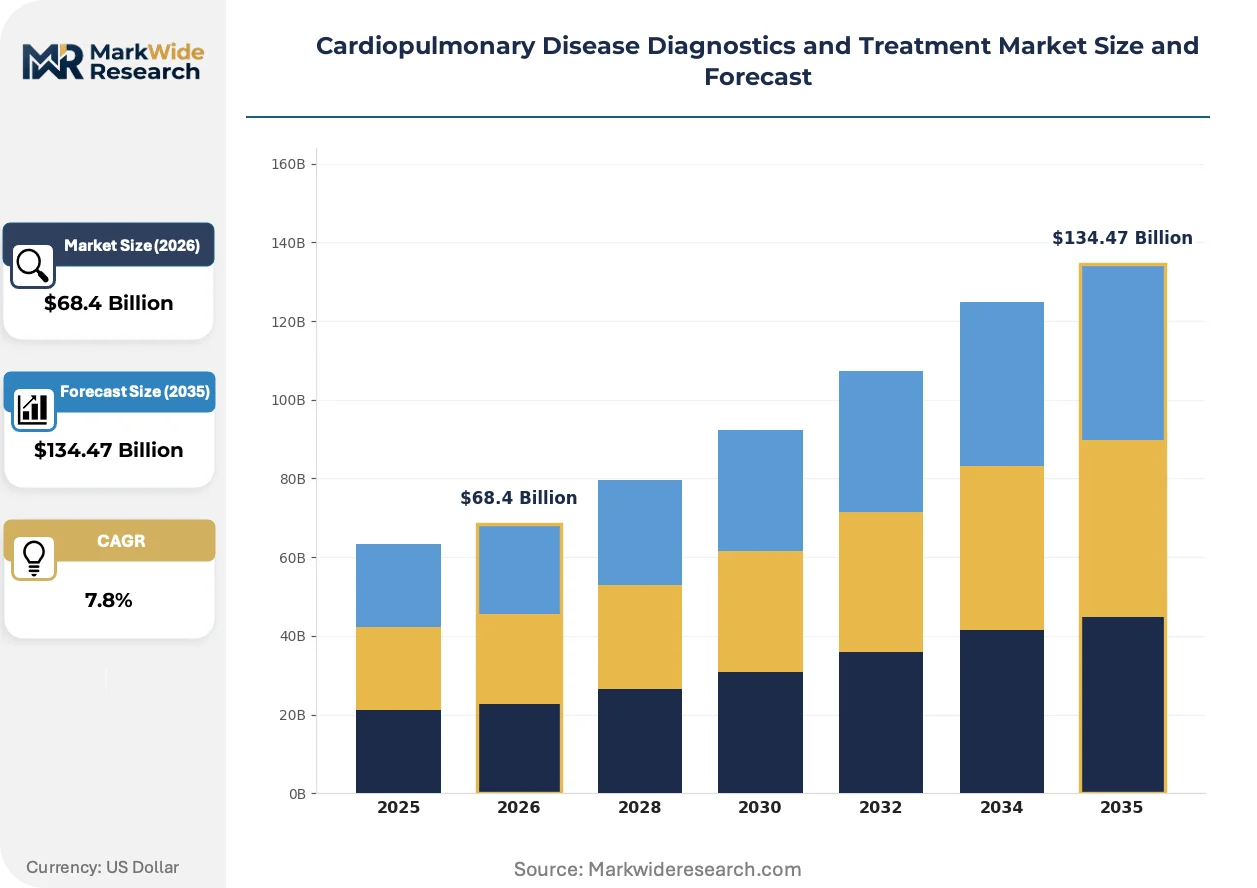
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $134.47 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Devices, Blood Gas Analyzers, Pulse Oximeters, Ventilators, ECG Machines, Cardiac Monitors Therapy Area: Pulmonary Hypertension, Chronic Obstructive Pulmonary Disorder, Heart Failure, Asthma, Arrhythmia, Acute Respiratory Distress Syndrome End User: Hospitals, Specialized Clinics, Diagnostic Laboratories, Ambulatory Surgical Centers, Rehabilitation Centers Delivery Mode: Invasive Procedure, Non-Invasive Technique, Ambulatory Monitoring, Home Care Devices, Telemedicine Solutions |
| Companies Covered | Abbott Laboratories, Medtronic plc, Boston Scientific Corporation, Siemens Healthineers, GE HealthCare, Roche Diagnostics, Edwards Lifesciences Corporation, Thermo Fisher Scientific, Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiopulmonary Disease Diagnostics and Treatment Market Strategic Shifts & Innovations
Miniaturization and data connectivity are fundamentally altering the form and function of cardiopulmonary devices. This shift moves diagnostic capabilities from centralized hospital settings toward distributed, patient-centric models of care that emphasize continuous monitoring and early intervention.
Biocompatible polymers are advanced materials used in implantable devices to improve patient safety and comfort. Specialized clinics and cardiac centers are adopting these materials for smaller, MRI-compatible monitors. This technology shift is rewriting the economics of implantable device manufacturing, favoring firms with strong materials science expertise.
The European Union's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance. This regulation increases the time and cost associated with bringing new devices to the European market. Manufacturers of high-risk devices, like implantable cardiac monitors, are most affected, forcing them to reallocate resources toward extensive clinical data generation.
A transition toward value-based healthcare models is changing purchasing criteria for diagnostic equipment. Hospital systems are increasingly prioritizing devices that integrate with telemedicine platforms and demonstrate a clear return on investment through improved patient outcomes. This trend is most visible in the United States, where reimbursement policies are increasingly tied to care quality.
Cardiopulmonary Disease Diagnostics and Treatment Market Segmentation
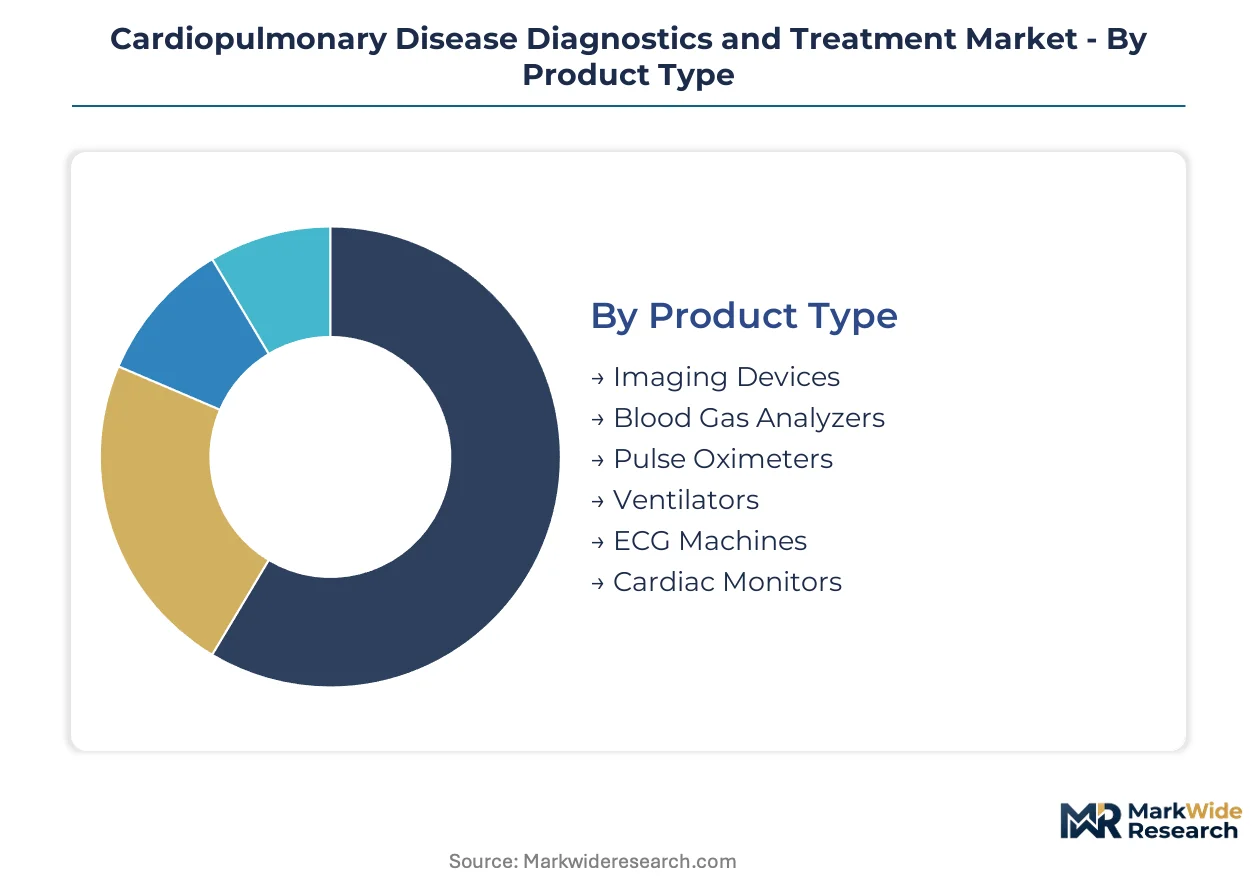
The Cardiopulmonary Disease Diagnostics and Treatment Market is segmented to provide a granular understanding of device types, therapeutic applications, end-user environments, and delivery mechanisms. This detailed classification helps stakeholders identify specific growth vectors and address distinct patient needs across the healthcare spectrum.
Product Type:
The Cardiopulmonary Disease Diagnostics and Treatment Market categorizes devices by their core technological function and design.
- Imaging Devices:These systems, including X-ray, CT, and MRI machines, visualize internal structures of the heart and lungs for diagnostic purposes. Demand concentrates in hospitals and specialized clinics, driven by the need for non-invasive, high-resolution diagnostics.
- Cardiac Monitors:These devices continuously track heart activity, ranging from wearable patches to implantable loop recorders, often utilizing advanced biocompatible polymers. China's expanding healthcare infrastructure creates significant demand for improved patient comfort and MRI compatibility.
- Blood Gas Analyzers:These instruments measure oxygen and carbon dioxide levels in arterial blood, providing critical data for respiratory and metabolic assessment. Hospitals and intensive care units represent the primary end-users for these rapid diagnostic tools.
- Pulse Oximeters:These non-invasive devices monitor oxygen saturation levels in the blood, essential for managing respiratory conditions and patient well-being. Home care settings and emergency medical services widely adopt these portable monitoring solutions.
- Ventilators:Mechanical ventilation systems support or replace breathing for patients with severe respiratory failure, ranging from critical care to portable designs. Intensive care units and long-term acute care facilities are the primary deployment sites for these life-sustaining devices.
- ECG Machines:Electrocardiogram devices record the heart's electrical activity using electrodes, with 12-lead configurations being standard for comprehensive cardiac assessment. Specialized clinics and emergency departments rely on ECG machines for rapid arrhythmia detection.
Imaging Devices leads on scale; Cardiac Monitors leads on momentum.
Therapy Area:
Therapy areas define the specific medical conditions addressed by cardiopulmonary diagnostics and treatment solutions.
- Chronic Obstructive Pulmonary Disorder:This segment addresses a progressive lung disease characterized by obstructed airflow, requiring long-term monitoring and management. Demand for diagnostic and therapeutic equipment is substantial in countries with aging populations, such as China.
- Heart Failure:This condition involves the heart's inability to pump enough blood, necessitating continuous monitoring and advanced therapeutic interventions. The rising prevalence of cardiovascular diseases globally sustains demand for sophisticated diagnostic tools and treatment devices.
- Pulmonary Hypertension:This therapy area focuses on high blood pressure in the arteries leading to the lungs, requiring specialized diagnostic imaging and targeted therapies. Specialized clinics in developed economies drive demand for advanced diagnostic solutions.
- Asthma:This chronic inflammatory airway disease requires regular monitoring of lung function and precise medication delivery systems. Pediatric and general practitioner clinics frequently utilize diagnostic tools for asthma management.
- Arrhythmia:This segment covers irregular heart rhythms, necessitating diagnostic tools like ECG machines and cardiac monitors for accurate detection and management. Electrophysiology labs and cardiology practices are key users of arrhythmia diagnostic equipment.
- Acute Respiratory Distress Syndrome:This severe lung condition requires immediate and intensive medical intervention, often involving mechanical ventilation and continuous physiological monitoring. Intensive care units are the primary settings for managing patients with ARDS.
Chronic Obstructive Pulmonary Disorder drives substantial patient volume, while Pulmonary Hypertension exhibits a steep expansion trajectory.
End User:
End-user segmentation reflects the primary healthcare settings where cardiopulmonary diagnostic and treatment equipment is deployed.
- Hospitals:These large medical institutions serve as central hubs for complex diagnostic procedures, critical care, and surgical interventions for cardiopulmonary diseases. Hospitals in the United States and European Union countries represent significant procurement centers for advanced equipment.
- Specialized Clinics:These focused healthcare facilities, including cardiology and pulmonology clinics, increasingly adopt AI-powered diagnostic tools for precise and efficient patient care. China's expanding network of specialized clinics drives demand for targeted diagnostic solutions.
- Diagnostic Laboratories:These facilities conduct a wide array of tests, including blood gas analysis and genetic screening, crucial for diagnosing cardiopulmonary conditions. Independent and hospital-affiliated labs support clinical decision-making with specialized testing services.
- Ambulatory Surgical Centers:These outpatient facilities perform less invasive procedures, requiring specific diagnostic and monitoring equipment for pre-operative assessment and post-operative recovery. Growth in these centers is influenced by cost-efficiency and patient convenience.
- Rehabilitation Centers:These centers focus on patient recovery and long-term management of chronic cardiopulmonary conditions, utilizing monitoring and therapeutic devices. Respiratory and cardiac rehabilitation programs rely on equipment for exercise testing and progress tracking.
Hospitals represent the foundational demand base, with Specialized Clinics rapidly expanding their equipment procurement.
Delivery Mode:
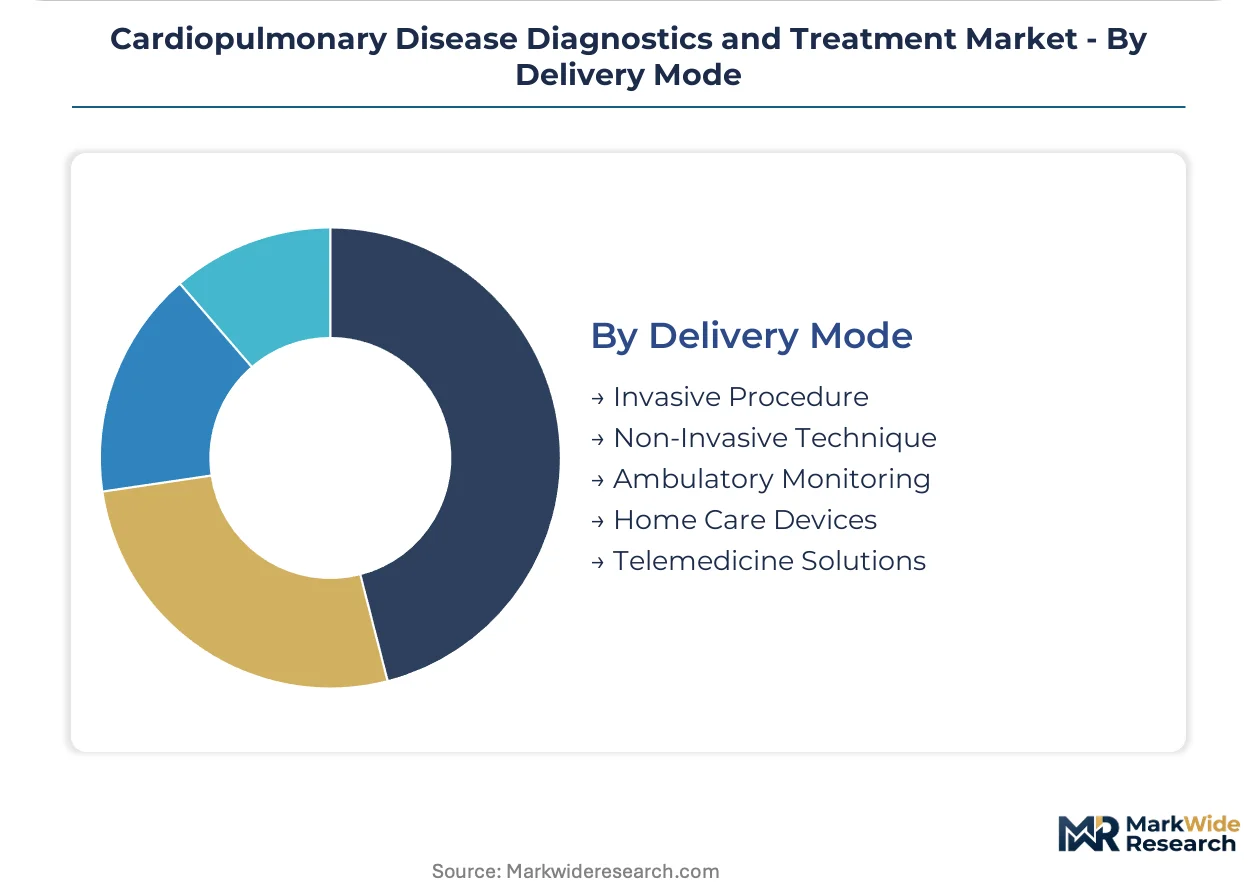
Delivery mode segmentation differentiates cardiopulmonary solutions based on their operational approach and patient interaction.
- Home Care Devices:These portable and user-friendly devices enable patients to monitor their cardiopulmonary health outside of clinical settings, supporting long-term disease management. Expanding telemedicine infrastructure in Southeast Asian countries boosts the adoption of these solutions.
- Telemedicine Solutions:This mode utilizes digital communication technologies to deliver remote diagnostic and monitoring services, enhancing accessibility and continuity of care. Navigating varied data requirements across jurisdictions presents a strategic challenge for manufacturers.
- Invasive Procedure:This mode involves diagnostic or therapeutic interventions that penetrate the body, such as catheterization or biopsies, requiring specialized medical instruments. Cardiac catheterization labs and interventional pulmonology suites primarily utilize invasive procedure equipment.
- Non-Invasive Technique:These methods diagnose or treat without breaking the skin, encompassing imaging, ECG, and external monitoring devices, prioritizing patient comfort and safety. Routine diagnostic screenings in primary care and outpatient settings heavily rely on non-invasive techniques.
- Ambulatory Monitoring:This involves continuous data collection from patients as they go about their daily activities, using wearable or portable devices. Holter monitors and event recorders are common examples, providing insights into intermittent cardiac events.
Non-Invasive Technique holds significant market breadth, and Home Care Devices are gaining share fastest among new modalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The MedTech Corridor in Minnesota, a significant hub for medical device innovation, anchors substantial demand for cardiopulmonary diagnostic and treatment solutions. This region, alongside other global centers, drives technological advancements and market penetration. Healthcare infrastructure expansion and chronic disease management remain central to regional market growth.
United States
Demand for advanced imaging devices and home care solutions remains robust across the United States, driven by a focus on early diagnosis and remote patient management. The US FDA's stringent approval pathways ensure device safety and efficacy, influencing product development cycles. Major medical device clusters in California and Massachusetts continue to innovate in cardiac monitoring and respiratory support technologies.
China
China's extensive healthcare infrastructure expansion creates sustained demand for diagnostic and therapeutic equipment, particularly for its aging population. The NMPA sets comprehensive standards for both imported and domestically produced medical equipment, shaping market entry strategies. Manufacturing hubs in the Yangtze River Delta region are rapidly expanding their capabilities in AI-powered diagnostic tools.
Germany
Germany exhibits strong demand for high-quality cardiopulmonary diagnostics, supported by a well-established healthcare system and a focus on precision engineering. Compliance with the EU MDR mandates extensive clinical data, impacting market access for new devices. Medical technology centers in Bavaria and Baden-Württemberg lead in developing advanced imaging systems and biocompatible implants.
Japan
An aging population in Japan drives a consistent need for advanced cardiopulmonary care, emphasizing miniaturized and patient-centric devices. The PMDA regulates medical devices, ensuring high safety standards and influencing product design for the local market. Research and development clusters in Tokyo and Osaka focus on integrating AI into diagnostic workflows and wearable sensors.
India
India's expanding healthcare access and rising chronic disease burden fuel demand for affordable and scalable cardiopulmonary diagnostic and treatment solutions. The CDSCO oversees medical device regulations, with a growing emphasis on local manufacturing and quality control. Medical device parks in Bengaluru and Hyderabad are becoming centers for developing cost-effective monitoring and therapeutic devices.
Cardiopulmonary Disease Diagnostics and Treatment Market Key Industry Players
Global majors compete with regional champions across technology innovation and market access strategies within the cardiopulmonary disease diagnostics and treatment market. The market structure features large diversified healthcare conglomerates, specialized device manufacturers, and emerging technology startups. Strategic partnerships and portfolio diversification are common competitive moves among established players.
Within the specialized device manufacturing tier, Medtronic plc and Boston Scientific Corporation exemplify companies leveraging materials science expertise for implantable devices and advanced cardiac rhythm management. Siemens Healthineers, a diversified healthcare technology leader, occupies a position focused on imaging and diagnostic systems. These firms anchor innovation in areas like MRI-compatible monitors and next-generation ventilator materials.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic plc |
| Boston Scientific Corporation |
| Siemens Healthineers |
| GE HealthCare |
| Roche Diagnostics |
| Edwards Lifesciences Corporation |
| Thermo Fisher Scientific |
| Philips |
| Others |
Cost & Logistics Intelligence
Advanced biocompatible polymers are reshaping implantable device cost structures and concentrating material supply among specialized manufacturers.
Pricing Analysis
Input cost volatility, particularly for specialized biocompatible polymers, directly influences device pricing. Value-based pricing models are gaining traction, especially for advanced diagnostic systems that demonstrate improved patient outcomes. Device pricing differentiates based on clinical evidence, regulatory approvals (e.g., US FDA clearance), and integrated software capabilities. Pricing softness in basic diagnostic equipment stems from increased competition from regional manufacturers. Smaller clinics and emerging market healthcare systems exhibit high price sensitivity, while specialized hospitals prioritize advanced features and reliability.
Supply Chain Analysis
Dual-sourcing requirements are becoming standard practice for critical components, mitigating risks for medical device manufacturers. Component manufacturing concentrates in China, Germany, and the United States. The market relies heavily on specialized sensors, microcontrollers, and advanced biocompatible polymers. Single-source vulnerability for these specialized materials poses a significant structural risk. Distribution primarily occurs through a network of specialized medical distributors and direct sales channels to hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cardiopulmonary Disease Diagnostics and Treatment Market remains a stable compounder, driven by the persistent global burden of chronic heart and lung conditions.
For Market Incumbents: Deepen R&D investments in AI-powered diagnostics to counter emerging technology startups. Consolidate market share through strategic acquisitions of specialized software firms to expand telemedicine solution portfolios. This proactive approach mitigates the threat of disruptive innovation from niche players. Leverage existing regulatory expertise to accelerate new product approvals, particularly under stringent frameworks like the EU MDR.
For New Entrants and Emerging Players: Wearable sensor integration offers a technology-first wedge into continuous patient monitoring. Target the home care segment in Southeast Asian countries, which exhibits underpenetrated demand for portable devices. Focus on user-friendly interfaces and robust data connectivity for remote patient management solutions. A direct-to-consumer or partnership-with-telemedicine-providers go-to-market angle can accelerate adoption.
For Investors and Strategic Acquirers: Valuations sit cheapest among established manufacturers of traditional diagnostic equipment facing margin compression. Long-term viability favors firms with strong intellectual property in AI algorithms and advanced materials science, offering sustained growth over a 5-10 year window. Acquisition targets should be specialized device manufacturers with proprietary biocompatible polymer expertise or integrated AI diagnostic platforms. The signal to watch is the rate of reimbursement expansion for remote patient monitoring solutions in developed markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI Algorithm Development | Enhances diagnostic accuracy and throughput for conditions like arrhythmia, attracting specialized clinics. |
| Expand Home Care Device Portfolio | Addresses the rising demand for remote patient monitoring, particularly in emerging markets like Southeast Asia. |
| Secure Biocompatible Polymer Supply | Mitigates supply chain risks and ensures production stability for next-generation implantable cardiac monitors. |
| Pursue EU MDR Compliance | Facilitates market access and strengthens trust for high-risk devices in the European Union. |
| Form Hospital System Partnerships | Drives adoption of integrated diagnostic platforms and telemedicine solutions through established procurement channels. |
Research Approach
Multiple input streams — primary interviews, regulatory filings, and industry reports — were reconciled to construct a robust market view. Primary fieldwork engaged clinicians, hospital purchasing committees, biomedical engineers, and regulatory affairs leads. Secondary data involved US FDA databases, EU MDR guidelines, NMPA standards, and academic literature on cardiopulmonary diseases. This approach utilized both bottom-up market sizing and top-down validation to ensure data accuracy.
Historical market performance was cross-referenced with expert panel input to project future trends across the analysis window. The analytical framework modeled segmentation across product type, therapy area, end-user, and device connectivity level. CAGRs were derived from growth drivers, market restraints, and strategic opportunities identified. Key forecast inputs included aging population demographics and healthcare infrastructure expansion rates.
The model holds under current regulatory stability and technological development trajectories; deviation in global pandemic resurgence or major policy shifts would shift market dynamics. Forecasts reflect assumptions regarding healthcare spending and AI integration rates. Geopolitical instability could significantly alter supply chain resilience.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Chronic Pulmonary Hypertension Treatment Market
Cardiovascular
Ventricular Tachycardia Market
Cardiovascular
Myocardial Infarction Therapeutics Market
Cardiovascular
Endocarditis Therapeutics Market
Cardiovascular
Heart Health Products Market
Cardiovascular
Takotsubo Syndrome Therapeutics Market
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Atherosclerosis Market
Cardiovascular
Peptide-Based Cardiovascular Therapeutics Market
Cardiovascular
Cardiovascular Clinical Trials Market
Cardiovascular
Cardiovascular Disease Drugs Market
Cardiovascular
Hypercholesterolemia Drugs Market
Cardiovascular
Ischemia Market
Cardiovascular
Global Deep Vein Thrombosis Market
Cardiovascular
Global Advanced Cardiovascular Life Support Market
Cardiovascular
Heart Blocks Treatment Market