
 Global Insurance Telematics Market | 2026-2036
Global Insurance Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Insurance Telematics Market Outlook
Market Context
Modular policy bundling is restructuring how fleet buyers and individual motorists evaluate telematics-enabled coverage. Progressive Corporation leverages its Snapshot program to sustain direct-to-consumer channel dominance in usage-based insurance. Octo Telematics S.p.A. anchors European commercial fleet accounts with hardware-software integration across multiple OEM protocols. Cambridge Mobile Telematics competes on smartphone-first deployment, eliminating dedicated hardware costs for price-sensitive segments.
Technical Definition and Segment Structure
Insurance telematics denotes the integrated capture, transmission, and analysis of vehicular operational data—encompassing GPS position, accelerometer-derived driving behavior, engine diagnostics via OBD-II port, and real-time collision detection—to enable risk-calibrated premium pricing and proactive loss prevention. The primary commercial purpose centers on transforming actuarial models from retrospective demographic pooling to prospective individual risk assessment. Hardware and connectivity segments currently occupy the largest revenue share due to embedded module requirements, though data analytics is registering the fastest expansion as insurers build proprietary scoring algorithms. Cloud-based deployment is displacing on-premise infrastructure among mid-tier insurers seeking elastic compute for seasonal policy volume swings.
Regulatory Framework and Outlook
FCC spectrum allocations govern device transmission protocols in the United States, while GDPR and the EU AI Act constrain automated scoring transparency across European markets. The California Consumer Privacy Act and analogous state statutes in Virginia and Colorado are fragmenting compliance architectures for carriers operating across multiple US jurisdictions. Stakeholders must monitor emerging algorithmic accountability requirements that could mandate explainable driving scores and restrict granular biometric inference from vehicle sensor data.
Market Dynamics
Cellular IoT modules and edge analytics are compressing the latency between data capture and premium adjustment, forcing insurers to rebuild actuarial infrastructure around real-time signal processing rather than retrospective pooling.
Growth Catalysts
- GDPR-compliant data architectures:European insurers investing in privacy-preserving analytics are unlocking fleet accounts previously blocked by consent management barriers.
- Commercial fleet digitization:Logistics operators deploying connected vehicle platforms are mandating telematics-enabled coverage as a procurement precondition.
- 5G network slicing:Ultra-reliable low-latency communication is enabling collision detection and emergency response workflows that reduce loss severity.
Market Restraints
- Semiconductor supply concentration:Cellular module production clusters in Taiwan and South Korea create single-source vulnerability for hardware-dependent deployments.
- State-level privacy fragmentation:The California Consumer Privacy Act and divergent statutes in Virginia and Colorado multiply compliance costs for US carriers operating across jurisdictions.
- Biometric inference limitations:EU AI Act restrictions on granular driver profiling constrain scoring algorithm sophistication in European markets.
Strategic Opportunities
- India's uninsured motorist pool:Regulatory pressure from the Insurance Regulatory and Development Authority of India to reduce road fatalities is opening mandatory telematics pilot zones.
- Pay-per-mile urban segments:Smartphone-first deployment models eliminate hardware costs for price-sensitive metropolitan drivers in Germany and the United Kingdom.
- Vehicle-to-everything integration:Convergence of telematics data with smart city infrastructure enables predictive risk routing for commercial fleets.
Industry Challenges
- Embedded systems integration:Insurers lack in-house capability to harmonize proprietary scoring algorithms with OEM data protocols.
- Cross-border data residency:GDPR localization requirements and US state statutes fragment cloud architecture decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Insurance Telematics Market |
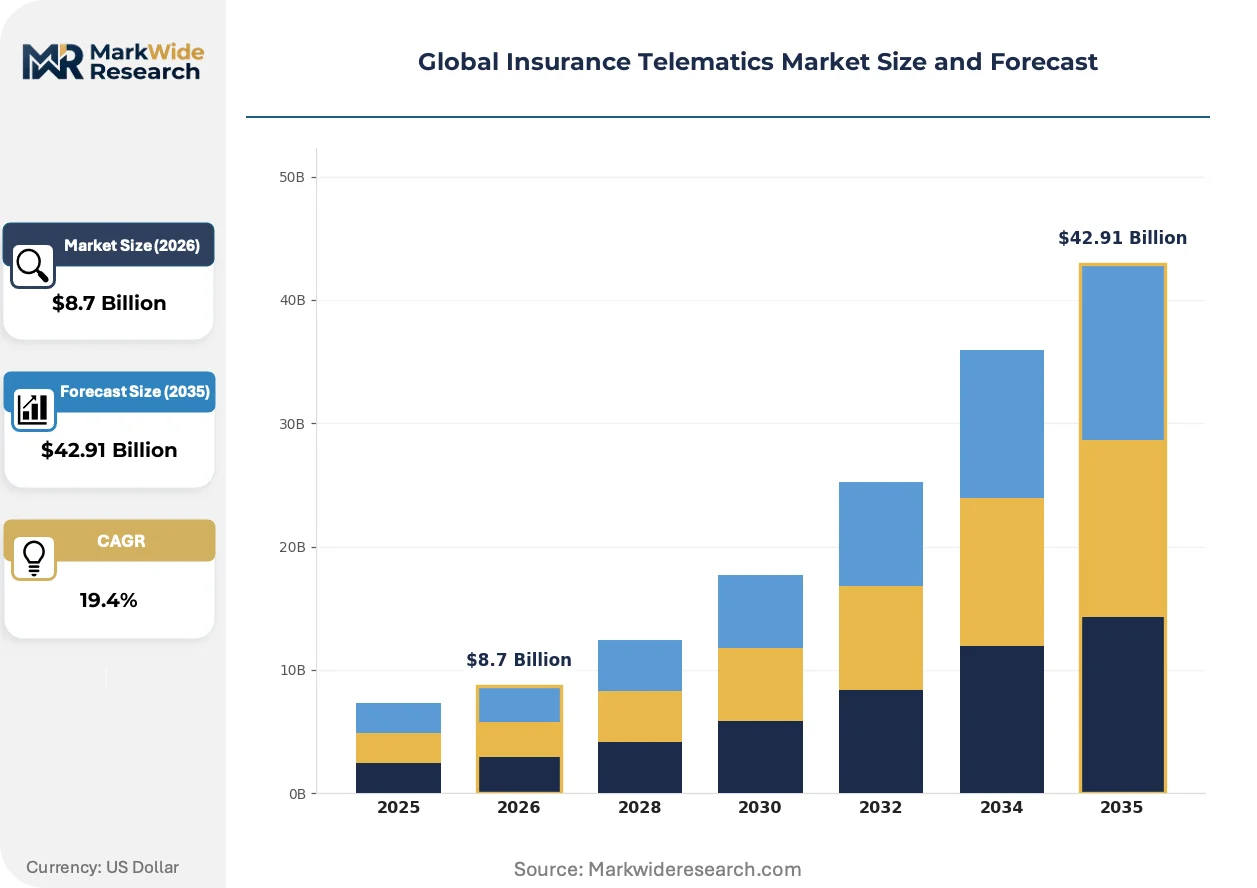
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Data Analytics, Hardware, Software, Connectivity End User: Insurance Companies, Fleet Operators, OEMs, Consumers Deployment: On-premise, Cloud-based, Hybrid, Mobile Application: Usage-Based Insurance, Safety Monitoring, Claims Management, Risk Assessment |
| Companies Covered | AllState Insurance Company, Liberty Mutual Insurance Company, Verizon Communications Inc., Octo Telematics S.p.A., Zurich Insurance Group, Axa SA, Progressive Corporation, Cambridge Mobile Telematics, Vodafone Group Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Insurance Telematics Market Strategic Shifts
Telematics platforms are converging with broader mobility ecosystems, transforming standalone insurance products into integrated risk services embedded within vehicle operating systems and fleet management software.
Edge computing architectures are unifying sensor fusion, local inference, and compressed data transmission within vehicle-mounted modules. Commercial fleet operators in Germany and the United States are adopting these systems to minimize cellular bandwidth costs while maintaining sub-second collision detection. This compression of compute and connectivity is unifying hardware and analytics procurement decisions under single-vendor relationships.
EU AI Act algorithmic transparency mandates are requiring insurers to document driving score logic and provide contestation pathways for policyholders. The regulation is forcing carriers to abandon black-box neural networks in favor of interpretable regression models for European deployments. Commercial lines in France and Italy are most affected, with underwriters rebuilding scoring engines to satisfy national regulator audit requirements.
Fleet procurement teams are consolidating vendor relationships around integrated mobility platforms that bundle telematics, maintenance scheduling, and insurance in unified contracts. This bundling is displacing standalone usage-based insurance policies among logistics operators with more than 500 vehicles. The shift is most visible in the United Kingdom, where fleet management software providers are acquiring insurance licenses to capture premium flows directly.
Global Insurance Telematics Market Segmentation
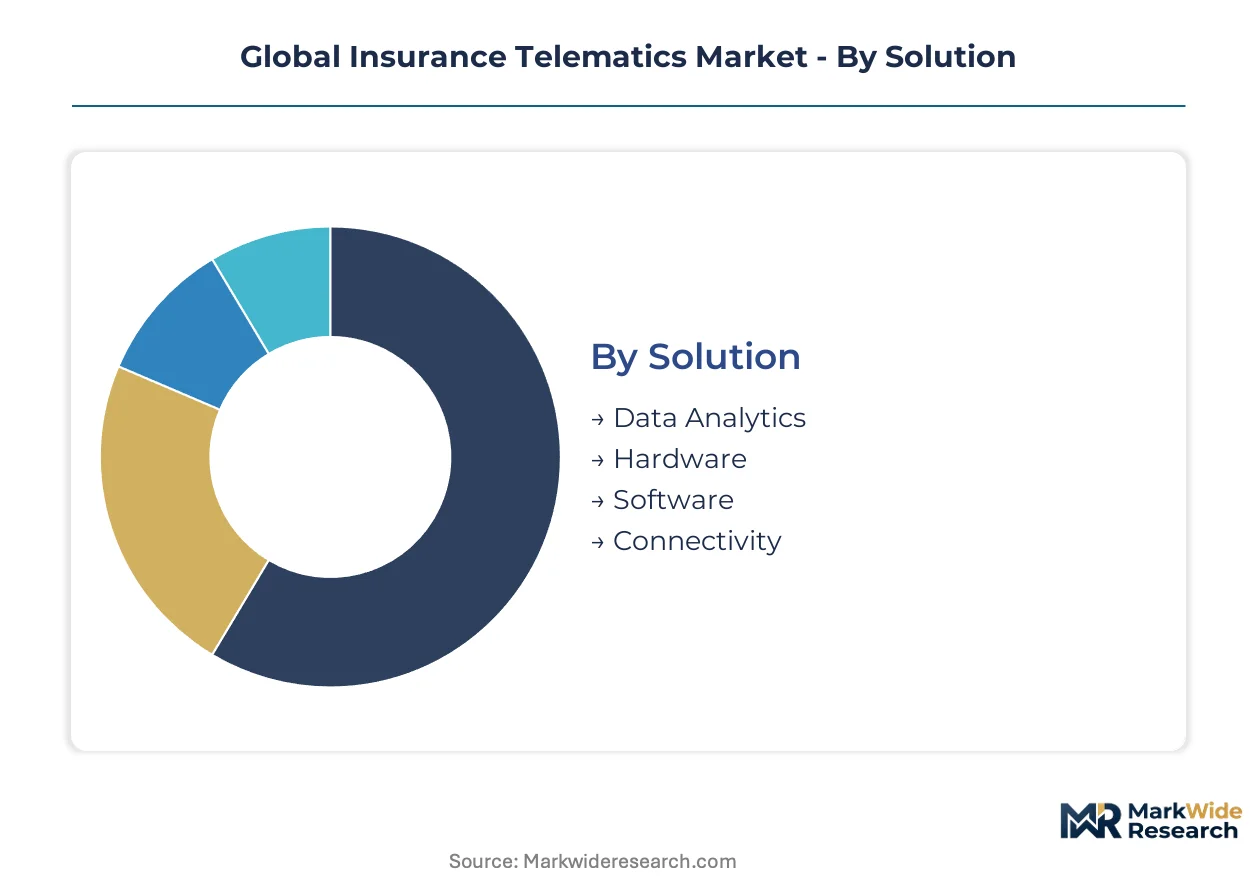
Insurance telematics vendors architect product portfolios around four intersecting dimensions: solution stack depth, buyer technical sophistication, infrastructure ownership preferences, and risk management use case. Segmentation choices determine margin structure, renewal rates, and integration complexity with OEM data streams.
Solution:
Hardware and connectivity components anchor standalone deployments, while analytics and software layers embed into broader mobility platforms.
- Hardware:OBD-II dongles, embedded cellular modules, and edge computing devices capture raw vehicular telemetry. Fleet operators in Germany and the United States dominate procurement, driven by mandates for real-time collision detection and driver behavior monitoring.
- Data Analytics:Proprietary scoring algorithms transform sensor streams into risk-calibrated premiums and predictive loss models. European insurers under GDPR and EU AI Act constraints invest most heavily, requiring explainable regression architectures over black-box neural networks.
- Software:Policy administration platforms and driver-facing mobile applications manage consent workflows and score visualization. Mid-tier US carriers favor cloud-native suites to bypass legacy infrastructure debt.
- Connectivity:Cellular IoT modules and network slicing protocols transmit compressed telemetry to insurer data lakes. 5G network investments by South Korean and Taiwanese semiconductor clusters shape module availability and pricing.
Volume placements concentrate in Hardware; the faster expansion belongs to Data Analytics.
End User:
Buyer segments separate by technical integration capability and procurement scale, from individual motorists to multinational fleet operators.
- Fleet Operators:Logistics and commercial transport buyers with 500+ vehicle fleets demand unified telematics-insurance-maintenance contracts. United Kingdom fleet management platforms are acquiring insurance licenses to capture premium flows directly.
- Insurance Companies:Carriers build proprietary scoring engines or license white-label platforms from telematics vendors. GDPR-compliant architectures unlock European fleet accounts previously blocked by consent management barriers.
- OEMs:Vehicle manufacturers embed telematics at factory installation, controlling data protocol access. Embedded systems integration challenges force insurers into complex partnership negotiations.
- Consumers:Individual motorists adopt smartphone-first or OBD-II dongle solutions for usage-based discounts. Price-sensitive urban drivers in Germany and the United Kingdom gravitate toward zero-hardware deployment models.
Fleet Operators command the largest contract values; Consumers show the steepest expansion trajectory through smartphone-first adoption.
Deployment:
Infrastructure choices reflect data sovereignty requirements, seasonal volume volatility, and in-house technical capacity.
- Cloud-based:Elastic compute resources accommodate seasonal policy volume swings without capital-intensive server procurement. Mid-tier US insurers migrating from on-premise legacy systems drive adoption.
- On-premise:Dedicated infrastructure satisfies strict data residency mandates under GDPR and emerging US state privacy statutes. Large European carriers with established IT operations maintain these deployments.
- Hybrid:Split architectures process sensitive driver data locally while transmitting aggregated analytics to cloud scoring engines. This configuration addresses cross-border data residency fragmentation.
- Mobile:Smartphone-native applications eliminate hardware costs entirely, relying on device sensors for accelerometer and GPS telemetry. Metropolitan pay-per-mile segments in Germany favor this lightweight approach.
Cloud-based deployments claim the dominant share; Hybrid architectures are climbing the fastest as compliance complexity deepens.
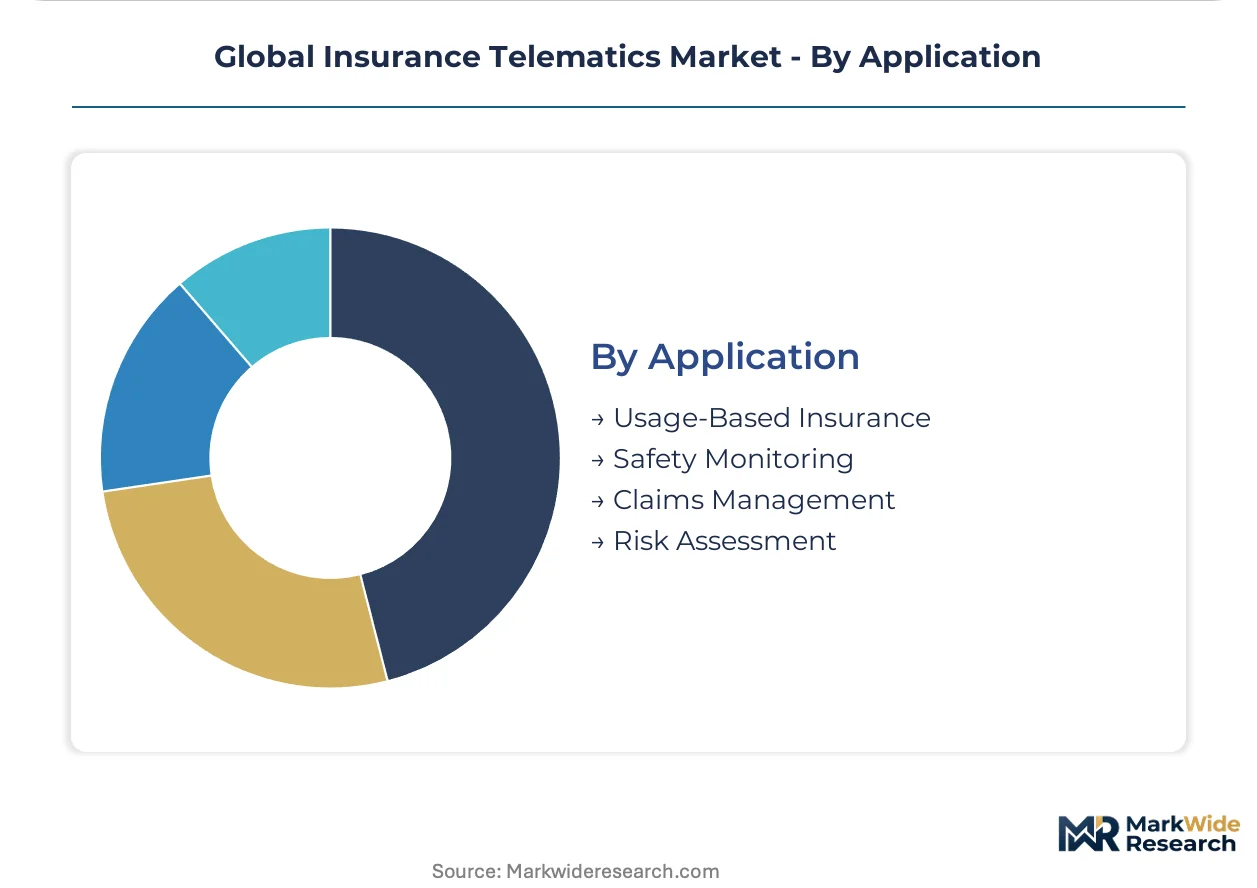
Application:
Use case segmentation aligns telematics investment with specific risk management outcomes and premium pricing models.
- Usage-Based Insurance:Pay-as-you-drive and pay-how-you-drive models calibrate premiums against actual mileage and behavior. This application anchors consumer adoption in Germany, the United Kingdom, and the United States.
- Safety Monitoring:Real-time driver coaching and collision detection workflows reduce loss severity. 5G network slicing enables sub-second emergency response integration for commercial fleets.
- Claims Management:Automated first notice of loss and fraud detection accelerates settlement timelines. Insurers leverage accelerometer signatures and GPS reconstruction to validate collision circumstances.
- Risk Assessment:Prospective individual risk scoring replaces retrospective demographic pooling in actuarial models. EU AI Act transparency mandates force algorithmic documentation and contestation pathways.
Usage-Based Insurance holds the deepest market penetration; Claims Management is gaining share fastest through automation ROI.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware module production clusters in Taiwan and South Korea while demand concentrates in Germany, the United Kingdom, and the United States where fleet digitization and regulatory clarity have advanced furthest. This production-consumption divide shapes vendor strategies around localization partnerships and data residency compliance.
United States
Commercial fleet operators with 500-plus vehicle mandates drive hardware procurement volumes. FCC spectrum allocations govern device transmission protocols while state-level privacy statutes in California, Virginia, and Colorado fragment compliance architectures. Dallas-Fort Worth logistics hubs anchor adoption clusters where fleet management platforms bundle telematics with maintenance scheduling.
Germany
Automotive OEM embedded systems integration creates captive data protocol access for factory-installed telematics. GDPR and the EU AI Act constrain automated scoring transparency, forcing insurers toward explainable regression models. Munich and Stuttgart industrial corridors concentrate vendor engineering partnerships with premium manufacturers.
United Kingdom
Smartphone-first deployment models eliminate hardware costs for price-sensitive urban motorists in London and Manchester. Fleet management software providers are acquiring insurance licenses to capture premium flows directly. The Information Commissioner's Office enforces strict consent management for driver behavioral data.
India
The Insurance Regulatory and Development Authority of India is mandating telematics pilot zones to reduce road fatalities among uninsured motorists. Commercial logistics operators in Maharashtra and Gujarat are deploying connected vehicle platforms as procurement preconditions. Mumbai-Pune industrial belt concentrates fleet digitization investments.
China
Domestic OEMs are embedding telematics at factory installation, controlling data protocol access for risk-calibrated products. MIIT standards govern cellular module certification while provincial regulators experiment with usage-based insurance pilots. Shenzhen and Shanghai technology corridors anchor module production and algorithm development clusters.
Global Insurance Telematics Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across hardware, connectivity, and analytics layers. The vendor base organizes into three tiers: integrated mobility platforms bundling telematics with fleet software, insurance carriers building proprietary scoring engines, and component suppliers providing cellular modules and edge devices. Strategic moves concentrate on embedded systems partnerships with OEMs and privacy-preserving analytics architectures for GDPR-compliant deployments.
Among diversified insurance carriers, Progressive Corporation and AllState Insurance Company exemplify the carrier-built telematics model. Octo Telematics S.p.A. represents the hardware-software integration specialist archetype serving European commercial accounts. These three anchors illustrate the competitive tension between captive data ecosystems and open-platform vendor relationships reshaping procurement decisions.
| Leading Market Players |
|---|
| AllState Insurance Company |
| Liberty Mutual Insurance Company |
| Verizon Communications Inc. |
| Octo Telematics S.p.A. |
| Zurich Insurance Group |
| Axa SA |
| Progressive Corporation |
| Cambridge Mobile Telematics |
| Vodafone Group Plc |
| Others |
Value Chain & Pricing Dynamics
Fleet procurement consolidation around unified telematics-insurance contracts is compressing hardware margins and forcing module suppliers to absorb connectivity costs upfront. This buyer-driven restructuring concentrates pricing power among logistics operators with 500-plus vehicle mandates while fragmenting vendor revenue recognition across multi-year service agreements.
Pricing Analysis
Cost-down pressure on embedded cellular modules accelerates because Taiwanese and South Korean semiconductor clusters face yield constraints at mature process nodes. Three-tier pricing structure across premium, standard, and economy levels separates OEM-integrated factory installations from aftermarket OBD-II dongles and smartphone-native deployments. Price differentiation traces to certification grade under FCC spectrum allocations and GDPR-compliant data architectures, with European deployments commanding service premiums for algorithmic transparency documentation. Fleet operators in the United States exhibit lowest price sensitivity due to mandated safety monitoring requirements, while individual motorists in Germany gravitate toward zero-hardware models.
Supply Chain Analysis
Cellular IoT module production rests on Taiwanese foundry capacity and South Korean memory integration, with edge computing silicon sourced from United States fabless designers. Raw material dependencies include gallium arsenide substrates, advanced packaging substrates, and lithium-ion power management components. Single-source vulnerability concentrates in Taiwan Strait logistics corridors, where geopolitical disruption would stall hardware deployments for European and North American fleet operators. Distribution runs through Tier 1 automotive suppliers and direct OEM procurement channels, bypassing traditional insurance vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insurance telematics sector is consolidating around vertical-integration races, with hardware vendors acquiring scoring algorithm capabilities and insurers building captive module supply relationships to secure data protocol access.
For Market Incumbents: Acquire proprietary scoring algorithm assets to defend against smartphone-first entrants eliminating hardware attach rates. Incumbents must embed edge analytics capabilities directly into vehicle-mounted modules, mirroring Octo Telematics S.p.A.'s hardware-software integration model. Capacity addition in GDPR-compliant cloud architectures unlocks European fleet accounts previously blocked by consent management barriers. For New Entrants and Emerging Players: India's uninsured motorist pool offers the most penetrable entry point, where IRDAI-mandated telematics pilot zones reduce competitive friction against established hardware vendors. Pay-per-mile urban segments in Germany and the United Kingdom present secondary white-space targets for smartphone-first deployment models. Go-to-market positioning should emphasize zero-hardware cost structures and rapid consent workflow deployment. For Investors and Strategic Acquirers: The window for entry favors analytics-specialist firms with explainable regression architectures compliant with EU AI Act transparency mandates. Long-term viability hinges on algorithmic differentiation rather than hardware volume scale, as edge computing compression unifies module and analytics procurement. Watch for IRDAI regulatory expansion beyond pilot zones as the inflection signal for Indian market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Systems Partnership | OEM data protocol access secures factory-installation revenue streams for hardware vendors. |
| Privacy-Preserving Analytics Investment | GDPR-compliant architectures unlock European fleet accounts blocked by consent barriers. |
| Smartphone-First Platform Launch | Zero-hardware deployment captures price-sensitive metropolitan motorists in Germany and the United Kingdom. |
| 5G Network Slicing Integration | Ultra-reliable low-latency communication enables sub-second collision detection for commercial fleets. |
| Insurance License Acquisition | Fleet management software providers capture premium flows directly in the United Kingdom market. |
Study Parameters
SEC filings, ETSI technical specifications, and national regulator disclosure databases formed the secondary backbone, supplemented by customs records tracking cellular module trade flows. Primary interviews with fleet procurement directors, insurance actuarial leads, OEM platform engineers, and telematics vendor product managers validated demand assumptions and pricing structures. Bottom-up triangulation across hardware shipment data and top-down reconciliation against premium revenue flows ensured segmentation integrity.
Historical trendline analysis examined connected-vehicle penetration curves and usage-based insurance adoption rates across the analysis window. The forecast framework modeled solution stack depth, buyer technical sophistication, deployment infrastructure preferences, and risk management use case as intersecting segmentation dimensions. CAGRs were derived from elasticity-adjusted adoption curves incorporating 5G network rollout timelines and regulatory mandate implementation schedules.
Revisions become necessary when semiconductor supply disruptions, GDPR enforcement pattern shifts, or IRDAI regulatory expansion beyond pilot zones materialize. Forecasts reflect assumptions about OEM data protocol openness and fleet procurement consolidation trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Insurtech Market
Insurance Technology
Singapore Insurtech Market
Insurance Technology
Global Insurance Agency Software Market
Insurance Technology
Germany AI in Insurance Market
Insurance Technology
China AI in Insurance Market
Insurance Technology
Insurance Software Market
Insurance Technology
Insurance Automation Market
Insurance Technology
Asia-Pacific P&C Insurance Software Market
Insurance Technology
UK Insurtech Market
Insurance Technology
North America Insurance Telematics Market
Insurance Technology
Global Blockchain in Insurance Market
Insurance Technology
Middle East AI in Insurance Market
Insurance Technology
Europe Insurtech Market
Insurance Technology
Europe Insurance Telematics Market
Insurance Technology
North America Insurtech Market
Insurance Technology
Artificial Intelligence in Insurtech Market