
 Global Insurance Rating Software Market | 2026-2036
Global Insurance Rating Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Insurance Rating Software Market Outlook
Market Context
Actuarial data science talent scarcity is redrawing competitive boundaries among software vendors. Guidewire Software leverages its extensive partner ecosystem to sustain implementation velocity across tier-one carriers. Duck Creek Technologies anchors its position through cloud-native architecture that reduces deployment cycles for mid-market insurers. Verisk Analytics competes on proprietary data assets that differentiate rating precision in catastrophe-prone lines.
Technical Definition and Segments
Insurance rating software comprises algorithmic engines that calculate premiums using actuarial models, underwriting rules, and regulatory filing parameters, typically processing thousands of rating variables in sub-second response times for quote generation. Cloud-based deployment leads product type segmentation due to elastic compute requirements during peak quoting periods, while hybrid configurations capture margin pools from carriers with data residency constraints. The end-user base fragments across insurance companies seeking direct channel control, brokers demanding multi-carrier comparison capabilities, and reinsurers requiring portfolio-level aggregation tools.
Regulatory Frame and Outlook
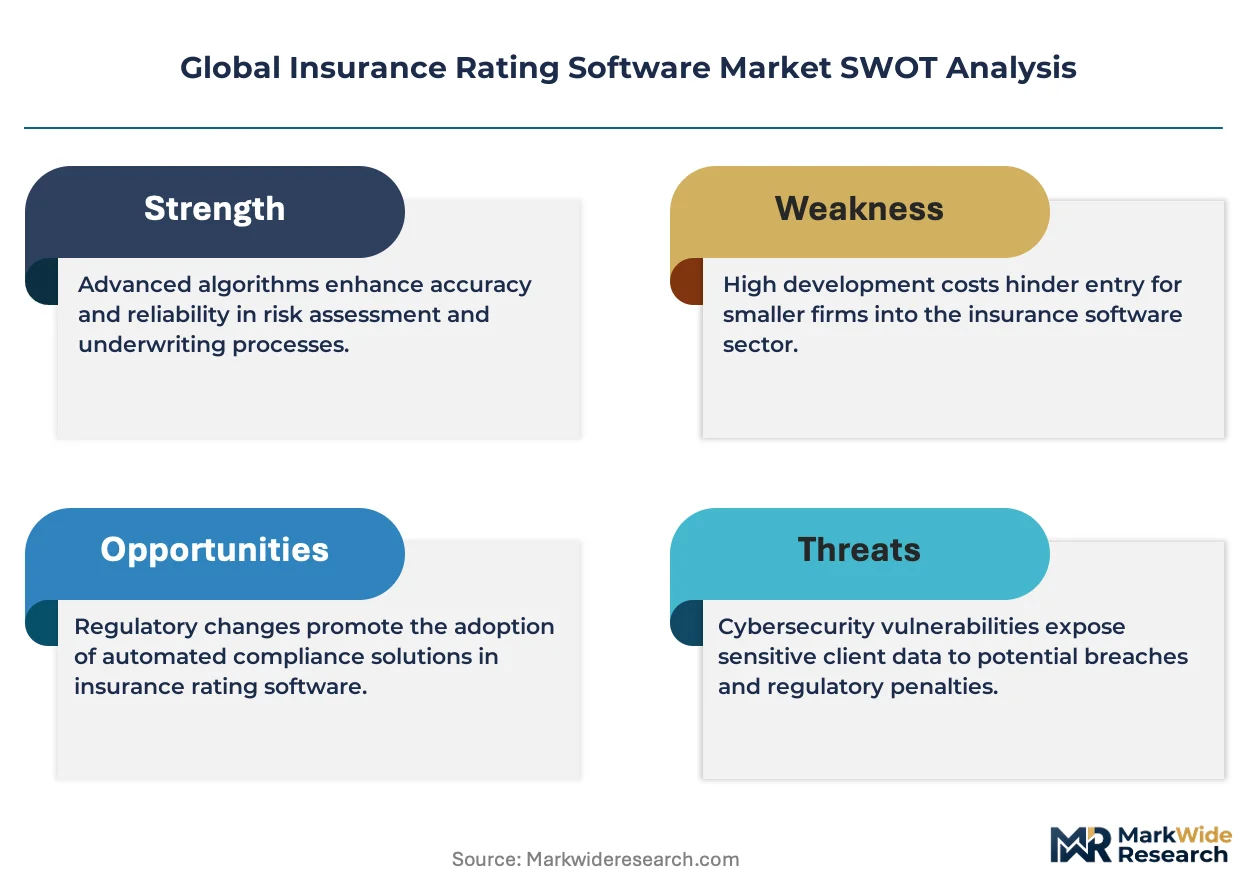
The US state insurance commissioners enforce rate filing transparency through SERFF, while the EU AI Act imposes algorithmic accountability standards on automated underwriting decisions. The UK's Financial Conduct Authority scrutinizes pricing fairness through consumer duty rules that affect rating model governance. Stakeholders must monitor divergence between prescriptive state-level filing requirements and principles-based European algorithmic governance as this tension shapes product roadmaps and geographic prioritization.
Market Dynamics
Cloud-native rating engine architecture is compressing deployment timelines from years to months, forcing incumbent vendors to restructure delivery models around API-first microservices that decouple rating logic from legacy policy administration monoliths.
Growth Catalysts
- EU AI Act compliance mandates:European carriers must document algorithmic decision logic for automated underwriting, creating procurement urgency for rating platforms with built-in explainability frameworks and audit trails.
- Real-time quoting demand:Direct-to-consumer distribution channels require sub-second rating responses across thousands of variables, pushing insurers toward elastic cloud compute architectures that scale during peak traffic.
- Telematics data integration:Usage-based auto insurance programs in the United States and Germany are expanding rating variable sets from hundreds to tens of thousands, necessitating specialized ingestion pipelines.
Market Restraints
- Actuarial talent scarcity:The intersection of statistical modeling and software engineering commands premium compensation that mid-market insurers struggle to match, constraining in-house development capacity.
- State filing fragmentation:US carriers must submit rate algorithms individually to fifty separate insurance departments, each with unique formatting requirements that multiply compliance overhead.
- Data residency requirements:German and Swiss carriers face strict localization mandates that block pure public cloud deployments, forcing expensive hybrid infrastructure investments.
Strategic Opportunities
- India's IRDAI digitization push:The regulator's mandatory e-insurance account framework and standardized product templates create openings for rating engines that automate compliance with local filing protocols.
- Parametric insurance expansion:Climate-linked triggers for crop and catastrophe coverage require new rating methodologies that correlate satellite data with payout structures, opening greenfield product categories.
- Embedded insurance APIs:Point-of-sale integration with automotive and e-commerce platforms lets carriers quote within partner workflows, bypassing traditional agent channels entirely.
Industry Challenges
- Legacy system integration complexity:Decades-old policy administration databases use proprietary data schemas that resist standard API connectivity, extending implementation timelines.
- Model governance staffing gaps:Carriers lack sufficient personnel to maintain version control, bias testing, and documentation across hundreds of concurrent rating algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Insurance Rating Software Market |
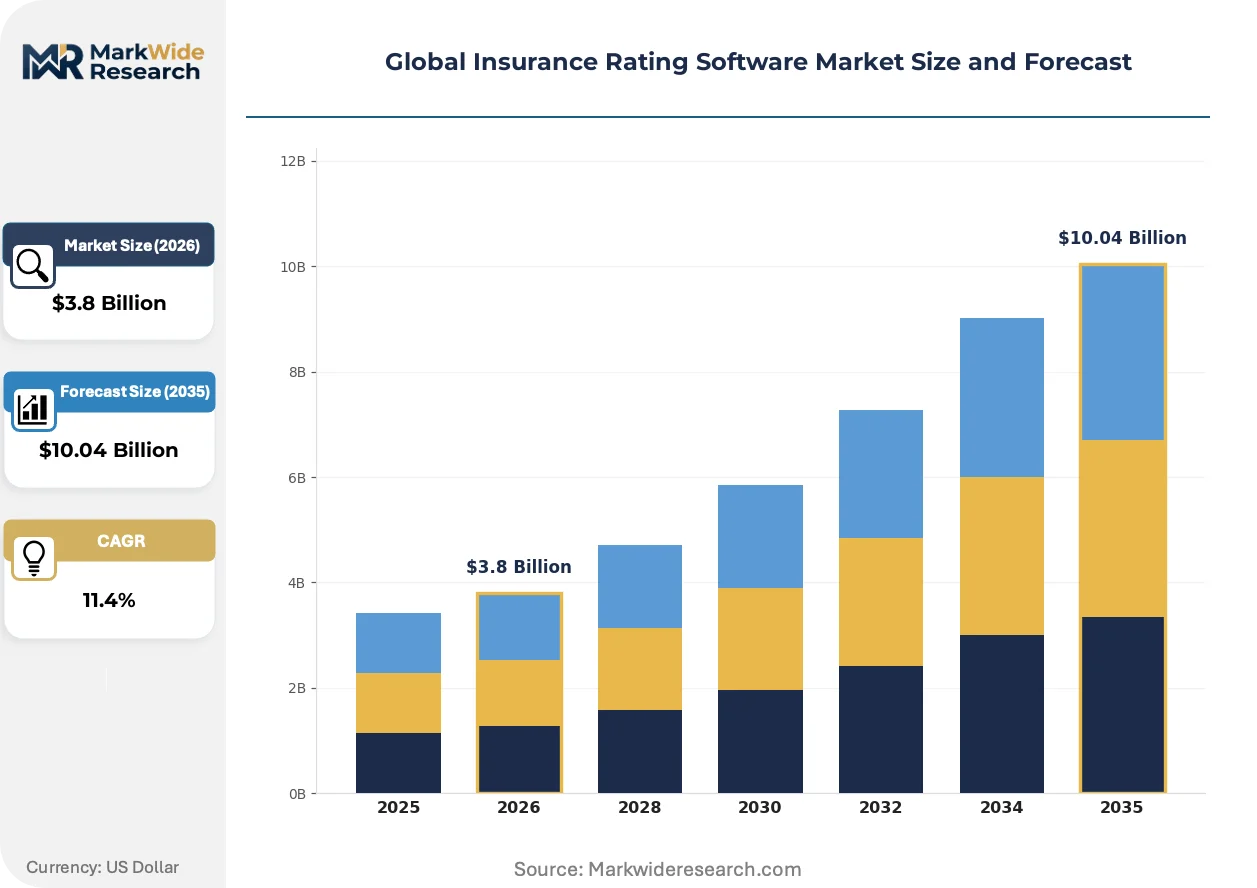
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, Web-Based End User: Insurance Companies, Brokers, Agents, Reinsurers Deployment: Private Cloud, Public Cloud, Hybrid Cloud, Local Server Service Type: Consulting, Implementation, Maintenance, Support |
| Companies Covered | Guidewire Software, Duck Creek Technologies, Verisk Analytics, Sapiens International Corporation, OneShield, Majesco, Insurity, Oracle Corporation, SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Insurance Rating Software Market Strategic Shifts
Algorithmic transparency requirements and edge computing economics are converging to reshape how rating engines are architected, deployed, and governed across property-casualty lines.
Containerized rating microservices are miniaturizing deployment footprints for regional insurers. Tier-two carriers in Australia and Canada now adopt pre-configured rating modules through Kubernetes orchestration rather than customizing monolithic platforms. This architecture is miniaturizing the minimum viable implementation from enterprise-scale transformation projects to incremental capability additions.
REACH and the EU AI Act together impose chemical safety and algorithmic accountability obligations on automated underwriting systems. Insurers must now trace rating factor provenance through supply chains while documenting decision logic for regulatory examination. Commercial lines carriers with complex multi-factor models face the steepest compliance reconstruction costs.
Subscription-based pricing for rating engine access is displacing perpetual license models among mid-market insurers. Brokers and managing general agents now prefer per-transaction economics that align software costs with premium volume rather than fixed annual commitments. This shift is most pronounced in the United Kingdom, where Lloyd's syndicates and coverholders prioritize capital-efficient technology procurement.
Global Insurance Rating Software Market Segmentation
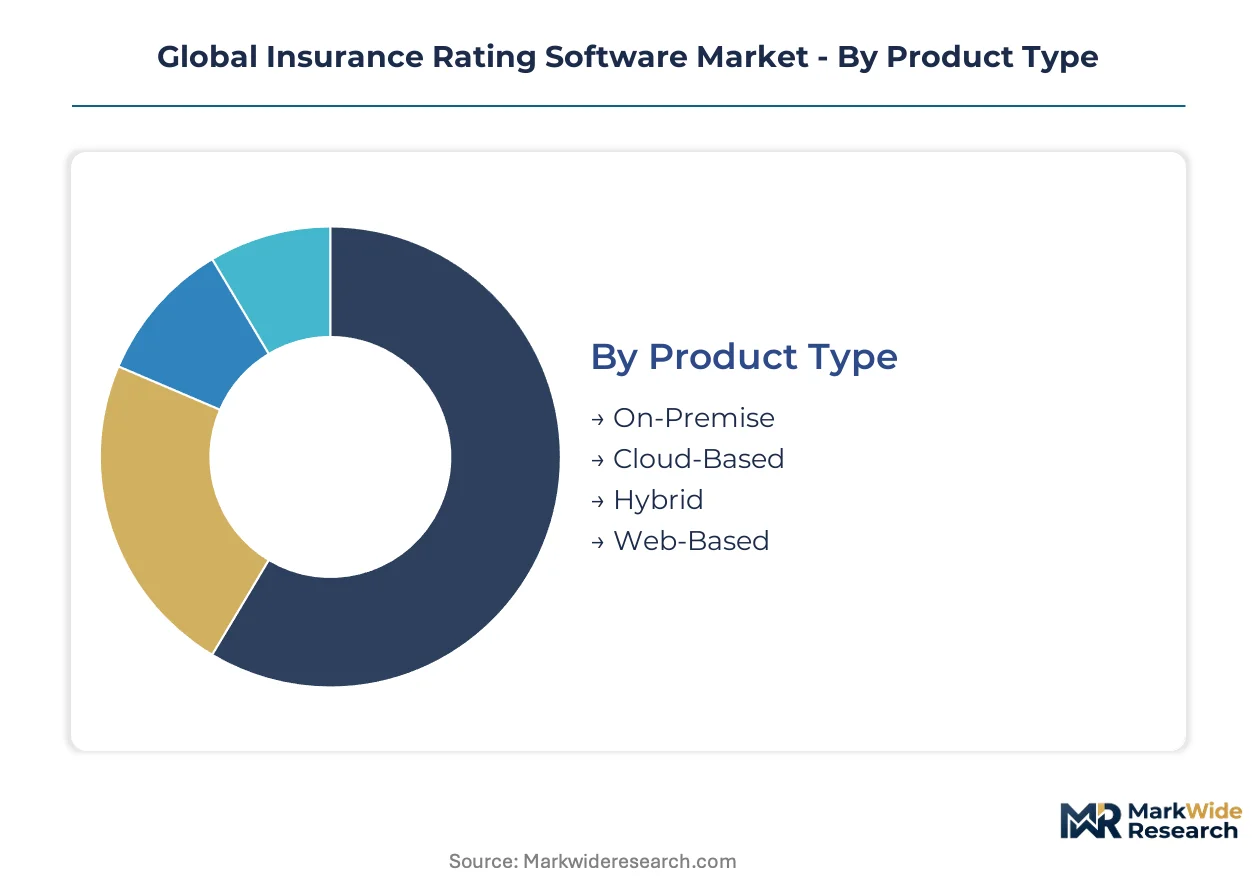
Insurance rating software segmentation reveals how procurement priorities diverge across carrier IT maturity levels and regulatory constraints. Deployment architecture choices directly determine which vendors can compete for specific account profiles.
Product Type:
Channel mix varies sharply by infrastructure model, with direct-to-consumer insurers favoring elastic cloud configurations while captive agents tolerate on-premise latency.
- Cloud-Based:Elastic compute architectures scale rating throughput during peak quoting windows without capital expenditure. United States direct auto insurers and German telematics programs concentrate procurement here, driven by real-time quote volume volatility and EU AI Act audit trail requirements.
- Hybrid:Split architectures host sensitive rating algorithms locally while pushing non-regulated compute to public cloud. Swiss and German carriers facing data residency mandates from national regulators anchor demand, balancing compliance against cloud economics.
- On-Premise:Perpetual license models persist among Japanese and South Korean carriers with conservative IT governance frameworks.
- Web-Based:Browser-delivered rating interfaces serve independent agent networks in Australia and Canada with minimal IT footprint.
By volume, Cloud-Based leads. By growth pace, Hybrid is climbing the fastest.
End User:
Margin profiles differ across the value chain, with reinsurers paying premium pricing for portfolio aggregation capabilities while agents drive commoditization through comparison shopping.
- Insurance Companies:Direct channel carriers invest most heavily in sub-second rating engine performance and regulatory filing automation. Tier-one property-casualty carriers in the United States and United Kingdom dominate procurement, prioritizing SERFF integration and Lloyd's market connectivity respectively.
- Reinsurers:Treaty and facultative pricing platforms require stochastic simulation engines that aggregate cedant exposure data. Bermuda and London market participants anchor this segment, driven by catastrophe model correlation requirements.
- Brokers:Multi-carrier comparison platforms in the United Kingdom and Netherlands favor API-first rating access over full platform licensing.
- Agents:Independent producer networks in the United States select web-based rating portals with minimal implementation friction.
By revenue concentration, Insurance Companies dominate. By contract value expansion, Reinsurers are gaining share fastest.
Deployment:
Customer type shapes infrastructure selection, with mid-market insurers accepting public cloud economics while national carriers invest in hybrid sovereignty.
- Public Cloud:Shared infrastructure delivers lowest per-transaction economics for variable quoting volumes. United States insurtech startups and Australian direct writers concentrate here, driven by capital efficiency and rapid scaling requirements.
- Private Cloud:Dedicated tenant environments satisfy financial services regulators in Singapore and Hong Kong regarding data segregation.
- Hybrid Cloud:Workload portability between environments serves Canadian carriers navigating provincial data localization variations.
- Local Server:Air-gapped installations persist among United States mutual insurers with mutual board technology risk aversion.
By deployment count, Public Cloud leads. By compliance-driven switching, Hybrid Cloud shows steepest expansion trajectory.
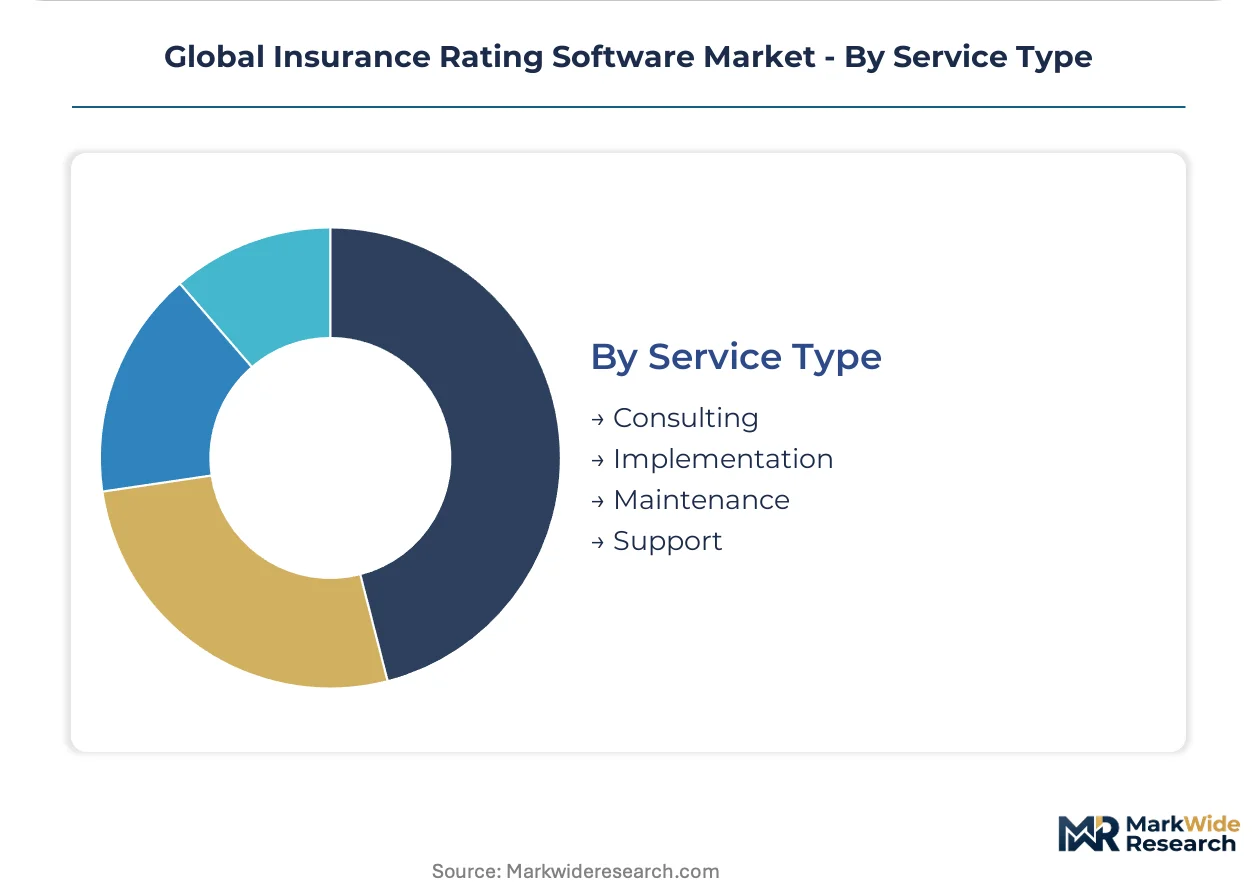
Service Type:
Maturity stage determines service mix, with greenfield implementations requiring heavy consulting while established platforms shift toward maintenance optimization.
- Implementation:System integration services bridge rating engines to legacy policy administration databases. Tier-two carriers in India and Brazil anchor demand, driven by IRDAI digitization mandates and SUSEP regulatory filing automation respectively.
- Consulting:Actuarial transformation advisory guides rating model governance framework design. European carriers facing EU AI Act documentation requirements concentrate procurement here.
- Maintenance:Version control and regression testing services stabilize algorithm portfolios for United States regional carriers.
- Support:Help desk and troubleshooting contracts serve United Kingdom managing general agents with limited internal IT capacity.
By service revenue, Implementation leads. By margin expansion, Consulting is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by regulatory maturity. United States carriers prioritize real-time quoting throughput, while European markets weight algorithmic auditability more heavily in procurement decisions.
United States
Direct-to-consumer auto insurers and commercial property carriers drive cloud-native rating engine procurement. State insurance commissioners enforce rate filing transparency through SERFF, with Texas, California, and New York maintaining the most stringent documentation requirements. Silicon Valley insurtech clusters and Hartford's legacy carrier concentration anchor demand for sub-second quote generation capabilities.
Germany
Telematics-enabled auto insurers and industrial commercial lines carriers dominate adoption. The national regulator imposes strict data residency mandates that block pure public cloud deployments, forcing hybrid infrastructure investments. Munich's reinsurance hub and Frankfurt's financial services corridor concentrate procurement of portfolio-level aggregation tools.
United Kingdom
Lloyd's syndicates and managing general agents prioritize API-first rating access for multi-carrier comparison platforms. The Financial Conduct Authority scrutinizes pricing fairness through consumer duty rules affecting rating model governance. London's specialty insurance market and Manchester's broker networks anchor demand for per-transaction pricing models.
India
IRDAI's mandatory e-insurance account framework and standardized product templates accelerate digitization among tier-two carriers. The regulator's filing protocol automation creates openings for rating engines that embed local compliance logic. Mumbai's financial district and Bangalore's technology corridor concentrate implementation services demand.
Australia
Direct writers and independent agent networks favor web-based rating portals with minimal IT footprint. APRA's risk-based capital framework influences rating model sophistication requirements for general insurers. Sydney's commercial lines concentration and Melbourne's broker networks drive containerized microservices adoption among regional carriers.
Global Insurance Rating Software Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, creating a two-speed competitive dynamic. The upper tier commands premium pricing through end-to-end platform integration, while specialists win on deployment velocity and domain-specific rating logic. Three archetypes dominate: legacy platform modernizers, cloud-native challengers, and data asset aggregators. Consolidation through strategic acquisitions and API ecosystem expansion represent the primary competitive vectors reshaping vendor positioning.
Within the legacy modernizer archetype, Guidewire Software and Oracle Corporation occupy positions anchored to extensive partner ecosystems and enterprise-scale implementation capacity. Duck Creek Technologies exemplifies the cloud-native challenger tier through architecture designed for compressed deployment cycles. Verisk Analytics sits within the data asset aggregator category, competing on proprietary information resources that differentiate rating precision.
| Leading Market Players |
|---|
| Guidewire Software |
| Duck Creek Technologies |
| Verisk Analytics |
| Sapiens International Corporation |
| OneShield |
| Majesco |
| Insurity |
| Oracle Corporation |
| SAP SE |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation contracts with hyperscale cloud providers lock in both compute access and cost predictability for rating engine vendors serving European carriers facing EU AI Act compliance deadlines. These arrangements tether software pricing to infrastructure commitments while insulating mid-market insurers from spot-market volatility during peak quoting windows.
Pricing Analysis
Subscription-based SaaS tiers dominate contract structures, with pricing stratifying across enterprise, mid-market, and entry-level bands based on API call volume and regulatory filing automation depth. Cost compression in the entry tier is intensifying because containerized microservices lowered deployment barriers for regional competitors. Mid-market insurers exhibit highest price sensitivity, while tier-one carriers prioritize sub-second latency guarantees over per-transaction economics.
Supply Chain Analysis
Actuarial talent pipelines in India, Poland, and the Philippines constrain rating model development capacity for vendors competing on implementation velocity. Cloud infrastructure draws from hyperscale data centers in the United States, Ireland, and Singapore, with compute hardware resting on semiconductor supply from Taiwan and South Korea. Single-source vulnerability in specialized GPU allocations for stochastic simulation engines threatens reinsurer pricing platform delivery timelines. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is recovering from a cyclical trough in legacy modernization spending, with carrier IT budget restoration following pandemic-era deferred upgrades now driving procurement urgency.
For Market Incumbents: Secure actuarial data science talent through captive development centers in Bangalore and Warsaw before specialist compensation inflation spreads to secondary markets. Consolidate partner ecosystems around API-first microservices to defend against cloud-native challengers eroding implementation timelines. For New Entrants and Emerging Players: Anchor in India's tier-two carrier segment where IRDAI digitization mandates outpace incumbent vendor delivery capacity. Target Lloyd's coverholders in London with per-transaction pricing models that bypass capital-intensive platform licensing barriers. For Investors and Strategic Acquirers: Cloud-native rating engine specialists with embedded compliance documentation tools represent the most defensible acquisition profile for the next investment cycle. Monitor SERFF filing automation adoption rates across state insurance departments as the inflection signal for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Enables real-time rating interoperability across Guidewire and Duck Creek policy administration platforms. |
| Compliance Documentation Automation | Reduces EU AI Act audit preparation costs for Munich and Frankfurt-based commercial lines carriers. |
| Actuarial Talent Acquisition | Secures scarce statistical modeling capacity ahead of competing vendors in Bangalore and Warsaw markets. |
| Hybrid Cloud Certification | Unlocks procurement eligibility among Swiss and German carriers facing BaFin data residency mandates. |
| Embedded Insurance Integration | Positions rating engines within automotive OEM and e-commerce checkout workflows bypassing agent channels. |
Study Parameters
Operator-level perspectives from chief underwriting officers, actuarial transformation leads, IT procurement directors at tier-one carriers, and systems integration partners anchored the qualitative base. These primary insights combined with secondary validation from NAIC SERFF filing databases, Lloyd's market transaction records, IRDAI regulatory circulars, and vendor SEC disclosures. Bottom-up carrier spending estimates triangulated against top-down software market sizing across deployment architecture and end-user segments.
Sensitivity analysis tested forecast outputs against varying assumptions for cloud migration velocity and regulatory filing automation adoption across the projection horizon. The analytical framework modeled segmentation across deployment model, carrier tier, line of business complexity, and regional regulatory cluster. CAGRs derived from trend extrapolation of quoted premium volumes and software procurement intensity ratios, with specific inputs for telematics data ingestion pipeline investments and parametric insurance algorithm development.
Decision-makers should treat outputs as directional under assumptions of sustained carrier IT budget growth and stable state regulatory filing requirements; material deviation in macroeconomic conditions or federal preemption of state rate review would warrant model refresh. Practitioners should keep alternative scenarios live as EU AI Act enforcement patterns and SERFF modernization timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Europe Insurtech Market
Insurance Technology
Latin America AI in Insurance Market
Insurance Technology
Insurance Fraud Detection Market
Insurance Technology
Global Insurance Agency Software Market
Insurance Technology
North America Insurtech Market
Insurance Technology
Global Blockchain in Insurance Market
Insurance Technology
United States Insurtech Market
Insurance Technology
Artificial Intelligence in Insurtech Market
Insurance Technology
Japan AI in Insurance Market
Insurance Technology
Insurance Software Market
Insurance Technology
UK Insurtech Market
Insurance Technology
Middle East AI in Insurance Market
Insurance Technology
Global Commercial Insurance Software Market
Insurance Technology
Insurtech Market
Insurance Technology
Europe Insurance Telematics Market
Insurance Technology
Middle East and Africa Insurtech Market