
 Insurance Software Market | 2026-2036
Insurance Software Market Size, Share, and Industry Trends Forecast 2026-2036
Insurance Software Market Intelligence
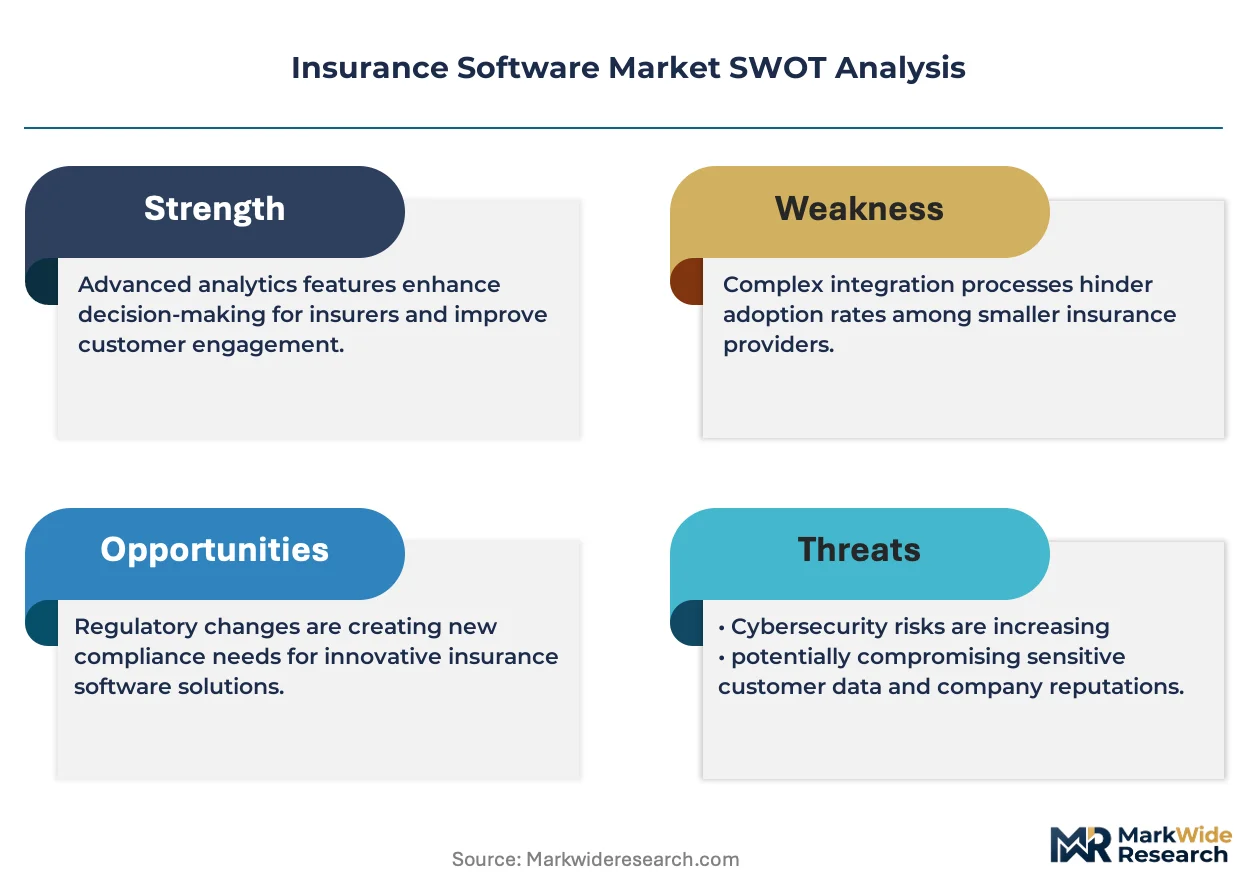
Cloud-native architecture is reshaping how insurance software is built and delivered, replacing monolithic legacy systems with microservices and API-first platforms. Guidewire leverages extensive R&D investment to anchor its position in property and casualty core systems. SAP competes through deep ERP integration that extends its insurance suite into enterprise finance workflows. Salesforce dominates customer engagement layers with CRM-native policy servicing tools.
Insurance software comprises modular applications that automate policy administration, claims adjudication, premium billing, and actuarial risk calculation through rules engines and workflow orchestration. The primary commercial purpose is reducing operational expense ratios while improving underwriting precision and policyholder retention. Claims management solutions lead current spending as carriers prioritize loss-cost containment, while cloud-based deployment represents the fastest-growing segment as insurers exit data center obligations. SaaS delivery is maturing fastest among mid-tier carriers seeking predictable IT expenditure, though on-premise systems still occupy large commercial lines carriers with complex customization requirements.
FDA oversight of software-as-medical-device interfaces affects health insurance platforms processing clinical data, while state insurance commissioners across the United States enforce NAIC model laws on data privacy and algorithmic fairness. The EU AI Act imposes risk-classification requirements on automated underwriting and claims scoring systems sold into European jurisdictions. Stakeholders must monitor how divergent regulatory timelines between U.S. state laboratories and EU harmonization efforts will fragment compliance architecture investments.
Market Dynamics
Cloud-native migration is compressing carrier IT refresh cycles as property and casualty insurers abandon decade-old monolithic cores for API-first microservices architectures. This structural shift accelerates vendor consolidation while elevating compliance architecture to a board-level priority.
Growth Catalysts
- EU AI Act:Risk-classification mandates for automated underwriting systems are forcing carriers to replace rule-based engines with auditable machine-learning pipelines, expanding software procurement budgets.
- Mid-tier carriers:Predictable SaaS expenditure models are displacing capital-intensive on-premise deployments, converting perpetual license holders to recurring revenue relationships.
- Claims management automation:Loss-cost containment priorities are redirecting IT spending toward intelligent adjudication platforms that reduce loss adjustment expense ratios.
Market Restraints
- Specialized talent scarcity:Actuarial data scientists with both domain expertise and MLOps proficiency command compensation premiums that inflate implementation costs.
- Cloud concentration risk:AWS, Azure, and GCP control hyperscale infrastructure, exposing carriers to egress cost volatility and single-provider dependency.
- State-by-state regulatory fragmentation:NAIC model laws diverge across United States jurisdictions, multiplying compliance engineering overhead for multi-state carriers.
Strategic Opportunities
- Embedded insurance APIs:B2B software platforms and IoT device manufacturers represent untapped distribution channels for policy origination at point of transaction.
- Climate risk modeling convergence:Satellite imagery and parametric triggers are opening new product categories in catastrophe-exposed markets previously deemed uninsurable.
- IRA climate disclosure rules:United States carriers face mandated emissions reporting requirements, creating demand for carbon accounting modules integrated with core policy systems.
Industry Challenges
- Core system migration complexity:Decades of policy data trapped in COBOL-based archives require expensive extraction and normalization before cloud migration.
- Algorithmic bias audits:Regulators in Germany and France now demand documented fairness testing for pricing models, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insurance Software Market |
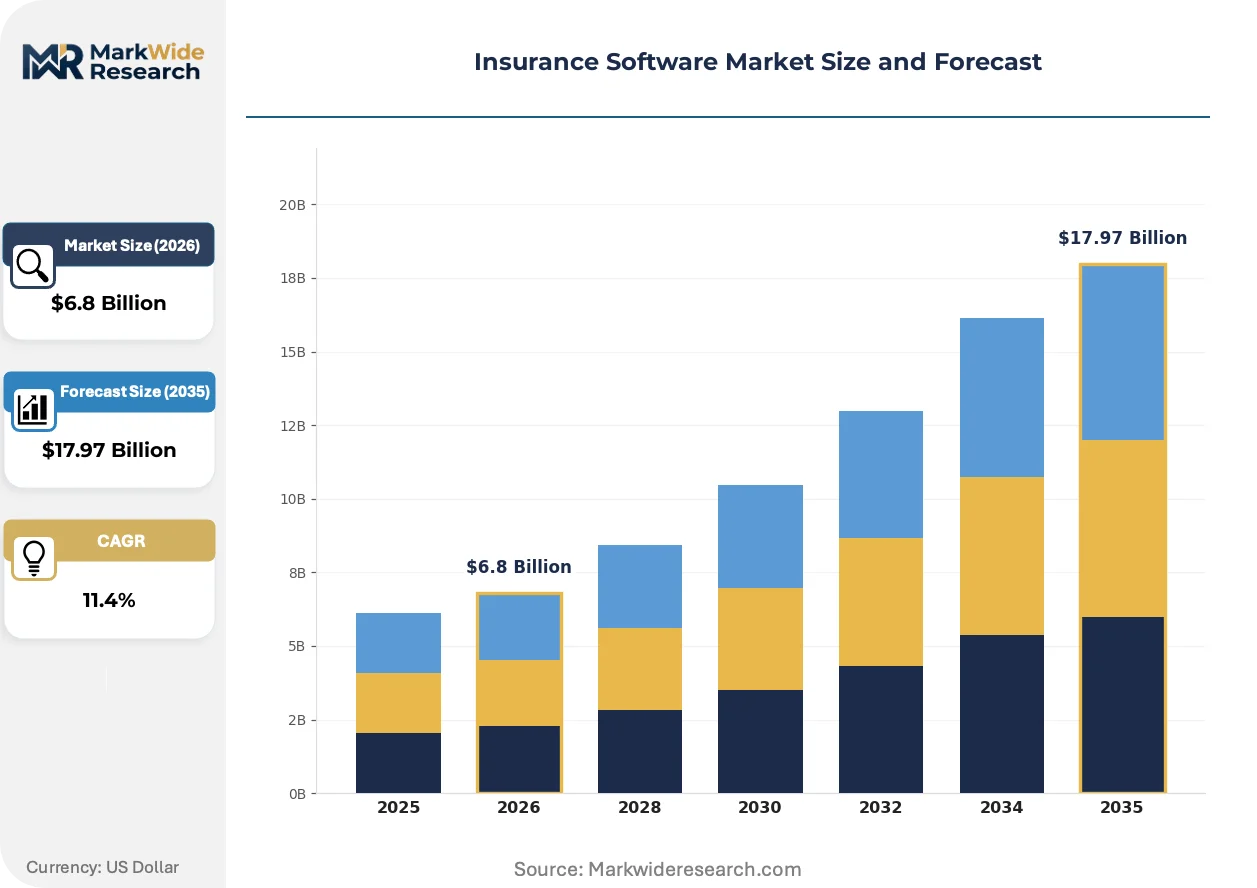
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Policy Management, Claims Processing, Billing, Underwriting Deployment: On-premise, Cloud-based, Hybrid, SaaS End User: Insurance Companies, Brokers, Agents, Third-party Administrators Solution: Claims Management, Risk Assessment, Customer Engagement, Compliance Management |
| Companies Covered | Salesforce, Microsoft, Guidewire, SAP, Oracle, Roper Technologies, Google, Sapiens, Vertafore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insurance Software Market Strategic Shifts & Innovations
Generative AI is penetrating insurance workflows through document ingestion, customer interaction, and code generation, though regulatory uncertainty constrains deployment velocity in regulated jurisdictions.
Low-code configuration layers are rendering obsolete the traditional professional services dependency for policy product launches. Regional carriers in the United States and United Kingdom are adopting these tools to compress product development cycles from quarters to weeks. The structural consequence is margin compression for implementation-heavy vendors.
The EU AI Act's risk-tier framework is reshaping vendor liability structures. Automated underwriting systems fall under "high-risk" classification, obligating providers to maintain quality management systems and human oversight protocols. European carriers are responding by bifurcating procurement between compliant EU vendors and restricted non-EU alternatives.
Subscription pricing for core systems is displacing perpetual license models among mid-market carriers. This shift transfers balance-sheet risk from buyer to vendor while locking carriers into long-term relationships. The transformation is most visible in Germany and the United Kingdom, where private equity-backed carriers prioritize predictable operating expenditure profiles.
Insurance Software Market Segmentation
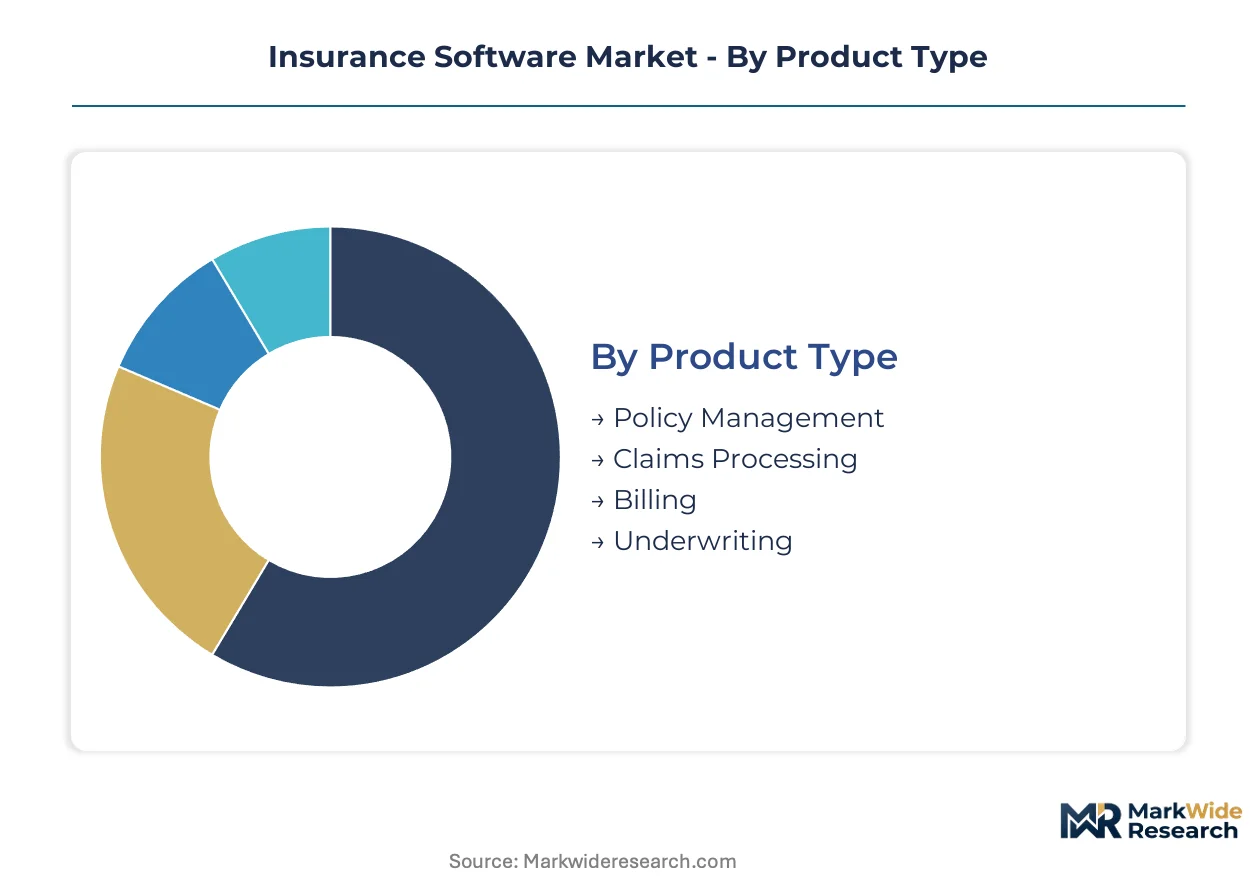
Insurance software procurement patterns diverge sharply across carrier size, regulatory exposure, and technical debt levels. Segment-level analysis reveals where vendor consolidation concentrates and which deployment models capture modernization budgets.
Product Type:
Application focus determines implementation complexity and integration architecture for carrier IT roadmaps.
- Policy Management:Core administration engines handle product configuration, lifecycle transactions, and document generation through rules-based workflows. Large multi-line carriers in Germany and the United States prioritize these systems for COBOL migration projects, though data normalization extends deployment timelines.
- Claims Processing:Intelligent adjudication platforms apply machine-learning models to first-notice-of-loss triage, reserve estimation, and fraud detection. Property and casualty carriers facing loss-cost pressure in catastrophe-exposed US states are redirecting capital toward these tools.
- Billing:Premium collection modules integrate payment gateways, commission accounting, and regulatory reporting. Mid-tier carriers favor these for SaaS conversion.
- Underwriting:Risk selection engines combine external data ingestion with pricing algorithms. EU AI Act compliance requirements are reshaping vendor selection criteria for European deployments.
Policy Management commands the established base. The steepest expansion runs through Claims Processing.
Deployment:
Infrastructure choice reflects carrier scale, customization requirements, and balance-sheet preferences for capital versus operating expenditure.
- Cloud-based:Hyperscale deployments on AWS, Azure, or GCP eliminate data center obligations while introducing egress cost volatility. United Kingdom carriers with private equity ownership are migrating fastest to compress IT capital intensity.
- SaaS:Multi-tenant subscriptions transfer implementation risk to vendors and lock carriers into recurring relationships. Mid-market property and casualty insurers across US state markets are converting perpetual licenses to these models for predictability.
- On-premise:Dedicated infrastructure persists among large commercial lines carriers with complex product configurations and regulatory data residency requirements.
- Hybrid:Split architectures maintain sensitive core data on-premise while extending customer-facing layers to cloud. German carriers navigating GDPR and EU AI Act obligations favor this approach.
On-premise retains the legacy footprint. Cloud-based deployments are gaining share fastest.
End User:
Organizational role shapes functional requirements, integration depth, and procurement authority within insurance distribution chains.
- Insurance Companies:Carriers demand end-to-end core systems with actuarial integration and regulatory reporting modules. Direct writers in the United States and United Kingdom dominate enterprise software procurement.
- Brokers:Intermediaries require comparative rating platforms and policy administration tools for multi-carrier placement. Independent broker networks in Germany are consolidating vendor relationships.
- Agents:Captive and independent agents utilize lightweight CRM-native policy servicing with mobile accessibility. US state-level agency networks drive volume for these solutions.
- Third-party Administrators:TPAs handling claims for self-insured employers need specialized adjudication and cost containment modules.
Insurance Companies anchor enterprise spending. Third-party Administrators are expanding procurement most quickly.
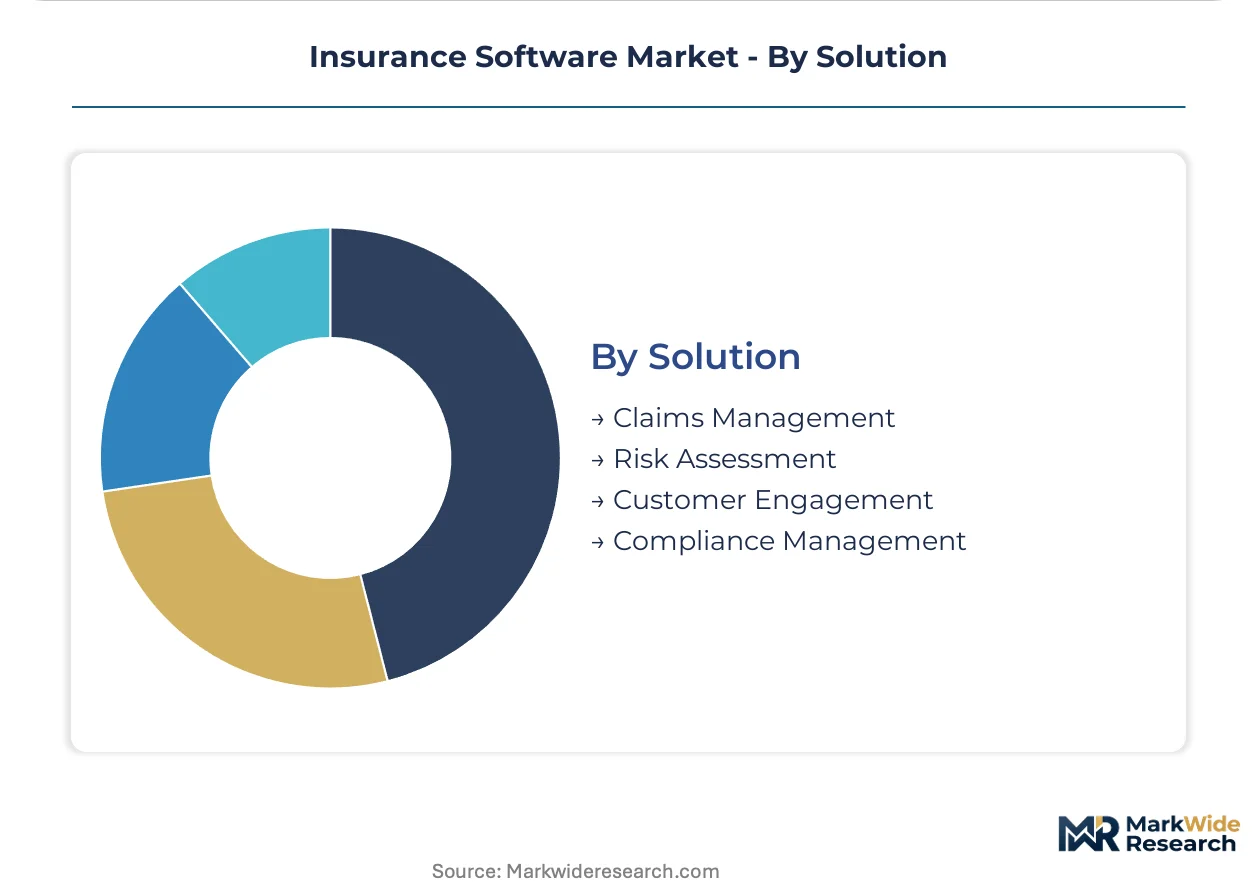
Solution:
Functional modules address specific operational pain points rather than monolithic replacement, allowing phased modernization.
- Claims Management:Comprehensive platforms span intake, investigation, settlement, and recovery workflows with litigation management. US carriers facing social inflation in liability lines are prioritizing these investments.
- Compliance Management:Regulatory engines automate NAIC model law adherence, EU AI Act documentation, and climate disclosure reporting. European jurisdictions are mandating these capabilities for automated underwriting systems.
- Risk Assessment:Data aggregation tools combine telematics, satellite imagery, and third-party databases for pricing refinement.
- Customer Engagement:Policyholder portals and communication platforms integrate with CRM systems for retention and cross-sell.
Claims Management holds the revenue concentration. Compliance Management is climbing the fastest as regulatory deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Insurance software trade flows reveal a pronounced import dependency in emerging markets, while the United States, United Kingdom, and Germany generate substantial export revenues through vendor licensing and SaaS subscriptions. Capital outflows from Asian carriers to North American and European software providers dominate cross-border procurement patterns.
United States
Property and casualty carriers in Florida and Texas are replacing legacy COBOL cores with cloud-native platforms following hurricane-season loss-cost pressures. State insurance commissioners enforce NAIC model laws on algorithmic fairness that complicate multi-state deployments. The Hartford insurance cluster in Connecticut anchors enterprise software R&D, with carriers there piloting AI-driven underwriting systems.
United Kingdom
London Market syndicates and private equity-backed carriers are compressing IT capital intensity through SaaS conversions. The Financial Conduct Authority's operational resilience requirements mandate 48-hour recovery capabilities that favor cloud-based policy administration. The City of London concentration drives demand for specialty lines software handling complex international risks.
Germany
Industrial insurers in Munich and reinsurance hubs are navigating GDPR and EU AI Act obligations through hybrid deployment architectures. The Federal Financial Supervisory Authority requires documented fairness testing for automated pricing models. The Baden-Württemberg automotive insurance corridor is integrating telematics platforms with manufacturing supply chains.
Japan
Domestic non-life carriers are importing claims management modules from US and European vendors amid actuarial talent shortages. METI's guidelines on AI utilization in financial services impose governance frameworks on automated underwriting. Tokyo's Marunouchi district concentrates vendor implementation partnerships for core system modernization.
India
General insurers are licensing cloud-based policy engines from foreign providers while building captive development centers for customization layers. IRDAI's sandbox regulations permit limited pilot deployments of algorithmic underwriting before full compliance certification. The Hyderabad-Gurgaon corridor houses delivery centers serving APAC carriers with cost-optimized implementation services.
Insurance Software Market Key Industry Players
On the supply side, the industry is consolidating around three distinct capability tiers: ERP-integrated suites, core system specialists, and customer engagement platforms. Incumbents with decades of policy data migration expertise command premium positioning in large commercial lines. Strategic moves concentrate on API ecosystem expansion and vertical capability acquisition to capture embedded insurance distribution channels.
Within the enterprise software tier, Salesforce and Microsoft exemplify platform-native entrants leveraging existing CRM and cloud infrastructure relationships to displace point solutions. SAP occupies a position bridging ERP workflows with insurance-specific modules. Guidewire anchors the pure-play core systems archetype, representing vendors whose entire capability stack targets property and casualty replacement cycles.
| Leading Market Players |
|---|
| Salesforce |
| Microsoft |
| Guidewire |
| SAP |
| Oracle |
| Roper Technologies |
| Sapiens |
| Vertafore |
| Others |
Cost & Logistics Intelligence
The Hyderabad-Gurgaon corridor concentrates implementation capacity for insurance software customization, with delivery center density translating directly into pricing leverage for mid-tier carriers negotiating SaaS conversions. This geographic concentration of engineering talent compresses implementation quotes while hyperscale cloud infrastructure costs introduce volatility into total cost of ownership calculations.
Pricing Analysis
Industrial OEM buyers anchor subscription-tiered pricing across deployment models. SaaS subscriptions stratify across premium, standard, and economy tiers based on customization depth and regulatory module inclusion. Cost compression in the standard tier intensifies because low-code configuration tools reduce professional services dependency. Mid-tier carriers exhibit highest price sensitivity, while large commercial lines carriers prioritize compliance architecture over unit economics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities now structure vendor-carrier relationships as SaaS models transfer implementation risk. Software development draws from India, Ireland, and Poland for engineering talent, with cloud infrastructure resting on AWS, Azure, and GCP hyperscale facilities. Single-source vulnerability concentrates in cloud egress pricing. Distribution runs through direct enterprise sales teams and systems integrator partnerships for complex core replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Insurance software constitutes a defensive-moat market where regulatory entrenchment protects incumbent positions. Switching costs escalate with decades of policy data normalization requirements and compliance certification investments.
For Market Incumbents: Pre-empt low-code disruption by acquiring configuration-layer specialists before margin compression accelerates. Fortify API ecosystem control to capture embedded insurance distribution channels. Prioritize EU AI Act compliance certification as a competitive barrier against non-European alternatives.
For New Entrants and Emerging Players: Build out climate risk modeling capabilities for catastrophe-exposed US state markets where incumbent platforms lack parametric trigger functionality. Target third-party administrator segments with specialized adjudication modules. Pursue channel partnerships with IoT device manufacturers for point-of-transaction policy origination.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue compounding play because SaaS conversion locks carriers into decade-long relationships with predictable expansion revenue. Acquisition target archetype: vertical specialists with regulatory moats in EU jurisdictions or climate risk data assets. Monitor EU AI Act enforcement actions as inflection indicator for vendor consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architecture enables embedded insurance distribution through B2B software partnerships. |
| Acquisition of Specialist Firm | Climate risk modeling targets parametric products for previously uninsurable catastrophe markets. |
| Regulatory Compliance Investment | EU AI Act quality management systems create vendor liability differentiation in European markets. |
| Geographic Expansion | German hybrid deployment expertise addresses GDPR and EU AI Act data residency requirements. |
| Product Launch | Low-code configuration layers compress product development cycles from quarters to weeks for regional carriers. |
Research Approach
Initial hypotheses were tested against primary input from carrier CTOs, insurance software procurement officers, systems integration specialists, and regulatory compliance leads and refined through secondary validation. Sources included NAIC model law filings, EU AI Act implementation guidance, SEC 10-K disclosures from listed software vendors, and hyperscaler capex reports. Bottom-up carrier spending analysis triangulated against top-down vendor revenue aggregation.
Demand-supply balance framing anchored the projection framework across the analysis window. Segmentation dimensions encompassed deployment model, carrier size tier, regulatory jurisdiction cluster, and integration complexity level. CAGRs derived from carrier IT budget growth trajectories and vendor booking patterns. Forecast inputs incorporated cloud migration velocity indicators and compliance deadline schedules.
Practitioners should monitor EU AI Act enforcement timing and US state regulatory divergence for early signals of vendor consolidation acceleration. Forecasts reflect assumptions on carrier modernization urgency and cloud cost trajectory stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Global Insurance Telematics Market
Insurance Technology
P and C Insurance Software Market
Insurance Technology
North America Insurance Telematics Market
Insurance Technology
Europe Insurance Telematics Market
Insurance Technology
Global Blockchain in Insurance Market
Insurance Technology
Singapore Insurtech Market
Insurance Technology
Latin America AI in Insurance Market
Insurance Technology
Asia-Pacific P&C Insurance Software Market
Insurance Technology
Europe Insurtech Market
Insurance Technology
Global Commercial Insurance Software Market
Insurance Technology
North America Insurtech Market
Insurance Technology
Japan AI in Insurance Market
Insurance Technology
Insurtech Market
Insurance Technology
Middle East and Africa Insurtech Market
Insurance Technology
United States Insurtech Market
Insurance Technology
Insurance Fraud Detection Market