
 Middle East and Africa MEMS and Sensors Market | 2026-2036
Middle East and Africa MEMS and Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa MEMS and Sensors Market Foresight
Automotive fleet operators are unwinding their historical reliance on aftermarket sensor suppliers and shifting procurement toward tier-one integrated modules. STMicroelectronics leverages its captive foundry capacity to anchor supply contracts with Gulf-based OEMs. Robert Bosch GmbH sustains dominance in pressure sensor modules through backward integration into wafer-level packaging. NXP Semiconductors differentiates via automotive-grade gyroscope portfolios calibrated for desert climate extremes.
Middle East and Africa MEMS and Sensors comprise microelectromechanical systems fabricated through silicon micromachining, bulk etching, and surface micromachination processes, converting physical stimuli into electrical signals for measurement and control functions. These devices typically operate across temperature ranges from minus forty to one hundred twenty-five degrees Celsius and achieve resolution thresholds measured in milli-g for accelerometers and degrees per hour for gyroscopes. Pressure sensors and accelerometers occupy the largest revenue share, driven by automotive safety mandates and industrial vibration monitoring, while optical sensors represent the fastest-expanding category due to smartphone camera stabilization and LiDAR prototyping in UAE autonomous vehicle trials. MEMS accelerometers compete with capacitive sensing architectures in wearable device applications, where power consumption below one hundred microamps determines design wins.
South Africa's National Regulator for Compulsory Specifications and the UAE's Telecommunications and Digital Government Regulatory Authority enforce electromagnetic compatibility and safety standards that filter non-compliant sensor imports, tightening market access for uncertified suppliers. Saudi Arabia's Saudi Standards, Metrology and Quality Organization aligns with EU RoHS restrictions on hazardous substances in electronic components, compelling manufacturers to reformulate packaging materials. Stakeholders must monitor how Gulf Cooperation Council harmonization of technical regulations reshapes certification burdens and whether local content requirements in Saudi Vision 2030 industrial zones redirect supply chain geography.
Market Dynamics
Automotive OEMs in the Gulf states and South Africa are consolidating sensor procurement around tier-one integrated module suppliers, compressing the aftermarket channel and rewiring supplier qualification protocols across the region.
Growth Catalysts
- ADAS Mandates:South Africa's National Regulator for Compulsory Specifications enforces stricter automotive safety standards, compelling OEMs to source higher-grade inertial measurement units for vehicle stability control.
- Smart City Infrastructure:Dubai's environmental monitoring and traffic management networks absorb substantial MEMS volumes, creating dedicated demand streams for pressure and optical sensors.
- Desert Climate Calibration:Automotive-grade gyroscopes calibrated for temperature extremes from minus forty to one hundred twenty-five degrees Celsius unlock fleet deployment across Saudi Arabia and UAE logistics corridors.
Market Restraints
- Input Material Concentration:Specialty silicon wafers and rare earth elements for magnetometers concentrate supply risk with East Asian foundries, exposing regional assemblers to price volatility.
- Regulatory Fragmentation:Divergent electromagnetic compatibility standards between South Africa's NRCS and UAE's TDRA force manufacturers to maintain multiple certification tracks, inflating compliance overhead.
- Technical Performance Ceiling:Capacitive sensing architectures in wearables constrain MEMS accelerometer design wins where power budgets must stay below one hundred microamps.
Strategic Opportunities
- LiDAR Prototyping:UAE autonomous vehicle trials are prototyping optical MEMS arrays for LiDAR systems, opening a high-value application segment beyond traditional automotive safety.
- Saudi Industrial Zones:Local content requirements under Saudi Vision 2030 redirect supply chain geography toward in-country packaging and testing facilities.
- Industrial Vibration Monitoring:Mining and oil & gas operations across Nigeria and Angola present underpenetrated demand for ruggedized pressure sensors and accelerometers.
Industry Challenges
- Certification Timeline Compression:Gulf Cooperation Council harmonization of technical regulations is accelerating compliance deadlines, straining testing laboratory capacity.
- Skill Scarcity in Wafer-Level Packaging:Regional universities produce limited graduates trained in bulk etching and surface micromachination processes, forcing manufacturers to import specialized technicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa MEMS and Sensors Market |
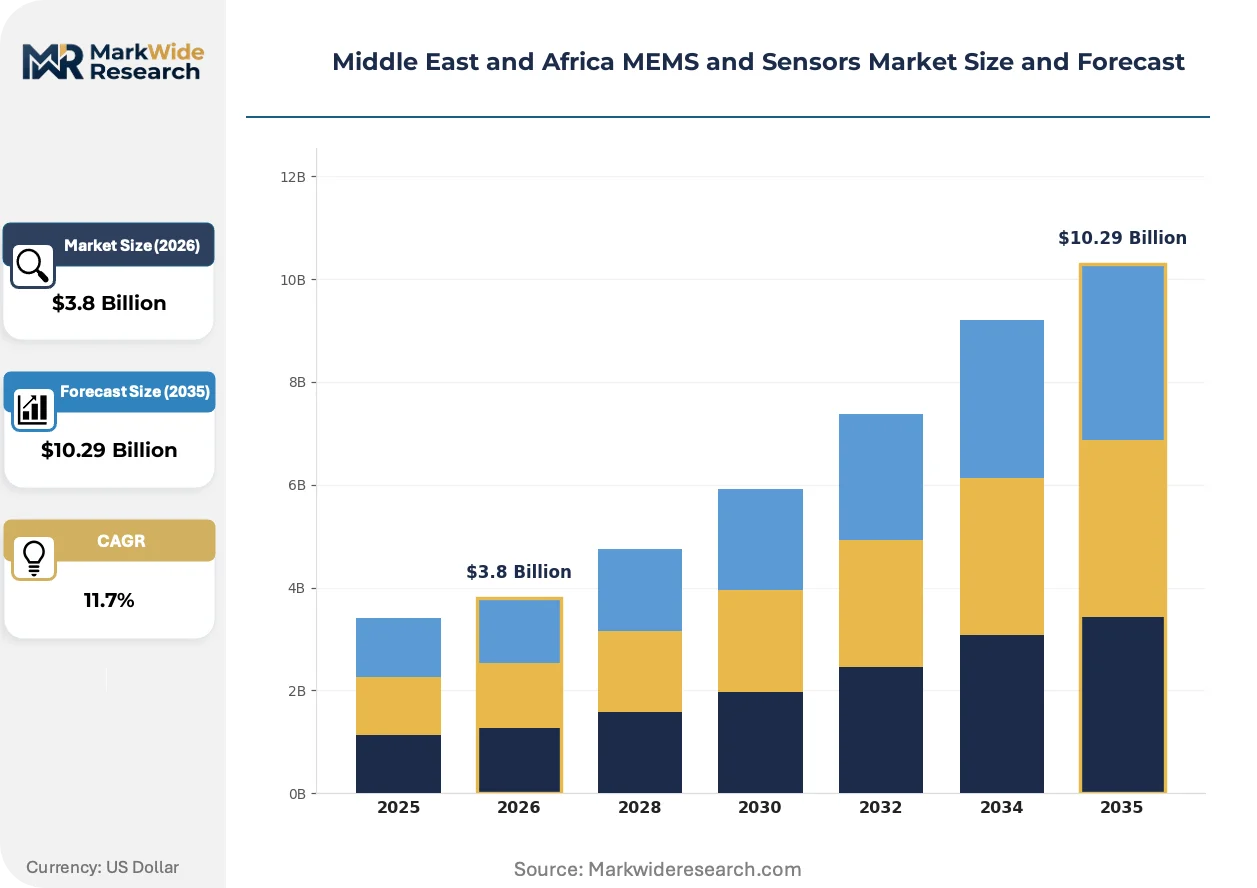
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensors, Accelerometers, Gyroscopes, Optical Sensors Technology: Microfabrication, MEMS Accelerometers, Capacitive Sensors, Thermal Sensors End User: Automotive, Consumer Electronics, Healthcare, Industrial Automation Application: Navigation Systems, Environmental Monitoring, Industrial Controls, Wearable Devices |
| Companies Covered | STMicroelectronics, Analog Devices, Robert Bosch GmbH, Invensense, Murata Manufacturing, Infineon Technologies, Honeywell International, Texas Instruments, NXP Semiconductors, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa MEMS and Sensors Market Shifts & Advancements
Sensor architectures are splitting between commodity volume plays and precision-grade specialization, while regulatory alignment and procurement consolidation reshape how value flows through Middle East and Africa supply chains.
Silicon photonics is bifurcating the optical sensor category. These devices convert light into electrical signals for LiDAR and camera stabilization. UAE autonomous vehicle developers and smartphone manufacturers are adopting hybrid silicon-photonic MEMS at accelerated procurement cycles. The technology is bifurcating supplier tiers into precision-grade specialists and commodity assemblers, compressing margins for undifferentiated players.
Saudi Standards, Metrology and Quality Organization alignment with EU RoHS restrictions on hazardous substances is reformulating packaging material compositions across the supply base. Manufacturers must eliminate lead and cadmium from sensor housings and solder joints. Automotive and industrial sensor modules destined for Saudi Arabia and re-export markets face the steepest material substitution costs.
Fleet operators are unwinding historical reliance on aftermarket sensor suppliers and contracting directly with tier-one integrated module vendors. This channel compression bypasses traditional distribution layers in South Africa and Nigeria. The shift is most visible in heavy-duty trucking and mining vehicle segments, where uptime guarantees now bundle sensor replacement into total cost of ownership contracts.
Middle East and Africa MEMS and Sensors Market Segmentation
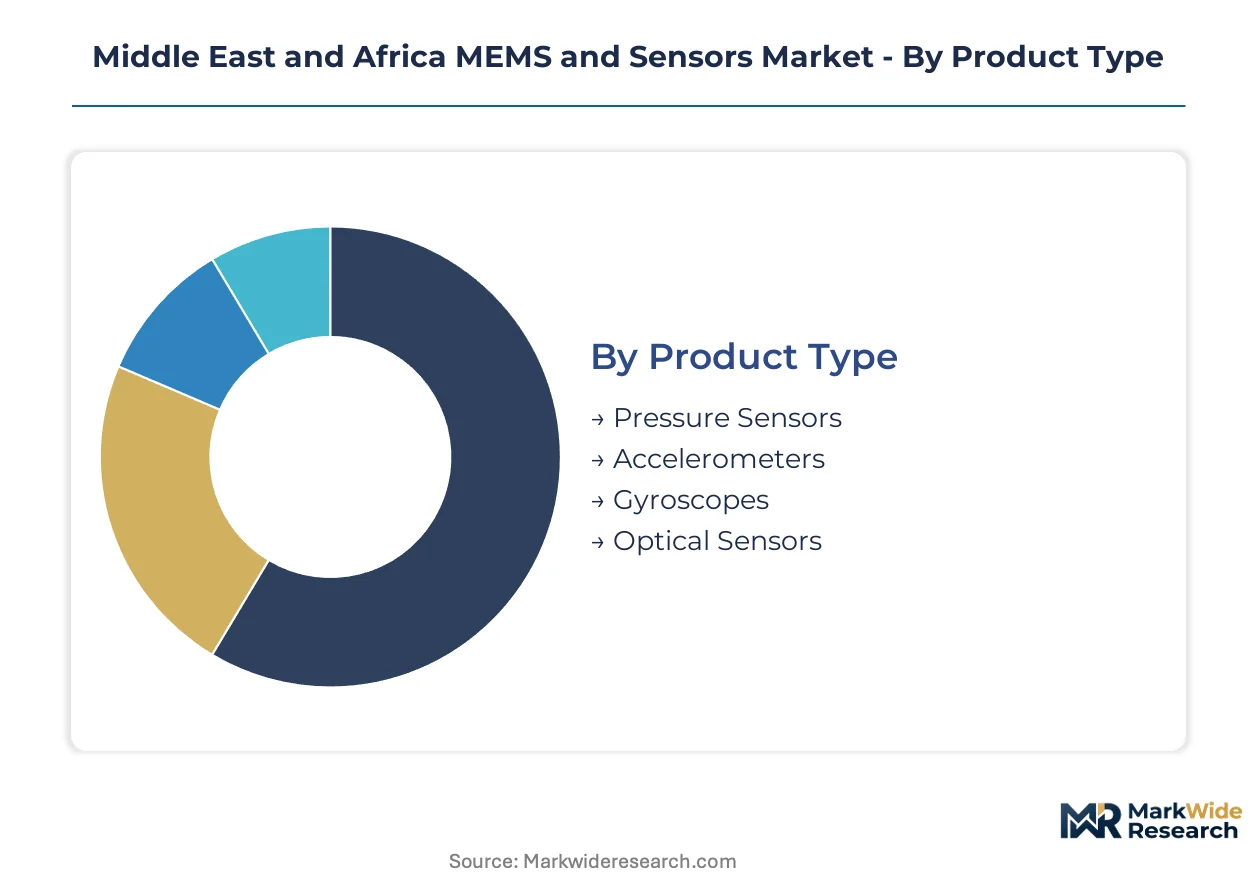
MEMS and Sensors segmentation in the Middle East and Africa reflects divergent certification requirements across South Africa's NRCS and UAE's TDRA, with product specifications calibrated for desert climate extremes and automotive safety mandates reshaping procurement patterns.
Product Type:
South Africa's National Regulator for Compulsory Specifications enforces distinct performance grades for automotive safety applications, while Dubai's smart city procurement specifications prioritize environmental monitoring accuracy.
- Pressure Sensors:These devices measure fluid or gas pressure through piezoresistive or capacitive transduction mechanisms, achieving resolution thresholds critical for vehicle stability systems. Demand concentrates in Gulf state automotive OEMs sourcing modules for advanced driver-assistance systems under tightening NRCS safety mandates. Pressure sensors handle the majority of throughput; optical sensors are gaining share fastest.
- Accelerometers:MEMS accelerometers detect linear acceleration via capacitive sensing architectures or piezoelectric elements, operating across temperature ranges from minus forty to one hundred twenty-five degrees Celsius. Fleet operators in Saudi Arabia and UAE logistics corridors procure desert-calibrated units for vehicle dynamics control, displacing aftermarket suppliers with tier-one integrated modules.
- Gyroscopes:Automotive-grade gyroscopes from NXP Semiconductors and STMicroelectronics provide angular rate measurement for electronic stability control.
- Optical Sensors:Silicon photonic MEMS arrays for LiDAR prototyping in UAE autonomous vehicle trials represent the fastest-expanding revenue category.
Pressure sensors dominate automotive procurement volumes; optical sensors climb the fastest on application expansion beyond traditional safety systems.
Technology:
Cost tier differentiation separates captive foundry production from fabless assembly, with wafer-level packaging economics determining regional manufacturing feasibility.
- Microfabrication:Bulk etching and surface micromachination processes fabricate silicon structures with micron-scale precision for transduction elements. South African universities produce limited graduates trained in these processes, forcing manufacturers to import specialized technicians and compressing local value capture.
- MEMS Accelerometers:These devices integrate proof masses, springs, and capacitive plates on single silicon dies, converting mechanical acceleration into electrical signals. Robert Bosch GmbH sustains dominance through backward integration into wafer-level packaging, anchoring supply contracts with Gulf-based OEMs seeking guaranteed uptime.
- Capacitive Sensors:Low-power architectures consuming below one hundred microamps compete with MEMS in wearable device design wins.
- Thermal Sensors:Temperature-compensated designs address industrial vibration monitoring in Nigerian and Angolan mining operations.
MEMS accelerometers command premium pricing in automotive; capacitive sensors expand most quickly in consumer power-constrained applications.
End User:
Customer procurement consolidation favors tier-one integrated module suppliers over fragmented aftermarket channels, with total cost of ownership contracts bundling sensor replacement in heavy-duty segments.
- Automotive:OEMs in South Africa and Gulf states source higher-grade inertial measurement units for vehicle stability control under NRCS enforcement, unwinding historical reliance on aftermarket suppliers. Dubai's environmental monitoring networks and Saudi logistics corridors absorb substantial calibrated gyroscope volumes.
- Consumer Electronics:Smartphone camera stabilization drives optical MEMS procurement from UAE and Saudi distribution channels.
- Healthcare:Wearable diagnostic devices require power consumption below one hundred microamps, constraining MEMS design wins.
- Industrial Automation:Ruggedized pressure sensors and accelerometers serve underpenetrated mining and oil & gas operations across Nigeria and Angola.
Automotive generates the dominant revenue share; industrial automation shows the steepest expansion trajectory on infrastructure investment.
Application:
Geography determines deployment priority, with UAE autonomous vehicle trials and Dubai smart city infrastructure creating dedicated demand streams distinct from South African automotive mandates.
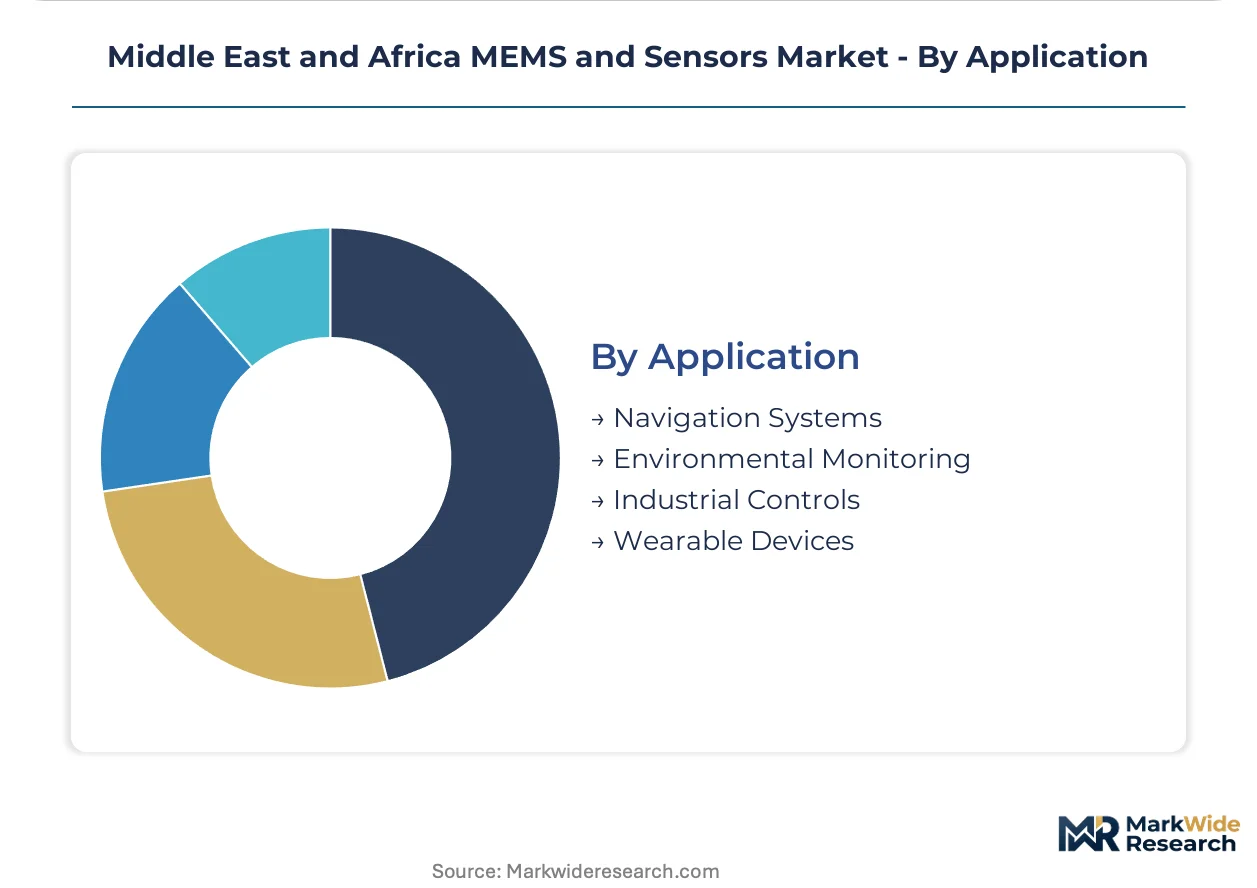
- Navigation Systems:Inertial measurement units combining accelerometers and gyroscopes provide dead reckoning capability for GPS-denied environments. Saudi Arabia and UAE logistics corridors deploy desert-calibrated automotive-grade units, with temperature stability from minus forty to one hundred twenty-five degrees Celsius unlocking fleet deployment.
- Environmental Monitoring:Pressure and optical sensor networks track air quality, humidity, and particulate levels across Dubai's urban sensor grids. Procurement concentrates in smart city infrastructure projects absorbing substantial MEMS volumes through government-backed deployment schedules.
- Industrial Controls:Vibration monitoring systems in Nigerian mining and Angolan oil & gas operations present underpenetrated demand for ruggedized accelerometers.
- Wearable Devices:Power budgets below one hundred microamps constrain MEMS accelerometer adoption against capacitive alternatives.
Environmental monitoring handles the majority of non-automotive throughput; navigation systems are expanding most quickly on logistics fleet modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South African automotive assemblers export sensor-integrated modules to logistics operators across Sub-Saharan Africa, while UAE-based distributors channel Gulf-sourced components into North African electronics manufacturing.
United Arab Emirates
Dubai's smart city infrastructure absorbs substantial MEMS volumes through environmental monitoring and traffic management networks. The Telecommunications and Digital Government Regulatory Authority enforces electromagnetic compatibility standards that filter non-compliant sensor imports. Abu Dhabi's industrial zones host packaging facilities serving Saudi and Kuwaiti automotive OEMs.
Saudi Arabia
Logistics corridors along the Riyadh-Dammam axis deploy desert-calibrated gyroscopes for fleet management and autonomous vehicle prototyping. The Saudi Standards, Metrology and Quality Organization aligns with EU RoHS restrictions, compelling manufacturers to reformulate packaging materials. NEOM's northwest development zone prototypes optical MEMS arrays for LiDAR systems.
South Africa
Automotive OEMs in Gauteng and the Eastern Cape source higher-grade inertial measurement units under National Regulator for Compulsory Specifications enforcement. The NRCS mandates stricter vehicle stability control standards, compressing aftermarket supplier channels. Port Elizabeth's vehicle assembly clusters integrate calibrated sensors for export to Sub-Saharan markets.
Nigeria
Mining operations in the Niger Delta and northern solid minerals belt present underpenetrated demand for ruggedized pressure sensors and accelerometers. The country's national standards body enforces industrial safety regulations for vibration monitoring equipment. Lagos-based distributors serve as the primary import channel for European and Asian sensor modules.
Israel
Defense and aerospace contractors in Haifa and the Tel Aviv corridor procure precision-grade gyroscopes for navigation systems. The national telecom regulator maintains strict electromagnetic compatibility certification for military-grade components. Jerusalem's technology clusters spin out MEMS startups targeting medical and industrial automation applications.
Middle East and Africa MEMS and Sensors Market Competitive Landscape
Listed leaders compete with private specialists across foundry capacity and module integration depth, creating a tiered structure where scale advantages concentrate with captive silicon producers. The vendor base splits between integrated device manufacturers owning wafer fabrication and fabless designers reliant on contract foundries. Three archetypes dominate: foundry-anchored module suppliers, precision-grade specialists, and commodity assemblers. Competitive moves center on backward integration into packaging and direct contracting with fleet operators bypassing distribution layers.
Within the foundry-anchored tier, STMicroelectronics and Robert Bosch GmbH exemplify players controlling upstream silicon production. NXP Semiconductors occupies a position among automotive-grade specialists calibrating for extreme temperature environments. These three entities anchor the premium-module segment where Gulf-based OEMs consolidate procurement.
| Leading Market Players |
|---|
| STMicroelectronics |
| Analog Devices |
| Robert Bosch GmbH |
| Invensense |
| Murata Manufacturing |
| Infineon Technologies |
| Honeywell International |
| Texas Instruments |
| NXP Semiconductors |
| Others |
Supply & Pricing Matrix
Captive foundry utilization rates above ninety percent in East Asian silicon fabrication facilities anchor price floors for MEMS accelerometers and gyroscopes across Middle East and Africa procurement channels. Scale concentration among three dominant wafer suppliers compresses margin flexibility for regional assemblers while reinforcing tier-one module vendors' pricing power in Gulf automotive contracts.
Pricing Analysis
Current-generation silicon-photonic optical MEMS command three-to-five-fold premiums over prior-generation piezoresistive pressure sensors, while next-generation LiDAR arrays remain pre-commercial with undefined pricing. Pricing stratifies across automotive-grade, industrial-grade, and consumer-grade certification tiers, with NRCS-compliant modules carrying material premiums over uncertified alternatives. Cost compression in consumer accelerometers is intensifying because capacitive sensing architectures displace MEMS in sub-one-hundred-microamp wearable applications. Fleet operators in Saudi logistics corridors exhibit lowest price sensitivity due to uptime guarantee bundling, while Nigerian mining procurement shows highest sensitivity to unit economics.
Supply Chain Analysis
Strait of Hormuz transit underwrites critical rare earth element flows for magnetometer production feeding UAE and Saudi automotive assembly. Specialty silicon wafers draw from Taiwan, South Korea, and Japan, while MEMS packaging equipment rests on German and Japanese capital goods suppliers. Single-source vulnerability concentrates in photolithography systems, where ASML's EUV monopoly creates irreplaceable chokepoints. Distribution runs through Dubai's Jebel Ali free zone for Gulf state redistribution and Lagos port complexes for West African mining operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Middle East and Africa MEMS and Sensors represents a high-growth disruption as Saudi Vision 2030 local content mandates and UAE autonomous vehicle trials simultaneously reshape demand architecture and procurement geography.
For Market Incumbents: Secure captive foundry capacity allocation through long-term offtake agreements with East Asian wafer suppliers before GCC regulatory harmonization accelerates compliance deadlines. Defend module pricing by embedding desert-calibration services into total cost of ownership contracts, neutralizing emerging fabless competitors lacking temperature-extreme testing infrastructure. For New Entrants and Emerging Players: Differentiate on industrial vibration monitoring specialization for Nigerian and Angolan mining operations, where ruggedized pressure sensor demand remains underserved by tier-one automotive-focused incumbents. Target Abu Dhabi packaging facilities as contract manufacturing anchors to satisfy Saudi local content requirements without full wafer-fab investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tier-one module suppliers bundling sensor replacement into fleet uptime guarantees across Saudi and UAE logistics corridors. Long-term viability favors acquisition targets with backward integration into wafer-level packaging and existing NRCS or TDRA certification portfolios. Watch NEOM LiDAR procurement timelines as inflection indicator for optical MEMS demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | Long-term silicon wafer offtakes with TSMC or GlobalFoundries lock in supply security for Gulf automotive contracts. |
| Desert Calibration Certification | NXP Semiconductors' temperature-extreme gyroscope validation opens Saudi logistics corridor deployment at premium pricing. |
| Local Packaging Facility Establishment | Abu Dhabi industrial zone assembly operations satisfy Saudi Vision 2030 content requirements without full fabrication investment. |
| LiDAR Array Prototyping Partnership | NEOM autonomous vehicle trials create first-mover positioning for silicon-photonic MEMS beyond traditional automotive safety. |
| Industrial Vibration Monitoring Specialization | Ruggedized accelerometer development for Nigerian mining addresses underpenetrated demand outside Gulf automotive concentration. |
Research Methodology
A standing panel of automotive OEM procurement directors, MEMS foundry operations managers, GCC regulatory affairs leads, and industrial automation engineers provided ongoing calibration throughout the study period. Primary interviews with tier-one module suppliers and tier-two aftermarket distributors combined with secondary validation against customs trade data, SEC semiconductor filings, and Saudi Standards, Metrology and Quality Organization regulatory bulletins. Bottom-up unit shipment estimates triangulated against top-down wafer consumption figures from East Asian foundry disclosures.
Consistency checks against IHS Markit vehicle production databases and UAE smart city infrastructure procurement schedules validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, technology generation, end-use industry, application, and regional regulatory cluster dimensions. CAGRs derived from logarithmic trend fitting of historical wafer consumption patterns, adjusted for GCC harmonization timeline acceleration and local content requirement phase-ins.
Material uncertainties — rare earth export restrictions, Strait of Hormuz logistics disruptions, and NRCS-TDRA regulatory divergence — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued East Asian foundry capacity expansion and stable GCC-South Africa trade corridors. Practitioners should keep alternative scenarios live as Saudi industrial zone buildout timelines and EU RoHS alignment enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Middle East and Africa Vibration Sensors Market
Sensors and Controls
United States Smart Sensors Market
Sensors and Controls
Asia-Pacific Thermocouple Temperature Sensors Market
Sensors and Controls
Silicon Photomultiplier (Sipm) Market
Sensors and Controls
Exhaust Sensors for Automotive Market
Sensors and Controls
Tooth Mounted Sensor Market
Sensors and Controls
Europe MEMS and Sensors Market
Sensors and Controls
Americas Sensor Market
Sensors and Controls
Safety Sensors Market
Sensors and Controls
Motorcycle Sensors Market
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
Accelerometer and Gyroscope Market
Sensors and Controls
MEMS for Mobile Devices Market
Sensors and Controls
Asia-Pacific Wireless Brain Sensors Market
Sensors and Controls
Digital Thermohygrometers Market
Sensors and Controls
Odor Detection Equipment Market