
 Europe Thermal Imaging Systems Market | 2026-2036
Europe Thermal Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Thermal Imaging Systems Market Foresight
France is narrowing its dependence on imported infrared cores through domestic cleanroom investments near Paris-Saclay. Teledyne FLIR leverages its vertically integrated foundry network to supply cooled detectors for aerospace programs across the continent. BAE Systems anchors its position through sovereign capability in night-vision integration for British military platforms. Thales Group competes on dual-use technology transfer between its defense and healthcare divisions.
Thermal imaging systems detect infrared radiation emitted by objects and convert it into visible images using microbolometer or photodetector arrays, operating across spectral bands from 7 to 14 micrometers for uncooled variants and 3 to 5 micrometers for cooled indium antimonide sensors. These systems serve industrial predictive maintenance, perimeter security, and clinical fever screening by revealing temperature differentials invisible to standard cameras. Handheld cameras dominate field service deployments due to portability, while fixed camera installations command premium pricing in critical infrastructure protection. Cooled technology leads military and scientific segments where resolution and frame rate justify cryogenic cooling costs, though uncooled modules are displacing legacy systems in commercial building diagnostics.
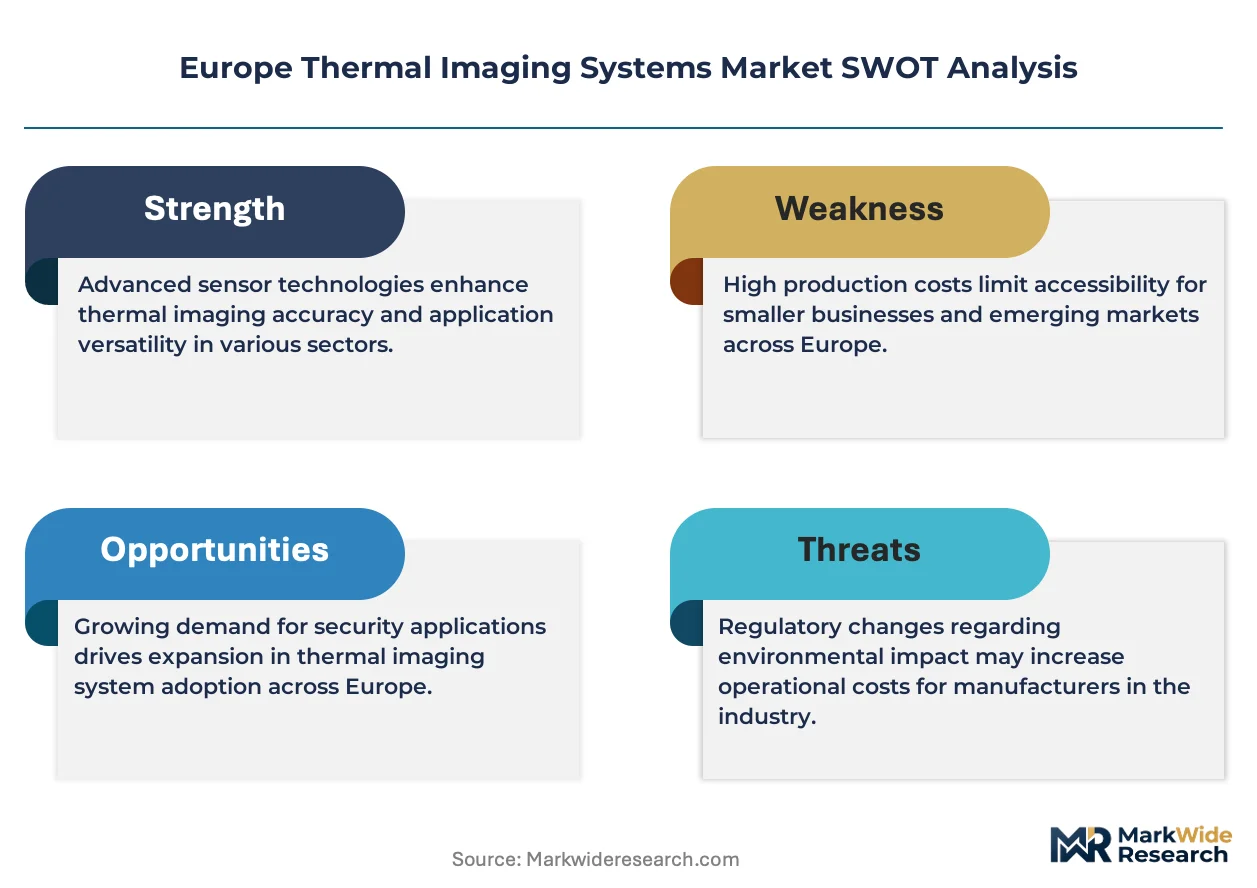
EMA medical device regulations and CE marking under MDR classify clinical thermal imagers as Class IIa devices, mandating thermal accuracy validation and software algorithm transparency for diagnostic claims. The EU AI Act imposes conformity assessments on automated fever-screening algorithms deployed in public venues, reshaping vendor certification roadmaps. REACH restrictions on lead-based solder materials are forcing supply chain transitions to compliant interconnect technologies. Stakeholders must monitor evolving harmonized standards under the EU Green Deal for energy efficiency in portable electronics, as battery-powered handheld units face emerging ecological design requirements.
Market Dynamics
The European thermal imaging market faces structural pressure from the EU AI Act's conformity assessment requirements, which force algorithm transparency for automated fever-screening systems and compress vendor certification timelines.
Growth Catalysts
- Defense Modernization Budgets:France and the United Kingdom sustain cooled infrared procurement for military platforms, with sovereign capability investments driving detector fabrication demand.
- REACH Compliance Transitions:Lead-free solder mandates under ECHA restrictions accelerate supply chain modernization toward compliant interconnect technologies for uncooled modules.
- Industrial Predictive Maintenance:German automotive plants expand uncooled module deployment for thermal inspection of electric vehicle battery assemblies and powertrain components.
Market Restraints
- Cryogenic Cooling Cost Burden:Cooled indium antimonide systems require liquid nitrogen or Stirling engine maintenance, limiting adoption outside defense and scientific budgets.
- CE Marking Timeline Friction:MDR Class IIa certification for medical-grade devices extends validation cycles by 12-18 months versus legacy MDD pathways.
- Uncooled Resolution Ceiling:Microbolometer arrays face fundamental NETD limitations below 50 millikelvin, constraining high-precision clinical diagnostic claims.
Strategic Opportunities
- Eastern European Infrastructure:Poland and Romania present underpenetrated demand for perimeter security systems at critical energy and transport nodes.
- EU Green Deal Efficiency Mandates:Ecological design requirements for battery-powered handheld units create first-mover advantage for low-consumption microbolometer designs.
- Dual-Use Technology Transfer:Defense-derived cooled detector architectures are migrating into high-end medical imaging and semiconductor wafer inspection applications.
Industry Challenges
- Cleanroom Talent Scarcity:Detector fabrication requires specialized vacuum deposition and lithography expertise concentrated in Paris-Saclay and Dresden clusters.
- Algorithm Validation Complexity:Automated fever-screening systems face software transparency requirements under EU AI Act conformity assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Thermal Imaging Systems Market |
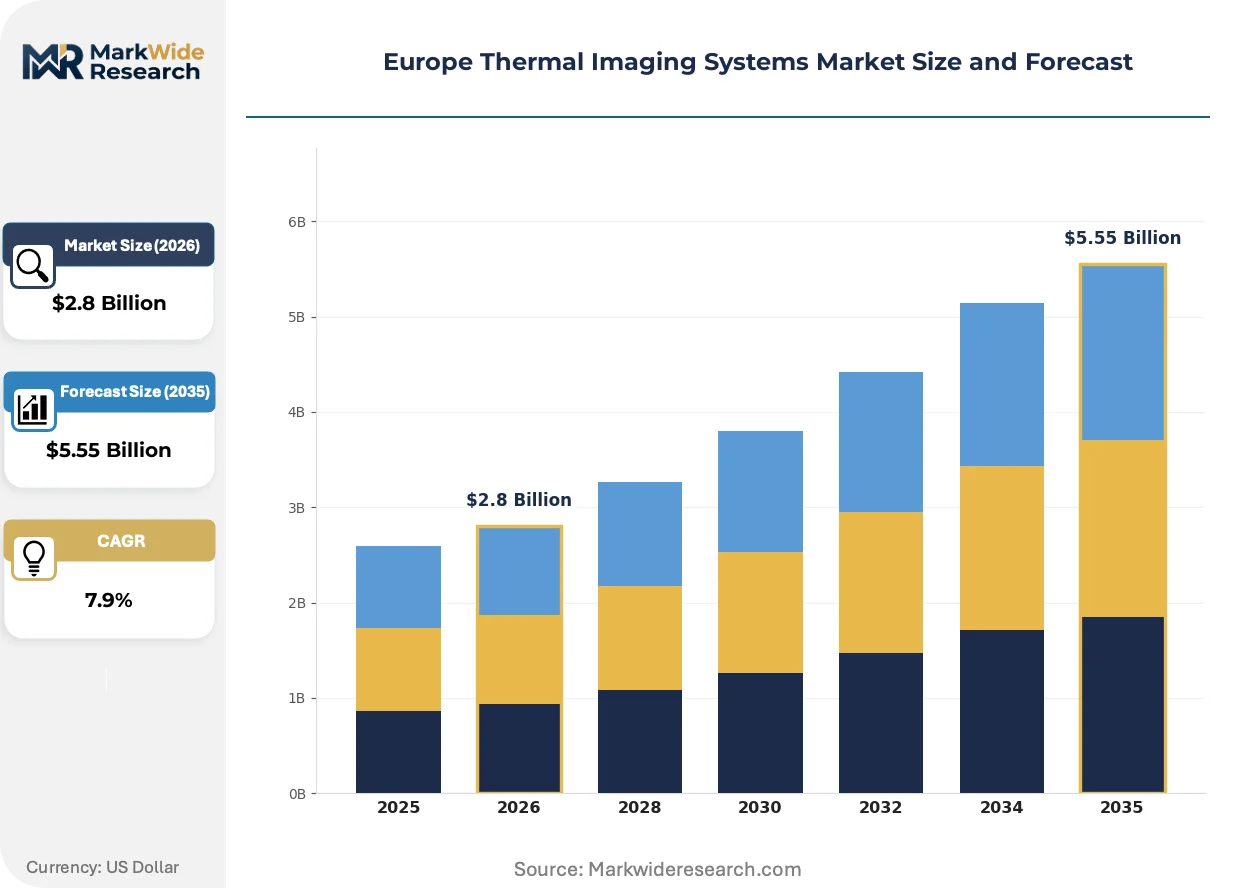
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Cameras, Fixed Cameras, Software, Modules Application: Security, Surveillance, Industrial Inspection, Medical Diagnosis End User: Government, Healthcare, Manufacturing, Aerospace Technology: Uncooled, Cooled, Hybrid, Long-Wave Infrared |
| Companies Covered | Teledyne FLIR, BAE Systems, Testo SE & Co. KGaA, Thales Group, Elbit Systems, RTX, Lockheed Martin, Axis Communications AB, Thermoteknix Systems Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Thermal Imaging Systems Market Shifts & Advancements
Technology trajectories in European thermal imaging center on resolution-cost tradeoff optimization, regulatory-driven algorithm standardization, and procurement model evolution toward integrated service contracts.
Vanadium oxide microbolometers are migrating from amorphous silicon alternatives in building diagnostics applications. Facility managers in Nordic commercial real estate favor the improved thermal stability and lower drift characteristics. This transition is compressing price premiums for uncooled modules in the 640×512 resolution class.
MDR Class IIa device classification mandates thermal accuracy validation and software algorithm transparency for clinical fever-screening claims. EMA-notified bodies now require pixel-level calibration documentation and temperature measurement uncertainty budgets. Medical-grade vendors are restructuring quality management systems to accommodate post-market surveillance obligations.
Integrated service contracts are displacing equipment-only procurement in industrial maintenance segments. German automotive OEMs now specify uptime guarantees and predictive analytics subscriptions alongside hardware delivery. This bundling concentrates in high-volume manufacturing environments where downtime costs exceed capital expenditure considerations.
Europe Thermal Imaging Systems Market Segmentation
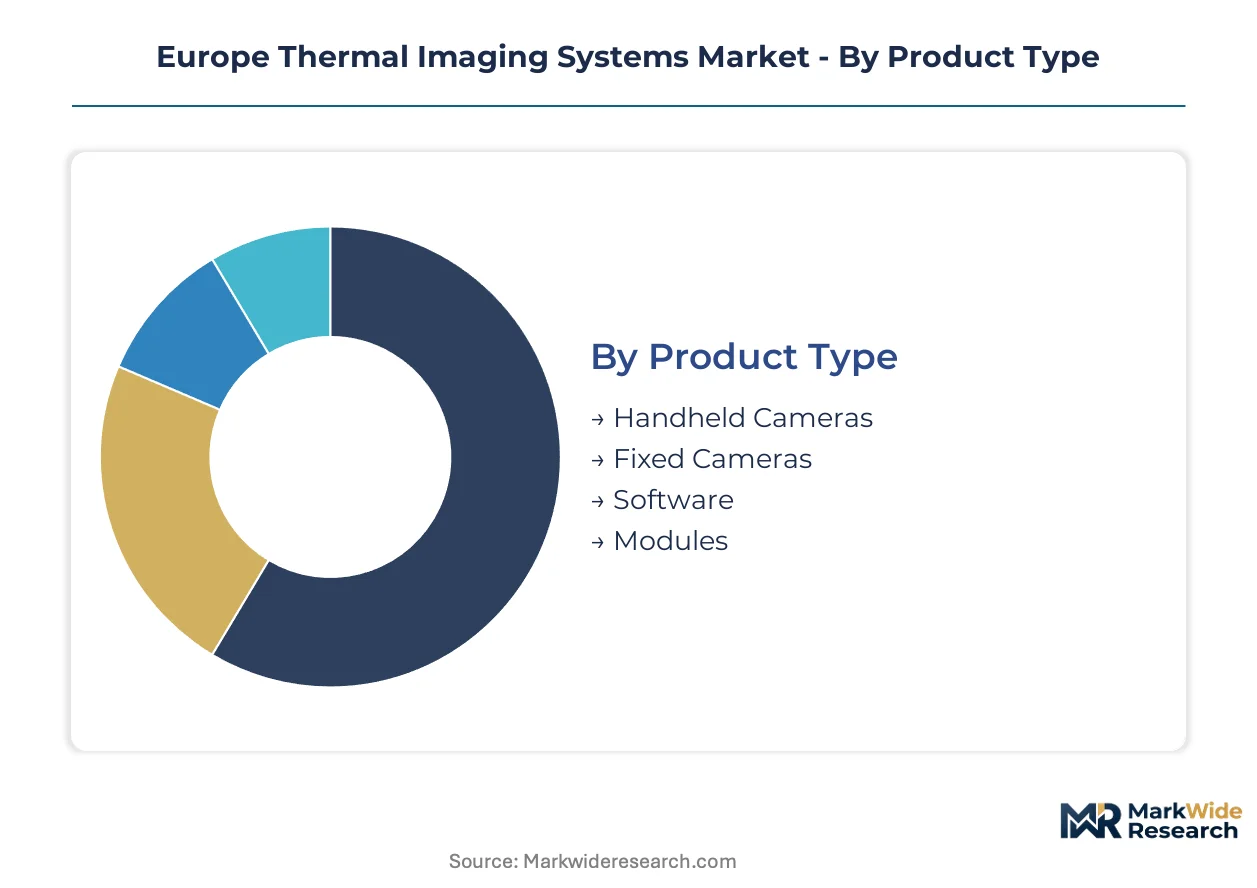
European procurement patterns for thermal imaging systems diverge sharply across product configurations and cooling architectures. End-user requirements in defense, healthcare, and automotive manufacturing create distinct specification thresholds that reshape vendor portfolio priorities.
Product Type:
Cost tier differentiation separates portable field equipment from permanently installed infrastructure, with software and modular components occupying intermediate price-performance positions.
- Handheld Cameras:Battery-powered units with vanadium oxide microbolometer arrays deliver 640×512 resolution for building diagnostics and electrical inspection. German automotive plants deploy these for thermal mapping of electric vehicle battery assemblies during production ramp-up.
- Fixed Cameras:Ruggedized installations with IP66 housings and motorized lenses protect critical infrastructure perimeters. Demand concentrates at Romanian energy transmission nodes and Polish transport hubs where 24-hour monitoring justifies capital expenditure.
- Software:Analytics platforms process radiometric data streams for automated anomaly detection and predictive maintenance scheduling.
- Modules:Uncooled detector cores and optical subassemblies integrate into OEM systems for medical devices and industrial equipment.
Handheld cameras command the established base across European maintenance operations. The steepest expansion runs through fixed camera installations at critical infrastructure sites.
Application:
Use-case maturity spans from commoditized building diagnostics to regulated clinical environments where CE marking under MDR imposes validation burdens.
- Security:Perimeter monitoring systems with video analytics detect human signatures against cluttered backgrounds. French nuclear facilities and British maritime ports specify cooled detectors for extended-range threat identification.
- Surveillance:Law enforcement and border control agencies deploy lightweight uncooled systems for mobile observation. Resolution demands here sit below scientific applications but above commercial building diagnostics.
- Industrial Inspection:Predictive maintenance programs in German automotive and Nordic commercial real estate favor thermal stability and low drift characteristics for electrical panel and HVAC assessment.
- Medical Diagnosis:Fever-screening and clinical thermal imaging face EMA Class IIa device classification with pixel-level calibration documentation requirements. EU AI Act conformity assessments add algorithm transparency obligations for automated screening deployments.
Industrial inspection retains the volume anchor position. Medical diagnosis is climbing the fastest as pandemic-era screening infrastructure converts to permanent clinical installations.
End User:
Customer type determines procurement authority structure and specification stringency, from sovereign defense programs to commercial manufacturing budgets.
- Government:Defense modernization budgets in France and the United Kingdom sustain cooled infrared procurement for military platforms. Sovereign capability investments drive detector fabrication demand near Paris-Saclay.
- Healthcare:Hospital systems and public health authorities procure clinical-grade imagers with thermal accuracy validation and software algorithm transparency. EMA-notified bodies extend validation cycles versus legacy MDD pathways.
- Manufacturing:German automotive OEMs now specify uptime guarantees and predictive analytics subscriptions alongside hardware delivery. This bundling concentrates where downtime costs exceed capital expenditure considerations.
- Aerospace:Satellite and airborne platforms demand cryogenically cooled indium antimonide sensors for resolution and frame rate performance.
Government programs anchor procurement value. Manufacturing sector uptake is expanding most quickly through integrated service contract adoption.
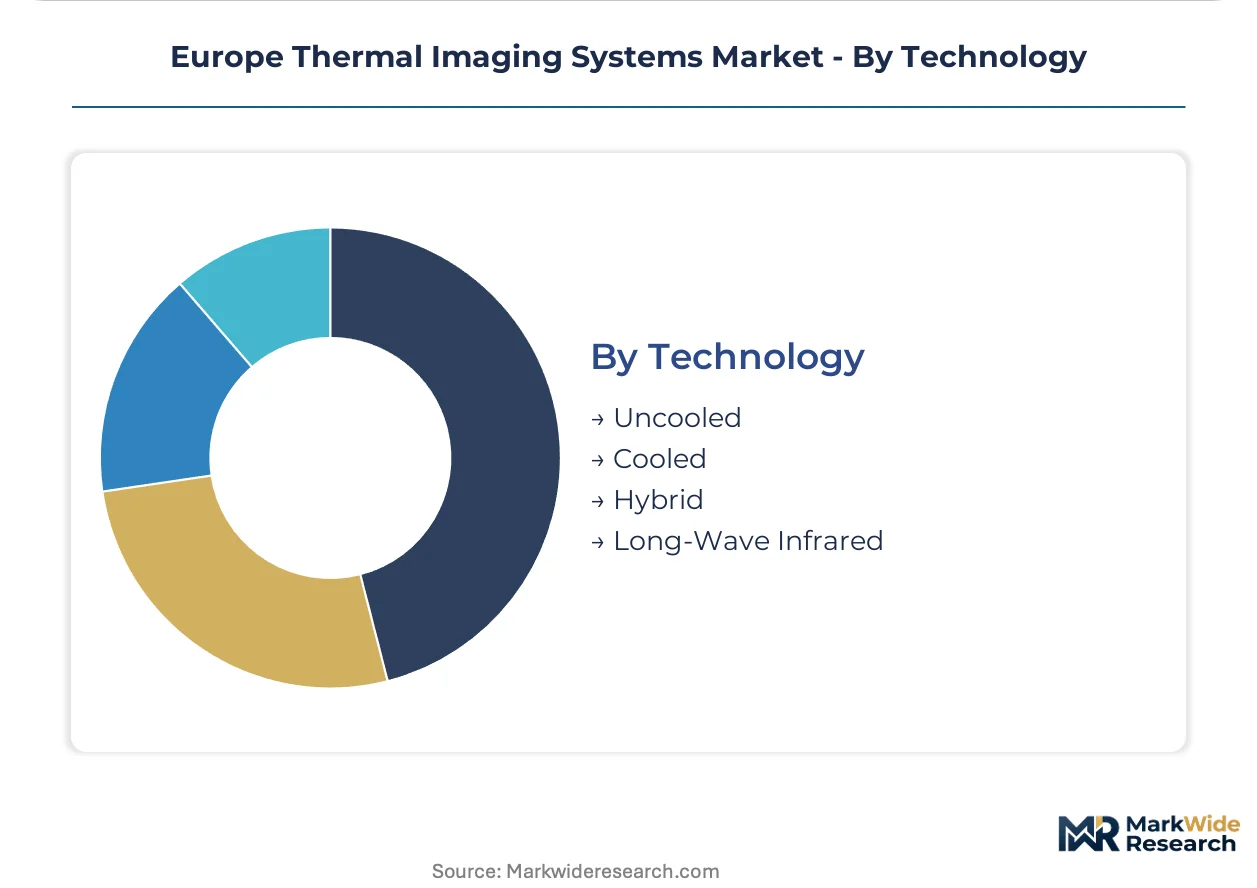
Technology:
Cooling architecture defines performance ceiling and cost floor, with spectral band selection determining atmospheric penetration and target contrast characteristics.
- Uncooled:Vanadium oxide microbolometers operate at ambient temperature with NETD specifications around 50 millikelvin. REACH compliance transitions on lead-free solder mandates accelerate supply chain modernization for these modules.
- Cooled:Indium antimonide photodetectors at cryogenic temperatures achieve sub-25 millikelvin sensitivity for defense and scientific applications. Liquid nitrogen or Stirling engine maintenance limits adoption outside premium budgets.
- Hybrid:Dual-band systems combine uncooled wide-area coverage with cooled narrow-field detail for specialized surveillance scenarios.
- Long-Wave Infrared:7-14 micrometer spectral response dominates uncooled commercial applications for thermal stability in building diagnostics.
Uncooled technology holds the installed base majority. Cooled systems are gaining share fastest in aerospace and defense platforms where resolution requirements justify operational complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Europe diverge sharply between defense-heavy western markets and infrastructure-focused eastern territories. France and the United Kingdom prioritize cooled detector procurement for military platforms, while Germany and the Nordic states concentrate spending on industrial predictive maintenance. Southern and eastern European markets emphasize perimeter security installations at critical energy nodes.
Germany
German automotive OEMs drive uncooled module demand for electric vehicle battery assembly inspection and powertrain thermal mapping. KBA vehicle safety standards intersect with REACH compliance timelines to accelerate lead-free solder transitions in detector packaging. Stuttgart and Munich manufacturing clusters anchor procurement through integrated service contracts bundling hardware with predictive analytics subscriptions.
France
Sovereign defense programs sustain cooled infrared procurement for aerospace and night-vision platforms, with domestic fabrication investments reducing import dependence. ANSM medical device oversight and EU AI Act conformity assessments reshape clinical thermal imager certification pathways. Paris-Saclay cleanroom facilities concentrate detector lithography expertise for both defense and emerging medical applications.
United Kingdom
British military modernization budgets anchor demand for cryogenically cooled systems in maritime and airborne surveillance roles. MHRA medical device regulations and post-Brexit UKCA marking requirements create parallel certification tracks for clinical fever-screening deployments. Cambridge and Bristol defense technology clusters sustain sovereign night-vision integration capabilities.
Poland
Critical infrastructure protection drives fixed camera installations at energy transmission nodes and transport corridors, with EU cohesion funds financing perimeter security upgrades. National cybersecurity regulations for critical infrastructure operators mandate thermal monitoring redundancy at classified sites. Warsaw and Krakow industrial zones concentrate distribution partnerships for eastern European market access.
Sweden
Nordic commercial real estate operators favor vanadium oxide microbolometers for HVAC diagnostics and building energy efficiency verification under stringent national environmental codes. Swedish Work Environment Authority guidelines mandate thermal inspection protocols for electrical panel maintenance in industrial facilities. Stockholm and Gothenburg facility management markets lead adoption of portable 640×512 resolution systems.
Europe Thermal Imaging Systems Market Competitive Landscape
Capability concentration sits with defense-anchored tier players possessing captive foundry access; scale advantage sits with diversified industrial sensor manufacturers with broad distribution networks. The vendor base stratifies across three tiers: sovereign defense integrators with classified program relationships, dual-use technology specialists bridging military and medical applications, and commercial component suppliers serving building diagnostics and predictive maintenance. Consolidation pressure operates through detector fabrication capacity scarcity rather than brand concentration. Dominant competitive moves include backward integration into microbolometer wafer processing and long-term service contract bundling to capture recurring revenue streams.
Within the sovereign defense tier, BAE Systems and Thales Group exemplify players with vertically controlled night-vision integration pipelines. Teledyne FLIR occupies a position spanning both defense and commercial domains through its foundry network architecture. Testo SE & Co. KGaA represents the industrial instrumentation specialist archetype, with its German corporate structure signaling concentration in building diagnostics and automotive quality assurance segments.
| Leading Market Players |
|---|
| Teledyne FLIR |
| BAE Systems |
| Testo SE & Co. KGaA |
| Thales Group |
| Elbit Systems |
| RTX |
| Lockheed Martin |
| Axis Communications AB |
| Thermoteknix Systems Ltd |
| Others |
Supply & Pricing Matrix
Undercapacity in Paris-Saclay detector fabrication facilities is compressing lead times for cooled indium antimonide arrays and empowering incumbent suppliers to enforce stricter contract terms on aerospace and defense buyers. This utilization squeeze propagates through the value chain, forcing procurement officers toward longer offtake commitments and eroding spot-market liquidity for high-performance thermal cores.
Pricing Analysis
Long-term offtake contracts dominate procurement for cooled military-grade detectors, while spot purchasing persists for uncooled microbolometer modules in building diagnostics. Price differentiation hinges on CE marking tier under MDR and volume scale, with medical-grade Class IIa devices commanding substantial premiums over industrial variants. Cost compression in the uncooled segment is intensifying as vanadium oxide wafer processing scales in Dresden. German automotive OEMs exhibit lowest price sensitivity due to downtime cost exposure, whereas Nordic facility managers face acute budget constraints.
Supply Chain Analysis
Tariff exposure between the United States and European Union threatens re-export flows of lithography equipment essential for microbolometer fabrication. Detector production concentrates in France, Germany, and the United Kingdom, drawing from germanium substrates, indium antimonide wafers, and vacuum-sealed cryogenic coolers. Single-source vulnerability sits with Stirling engine suppliers for cooled systems. Distribution runs through authorized integrators serving defense primes and direct OEM relationships in automotive and medical verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from predictive analytics subscriptions and uptime guarantees is expanding faster than hardware sales in German automotive procurement, reframing thermal imaging as a recurring-revenue platform rather than capital equipment.
For Market Incumbents: Insulate foundry capacity through exclusive wafer supply agreements with Paris-Saclay and Dresden clusters before cleanroom talent scarcity worsens. Deepen backward integration into vanadium oxide deposition equipment to offset REACH-driven solder material transitions. Lock in multi-year service contracts with French defense programs to deter dual-use entrants from bridging medical and military applications. For New Entrants and Emerging Players: Eastern European perimeter security at Polish energy transmission nodes and Romanian transport corridors represents the most penetrable entry point, with EU cohesion funds financing infrastructure upgrades and local distribution partnerships underdeveloped. Target mid-tier uncooled modules for Nordic commercial real estate HVAC diagnostics, where environmental code enforcement is tightening. Pursue white-label integration with German automotive Tier 1s seeking second-source thermal inspection modules. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across medical-grade detector fabrication as MDR Class IIa validation cycles extend and pixel-level calibration documentation demands proliferate. Long-term viability favors acquiring dual-use technology specialists with existing EMA-notified body relationships and cleanroom operational expertise. Watch for inflection when sovereign defense programs accelerate domestic fabrication subsidies in response to import dependency concerns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbolometer Wafer Processing | Captive supply of vanadium oxide arrays insulates margins from Paris-Saclay capacity constraints. |
| Long-term Service Contract Bundling | Uptime guarantees with German automotive OEMs convert transactional hardware sales into recurring revenue streams. |
| CE Marking Pathway Investment | MDR Class IIa certification opens clinical fever-screening deployments subject to EU AI Act algorithm transparency. |
| Dual-Use Technology Transfer Program | Defense-derived cooled detector architectures migrate into high-end medical imaging and semiconductor wafer inspection. |
| Geographic Expansion into Eastern European Infrastructure | Polish and Romanian energy node security upgrades present underpenetrated demand for fixed perimeter installations. |
Research Methodology
Operator-level perspectives from defense procurement officers, biomedical engineers at hospital purchasing committees, automotive quality assurance directors, and facility managers in Nordic commercial real estate anchored the qualitative base. Primary interviews triangulated against EMA device registration databases, EU defense procurement disclosures, German KBA vehicle safety filings, and REACH compliance documentation from ECHA. Secondary validation incorporated customs records for detector module trade flows and SEC filings from diversified sensor manufacturers. Bottom-up segment sizing reconciled with top-down macroeconomic anchors across the analysis window.
Scenario-bracketing framed the analytical approach, with demand trajectories tested against defense budget elasticity, MDR certification timeline extensions, and EV production ramp rates in German manufacturing clusters. Segmentation dimensions modeled include cooling architecture, resolution class, end-use vertical, and procurement authority structure. CAGRs derived from installed base evolution and replacement cycle analysis, with inputs from cleanroom capacity expansion schedules and EU Green Deal ecological design mandates for portable electronics.
Macroeconomic conditions sit as an overlay; deviation in defense modernization budgets, EV adoption curves, or EMA regulatory enforcement intensity would shift the trajectory. Forecasts embed assumptions regarding REACH transition timelines and EU AI Act implementation pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Holotomographic Imaging Market
Imaging
Instant Digital Cameras Market
Imaging
India CCTV Camera Market
Imaging
Semiconductor Microscopes Market
Imaging
Middle East and Africa Hyperspectral Imaging Systems Market
Imaging
Handheld Imager Market
Imaging
3D Time-Of-Flight Image Sensor Market
Imaging
Machine Vision Market
Imaging
North America Image Sensors Market
Imaging
Photoacoustic Microscope Market
Imaging
Digital Image Processing Market
Imaging
Infrared Imaging Software Market
Imaging
AI-Based Fever Detection Camera Market
Imaging
Latin America Surveillance Analog Camera Market
Imaging
Photography Equipment Market
Imaging
Event Camera Market