
 Middle East and Africa Ice Cream Market | 2026-2036
Middle East and Africa Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Ice Cream Market Foresight
Multi-sourcing of dairy and flavor ingredients is pivoting as manufacturers balance cost volatility against supply security. Unilever PLC leverages its regional manufacturing footprint to sustain distribution density across North African markets. Nestlé S.A. anchors its position through specialized formulations adapted to local taste preferences and climate conditions.
Ice cream is a frozen dairy dessert typically containing milk fat, sweeteners, stabilizers, and air overrun of 20–100 percent, manufactured through continuous freezing and hardening processes designed to deliver controlled texture and scoopability for commercial and household consumption. Cup formats dominate impulse purchases in hot-climate markets where portion control and portability drive transaction frequency. Online Retail channels represent the fastest-growing distribution pathway as last-mile cold chain capabilities expand across urban centers in the region.
SFDA standards in Saudi Arabia and FSSAI guidelines in India—both referenced by regional exporters—govern microbial limits, labeling, and additive permissions that determine product eligibility for cross-border trade. The EU Green Deal's extraterritorial influence on ingredient sustainability certification is reshaping procurement criteria for multinational suppliers operating in Middle Eastern markets. Stakeholders must monitor evolving halal certification harmonization and energy cost trajectories that directly affect cold storage economics and pricing flexibility.
Market Dynamics
Cold chain infrastructure investments are compressing distribution timelines across the Middle East and Africa, enabling manufacturers to extend reach into secondary urban centers previously excluded by temperature-controlled logistics constraints.
Growth Catalysts
- Urban food service expansion:Hotel and restaurant chains in Dubai, Riyadh, and Johannesburg are adding dedicated frozen dessert stations, creating pull-through demand for bulk and portion-controlled formats.
- SFDA export alignment:Saudi Arabia's food safety standards are becoming the regional reference point, allowing compliant manufacturers to access Gulf Cooperation Council markets through mutual recognition protocols.
- Air overrun optimization:Continuous freezing technology is reducing energy intensity per liter while maintaining scoopability standards demanded by hot-climate consumers.
Market Restraints
- Dairy input cost volatility:Powdered milk and butterfat prices fluctuate with New Zealand and European Union auction cycles, compressing margin predictability for regional formulators.
- Generator-dependent cold storage:Nigerian and Kenyan distributors face 40-60% higher energy costs than grid-connected facilities, limiting price competitiveness against imported finished goods.
- Halal certification fragmentation:Divergent standards between UAE's ESMA, Saudi's SFDA, and Malaysia's JAKIM create redundant audit costs for pan-regional brands.
Strategic Opportunities
- Morocco's underdeveloped modern trade:Independent retail still commands 70% of frozen dessert volume, presenting white space for branded freezer cabinet placement programs.
- Plant-based formulation convergence:Date syrup and coconut cream bases are merging with European stabilizer technology to create heat-stable alternatives for fasting-season consumption.
- Direct-to-hotel distribution:Bypassing traditional wholesale layers through captive delivery fleets is capturing margin previously lost to multi-tier distribution in Egyptian resort corridors.
Industry Challenges
- Cold chain technician scarcity:Refrigeration mechanics with frozen food handling certification remain concentrated in South Africa and UAE, forcing importers in Ethiopia and Ghana to rely on expatriate maintenance contracts.
- Legacy freezer asset integration:Retrofitting open-chest displays with temperature logging systems for FSSAI traceability requirements demands capital outlays that independent retailers resist.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Ice Cream Market |
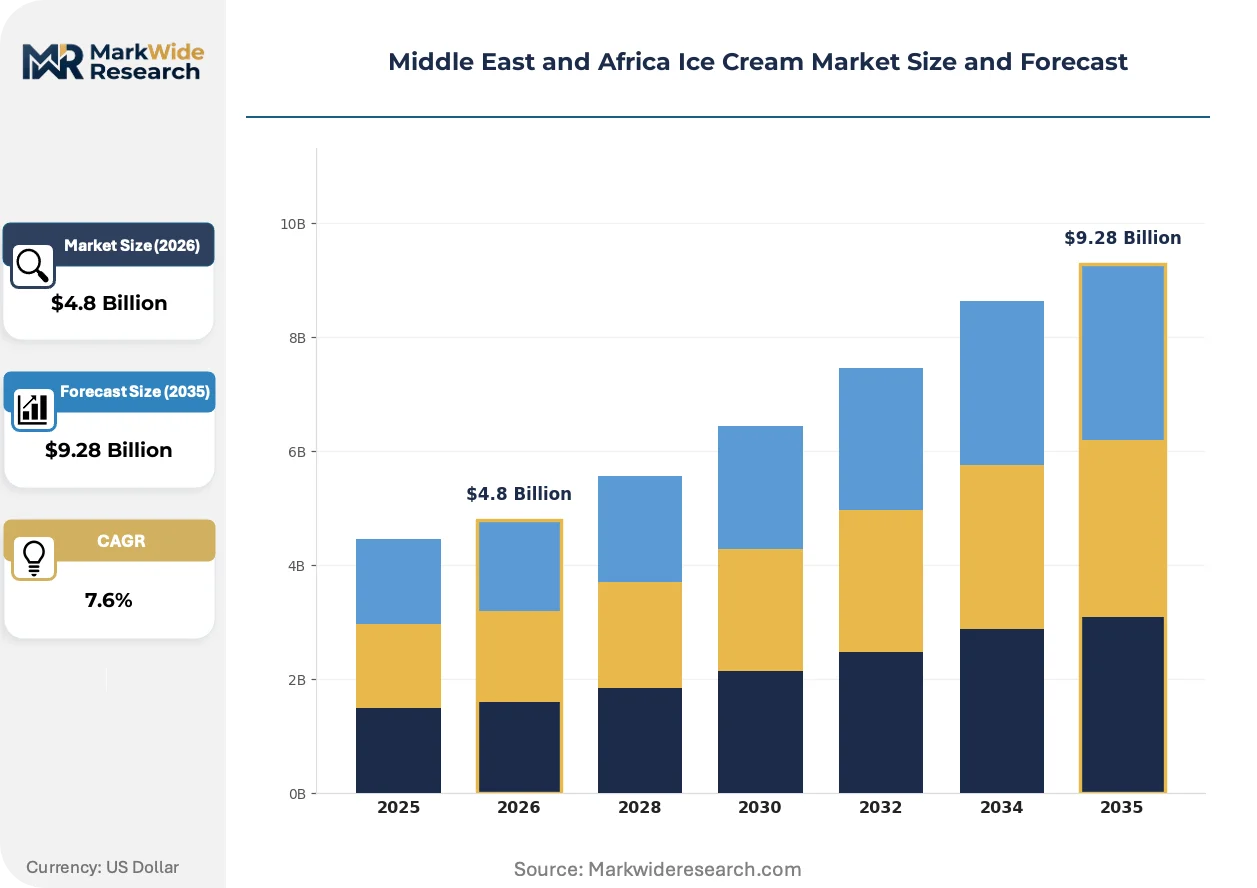
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cup, Cone, Stick, Sandwich Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service Flavor: Vanilla, Chocolate, Strawberry, Mango End User: Children, Adults, Families, Seniors |
| Companies Covered | IFFCO Group, Inspire Brands Inc, Nestlé S.A., Danone S.A., Wells Enterprises Inc, Unilever PLC, General Mills Inc, Froneri International Ltd, Mars Incorporated, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Ice Cream Market Shifts & Advancements
Reformulation priorities are shifting from simple flavor extension toward structural stability under thermal stress, as ambient temperatures in core markets regularly exceed 40°C during peak consumption months.
Modified starch and hydrocolloid blends are unifying the functions of traditional stabilizers, emulsifiers, and water-binding agents into single-ingredient systems. Premium manufacturers in UAE and Qatar are adopting these at pace, drawn by simplified procurement and reduced recipe complexity. This convergence is unifying supply chains previously segmented by functional additive categories, compressing supplier bases and raising minimum volume thresholds for ingredient vendors.
The EU Green Deal's extraterritorial sustainability certification requirements are reshaping procurement criteria for multinational suppliers operating in Middle Eastern markets. Dairy and cocoa sourcing now demands deforestation-free documentation and carbon footprint disclosure, adding compliance layers to cross-border trade. European-anchored brands with existing sustainability infrastructure are responding faster than regional pure-plays, creating competitive separation in retail listing negotiations.
Young adult consumers in Cairo, Lagos, and Nairobi are treating ice cream as an everyday refreshment rather than celebratory indulgence, collapsing the traditional occasion-based purchase cycle. Convenience stores and petrol station forecourts are displacing traditional grocery as the dominant impulse channel, with single-serve cups and mini-sticks capturing transaction frequency previously associated with bulk family packs. This rotation is most visible in South African metropolitan areas, where on-the-go consumption now exceeds home consumption for consumers under 30.
Middle East and Africa Ice Cream Market Segmentation
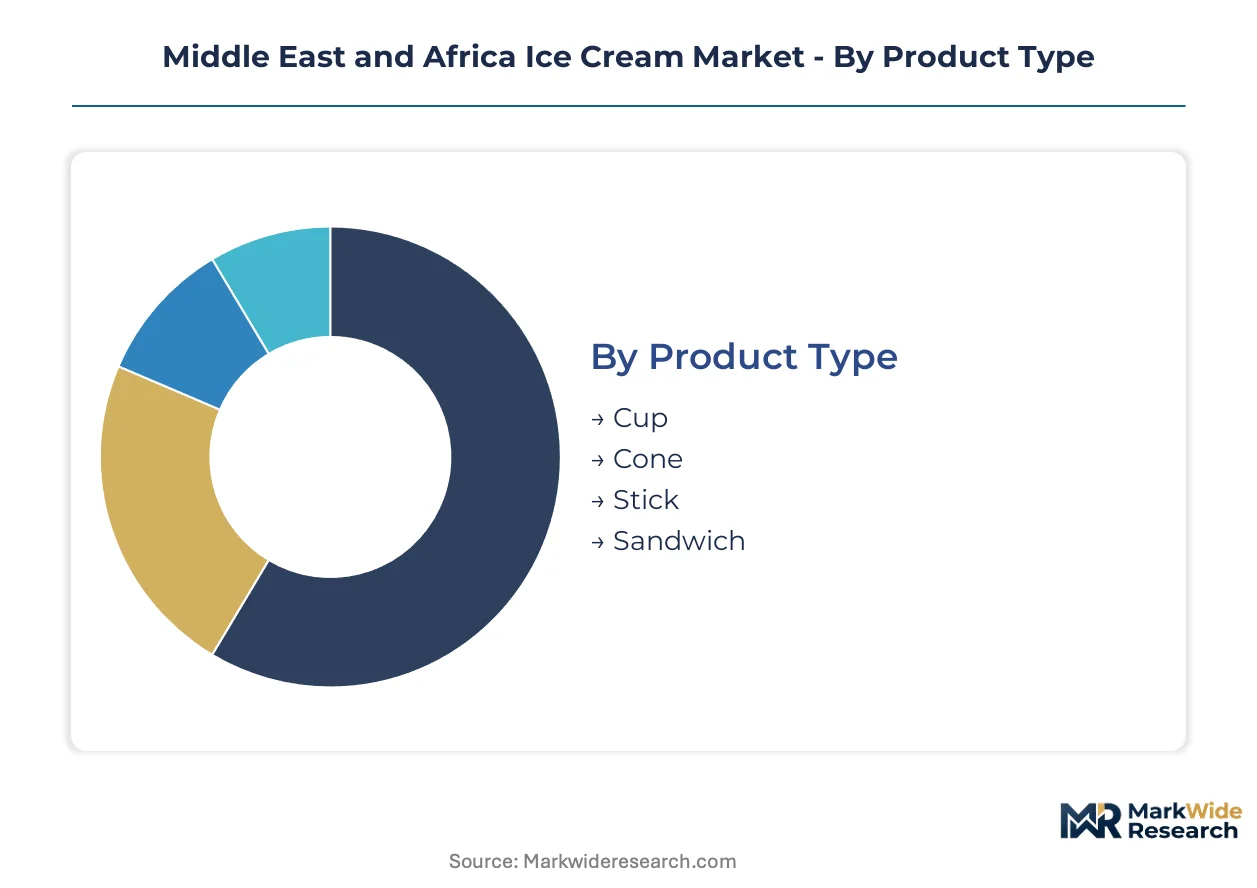
Ice cream segmentation in the Middle East and Africa reflects divergent consumption contexts across scorching climates, income stratification, and rapidly modernizing retail infrastructure. Manufacturers calibrate portion sizes, thermal stability formulations, and channel-specific packaging to capture transactions ranging from impulse petrol-station purchases to family bulk buying.
Product Type:
Purchase occasion and ambient temperature exposure separate buyers across formats, with portability and melt resistance commanding premium positioning in Gulf markets.
- Cup:Single-serve polystyrene or paper vessels with fitted lids dominate impulse channels where portion control and drip containment matter. Dubai and Riyadh convenience stores report highest transaction frequency for 100-150ml cups during afternoon temperature peaks.
- Cone:Pre-filled sugar or wafer cones with chocolate-lined barriers against sogginess. South African metropolitan on-the-go consumption under 30 favors mini-cones for walkaway eating.
- Stick:Molded bars on wooden or plastic sticks, often enrobed in compound coatings for structural integrity. Popular in Nigerian open-chest freezer retail where handling simplicity outweighs premium positioning.
- Sandwich:Biscuit-wafer layers with ice cream cores, valued for eat-without-mess properties. Egyptian resort corridors and Saudi mall food courts favor this format for family sharing occasions.
Cup formats lead volumes today; Online Retail bundling of variety packs is gaining share fastest.
Distribution Channel:
Cold chain maturity and last-mile temperature control determine which channels can stock premium formulations without quality degradation.
- Supermarkets:Branded freezer cabinets with transparent sliding doors and consistent temperature logging. South African chains Checkers and Pick n Pay have deployed FSSAI-aligned monitoring systems across frozen dessert aisles.
- Convenience Stores:Compact open-chest displays in petrol forecourts and neighborhood shops. Lagos and Nairobi operators prioritize generator-backed units to maintain scoopability during grid instability.
- Online Retail:Direct-to-consumer platforms with insulated packaging and same-day delivery slots. UAE and Saudi last-mile cold chain expansion enables premium product access previously limited to physical retail.
- Food Service:Hotel restaurants, cinema chains, and QSR dessert stations sourcing bulk tubs or portion-controlled formats. Johannesburg and Dubai hospitality sectors drive demand for display-worthy artisan presentations.
Convenience Stores anchor transaction frequency today; Online Retail is expanding most quickly.
Flavor:
Local ingredient availability and fasting-season consumption patterns steer formulation priorities away from purely Western taste replication.
- Vanilla:Standard base for mix-in customization and milkshake blending. Egyptian and Moroccan manufacturers favor Madagascar-sourced extract for premium positioning in hotel food service.
- Chocolate:Cocoa-intensive profiles requiring EU Green Deal-compliant deforestation-free sourcing documentation. European-anchored brands leverage existing sustainability infrastructure for retail listing advantages.
- Strawberry:Fruit-based formulations with higher water content demanding enhanced stabilizer systems for heat resistance. Less prominent in Gulf markets where date and tropical profiles dominate.
- Mango:Alphonso and Kent puree variants resonating with South Asian diaspora populations in UAE and Saudi Arabia. Seasonal availability drives procurement timing for regional formulators.
Vanilla leads baseline volumes today; Mango is climbing the fastest on diaspora demand and local fruit processing investments.
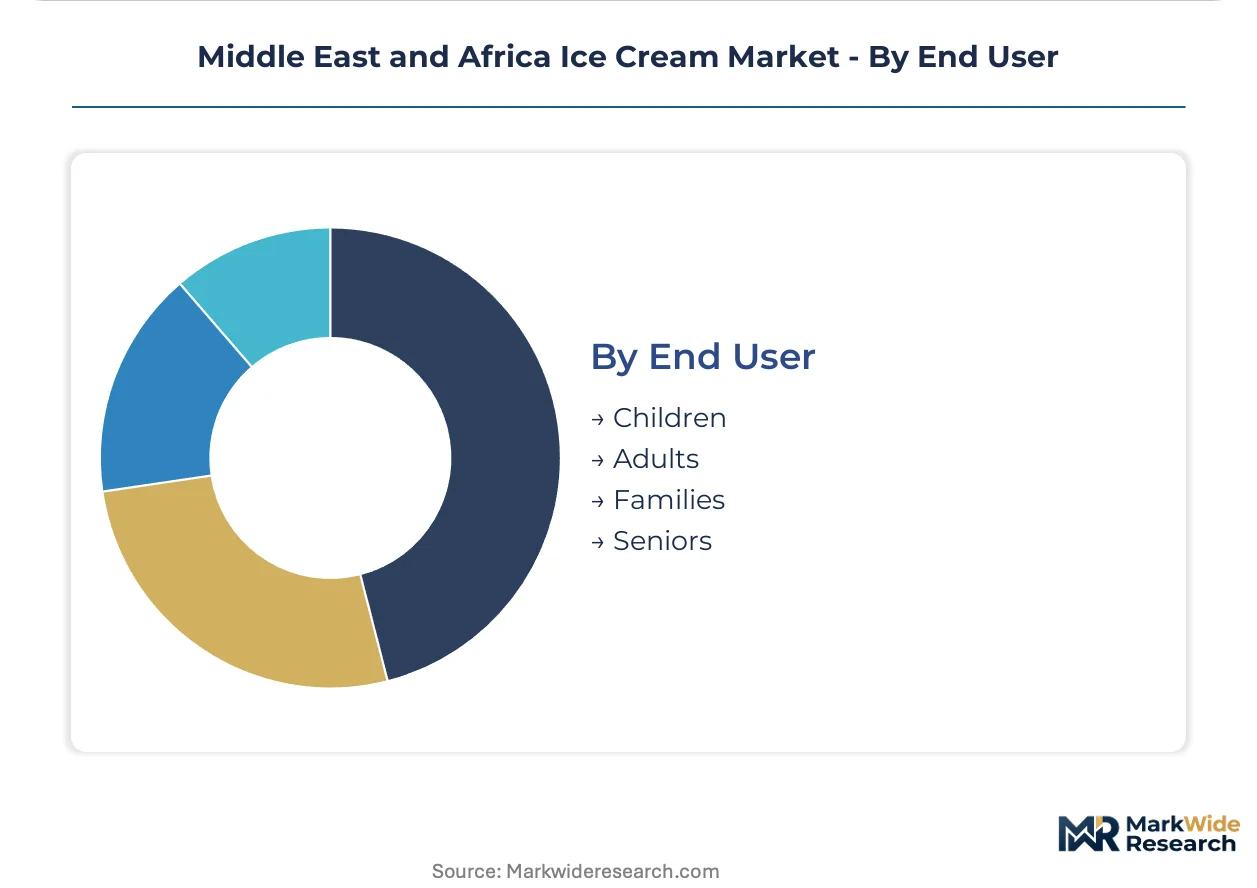
End User:
Age-cohort consumption occasions and health-positioning tolerance shape product development and marketing allocation.
- Children:Character-licensed packaging and lower-price-point sticks or cones. Nigerian and Kenyan independent retailers prioritize bright visual packaging for open-chest display visibility.
- Adults:Premium single-serve cups and reduced-sugar formulations. Cairo and Lagos young adult consumers treat ice cream as everyday refreshment rather than celebratory indulgence.
- Families:Bulk tubs and multi-pack value offerings for home freezer stocking. South African metropolitan households drive volume through weekend supermarket purchasing.
- Seniors:Smaller portion formats with texture-softening formulations. Limited dedicated product development reflects perceived market size constraints in region.
Adults command transaction frequency growth today; Families retain largest absolute volume contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
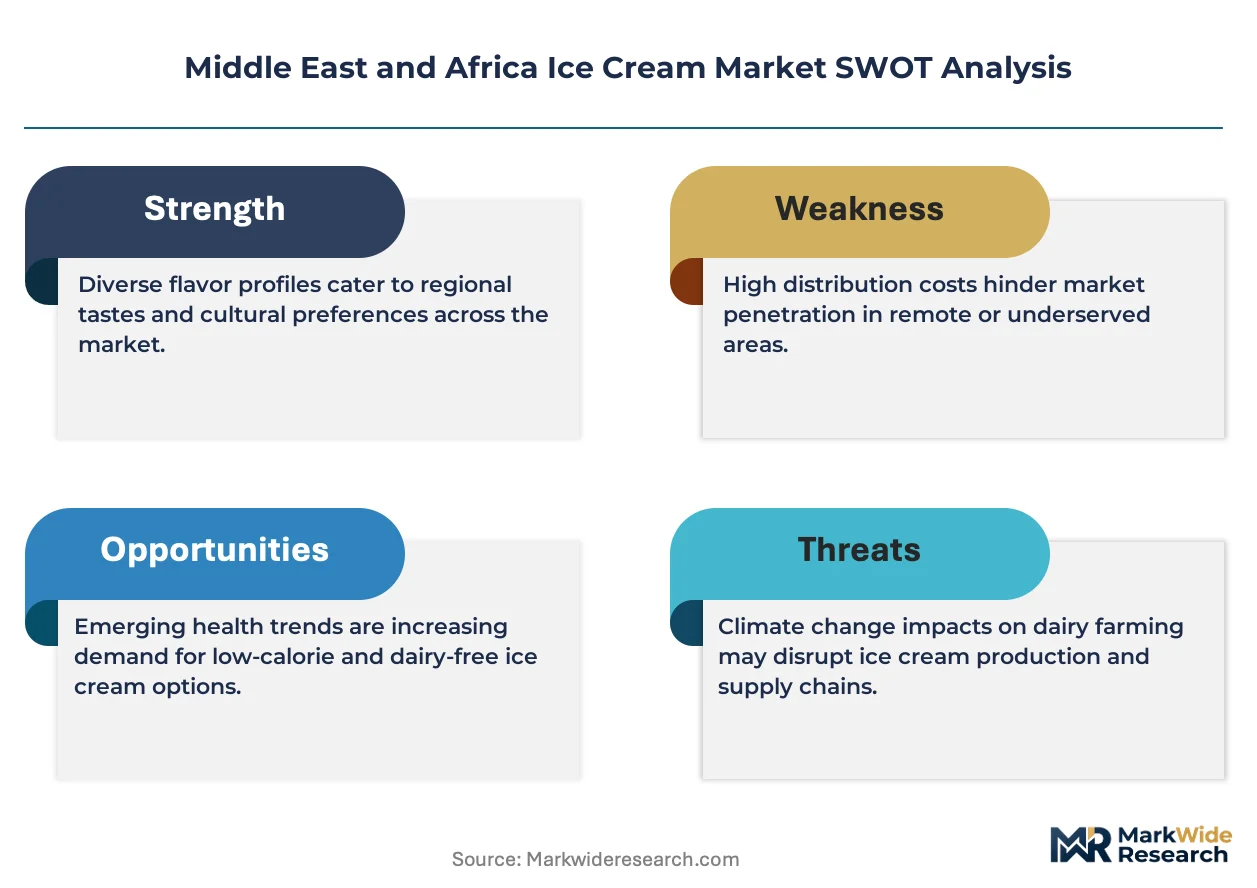
Dubai's hospitality corridor anchors premium ice cream consumption across the Gulf, while Johannesburg drives volume through modern retail density. Cold chain investments in Riyadh and Lagos are compressing distribution timelines and enabling format experimentation.
Saudi Arabia
SFDA export alignment protocols allow compliant manufacturers to access Gulf Cooperation Council markets through mutual recognition frameworks. The Saudi Food and Drug Authority governs microbial limits, labeling standards, and additive permissions that determine cross-border eligibility. Riyadh's food service expansion includes dedicated frozen dessert stations in hotel and restaurant chains, creating pull-through demand for bulk formats.
United Arab Emirates
Dubai's young adult consumers treat ice cream as everyday refreshment rather than celebratory indulgence, collapsing traditional occasion-based purchase cycles. ESMA halal certification standards diverge from Saudi and Malaysian frameworks, creating redundant audit costs for pan-regional brands. Abu Dhabi's last-mile cold chain expansion enables premium product access through online retail channels previously limited to physical stores.
South Africa
Checkers and Pick n Pay supermarket chains have deployed FSSAI-aligned temperature monitoring systems across frozen dessert aisles. The country's national food safety regulator references international standards for microbial traceability requirements. Johannesburg's metropolitan on-the-go consumption now exceeds home consumption for consumers under thirty, driving convenience store transaction frequency.
Egypt
Direct-to-hotel distribution models are bypassing traditional wholesale layers through captive delivery fleets in resort corridors. Egyptian food safety protocols align with FSSAI guidelines referenced by regional exporters for cross-border trade eligibility. Cairo's young adult demographic is expanding consumption beyond traditional occasions, treating single-serve cups as afternoon refreshment during temperature peaks.
Nigeria
Generator-dependent cold storage imposes forty to sixty percent higher energy costs than grid-connected facilities, limiting price competitiveness against imported finished goods. The country's national food safety regulator maintains evolving standards for frozen dessert handling and distribution. Lagos operators prioritize generator-backed open-chest displays to maintain scoopability during grid instability.
Middle East and Africa Ice Cream Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue plant-based formulation spaces and direct-to-hotel distribution channels. The market structure reflects a consolidated core of multinational fast-moving consumer goods conglomerates with regional manufacturing footprints, surrounded by fragmented local processors serving independent retail. Three archetypes dominate: scale-driven multinationals leveraging backward integration into dairy sourcing, mid-tier regional specialists adapting formulations to local taste preferences, and niche entrants exploiting halal certification harmonization gaps. Competitive intensity centers on cold chain partnerships and freezer cabinet placement programs rather than price alone.
Within the multinational tier, Unilever PLC and Nestlé S.A. exemplify divergent strategic positioning. Unilever leverages its regional manufacturing footprint to sustain distribution density across North African markets. Nestlé anchors its position through specialized formulations adapted to local taste preferences and climate conditions. Froneri International Ltd occupies a distinct position as a dedicated frozen dessert specialist with concentrated category expertise.
| Leading Market Players |
|---|
| IFFCO Group |
| Inspire Brands Inc |
| Nestlé S.A. |
| Danone S.A. |
| Wells Enterprises Inc |
| Unilever PLC |
| General Mills Inc |
| Froneri International Ltd |
| Mars Incorporated |
| Others |
Supply & Pricing Matrix
The EU Green Deal's deforestation-free documentation requirements now gate qualified supply access and premium-tier pricing eligibility for multinational suppliers serving Middle Eastern markets. Manufacturers lacking carbon footprint disclosure capabilities face exclusion from retail listing negotiations, compressing margin recovery options while compliant competitors capture shelf space.
Pricing Analysis
Powdered milk and butterfat auction cycles from New Zealand and the European Union transmit directly into regional formulator margins through quarterly contract adjustments. Pricing stratifies across premium, standard, and economy tiers based on halal certification grade and cold chain integrity guarantees, with generator-dependent Nigerian distributors absorbing forty to sixty percent energy cost premiums versus grid-connected Gulf facilities. Cost compression in the standard tier is intensifying as private-label entrants exploit dairy input volatility. Independent retailers in Morocco and Kenya exhibit highest price sensitivity, while Dubai hospitality buyers prioritize scoopability assurance over unit economics.
Supply Chain Analysis
Dairy solids supply rests on New Zealand, European Union, and Australian auction markets, with cocoa butter and chocolate liquor drawing from West African cooperatives and Southeast Asian processors. Coconut cream bases for plant-based formulations source from Indonesian and Philippine processors, while modified starch stabilizers come from Thai and Indian specialty chemical producers. Single-source vulnerability concentrates in EU-anchored sustainability certification bodies, where documentation bottlenecks delay cross-border shipments. Distribution runs through Unilever and Nestlé captive logistics networks across North Africa, supplemented by independent cold chain operators in Lagos and Nairobi.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through air overrun optimization technology that reduces energy intensity per liter while maintaining hot-climate scoopability standards demanded by premium buyers.
For Market Incumbents: Anchor freezer cabinet placement programs in Morocco's independent retail corridor before branded competitors consolidate shelf space. Secure backward integration into date syrup and coconut cream sourcing to lock plant-based formulation inputs against commodity volatility. Defend against emerging direct-to-hotel distributors by deploying captive delivery fleets in Egyptian and Saudi resort corridors.
For New Entrants and Emerging Players: The gap between premium artisan positioning and economy stick pricing creates white space for mid-tier heat-stable cup formats. Target Nigeria's generator-backed convenience store channel with portion-controlled mini-cups engineered for ambient temperature exposure. Enter through halal certification harmonization arbitrage, exploiting audit redundancy costs that burden pan-regional brands.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional dairy processors with underutilized cold storage assets and latent FSSAI compliance infrastructure. Long-term viability hinges on last-mile cold chain density rather than brand equity alone. Watch for SFDA-GCC mutual recognition expansion as the signal triggering consolidation premiums for compliant manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Air Overrun Technology Deployment | Reduces energy intensity per liter while preserving scoopability in 40°C ambient conditions. |
| Direct-to-Hotel Distribution Buildout | Captures margin previously lost to multi-tier wholesale layers in Egyptian resort corridors. |
| Plant-Based Formulation Convergence | Merges date syrup bases with European stabilizer technology for fasting-season consumption. |
| Freezer Cabinet Placement Programs | Secures branded visibility in Morocco's 70% independent retail volume before consolidation. |
| Halal Certification Harmonization | Eliminates redundant ESMA-SFDA-JAKIM audit costs that erode pan-regional brand margins. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers, category buyers at Checkers and Pick n Pay, cold chain logistics operators, and FSSAI compliance officers with secondary validation against customs records, Nielsen retail audit data, and SFDA regulatory filings. Bottom-up volume builds from manufacturer shipments and top-down demand estimates from retail channel audits were triangulated for consistency.
Historical reference periods anchored the projection horizon through indexed input cost trajectories and channel penetration curves. Segmentation dimensions modeled include product format, distribution channel, flavor profile, and end-user age cohort alongside climate-zone thermal stress requirements. CAGRs were derived from fitted growth curves calibrated to cold chain investment pipelines and urban food service expansion timelines. Forecast inputs incorporated dairy auction price volatility bands and generator fuel cost scenarios for Nigerian and Kenyan distributors.
Caveats apply where SFDA regulatory amendments, EU Green Deal certification expansion, or cold chain technician scarcity could materially shift the outlook. Forecasts reflect assumptions about halal harmonization progress and energy grid stability that warrant sensitivity testing. A small set of named triggers—ESMA-SFDA alignment breakthroughs, date syrup supply shocks, and Gulf hospitality sector contraction—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Chilled Meal Kits Market
Processed and Frozen Foods
Frozen Novelty Market
Processed and Frozen Foods
South America Frozen Food Market
Processed and Frozen Foods
Frozen Mackerel Market
Processed and Frozen Foods
Frozen Chicken Market
Processed and Frozen Foods
Frozen Processed Food Market
Processed and Frozen Foods
Frozen Sardine Market
Processed and Frozen Foods
United States Frozen Pizza Market
Processed and Frozen Foods
French Fries Market
Processed and Frozen Foods
Low-Fat Cool Whip Market
Processed and Frozen Foods
Dehydrated Food Market
Processed and Frozen Foods
Vegan Frozen Food Market
Processed and Frozen Foods
Europe Ice Cream Market
Processed and Frozen Foods
Asia-Pacific Frozen Food Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
Europe Frozen Pizza Market