
 Frozen Mackerel Market | 2026-2036
Frozen Mackerel Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Mackerel Market Foresight
Subscription-based cold chain monitoring is shifting how frozen mackerel suppliers monetize logistics relationships beyond commodity sales. Maruha Nichiro Corporation leverages integrated vessel-to-retail operations across the North Pacific. Nissui Corporation sustains long-term supply contracts with Japanese institutional canteens. Thai Union Group competes through scaled procurement networks spanning Southeast Asian waters.
Frozen mackerel consists of Scombridae species preserved at temperatures below minus 18 degrees Celsius through blast freezing or plate freezing within hours of catch to inhibit enzymatic degradation and lipid oxidation. The primary commercial purpose centers on extending seasonal availability for human consumption and industrial processing into value-added products. Whole frozen mackerel occupies the highest volume tier due to cost efficiency in bulk export trade, while fillets command stronger unit margins in European and North American retail channels. Minced mackerel represents the fastest-expanding product type as surimi and processed seafood manufacturers seek functional protein inputs.
FDA seafood HACCP regulations and EU IUU fishing controls shape import eligibility and traceability documentation requirements for frozen mackerel entering major consumption markets. Japan's Food Sanitation Act and JIS standards govern residual histamine limits and processing hygiene for domestic distribution and re-export. Stakeholders must monitor evolving quota allocations under regional fisheries management organizations and cold chain energy costs that determine margin sustainability in frozen distribution.
Market Dynamics
Cold chain logistics consolidation is compressing margin structures for frozen mackerel distributors as vessel operators and warehouse providers merge into integrated platforms controlling blast freezing capacity and port storage.
Growth Catalysts
- Foodservice menu expansion:Hotels and restaurant chains across Southeast Asia are adding frozen mackerel to seafood offerings, driving procurement volumes from Thai and Vietnamese processors.
- EU IUU fishing controls:Enhanced traceability documentation requirements are filtering out non-compliant suppliers, concentrating demand among certified fleet operators with documented catch certificates.
- Blast freezing advancement:Cryogenic tunnel freezing systems are reducing post-harvest spoilage rates and extending shelf life for transoceanic shipments.
Market Restraints
- Fuel cost volatility:Marine diesel price swings directly compress operating margins for distant-water fishing fleets supplying frozen mackerel to Japanese and European buyers.
- North Pacific supply concentration:Quota allocations under regional fisheries management organizations concentrate harvest rights among a limited set of flag-state operators, restricting new market entry.
- Histamine regulatory limits:Japan's Food Sanitation Act and FDA HACCP thresholds for residual histamine create rejection risk for temperature-abused lots, forcing costly quality control investments.
Strategic Opportunities
- Indian retail underpenetration:Organized retail chains in Mumbai and Chennai are expanding frozen seafood sections, creating first-mover positioning for cold chain-equipped suppliers.
- Surimi processor demand:Minced mackerel specifications for functional protein inputs are opening contract supply relationships with Asian surimi manufacturers.
- Subscription monitoring services:IoT-enabled cold chain tracking is generating recurring revenue streams beyond commodity sales for logistics providers serving institutional canteens.
Industry Challenges
- Refrigeration technician scarcity:Qualified personnel for maintaining blast freezing and controlled atmosphere systems are in short supply across Southeast Asian processing hubs.
- Legacy ERP integration:Fleet management and catch documentation software must interface with customer traceability portals, creating data standardization friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Mackerel Market |
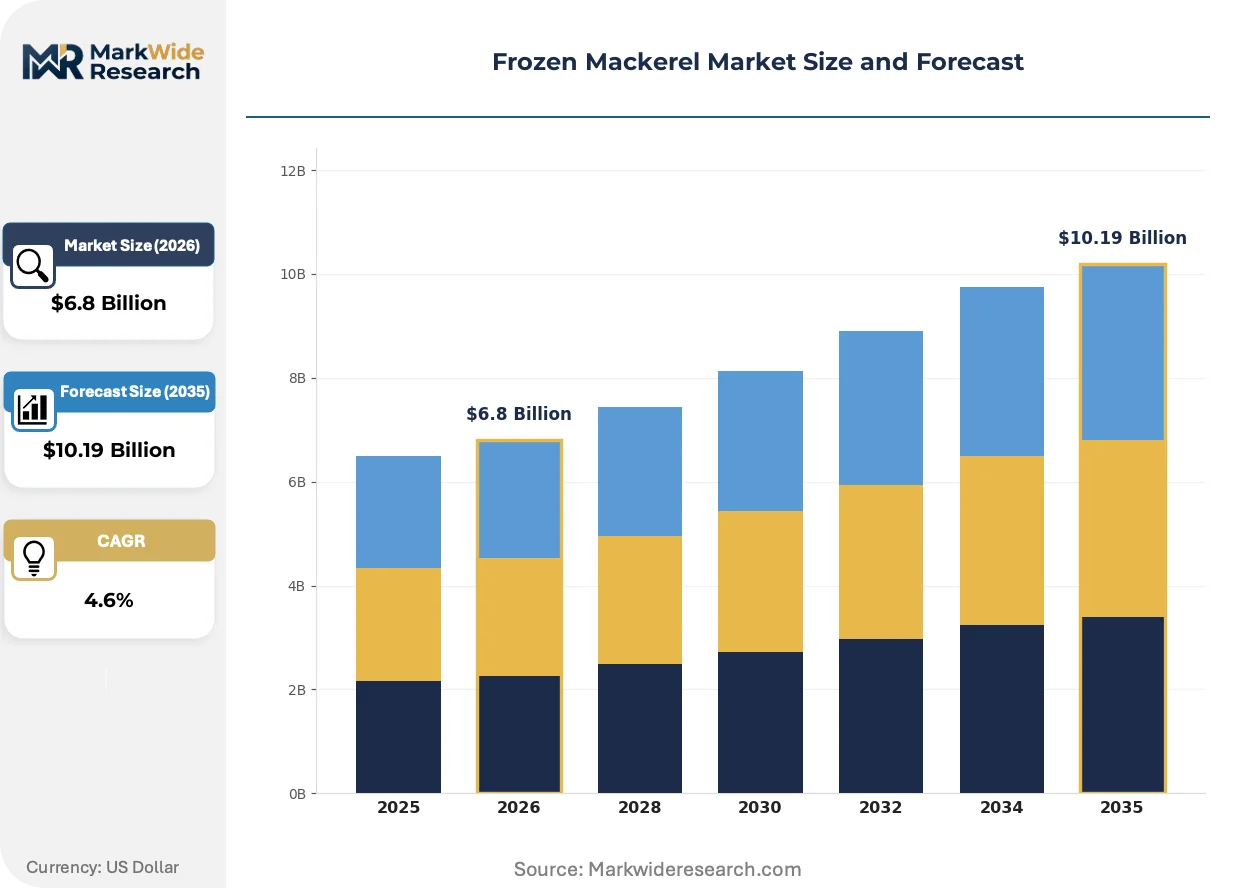
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Frozen Mackerel, Fillets, Steaks, Minced Mackerel, Smoked Frozen Mackerel Distribution Channel: Supermarkets, Online Retailers, Seafood Wholesalers, Specialty Stores, Foodservice Distributors Application: Household Consumption, Foodservice Industry, Processed Seafood Products, Pet Food Manufacturing, Nutraceutical Ingredients End User: Restaurants, Hotels, Institutional Canteens, Exporters, Seafood Processing Units |
| Companies Covered | Maruha Nichiro Corporation, Nissui Corporation, Thai Union Group, Ocean Treasure World Foods, Austevoll Seafood ASA, Leroy Seafood Group ASA, FCF Fishery Co. Ltd., Pelagia AS, Hottlet Frozen Foods NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Mackerel Market Shifts & Advancements
Digital traceability platforms are intersecting with cold chain hardware to create condition-verified supply chains that command premium positioning in institutional procurement.
Blockchain-enabled catch documentation is unifying vessel logbooks, temperature records, and customs declarations into single-source verification systems. Japanese supermarket chains and European processors are mandating platform participation for contract eligibility. This unifying architecture is compressing supplier qualification timelines from months to weeks while raising compliance barriers for smaller fleet operators.
EU F-Gas Regulation phase-down schedules are forcing cold chain operators to retrofit refrigeration systems with lower-global-warming-potential alternatives. Equipment suppliers are accelerating ammonia-CO2 cascade system deployments in European blast freezing facilities. Nordic and Baltic port storage operators are responding fastest, leveraging existing technical expertise in natural refrigerant handling.
Direct procurement relationships between surimi manufacturers and distant-water fleets are displacing traditional auction-house spot purchasing. Large-scale processors in Thailand and South Korea are signing multi-year offtake agreements with North Pacific operators. This pattern is most visible in the Tsukiji-adjacent trading community, where intermediary commission structures are eroding.
Frozen Mackerel Market Segmentation
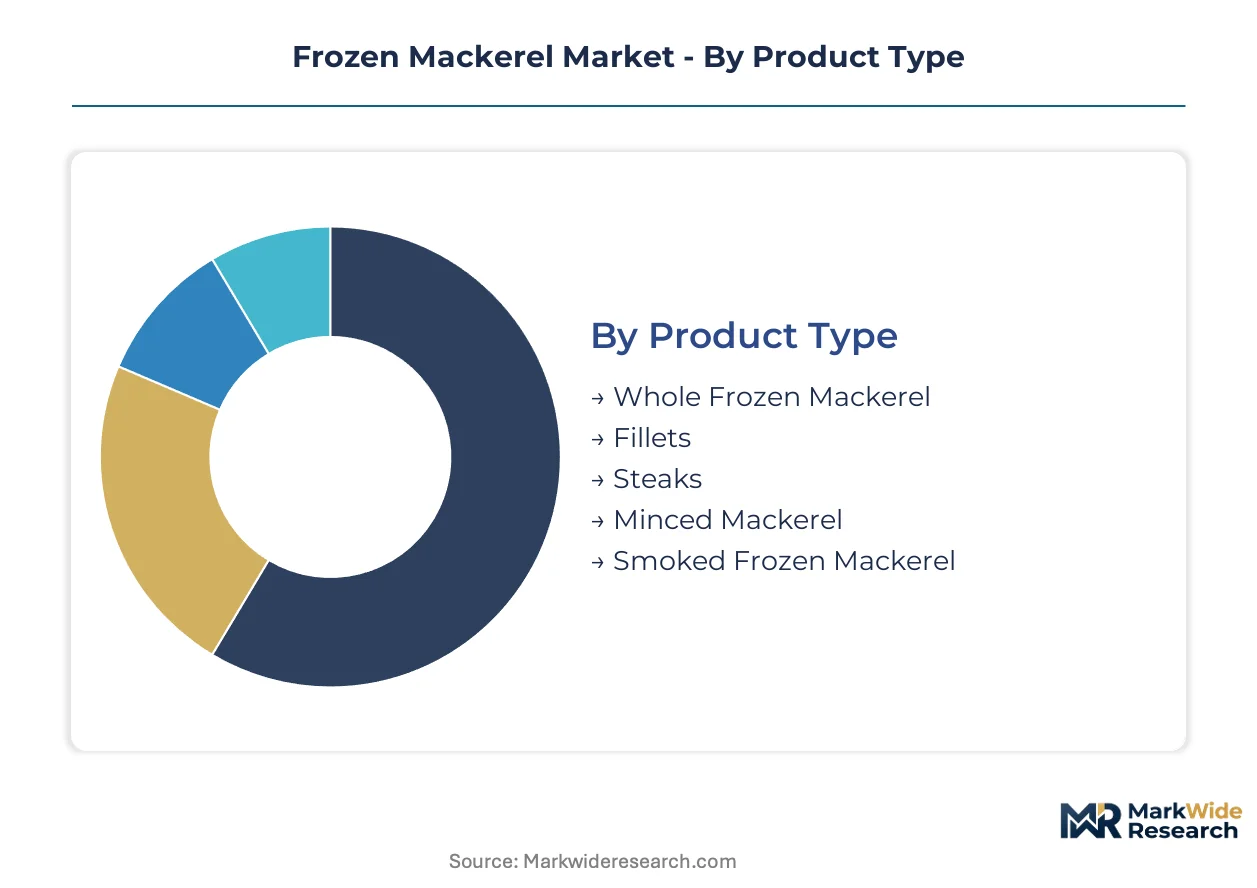
Frozen mackerel procurement decisions hinge on shelf-life requirements, processing economics, and end-use specifications. Each segmentation dimension reveals distinct margin structures and logistics constraints that shape supplier positioning across vessel-to-retail value chains.
Product Type:
Buyers select product formats based on labor substitution needs and destination market equipment capabilities.
- Whole Frozen Mackerel:Unprocessed round fish preserved in blast-frozen blocks for bulk export efficiency. Japanese institutional canteens and Southeast Asian re-processors dominate procurement due to in-house filleting capacity and cost-minimization mandates.
- Fillets:Skin-on or skin-off portions processed at origin to reduce downstream labor. European retail chains and North American supermarkets concentrate demand here, driven by consumer convenience expectations and limited seafood counter staffing.
- Steaks:Cross-section cuts suited for grilling applications in Mediterranean and Middle Eastern foodservice. Portion consistency commands modest premiums in hotel banquet operations.
- Minced Mackerel:Mechanical deboning output for surimi and functional protein applications. Thai and South Korean processors are expanding offtake agreements with North Pacific fleets for this input grade.
- Smoked Frozen Mackerel:Value-added preservation combining traditional curing with frozen distribution. Baltic and Nordic suppliers dominate this niche for European deli retail.
Whole frozen mackerel leads on scale; minced mackerel leads on momentum.
Distribution Channel:
Channel selection determines cold chain custody handoffs and traceability documentation burdens.
- Supermarkets:Organized retail chains with dedicated frozen seafood sections requiring temperature-logged deliveries. Japanese and European operators are mandating blockchain-enabled catch documentation for contract eligibility.
- Online Retailers:Direct-to-consumer platforms with last-mile frozen logistics. Mumbai and Chennai-based e-grocers are expanding this channel in underpenetrated Indian metropolitan markets.
- Seafood Wholesalers:Traditional auction-adjacent intermediaries consolidating volumes for redistribution. Their role is eroding as surimi manufacturers establish direct fleet relationships.
- Specialty Stores:Ethnic and premium seafood retailers serving diaspora communities. These outlets prioritize specific origin labeling and traditional processing methods.
- Foodservice Distributors:Institutional supply specialists with blast freezing and controlled atmosphere storage assets. Subscription-based cold chain monitoring is shifting their revenue model beyond commodity margins.
Seafood wholesalers retain volume concentration; online retailers are climbing the fastest.
Application:
Application segmentation separates commodity protein flows from value-added ingredient streams.
- Household Consumption:Retail-packaged products for home preparation. European demand concentrates here, with fillets and smoked formats dominating supermarket freezer cases.
- Foodservice Industry:Hotel and restaurant procurement of portion-controlled products. Southeast Asian hospitality expansion is strengthening this segment's procurement volumes.
- Processed Seafood Products:Industrial inputs for canning, surimi, and ready-meal manufacturing. This application commands the largest volume throughput via long-term offtake contracts.
- Pet Food Manufacturing:Lower-grade mackerel meal and mince for premium pet nutrition brands. Quality specifications are tightening as human-grade ingredient claims proliferate.
- Nutraceutical Ingredients:Omega-3 oil extraction and protein isolate production. Regulatory complexity from FDA and EFSA novel food assessments constrains supplier entry.
Processed seafood products anchor volume; nutraceutical ingredients show steepest expansion trajectory.
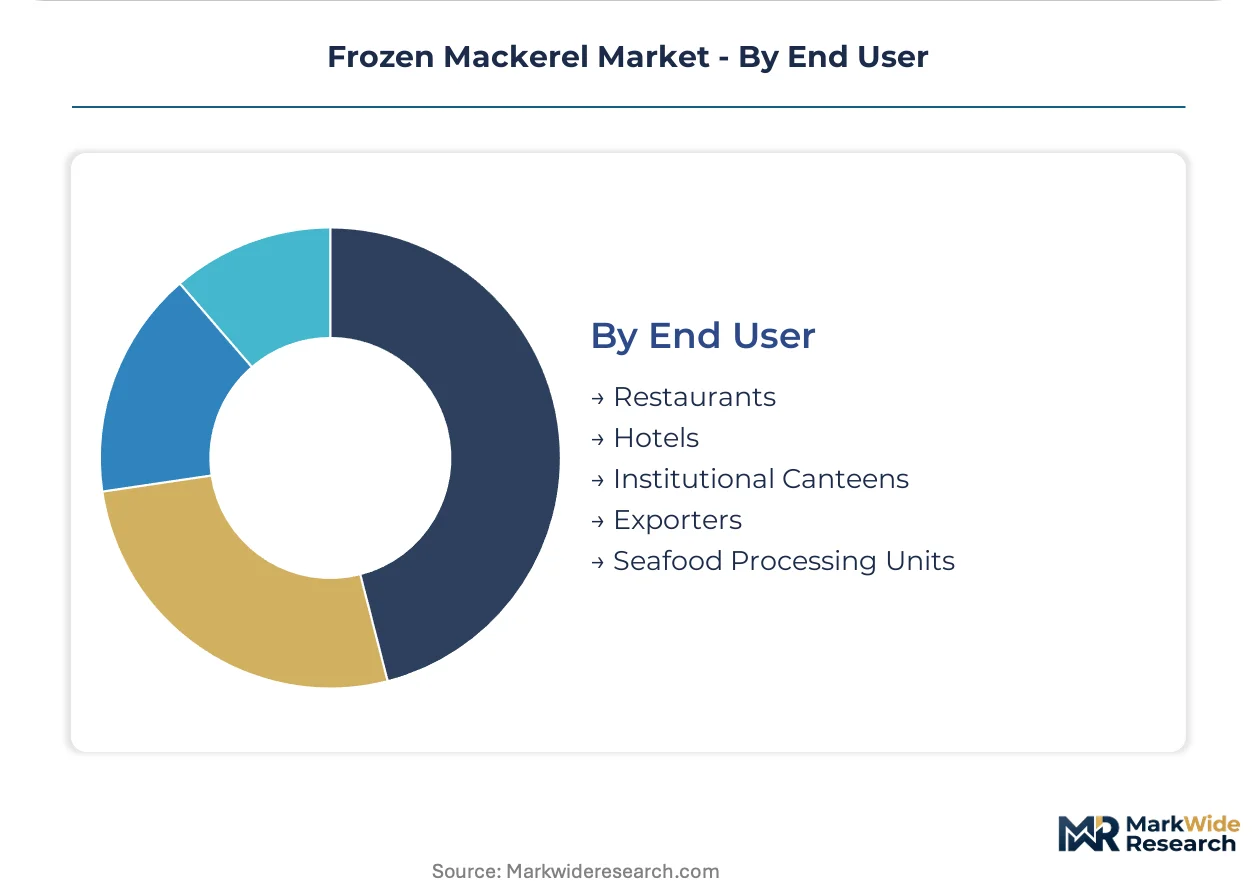
End User:
End-user categories reflect distinct procurement sophistication and contract structures.
- Restaurants:Independent and chain operators requiring consistent portion sizes and delivery frequency. Japanese izakaya chains and Southeast Asian hotel restaurants are expanding frozen mackerel menu placements.
- Hotels:Full-service properties with banquet and room service operations. Their procurement favors premium fillet grades with verified sustainability credentials.
- Institutional Canteens:Corporate, school, and hospital feeding operations with cost-minimization mandates. Nissui Corporation maintains long-term supply contracts with this segment in Japan.
- Exporters:Trading companies re-exporting to third markets with documentation-heavy requirements. EU IUU fishing controls and catch certificates filter participation to certified fleet operators.
- Seafood Processing Units:Surimi manufacturers and canneries with dedicated freezing and storage infrastructure. Direct procurement from distant-water fleets is displacing auction-house spot purchasing.
Seafood processing units dominate throughput; institutional canteens offer steadiest contract visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan consumes frozen mackerel at volumes that dwarf Norwegian household penetration, while Vietnam's foodservice sector is expanding cold chain infrastructure at faster absolute rates than established European markets.
Japan
Institutional canteens and processed seafood exporters sustain procurement volumes through long-term supply contracts. The Food Sanitation Act and JIS standards govern residual histamine limits and processing hygiene for domestic distribution. Tokyo's Tsukiji-adjacent trading community is witnessing intermediary commission structures erode as surimi manufacturers establish direct fleet relationships.
Norway
Premium smoked frozen mackerel formats command positioning in European deli retail channels. EU F-Gas Regulation phase-down schedules are forcing cold chain operators to retrofit refrigeration systems with lower-global-warming-potential alternatives. Nordic port storage operators are accelerating ammonia-CO2 cascade system deployments.
Vietnam
Hotels and restaurant chains across Southeast Asia are adding frozen mackerel to seafood offerings, driving procurement volumes from local processors. The country's national food safety regulator enforces HACCP-aligned standards for export eligibility. Ho Chi Minh City-based cold chain hubs are consolidating blast freezing capacity and port storage into integrated platforms.
Thailand
Surimi and processed seafood manufacturers are expanding offtake agreements with North Pacific fleets for minced mackerel specifications. National fisheries authorities align with regional fisheries management organization quota protocols for import certification. Bangkok-centered procurement networks are displacing traditional auction-house spot purchasing through multi-year contracts.
India
Organized retail chains in Mumbai and Chennai are expanding frozen seafood sections, creating first-mover positioning for cold chain-equipped suppliers. FSSAI standards govern import hygiene and labeling requirements for frozen fish distribution. Metropolitan e-grocers are building last-mile frozen logistics capabilities in underpenetrated urban markets.
Frozen Mackerel Market Competitive Landscape
Top-tier vendors anchor vessel-to-retail integration, while mid-scale processors compete through specialized surimi supply relationships. Fleet operators with documented catch certificates are capturing share as EU IUU fishing controls filter non-compliant suppliers. Three archetypes dominate: integrated distant-water operators controlling blast freezing capacity, regional procurement specialists serving institutional canteens, and surimi-focused processors securing functional protein inputs. Competitive moves concentrate on direct offtake agreements displacing auction intermediaries, and cold chain monitoring subscriptions generating recurring revenue beyond commodity margins.
Among integrated distant-water operators, Maruha Nichiro Corporation exemplifies the vessel-to-retail archetype through North Pacific coverage. Nissui Corporation occupies a position within the institutional supply tier, anchoring long-term contract visibility with Japanese canteen networks. Thai Union Group represents the scaled procurement archetype, with Southeast Asian water networks supporting foodservice expansion across the region.
| Leading Market Players |
|---|
| Maruha Nichiro Corporation |
| Nissui Corporation |
| Thai Union Group |
| Ocean Treasure World Foods |
| Austevoll Seafood ASA |
| Leroy Seafood Group ASA |
| FCF Fishery Co. Ltd. |
| Pelagia AS |
| Hottlet Frozen Foods NV |
| Others |
Supply & Pricing Matrix
EU IUU fishing control mandates for documented catch certificates are forcing distant-water fleets to consolidate around certified operators, compressing spot-market liquidity and elevating contract premiums for compliant supply. Japanese institutional canteens and surimi manufacturers are responding with multi-year offtake agreements that lock in volume commitments and reduce price volatility exposure.
Pricing Analysis
Capacity additions in Vietnam and Thailand are reshaping price floors for frozen mackerel fillets and minced grades. Three-tier pricing structure across premium certified, standard compliant, and economy spot tiers reflects differentiation by catch documentation completeness and cold chain custody rigor. Cost compression in economy spot tiers is intensifying because non-certified fleet operators face exclusion from EU and Japanese procurement channels. Institutional canteens exhibit highest price sensitivity due to volume scale and budget rigidity, while European deli retailers show least sensitivity for smoked premium formats.
Supply Chain Analysis
Blast freezing equipment supply rests on Japanese and Nordic engineering specialists with ammonia-CO2 cascade system expertise. The frozen mackerel supply chain draws from North Pacific distant-water fleets, Vietnamese coastal processors, and Thai surimi manufacturers as primary concentration points. Marine diesel, cryogenic gases, and food-grade packaging films constitute critical input dependencies. Single-source vulnerability in qualified refrigeration technician pools across Southeast Asian hubs poses structural risk. Distribution runs through integrated vessel-to-retail platforms controlling port storage and last-mile cold chain custody.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The frozen mackerel market functions as a stable compounder anchored by recurring institutional procurement and surimi processor demand for functional protein inputs. Long-term supply contracts with foodservice distributors and processed seafood manufacturers sustain volume visibility through cyclical catch fluctuations.
For Market Incumbents: Acquire blast freezing and controlled atmosphere storage assets in Vietnamese and Indian port zones to secure capacity ahead of foodservice expansion. Deepen backward integration into distant-water fleet operations to capture margin compression from auction intermediary displacement. Defend against surimi manufacturer direct procurement threats by embedding subscription-based cold chain monitoring services that generate recurring revenue and switching costs. For New Entrants and Emerging Players: Enter via underpenetrated Indian organized retail and e-grocer channels in Mumbai and Chennai metropolitan markets where cold chain infrastructure gaps create first-mover positioning. Target minced mackerel supply relationships with Thai and South Korean surimi processors seeking functional protein inputs outside established North Pacific fleet networks. Build go-to-market credibility through IoT-enabled temperature logging systems that satisfy Japanese supermarket blockchain documentation mandates. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated distant-water operators possessing documented catch certificates and blast freezing capacity under EU IUU compliance frameworks. Five-to-ten year viability hinges on quota allocation stability under regional fisheries management organizations and cold chain energy cost trajectories. Monitor F-Gas Regulation retrofit timelines and ammonia-CO2 cascade system deployment rates as inflection signals for margin sustainability in European storage and processing assets.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Fleet Procurement Agreements | Surimi manufacturers in Thailand bypass auction intermediaries to secure minced mackerel volumes. |
| Cold Chain Monitoring Subscriptions | Foodservice distributors monetize IoT-enabled logistics relationships beyond commodity margins. |
| Refrigeration System Retrofit | EU F-Gas Regulation phase-down forces ammonia-CO2 cascade adoption in Nordic blast freezing facilities. |
| Blockchain Traceability Integration | Japanese supermarket chains mandate platform participation for frozen mackerel contract eligibility. |
| Indian Retail Channel Expansion | Mumbai and Chennai e-grocers build last-mile frozen logistics in underpenetrated metropolitan markets. |
Research Methodology
Multiple input streams — primary interviews with distant-water fleet operators, surimi procurement directors, and cold chain logistics managers; secondary validation through customs trade databases, regional fisheries management organization quota filings, and SEC disclosures from integrated seafood conglomerates; plus bottom-up and top-down triangulation — were reconciled to construct market estimates. Vessel catch documentation systems, blast freezing capacity registries, and foodservice distributor contract structures provided granular segmentation inputs.
Data-stream reconciliation across product type, distribution channel, application, and end-user dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from modeled volume and value trajectories reflecting catch quota allocations, cold chain infrastructure buildout rates, and foodservice menu expansion patterns. Fuel cost volatility curves and histamine regulatory compliance thresholds informed scenario boundaries.
The model holds under stable quota allocations and cold chain energy cost trajectories; deviation in regional fisheries management organization harvest rights reallocation or marine diesel price spikes would shift volume and value outputs. Forecasts reflect documented assumptions about fleet certification penetration and blast freezing capacity expansion timing. A small set of named triggers — F-Gas Regulation enforcement intensity, Indian retail cold chain investment rates, and surimi processor direct procurement adoption — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Tart Shells Market
Processed and Frozen Foods
Frozen Meat Grinder Market
Processed and Frozen Foods
Turkey Cold Storage Market
Processed and Frozen Foods
GCC Frozen Fruits and Vegetables Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
South America Frozen Food Market
Processed and Frozen Foods
Frozen Yogurt Market
Processed and Frozen Foods
Global Chilled and Deli Foods Market
Processed and Frozen Foods
Cold Storage Market
Processed and Frozen Foods
Europe Ice Cream Market
Processed and Frozen Foods
Frozen Fruit Bars Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
Frozen Snacks Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market
Processed and Frozen Foods
Frozen Cheese Market
Processed and Frozen Foods
Frozen Pork Belly Market