
 Low-Fat Cool Whip Market | 2026-2036
Low-Fat Cool Whip Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Fat Cool Whip Market Analytics
The capital-intensity divergence between fully integrated dairy processors and contract-manufactured private labels is rotating competitive advantage toward players with captive cream supply. The Kraft Heinz Company leverages its branded formulation heritage and frozen distribution infrastructure to sustain premium positioning in tub and aerosol formats. Conagra Brands anchors its Reddi-wip portfolio through dairy-alternative R&D pipelines that compete directly on fat-reduction claims. Rich Products Corporation specializes in foodservice-scale production, occupying institutional channels where volume contracts dominate purchasing decisions.
Low-fat Cool Whip denotes an aerated, emulsified dessert topping containing reduced milk fat content, typically stabilized with polysorbate 80, sorbitan monostearate, and hydrocolloid gums to maintain overrun structure at sub-ten-percent fat levels. The product functions primarily as a convenience-driven pie topping, fruit dip base, and beverage garnish across retail and foodservice environments. Whipped topping formulations lead volume within product type segments due to their longer ambient stability and lower dairy input costs, while sugar-free versions are gaining fastest as diabetic-friendly and keto-aligned diets expand. Tub packaging dominates household purchases for controlled portioning, though single-serve cups are capturing incremental share in convenience stores and institutional meal kits where grab-and-go formats reduce waste.
The FDA governs low-fat labeling thresholds and trans fat disclosure requirements, while the USDA oversees Grade A dairy ingredient standards that constrain reformulation pathways for dairy-based variants. State-level dairy compacts in Wisconsin and California further complicate interstate sourcing economics for manufacturers without multi-state processing licenses. Stakeholders must monitor evolving clean-label enforcement at FDA and shifting retail buyer specifications at Kroger and Walmart, as these channel gatekeepers increasingly mandate front-of-pack ingredient transparency that exceeds federal minimums.
Market Dynamics
Reformulation mandates from the FDA's updated nutrition labeling requirements are compressing margins across the low-fat whipped topping category while simultaneously accelerating clean-label R&D investments among dairy processors and emulsion specialists.
Growth Catalysts
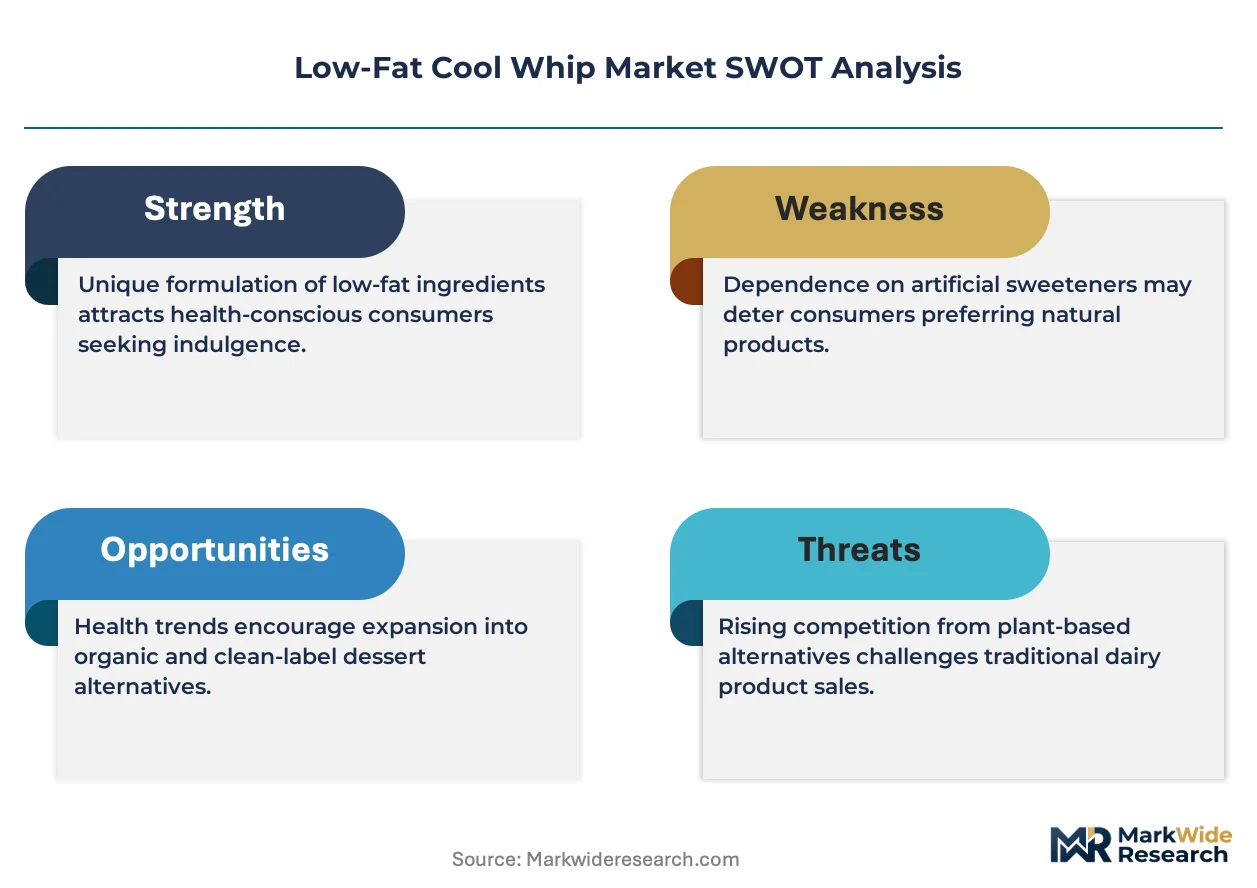
- FDA Trans Fat Restrictions:The agency's tightened disclosure thresholds for partially hydrogenated oils are compelling manufacturers to eliminate legacy emulsifiers, opening procurement contracts for polysorbate 80 and sorbitan monostearate alternatives.
- Diabetic-Friendly Diet Expansion:Sugar-free whipped topping variants are capturing shelf space as keto-aligned and glycemic-conscious consumers reject traditional high-sugar dessert garnishes in favor of reduced-carbohydrate substitutes.
- Foodservice Institutional Contracts:Hospital cafeterias, K-12 meal programs, and senior living facilities are standardizing low-fat toppings to meet USDA sodium and saturated fat guidelines for federally subsidized meal service.
Market Restraints
- Cream Supply Concentration:Wisconsin and California dairy compacts control Grade A fluid cream allocation, forcing out-of-region manufacturers to absorb interstate transport premiums or accept inferior non-Grade A inputs that compromise overrun stability.
- Hydrocolloid Price Volatility:Guar gum and carrageenan sourcing from India and Chilean seaweed harvesters exposes formulation costs to monsoon-driven supply interruptions and marine ecosystem regulatory closures.
- Clean-Label Technical Ceiling:Removing polysorbate 80 degrades freeze-thaw stability in tub formats, limiting ambient distribution reach for reformulated products and confining them to refrigerated cold chains with higher logistics burn.
Strategic Opportunities
- Single-Serve Convenience Channel:Grab-and-go cup formats for meal-kit assembly and convenience store dessert sections remain underdeveloped relative to household tub penetration, offering first-mover positioning.
- Aerosol Dairy-Alternative Convergence:Coconut cream and oat base emulsions combined with nitrous oxide propellant systems enable vegan fat-reduction claims that bypass traditional dairy input constraints entirely.
- Private-Label Transparency Mandates:Walmart and Kroger front-of-pack ingredient specifications exceed FDA minimums, creating supplier certification premiums for compliant manufacturers willing to disclose full hydrocolloid sourcing.
Industry Challenges
- Emulsion Chemistry Talent Scarcity:Food science programs produce fewer specialists in aerated fat-structure stabilization than industry retirements demand, lengthening product development cycles for reformulated clean-label variants.
- Multi-State Dairy Licensing Complexity:Captive cream supply requires separate processing permits in Wisconsin, California, and New York, each with distinct inspection cadences and fluid milk grading standards that delay regional scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Fat Cool Whip Market |
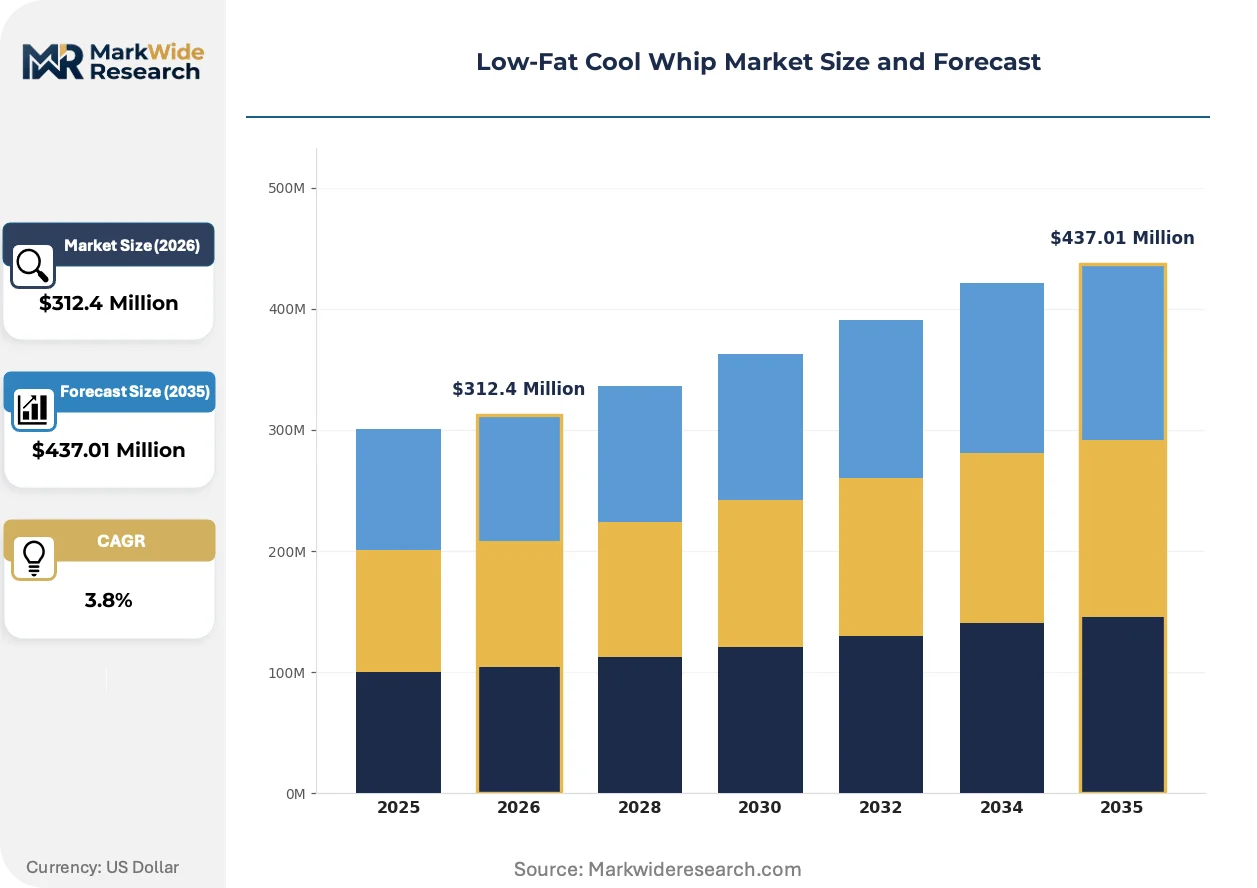
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $437.01 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whipped Topping, Dairy Cream, Non-Dairy Option, Sugar-Free Version Packaging Type: Tub, Squeeze Bottle, Carton, Single-Serve Cups Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops End User: Households, Cafes, Restaurants, Bakeries |
| Companies Covered | The Kraft Heinz Company (Cool Whip), Conagra Brands (Reddi-wip), Land O'Lakes, Walmart (Great Value), Kroger, Rich Products Corporation, FrieslandCampina (Debic), Fonterra (Anchor), Lactalis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Fat Cool Whip Market Evolving Landscape
Ingredient transparency mandates and alternative protein emulsion technologies are restructuring competitive advantage away from heritage dairy formulations toward biotechnology-enabled fat mimics and plant-derived stabilizer systems.
Precision fermentation-derived milk proteins from Perfect Day and similar suppliers are displacing conventional Grade A cream in premium whipped topping formulations. Bakery and dessert manufacturers in the Pacific Northwest are piloting these inputs at 15-20% cost premiums to secure vegan-label eligibility. The technology is displacing traditional dairy procurement contracts in institutional channels where allergen-free claims determine vendor selection.
The FDA's 2023 updated guidance on "healthy" nutrient content claims restricts saturated fat thresholds for front-of-pack labeling eligibility. Reformulated low-fat Cool Whip variants must now demonstrate less than 5% calories from saturated fat to qualify, compressing permissible butterfat inputs and accelerating hydrocolloid substitution rates. Frozen dessert and pie topping segments are responding with accelerated clean-label R&D timelines to maintain retail placement.
Retail buyer consolidation at Walmart and Kroger is compressing supplier negotiation leverage and mandating outcome-based shelf performance metrics. Smaller regional whipped topping brands now face delisting thresholds tied to velocity-per-sku-week minimums that favor national distribution scale. This concentration is most visible in the Midwest and Southeast retail corridors where private-label penetration has already exceeded branded volume in tub formats.
Low-Fat Cool Whip Market Segmentation
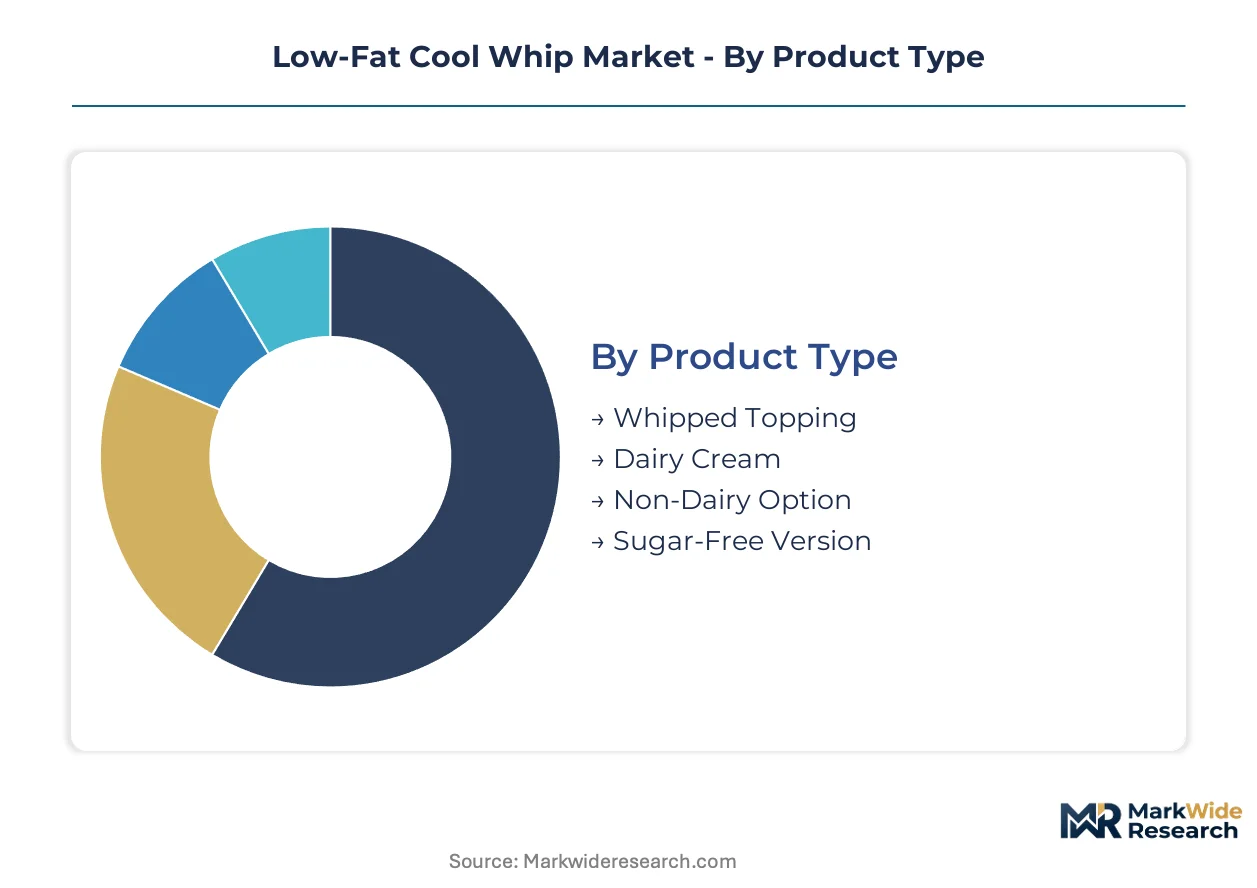
Segmentation in low-fat whipped toppings reveals how reformulation pressures and channel access determine manufacturer profitability. Each dimension—product chemistry, packaging format, route to market, and end-use application—creates distinct margin profiles and regulatory exposure.
Product Type:
Channel-mix dynamics concentrate volume through retail grocery for ambient-stable formats while foodservice procurement favors refrigerated dairy-based variants with shorter ingredient decks.
- Whipped Topping:Aerated emulsions stabilized with polysorbate 80 and hydrocolloid gums achieve overrun stability at sub-ten-percent fat levels. Households in the United States drive baseline volume through tub purchases for pie garnishing and fruit dipping applications.
- Sugar-Free Version:Reformulated with alternative sweeteners to meet diabetic-friendly and keto-aligned dietary requirements. United States retail buyers at Kroger and Walmart are expanding shelf space allocation as glycemic-conscious consumers reject traditional high-sugar dessert toppings.
- Dairy Cream:Grade A fluid cream inputs constrained by Wisconsin and California dairy compacts.
- Non-Dairy Option:Coconut cream and oat base emulsions bypassing traditional dairy input constraints.
Whipped topping dominates installed base. Sugar-free version is where expansion concentrates.
Packaging Type:
Cost tier stratification separates premium aerosol systems from economy tub formats, with mid-tier squeeze bottles capturing incremental convenience-store volume.
- Tub:Polypropylene containers with resealable lids enable controlled portioning for household dessert preparation. United States households favor this format for refrigerated storage stability and multi-use flexibility across pie toppings and beverage garnishes.
- Single-Serve Cups:Polypropylene portion cups designed for grab-and-go meal-kit assembly and institutional meal programs. Convenience stores and senior living facilities in the United States are standardizing these formats to reduce waste and meet USDA sodium guideline compliance.
- Squeeze Bottle:LDPE bottles with flip-top dispensing for controlled drizzle applications.
- Carton:Gable-top paperboard for foodservice bulk dispensing.
Tub packaging dominates installed base. Single-serve cups represent the fastest-growing trajectory.
Distribution Channel:
Customer-type concentration splits between price-sensitive retail procurement and specification-driven foodservice contracting, with emerging direct-to-consumer routes testing subscription models.
- Supermarkets:Primary volume channel where private-label competition and health-conscious retail buyers reshape shelf space allocation. Kroger and Walmart front-of-pack ingredient specifications exceed FDA minimums, creating supplier certification premiums for compliant manufacturers.
- Online Retail:E-commerce platforms enabling direct-to-household fulfillment of specialty and subscription formats. Keto-aligned consumers in the United States are migrating toward online channels for sugar-free variant access unavailable in conventional grocery.
- Convenience Stores:Grab-and-go formats for immediate consumption and travel occasions.
- Specialty Shops:Gourmet and organic-positioned retailers with clean-label mandates.
Supermarkets dominate installed base. Online retail is climbing the fastest.
End User:
Application-mix variation separates indulgence-driven household consumption from institutional procurement governed by federal nutrition guidelines.
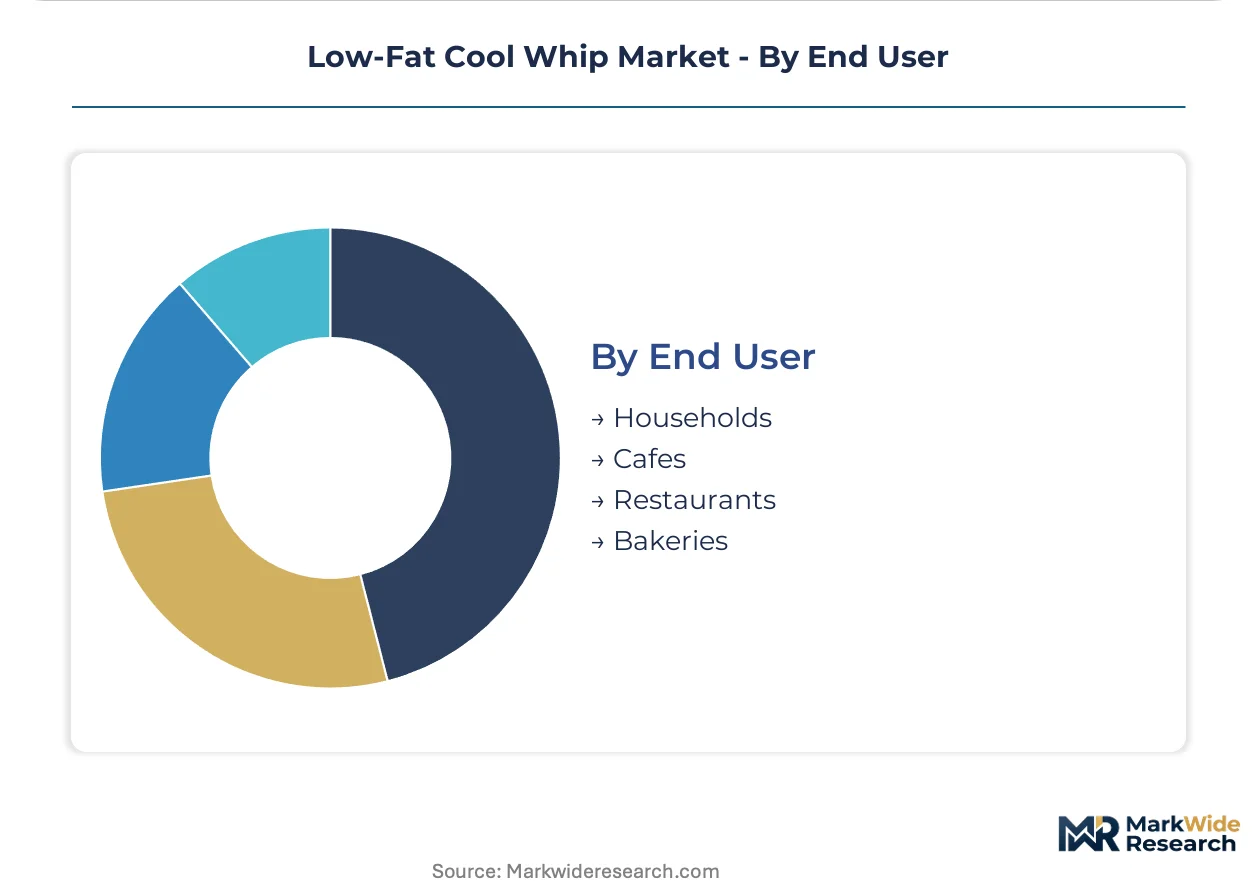
- Households:Convenience-driven consumers prioritizing reduced-calorie indulgences for home dessert preparation. United States households represent baseline demand for tub and aerosol formats across pie topping and fruit dip applications.
- Bakeries:Commercial dessert manufacturers requiring volume-scale whipped topping with consistent overrun performance. United States bakeries are expanding procurement of low-fat variants as reformulation pressures from FDA trans fat restrictions compress permissible ingredient decks.
- Restaurants:Full-service operators balancing portion cost with plate presentation requirements.
- Cafes:Coffee-focused operators utilizing toppings for beverage garnish differentiation.
Households dominate installed base. Bakeries are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Wisconsin and California dairy compacts, while out-of-region manufacturers absorb interstate transport premiums or accept inferior non-Grade A inputs. This asymmetry compresses margins for processors without captive cream supply while reinforcing the dominance of vertically integrated dairy cooperatives.
United States
Household demand for reduced-calorie indulgences drives baseline volume through tub and aerosol formats. FDA trans fat restrictions and updated nutrition labeling requirements compel reformulation toward cleaner ingredient decks. Chicago and Midwest dairy processing clusters anchor production capacity for national distribution.
Germany
EFSA clean-label enforcement and REACH chemical registration requirements accelerate hydrocolloid substitution in aerated emulsion formulations. Bavarian and North Rhine-Westphalian dairy processors specialize in precision fermentation-derived fat mimics for export markets. Private-label penetration in discounters reshapes shelf space allocation toward transparency-certified suppliers.
France
Gourmet dessert culture sustains premium positioning for dairy-alternative whipped toppings in patisserie channels. ANSM and DGCCRF monitor front-of-pack ingredient disclosure exceeding EU baseline requirements. Île-de-France and Auvergne-Rhône-Alpes food technology clusters pilot oat base and coconut cream emulsion systems.
United Kingdom
Keto-aligned and diabetic-friendly diet expansion propels sugar-free variant demand through online retail channels. Food Standards Agency enforcement of allergen labeling creates procurement premiums for vegan-certified manufacturers. Greater London and Midlands distribution hubs concentrate foodservice contract fulfillment for institutional meal programs.
Japan
Convenience store grab-and-go formats capture incremental share through single-serve cup packaging for controlled portioning. METI and Consumer Affairs Agency standards for functional food claims constrain fat-reduction marketing language. Kanto and Kansai metropolitan areas concentrate R&D investment in aerated emulsion stability technologies.
Low-Fat Cool Whip Market Competitive Landscape
Concentration sits with heritage branded manufacturers and captive-supply dairy cooperatives, while private-label contract manufacturers compete on transparency certification. The vendor base stratifies across three tiers: multinational CPG conglomerates with frozen distribution infrastructure, regional dairy processors with Grade A fluid cream allocation, and emerging biotechnology-enabled fat mimic specialists. Dominant competitive moves include strategic partnerships with precision fermentation suppliers and geographic expansion through multi-state dairy licensing.
Within the branded CPG tier, The Kraft Heinz Company and Conagra Brands exemplify formulation heritage and aerosol format dominance. Rich Products Corporation anchors foodservice-scale production with institutional channel specialization. These three entities occupy positions spanning retail grocery, convenience store, and federally subsidized meal program procurement.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Conagra Brands |
| Land O'Lakes |
| Walmart |
| Kroger |
| Rich Products Corporation |
| FrieslandCampina |
| Fonterra |
| Lactalis |
| Others |
Value Network & Pricing Analysis
Precision fermentation-derived milk proteins displacing Grade A fluid cream are redrawing procurement geography toward biotechnology suppliers in California and the Pacific Northwest while compressing legacy dairy-based pricing premiums. This substitution simultaneously elevates input costs for clean-label formulations and fragments volume discounts previously anchored to Wisconsin and California dairy cooperative contracts.
Pricing Analysis
The customization-premium spread between standard tub formats and certified clean-label variants reaches its widest point in aerosol dairy-alternative offerings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with private-label transparency mandates at Walmart and Kroger compressing mid-tier margins. Pricing pressure stems from hydrocolloid price volatility and reformulation R&D burn, with foodservice institutional buyers exhibiting highest price sensitivity due to federal meal program reimbursement caps.
Supply Chain Analysis
Inventory lead times for polysorbate 80 alternatives and sorbitan monostearate replacements have extended as FDA trans fat restrictions eliminate legacy emulsifier stocks. Supply concentrates in Wisconsin and California for Grade A fluid cream, with India and Chile anchoring guar gum and carrageenan sourcing. Single-source vulnerability sits with monsoon-driven guar harvests and marine ecosystem regulatory closures. Distribution runs through frozen and refrigerated cold chains to retail grocery and foodservice institutional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where formulation consulting and clean-label certification support expand faster than base product volume. Recurring revenue from supplier certification premiums at Kroger and Walmart outpaces commodity tub sales growth.
For Market Incumbents: Consolidate captive cream supply through multi-state dairy licensing in Wisconsin, California, and New York to defend against precision fermentation entrants. Lock in aerosol format dominance through nitrous oxide propellant system partnerships. Channel control at institutional foodservice represents the critical defensive lever against private-label contract manufacturers. For New Entrants and Emerging Players: Clean-label technical consulting where incumbents under-serve offers immediate white-space access. Target single-serve cup formats in convenience stores and meal-kit assembly channels where grab-and-go penetration remains underdeveloped. Pursue direct-to-consumer online retail for sugar-free variants with keto-aligned subscription models as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturers holding Walmart and Kroger transparency certifications but lacking captive dairy supply. Five-to-ten year viability hinges on biotechnology-enabled fat mimic adoption curves. Watch precision fermentation cost parity with Grade A cream as the inflection signal for portfolio rebalancing toward dairy-alternative specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Partnership | Precision fermentation suppliers like Perfect Day enable FDA-compliant saturated fat thresholds for front-of-pack "healthy" claims. |
| Multi-State Dairy Licensing Expansion | Separate processing permits in Wisconsin, California, and New York secure Grade A fluid cream allocation against cooperative concentration. |
| Single-Serve Cup Format Launch | Polypropylene portion cups capture convenience store and institutional meal-kit channels where grab-and-go formats reduce waste. |
| Aerosol Dairy-Alternative Convergence | Coconut cream and oat base emulsions with nitrous oxide propellants bypass traditional dairy input constraints entirely. |
| Transparency Certification Investment | Walmart and Kroger front-of-pack ingredient specifications exceeding FDA minimums create supplier premiums for compliant manufacturers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with bakery procurement managers, dessert manufacturer R&D directors, foodservice contract specialists, and retail category buyers at Kroger and Walmart. Secondary validation drew from FDA nutrition labeling guidance, USDA Grade A dairy standards, customs records for hydrocolloid imports, and SEC filings from CPG conglomerates. Bottom-up volume modeling triangulated against top-down category sizing from retail audit databases.
Across the analysis window, forecasts employed product chemistry segmentation by whipped topping, sugar-free, dairy cream, and non-dairy variants crossed with packaging format and distribution channel dimensions. CAGRs derived from trend extrapolation of diabetic-friendly diet expansion, institutional procurement standardization, and clean-label enforcement trajectories. Industry-specific inputs included precision fermentation adoption curves and multi-state dairy licensing completion rates.
Underlying assumptions cover sustained FDA trans fat restriction enforcement and stable hydrocolloid supply from India and Chile, with deviation risk concentrated in monsoon-driven guar gum harvest failures and marine ecosystem regulatory closures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
French Fries Market
Processed and Frozen Foods
Processed and Frozen Fruits Market
Processed and Frozen Foods
Latin America Frozen Finger Chips Market
Processed and Frozen Foods
United States Frozen Yogurt Market
Processed and Frozen Foods
South America Frozen Desserts Market
Processed and Frozen Foods
Frozen Processed Food Market
Processed and Frozen Foods
Ice Structuring Protein Market
Processed and Frozen Foods
Frozen Snacks Market
Processed and Frozen Foods
North America French Fries Market
Processed and Frozen Foods
Turkey Cold Storage Market
Processed and Frozen Foods
Frozen Potato Market
Processed and Frozen Foods
Ice Cream and Frozen Dessert Market
Processed and Frozen Foods
Frozen Bread Market
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Germany Frozen Snack Market