
 South America Frozen Food Market | 2026-2036
South America Frozen Food Market Size, Share, and Industry Trends Forecast 2026-2036
South America Frozen Food Market Analytics
Aftermarket cold-chain logistics revenue is rewriting margin distribution across the South America frozen food value chain. McCain Foods Limited leverages its potato processing specialization to dominate Brazil's frozen vegetable segment. BRF SA anchors its position through backward integration into poultry sourcing, controlling feed-to-freezer quality. Nestlé S.A. differentiates via brand strength in frozen ready-meal categories across Argentine urban markets.
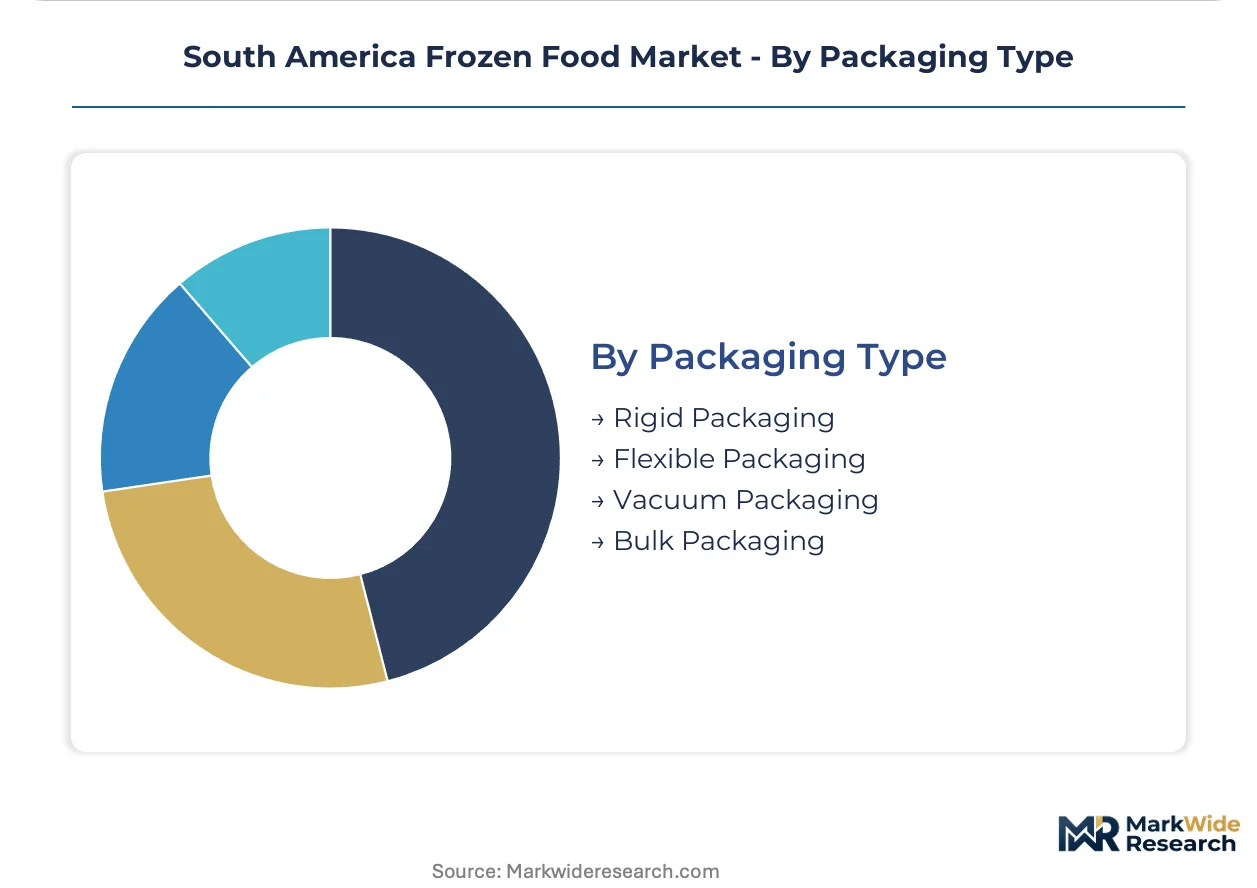
Frozen food encompasses products preserved through rapid temperature reduction to minus 18 degrees Celsius or below, maintaining cellular structure via flash-freezing techniques that inhibit microbial activity and enzymatic degradation. The primary commercial purpose centers on extending shelf life while retaining nutritional content, enabling year-round distribution of seasonal produce and proteins across distant retail and foodservice endpoints. Frozen meat commands the largest revenue pool within product type segmentation, sustained by Brazil's beef and poultry export infrastructure. Online retail distribution channels represent the fastest-expanding access route, accelerated by last-mile refrigeration investments in Colombian and Chilean metropolitan zones. Rigid packaging retains volume leadership in packaging type segmentation, though vacuum packaging captures premium margin pools through extended shelf-life claims.
Brazil's national food safety regulator ANVISA mandates HACCP compliance across frozen food manufacturing facilities, elevating capital requirements for market entry. Argentina's national food safety authority enforces frozen product labeling standards that disclose blast-freezing dates and temperature maintenance records. Chile's Ministry of Health applies cold-chain certification requirements for imported frozen seafood. Stakeholders must monitor evolving Mercosur harmonization negotiations, as unified sanitary standards would reshape cross-border frozen product flows and facility certification costs across the trade bloc.
Market Dynamics
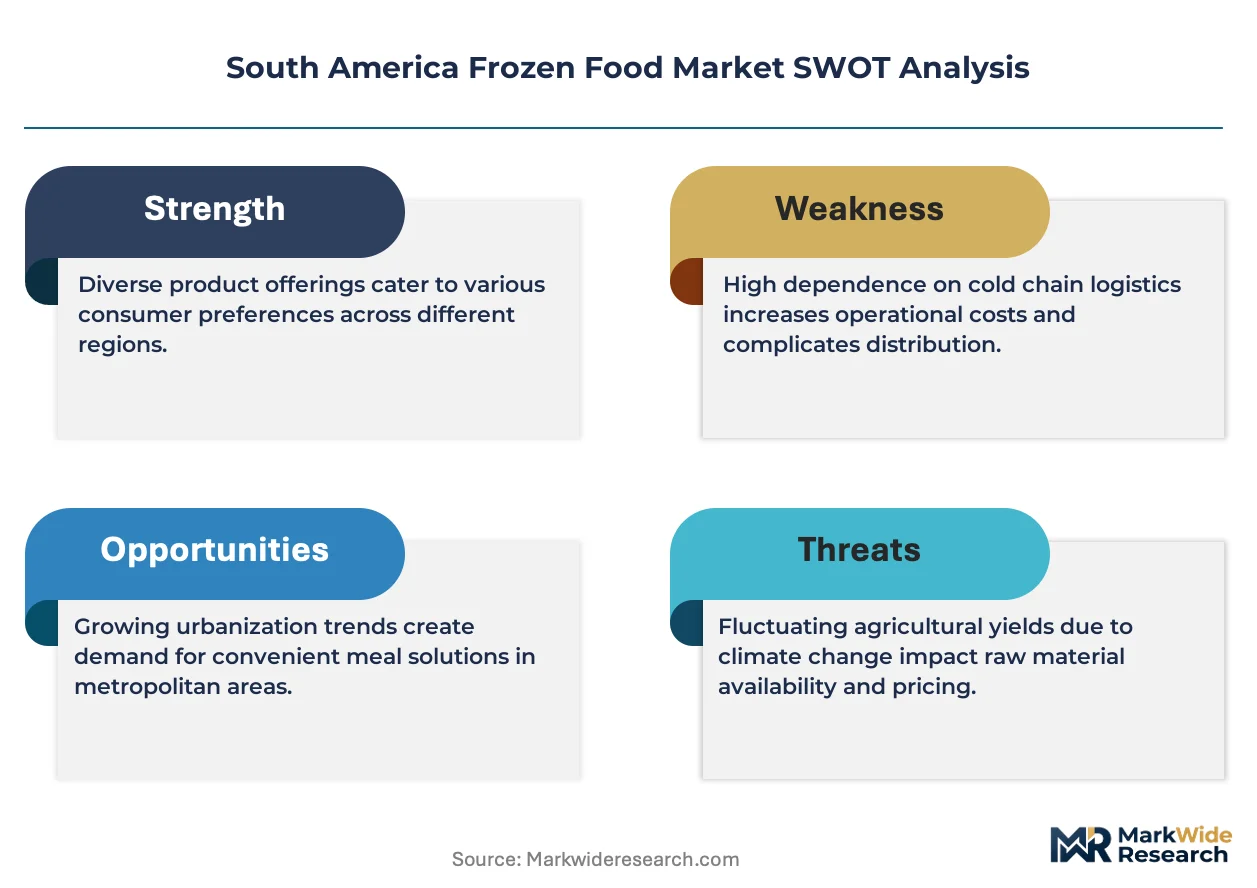
Cold-chain infrastructure modernization is redistributing margin capture across the South America frozen food value chain, as aftermarket logistics providers extract premium returns from temperature-controlled last-mile delivery networks.
Growth Catalysts
- ANVISA HACCP Mandates:Brazil's food safety regulator enforces hazard analysis protocols across manufacturing facilities, accelerating facility consolidation among compliant processors.
- Quick-Service Restaurant Expansion:Brazilian fast-food chains are scaling frozen ingredient procurement to standardize quality across multi-state franchise networks.
- Blast-Freezing Equipment Upgrades:Argentine processors are retrofitting production lines with rapid temperature reduction systems to meet export-grade cellular preservation standards.
Market Restraints
- Energy Cost Volatility:Cold storage facilities face margin compression from diesel-powered refrigeration backup systems during grid instability events.
- Import Concentration Risk:Chilean frozen seafood distributors depend on single-source Pacific corridor shipping lanes vulnerable to port congestion.
- Labeling Compliance Friction:Argentina's disclosure requirements for blast-freezing dates create inventory management complexity for cross-border traders.
Strategic Opportunities
- Colombian Metropolitan Zones:Bogotá and Medellín present underpenetrated demand for direct-to-consumer frozen meal delivery through app-based platforms.
- Vacuum Packaging Convergence:Modified atmosphere technology combined with smart labeling extends shelf-life claims for premium protein segments.
- Mercosur Harmonization Tailwind:Unified sanitary standards under negotiation would eliminate redundant certification costs for Brazilian exporters serving Argentine retail.
Industry Challenges
- Refrigeration Technician Scarcity:Cold-chain maintenance requires specialized ammonia and CO2 system expertise concentrated in São Paulo and Buenos Aires labor pools.
- Legacy ERP Integration:Temperature logging data from IoT sensors must reconcile with established inventory management platforms at Argentine distribution centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Frozen Food Market |
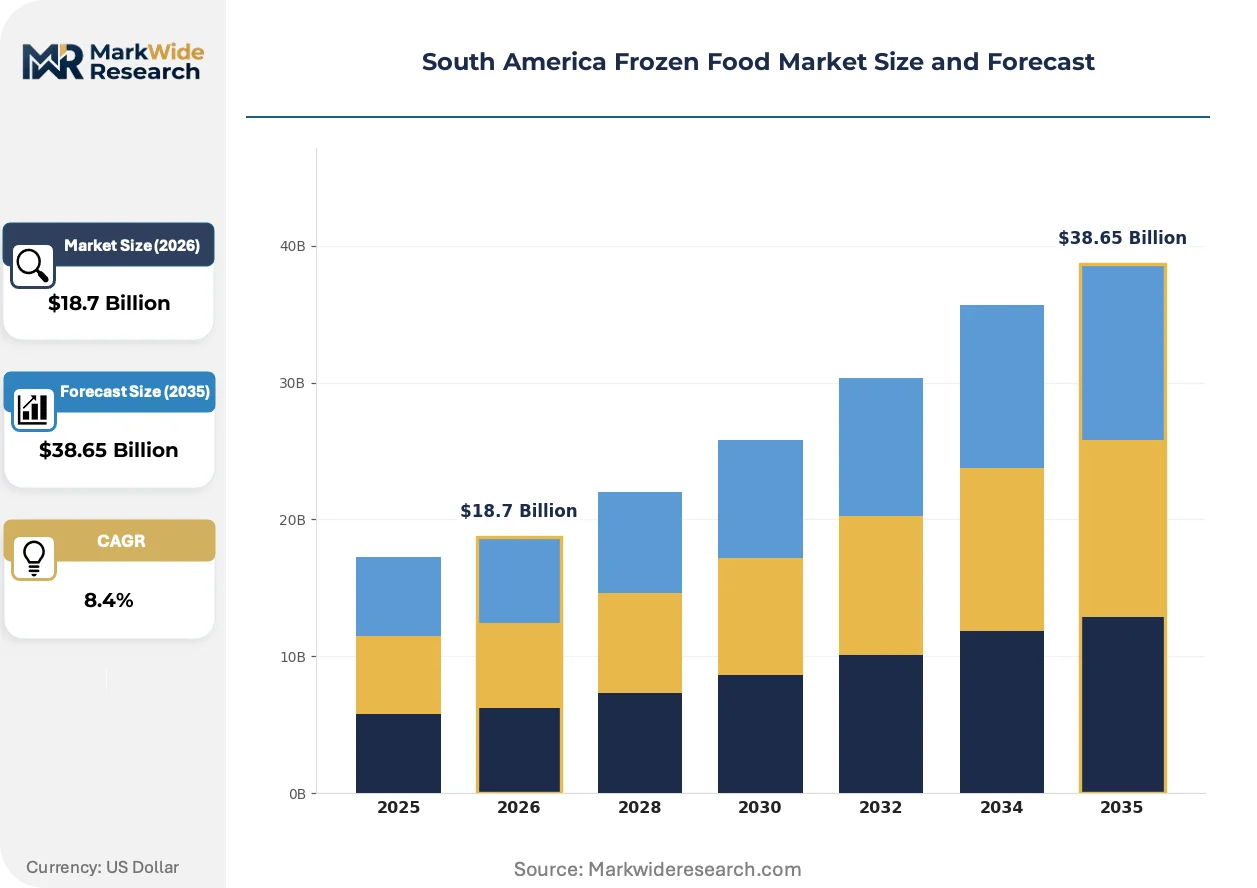
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Vegetables, Frozen Fruits, Frozen Meat, Frozen Seafood Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores End User: Households, Restaurants, Food Service, Catering Packaging Type: Rigid Packaging, Flexible Packaging, Vacuum Packaging, Bulk Packaging |
| Companies Covered | McCain Foods Limited, Unilever PLC, BRF SA, The Kraft Heinz Company, General Mills Inc., JBS SA, Tyson Foods Inc., Conagra Brands Inc., Nestlé S.A., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Frozen Food Market Evolving Landscape
Flash-freezing technology advancement and regulatory disclosure requirements are converging to reshape product positioning and facility investment priorities across the South American frozen food sector.
Individual Quick Freezing technology is migrating from bulk commodity processing to premium ready-meal manufacturing. Brazilian vegetable processors are adopting IQF tunnel systems to preserve texture in value-added side dishes. This migration from conventional blast freezing is compressing batch cycle times and enabling just-in-time production for foodservice clients.
ANVISA's cold-chain certification requirements for imported frozen proteins are tightening traceability documentation standards. Brazilian customs authorities now mandate temperature maintenance records from origin port through final distribution. Seafood importers in Santos are responding by pre-positioning bonded warehouse capacity to reduce inspection delays.
Urban dual-income households in São Paulo state are consolidating weekly grocery trips into single hypermarket visits with larger frozen category baskets. Traditional daily fresh market purchasing is yielding to monthly freezer stocking cycles among apartment-dwelling professionals. This behavioral shift concentrates demand in retail channels with dedicated frozen aisle square footage and energy-efficient display cases.
South America Frozen Food Market Segmentation
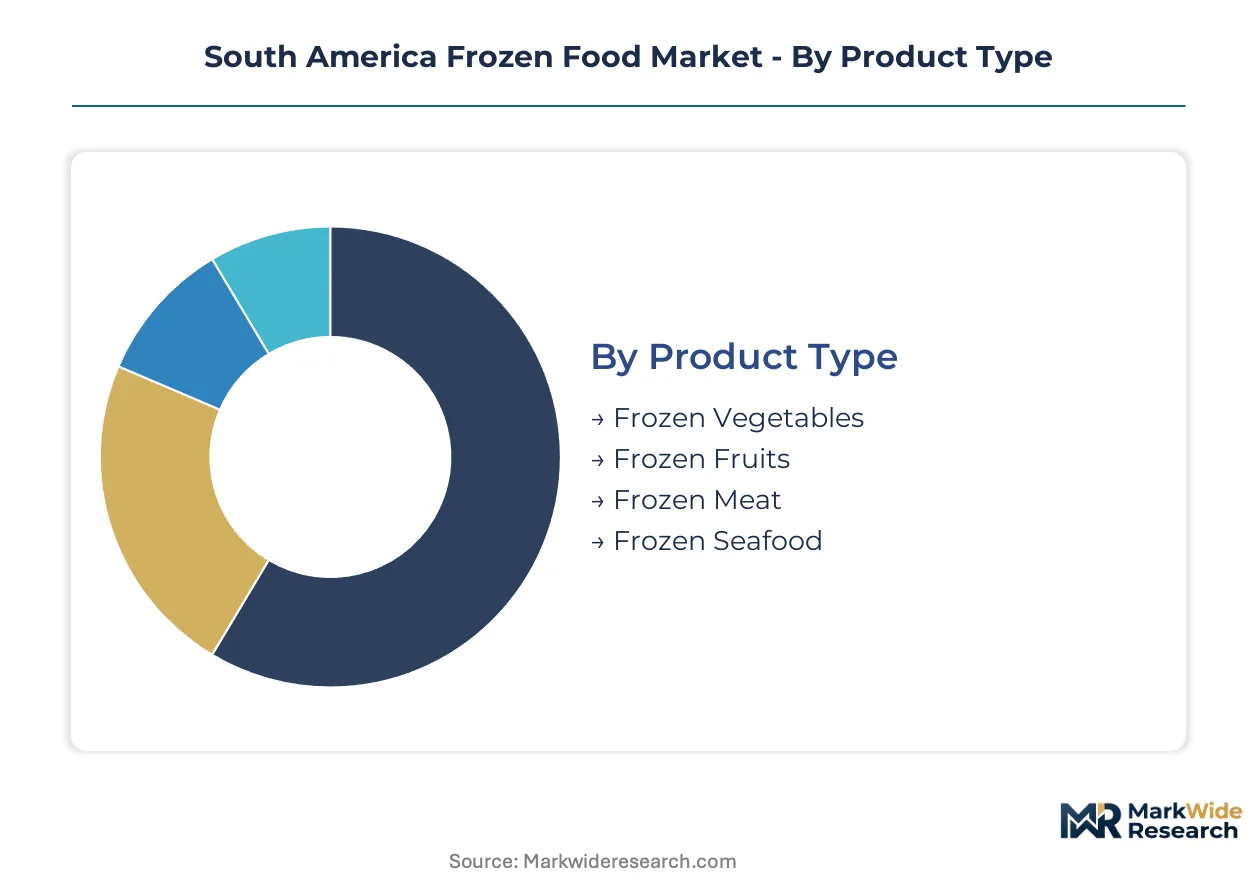
Frozen food segmentation across South America reflects divergent cold-chain maturity and consumption patterns. Product type and distribution channel splits reveal where infrastructure investment concentrates versus where behavioral shifts are opening new access routes.
Product Type:
Mature protein categories anchor revenue while emerging vegetable formats capture modernization tailwinds.
- Frozen Meat:Beef and poultry cuts preserved through blast-freezing dominate Brazilian export infrastructure and domestic retail. São Paulo state's supermarket chains allocate premium freezer aisle space to national meatpacker brands. Cold-chain reliability here determines margin capture across Mercosur trade corridors.
- Frozen Vegetables:IQF-processed broccoli, corn, and green beans are displacing conventional bulk freezing in Argentine processing plants. Brazilian quick-service restaurants are scaling procurement of pre-portioned vegetable sides to standardize kitchen operations across franchise networks.
- Frozen Fruits:Mango, açaí, and pineapple pulp concentrates serve Brazilian juice bar chains and export-oriented smoothie manufacturers.
- Frozen Seafood:Pacific-harvested hake and salmon fillets move through Chilean cold-storage hubs subject to Ministry of Health import certification requirements.
Frozen meat retains volume leadership; frozen vegetables hold the steepest expansion curve.
Distribution Channel:
Cost tier stratification separates capital-intensive retail formats from leaner last-mile models.
- Supermarkets:Hypermarket chains in São Paulo and Buenos Aires dedicate 8-12% of floor space to frozen aisles with energy-efficient display cases. Dual-income households conduct monthly freezer-stocking trips that consolidate category basket values.
- Online Retail:App-based platforms in Bogotá and Medellín are piloting direct-to-consumer frozen meal delivery through third-party cold-chain logistics partnerships. Colombian metropolitan zones present underpenetrated demand for this access route.
- Convenience Stores:Limited freezer capacity restricts assortment to high-velocity ice cream and snack items in Brazilian urban convenience networks.
- Specialty Stores:Premium protein boutiques in Argentine coastal cities cater to high-income consumers seeking traceability-certified seafood.
Supermarkets retain volume leadership; online retail holds the steepest expansion curve.
End User:
Application differentiation splits procurement patterns between inventory-heavy foodservice and convenience-driven household consumption.
- Restaurants:Brazilian fast-food chains are expanding frozen ingredient procurement to synchronize quality across multi-state franchise networks. Standardized pre-cut proteins and vegetable blends reduce kitchen labor costs.
- Households:São Paulo apartment-dwelling professionals have shifted from daily fresh market visits to weekly hypermarket trips with larger frozen category baskets.
- Food Service:Institutional cafeterias and hospital kitchens in Argentine urban centers source bulk-frozen proteins through negotiated supply contracts.
- Catering:Event-service providers in Chilean metropolitan zones combine frozen prepared appetizers with fresh garnish to manage perishability risk.
Restaurants retain volume leadership; households hold the steepest expansion curve.
Packaging Type:
Margin tier differentiation separates commodity bulk formats from premium shelf-life extension technologies.
- Rigid Packaging:Cardboard cartons and plastic trays dominate Brazilian retail freezer shelves due to stacking efficiency and brand visibility. São Paulo hypermarket chains specify standardized case dimensions for automated warehouse handling.
- Vacuum Packaging:Modified atmosphere technology captures premium margin pools in Argentine beef export segments through extended shelf-life claims. ANVISA traceability mandates favor this format's documentation compatibility.
- Flexible Packaging:Polyethylene bags serve commodity vegetable processors seeking transport cost minimization across Mercosur borders.
- Bulk Packaging:Foodservice-directed corrugated totes with gel-pack insulation support restaurant chain procurement at scale.
Rigid packaging retains volume leadership; vacuum packaging holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil consumes frozen food through quick-service restaurant procurement networks, while Argentina and Chile orient demand toward retail household stocking and export-grade seafood processing respectively.
Brazil
ANVISA enforces HACCP compliance across manufacturing facilities, consolidating processing capacity among capital-rich operators. São Paulo state's hypermarket chains dedicate premium freezer aisle space to national meatpacker brands, while quick-service restaurant chains scale frozen ingredient procurement to synchronize quality across multi-state franchise networks.
Argentina
The national food safety authority mandates blast-freezing date disclosure on frozen product labels, creating inventory complexity for cross-border traders. Buenos Aires apartment-dwelling professionals have shifted from daily fresh market visits to monthly hypermarket trips with larger frozen category baskets. Argentine processors retrofit production lines with rapid temperature reduction systems to meet export-grade cellular preservation standards.
Chile
The Ministry of Health applies cold-chain certification requirements for imported frozen seafood, concentrating distribution through Santos port pre-positioned bonded warehouse capacity. Santiago metropolitan catering providers combine frozen prepared appetizers with fresh garnish to manage perishability risk. Pacific-harvested hake and salmon fillets move through Chilean cold-storage hubs subject to stringent import documentation standards.
Colombia
Bogotá and Medellín present underpenetrated demand for direct-to-consumer frozen meal delivery through app-based platforms piloting third-party cold-chain logistics partnerships. Colombian metropolitan zones accelerate last-mile refrigeration investments that expand online retail access routes. Urban dual-income households consolidate weekly grocery trips into single hypermarket visits with larger frozen category baskets.
South America Frozen Food Market Competitive Landscape
Capability concentration sits with specialized protein processors; scale advantage sits with diversified multinational food manufacturers. The market structures around three tiers: integrated meatpackers controlling feed-to-freezer supply chains, frozen vegetable specialists leveraging potato processing expertise, and diversified consumer goods conglomerates anchoring ready-meal categories. Strategic moves center on backward integration into poultry sourcing and blast-freezing equipment upgrades to capture export-grade certification premiums.
Within the integrated protein tier, BRF SA and JBS SA exemplify backward integration archetypes that control captive supply from feed operations through processing. McCain Foods Limited occupies a position representing frozen vegetable specialization, while Nestlé S.A. anchors the diversified ready-meal segment across Argentine urban markets. These three companies illustrate the competitive spectrum spanning commodity protein consolidation, crop-specific processing depth, and brand-driven consumer packaged goods scale.
| Leading Market Players |
|---|
| McCain Foods Limited |
| Unilever PLC |
| BRF SA |
| The Kraft Heinz Company |
| General Mills Inc. |
| JBS SA |
| Tyson Foods Inc. |
| Conagra Brands Inc. |
| Nestlé S.A. |
| Others |
Value Network & Pricing Analysis
Undercapacity in Argentine blast-freezing facilities is compressing supplier margins while amplifying pricing power for Brazilian processors with certified export capacity. São Paulo's cold-storage operators exploit this utilization gap to command premium rates for Mercosur cross-border shipments.
Pricing Analysis
Long-term offtake contracts dominate Brazilian frozen meat procurement between integrated meatpackers and quick-service restaurant chains, insulating buyers from spot-market volatility. Price differentiation hinges on ANVISA HACCP certification tier and volume scale, with certified processors capturing 15-20% premiums over non-compliant competitors. Pricing pressure stems from diesel-powered refrigeration backup costs during grid instability events. Quick-service restaurant chains exhibit lowest price sensitivity due to quality standardization requirements, while Colombian app-based meal delivery platforms face acute cost compression.
Supply Chain Analysis
Extended payment terms from Brazilian supermarket chains are forcing Argentine processors to seek supply-chain finance facilities from regional lenders. Raw material flows draw from Brazil's Mato Grosso beef belt, Argentina's Pampas poultry corridor, and Chile's Pacific seafood harvesting zones. Supply chain risk centers on single-source Pacific corridor shipping lanes vulnerable to port congestion. Distribution runs through São Paulo's bonded warehouse clusters for Mercosur re-export.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Brazilian quick-service restaurant chains as franchise network consolidation reduces supplier count per procurement category. This shift rewards processors with multi-state certification coverage.
For Market Incumbents: Entrench market position through backward integration into feed operations and ammonia refrigeration system capacity expansion in São Paulo state. ANVISA's tightening HACCP enforcement threatens non-compliant competitors with facility closure. Certification investment represents the priority defensive lever.
For New Entrants and Emerging Players: Pursue white-space opportunity in Bogotá and Medellín direct-to-consumer frozen meal delivery through third-party cold-chain logistics partnerships. Colombian metropolitan zones present the most penetrable geography. Go-to-market execution should anchor on app-based platform integration with 30-minute delivery guarantees.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across IQF equipment upgrade cycles as Argentine processors retrofit for export-grade certification. Long-term viability favors integrated processors with captive poultry supply chains. Acquisition targets should display ANVISA-compliant facility footprints. The signal to monitor is Mercosur sanitary harmonization ratification timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Operations | BRF SA and JBS SA control quality from grain sourcing through freezer output. |
| IQF Equipment Retrofit Program | Argentine processors adopt tunnel freezing to meet cellular preservation standards. |
| Direct-to-Consumer Platform Launch | Colombian metropolitan zones pilot app-based frozen meal delivery partnerships. |
| Vacuum Packaging Technology Upgrade | Modified atmosphere systems capture premium margins in beef export segments. |
| Bonded Warehouse Pre-Positioning | Santos port capacity reduces ANVISA inspection delays for seafood importers. |
Research Methodology
Desk research of ANVISA regulatory filings, Mercosur trade statistics, and cold-chain infrastructure databases preceded structured interviews with frozen food plant managers, quick-service restaurant procurement directors, supermarket category buyers, and third-party logistics operators. Secondary validation drew from Brazilian customs records, Argentine Ministry of Agriculture export certifications, and Chilean Ministry of Health import documentation. Bottom-up facility capacity assessments triangulated against top-down consumption estimates across the analysis window.
Assumptions regarding ANVISA enforcement intensity, Mercosur harmonization progress, and Colombian last-mile refrigeration investment rates were held fixed while energy cost volatility and exchange rate movements were stress-tested. Segmentation modeling spanned product type, distribution channel, end user, and packaging format dimensions. CAGRs were derived from logistic curve fitting to historical consumption trajectories. Forecast inputs included São Paulo household freezer penetration rates and Brazilian quick-service restaurant outlet expansion plans.
Macroeconomic conditions sit as an overlay; deviation in Brazilian diesel prices, Argentine peso stability, or Chilean port throughput would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement and infrastructure investment pacing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Refrigerated & Frozen Soup Market
Processed and Frozen Foods
Middle East and Africa Frozen Food Market
Processed and Frozen Foods
Vegan Frozen Food Market
Processed and Frozen Foods
Individual Quick Frozen Cheese Market
Processed and Frozen Foods
North America French Fries Market
Processed and Frozen Foods
Vegan Frozen Pizza Market
Processed and Frozen Foods
Asia-Pacific Frozen Food Market
Processed and Frozen Foods
Middle East and Africa Freeze-Dried Product Market
Processed and Frozen Foods
United Arab Emirates Frozen Food Market
Processed and Frozen Foods
Asia-Pacific Frozen Pizza Market
Processed and Frozen Foods
GCC Frozen Fruits and Vegetables Market
Processed and Frozen Foods
Freeze Dried Fruit Extract Market
Processed and Frozen Foods
Scandinavia Frozen Food Market
Processed and Frozen Foods
South America Frozen Desserts Market
Processed and Frozen Foods
Chocolate Ice Cream Market
Processed and Frozen Foods
Europe Freeze-Dried Products Market