
 Frozen Chicken Market | 2026-2036
Frozen Chicken Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Chicken Market Foresight
Aftermarket service revenue from cold-chain logistics and inventory management is narrowing as processors bring temperature-controlled distribution in-house. Tyson Foods leverages vertical integration from feed mills to retail distribution, sustaining margin control across the value chain. JBS S.A. anchors its position through global slaughtering capacity and export-grade certification networks. Perdue Farms differentiates via antibiotic-free product lines and direct-to-retail channel control.
Frozen chicken comprises poultry meat blast-frozen to minus 18 degrees Celsius or below, typically packaged in vacuum-sealed films or modified-atmosphere trays to inhibit microbial growth and preserve protein integrity for periods exceeding twelve months. The product serves commercial foodservice operators, retail grocers, and institutional buyers requiring predictable inventory cycles without live-supply volatility. Chicken cuts and chicken nuggets command the largest volume positions, with nuggets capturing expanding quick-service restaurant procurement as operators standardize portion weights and reduce kitchen labor. Whole chicken retains strength in emerging-market retail channels where consumers prioritize cost per kilogram over convenience, while chicken wings concentrate margin pools in sports-bar and delivery-app segments during event-driven consumption peaks.
USDA-FSIS pathogen reduction and HACCP enforcement shape processing standards in the United States, while Brazil's MAPA export certification protocols govern access to European and Asian buyers. China's SAMR food safety labeling requirements and cold-chain logistics standards are tightening import clearance procedures for frozen poultry. Stakeholders must monitor regulatory divergence between blocs, as compliance fragmentation threatens cross-border shipment economics and favors processors with dedicated in-house certification teams.
Market Dynamics
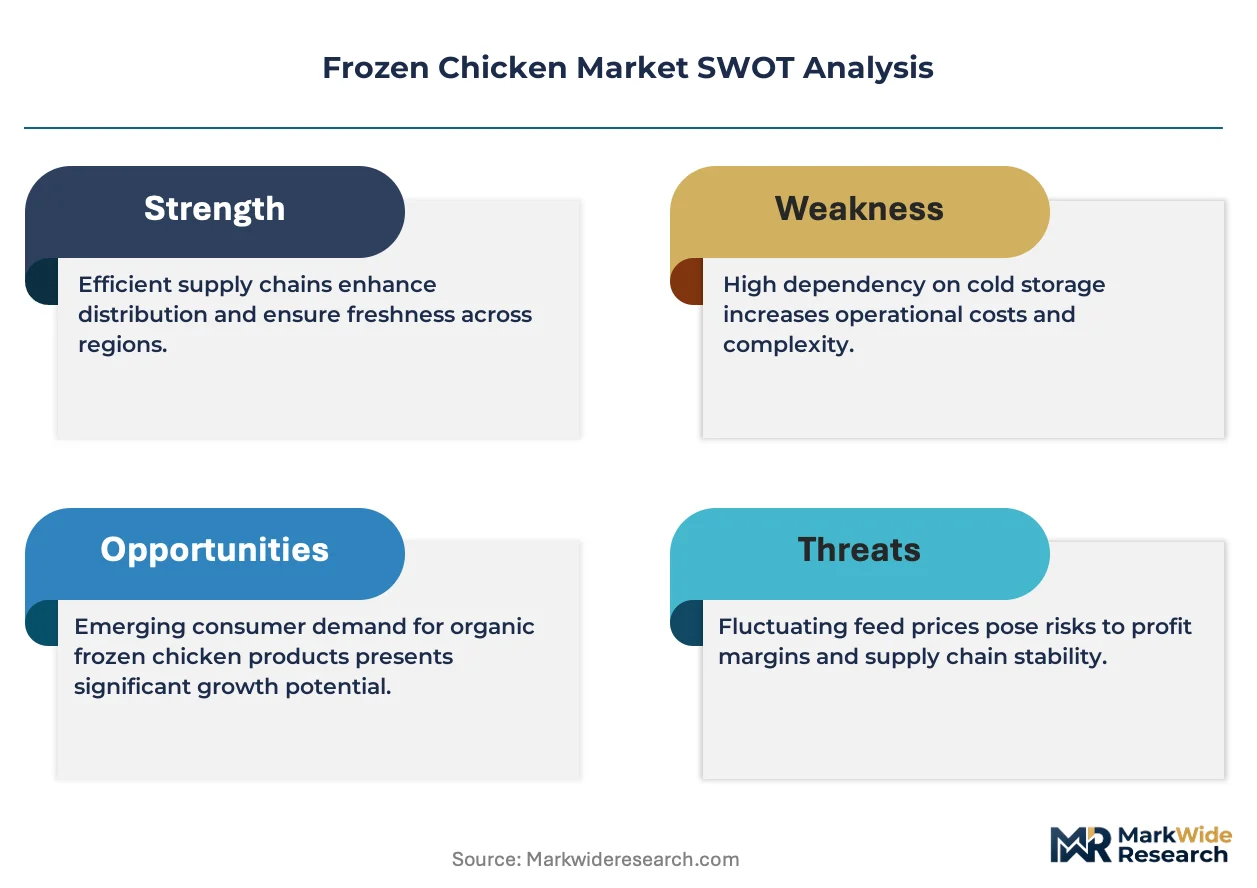
Blast-freezing technology upgrades and USDA-FSIS pathogen reduction standards are compressing processing margins while forcing capital redeployment toward automated deboning and real-time microbial detection systems.
Growth Catalysts
- Quick-service restaurant automation:Labor reduction mandates across US and Brazilian foodservice chains are accelerating procurement of pre-portioned nuggets and wings that eliminate back-of-house prep time.
- EU Green Deal cold-chain incentives:Refrigeration efficiency subsidies are retrofitting European distribution networks with lower-carbon freezing infrastructure that extends shelf stability.
- Export-grade certification expansion:Brazil's MAPA protocols are unlocking Asian market access for integrated processors with dedicated in-house compliance teams.
Market Restraints
- Feed grain price volatility:Corn and soybean cost swings in the US Corn Belt transmit directly to live-bird production economics within six-week cycles.
- Slaughtering capacity concentration:Three Brazilian states control over half of national processing volume, creating regional supply vulnerability during logistics disruptions.
- Cell-cultured protein substitution:Singapore and US regulatory approvals for lab-grown poultry are establishing competitive benchmarks for conventional frozen product positioning.
Strategic Opportunities
- Antibiotic-free premium tier:USDA Process Verified shield and EU organic standards enable 15-20% price premiums in German and UK retail channels.
- Direct-to-foodservice platforms:B2B e-procurement portals are disintermediating traditional distributor markups for mid-scale restaurant groups in São Paulo and Shanghai.
- Spent-heat recovery systems:Ammonia-based freezing plants with waste-heat capture are qualifying for China's dual carbon goal subsidies while cutting energy intensity.
Industry Challenges
- HACCP auditor scarcity:USDA-FSIS certification backlogs are delaying facility approvals by 4-6 months for new market entrants.
- Legacy ERP integration:Temperature-monitoring IoT sensors require middleware development to sync with decade-old inventory management systems at regional cold-storage facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Chicken Market |
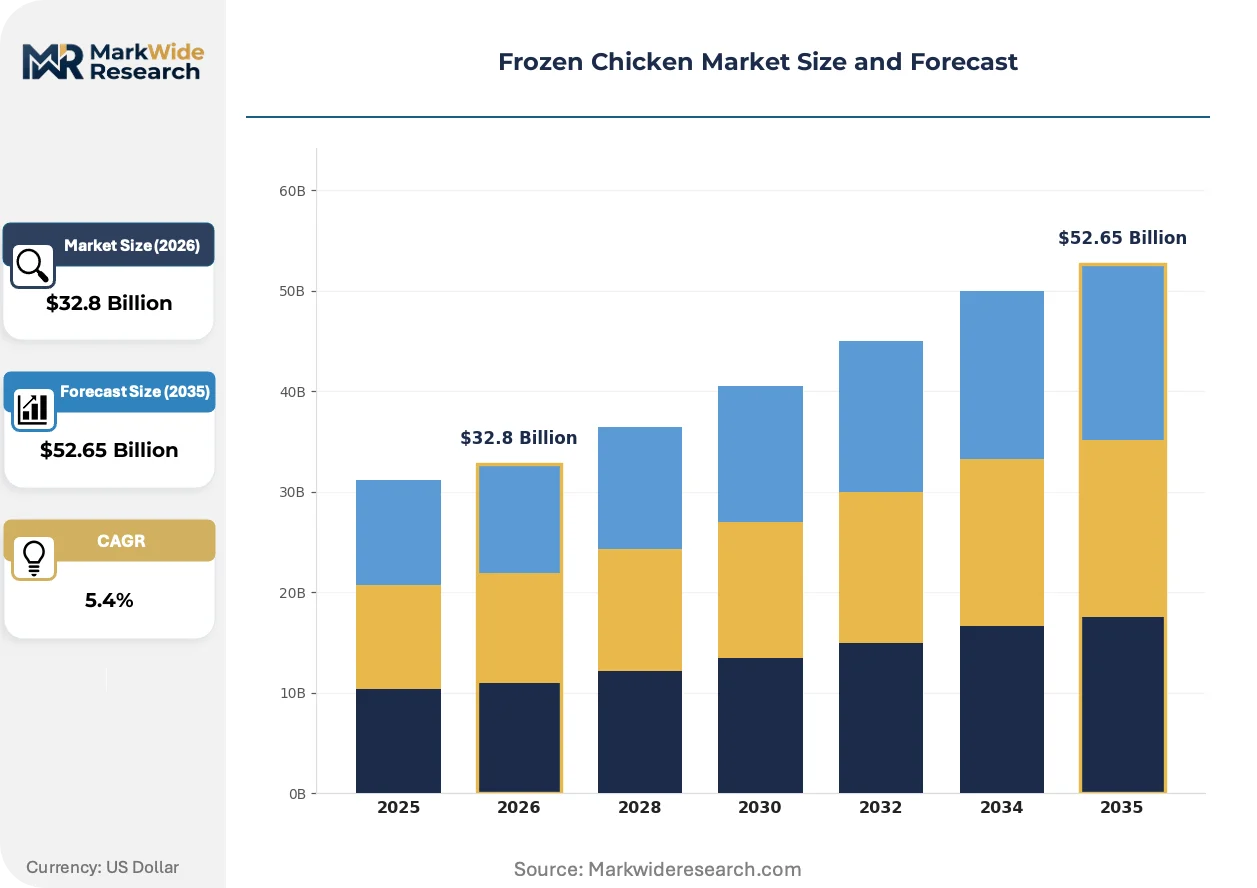
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Chicken, Chicken Cuts, Chicken Nuggets, Chicken Wings, Chicken Drumsticks Packaging Type: Vacuum Pack, Frozen Bags, Trays, Bulk Boxes, Retail Packs Distribution Channel: Supermarkets, Wholesalers, Online Retailers, Food Service Providers, Convenience Stores End User: Restaurants, Catering Services, Institutional Buyers, Fast Food Chains, Hotels |
| Companies Covered | Perdue Farms, Foster Farms, Tyson Foods, BRF S.A., Mountaire Farms, Pilgrim's Pride, Cargill, JBS S.A., Sanderson Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Chicken Market Shifts & Advancements
Processing automation and regulatory digitization are converging to reshape competitive economics across the frozen chicken value chain, with first-mover advantages accruing to operators that synchronize equipment upgrades with compliance infrastructure.
Hyperspectral imaging systems are digitizing quality control workflows by detecting bone fragments and bruising at line speeds exceeding 200 birds per minute. Brazilian and Thai processors are deploying these units at a 40% annual replacement rate for manual inspection stations. The technology is digitizing labor allocation patterns while compressing defect-related recall exposure.
China's SAMR traceability mandates now require blockchain-anchored cold-chain records for all imported frozen poultry, with QR-code disclosure obligations extending to retail packaging. The regulation is forcing exporters to retrofit legacy inventory systems with interoperable data architectures. European suppliers to the Chinese market are consolidating certification documentation through third-party logistics platforms to manage clearance velocity.
Subscription-based inventory programs are replacing spot purchasing for US regional restaurant chains, with processors guaranteeing fixed monthly volumes against price-band commitments. The model transfers demand-forecasting risk upstream while locking in offtake certainty. Quick-service operators in Texas and Florida are piloting these arrangements to buffer against wing-price volatility during sports-calendar peaks.
Frozen Chicken Market Segmentation
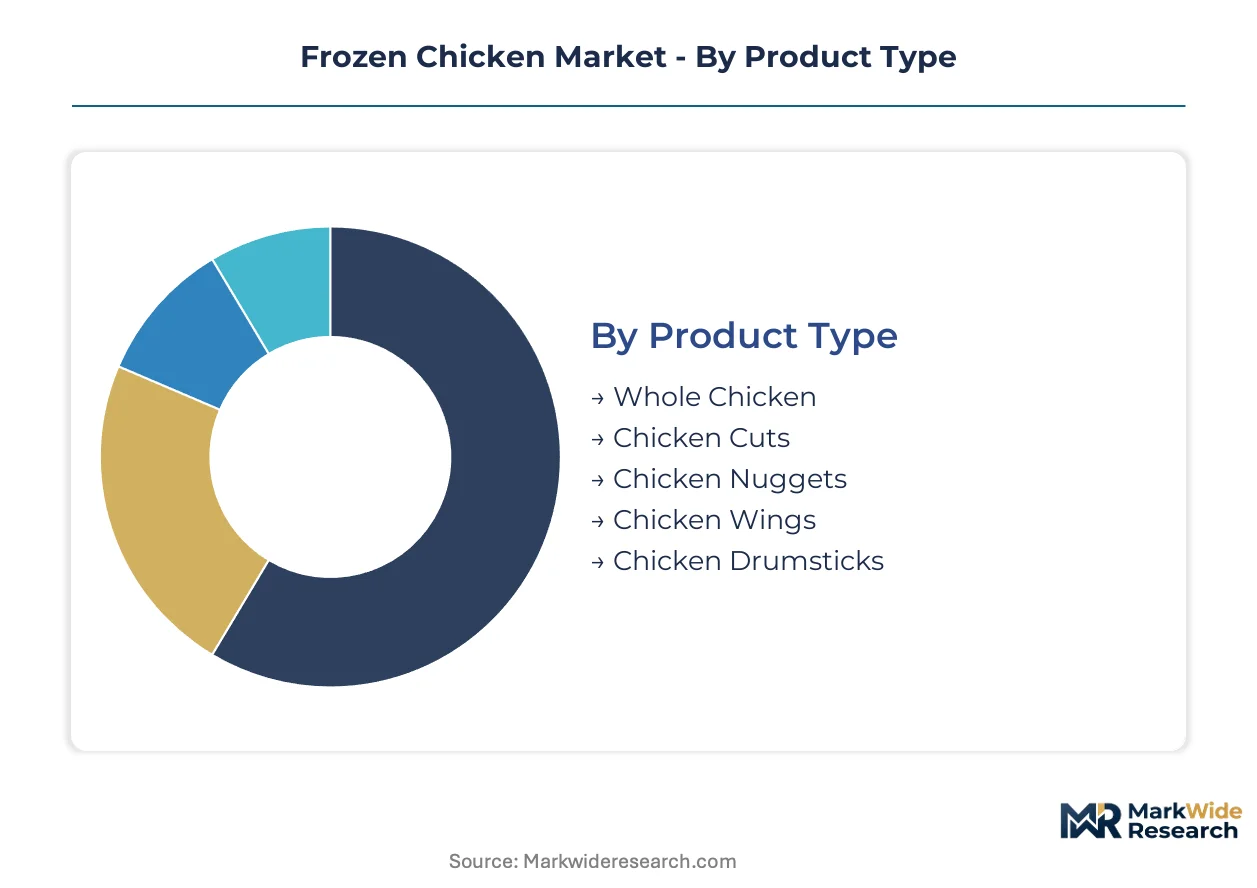
Frozen chicken segmentation tracks how product form, packaging configuration, channel access, and buyer type reshape procurement economics. Each dimension carries distinct margin profiles and capital requirements that processors must align against their operational strengths.
Product Type:
Product form determines processing intensity, shelf stability, and the addressable customer base across foodservice and retail channels.
- Whole Chicken:Intact carcasses blast-frozen post-slaughter retain bone structure and skin integrity for extended storage. Demand concentrates in Brazilian and Chinese retail channels where cost-per-kilogram sensitivity outweighs convenience preferences.
- Chicken Cuts:Separated breast, thigh, and leg portions undergo portion-controlled trimming before vacuum sealing. Quick-service restaurant procurement of pre-cut portions is climbing fastest as operators eliminate back-of-house labor.
- Chicken Nuggets:Mechanically separated meat formed into standardized shapes with breadcrumb coating. Fast-food chains in the United States and Germany are expanding automated fryer-compatible formats.
- Chicken Wings:Joint-separated mid-wing and drumette portions target sports-bar and delivery-app consumption peaks. Event-driven demand volatility requires processors to maintain buffer inventories during off-peak months.
- Chicken Drumsticks:Single-bone portions with skin-on or skin-off specifications serve institutional catering and mid-tier restaurant segments. Brazilian export certification protocols favor drumstick shipments to Middle Eastern buyers.
Whole chicken commands the established base. The steepest expansion runs through chicken nuggets.
Packaging Type:
Packaging technology governs oxygen exposure, moisture retention, and retail presentation economics across cold-chain distribution.
- Vacuum Pack:Polyethylene films evacuated to sub-atmospheric pressure inhibit aerobic microbial proliferation. German retail chains are mandating vacuum-sealed formats for private-label premium lines.
- Frozen Bags:Multi-layer polymer pouches with zip-seal closures serve household portioning needs. Chinese e-commerce platforms are driving frozen bag volumes through subscription-based replenishment models.
- Trays:Expanded polystyrene or pressed-fiber bases with overwrap film enable modified-atmosphere preservation. UK supermarkets specify tray formats for counter-ready display merchandising.
- Bulk Boxes:Corrugated containers with polyethylene liners deliver 10-20 kilogram shipments to foodservice distributors. Brazilian processors utilize bulk boxing for export shipments to Saudi Arabian wholesale importers.
- Retail Packs:Consumer-facing units with branded labeling and nutritional disclosure panels. US FDA labeling requirements and EU FIC regulations dictate retail pack information architecture.
Bulk boxes anchor foodservice procurement. The fastest volume gains are appearing in retail packs.
Distribution Channel:
Channel structure determines price realization, working capital cycles, and the required certification documentation burden.
- Supermarkets:Branded and private-label placement through refrigerated display cases requires slotting fee negotiations. French and UK supermarket chains are consolidating frozen poultry sourcing through centralized procurement hubs.
- Wholesalers:Intermediate distributors aggregating mixed-protein shipments for independent restaurant accounts. São Paulo-based wholesalers are disintermediating traditional distributor tiers through direct processor relationships.
- Online Retailers:Temperature-controlled last-mile delivery platforms with real-time inventory visibility. Chinese online retailers are integrating blockchain-anchored traceability to satisfy SAMR clearance mandates.
- Food Service Providers:Broadline distributors serving multi-unit restaurant chains with scheduled delivery routes. US foodservice providers are piloting subscription-based inventory programs to lock in wing-price certainty.
- Convenience Stores:Small-format retail with limited freezer capacity favoring high-velocity SKUs. Japanese convenience store chains are expanding fried chicken hot-case offerings from frozen inputs.
Food service providers capture the largest throughput volumes. Convenience stores are expanding most quickly as freezer infrastructure penetrates emerging urban clusters.
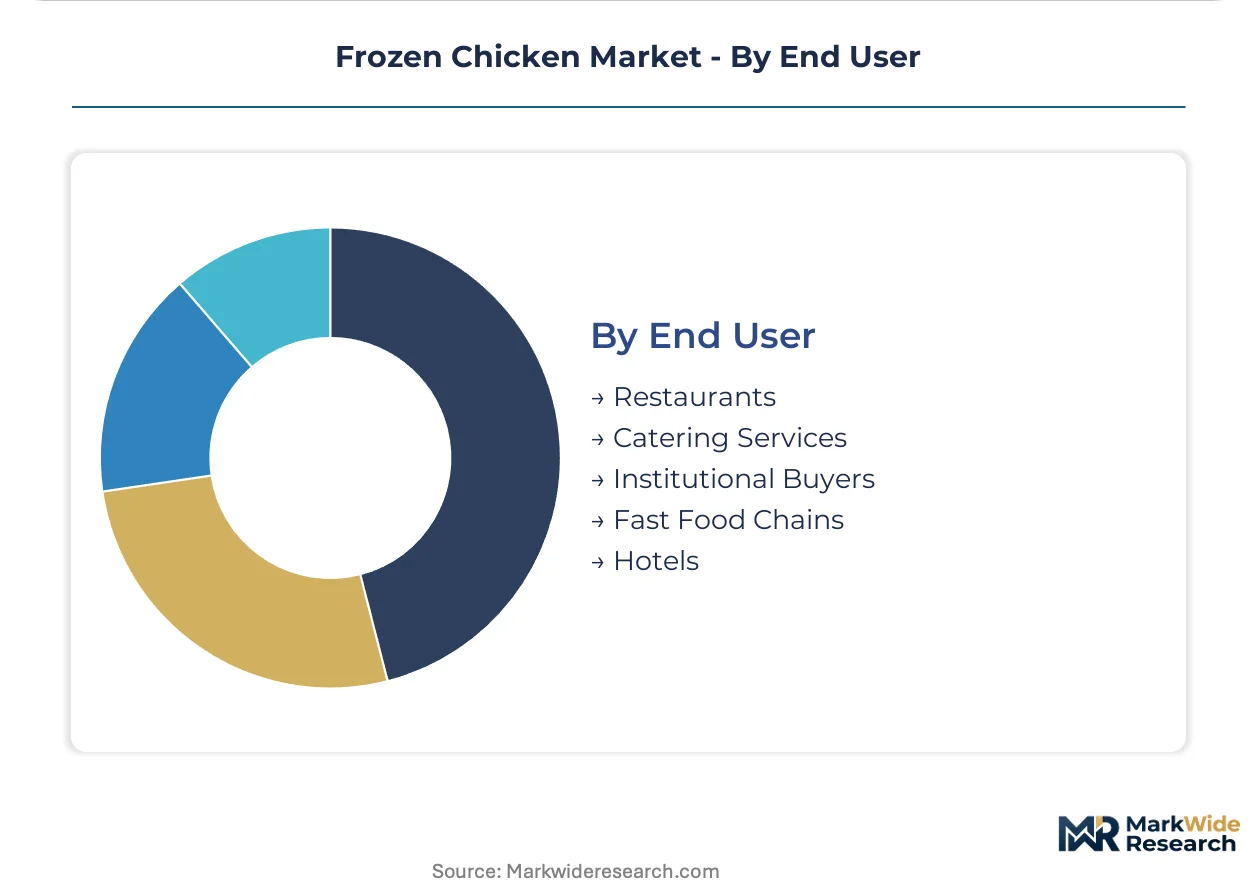
End User:
Buyer category shapes portion specifications, delivery frequency, and the sensitivity to supply disruption.
- Restaurants:Full-service and casual dining operators requiring consistent portion weights for menu costing. Texas and Florida restaurant groups are adopting fixed-volume commitments against price-band guarantees.
- Catering Services:Event-based volume spikes with irregular scheduling demanding flexible fulfillment windows. Brazilian catering services are consolidating procurement through integrated processors with dedicated compliance teams.
- Institutional Buyers:School districts, hospital systems, and military commissaries with tender-based procurement cycles. USDA commodity purchase programs influence institutional buyer pricing benchmarks in the United States.
- Fast Food Chains:Quick-service operators with standardized menu specifications and national distribution requirements. Brazilian fast food chains are scaling MAPA-certified supply chains for domestic and export market access.
- Hotels:Full-service hospitality properties with breakfast buffet and banquet service demands. Shanghai hotel operators are sourcing through B2B e-procurement portals to disintermediate distributor markups.
Fast food chains anchor volume concentration. Hotels are gaining share fastest as tourism recovery drives banquet and in-room dining requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Brazilian buyers prioritize whole-carcass value for home preparation. German and US foodservice operators demand pre-portioned cuts that eliminate kitchen labor. Chinese procurement is splitting between mass retail and premium cold-chain delivery platforms.
Brazil
Integrated poultry operations in Paraná and São Paulo states supply MAPA-certified export volumes to Middle Eastern and Asian buyers. The country's agricultural ministry enforces strict export protocols that govern cold-chain documentation. São Paulo-based processors are consolidating slaughtering capacity to meet EU and Chinese sanitary clearance requirements.
United States
Quick-service restaurant chains in Texas and Florida drive nugget and wing procurement through subscription-based volume commitments. USDA-FSIS pathogen reduction standards and HACCP enforcement shape facility approval timelines. Georgia and Arkansas processing clusters are deploying automated deboning systems to compress labor costs.
China
E-commerce platforms and convenience store chains in Shanghai and Beijing are expanding frozen poultry penetration through temperature-controlled last-mile delivery. SAMR traceability mandates require blockchain-anchored cold-chain records for all imports. Yangtze River Delta cold-storage hubs are retrofitting IoT monitoring to satisfy clearance velocity requirements.
Germany
Retail chains in Bavaria and North Rhine-Westphalia are mandating vacuum-sealed formats for private-label premium lines. EU Green Deal refrigeration efficiency subsidies are retrofitting distribution networks with lower-carbon freezing infrastructure. Berlin-based wholesalers are consolidating procurement through centralized hubs to reduce distributor markups.
Saudi Arabia
Wholesale importers in Riyadh and Jeddah anchor demand for Brazilian drumstick shipments that comply with halal certification protocols. The country's food and drug authority enforces import clearance procedures that favor suppliers with dedicated in-house compliance teams. Eastern Province logistics corridors are expanding cold-storage capacity to handle seasonal pilgrimage volume spikes.
Frozen Chicken Market Competitive Landscape
Capability concentration sits with integrated processors that control feed-to-retail value chains; scale advantage sits with diversified protein conglomerates that leverage global slaughtering networks. The market structures around three archetypes: vertically integrated specialists with captive breeding operations, diversified agribusiness divisions with multi-protein portfolios, and regional processors with export-grade certification focus. Competitive moves center on backward integration into feed milling and forward integration into direct-to-foodservice distribution platforms.
Within the integrated-processor tier, Tyson Foods and JBS S.A. exemplify scale-driven positioning through multi-continent production footprints and captive distribution networks. Perdue Farms occupies a differentiated position through antibiotic-free product lines and direct retail channel control. These three entities represent the dominant competitive anchors against which mid-scale regional operators benchmark certification, automation, and procurement contracting capabilities.
| Leading Market Players |
|---|
| Perdue Farms |
| Foster Farms |
| Tyson Foods |
| BRF S.A. |
| Mountaire Farms |
| Pilgrim's Pride |
| Cargill |
| JBS S.A. |
| Sanderson Farms |
| Others |
Supply & Pricing Matrix
Paraná state slaughtering clusters transmit pricing power downstream through captive feed milling and export-grade certification control. Brazilian integrated processors leverage MAPA protocol compliance to command premium realizations in Middle Eastern and Asian wholesale channels.
Pricing Analysis
Long-term offtake contracts dominate procurement between quick-service restaurant chains and integrated processors, with subscription-based volume commitments replacing spot purchasing for wing and nugget categories. Price differentiation rests on USDA Process Verified shield certification and antibiotic-free product tiers in German and UK retail channels. Cost compression in standard-grade cuts is intensifying because feed grain volatility transmits directly to live-bird production economics within six-week cycles. Institutional buyers exhibit highest price sensitivity due to tender-based procurement cycles, while fast food chains absorb moderate premiums for portion consistency and labor elimination.
Supply Chain Analysis
Tariff exposure between Brazil and European Union member states dominates supply chain risk calculus for drumstick and whole-carcass shipments. Geographic supply concentration centers on Brazil, the United States, and China as these countries scale integrated poultry operations for export and domestic consumption. Raw material dependencies draw from corn and soybean inputs in the US Corn Belt, plus ammonia-based refrigerants for blast-freezing infrastructure. Single-source vulnerability concentrates in three Brazilian states controlling over half of national processing volume. Distribution runs through foodservice providers and broadline distributors serving multi-unit restaurant chains with scheduled delivery routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment. USDA-FSIS certification backlogs and HACCP auditor scarcity create structural barriers that favor incumbents with dedicated compliance infrastructure.
For Market Incumbents: Harden defensive positioning through backward integration into feed milling and captive breeding operations to buffer against grain price volatility. Expand MAPA-certified slaughtering capacity in São Paulo state to secure Asian market access. Cell-cultured protein substitution in Singapore and US markets threatens long-term volume pools; preempt through antibiotic-free premium tier expansion in German retail channels. For New Entrants and Emerging Players: Pursue white-space opportunities in direct-to-foodservice B2B e-procurement platforms disintermediating traditional distributor markups. Brazilian mid-scale restaurant groups in São Paulo and Shanghai represent the most penetrable buyer segment. Launch through spent-heat recovery ammonia freezing systems qualifying for China's dual carbon goal subsidies to differentiate on energy intensity credentials. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated processors with blockchain-anchored cold-chain traceability infrastructure. Long-term viability over a five-to-ten year window rests on automation deployment and regulatory digitization capabilities. Target acquisition archetypes include regional processors with export-grade certification focus and underutilized slaughtering capacity. The signal to watch is USDA-FSIS facility approval velocity as indicator of competitive entry friction.| Strategic Initiative | Industry Significance |
|---|---|
| Blast-Freezing Technology Upgrade | USDA-FSIS pathogen reduction compliance compresses defect-related recall exposure for integrated processors. |
| Antibiotic-Free Product Line Expansion | USDA Process Verified shield unlocks 15-20% price premiums in German and UK retail channels. |
| Direct-to-Foodservice Platform Launch | B2B e-procurement disintermediates distributor markups for mid-scale restaurant groups in São Paulo. |
| Blockchain Cold-Chain Integration | China SAMR traceability mandates require interoperable data architectures for import clearance velocity. |
| Spent-Heat Recovery System Deployment | Ammonia-based freezing with waste-heat capture qualifies for China's dual carbon goal subsidies. |
Research Methodology
A spread of perspectives from plant operations managers, quick-service restaurant procurement directors, cold-chain logistics specialists, and export certification consultants converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through USDA-FSIS facility inspection records, MAPA export certification databases, China SAMR import clearance filings, and EU Green Deal refrigeration subsidy disclosures. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Demand-supply-balance framing anchored the forecast framework, with segmentation dimensions spanning product form, packaging configuration, distribution channel, and end-user category. Projections incorporated processing automation adoption curves, regulatory digitization timelines, and cold-chain infrastructure penetration patterns. CAGRs were derived through iterative reconciliation of historical trajectory analysis and forward-looking scenario weighting across the projection horizon.
Sensitivities concentrate around feed grain price volatility, cell-cultured protein regulatory approvals, and HACCP auditor availability. Forecasts reflect documented assumptions regarding trade flow continuity and certification protocol stability. Material shifts in USDA-FSIS enforcement intensity or Brazil-Asia shipping route economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
Frozen Dumplings Market
Processed and Frozen Foods
Ice Cream and Frozen Dessert Market
Processed and Frozen Foods
Vegan Frozen Pizza Market
Processed and Frozen Foods
North America Freeze Dried Products Market
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
North America Frozen Pizza Market
Processed and Frozen Foods
French Fries Market
Processed and Frozen Foods
Dry Mix Base for Frozen Desserts Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market
Processed and Frozen Foods
Global Frozen Fish and Seafood Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
Middle East and Africa Frozen Bread Market
Processed and Frozen Foods
GCC Frozen Fruits and Vegetables Market
Processed and Frozen Foods
Europe Frozen Food Market
Processed and Frozen Foods
Popsicle and Ice Cream Bar Market