
 Dehydrated Food Market | 2026-2036
Dehydrated Food Market Size, Share, and Industry Trends Forecast 2026-2036
Dehydrated Food Market Analysis
The EU Green Deal's farm-to-fork sustainability targets is restructuring procurement criteria across European food processing, compelling dehydration operators to document water-use reductions and carbon footprints. Olam Food Ingredients leverages its integrated supply chain from origination to processing to meet these traceability requirements. BCFoods Inc. anchors its position through specialized vegetable dehydration capacity in North American growing regions. Sensient Technologies differentiates via advanced extraction and concentration technologies that preserve volatile flavor compounds.
Dehydrated food refers to products from which moisture content has been reduced to typically 2-5% through controlled thermal processing, freeze-drying, or air-drying methods, achieving water activity levels below 0.6 to inhibit microbial growth and enzymatic degradation while maintaining nutritional density and extending shelf life to 12-25 years for commercial and emergency applications. The fruits and vegetables product categories dominate current volume flows due to their integration into ingredient supply chains for soups, sauces, and ready meals. Pouch packaging is gaining share fastest among military and outdoor recreation end users because of its weight reduction and rehydration convenience. The household end user segment remains mature in developed economies but shows revitalization through subscription-based emergency preparedness kits.
The FDA enforces Current Good Manufacturing Practice and Hazard Analysis Critical Control Point standards that govern dehydration facility sanitation and allergen controls, while the USDA monitors organic certification claims for dried fruit and vegetable products. EFSA and national regulators across EU member states apply maximum residue limits for pesticides on dehydrated produce imports, creating compliance barriers for non-European suppliers. Stakeholders must monitor evolving packaging sustainability mandates from the EPA and state-level extended producer responsibility laws that will reshape material specifications for bags and pouches.
Market Dynamics
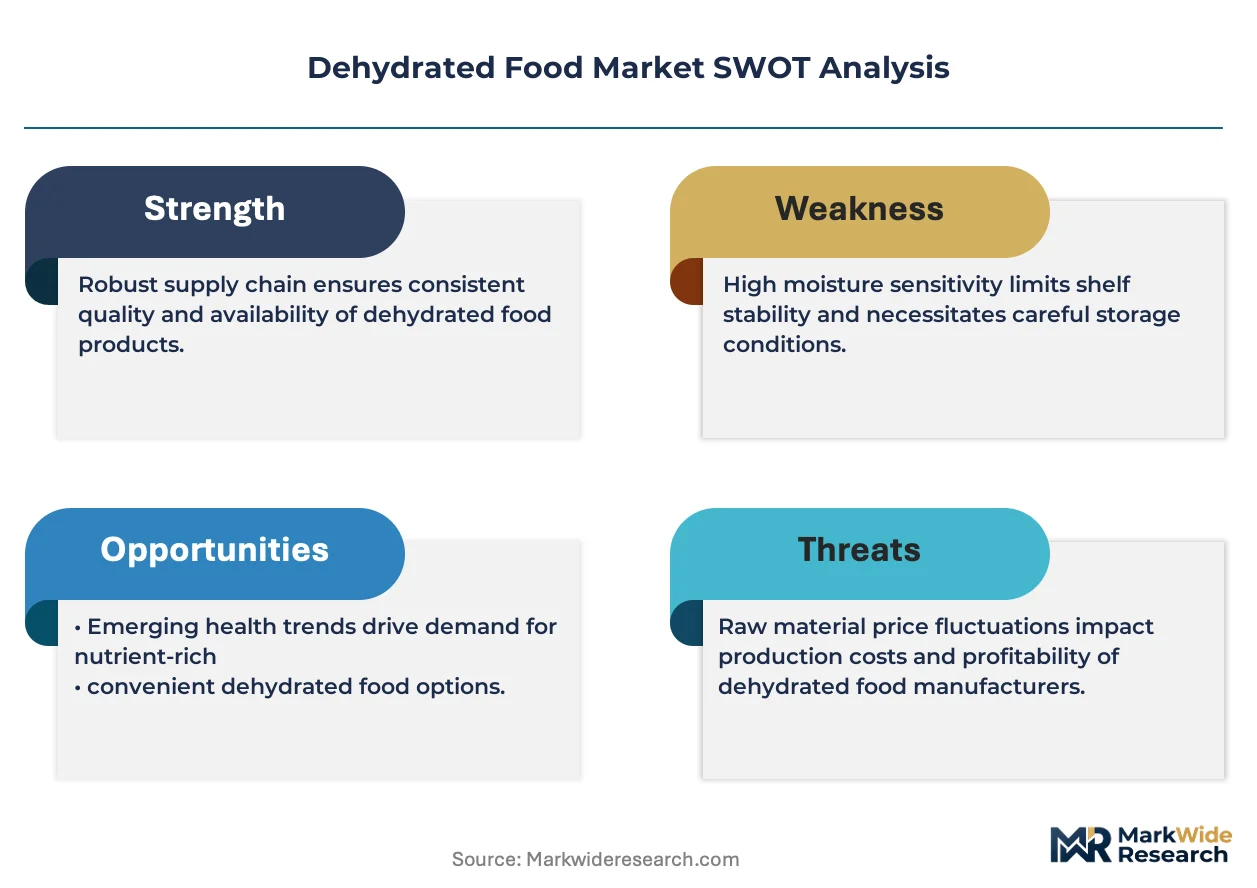
The dehydrated food market is experiencing structural compression from FDA's Food Safety Modernization Act traceability mandates, which are forcing dehydration facilities to deploy digital lot-tracking infrastructure or exit institutional supply chains entirely.
Growth Catalysts
- NATO Military Procurement:Shelf-stable ration contracts are expanding across member states, creating dedicated demand streams for freeze-dried meal kits with 25-year shelf life specifications.
- EU Green Deal Farm-to-Fork:Sustainability documentation requirements are rewarding operators who certify water-use reductions and carbon footprint transparency in European procurement.
- Emergency Preparedness Retail:Subscription-based household kits are revitalizing mature developed-economy demand through automated replenishment and disaster-scenario marketing.
Market Restraints
- Energy Input Volatility:Thermal dehydration and freeze-drying processes consume substantial electricity and natural gas, exposing margins to utility price swings in manufacturing-heavy regions.
- EFSA Pesticide Residue Limits:Maximum residue limits on dehydrated produce imports create compliance barriers for non-European suppliers seeking EU market access.
- Refrigerated Supply Chain Substitution:Cold chain infrastructure expansion in emerging markets reduces the relative advantage of shelf-stable formats for certain ingredient applications.
Strategic Opportunities
- US State-Level Extended Producer Responsibility:Packaging sustainability mandates are opening first-mover advantages for biodegradable pouch developers ahead of federal harmonization.
- Pouch Format Weight Reduction:Military and outdoor recreation end users are accelerating adoption of flexible packaging that cuts transport costs and rehydration time.
- Volatile Flavor Preservation:Advanced extraction and concentration technologies are enabling premium positioning in ingredient supply chains for soups and sauces.
Industry Challenges
- Digital Lot-Tracking Integration:Legacy dehydration facilities face capex burdens and workflow disruption when retrofitting FDA-compliant traceability systems.
- Organic Certification Timelines:USDA organic dried fruit and vegetable claims require multi-year transition periods and documentation audits that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dehydrated Food Market |
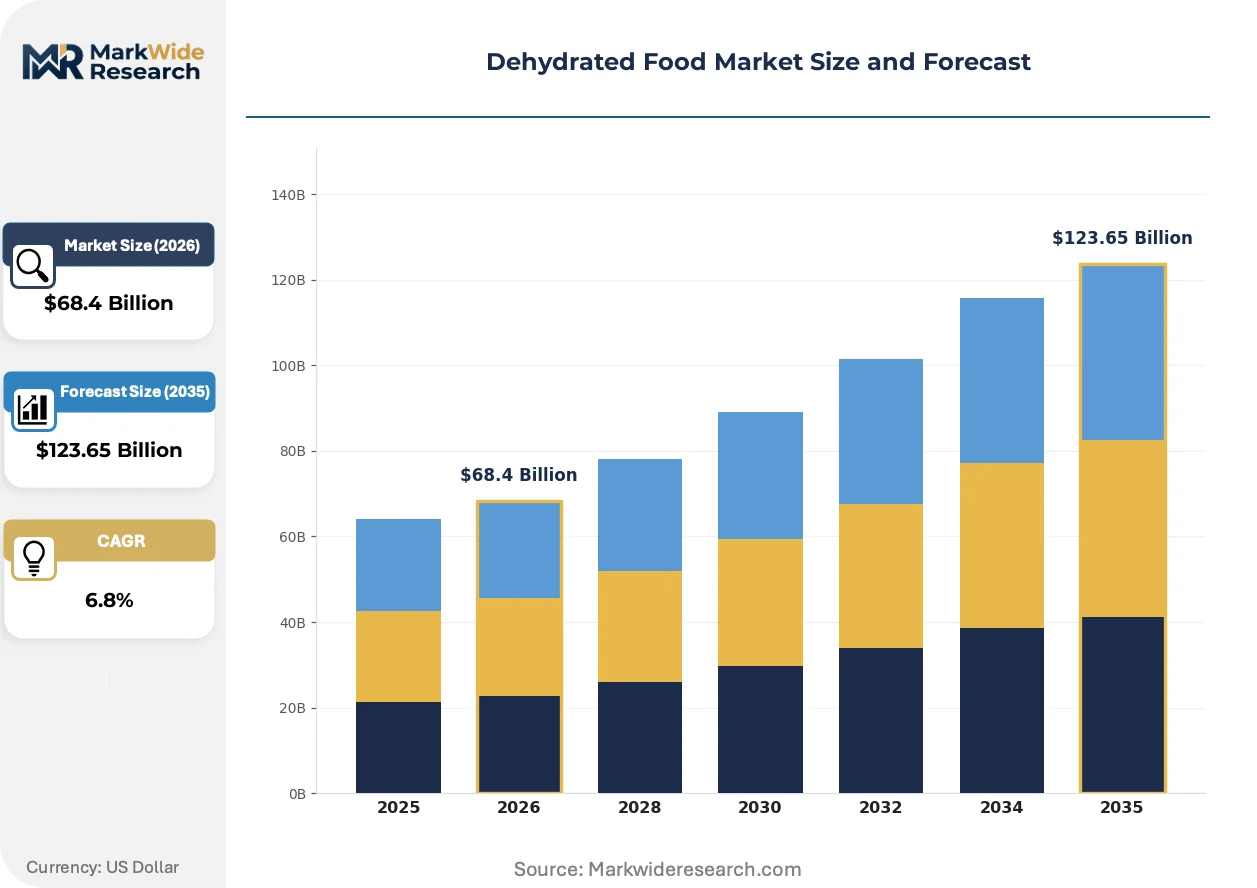
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Meals, Snacks End User: Households, Food Service, Retailers, Military Packaging Type: Bags, Cans, Jars, Pouches Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Olam Food Ingredients, Jain Farm Fresh Foods, Nestlé SA, BCFoods Inc., Van Drunen Farms, Kraft Foods Inc., ShunDi Foods, Sensient Technologies, Ajinomoto Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dehydrated Food Market Emerging Trajectories
Dehydration technology is fragmenting across multiple processing modalities, with thermal, freeze-drying, and air-drying methods competing for specific end-use applications based on nutritional preservation requirements and capital intensity.
Radio-frequency drying is decentralizing production geography by enabling smaller-scale, continuous-flow operations that bypass the centralized freeze-drying infrastructure concentrated in legacy manufacturing clusters. Regional ingredient processors are adopting RF systems to retain value-add locally rather than shipping wet commodities to distant dehydration facilities. This distributed model is compressing transport costs and spoilage losses while complicating quality standardization across fragmented supplier bases.
EPA packaging sustainability mandates are forcing material specification changes for bags and pouches used in dehydrated food distribution. The industrial consequence is accelerated R&D spending on compostable barrier films that maintain 12-25 year shelf life protection. Military and emergency preparedness segments are most affected, as they balance durability requirements against emerging extended producer responsibility compliance obligations.
Household buyers are consolidating purchases through subscription-based emergency preparedness channels that displace traditional retail stocking patterns. Direct-to-consumer platforms are capturing share from brick-and-box grocers by bundling multi-year supply kits with automated rotation and replacement services. The United States exhibits the most visible channel shift, where institutional buyers and preparedness retailers are scaling coordinated procurement of freeze-dried meal formats.
Dehydrated Food Market Segmentation
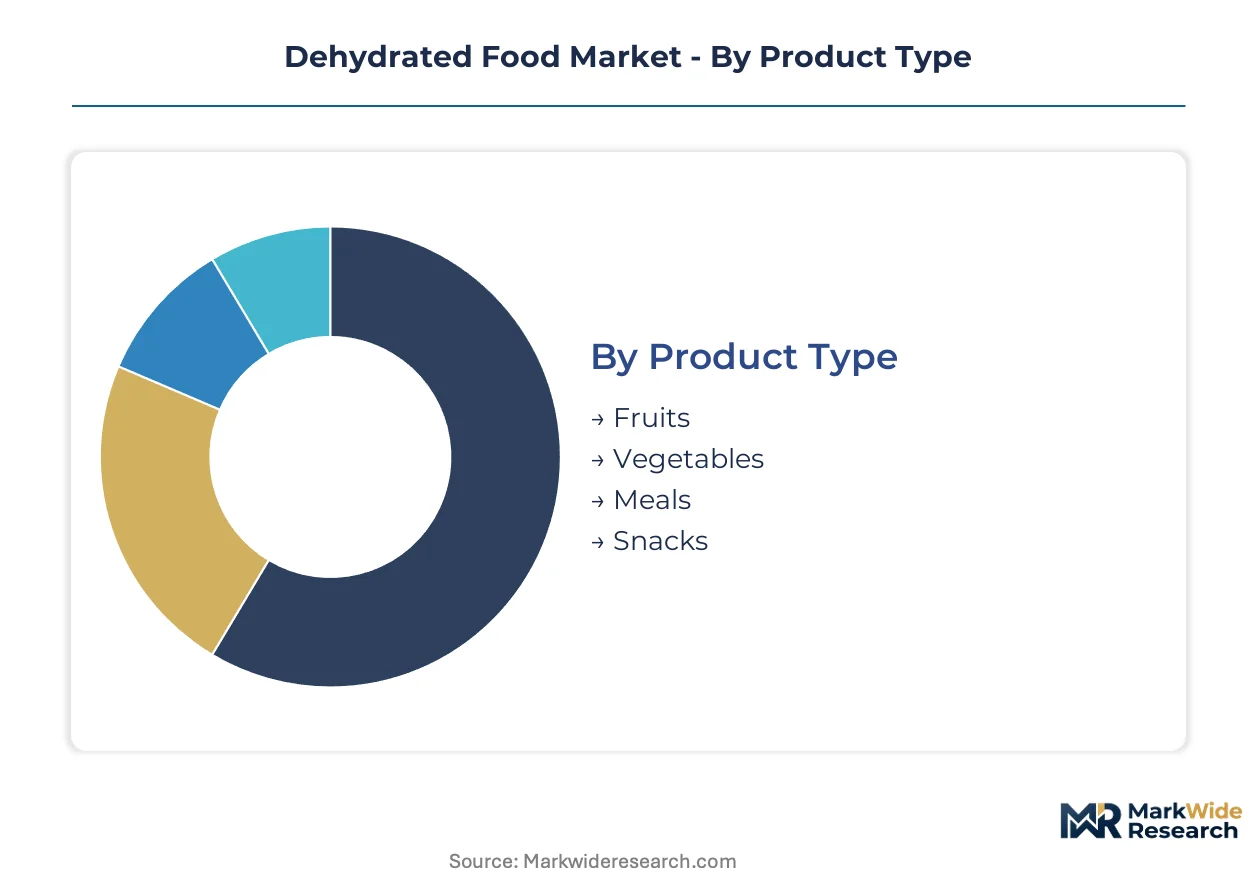
Dehydrated food segmentation reveals how processing technology, shelf-life specifications, and procurement channels fragment demand across military, emergency preparedness, and ingredient supply chains. Understanding these divides exposes where margin concentrates and where capital deployment faces regulatory friction.
Product Type:
Thermal processing intensity and moisture targets vary sharply across product categories, determining capital requirements and shelf-life outcomes.
- Fruits:Air-dried and freeze-dried formats achieve 2-5% moisture content while preserving natural sugars and volatile aromatics. Demand concentrates in ingredient supply chains for breakfast cereals and baked goods, where USDA organic certification claims command procurement premiums.
- Vegetables:Controlled thermal dehydration reduces water activity below 0.6 for soups, sauces, and ready-meal applications. European procurement under EU Green Deal farm-to-fork mandates now requires documented water-use reductions and carbon footprint transparency.
- Meals:Complete freeze-dried entrees with 25-year shelf life specifications serve NATO military ration contracts and subscription-based emergency preparedness kits in the United States.
- Snacks:Crisp-textured fruit and vegetable chips target health-conscious retail channels with shorter shelf-life positioning and premium price tiers.
Vegetables lead on scale through ingredient supply chain integration; meals lead on momentum through military and emergency procurement expansion.
End User:
Procurement sophistication and volume commitment separate institutional buyers from fragmented household demand.
- Households:Subscription-based emergency preparedness channels are revitalizing mature developed-economy demand through automated replenishment and disaster-scenario marketing in the United States.
- Food Service:Restaurants and institutional kitchens deploy dehydrated ingredients for inventory efficiency and labor reduction in soup and sauce preparation.
- Retailers:Brick-and-box grocers face share displacement from direct-to-consumer platforms bundling multi-year supply kits with rotation services.
- Military:NATO member states are expanding shelf-stable ration contracts with 25-year shelf life specifications, creating dedicated demand streams insulated from consumer price sensitivity.
Military procurement anchors volume stability; household subscription models are climbing the fastest as channel economics shift.
Packaging Type:
Material specifications face escalating sustainability mandates while shelf-life protection requirements tighten.
- Bags:Flexible multi-layer laminates dominate commodity dehydrated produce distribution, though EPA and state-level extended producer responsibility laws are forcing material specification changes.
- Cans:Metal containers retain position for long-duration emergency stockpiles where mechanical durability outweighs weight penalties.
- Jars:Glass packaging serves premium retail positioning and home-dehydration hobbyist segments with resealability advantages.
- Pouches:Lightweight flexible formats with rehydration convenience are gaining share fastest among military and outdoor recreation end users, cutting transport costs and field preparation time.
Bags retain installed base dominance; pouches show steepest expansion trajectory as weight reduction priorities intensify.
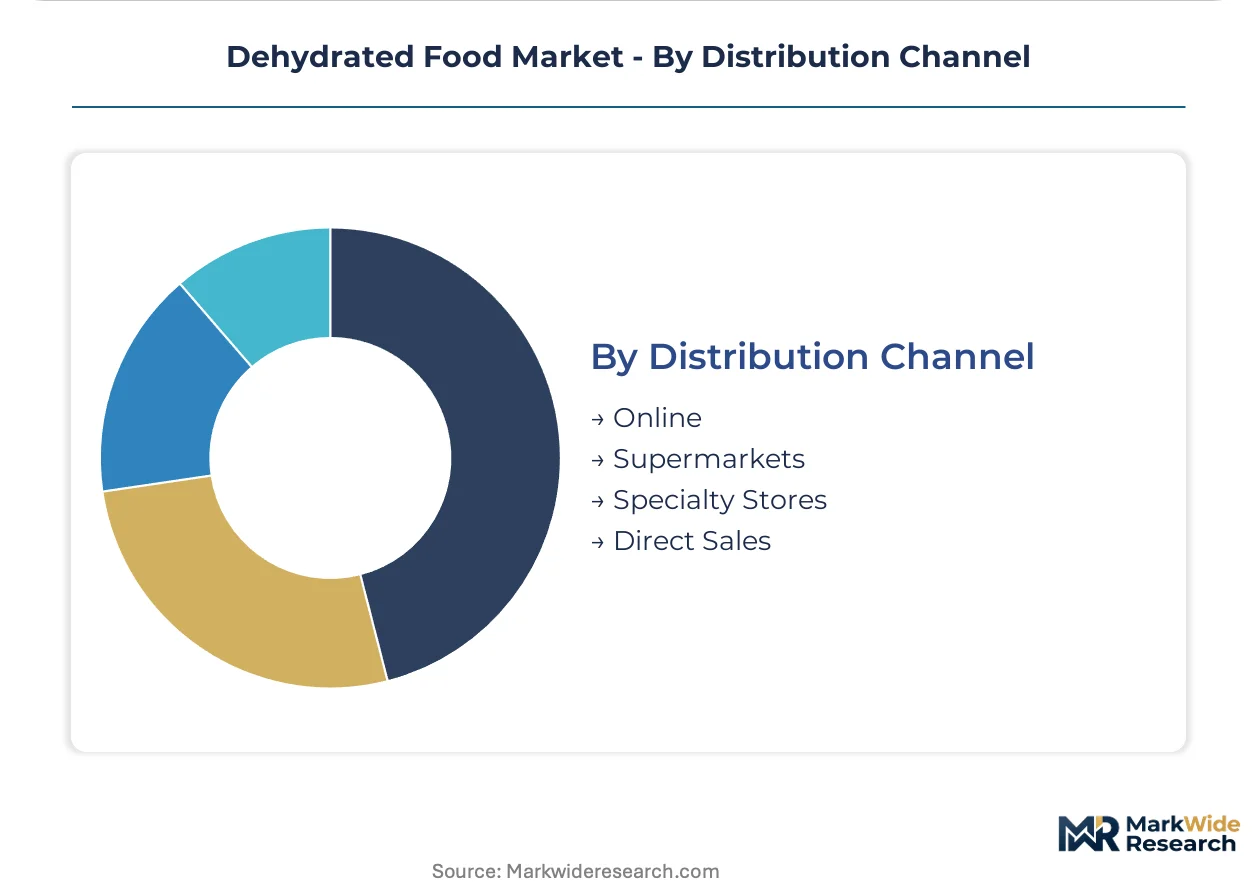
Distribution Channel:
Channel economics fragment between high-touch specialty positioning and automated replenishment efficiency.
- Online:Direct-to-consumer platforms capture emergency preparedness kit demand through subscription automation and disaster-scenario content marketing.
- Supermarkets:Mass retail channels face margin compression as dehydrated ingredients commoditize alongside private-label expansion.
- Specialty Stores:Outdoor recreation and survivalist retailers curate premium freeze-dried meal selections with technical specification education.
- Direct Sales:Institutional procurement from military and food service buyers bypasses retail markup through contracted volume agreements.
Direct sales anchor institutional volume; online channels are expanding most quickly as subscription models displace traditional stocking patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern dehydrated food industry traces its industrial-scale origins to United States military logistics during World War II, when freeze-drying technology matured to preserve battlefield rations. This heritage continues shaping procurement patterns and processing infrastructure distribution across key manufacturing clusters today.
United States
Emergency preparedness retail channels and institutional buyers are scaling coordinated procurement of freeze-dried meal kits, particularly in the Mountain West and Pacific Northwest where disaster-scenario marketing concentrates. The FDA's updated Food Safety Modernization Act traceability rules are pressuring dehydration facilities to upgrade digital lot-tracking systems or forfeit institutional contracts. Utah's Wasatch Front anchors the highest density of long-shelf-life meal producers serving both military and civilian preparedness segments.
Germany
EU Green Deal farm-to-fork sustainability targets are restructuring procurement criteria across German food processing, compelling dehydration operators to document water-use reductions and carbon footprints. EFSA maximum residue limits for pesticides on dehydrated produce imports create compliance barriers for non-European suppliers seeking market access. The Baden-Württemberg region hosts specialized vegetable dehydration capacity integrated into Central European ingredient supply chains.
China
Domestic demand for dehydrated ingredients in instant noodle and soup applications sustains massive thermal dehydration capacity concentrated in Shandong and Henan provinces. The country's dual carbon goals are forcing energy-intensive processing facilities to retrofit with natural gas alternatives or renewable thermal systems. Zhengzhou's agro-processing corridor represents the largest cluster of air-dried vegetable exporters serving Southeast Asian and Middle Eastern markets.
India
FSSAI enforcement of food safety standards is accelerating consolidation among informal dehydration operators in Maharashtra and Gujarat. Jain Farm Fresh Foods and similar integrated players leverage captive agricultural supply to meet European and North American organic certification requirements. The Nashik-Solapur corridor specializes in onion and garlic dehydration, supplying ingredient streams for global soup and sauce manufacturers.
Brazil
Agricultural commodity dehydration for export concentrates in São Paulo state and Paraná, where soybean and corn processing infrastructure supports adjacent fruit and vegetable drying operations. ANVISA's pharmaceutical-grade food ingredient standards are opening premium positioning for dehydration facilities achieving certification. The Campinas agritech cluster is incubating radio-frequency drying adoption to reduce energy intensity versus legacy thermal systems.
Dehydrated Food Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the dehydrated food landscape, creating a tiered structure where integrated agricultural processors coexist with specialized technology licensors. The vendor base fragments across three strategic archetypes: upstream-integrated farm-to-processor operators, midstream dehydration specialists with regional scale, and downstream brand houses outsourcing production. Dominant competitive moves include backward integration into captive agricultural supply and technology licensing partnerships for advanced extraction methods.
Among integrated supply chain operators, Olam Food Ingredients exemplifies the upstream-controlled archetype through origination-to-processing verticality. BCFoods Inc. and Sensient Technologies occupy complementary positions within the North American and European processing tiers, with the former representing regional vegetable dehydration scale and the latter anchoring advanced flavor preservation technology licensing. These three entities collectively illustrate how competitive positioning stratifies across agricultural control, processing scale, and technological differentiation vectors.
| Leading Market Players |
|---|
| Olam Food Ingredients |
| Jain Farm Fresh Foods |
| Nestlé SA |
| BCFoods Inc. |
| Van Drunen Farms |
| Kraft Foods Inc. |
| ShunDi Foods |
| Sensient Technologies |
| Ajinomoto Co. Inc. |
| Others |
Supply Flow & Price Mechanics
NATO military procurement programs anchor pricing power for freeze-dried meal kits with 25-year shelf life specifications, creating contract-based long-term offtake structures that insulate premium tiers from commodity volatility. Subscription-based emergency preparedness channels in the United States reinforce this bifurcation, locking household buyers into automated replenishment at fixed price points while ingredient supply chains negotiate spot-adjacent contracts for dehydrated vegetables.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates military-specification freeze-dried meals from commercial ingredient grades and private-label commodity produce. Price differentiation hinges on USDA organic certification tier and volume scale, with certified organic dried fruits commanding procurement premiums from breakfast cereal manufacturers. Cost compression in standard-tier vegetable dehydration is intensifying because energy input volatility exposes margins to utility price swings in manufacturing-heavy regions. Military buyers exhibit the least price sensitivity due to shelf-life performance requirements, while food service operators face acute pressure from refrigerated supply chain substitution in emerging markets.
Supply Chain Analysis
Regional distribution centers in Utah's Wasatch Front, Germany's Baden-Württemberg, and China's Shandong province anchor hub-and-spoke patterns for finished dehydrated products. Raw material flows draw from concentrated vegetable growing regions in the United States, India, and Brazil, with natural gas and electricity feedstocks representing critical cost components. Single-source vulnerability concentrates in legacy freeze-drying infrastructure clusters, where centralized thermal processing capacity complicates contingency planning. Distribution runs through institutional procurement channels for military and food service volumes, while direct-to-consumer platforms bypass traditional wholesale tiers for subscription emergency preparedness kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU Green Deal compliance costs in Europe and energy-intensive thermal processing advantages in North American natural gas markets. Regulatory divergence between EFSA pesticide residue limits and FDA traceability mandates creates cost-structure asymmetries that reward multi-continental production footprints.
For Market Incumbents: Lock in backward integration into captive agricultural supply to defend against radio-frequency drying disruption from regional ingredient processors. Prioritize certification investment for EU Green Deal farm-to-fork documentation to maintain European procurement access, while adding freeze-drying capacity in Utah or Idaho to exploit domestic energy cost advantages against Asian thermal dehydration competitors.
For New Entrants and Emerging Players: The gap between premium military-specification pricing and economy-tier commodity produce creates white-space opportunity in mid-market outdoor recreation segments. Target specialty retailers with technical education positioning for freeze-dried meals, and penetrate the subscription emergency preparedness channel through direct-to-consumer platforms with automated rotation services that displace brick-and-box grocer relationships.
For Investors and Strategic Acquirers: Integrated food conglomerates with existing agricultural origination networks are the most active acquirer in this space, seeking dehydration capacity to complete vertical control over ingredient supply chains. Acquisition target archetypes include regional vegetable dehydration specialists with established organic certification and radio-frequency technology licensors enabling distributed processing models. Watch for FDA enforcement actions on digital lot-tracking compliance as an inflection indicator for facility valuation discounts among legacy operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Agricultural Supply | Olam Food Ingredients leverages origination-to-processing verticality to meet EU Green Deal traceability requirements. |
| Radio-Frequency Drying Technology Licensing | Sensient Technologies enables regional processors to retain value-add locally rather than shipping wet commodities to distant facilities. |
| Subscription-Based Direct-to-Consumer Launch | Emergency preparedness retailers in the Mountain West capture household demand through automated replenishment and disaster-scenario marketing. |
| USDA Organic Certification Investment | Jain Farm Fresh Foods leverages captive agricultural supply from Maharashtra to meet North American and European organic procurement standards. |
| Biodegradable Pouch Packaging Development | BCFoods Inc. addresses EPA and state-level extended producer responsibility mandates ahead of federal harmonization. |
Methodological Framework
Coverage spans the United States, Germany, China, India, and Brazil, with primary inputs from each market combining interviews with dehydration facility operations managers, military procurement officers, retail category buyers, and agricultural supply chain directors. Secondary validation draws from FDA enforcement records, EFSA pesticide residue databases, USDA organic certification registries, and customs trade data for dehydrated produce flows. Bottom-up facility capacity modeling and top-down demand segmentation triangulate volume and value estimates.
Granularity-level framing applies separate modeling intensity across product type, end user, packaging format, and distribution channel dimensions, with additional disaggregation by processing technology modality. CAGRs were derived from segment-level growth trajectory analysis across the analysis window, incorporating NATO military procurement contract schedules, EU Green Deal implementation timelines, and energy price scenario inputs for thermal and freeze-drying operations.
Caveats apply where FDA traceability rule enforcement intensity, EFSA maximum residue limit revisions, or energy price volatility could materially shift the outlook for facility economics and procurement channel viability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Popsicle Market
Processed and Frozen Foods
Frozen Meat Grinder Market
Processed and Frozen Foods
Frozen Dumplings Market
Processed and Frozen Foods
Frozen Potato Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Freeze Dried Vegetables Market
Processed and Frozen Foods
Global Frozen Breakfast Entrees/Sandwiches Market
Processed and Frozen Foods
Europe Frozen Food Market
Processed and Frozen Foods
Europe Frozen Desserts Market
Processed and Frozen Foods
Asia Pacific Frozen Desserts Market
Processed and Frozen Foods
Deli Meat Market
Processed and Frozen Foods
Frozen Fruit Bars Market
Processed and Frozen Foods
IQF Food Products Market
Processed and Frozen Foods
Frozen Tortilla Market
Processed and Frozen Foods
Frozen Snacks Market
Processed and Frozen Foods
Freeze Dried Mangos Market