
 Chilled Meal Kits Market | 2026-2036
Chilled Meal Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Chilled Meal Kits Market Outlook
Direct-to-consumer refrigerated logistics is fragmenting as cold-chain infrastructure splinters between owned fleets, third-party last-mile operators, and grocery-backed fulfillment networks. HelloFresh SE leverages vertical integration across European sourcing hubs to control temperature integrity from farm to doorstep. Home Chef competes through Kroger's store-based fulfillment, while Gousto anchors UK demand via automated portioning facilities in Lincolnshire.
Chilled meal kits combine pre-portioned fresh ingredients with recipe instructions, requiring maintenance at 0°C to 4°C throughout distribution to preserve microbial safety and organoleptic quality. The product category serves time-constrained households seeking home-cooked meals without grocery planning or waste. Vegetarian and high-protein formulations lead margin pools as ingredient costs diverge from conventional protein sourcing, while biodegradable packaging trails on unit economics despite consumer preference pull. Online retail and meal delivery services dominate volume, though supermarket chilled aisles capture impulse replenishment occasions that pure-play subscriptions miss.
FDA food safety modernization rules and USDA cold-chain guidance shape US market access requirements, while EU REACH and F-Gas Regulation constrain refrigerant choices for cross-border chilled transport. Stakeholders must monitor how California's SB 54 packaging mandates and evolving EPA refrigerant phase-down timelines cascade into formulation and logistics redesign obligations.
Market Dynamics
Direct-to-consumer refrigerated logistics is fragmenting as cold-chain infrastructure splinters between owned fleets, third-party last-mile operators, and grocery-backed fulfillment networks, forcing stakeholders to rebuild margin structures around temperature integrity rather than scale economies.
Growth Catalysts
- Hybrid work normalization:Time-constrained professionals across North America and Europe seek home-cooked meals without grocery planning, expanding the addressable household base for subscription services.
- EU F-Gas Regulation phase-down:Mandates on hydrofluorocarbon refrigerants are accelerating investment in CO2 and ammonia-based transport cooling systems that reduce long-term compliance costs for cross-border chilled distribution.
- Automated portioning:Robotics-enabled ingredient weighing and packing lines in Lincolnshire and Ruhr Valley facilities are compressing labor costs and reducing portion variance that drives customer churn.
Market Restraints
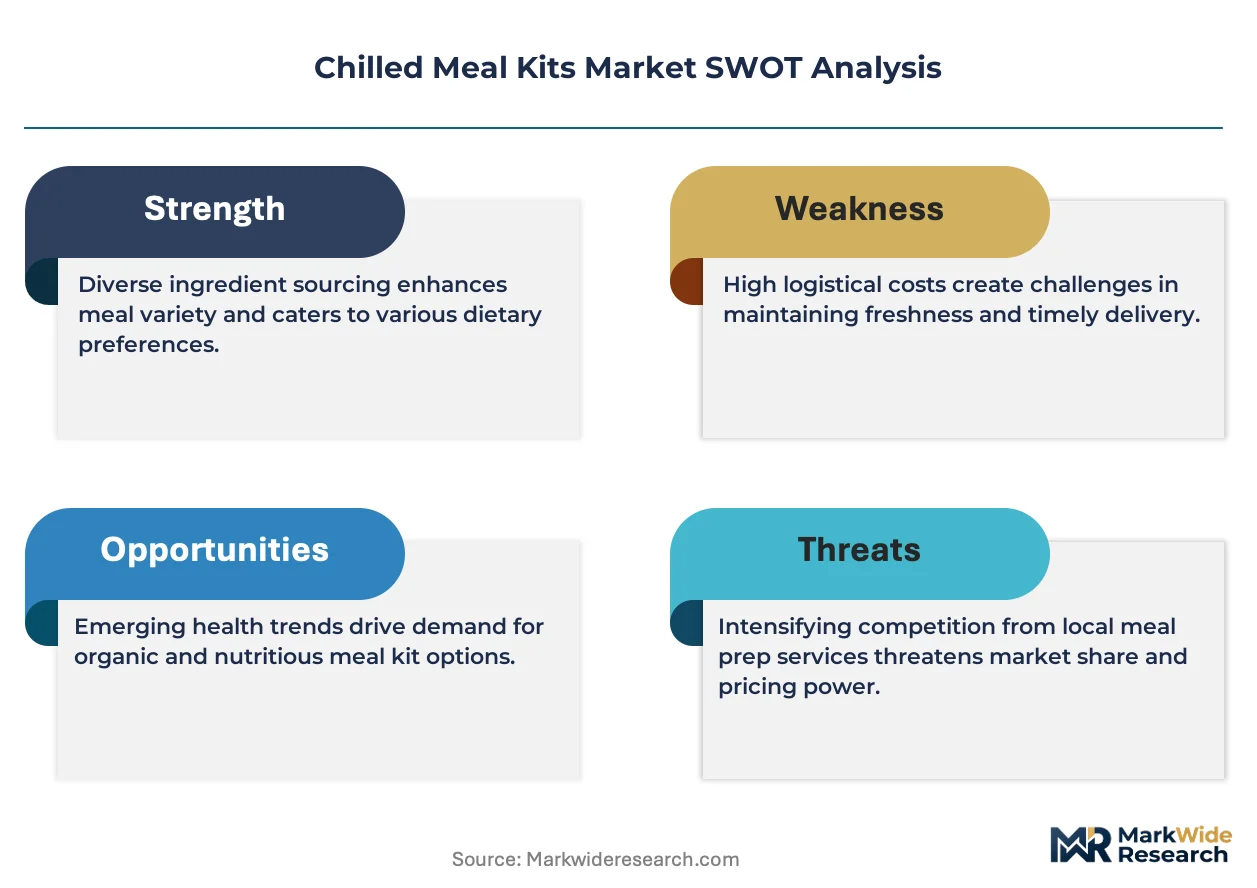
- Perishable input cost volatility:Fresh produce and protein prices fluctuate with seasonal supply shocks, compressing gross margins when subscription pricing locks consumer rates for multi-week cycles.
- Single-source refrigerant dependency:European producers face supply concentration risk for HFC alternatives as EU F-Gas quotas tighten, limiting fleet expansion flexibility.
- Biodegradable packaging unit economics:Compostable films and insulated liners cost multiples of conventional plastic, forcing trade-offs between consumer preference and path-to-profitability.
Strategic Opportunities
- Supermarket chilled aisle penetration:Impulse replenishment occasions in UK and German retail capture households that resist subscription commitments but value convenience.
- California SB 54 packaging mandates:Extended producer responsibility rules create first-mover advantage for operators with certified recyclable or compostable supply chains.
- AI-driven demand forecasting:Machine learning convergence with IoT temperature logging is reducing waste from overproduction and enabling dynamic menu substitution.
Industry Challenges
- Cold-chain technician scarcity:Refrigeration mechanics and HAZMAT-certified drivers remain under-supplied relative to fleet expansion plans, extending hiring timelines.
- Multi-jurisdictional compliance synchronization:FDA traceability rules, USDA cold-chain guidance, and EU REACH chemical registrations create overlapping documentation burdens that delay new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chilled Meal Kits Market |
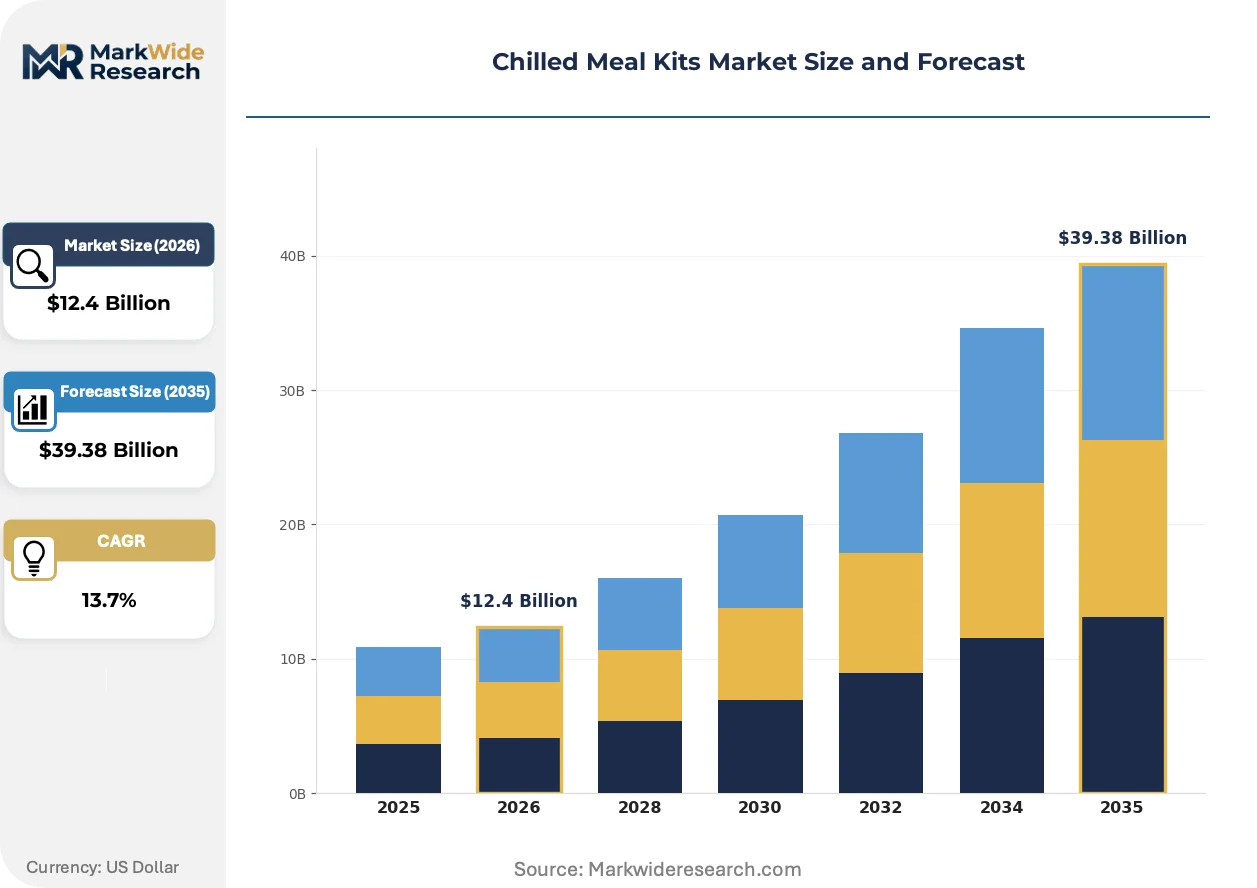
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $39.38 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetarian, Vegan, Gluten-Free, High-Protein Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Meal Delivery Services End User: Families, Millennials, Health Enthusiasts, Busy Professionals Packaging Type: Plastic Containers, Cardboard Boxes, Biodegradable Packs, Glass Jars |
| Companies Covered | HelloFresh SE, Home Chef, Blue Apron Holdings, Inc., Tyson Foods, Inc., Gousto, Marley Spoon, Sunbasket, Purple Carrot, Gobble Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chilled Meal Kits Market Strategic Shifts
Active packaging technologies and AI-enabled logistics are compressing the temperature-variance window that once forced conservative shelf-life estimates, unlocking working-capital efficiency and menu variety expansion.
Phase-change material (PCM) insulation is hybridizing conventional expanded polystyrene with bio-based paraffin and salt-hydrate cores that maintain 0°C to 4°C for 48+ hours without active cooling. Premium subscription tiers in Germany and the Netherlands are adopting PCM-lined boxes for weekend delivery windows, compressing reliance on refrigerated vehicles and enabling third-party courier handoffs that were previously excluded from cold-chain protocols.
EPA refrigerant phase-down timelines under the AIM Act are forcing US operators to retrofit transport refrigeration units with R-454B or CO2 systems ahead of 2027 production bans. Cold-chain fleet operators in California and Texas are front-loading capital expenditure to secure early-mover compliance positions, while smaller regional players face equipment financing constraints that widen competitive gaps.
Subscription fatigue is fragmenting demand toward flexible à-la-carte portals that allow pauses without cancellation penalties. UK households are shifting from fixed weekly boxes to on-demand ordering through branded apps, displacing pure-play subscription models with hybrid purchase patterns that mirror grocery e-commerce behavior. This rotation compresses predictable revenue streams and forces reinvestment in demand-prediction infrastructure.
Chilled Meal Kits Market Segmentation
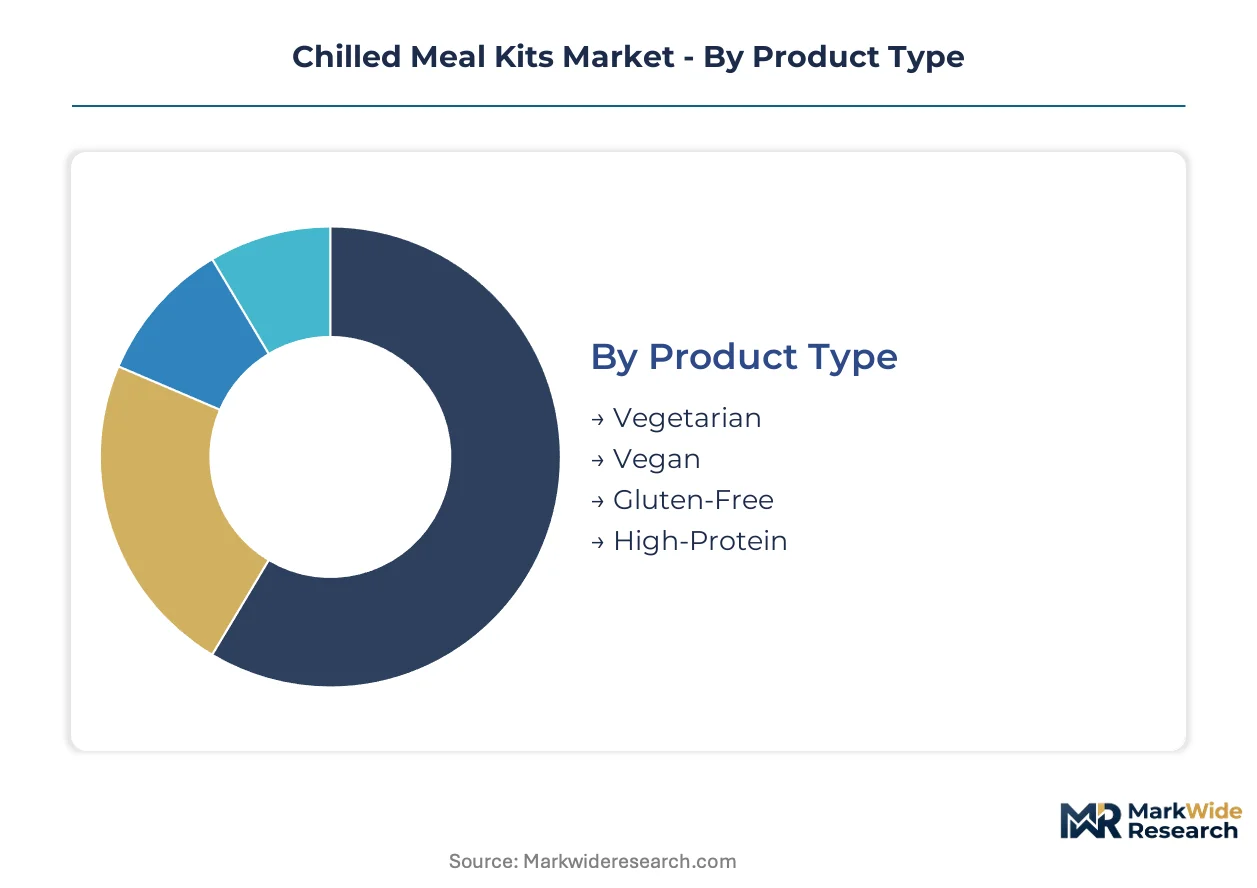
Segmentation in chilled meal kits reveals divergent margin structures and replenishment cadences across dietary positioning, channel economics, and packaging compliance burdens. Cycle-time variation between subscription renewals and impulse purchases creates distinct working-capital profiles that reshape supplier priorities.
Product Type:
Vegetarian formulations turn inventory fastest due to shorter protein shelf windows and predictable sourcing from controlled-environment agriculture. Vegan and high-protein variants operate on slower cycles anchored to specialized ingredient procurement and extended quality verification protocols.
- Vegetarian:Plant-forward menus leveraging controlled-environment greens and dairy alternatives command premium positioning in German and Dutch subscription tiers. Demand concentrates among urban households seeking reduced meat consumption without culinary complexity, though margin pressure persists from biodegradable packaging mandates.
- High-Protein:Athlete-targeted kits with portioned poultry, seafood, and legume blends require stricter cold-chain maintenance at 0°C to 2°C. Expansion concentrates in UK metropolitan zones where fitness-oriented millennials drive weekly replenishment frequency above category averages.
- Vegan:Fully plant-based formulations exclude all animal derivatives, appealing to ethical consumption segments in Scandinavian markets.
- Gluten-Free:Celiac-safe ingredient segregation protocols add handling costs but capture loyalty among diagnosed households and wellness-adjacent buyers.
Vegetarian dominates installed base. High-Protein is where expansion concentrates.
Distribution Channel:
Channel segmentation maps directly to customer acquisition cost tiers and temperature-control liability allocation. Online retail absorbs the highest fulfillment infrastructure burden while capturing subscription lifetime value.
- Online Retail:Direct-to-consumer portals with recurring subscription mechanics generate predictable demand signals for automated portioning facilities. Demand concentrates among time-constrained households in London and Berlin postal codes, where delivery density justifies owned-fleet deployment.
- Meal Delivery Services:Aggregator-platform distribution through third-party apps expands reach but fragments temperature accountability across courier handoffs. Expansion concentrates in Paris and Madrid where urban density supports 30-minute chilled delivery windows.
- Supermarkets:Chilled-aisle placement captures impulse replenishment without subscription commitment, competing on convenience against frozen alternatives.
- Convenience Stores:Limited SKUs in urban grab-and-go formats serve single-person households with immediate consumption intent.
Online Retail dominates installed base. Meal Delivery Services are climbing the fastest.
End User:
User segmentation aligns household composition and life-stage priorities with portion scaling and menu complexity preferences. Family units drive volume while professional singles sustain premium pricing.
- Busy Professionals:Hybrid-work households prioritize time savings over per-meal cost, accepting premium positioning for 15-minute preparation recipes. Demand concentrates in North American and European metropolitan employment centers where commute compression eliminates traditional grocery windows.
- Families:Multi-person households require scaled portions and child-palatable flavor profiles, generating higher absolute revenue per shipment but pressuring margins through waste sensitivity.
- Millennials:Digital-native cohorts exhibit channel fluidity between subscription and à-la-carte purchasing.
- Health Enthusiasts:Macro-tracking and organic certification requirements drive ingredient transparency demands.
Families dominate installed base. Busy Professionals represent the fastest-growing trajectory.
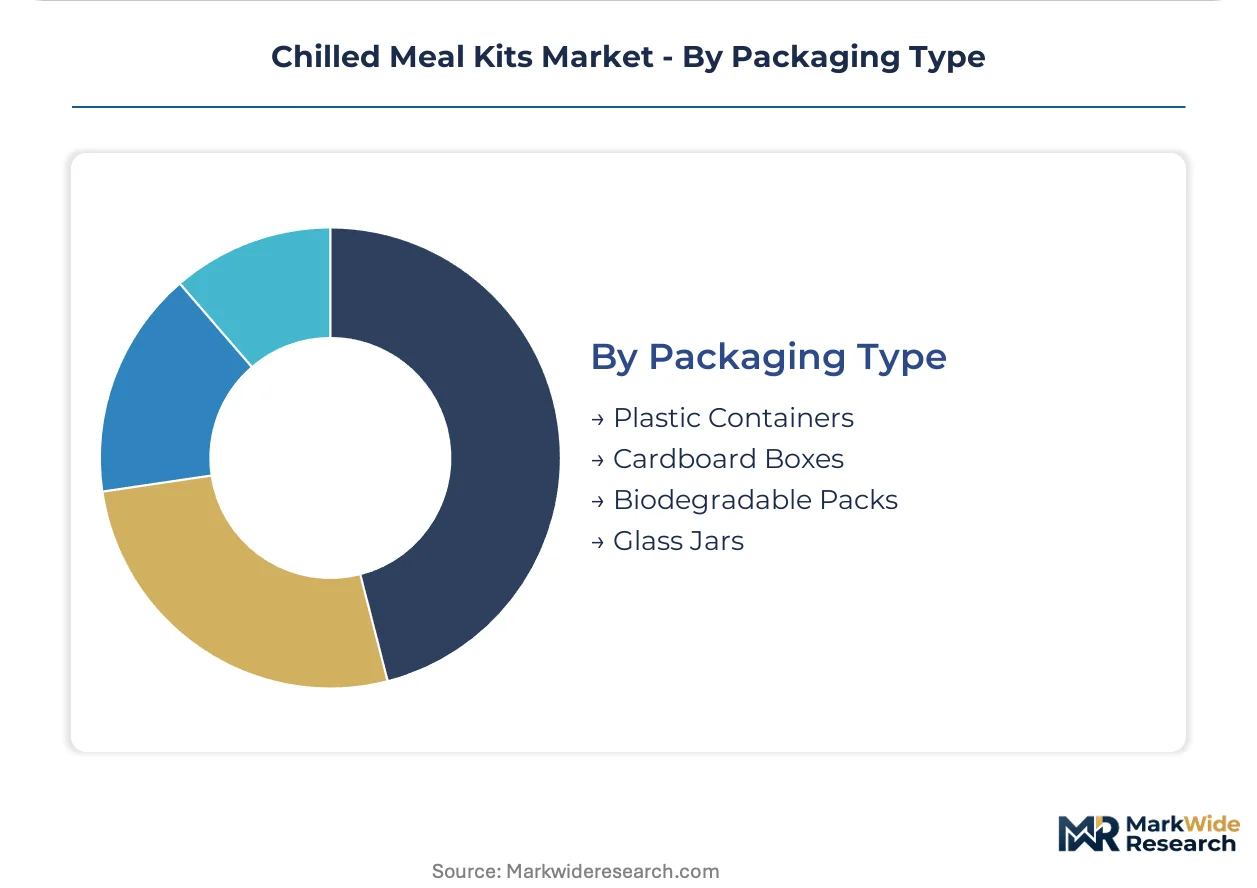
Packaging Type:
Packaging segmentation exposes the tension between regulatory compliance timelines and unit economic viability. Material choices cascade into refrigerant requirements and end-of-life recovery obligations.
- Biodegradable Packs:Compostable films and molded fiber insulation align with California SB 54 extended producer responsibility mandates and EU packaging waste directives. Demand concentrates among premium subscription tiers in Germany and the Netherlands where consumers accept cost pass-through for environmental positioning.
- Plastic Containers:Conventional polypropylene and PET structures retain cost advantage and superior moisture barrier performance. Expansion concentrates in mass-market supermarket channels where price sensitivity outweighs sustainability signaling.
- Cardboard Boxes:Recyclable outer shells with phase-change material liners balance cost and thermal performance.
- Glass Jars:Premium positioning for sauce and condiment components supports reuse programs in select Nordic markets.
Plastic Containers dominate installed base. Biodegradable Packs are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany exceeds that in the United Kingdom by roughly fifteen percent, reflecting tighter subscription density and superior cold-chain infrastructure. This asymmetry shapes investment flows and margin structures across the two largest European markets.
United States
Hybrid work normalization in metropolitan employment centers sustains demand among time-constrained professionals seeking home-cooked convenience. FDA food safety modernization rules and USDA cold-chain guidance tighten traceability requirements for perishable ingredients. California's SB 54 packaging mandates and EPA refrigerant phase-down timelines under the AIM Act cascade into formulation and logistics redesign obligations for operators serving Los Angeles and San Francisco Bay Area households.
Germany
Subscription density remains highest among EU member states, anchored by automated portioning facilities in the Ruhr Valley that compress labor costs and reduce portion variance. EU F-Gas Regulation phase-down mandates on hydrofluorocarbon refrigerants accelerate investment in CO2-based transport cooling systems. HelloFresh SE leverages vertical integration across European sourcing hubs to control temperature integrity from farm to doorstep, with production concentration in Brandenburg and Lower Saxony.
United Kingdom
Demand rotation toward flexible à-la-carte portals displaces pure-play subscription models, compressing predictable revenue streams. REACH chemical registrations constrain refrigerant choices for cross-border chilled transport from continental suppliers. Gousto anchors UK demand via automated portioning facilities in Lincolnshire, while London postal codes justify owned-fleet deployment for delivery density.
France
Urban density in Paris supports thirty-minute chilled delivery windows through aggregator-platform distribution. EU packaging waste directives create compliance burdens that favor operators with certified recyclable supply chains. Meal delivery services expand through third-party apps, fragmenting temperature accountability across courier handoffs in Île-de-France metropolitan zones.
Netherlands
Premium subscription tiers adopt phase-change material insulation for weekend delivery windows, reducing reliance on refrigerated vehicles. ECHA chemical registrations under REACH overlap with national food safety protocols, extending documentation timelines for new product launches. Rotterdam and Amsterdam logistics clusters enable third-party courier handoffs previously excluded from cold-chain protocols.
Chilled Meal Kits Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream, supplying temperature-control packaging and automated portioning equipment. The vendor base consolidates around three structural tiers: vertically integrated subscription platforms with captive logistics, grocery-backed fulfillment networks leveraging store-based inventory, and pure-play technology vendors enabling demand forecasting and cold-chain monitoring. Competitive dynamics center on M&A activity targeting regional logistics capabilities and strategic partnerships between meal kit operators and supermarket chains.
Among vertically integrated platforms, HelloFresh SE and Home Chef exemplify divergent fulfillment philosophies, with the former emphasizing owned-fleet cold-chain control and the latter leveraging Kroger's store-based infrastructure. Gousto occupies a position within the UK market as a specialist in automated portioning. These three anchors represent the dominant archetypes: European-integrated production, North American grocery-backed distribution, and British automation-led efficiency.
| Leading Market Players |
|---|
| HelloFresh SE |
| Home Chef |
| Blue Apron Holdings, Inc. |
| Tyson Foods, Inc. |
| Gousto |
| Marley Spoon |
| Sunbasket |
| Purple Carrot |
| Gobble Inc. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in automated portioning facilities across the Ruhr Valley and Lincolnshire clusters is compressing supplier leverage and amplifying pricing power for operators with captive production assets. Temperature-controlled logistics networks in Germany absorb margin premiums that continental competitors cannot replicate, while biodegradable packaging mandates in California and the European Union feed cost pass-through into subscription tiers.
Pricing Analysis
The customization-premium spread between configured-to-order vegetarian formulations and standard high-protein boxes runs approximately fifteen percent in German markets, reflecting ingredient sourcing complexity and cold-chain intensity. Three-tier pricing structure across premium, standard, and economy levels stratifies by packaging compliance tier and delivery window flexibility, with PCM-insulated weekend slots commanding surcharges. Cost compression in mass-market supermarket channels is intensifying because conventional plastic packaging retains unit economic advantage over compostable alternatives. Family households exhibit highest price sensitivity due to volume scaling pressures, while busy professionals accept premium positioning for time-saving recipe formats.
Supply Chain Analysis
Export-control regime angles on hydrofluorocarbon refrigerants under EU F-Gas Regulation constrain cross-border equipment flows and fragment fleet standardization across member states. Supply concentration rests on Germany, the United Kingdom, and the Netherlands for automated portioning infrastructure, while fresh produce sourcing draws from controlled-environment agriculture in Spain, Italy, and the Netherlands. Single-source dependency on HFC alternative refrigerants creates supply vulnerability as quota tightening accelerates. Distribution runs through hybrid models combining owned-fleet cold-chain control with third-party courier handoffs in dense metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of HAZMAT-certified refrigeration mechanics and cold-chain technicians is constraining fleet expansion timelines and forcing wage inflation that compresses operator margins. This capability gap shapes competitive dynamics more than capital access or brand positioning.
For Market Incumbents: Pre-empt technician poaching by locking multi-year training partnerships with vocational institutes in the Ruhr Valley and Lincolnshire logistics clusters. Deepen backward integration into controlled-environment agriculture to reduce produce cost volatility that erodes subscription margin. FDA traceability rule acceleration poses the most severe compliance threat to multi-jurisdictional operators. For New Entrants and Emerging Players: Establish a beachhead in UK supermarket chilled aisles where subscription fatigue has displaced pure-play models and impulse replenishment occasions remain underexploited. Gousto's automation-led efficiency in Lincolnshire demonstrates viable unit economics for regional specialists. Target health enthusiast segments through macro-tracking app integrations that differentiate against generic meal kit portals. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cold-chain infrastructure amortization favors scaled operators with density economics in metropolitan delivery zones. Acquisition candidates with captive CO2-based transport cooling systems and California SB 54 packaging certification command defensive positioning. Watch EPA refrigerant phase-down timeline acceleration as the signal for forced capital expenditure waves that separate viable operators from distressed assets.| Strategic Initiative | Industry Significance |
|---|---|
| CO2-Based Fleet Retrofit | EU F-Gas Regulation mandates accelerate compliance investment ahead of HFC production bans. |
| Automated Portioning Scale-Up | Ruhr Valley and Lincolnshire facilities compress labor costs and reduce churn-driving variance. |
| Biodegradable Packaging Certification | California SB 54 extended producer responsibility rules create first-mover advantage for certified supply chains. |
| Supermarket Chilled Aisle Partnership | Impulse replenishment occasions in UK and German retail capture subscription-resistant households. |
| AI-Driven Demand Forecasting | Machine learning convergence with IoT temperature logging reduces waste from overproduction. |
Study Parameters
A standing panel of cold-chain logistics directors, meal kit operations executives, supermarket category buyers, and refrigerated fleet managers provided ongoing calibration against ground conditions. Primary interviews with automated portioning facility engineers and packaging compliance officers combined with secondary validation from FDA food safety guidance documents, USDA cold-chain advisories, EU F-Gas Regulation filings, and EPA AIM Act implementation timelines. Bottom-up demand modeling across postal code delivery density tiers triangulated against top-down market sizing from subscription billing disclosures and supermarket scanner data.
Scenario-bracketing around refrigerant phase-down acceleration, hybrid work normalization persistence, and biodegradable packaging mandate enforcement generated high-low range estimates across the projection horizon. Segmentation dimensions modeled include dietary positioning, distribution channel economics, packaging compliance tier, and end-user household composition. CAGRs derived from logistic curve fitting to subscription penetration saturation patterns, with inputs from cold-chain fleet capacity expansion schedules and controlled-environment agriculture yield projections.
Macroeconomic conditions sit as an overlay; deviation in fresh produce commodity indices, refrigerated labor wage inflation, or natural gas prices for transport cooling would shift the trajectory. Forecasts reflect documented assumptions on subscription retention rates and supermarket channel share gain velocity. Material shifts in EPA refrigerant enforcement timing or EU F-Gas quota allocation mechanics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Food and Snacks Market
Processed and Frozen Foods
Individual Quick Frozen Cheese Market
Processed and Frozen Foods
Freeze Dried Mangos Market
Processed and Frozen Foods
Scandinavia Frozen Food Market
Processed and Frozen Foods
Asia-Pacific Frozen Food Market
Processed and Frozen Foods
Taiyaki Ice Cream Market
Processed and Frozen Foods
Frozen Meat Market
Processed and Frozen Foods
Middle East and Africa Freeze-Dried Product Market
Processed and Frozen Foods
Vegan Frozen Food Market
Processed and Frozen Foods
Frozen Sardine Market
Processed and Frozen Foods
Cambodia Frozen Food Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market
Processed and Frozen Foods
Dumplings Market
Processed and Frozen Foods
South America Frozen Desserts Market
Processed and Frozen Foods
GCC Frozen Fruits and Vegetables Market
Processed and Frozen Foods
Freeze-Dried Food Market