
 French Fries Market | 2026-2036
French Fries Market Size, Share, and Industry Trends Forecast 2026-2036
French Fries Market Intelligence
The integration of cryogenic freezing and AI-powered optical sorting technologies is reshaping product consistency and reducing waste in high-volume potato processing. McCain Foods Limited leverages its extensive global logistics network to maintain supply stability for major quick service restaurant chains. Lamb Weston Holdings Inc. differentiates through potato variety innovation and processing efficiency to serve diverse international tastes. J.R. Simplot Company operates with significant backward integration into potato farming, ensuring raw material control.
French fries are batons of potato, typically from varieties like Russet Burbank or Bintje, that are deep-fried, baked, or air-fried. Their primary commercial purpose is serving as a staple side dish or standalone snack in food service establishments and for at-home consumption. The frozen product type dominates sales, valued for its long shelf life and convenience in the supply chain for quick service restaurants. While crinkle cut and shoestring styles remain popular, waffle and curly fries are gaining share, driven by consumer demand for novelty.
Food safety and labeling standards enforced by agencies like the US FDA and the European Food Safety Authority (EFSA) govern acrylamide levels and allergen declarations. In developing markets, bodies such as the Food Safety and Standards Authority of India (FSSAI) are implementing stricter controls on trans-fats and sodium content. Producers must navigate these evolving nutritional guidelines while balancing cost pressures and consumer taste preferences.
Market Dynamics
The market's evolution is defined by the tension between consumer demand for convenient, indulgent foods and mounting pressure for healthier product profiles. This dynamic forces innovation in processing technologies that can reduce fat and sodium without compromising traditional taste and texture expectations.
Growth Catalysts
- QSR Expansion:Growth of quick service restaurants in Southeast Asian cities creates a stable, high-volume demand channel for standardized frozen fries.
- Product Novelty:Consumer appetite for variety drives sales of specialty cuts like waffle and curly fries, diversifying menus beyond traditional shoestring styles.
- Healthier Processing:Industrial air frying allows for lower-fat products, attracting health-conscious consumers and broadening the market's appeal.
Market Restraints
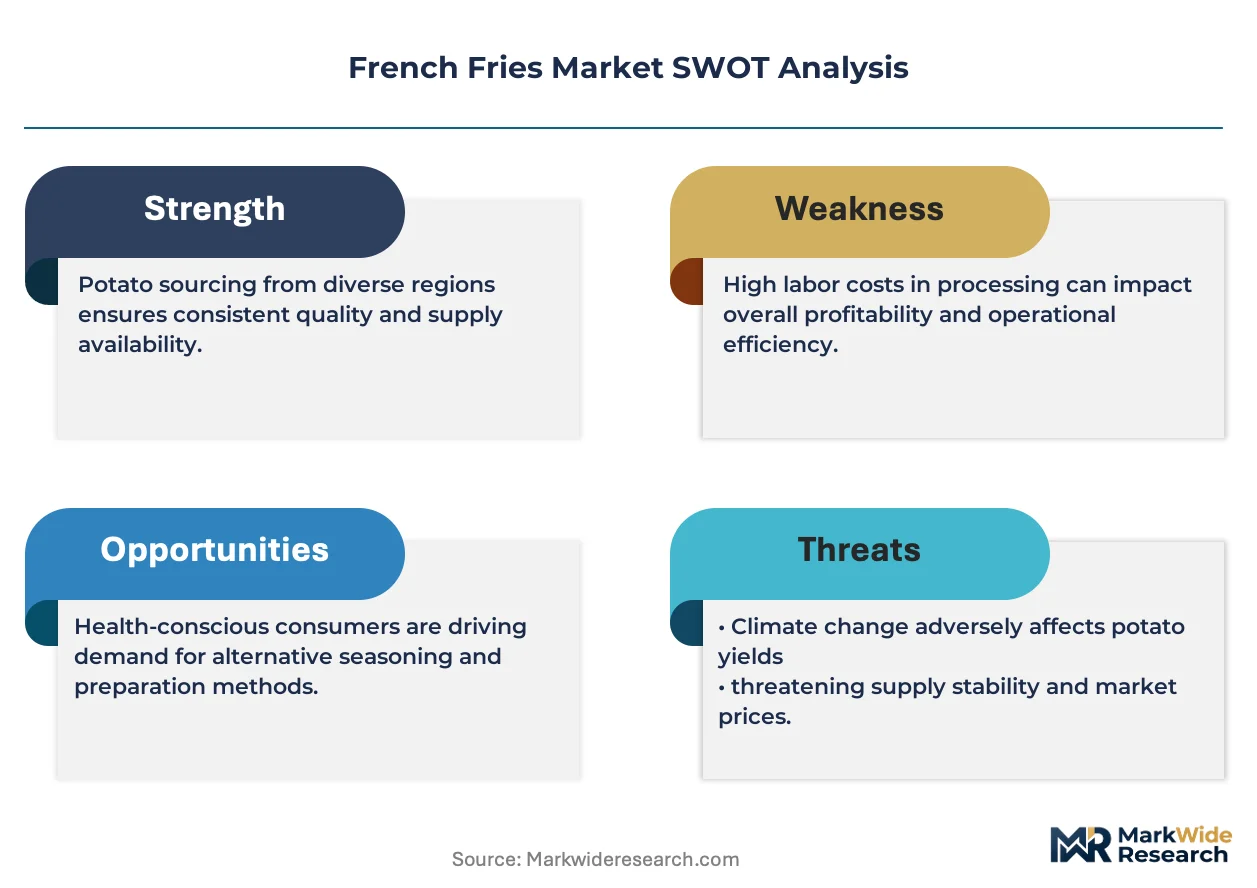
- Input Cost Volatility:Processor margins face pressure from fluctuating prices of key raw materials, namely specific potato varieties and edible oils.
- Health-Related Regulation:Stricter rules on acrylamide, trans-fats, and sodium from bodies like EFSA and FSSAI add significant compliance costs and complexity.
- Substitution Threat:Health-conscious consumers are increasingly opting for alternative side dishes or snacks perceived as healthier than traditional deep-fried potatoes.
Strategic Opportunities
- Alternative Vegetable Fries:Products from sweet potatoes or zucchini can capture health-focused consumers and establish premium-priced niches.
- Rural Market Penetration:Extending cold chain infrastructure into rural parts of developing Asian economies opens new consumer markets for frozen products.
- AI-Driven Efficiency:Implementing AI-powered optical sorting in processing reduces waste and improves final product consistency, directly boosting profitability.
Industry Challenges
- Energy Cost Management:The energy intensity of industrial frying and freezing exposes processors to cost volatility from fluctuating utility prices.
- Cold Chain Logistics:Maintaining required temperatures for frozen products across complex, global supply chains remains a critical logistical challenge.
- Regulatory Fragmentation:Adhering to disparate food safety standards from the FDA, EFSA, and FSSAI complicates global trade and production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | French Fries Market |
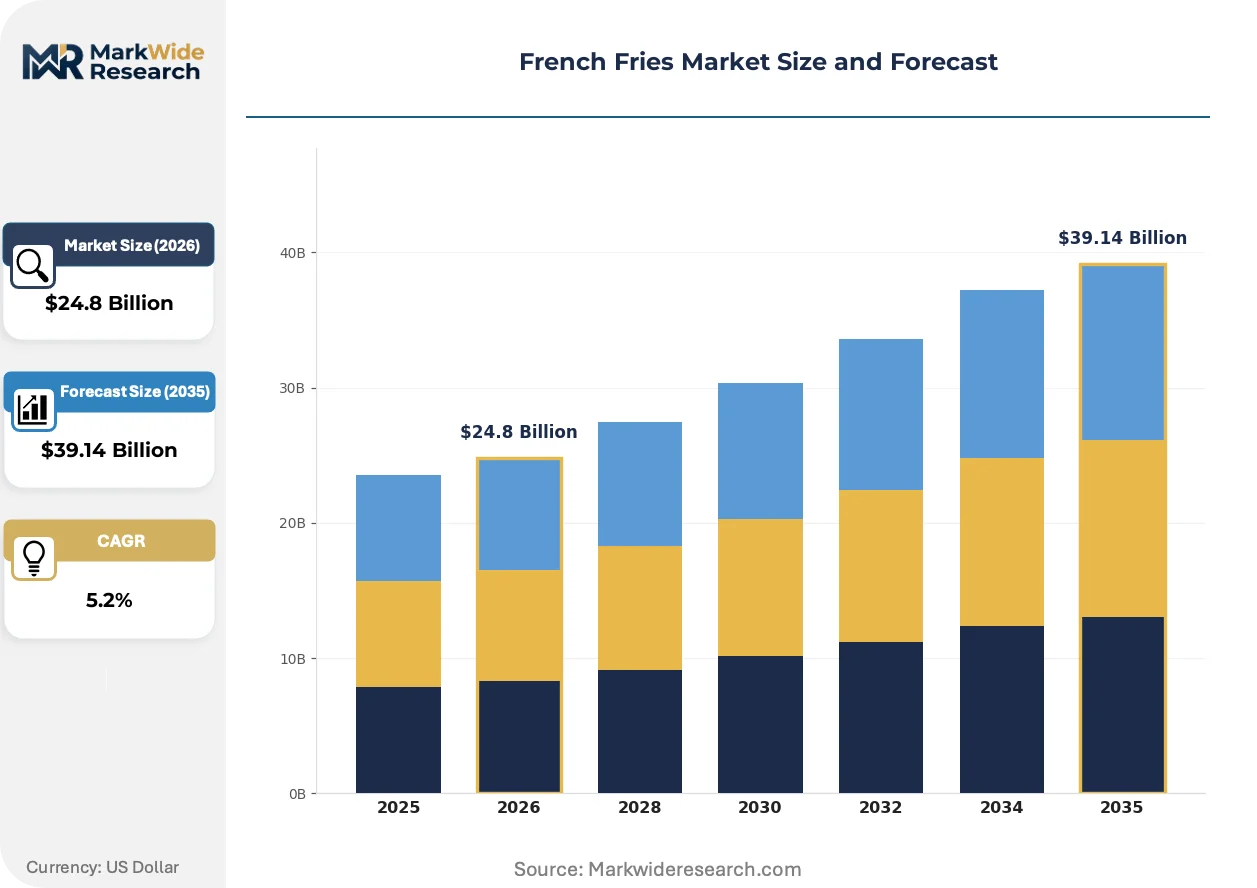
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $39.14 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen, Fresh, Shoestring, Crinkle Cut, Waffle, Curly Cooking Method: Deep Fried, Oven Baked, Air Fried, Microwaved, Grilled End User: Quick Service Restaurants, Cafeterias, Food Trucks, Catering Services, Concession Stands Packaging Type: Bulk Bags, Individual Servings, Vacuum Packed, Retail Boxes, Foil Packs |
| Companies Covered | The Kraft Heinz Co, Aviko B.V., McCain Foods Limited, Bart's Potato Company, Farm Frites International B.V., Lamb Weston Holdings Inc, Agristo NV, Himalaya Food International Ltd, J.R. Simplot Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
French Fries Market Strategic Shifts & Innovations
The market is being reshaped by the dual pursuit of healthier product formulations and greater operational efficiency. This drives investment in advanced processing technologies that meet stricter nutritional guidelines without sacrificing the convenience and taste that define the category.
Industrial air frying technology uses superheated, high-velocity air with minimal oil to cook frozen potato products. Food service operators and frozen food manufacturers are adopting this method to deliver products with a perceived health halo. This process is hybridizing traditional deep-frying with convection cooking, creating a product that achieves a crispy exterior with a significantly lower fat content.
European Food Safety Authority (EFSA) mandates on acrylamide benchmark levels are forcing process adjustments across the industry. These regulations require processors to control cooking temperatures and select specific potato varieties with lower sugar content. The frozen product segment is most impacted, compelling producers to revise blanching and pre-frying protocols to ensure compliance for market access in the EU.
A distinct shift in consumer preference toward experiential and novel food formats is gaining momentum. This behavioral change is disrupting the dominance of standard shoestring cuts, compelling processors to invest in flexible lines for waffle, curly, and other specialty shapes. The trend is most visible within the fast-casual and casual dining segments in North America and Western Europe, where menu innovation is a key competitive differentiator.
French Fries Market Segmentation

Market segmentation provides a granular view of the French fries industry, highlighting the diverse product forms, preparation methods, end-user applications, and packaging formats that define its commercial landscape. Understanding these distinct segments is crucial for producers to tailor offerings, manage supply chains efficiently, and respond to evolving consumer preferences across various global markets.
Product Type:
The market differentiates across various product forms and styles, each catering to distinct consumer preferences and operational requirements.
- Frozen:These pre-processed potato batons are par-fried and flash-frozen, offering extended shelf life and convenience for quick service restaurants and at-home consumers. Frozen products dominate sales due to their logistical advantages and ease of preparation in high-volume settings.
- Waffle:Characterized by their distinctive lattice-like cut, waffle fries offer a larger surface area for crispiness and a unique texture, appealing to consumers seeking novel and experiential food formats. Demand for waffle fries is accelerating within fast-casual dining in North America.
- Fresh:Unprocessed or minimally processed potato cuts requiring immediate preparation, primarily served in traditional diners or upscale restaurants emphasizing fresh ingredients.
- Shoestring:Thin, long potato strips that cook quickly and achieve a high crisp-to-soft ratio, remaining a classic choice for many quick service restaurant menus.
- Crinkle Cut:Featuring a corrugated surface, these fries offer a distinct texture and hold sauces well, appealing to both children and adults in various food service environments.
- Curly:Spiral-shaped potato fries seasoned with spices, providing a playful and flavorful alternative to straight-cut varieties, popular in casual dining.
Frozen products hold significant installed processing capacity. Waffle fries are rotating up the share rankings.
Cooking Method:
Preparation methods significantly influence the final product's nutritional profile and consumer appeal, driving distinct market sub-segments.
- Deep Fried:Potatoes are fully submerged in hot oil, resulting in a crispy exterior and tender interior, providing the traditional taste and texture associated with French fries. Deep-fried options maintain primary volume in quick service restaurants globally.
- Air Fried:This method uses superheated, high-velocity air to cook fries with minimal oil, offering a healthier product profile with reduced fat content. Industrial air frying technology is gaining commercial adoption in Europe.
- Oven Baked:Prepared by baking in an oven, these fries offer a lower-fat alternative to deep-fried versions, primarily favored for at-home consumption and institutional food service.
- Microwaved:Convenience-oriented frozen fries designed for quick heating in a microwave, often featuring specialized coatings to improve texture.
- Grilled:A less common preparation method, grilled fries offer a smoky flavor and slightly firmer texture, sometimes found in specialty restaurants.
Deep frying remains the primary preparation method. Air frying is expanding most quickly in commercial adoption.
End User:
Customer type defines volume requirements and service expectations across the French fries market.
- Quick Service Restaurants:High-volume establishments requiring standardized, easy-to-prepare frozen products with consistent quality and rapid turnaround times. Quick Service Restaurants represent the largest demand channel in Southeast Asia.
- Food Trucks:Mobile food vendors serving a diverse clientele, often seeking unique or gourmet fry options that can be prepared efficiently in compact kitchens. Food trucks drive demand for specialty cuts in urban centers.
- Cafeterias:Institutional food service providers in schools, hospitals, or corporate settings that prioritize cost-effectiveness, ease of preparation, and often healthier options.
- Catering Services:Event-based food providers that require versatile and high-quality fry products suitable for large gatherings and diverse menu offerings.
- Concession Stands:Venues like sports stadiums and movie theaters that need fast-serving, convenient fry products to handle peak demand efficiently.
Quick Service Restaurants represent the largest customer base. Food trucks show the steepest expansion trajectory for specialty items.
Packaging Type:
Packaging type reflects both operational efficiency needs for commercial users and convenience demands from consumers.
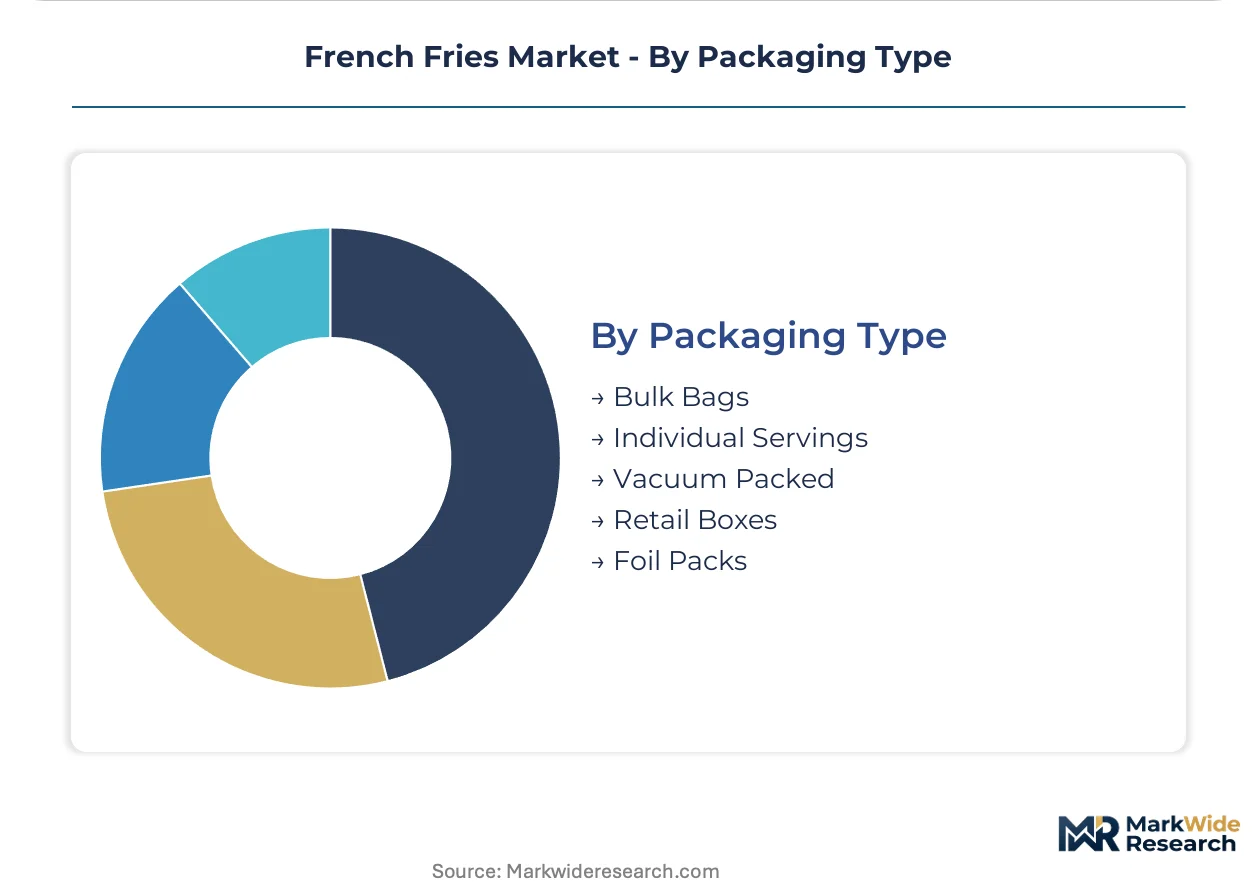
- Bulk Bags:Large format packaging, typically 5-10 kg bags, designed for high-volume commercial kitchens in quick service restaurants and cafeterias to minimize waste and reduce labor. Bulk bags are essential for large-scale food service operations.
- Retail Boxes:Consumer-sized cartons, usually 500g to 1.5kg, sold in supermarkets for at-home preparation, emphasizing convenience and ease of storage. Retail boxes are gaining share in urban household consumption in Indonesia.
- Individual Servings:Small, pre-portioned bags or containers, ideal for grab-and-go options in convenience stores, vending machines, or as a component in meal kits.
- Vacuum Packed:Packaging that removes air to extend shelf life for fresh or par-fried products, preserving quality and freshness for specialty applications.
- Foil Packs:Heat-retaining packaging sometimes used for pre-cooked or hot fries in food service to maintain temperature during transport or for immediate consumption.
Bulk bags underpin large-scale food service operations. Retail boxes are gaining share fastest in the at-home segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale processed potato product exports from European and North American processing hubs increasingly flow into expanding Southeast Asian quick service restaurant markets. These regions also represent significant domestic consumption bases and innovation centers for product development. Regulatory frameworks across these areas influence production methods and market access for French fries.
United States
Quick service restaurant expansion and robust at-home consumption drive demand in the United States. US FDA standards strictly govern food safety and labeling for potato products. Idaho, a major potato-growing state, hosts significant processing facilities for national distribution.
Netherlands
European demand for processed potato products and extensive export capabilities define the Netherlands market. EFSA mandates on acrylamide levels force process adjustments across Dutch producers. Zeeland province, a key agricultural region, supports large-scale potato processing operations.
Vietnam
Shifting dietary habits and rapid proliferation of Western-style quick service restaurants increase demand in Vietnam. National food safety standards regulate imported frozen potato products entering the country. Ho Chi Minh City's urban centers exhibit concentrated demand for standardized fried potato offerings.
Indonesia
Urban household consumption of retail-packaged fries and quick service restaurant expansion propel demand in Indonesia. BPOM (Badan Pengawas Obat dan Makanan) enforces stringent food labeling requirements for all food imports. Jakarta, a sprawling metropolitan area, shows substantial growth in frozen product retail sales.
India
Quick service restaurant expansion and rising disposable incomes fuel market growth in India. The FSSAI (Food Safety and Standards Authority of India) implements stricter controls on trans-fats and sodium content. Punjab, a major potato-cultivating region, sees emerging processing units to serve domestic demand.
French Fries Market Key Industry Players
Channel-controlling players compete with product-specialist players within the French fries market. The industry structure shows consolidation among large-scale processors supplying global quick service restaurant chains. Strategic archetypes include integrated potato growers, high-volume frozen product manufacturers, and niche specialty cut providers. Companies pursue capacity expansion and portfolio diversification to capture market share.
Global processors like McCain Foods Limited and Lamb Weston Holdings Inc. exemplify the large-scale, international supply model. These entities maintain extensive logistics networks to serve major quick service restaurant chains worldwide. J.R. Simplot Company occupies a position anchored by significant backward integration into potato farming, ensuring raw material control.
| Leading Market Players |
|---|
| The Kraft Heinz Co |
| Aviko B.V. |
| McCain Foods Limited |
| Bart's Potato Company |
| Farm Frites International B.V. |
| Lamb Weston Holdings Inc |
| Agristo NV |
| Himalaya Food International Ltd |
| J.R. Simplot Company |
| Others |
Cost & Logistics Intelligence
Commodity volatility in specific potato varieties and edible oils determines both pricing tier spreads and the geographic shape of the French fries supply chain. This input cost variability directly impacts processor margins across all product types and end-user segments.
Pricing Analysis
The technology-generation pricing gap between industrial air frying and traditional deep-frying influences product pricing. Contract-based long-term offtake agreements dominate pricing for large quick service restaurant chains. Price differentiation stems from potato variety quality and processing efficiency. Pricing softness runs through the at-home retail segment due to intense competition. Quick service restaurants are least price-sensitive for consistent, high-volume supply.
Supply Chain Analysis
Commodity price volatility in specific potato varieties and edible oils presents a structural risk for French fries processors. Geographic supply concentration centers on potato-rich regions like Idaho in the United States and Zeeland in the Netherlands. Raw material dependencies include Russet Burbank potatoes and various edible oils. The cold chain logistics network is critical for distributing frozen products. Distribution runs primarily through large food service distributors to quick service restaurants globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The French fries market is an early-cycle expansion story, driven by the increasing penetration of western-style food service chains in emerging urban centers. This global shift in dietary habits presents substantial long-term volume growth.
For Market Incumbents:Pre-empt margin erosion from input cost volatility by deepening backward integration into potato farming. Invest in advanced processing technologies like industrial air frying to counter health-related regulation threats. Expand cold chain logistics in Southeast Asia to secure new quick service restaurant volume. McCain Foods Limited can leverage its global network to maintain supply stability.
For New Entrants and Emerging Players:Build out premium-priced niches with alternative vegetable fries from sweet potatoes or zucchini. Target fast-casual dining segments in North America and Western Europe for product novelty adoption. The most penetrable segment is health-conscious consumers seeking innovative side dishes. A go-to-market angle involves direct partnerships with specialty food distributors.
For Investors and Strategic Acquirers:The market sits at a growth phase that favors processors with strong technological differentiation and supply chain control. Long-term viability hinges on adapting to evolving nutritional guidelines and consumer demand for healthier options. Acquisition targets include mid-sized specialty fry manufacturers with unique product lines or regional processing capabilities. The signal to watch is the commercial adoption rate of industrial air frying technology.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Supports rapid quick service restaurant growth and captures new urban consumption. |
| Investment in Industrial Air Frying | Addresses health-related regulation and caters to health-conscious consumer demand. |
| Backward Integration into Potato Farming | Mitigates input cost volatility and ensures consistent raw material supply. |
| Diversification into Alternative Vegetable Fries | Captures premium-priced niches and attracts health-focused consumer segments. |
| Enhancement of Cold Chain Logistics | Ensures product quality and extends market reach into developing rural economies. |
Research Approach
Two parallel data streams informed the analysis: direct primary interviews with industry stakeholders and extensive secondary validation. This involved conversations with quick service restaurant procurement managers, potato processors, food technologists, and logistics specialists. Secondary sources included US FDA and EFSA regulatory documents, trade association reports, and company financial filings. A bottom-up and top-down triangulation approach ensured data accuracy.
Forecast inputs considered market dynamics, technological advancements, and evolving consumer preferences across the analysis window. The segmentation modeled product type, cooking method, end-user, packaging type, and regional regulatory frameworks. Compound annual growth rates were derived through a multifactorial assessment of historical trends and projected future drivers. Key inputs included quick service restaurant expansion rates and industrial air frying adoption metrics.
Sensitivities concentrate around shifts in commodity prices, new health regulations, and unforeseen supply chain disruptions. Forecasts reflect assumptions regarding market conditions and technological trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Pizza Market
Processed and Frozen Foods
Freeze Dried Fruits Market
Processed and Frozen Foods
Middle East and Africa Frozen Food Market
Processed and Frozen Foods
Frozen Shrimp Market
Processed and Frozen Foods
Spiral Freezer Market
Processed and Frozen Foods
Freeze Dried Tropical Fruits Market
Processed and Frozen Foods
Europe Frozen Desserts Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market
Processed and Frozen Foods
Frozen Mackerel Market
Processed and Frozen Foods
Cambodia Frozen Food Market
Processed and Frozen Foods
Dehydrated Potato Products Market
Processed and Frozen Foods
Icebreakers Market
Processed and Frozen Foods
Europe Frozen Food Market
Processed and Frozen Foods
Frozen Baby Food Market
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
Deli Meat Market