
 Europe Ice Cream Market | 2026-2036
Europe Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ice Cream Market Analysis
A capital-intensity divergence between artisan craft producers and industrial scale manufacturers is redrawing competitive boundaries in frozen desserts. Unilever Group leverages its pan-European distribution infrastructure to sustain volume leadership across multiple price tiers. Nestlé SA anchors its position through in-house dairy sourcing and controlled cold chain logistics. Froneri International Limited differentiates via specialized gelato manufacturing expertise acquired through focused brand portfolio development.
Europe ice cream comprises a frozen dairy or water-based confection typically containing milk fat, sugar, air overrun of 20-100%, and stabilizer systems, produced through continuous freezing and hardening processes for retail and foodservice consumption. The product type segment shows gelato commanding premium margin pools due to lower overrun and denser texture positioning, while hard ice cream dominates volume through supermarket tub distribution. Distribution channel dynamics reveal foodservice recovering experiential consumption occasions, though supermarkets retain baseline household replenishment frequency across pouches and tub packaging formats.
EFSA governs food additive authorizations including emulsifiers and stabilizers in frozen dessert formulations, while ECHA oversees REACH compliance for processing equipment materials and packaging substrates. The EU Green Deal is pressuring manufacturers to reformulate toward lower-carbon dairy sourcing and recyclable mono-material packaging structures. Stakeholders must monitor F-Gas Regulation phase-down timelines for freezer cabinet replacements and assess plant-based fat system investments ahead of evolving EFSA novel food opinions on precision fermentation-derived ingredients.
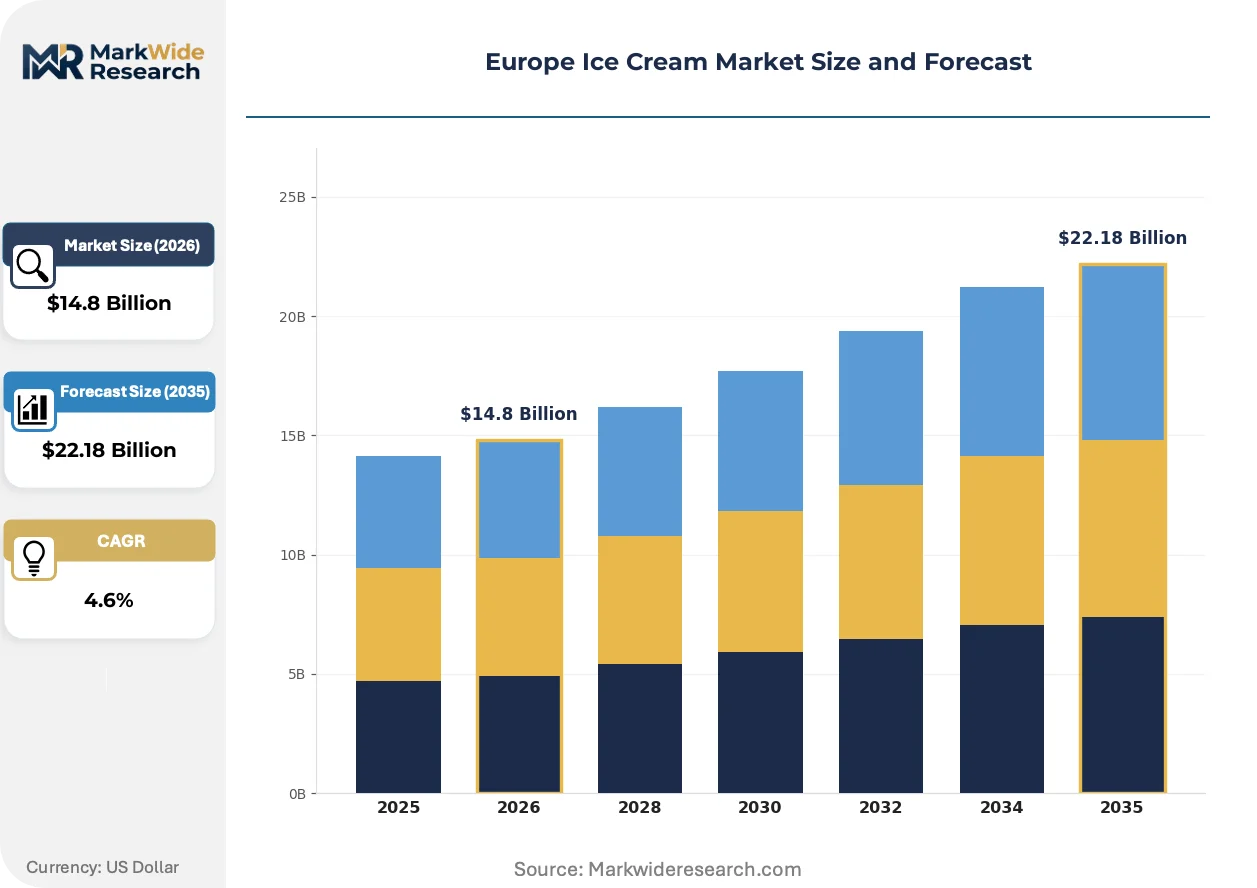
Market Dynamics
The EU F-Gas Regulation is forcing frozen dessert manufacturers to accelerate cold chain infrastructure replacement timelines while simultaneously absorbing capital costs for lower-carbon refrigeration systems. This regulatory pressure intersects with artisanal gelato's premium positioning to create divergent investment paths across the value chain.
Growth Catalysts
- EU Green Deal carbon accounting:Manufacturers reformulating toward lower-carbon dairy sourcing gain preferential shelf placement in German and French retail networks.
- Gelato experiential positioning:Adult consumers in Italy and Spain allocate higher per-occasion spending for denser texture formats with authentic provenance narratives.
- Foodservice channel recovery:Post-pandemic experiential consumption occasions in Milan, Barcelona, and Paris drive premium tub and stick format demand.
Market Restraints
- Dairy input cost volatility:Butterfat and milk powder price swings compress margin predictability for mid-tier producers dependent on spot purchasing.
- Supply concentration in Italian gelato equipment:Carpigiani and Cattabriga dominate artisanal batch freezer manufacturing, creating procurement bottlenecks for new market entrants.
- Substitution from frozen yogurt and sorbet:Health-positioned alternatives capture lactose-intolerant and reduced-calorie consumer segments in Nordic markets.
Strategic Opportunities
- Underpenetrated Eastern European markets:Poland and Romania show accelerating freezer cabinet penetration in modern trade formats with localized flavor development.
- Precision fermentation-derived dairy proteins:EFSA novel food approval pathways for animal-free fat systems enable reformulation for carbon-conscious premium lines.
- Direct-to-foodservice distribution platforms:Digital ordering infrastructure bypasses traditional wholesale intermediaries for artisanal producers in London and Amsterdam.
Industry Challenges
- Gelato craftsmanship skill scarcity:Traditional pasteurization and aging technique mastery is concentrating among aging Italian and French workforce cohorts.
- Refrigeration capex intensity:F-Gas compliant freezer cabinet replacement cycles strain working capital for independent foodservice operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ice Cream Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelato, Sorbet, Soft Serve, Hard Ice Cream Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Foodservice Packaging Type: Cups, Cones, Tubs, Pouches Flavor Profile: Vanilla, Chocolate, Strawberry, Mint |
| Companies Covered | Froneri International Limited, Unilever Group, Nestlé SA, General Mills, DMK Group, Danone S.A., Mars Incorporated, Glacier, Mondelez International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ice Cream Market Emerging Trajectories
Refrigeration technology and formulation science are converging to reshape competitive boundaries between industrial scale and artisanal craft production. Three developments merit particular attention.
Advanced blast freezing equipment with precision temperature profiling is miniaturizing. Boutique gelato shops in Rome and Turin adopt compact continuous freezers previously restricted to industrial plants. This compression of capital requirements enables micro-producers to achieve texture consistency rivaling established manufacturers.
REACH compliance for processing equipment materials is tightening. ECHA scrutiny of nickel and chromium migration from aging batch freezer bowls forces stainless steel grade upgrades. Italian equipment manufacturers face compressed redesign timelines to maintain CE marking validity for export markets.
Experiential retail formats are displacing conventional impulse purchase occasions. Flagship gelato boutiques in Paris and Barcelona integrate production visibility with tasting rituals. This channel evolution concentrates margin capture at the point of consumption rather than through packaged retail distribution.
Europe Ice Cream Market Segmentation
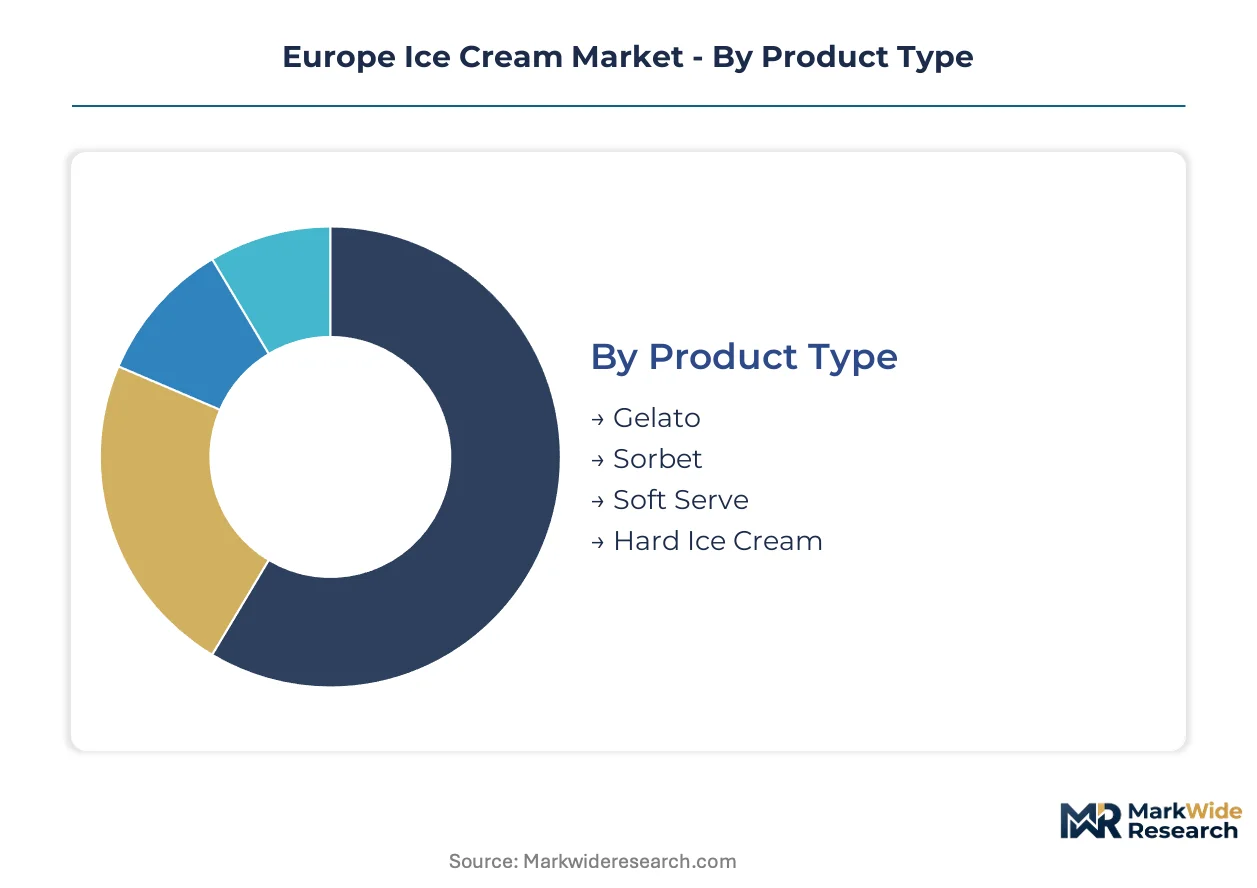
Segment boundaries in European frozen desserts reflect divergent pressure from health-positioned alternatives and experiential consumption formats. Manufacturers must align portfolio depth with channel-specific margin structures and regulatory compliance costs.
Product Type:
Substitution pressure from frozen yogurt and plant-based alternatives hits water-based and dairy-light segments hardest, while dense-texture formats defend through provenance positioning.
- Gelato:Lower overrun of 20-35% produces denser texture and intensified flavor delivery. Italian consumers in Milan and Turin drive premium per-occasion spending for authentic artisanal provenance narratives.
- Hard Ice Cream:Higher overrun of 50-100% enables efficient mass production and extended shelf stability. German and French supermarkets anchor household replenishment frequency through multi-liter tub formats.
- Sorbet:Water-based formulation with fruit puree concentration targets lactose-intolerant and reduced-calorie segments. Nordic markets show strongest adoption for health-positioned dessert occasions.
- Soft Serve:Fresh-frozen preparation with 30-50% overrun serves immediate consumption occasions. Beachfront and amusement park foodservice operators in Spain and Greece concentrate seasonal demand.
Hard ice cream retains volume leadership; gelato holds the steepest expansion curve.
Distribution Channel:
Cost tier stratification separates capital-intensive cold chain operators from asset-light digital intermediaries, with margin capture concentrating at poles of the value chain.
- Supermarkets:Multi-temperature logistics and dedicated freezer aisle placement sustain baseline household penetration. Carrefour and REWE networks in France and Germany prioritize private label and national brand shelf space allocation.
- Foodservice:Gelato boutiques and restaurant dessert programs command premium pricing through experiential consumption rituals. Paris, Barcelona, and Rome concentrate flagship format development with visible production theater.
- Convenience Stores:Impulse-oriented single-serve formats with limited freezer capacity favor established brands with direct store delivery infrastructure. Urban transit-adjacent locations in London and Amsterdam drive grab-and-go velocity.
- Online Retail:Insulated packaging and same-day cold chain fulfillment enable subscription and bulk replenishment models. Ocado and Getir operations in UK and Netherlands test direct-to-home frozen dessert logistics economics.
Supermarkets retain volume leadership; online retail gains share fastest.
Packaging Type:
Application-driven format selection balances portion control, consumption occasion, and EFSA-compliant material compliance costs.
- Tubs:Rigid polypropylene or paperboard structures serve multi-portion household stock-up occasions. German retail networks drive standardization toward recyclable mono-material formats under EU Green Deal pressure.
- Cones:Edible wafer or sugar-based carriers eliminate secondary waste for immediate consumption. Italian gelaterias emphasize artisanal cone production as part of visible craft theater.
- Cups:Single-serve paper or bioplastic vessels portion-control impulse purchases. Convenience channel operators in France favor branded cup formats for brand visibility in limited freezer space.
- Pouches:Flexible multi-layer structures enable squeezable and novelty formats for children's segments. UK supermarkets test pouch reduction to meet plastic packaging tax compliance.
Tubs retain volume leadership; cones show strongest margin expansion.
Flavor Profile:
Maturity gradients separate heritage-positioned staples from innovation-dependent seasonal rotations, with geographic preference clusters driving localization requirements.
- Vanilla:Bourbon and Tahitian varietal positioning enables premium tier differentiation within seemingly commodity segment. French producers emphasize Madagascar provenance for gastronomic credibility.
- Chocolate:Cocoa percentage and origin labeling support craft positioning in Italian and Belgian markets. Sustainability certifications increasingly influence retail buyer selection criteria.
- Strawberry:Seasonal fruit content claims and local sourcing narratives defend against private label substitution. Spanish producers leverage Huelva strawberry harvest proximity for freshness positioning.
- Mint:Limited but loyal consumer base concentrates in UK and Ireland markets. Peppermint oil sourcing from Mitcham and Pacific Northwest supplies distinct regional formulations.
Vanilla retains volume leadership; chocolate climbs the fastest on premium tier expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian consumers demonstrate the lowest price elasticity for gelato, paying premiums for artisanal provenance, while Polish and Romanian buyers remain highly sensitive to per-liter pricing in supermarket channels.
Italy
Milan and Turin sustain Europe's densest concentration of artisanal gelaterias, with consumers prioritizing texture density and origin narratives over cost. EFSA novel food pathways for precision fermentation ingredients attract reformulation investment from Lombardy-based producers. The Carpigiani manufacturing cluster around Bologna supplies batch freezer technology across Mediterranean export markets.
Germany
Supermarket private label and national brand competition in Berlin and Munich drives volume purchasing through multi-liter tub formats. EU Green Deal carbon accounting requirements pressure REWE and Edeka networks to prioritize lower-carbon dairy sourcing claims. Bavarian dairy cooperatives anchor industrial-scale production capacity serving Central European distribution networks.
France
Paris concentrates flagship gelato boutique development where experiential retail formats command per-occasion premiums. REACH compliance timelines from ECHA force stainless steel equipment upgrades across processing facilities in Île-de-France. Madagascar vanilla provenance positioning dominates premium tier differentiation strategies among gastronomic retailers.
Spain
Barcelona and Madrid foodservice operators recover experiential consumption occasions with visible production theater formats. F-Gas Regulation phase-down accelerates freezer cabinet replacement cycles for beachfront soft-serve operators in Costa del Sol. Huelva strawberry harvest proximity enables seasonal freshness claims defending against private label substitution.
Poland
Accelerating modern trade freezer cabinet penetration in Warsaw and Krakow creates localized flavor development opportunities. Dairy input cost volatility from spot purchasing patterns compresses margin predictability for mid-tier producers. Emerging direct-to-foodservice digital platforms test bypass of traditional wholesale intermediaries for artisanal entrants.
Europe Ice Cream Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in Europe's frozen dessert structure. Pan-European distribution infrastructure and captive dairy sourcing separate scale operators from craft producers dependent on regional cold chain partnerships. Three archetypes dominate: diversified FMCG conglomerates with frozen dessert divisions, specialized gelato-focused manufacturers, and private-label suppliers serving retail networks. Competitive moves concentrate on portfolio diversification across premium and standard tiers, plus strategic partnerships for plant-based fat system development.
Within the diversified conglomerate tier, Unilever Group and Nestlé SA occupy positions defined by pan-European logistics scale and backward integration into dairy supply chains. Froneri International Limited exemplifies the specialized gelato archetype through focused brand portfolio concentration. These three anchors illustrate how capital intensity and cold chain control separate volume leadership from craft positioning in frozen dessert competition.
| Leading Market Players |
|---|
| Froneri International Limited |
| Unilever Group |
| Nestlé SA |
| General Mills |
| DMK Group |
| Danone S.A. |
| Mars Incorporated |
| Glacier |
| Mondelez International |
| Others |
Supply Flow & Price Mechanics
Long-term dairy offtake contracts with Bavarian and Lombardy cooperatives lock in butterfat supply visibility for industrial manufacturers while exposing artisanal producers to spot market volatility. This contract-structure divergence concentrates pricing power among scale operators with backward-integrated milk powder sourcing.
Pricing Analysis
After-sales service revenue from freezer cabinet maintenance contracts drives lifetime value for equipment manufacturers serving the foodservice channel. Three-tier pricing structure across premium artisanal gelato, standard packaged formats, and economy private-label tiers separates margin pools. Cost compression in mid-tier hard ice cream intensifies because German retailers prioritize lower-carbon dairy claims over brand loyalty. Polish and Romanian supermarket buyers exhibit highest price sensitivity, while Milan and Paris foodservice operators accept per-occasion premiums for provenance positioning.
Supply Chain Analysis
Italy and Germany anchor European frozen dessert production, with Bologna housing the Carpigiani equipment cluster and Bavaria concentrating industrial-scale dairy processing. Butterfat, milk powder, and vanilla extract feed formulation costs, with Madagascar and Tahitian bean sourcing tethered to currency and harvest volatility. Single-source vulnerability in artisanal batch freezer procurement from Italian manufacturers exposes new entrants to extended lead times. Distribution runs through temperature-controlled logistics networks serving Carrefour and REWE retail systems, plus direct-to-gelateria routes in Mediterranean markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as experiential consumption splits demand between industrial scale and craft authenticity, creating niche positioning space for specialized operators.
For Market Incumbents: Secure captive dairy sourcing through cooperative equity stakes in Bavaria and Lombardy to defend against butterfat spot price volatility. Consolidate foodservice distribution infrastructure in Paris and Barcelona before artisanal digital platforms bypass traditional wholesale channels. EFSA novel food approval timelines for precision fermentation ingredients represent the critical R&D lever for carbon-neutral premium line extensions. For New Entrants and Emerging Players: Differentiate on localized Eastern European flavor development in Warsaw and Krakow where modern trade freezer penetration accelerates without entrenched competitor presence. Target direct-to-foodservice digital ordering platforms in London and Amsterdam where traditional distribution intermediaries retain margin capture. White-space concentration in Romanian market development offers lowest competitive density for private-label supply partnerships. For Investors and Strategic Acquirers: Capital is best deployed toward specialized gelato equipment manufacturers with REACH-compliant stainless steel redesign capabilities and export market CE marking validity. Long-term viability over the medium-term projection horizon rests on regulatory compliance infrastructure rather than volume scale alone. EFSA opinions on precision fermentation-derived dairy proteins signal the inflection point for animal-free fat system investment prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Supply | Bavarian cooperative equity stakes lock in butterfat cost visibility against spot market swings. |
| Direct-to-Foodservice Digital Platform Launch | London and Amsterdam ordering infrastructure bypasses wholesale margin extraction for artisanal producers. |
| F-Gas Compliant Equipment Redesign | Italian manufacturers face compressed timelines to maintain CE marking validity for export markets. |
| Precision Fermentation Partnership | EFSA novel food pathways enable carbon-neutral premium positioning ahead of regulatory approval. |
| Eastern European Flavor Localization | Polish and Romanian modern trade expansion creates first-mover advantage in underpenetrated freezer cabinet networks. |
Methodological Framework
A standing panel of gelateria owners, dairy cooperative procurement managers, retail category buyers at Carrefour and REWE, and EFSA regulatory affairs specialists provided ongoing calibration throughout the study period. Primary interview findings triangulated against secondary sources including EU dairy trade statistics, ECHA REACH compliance databases, and supermarket private-label assortment data. Bottom-up volume modeling across product type and distribution channel segments converged with top-down macroeconomic anchoring.
Consistency checks validated volume and value outputs against external benchmarks including customs records for gelato equipment exports and Nielsen retail audit data for packaged ice cream velocity. Segmentation dimensions modeled encompass product type, distribution channel, packaging format, and regional consumption cluster across the analysis window. CAGRs derived from historical trajectory analysis adjusted for F-Gas Regulation compliance cost absorption and EU Green Deal carbon accounting adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained dairy input cost stability and EFSA novel food approval timelines would require recalibration. Forecasts reflect documented assumptions regarding cold chain infrastructure replacement cycles and experiential consumption recovery patterns. Recalibration cycles align with material shifts in F-Gas phase-down enforcement and precision fermentation regulatory determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Novelty Market
Processed and Frozen Foods
Frozen Ready Meals Market
Processed and Frozen Foods
Refrigerated Liquid Eggs Market
Processed and Frozen Foods
North America Freeze Dried Products Market
Processed and Frozen Foods
Freeze Dried Fruits Market
Processed and Frozen Foods
Frozen Baby Food Market
Processed and Frozen Foods
Middle East and Africa Frozen Food Market
Processed and Frozen Foods
United States Frozen Yogurt Market
Processed and Frozen Foods
Deli Meat Market
Processed and Frozen Foods
Frozen Dumplings Market
Processed and Frozen Foods
Popsicle and Ice Cream Bar Market
Processed and Frozen Foods
Europe Frozen Desserts Market
Processed and Frozen Foods
Frozen Yogurt Market
Processed and Frozen Foods
Chocolate Ice Cream Market
Processed and Frozen Foods
Scandinavia Frozen Food Market
Processed and Frozen Foods
North America Frozen Pizza Market