
 Frozen Sardine Market | 2026-2036
Frozen Sardine Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Sardine Market Insights
Plant-based protein alternatives is decoupling frozen sardine pricing from traditional commodity fish benchmarks in select retail channels. Marine Harvest AS leverages its integrated aquaculture infrastructure to sustain year-round supply consistency for European buyers. Thai Union Group anchors its competitive stance through scale advantages in Southeast Asian processing. King Oscar differentiates via premium branding and controlled retail shelf positioning in Nordic markets.
Frozen sardine denotes small pelagic fish preserved at temperatures below minus eighteen degrees Celsius to arrest enzymatic degradation and maintain omega-3 fatty acid integrity; blast freezing remains the dominant industrial method due to its throughput efficiency and minimal ice crystal formation. The product serves as a cost-effective protein input for human consumption, pet nutrition, and fishmeal derivatives. Frozen whole sardines dominate volume flows into African and Asian wholesale channels where downstream processing occurs locally. Individually quick frozen fillets command margin premiums in European retail chains demanding portion-controlled convenience. Block frozen formats retain cost leadership for food manufacturers operating dedicated thaw-and-process lines.
FDA seafood HACCP regulations govern US import safety protocols while EU EFSA maximum residue limits for histamine shape Atlantic supplier compliance costs. Morocco's national fisheries office and the country's food safety authority enforce landing quotas and cold-chain certification for export-bound product. Stakeholders must monitor evolving EU Green Deal sustainability traceability requirements and their cascading documentation burdens on Mediterranean and West African supply origins.
Market Dynamics
EU Green Deal sustainability traceability requirements are forcing Atlantic suppliers to reconfigure documentation systems and cold-chain verification protocols ahead of enforcement deadlines.
Growth Catalysts
- Pet food protein reformulation:Manufacturers are redirecting sourcing toward marine ingredients as they reduce land-based protein dependence. This end-use vertical now absorbs expanding frozen sardine volumes for premium kibble and wet food formulations.
- EFSA histamine compliance infrastructure:Moroccan coastal processors have invested in rapid-testing cold-chain certification. These facilities now capture expanded European retail placement through verified safety documentation.
- Blast freezing throughput efficiency:Industrial freezing technology preserves omega-3 integrity at scale. Processing clusters in Agadir and Safi leverage this method to serve high-volume food manufacturers.
Market Restraints
- Atlantic catch-limit constraints:The EU's Common Fisheries Policy revisions have reduced allowable harvesting volumes. Moroccan and Spanish fleets face compressed quota allocations that constrain raw material availability.
- Plant-based protein substitution:Pea and soy protein isolates are capturing formulation share in mid-tier pet food segments. Alternative proteins decouple pricing from traditional fish commodity benchmarks in select retail channels.
- Histamine testing cost burden:EFSA maximum residue limits require dedicated laboratory infrastructure. Small-scale West African suppliers lack capital to deploy compliant testing protocols.
Strategic Opportunities
- IQF fillet penetration in German retail:Portion-controlled convenience formats command margin premiums in European supermarket chains. Dedicated thaw-and-process lines at food manufacturers sustain demand for this higher-value product form.
- EU Green Deal traceability mandates:Early compliance with sustainability documentation requirements creates preferential supplier status. Moroccan exporters positioning ahead of enforcement capture shelf-space commitments from major retailers.
- Blockchain-cold chain convergence:Distributed ledger verification integrated with temperature monitoring is consolidating trust architectures. This technology pairing enables direct-to-retailer contracts that bypass traditional wholesale layers.
Industry Challenges
- Skilled cold-chain technician scarcity:Moroccan processing clusters face recruitment gaps for blast-freezing equipment specialists. Training pipelines lag behind facility expansion timelines.
- Legacy documentation system integration:Small-scale Atlantic suppliers struggle to retrofit paper-based traceability for EU digital submission requirements. Compliance timeline compression strains IT infrastructure budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Sardine Market |
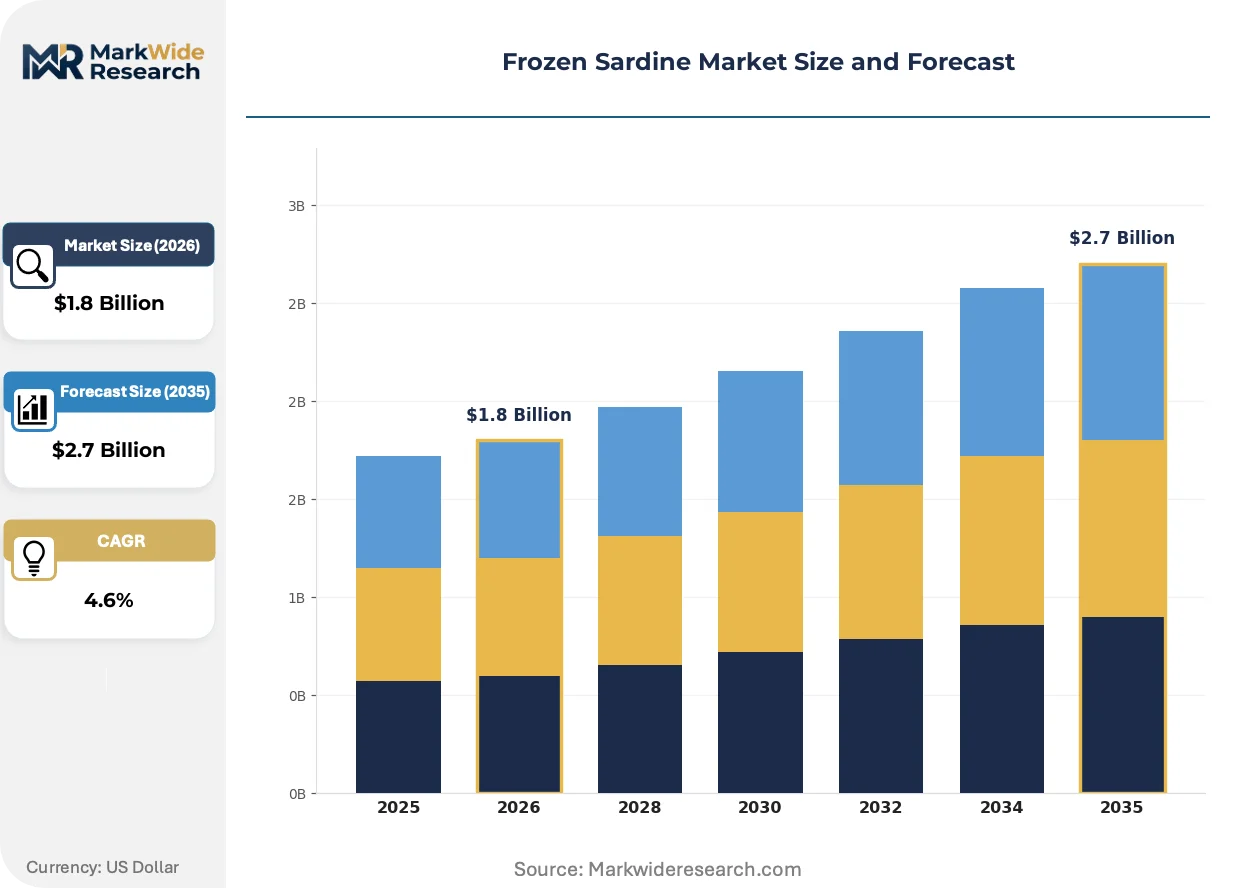
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Whole, Frozen Fillets, Frozen Steaks, Frozen Minced Processing Method: Individually Quick Frozen, Block Frozen, Cryogenic Frozen, Blast Frozen End User: Seafood Distributors, Food Manufacturers, Restaurants, Retail Chains Packaging Type: Vacuum Packed, Plastic Bags, Cardboard Cartons, Frozen Trays |
| Companies Covered | Marine Harvest AS, Xiamen Taiseng Seafoods, WHOLEY'S, Alga International, China Boasea Seafood, Thai Union Group, Bumble Bee Seafoods, King Oscar, Pescanova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Sardine Market Trends and Innovations
Processing technology and regulatory architecture are converging to reshape competitive positioning in frozen sardine supply chains. Three developments warrant particular attention.
Blast freezing with optimized airflow control is consolidating quality differentiation between industrial-scale Moroccan processors and smaller competitors. Pet food manufacturers and European retail chains are adopting IQF fillets at accelerating rates as portion consistency reduces downstream waste. This technology compression is enabling direct contracting models that disintermediate traditional wholesale layers.
EU Green Deal sustainability traceability requirements are mandating granular catch-documentation and cold-chain verification. Atlantic suppliers must now deploy blockchain-enabled tracking from vessel to retail shelf. Moroccan exporters with early compliance infrastructure are capturing preferential placement in Nordic and German supermarket chains.
Buyer concentration among European pet food conglomerates is compressing procurement cycles and demanding year-round supply consistency. Long-term volume commitments are replacing spot-market purchasing for premium-grade frozen sardine. This contractual shift is most visible in German and Dutch manufacturing hubs where reformulation timelines require predictable input security.
Frozen Sardine Market Segmentation
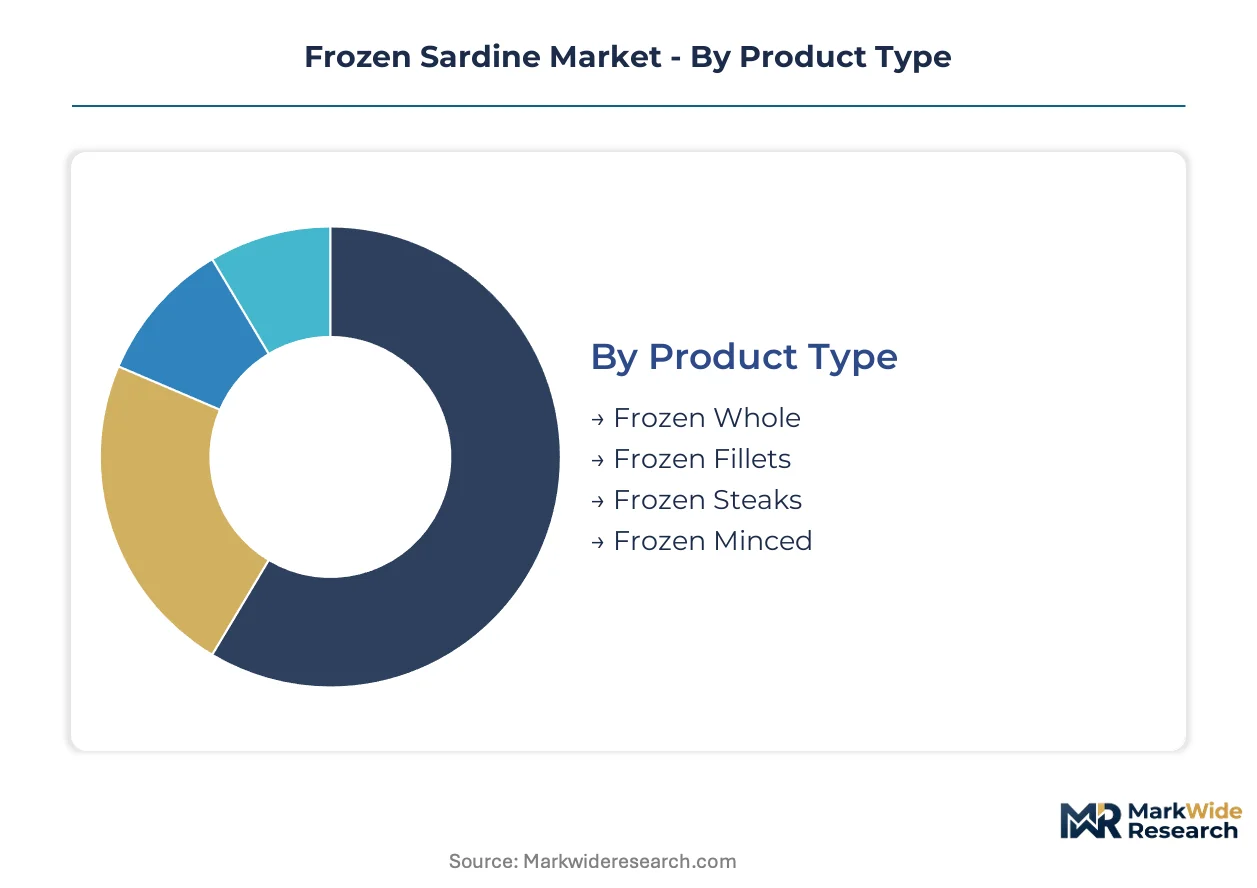
Frozen sardine supply chains fragment across four structural dimensions that determine margin capture and procurement patterns. Product form and processing technology define cold-chain economics, while end-user concentration and packaging specifications shape downstream distribution architectures.
Product Type:
Supply concentration in Moroccan coastal clusters favors formats that maximize blast-freezing throughput and minimize handling damage.
- Frozen Whole:Unprocessed fish preserved in round form for downstream filleting at destination markets. African wholesale channels and Asian processing hubs absorb the largest volumes, driven by labor cost arbitrage in manual processing operations.
- Frozen Fillets:Deboned and portion-controlled cuts preserved through IQF or blast freezing. European retail chains in Germany and France concentrate demand here, with pet food manufacturers now driving the steepest expansion trajectory for premium-grade material.
- Frozen Steaks:Cross-section cuts retaining bone structure for grilling applications. Mediterranean foodservice distributors maintain steady procurement for traditional preparation methods.
- Frozen Minced:Mechanically separated flesh for surimi and fishcake production. Southeast Asian processors source this format for restructured seafood manufacturing.
Today's leader: Frozen Whole. Tomorrow's challenger: Frozen Fillets.
Processing Method:
Cost tier separation between industrial-scale operators and smaller competitors hinges on freezing technology selection and energy efficiency.
- Blast Frozen:High-velocity cold air circulation achieves rapid temperature reduction with minimal ice crystal formation. Agadir and Safi processing clusters deploy this method to serve high-volume European food manufacturers demanding omega-3 integrity at scale.
- Individually Quick Frozen:Single-piece freezing enables portion control and reduces thaw waste. German supermarket chains and Nordic retail buyers concentrate procurement here, paying margin premiums for convenience and presentation consistency.
- Block Frozen:Bulk freezing in rectangular forms for industrial thaw-and-process lines. Cost-sensitive African distributors and fishmeal producers favor this format for maximum yield per cubic meter of cold storage.
- Cryogenic Frozen:Liquid nitrogen or carbon dioxide immersion for ultra-rapid temperature reduction. Premium sashimi-grade applications in Japanese and South Korean markets absorb limited but high-value volumes.
Blast freezing commands volume leadership. IQF is gaining share fastest in European retail placement.
End User:
Customer type concentration determines contract structure, with procurement cycles compressing among buyers requiring year-round supply security.
- Food Manufacturers:Industrial processors of canned, dried, and value-added sardine products. Moroccan and Spanish canneries anchor demand, though pet food reformulation in German and Dutch manufacturing hubs is expanding marine protein procurement.
- Seafood Distributors:Wholesale intermediaries consolidating volumes for redistribution to smaller retail and foodservice accounts. West African landing ports and Marseille trading houses maintain traditional channel dominance.
- Retail Chains:Supermarket operators demanding portion-controlled, labeled, and traceable product. E.Leclerc, Carrefour, and REWE Group specifications are forcing upstream compliance investments.
- Restaurants:Foodservice operators from casual dining to institutional catering. Mediterranean coastal tourism markets and Portuguese tasca networks sustain seasonal demand spikes.
Food manufacturers dominate contract volumes. Retail chains are tightening procurement specifications fastest.
Packaging Type:
Margin differentiation across packaging tiers reflects cold-chain duration requirements and retail presentation standards.
- Vacuum Packed:Oxygen-exclusion barrier films extending shelf life and preventing freezer burn. Premium European retail and direct-to-consumer channels concentrate here, with EU Green Deal traceability labeling adding documentation layers.
- Plastic Bags:Polyethylene or polypropylene flexible packaging for cost-sensitive bulk distribution. African wholesale channels and industrial food manufacturers prioritize unit economics over shelf presentation.
- Cardboard Cartons:Corrugated outer shells for palletized logistics and brand visibility. Nordic retail chains specify printed cartons for controlled shelf positioning.
- Frozen Trays:Rigid plastic or aluminum containers for oven-ready presentation. UK and French supermarket private-label programs drive format innovation here.
Vacuum packed leads premium placement. Frozen trays are climbing fastest in convenience-oriented retail segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agadir-Safi coastal processing clusters anchor frozen sardine supply flows into European retail chains, with Moroccan infrastructure investments reshaping Atlantic sourcing patterns.
Morocco
Pet food manufacturers in Germany and the Netherlands drive Moroccan export volumes as they reformulate protein sourcing away from land-based inputs. The national fisheries office enforces landing quotas and cold-chain certification for export-bound product. Agadir and Safi processing clusters deploy blast-freezing infrastructure to serve high-volume European food manufacturers demanding omega-3 integrity at scale.
Spain
Atlantic canneries and frozen distributors absorb significant volumes for domestic consumption and re-export to Latin American markets. EU EFSA maximum residue limits for histamine shape supplier compliance costs and testing protocols. Galician fishing ports and Vigo-based processing facilities maintain traditional channel dominance despite compressed quota allocations under Common Fisheries Policy revisions.
Germany
Supermarket chains REWE Group and E.Leclerc specifications force upstream compliance investments in traceability and portion control. EU Green Deal sustainability documentation requirements mandate granular catch-verification from Atlantic suppliers. Hamburg and Bremen distribution hubs consolidate volumes for redistribution to Central European retail and foodservice accounts.
France
Mediterranean foodservice distributors sustain seasonal demand spikes from coastal tourism markets and traditional tasca networks. EFSA histamine testing protocols filter supplier eligibility for frozen fillet procurement. Marseille trading houses maintain wholesale intermediary functions, though direct-to-retailer contracting is displacing traditional layers.
Thailand
Southeast Asian processing infrastructure serves surimi and fishcake manufacturing for Japanese and South Korean markets. Thai Union Group anchors regional competitive stance through scale advantages in block-frozen format production. Bangkok-based exporters leverage cryogenic freezing capabilities for limited but high-value sashimi-grade applications.
Frozen Sardine Market Competitive Landscape
Global majors compete with regional champions across processing scale and retail shelf positioning, with market structure tiering between integrated aquaculture operators and specialized coastal processors. Consolidation pressure concentrates among European pet food conglomerates demanding year-round supply security. Three archetypes dominate: vertically integrated Nordic salmon farmers extending into pelagic species, Southeast Asian scale processors, and Moroccan coastal cluster specialists. M&A activity targets cold-chain certification assets, while capacity expansion focuses on IQF fillet lines for premium retail placement.
Within the integrated aquaculture tier, Marine Harvest AS exemplifies Nordic infrastructure leverage for supply consistency. Thai Union Group and King Oscar occupy distinct positioning vectors—scale-driven Southeast Asian processing versus premium branding with controlled retail shelf positioning in Nordic markets. These three entities represent the structural fault lines between volume leadership, geographic anchoring, and brand-premium strategies that competitors must navigate.
| Leading Market Players |
|---|
| Marine Harvest AS |
| Xiamen Taiseng Seafoods |
| WHOLEY'S |
| Alga International |
| China Boasea Seafood |
| Thai Union Group |
| Bumble Bee Seafoods |
| King Oscar |
| Pescanova |
| Others |
Pricing and Supply Chain Analysis
Family-owned Moroccan coastal processors anchor supply concentration along the Agadir-Safi corridor, enabling disciplined pricing power through blast-freezing infrastructure that smaller West African competitors cannot replicate. Their sovereign-backed financing access from the national fisheries office reinforces long-term contract security with European pet food manufacturers and retail chains, compressing spot-market volatility into predictable annual pricing frameworks.
Pricing Analysis
Input-cost pass-through from Atlantic quota constraints and energy-intensive blast-freezing operations shapes contract negotiations between Moroccan exporters and German retail buyers. Pricing stratifies across IQF fillet premiums for portion-controlled convenience, blast-frozen whole fish for industrial food manufacturers, and block-frozen economy tiers for African wholesale channels. Cost compression in the economy tier is intensifying because small-scale West African suppliers lack EFSA histamine testing infrastructure, forcing volume concentration among Moroccan facilities with certified cold-chain documentation. Pet food manufacturers demonstrate lowest price sensitivity due to reformulation timelines requiring supply security, while African distributors remain most responsive to unit-cost fluctuations.
Supply Chain Analysis
Workforce availability constraints in Agadir and Safi processing clusters limit blast-freezing equipment specialist recruitment, forcing facility expansion timelines to lag behind demand growth from European pet food reformulation. Supply concentrates in Morocco, Spain, and Thailand, with raw material dependencies on Atlantic sardine landings, cryogenic freezing gases, and EU-compliant packaging films. Single-source vulnerability runs through Moroccan coastal infrastructure for EFSA-certified export capacity. Distribution runs through Hamburg and Bremen consolidation hubs for Central European redistribution, with direct-to-retailer contracting displacing traditional Marseille trading house intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through IQF fillet premiumization as pet food manufacturers absorb higher input costs for traceable marine protein, while blast-freezing scale economies compress unit costs for compliant Moroccan processors.
For Market Incumbents: Cement supply security through backward integration into Moroccan coastal landing rights and blast-freezing capacity expansion ahead of EU Green Deal enforcement deadlines. Plant-based protein substitution in mid-tier pet food segments threatens volume absorption, demanding defensive certification investments in blockchain-cold chain traceability to lock in German retail shelf commitments. For New Entrants and Emerging Players: Enter via cryogenic freezing specialization for sashimi-grade exports to Japanese and South Korean markets, where limited supply and high value-per-unit offset capital intensity. The most penetrable white-space sits in EFSA-compliant testing infrastructure for small-scale West African suppliers seeking European market access, with go-to-market execution through technology licensing partnerships rather than asset-heavy facility construction. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Moroccan processors lacking IQF fillet lines but holding EFSA certification assets ripe for capability upgrade. Long-term viability hinges on contractual shift from spot-market purchasing to year-round volume commitments with pet food conglomerates, with the inflection signal to monitor being German supermarket chain direct-to-processor contracting volume displacing wholesale intermediary layers.| Strategic Initiative | Industry Significance |
|---|---|
| IQF Fillet Line Capacity Expansion | Captures margin premiums from REWE Group and E.Leclerc portion-control specifications. |
| Blockchain-Cold Chain Integration | Enables EU Green Deal compliance and direct-to-retailer contracting bypassing Marseille intermediaries. |
| Backward Integration into Landing Rights | Secures raw material access against Common Fisheries Policy quota compression for Atlantic fleets. |
| Cryogenic Freezing Capability Addition | Opens high-value sashimi-grade access to Japanese and South Korean premium markets. |
| EFSA Histamine Testing Infrastructure Licensing | Monetizes compliance capability among small-scale West African suppliers excluded from European retail. |
Research Methodology
Bottom-up pet food manufacturer and retail chain modeling reconciled against top-down Moroccan processing capacity and Atlantic landing tracking forms the analytical core of this study. Primary interviews with blast-freezing equipment specialists, EFSA compliance officers at Moroccan coastal facilities, German supermarket category buyers, and pet food procurement directors combined with secondary validation from EU Common Fisheries Policy quota filings, EFSA maximum residue limit documentation, Moroccan national fisheries office landing statistics, and Hamburg customs re-export records. Triangulation across these sources ensures volume and value estimates reflect actual contract flows rather than reported capacity alone.
Historical trendline analysis of frozen sardine trade flows, processing technology adoption curves, and regulatory compliance cost trajectories informed projection modeling across the analysis window. Segmentation dimensions include product form, processing method, end-user concentration, and packaging specification, with CAGRs derived from elasticity modeling against pet food protein reformulation rates and EU sustainability documentation enforcement timelines. Forecast inputs incorporate Moroccan cold-chain infrastructure investment pipelines and Atlantic biomass survey data from fisheries research institutes.
The model holds under stable EU Green Deal implementation schedules and continued pet food manufacturer marine protein sourcing commitment; deviation in Atlantic sardine biomass assessments or abrupt EFSA histamine limit tightening would shift volume and value trajectories. Forecasts reflect documented assumptions regarding processing technology adoption rates and contractual purchasing pattern persistence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Meat and Fish Market
Processed and Frozen Foods
Europe Dehydrated Food Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
South America Freeze Dried Products Market
Processed and Frozen Foods
Frozen Fruit Bars Market
Processed and Frozen Foods
Frozen Mackerel Market
Processed and Frozen Foods
Europe Frozen Pizza Market
Processed and Frozen Foods
Frozen Potato Market
Processed and Frozen Foods
Ice Cream and Frozen Dessert Market
Processed and Frozen Foods
Middle East and Africa Ice Cream Market
Processed and Frozen Foods
Dry Mix Base for Frozen Desserts Market
Processed and Frozen Foods
Cold Cuts Market
Processed and Frozen Foods
Europe Freeze-Dried Products Market
Processed and Frozen Foods
Bangladesh Frozen Food Market
Processed and Frozen Foods
Frozen French Fries Market
Processed and Frozen Foods
Germany Frozen Snack Market