
 Asia-Pacific Frozen Food Market | 2026-2036
Asia-Pacific Frozen Food Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Frozen Food Market Outlook
Plant-based protein formulations are broadening the ingredient base for frozen meat alternatives across Asia-Pacific. McCain Foods Limited leverages its potato-processing scale to anchor frozen vegetable supply contracts with quick-service chains. Nichirei Corporation sustains dominance in Japan's frozen seafood segment through integrated cold-chain logistics. CJ CheilJedang Corporation specializes in Korean-style frozen ready-to-eat meals, competing on fermented flavor profiles that travel well through retail freezers.
Asia-Pacific frozen food encompasses raw, partially prepared, or fully cooked products preserved at temperatures below minus eighteen degrees Celsius to arrest microbial activity and maintain nutritional integrity; blast freezing and individual quick freezing constitute the dominant industrial methods for texture retention. Frozen seafood commands premium shelf space in Japanese and South Korean retail channels due to perishability concerns and consumer willingness to pay for sashimi-grade preservation. Ready-to-eat meals represent the fastest-growing application segment, driven by dual-income households in Chinese tier-one cities seeking convenience without restaurant premiums. Bulk distributors still occupy the largest margin pool in food service procurement, though online retail is fragmenting last-mile frozen delivery economics.
China's SAMR enforces GB standards for frozen food labeling and cold-chain traceability, while Japan's METI coordinates JIS refrigeration benchmarks that shape equipment investment across processing facilities. India's FSSAI has tightened frozen dairy import protocols, forcing reformulation of ice cream and dessert lines for local manufacturing compliance. South Korea's MFDS audits frozen seafood radiation testing protocols in response to regional sourcing concerns. Stakeholders must monitor divergent national freezing standards as they decide whether to centralize production in low-cost hubs or replicate facilities inside each major market to satisfy localized certification requirements.
Market Dynamics
China's SAMR enforcement of GB standards for cold-chain traceability is forcing cross-border suppliers to replicate certification infrastructure inside the country rather than centralize production in low-cost hubs.
Growth Catalysts
- Quick-service restaurant standardization:Southeast Asian QSR chains are scaling frozen ingredient procurement to reduce kitchen labor and ensure consistent quality across outlets.
- India's FSSAI dairy protocols:Tightened frozen dairy import regulations are accelerating local manufacturing investments by international dessert brands.
- Individual quick freezing adoption:IQF technology is expanding texture retention capabilities for premium frozen seafood destined for Japanese and South Korean retail channels.
Market Restraints
- Cold-chain infrastructure gaps:Last-mile frozen delivery economics in India's tier-two cities remain prohibitive due to unreliable refrigeration networks and high diesel costs for transport.
- Radiation testing compliance:South Korea's MFDS seafood audit protocols create sourcing friction for Japanese and Russian suppliers of sashimi-grade products.
- Fresh-market substitution:Wet markets in Vietnam and Indonesia retain price advantages for protein categories where frozen alternatives carry 15-30% premiums.
Strategic Opportunities
- Vietnam's underpenetrated retail freezer base:Modern trade expansion in Ho Chi Minh City and Hanoi creates first-mover positioning for branded frozen ready-to-eat meals.
- Plant-based protein convergence:Fermentation-derived meat alternatives are opening new formulation possibilities for Korean-style frozen mandu and Japanese gyoza lines.
- Online retail fragmentation:Dark-store networks in Chinese tier-one cities are enabling 30-minute frozen delivery windows that bypass traditional distributor margins.
Industry Challenges
- Blast freezing capex intensity:Tunnel freezer installations require 18-24 month commissioning timelines and specialized ammonia refrigeration engineering talent scarce across Southeast Asia.
- Dual certification complexity:Suppliers serving both China and Japan must maintain parallel GB and JIS compliance documentation, doubling quality assurance headcount requirements.
- Cold-chain talent scarcity:Temperature-controlled logistics management expertise concentrates in Singapore and Shanghai, leaving regional expansion teams dependent on expatriate hiring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Frozen Food Market |
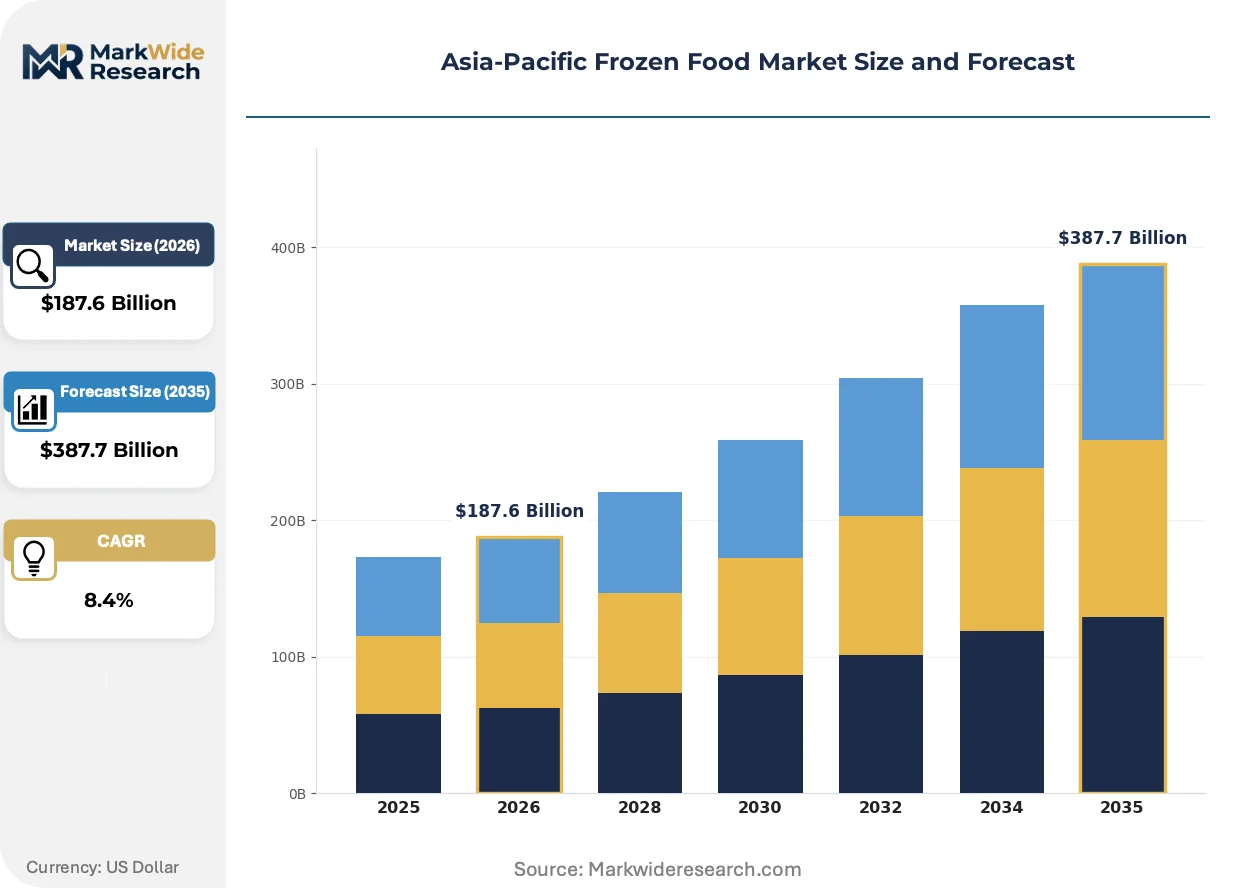
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $387.7 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Vegetables, Frozen Meat, Frozen Dairy, Frozen Seafood Application: Home Cooking, Food Service, Ready-to-Eat Meals, Bakery Products End User: Households, Restaurants, Catering Services, Retail Chains Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Bulk Distributors |
| Companies Covered | McCain Foods Limited, Nichirei Corporation, CJ CheilJedang Corporation, Sanquan Food Co. Ltd., COFCO Corporation, Ajinomoto Co., Inc., Charoen Pokphand Group, Maruha Nichiro Group, Nestlé S.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Frozen Food Market Strategic Shifts
Processing technology, regulatory digitization, and channel restructuring are compressing traditional frozen food value chains across the Asia-Pacific region.
Artificial intelligence-driven demand forecasting is converging with automated warehouse robotics in Chinese cold-storage facilities. JD Logistics and SF Cold Chain are deploying predictive algorithms to optimize frozen inventory turns across their hub networks. This convergence is compressing working capital requirements for frozen seafood importers serving Shanghai and Beijing.
Japan's METI is mandating blockchain-based temperature logging for frozen food exports under revised JIS cold-chain standards. Processing facilities must install IoT sensors generating immutable records from blast freezing through retail delivery. Japanese frozen bento manufacturers are responding by consolidating supplier audits to reduce documentation duplication.
Dual-income households in Chinese tier-one cities are abandoning daily wet-market visits for weekly frozen meal stockpiling. Hema Fresh and Missfresh are capturing this behavioral pivot with subscription-based freezer replenishment models. This shift is most visible in Shenzhen and Hangzhou, where apartment sizes limit refrigerator capacity and favor compact frozen SKUs.
Asia-Pacific Frozen Food Market Segmentation
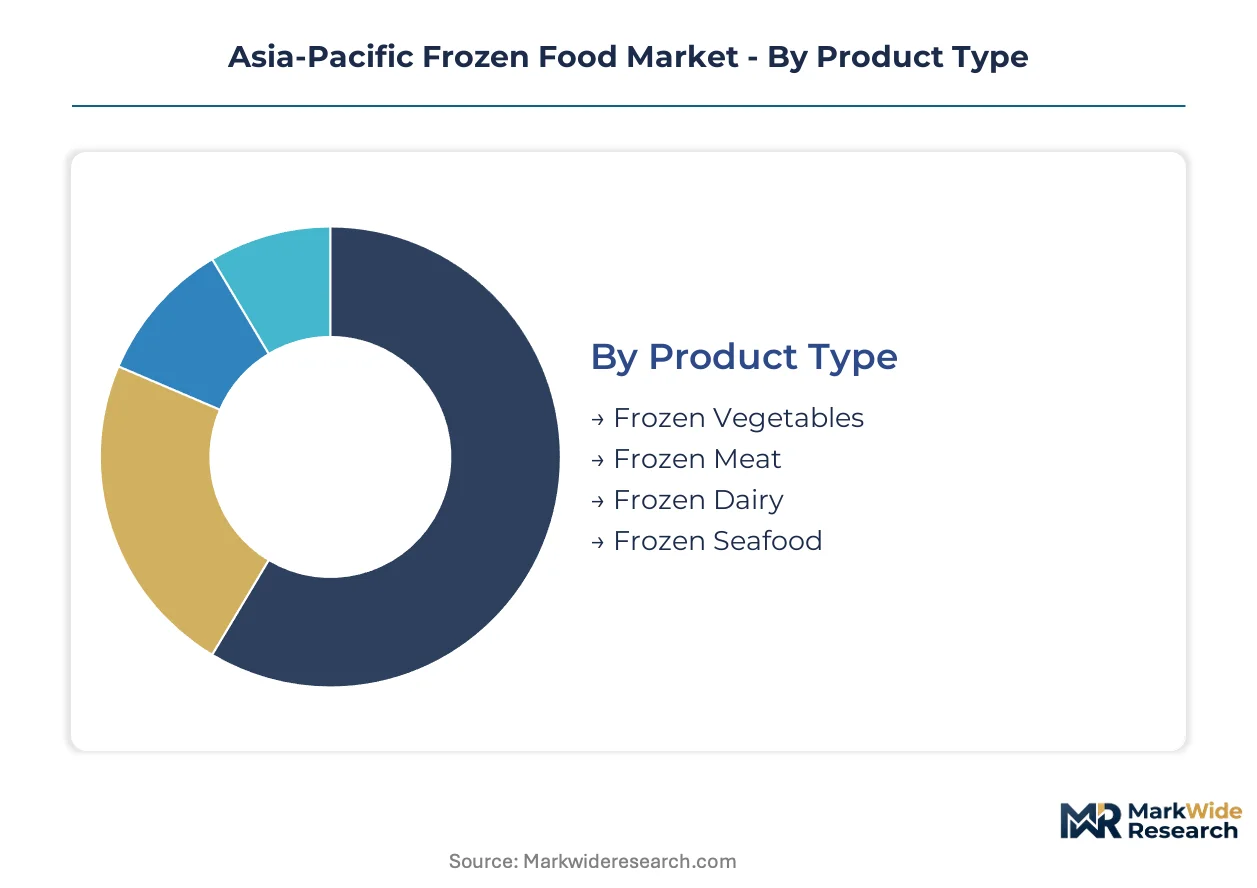
Frozen food segmentation across Asia-Pacific reflects divergent cold-chain maturity and purchasing power gradients. Premium preservation technologies concentrate in Japan and South Korea, while bulk procurement dominates Southeast Asian food service channels.
Product Type:
Volume leadership sits with commodity categories, while premium margins attach to perishability-sensitive segments requiring specialized freezing protocols.
- Frozen Seafood:Sashimi-grade tuna and salmon demand IQF preservation at minus forty degrees Celsius to maintain cellular structure for raw consumption. Japanese retail channels absorb premium pricing for radiation-tested Pacific catch, with South Korean consumers following similar quality benchmarks.
- Frozen Vegetables:Blast-frozen broccoli, peas, and corn serve quick-service restaurant chains across Southeast Asia seeking standardized cooking times and reduced prep labor. McCain Foods anchors supply contracts through dedicated potato-processing infrastructure.
- Frozen Meat:Beef and pork cuts preserved for prolonged retail shelf life, concentrated in Chinese tier-one cities where apartment refrigeration limits fresh protein purchasing frequency.
- Frozen Dairy:Ice cream and dessert formulations reformulated under India's FSSAI import protocols, accelerating local manufacturing investments by international brands.
Today's leader: Frozen Vegetables. Tomorrow's challenger: Frozen Seafood.
Application:
Convenience premiums separate at-home preparation from commercial food service procurement, with ready-to-eat formats capturing dual-income household expenditure shifts.
- Ready-to-Eat Meals:Korean-style frozen mandu and Japanese bento boxes target time-constrained professionals in Chinese tier-one cities. CJ CheilJedang competes on fermented flavor profiles that withstand freezer storage without degradation.
- Food Service:Frozen ingredient procurement by Southeast Asian QSR chains standardizes quality across outlet networks while compressing kitchen labor requirements. Bulk distributors capture margin pools through volume contracting.
- Home Cooking:Raw and partially prepared products for consumer-initiated meal completion, prevalent in Indian metropolitan corridors transitioning from wet-market purchasing habits.
- Bakery Products:Par-baked frozen dough and pastry items supplied to convenience store chains and in-store bakery operations.
Food Service commands current volume. Ready-to-Eat Meals show steepest expansion trajectory.
End User:
Procurement scale and temperature-control requirements differentiate household purchasing from institutional buyers with captive cold-chain infrastructure.
- Restaurants:Quick-service and casual dining chains across Vietnam and Indonesia source frozen proteins and vegetables to bypass fresh-market price volatility and supply inconsistency.
- Households:Urban Indian families in Mumbai and Delhi are shifting weekly purchasing toward branded frozen alternatives as modern trade freezer penetration expands.
- Catering Services:Event and institutional food providers relying on frozen prepared foods for menu consistency and inventory predictability.
- Retail Chains:Supermarket and hypermarket operators curating private-label frozen assortments for middle-income consumer segments.
Restaurants dominate procurement tonnage. Households are gaining share fastest.
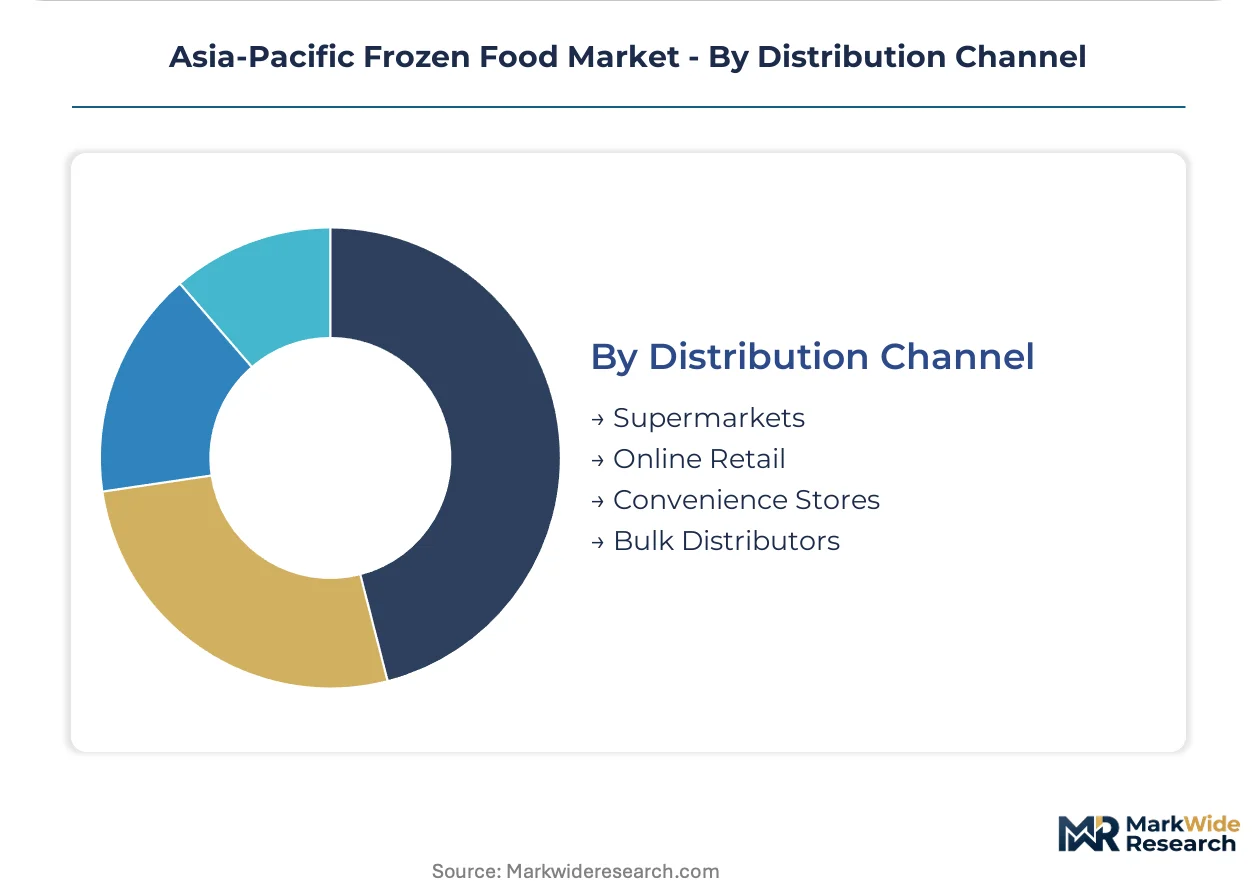
Distribution Channel:
Traditional bulk distribution retains food service volume while online retail fragments last-mile economics through dark-store networks.
- Online Retail:JD Logistics and SF Cold Chain deploy predictive algorithms optimizing frozen inventory turns across Chinese hub networks. Hema Fresh and Missfresh capture subscription-based freezer replenishment demand in Shenzhen and Hangzhou.
- Bulk Distributors:Regional logistics specialists serving Southeast Asian QSR chains with consolidated frozen procurement and temperature-controlled delivery scheduling.
- Supermarkets:Modern trade freezer cabinets in Ho Chi Minh City and Hanoi creating first-mover positioning for branded frozen ready-to-eat meals.
- Convenience Stores:Frozen snack and single-serve meal formats targeting impulse purchasing and immediate consumption occasions.
Bulk Distributors hold current margin concentration. Online Retail is reshaping competitive positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors cold-chain infrastructure investment across the Asia-Pacific frozen food corridor. The Yangtze River Delta cluster processes premium seafood exports while serving as the gateway for imported frozen proteins destined for Chinese tier-one cities.
China
Urban households in Shenzhen and Hangzhou are abandoning wet-market purchasing for subscription-based frozen meal replenishment. SAMR enforces GB standards for cold-chain traceability that force cross-border suppliers to replicate certification infrastructure domestically. Yangtze River Delta processing facilities concentrate IQF technology deployment for sashimi-grade seafood preservation.
Japan
Dual-income professionals in Tokyo and Osaka drive demand for frozen bento and premium seafood retail formats. METI mandates blockchain-based temperature logging for exports under revised JIS cold-chain standards. Kansai industrial corridors host integrated cold-chain logistics networks sustaining Nichirei's frozen seafood distribution dominance.
India
Mumbai and Delhi metropolitan households are shifting weekly protein purchasing toward branded frozen alternatives as modern trade expands. FSSAI tightened frozen dairy import protocols, accelerating local manufacturing investments by international dessert brands. Maharashtra and Gujarat processing zones concentrate blast-freezing capacity for domestic vegetable supply.
South Korea
Seoul Capital Area consumers absorb premium pricing for radiation-tested Pacific seafood following Fukushima sourcing concerns. MFDS audits frozen seafood radiation testing protocols, creating compliance friction for Japanese and Russian suppliers. Busan-Ulsan corridors anchor cold-chain logistics for imported frozen protein redistribution.
Vietnam
Ho Chi Minh City and Hanoi modern trade expansion creates first-mover positioning for branded frozen ready-to-eat meals. Wet markets retain price advantages for protein categories where frozen alternatives carry significant premiums. Southern industrial zones concentrate tunnel freezer installations serving emerging QSR procurement demand.
Asia-Pacific Frozen Food Market Competitive Environment
Global majors compete with regional champions across cold-chain infrastructure and flavor localization capabilities. The vendor base stratifies into three tiers: multinational conglomerates with integrated processing networks, national champions dominating domestic distribution, and specialized mid-cap players serving niche preservation segments. Strategic archetypes include scale-driven commodity processors, fermentation-technology specialists, and captive cold-chain operators. Capacity expansion and backward integration into raw material sourcing constitute the dominant competitive moves across the region.
Within the fermentation-technology specialist tier, CJ CheilJedang Corporation exemplifies Korean-style frozen ready-to-eat meal positioning through flavor profiles engineered for freezer stability. Among integrated cold-chain operators, Nichirei Corporation occupies a position representing Japanese seafood preservation and logistics consolidation. At the multinational scale-driven end, McCain Foods Limited anchors vegetable processing contracts through dedicated potato supply infrastructure. These three archetypes—specialist, integrated operator, and scale processor—capture distinct margin pools across the Asia-Pacific frozen food value chain.
| Leading Market Players |
|---|
| McCain Foods Limited |
| Nichirei Corporation |
| CJ CheilJedang Corporation |
| Sanquan Food Co. Ltd. |
| COFCO Corporation |
| Ajinomoto Co., Inc. |
| Charoen Pokphand Group |
| Maruha Nichiro Group |
| Nestlé S.A. |
| Others |
Value Chain & Pricing Dynamics
IQF-grade seafood certification creates a three-tier pricing structure across premium, standard, and economy levels that segments procurement flows through dedicated cold-chain corridors in Japan and South Korea versus bulk vegetable channels serving Southeast Asian QSR networks. This bifurcation concentrates margin capture among blast-freezing operators with ammonia refrigeration engineering capabilities while compressing economics for commodity distributors lacking temperature-control infrastructure.
Pricing Analysis
Input-cost pass-through from diesel refrigeration transport and ammonia-based tunnel freezer energy consumption is intensifying margin pressure across India's tier-two city distribution networks. Price differentiation hinges on JIS cold-chain certification grade and volume-scale contracting with quick-service restaurant chains. Pricing softness reflects wet-market substitution in Vietnam and Indonesia where fresh protein alternatives undercut frozen premiums by significant margins. Food service buyers exhibit highest price sensitivity due to standardized procurement budgets, while Japanese retail channels absorb premium IQF pricing for sashimi-grade preservation.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised frozen inventory remain underdeveloped across Asia-Pacific, forcing write-off rates that inflate effective procurement costs for distributors lacking dark-store networks. Supply concentrates in China's Yangtze River Delta processing zones, Thailand's integrated seafood corridors, and India's Maharashtra-Gujarat vegetable belt. Raw material dependencies include Pacific tuna catch, Australian wheat for frozen dough formulations, and palm oil derivatives for par-fried potato coatings. Single-source vulnerability runs through ammonia refrigeration engineering talent pools concentrated in Singapore and Shanghai. Distribution runs through bulk logistics specialists serving Southeast Asian QSR chains alongside emerging dark-store networks in Chinese tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific frozen food operates as a regulatory compounder where China's SAMR enforcement of GB cold-chain traceability standards is accelerating domestic certification infrastructure investments and fragmenting cross-border supply economics.
For Market Incumbents: Acquire captive ammonia refrigeration engineering capabilities to reduce commissioning timeline risk for tunnel freezer installations. Consolidate supplier audit documentation to reduce duplication burden from parallel GB and JIS compliance requirements. Nichirei's integrated logistics model demonstrates how cold-chain control defends margin position against commodity distributors lacking temperature-control infrastructure. For New Entrants and Emerging Players: Launch via dark-store networks in Ho Chi Minh City and Hanoi where modern trade freezer penetration remains underdeveloped relative to Chinese tier-one benchmarks. Target Vietnamese ready-to-eat meal segments where wet-market substitution pressure is weakest and branded frozen alternatives command first-mover positioning. Partner with local QSR chains seeking standardized ingredient procurement to bypass fresh-market volatility. For Investors and Strategic Acquirers: Consolidation pressure builds where dual certification complexity doubles quality assurance headcount requirements for suppliers serving both China and Japan. Long-term viability favors fermentation-technology specialists with freezer-stable flavor formulation capabilities and integrated cold-chain operators with captive logistics networks. Monitor MFDS radiation testing protocol adjustments as inflection signal for Japanese and Russian seafood supplier restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Investment | Tunnel freezer commissioning in Vietnam's southern industrial zones captures emerging QSR procurement demand. |
| Dual Certification Consolidation | Parallel GB and JIS documentation streamlines quality assurance for cross-border suppliers. |
| Dark-Store Network Expansion | JD Logistics predictive algorithms optimize frozen inventory turns across Chinese hub networks. |
| Fermentation Technology Acquisition | Freezer-stable flavor profiles differentiate Korean-style mandu in Chinese tier-one retail channels. |
| Blockchain Temperature Logging | METI-mandated IoT sensor deployment creates compliance barrier for non-integrated operators. |
Study Parameters
Direct dialogue with cold-chain logistics directors, frozen food procurement managers at quick-service restaurant chains, ammonia refrigeration engineering specialists, and regulatory compliance officers at SAMR and METI shaped qualitative grounding for this analysis. Secondary validation drew from customs trade databases, GB and JIS standards filings, SEC disclosures by listed food processing conglomerates, and cold-chain equipment import records. Bottom-up volume modeling across product type, application, and distribution channel segments triangulated against top-down macroeconomic consumption indicators.
Segment-level projections across frozen seafood, vegetables, meat, and dairy categories combined with application splits between ready-to-eat meals, food service, and home cooking channels generated volume and value trajectories across the analysis window. CAGRs were derived from regression analysis against urban household income growth, modern trade freezer penetration rates, and QSR outlet expansion metrics. IQF technology adoption curves and dark-store network density served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt FSSAI dairy protocol adjustments or MFDS radiation testing escalation. Practitioners should monitor SAMR cold-chain digitization timelines and wet-market price volatility in Vietnam and Indonesia for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
Freeze Dried Fruit Extract Market
Processed and Frozen Foods
Freeze Dried Melt Market
Processed and Frozen Foods
Cold Cuts Market
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
Europe Frozen Desserts Market
Processed and Frozen Foods
Frozen Pizza Market
Processed and Frozen Foods
Refrigerated Liquid Eggs Market
Processed and Frozen Foods
Frozen Baby Food Market
Processed and Frozen Foods
Middle East and Africa Frozen Food Market
Processed and Frozen Foods
Middle East and Africa Ice Cream Market
Processed and Frozen Foods
Frozen Novelty Market
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
Global Chilled and Deli Foods Market
Processed and Frozen Foods
Global Frozen Breakfast Entrees/Sandwiches Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market