
 Conductive Adhesive Market | 2026-2036
Conductive Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Conductive Adhesive Market Analysis
Asset-light contract manufacturing and third-party toll blending is rewriting capital requirements for conductive adhesive entrants. Henkel AG & Co. KGaA leverages its European formulation network to sustain high-margin silver paste supply to automotive OEMs. 3M Company anchors North American demand through fluoropolymer-compatible conductive films for aerospace cable assemblies. Creative Materials Inc. competes via specialized low-temperature cure epoxies for temperature-sensitive substrates.
Conductive adhesives are polymer-based compounds loaded with metallic or carbon fillers that establish electrical continuity between bonded surfaces while eliminating thermal damage from soldering; typical silver formulations achieve bulk resistivity below 0.0001 ohm-cm and cure at temperatures between 80°C and 150°C. Silver adhesives dominate current value generation due to unmatched conductivity in microelectronics die-attach applications. Carbon adhesives represent the fastest-expanding product category as electric vehicle battery pack manufacturers adopt them for lightweight current collection layers. Paste formulations capture the largest volume share, though film formats command premium positioning in automated pick-and-place assembly lines.
EPA oversight of volatile organic compound emissions constrains solvent-based adhesive production in the United States, while REACH registration requirements in Europe elevate compliance costs for imported silver flake suppliers. China's GB standards for electronic component reliability and RoHS-aligned substance restrictions in multiple jurisdictions collectively filter market access toward halogen-free, low-outgassing formulations. Stakeholders must monitor evolving solder replacement mandates across automotive and telecommunications certification bodies to anticipate formulation specification shifts.
Market Dynamics
Silver flake supply concentration in East Asian refining corridors is compressing formulation margins while RoHS-driven solder replacement mandates across automotive and telecommunications certification bodies accelerate specification shifts toward conductive adhesive alternatives.
Growth Catalysts
- RoHS restrictions:European lead-based solder bans redirect electronics assembly lines toward adhesive bonding solutions in automotive control modules and telecommunications infrastructure.
- Semiconductor packaging corridors:China's die-attach operations expand procurement of silver-filled formulations for flip-chip and wafer-level packaging applications.
- Electric vehicle battery manufacturing:Carbon adhesive adoption for lightweight current collection layers in cell-to-pack architectures accelerates demand from automotive OEMs.
Market Restraints
- Silver price volatility:Precious metal cost fluctuations in London and Shanghai bullion markets compress margins for high-fill formulations above 70% silver loading.
- REACH registration burdens:ECHA compliance requirements for imported silver flake suppliers elevate fixed costs for European market entry.
- Thermal conductivity ceiling:Polymer matrix limitations prevent conductive adhesives from matching solder joint thermal dissipation in high-power semiconductor modules.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and display fabrication create virgin demand for die-attach and flex-circuit bonding materials.
- Film format automation:Pick-and-place assembly lines in South Korean display panel clusters favor precision-cut conductive film over dispensed paste for micro-LED transfer.
- Halogen-free mandates:GB standards alignment with RoHS substance restrictions filters market access toward low-outgassing formulations in Chinese consumer electronics.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in rheology control and filler dispersion for sub-50-micron bond lines remains concentrated among veteran technologists at established suppliers.
- Reliability certification timelines:Automotive AEC-Q100 and telecommunications Telcordia qualification protocols extend product validation cycles to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conductive Adhesive Market |
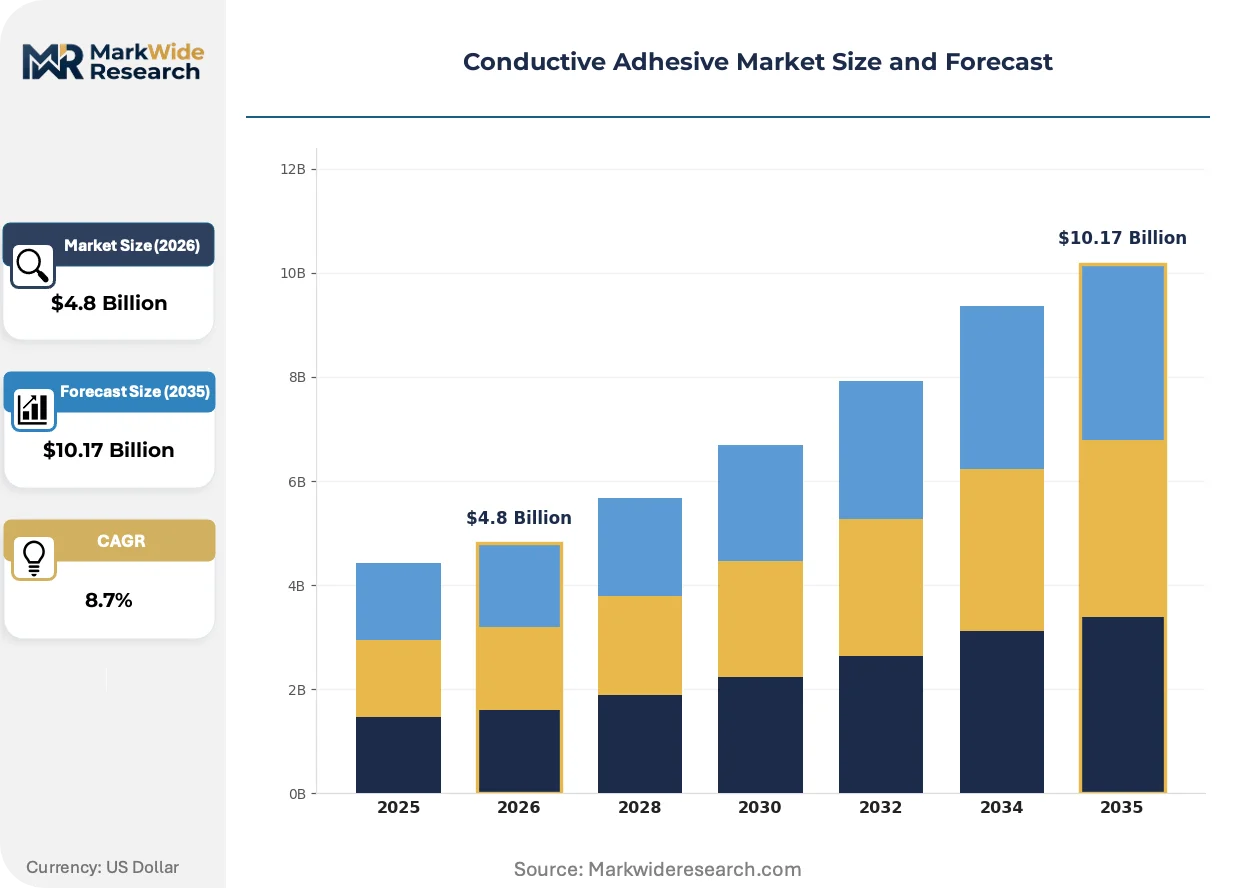
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
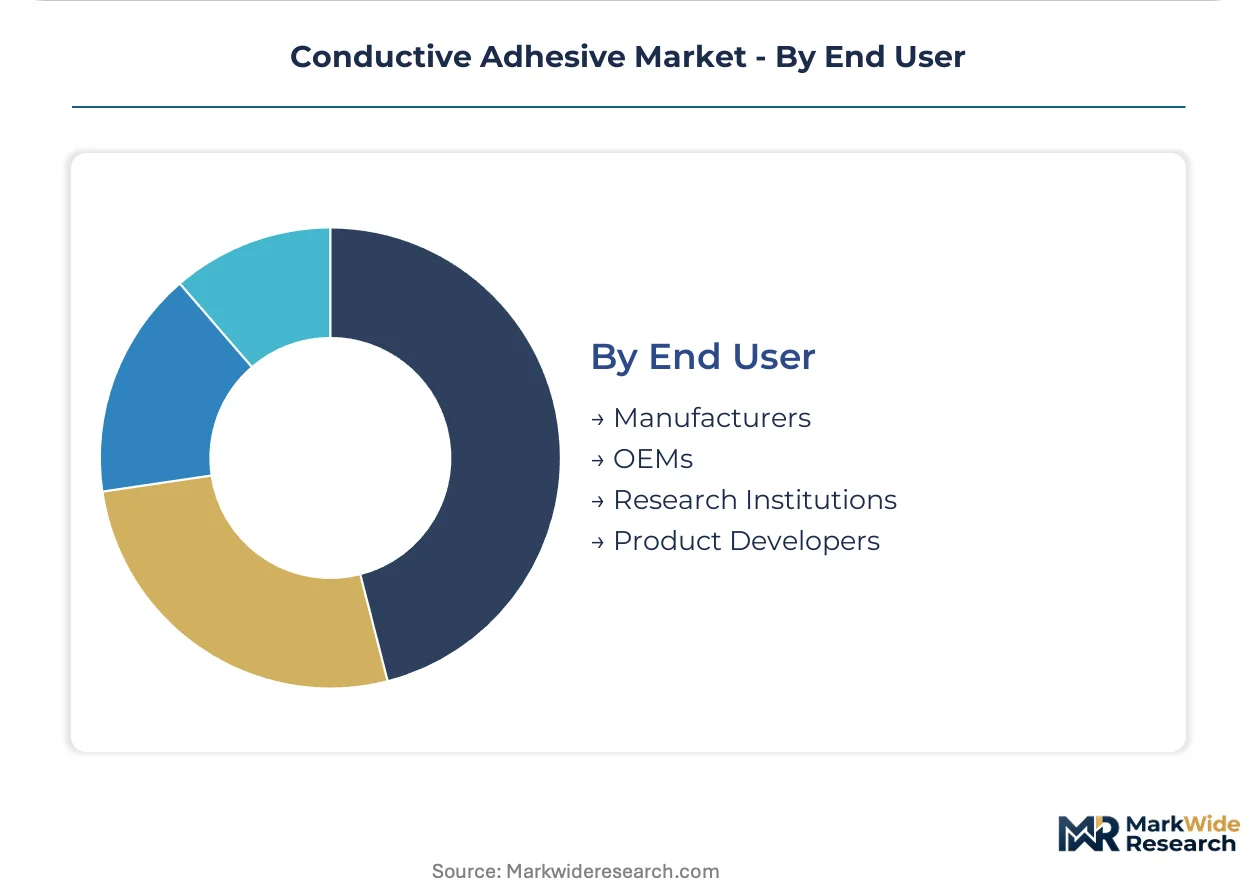
| Segmentation | Product Type: Silver Adhesives, Copper Adhesives, Carbon Adhesives, Epoxy Adhesives Application: Electronics, Automotive, Telecommunications, Aerospace Form: Paste, Film, Liquid, Gel End User: Manufacturers, OEMs, Research Institutions, Product Developers |
| Companies Covered | Aremco Products, Inc., Creative Materials Inc., 3M Company, Permabond LLC, Delo Industrial Adhesives, Henkel AG & Co. KGaA, Dow Corning Corporation, Epoxy Technology Inc., H.B. Fuller Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conductive Adhesive Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to redefine performance benchmarks and supply chain qualification protocols across conductive adhesive applications.
Nickel-coated graphite hybrid fillers are migrating from cost-driven consumer electronics into automotive sensor packaging where electromagnetic interference shielding requirements intersect with corrosion resistance mandates. Tier-2 automotive suppliers in Germany and Japan accelerate validation of these formulations for radar module assembly. The shift is compressing addressable volume for pure silver adhesives in mid-tier conductivity applications.
EPA volatile organic compound emission thresholds constrain solvent-based adhesive production across United States manufacturing facilities, forcing waterborne and hot-melt formulation development. Electronics contract manufacturers in Mexico and Southeast Asia face equivalent pressure through customer-imposed sustainability scorecards. The regulatory friction elevates capital requirements for new entrants while advantaging incumbents with established aqueous dispersion capabilities.
Consolidated procurement through electronic manufacturing services providers concentrates volume among three to five global contract manufacturers. Direct supplier relationships with original equipment designers are fragmenting as Foxconn, Jabil, and Pegatron centralize material specification authority. The concentration is most visible in South Korean and Taiwanese display panel supply chains where adhesive selection now flows through EMS technical committees rather than brand engineering teams.
Conductive Adhesive Market Segmentation
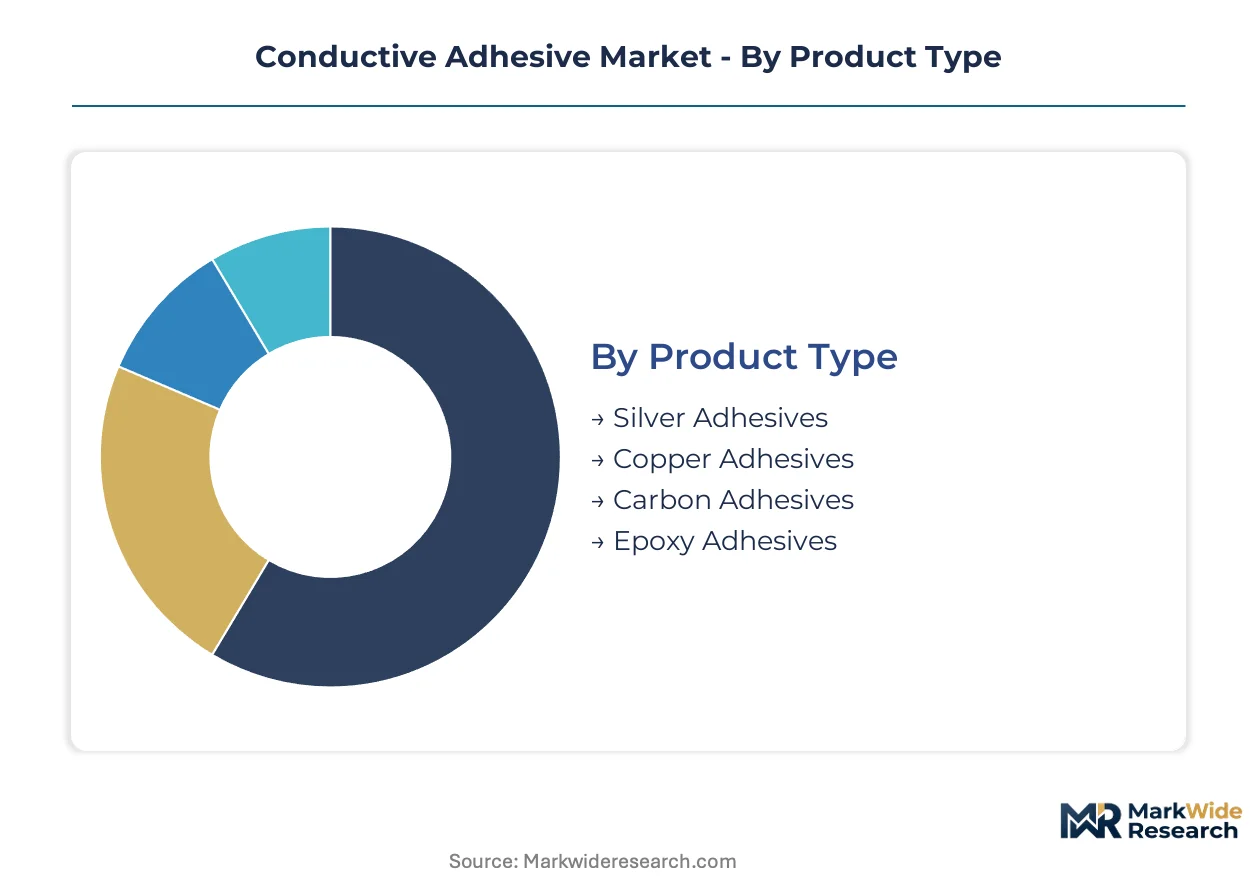
Conductive adhesive specification varies sharply across electrical performance requirements, thermal tolerance thresholds, and assembly automation compatibility. Procurement decisions hinge on filler loading percentages, cure kinetics, and substrate sensitivity rather than price alone.
Product Type:
Formulation chemistry spans precious metal conductivity through polymer-engineered alternatives, each occupying distinct positions on the cost-performance spectrum.
- Silver Adhesives:These formulations incorporate flake or spherical silver particles at loadings exceeding 70% by weight, achieving bulk resistivity below 0.0001 ohm-cm. Die-attach operations in China's semiconductor packaging corridors specify these for flip-chip interconnects where solder replacement is mandatory under RoHS restrictions.
- Carbon Adhesives:Graphite and carbon black composites deliver moderate conductivity at substantially lower material cost. Electric vehicle battery pack manufacturers in South Korea and Germany adopt these for lightweight current collection layers in cell-to-pack architectures, displacing heavier metal busbar solutions.
- Copper Adhesives:Oxidation-resistant coatings enable copper filler use in cost-sensitive consumer electronics where silver economics prove prohibitive.
- Epoxy Adhesives:These thermosetting systems provide structural bonding with modest conductivity for electromagnetic interference shielding applications.
The dominant share belongs to Silver Adhesives, while Carbon Adhesives is closing the gap fastest.
Application:
End-use environments dictate cure temperature limits, outgassing specifications, and reliability qualification protocols.
- Electronics:Printed circuit board assembly, display panel bonding, and semiconductor packaging drive volume demand. Micro-LED transfer operations in South Korean manufacturing clusters specify sub-50-micron bond line control.
- Automotive:Power module attachment, sensor packaging, and battery interconnects require AEC-Q100 thermal cycling validation. Radar module assembly in Germany accelerates adoption of nickel-coated graphite hybrids for electromagnetic interference shielding.
- Telecommunications:Base station infrastructure and fiber optic assemblies specify Telcordia-qualified formulations for decades-long service life.
- Aerospace:Fluoropolymer-compatible conductive films serve cable assembly applications where outgassing constraints under ESA and NASA specifications apply.
Electronics commands the largest procurement volumes, though Automotive is expanding most quickly as electrification multiplies adhesive attachment points per vehicle.
Form:
Physical configuration determines dispensing equipment requirements, automation compatibility, and material utilization efficiency.
- Paste:Screen-printable and syringe-dispensed formulations dominate high-volume electronics assembly. Stencil printing in Chinese contract manufacturing facilities achieves throughput rates unmatched by alternative formats.
- Film:Precision-cut sheets enable pick-and-place transfer in micro-LED and advanced packaging applications. South Korean display panel clusters favor this format for thickness uniformity and elimination of solvent outgassing.
- Liquid:Low-viscosity systems penetrate porous substrates and complex geometries in automotive sensor housings.
- Gel:Thixotropic formulations maintain position on vertical surfaces during cure cycles for telecommunications enclosure sealing.
Paste formulations capture the broadest installation base, while Film is gaining share fastest in premium automated assembly lines.
End User:
Technical specification authority concentrates differently across direct manufacturers, delegated procurement channels, and pre-commercial development entities.
- Manufacturers:Electronics manufacturing services providers including Foxconn, Jabil, and Pegatron centralize material specification authority. These entities consolidate volume across multiple OEM brands, compressing supplier counts and standardizing formulation selections.
- OEMs:Automotive and aerospace original equipment designers retain direct adhesive qualification for safety-critical applications where liability exposure demands in-house validation.
- Research Institutions:University and national laboratory programs advance novel filler geometries and bio-based polymer matrices with limited near-term procurement scale.
- Product Developers:Early-stage hardware startups specify conductive adhesives for rapid prototyping where soldering infrastructure investment is deferred.
Manufacturers exercise the greatest procurement leverage, while OEMs are extending specification control deepest into supply chains as reliability requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronics manufacturing services providers concentrate procurement authority across three dominant geographies. Contract manufacturers in China, South Korea, and Germany centralize material specifications for global OEM brands. Regional regulatory divergence shapes formulation compliance requirements.
China
Semiconductor packaging corridors in Jiangsu and Shanghai provinces drive silver-filled adhesive consumption for flip-chip die-attach operations. GB standards for electronic component reliability mandate halogen-free, low-outgassing formulations across consumer electronics supply chains. Shenzhen and Dongguan contract manufacturing clusters standardize adhesive selections through centralized technical committees at Foxconn and Pegatron.
South Korea
Display panel manufacturers in Gyeonggi Province specify precision-cut conductive films for micro-LED transfer automation. The Ministry of Environment enforces RoHS-aligned substance restrictions that redirect assembly lines from lead-based solders. Samsung and LG Display clusters in Suwon and Paju favor film formats for thickness uniformity in advanced packaging applications.
Germany
Automotive sensor packaging operations in Bavaria and Baden-Württemberg validate nickel-coated graphite hybrid fillers for radar module assembly. ECHA REACH registration requirements elevate compliance costs for imported silver flake suppliers. Continental and Bosch engineering centers in Ingolstadt and Stuttgart retain direct adhesive qualification authority for AEC-Q100 safety-critical applications.
United States
Aerospace cable assembly manufacturers specify fluoropolymer-compatible conductive films for NASA and ESA outgassing-constrained missions. EPA volatile organic compound emission thresholds constrain solvent-based adhesive production across domestic facilities. 3M anchors North American supply from Minnesota formulation facilities serving defense and telecommunications infrastructure.
India
PLI scheme incentives for semiconductor and display fabrication create virgin demand for die-attach materials in Gujarat and Karnataka. BIS certification requirements filter market access toward standardized reliability grades. Foxconn and Dixon Electronics manufacturing clusters in Sri City and Noida centralize procurement for emerging smartphone and television assembly lines.
Conductive Adhesive Market Vendor Landscape
Channel-controlling players compete with product-specialist players across formulation tiers. Electronics manufacturing services consolidation concentrates volume among three to five global contract manufacturers, compressing supplier counts and standardizing selections. Three strategic archetypes dominate: diversified chemical conglomerates with European formulation networks, North American materials science specialists with fluoropolymer expertise, and regional low-temperature cure epoxy specialists. Competitive moves center on backward integration into silver flake supply and geographic expansion through toll blending partnerships.
Among diversified adhesive conglomerates, Henkel AG & Co. KGaA and H.B. Fuller Company exemplify the European and North American multinational archetype respectively. Creative Materials Inc. and Epoxy Technology Inc. occupy specialist positions within the low-temperature formulation tier. 3M Company anchors the materials science vector with fluoropolymer-compatible film capabilities. These named entities represent distinct competitive positions without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| Aremco Products, Inc. |
| Creative Materials Inc. |
| 3M Company |
| Permabond LLC |
| Delo Industrial Adhesives |
| Henkel AG & Co. KGaA |
| Dow Corning Corporation |
| Epoxy Technology Inc. |
| H.B. Fuller Company |
| Others |
Supply Flow & Price Mechanics
Silver price volatility in London and Shanghai bullion markets determines both tier spreads between high-fill and economy formulations and the geographic shape of supply chain sourcing decisions for conductive adhesive manufacturers.
Pricing Analysis
Cost-plus contracts with London Bullion Market Association silver indexation dominate procurement between East Asian refiners and European formulators. Pricing stratifies across AEC-Q100 certified automotive grades, standard industrial tiers, and economy consumer electronics formulations. Cost compression in high-fill silver adhesives above 70% loading is intensifying because precious metal spot fluctuations pass directly through contract structures. Electronics manufacturing services providers exhibit the highest price sensitivity due to consolidated volume leverage, while aerospace OEMs tolerate premium positioning for fluoropolymer-compatible films.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for conductive adhesive producers. Silver flake refining concentrates in China, Japan, and South Korea, while polymer resin supply draws from Germany and the United States. Raw material dependencies include silver bullion, specialty epoxy resins, and nickel-coated graphite hybrid fillers. Single-source vulnerability exists for high-purity silver flake from Jiangsu province refiners. Distribution runs through electronic manufacturing services technical committees rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemist expertise in rheology control and sub-50-micron bond line dispersion represents the critical capability gap constraining competitive entry and expansion in conductive adhesive markets.
For Market Incumbents: Pre-empt nickel-coated graphite hybrid displacement of pure silver formulations in automotive radar modules by accelerating AEC-Q100 validation timelines and securing captive silver flake supply through backward integration into East Asian refining partnerships. Channel control through Foxconn and Pegatron technical committees remains the priority defensive lever against specialty epoxy entrants. For New Entrants and Emerging Players: India's PLI scheme semiconductor packaging corridors in Gujarat and Karnataka represent the most penetrable entry point for die-attach adhesive qualification without entrenched incumbent relationships. Low-temperature cure epoxy specialization for temperature-sensitive substrates offers a differentiated go-to-market angle against high-cure silver paste incumbents. For Investors and Strategic Acquirers: The market sits at a specification-consolidation phase that favors aqueous dispersion capability holders over solvent-dependent legacy players. Long-term viability across the projection horizon hinges on REACH-compliant formulation portfolios and halogen-free certification depth. The signal to watch is EMS provider technical committee standardization decisions that permanently freeze out non-qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver Flake Supply | Henkel's European formulation network secures margin protection against Shanghai bullion volatility. |
| Aqueous Dispersion Capability Buildout | EPA emission thresholds force solvent-to-waterborne transitions across United States manufacturing. |
| AEC-Q100 Certification Acceleration | Automotive radar module assembly in Bavaria demands 18-month validation compression for hybrid fillers. |
| Film Format Precision Manufacturing | Samsung and LG Display clusters in Suwon specify thickness uniformity for micro-LED transfer automation. |
| Toll Blending Partnership Expansion | Asset-light contract manufacturing rewrites capital requirements for regional market entry. |
Methodological Framework
Desk research of SEC 10-K filings, customs trade databases, and ECHA REACH registration records preceded structured interviews with adhesive formulation chemists, EMS procurement directors, and automotive Tier 1 supplier quality engineers. Primary fieldwork across China's semiconductor packaging corridors and South Korea's display panel clusters combined with secondary validation from GB standards documentation and RoHS directive amendments. Bottom-up volume triangulation against top-down value estimates anchored segmentation splits.
Assumptions around silver price band stability and RoHS solder replacement mandate timelines were held fixed while electric vehicle battery pack adoption rates and micro-LED transfer automation penetration were varied across sensitivity scenarios. The analytical framework modeled product type, application environment, physical form, and end-user procurement authority dimensions throughout the forecast period. CAGRs derived from segment-level volume buildups incorporating fill loading percentages and cure temperature band specifications.
Macroeconomic conditions sit as an overlay; deviation in precious metal spot prices or semiconductor capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions around regulatory compliance cost pass-through and EMS provider consolidation continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Fabric Glue Market
Adhesives & Sealants
Global Bonding Varnish Market
Adhesives & Sealants
Acrylic Glue Market
Adhesives & Sealants
UV-Curable Adhesives Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
Solvent Based Laminating Adhesives Market
Adhesives & Sealants
Global Self-Adhesive Vinyl Films Market
Adhesives & Sealants
France Sealants Market
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
Thailand Adhesives Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
Europe Cyanoacrylate Adhesives Market
Adhesives & Sealants
Global Underfill Material Market
Adhesives & Sealants
Joint Sealants Market
Adhesives & Sealants
Industrial Wood Adhesives Market
Adhesives & Sealants
Asia-Pacific Urea-Formaldehyde Glues and Resins Market