
 Metal Glue Market | 2026-2036
Metal Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Glue Market Analytics
Buyer concentration among automotive OEMs is realigning procurement volumes toward qualified adhesive suppliers with certified bonding systems. Henkel AG & Co. KGaA leverages its Loctite platform to dominate structural bonding programs for aluminum-intensive vehicle architectures. 3M Company sustains aerospace-grade adhesive qualification through extensive OEM specification lock-ins. Sika AG anchors European industrial demand with specialized polyurethane formulations for metal-to-composite joints.
Metal glue comprises engineered adhesive systems formulated with epoxy, acrylic, polyurethane, or silicone chemistries designed to bond ferrous and non-ferrous substrates under load-bearing conditions. These formulations typically achieve shear strengths exceeding 20 MPa on etched aluminum surfaces while operating across temperature ranges from minus 40 to 150 degrees Celsius, serving primary functions in structural assembly where welding induces thermal distortion or dissimilar metals prevent fusion. Epoxy systems command the largest volume share due to their established qualification in automotive crash-structure bonding, while acrylic adhesives represent the fastest-expanding category as methyl methacrylate formulations gain traction in marine and wind-energy applications where rapid fixture and gap-filling tolerance prove critical. Polyurethane segments retain margin concentration in customized construction and transportation OEM specifications where flexibility and vibration damping justify premium positioning.
REACH substance restrictions and RoHS hazardous substance limits in Europe, alongside EPA VOC emission standards in the United States, collectively constrain solvent-based formulations while accelerating demand for low-emission structural adhesives. China's GB standards and SAMR product safety frameworks impose additional testing protocols for imported metal bonding systems entering industrial supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation investments and qualification timeline compression.
Market Dynamics
Automotive lightweighting mandates are compressing qualification timelines for structural adhesive systems as OEMs phase out spot-welding in aluminum-intensive architectures. This pressure cascades through formulation chemistry, certification protocols, and supplier qualification workflows.
Growth Catalysts
- Electric Vehicle Platform Expansion:Battery enclosure bonding requirements are pulling methyl methacrylate adhesives into high-volume automotive programs. Henkel and Sika have qualified crash-resistant formulations for aluminum-intensive skateboard architectures.
- REACH Substance Restrictions:ECHA's tightening thresholds on isocyanates and heavy-metal catalysts are accelerating solvent-to-reactive adhesive conversions across European industrial metalworking clusters.
- Wind Turbine Manufacturing Scale-Up:Offshore turbine nacelle assembly is consuming toughened epoxy systems for steel-to-composite load transfer joints in Denmark and China fabrication yards.
Market Restraints
- Petrochemical Feedstock Volatility:Epoxy resin and polyurethane precursor costs swing with propylene and benzene derivative markets, compressing formulation margins unpredictably.
- Specialized Curing Equipment Concentration:Industrial-scale induction and infrared curing system suppliers cluster in Germany and Japan, creating equipment procurement bottlenecks for new adhesive line installations.
- Mechanical Fastener Substitution:Self-piercing rivets and flow-drill screws retain cost advantages in high-strength steel joints, limiting adhesive penetration in budget vehicle segments.
Strategic Opportunities
- India Industrial Infrastructure Build-Out:PLI scheme incentives for domestic manufacturing are opening specification windows for qualified adhesive suppliers in railway and construction equipment sectors.
- Repair and Retrofit Channel Development:Aftermarket structural bonding kits for collision repair and infrastructure maintenance represent untapped volume outside OEM captive supply agreements.
- Digital Cure Monitoring Integration:IoT-enabled adhesive bond-line quality assurance systems are creating service-revenue layers and locking in formulation-specification relationships with tier-one automotive suppliers.
Industry Challenges
- Adhesion Scientist Talent Scarcity:Formulation chemistry expertise in surface science and rheology concentrates among aging specialists in European and Japanese corporate labs, constraining R&D expansion.
- OEM Qualification Timeline Compression:Crash-structure adhesive approvals now require 18-24 month validation cycles against 10-year vehicle platform lifespans, straining supplier cash conversion.
- Multi-Material Joint Complexity:Dissimilar substrate bonding (aluminum-to-carbon fiber, steel-to-magnesium) demands customized surface preparation protocols that fragment production workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Glue Market |
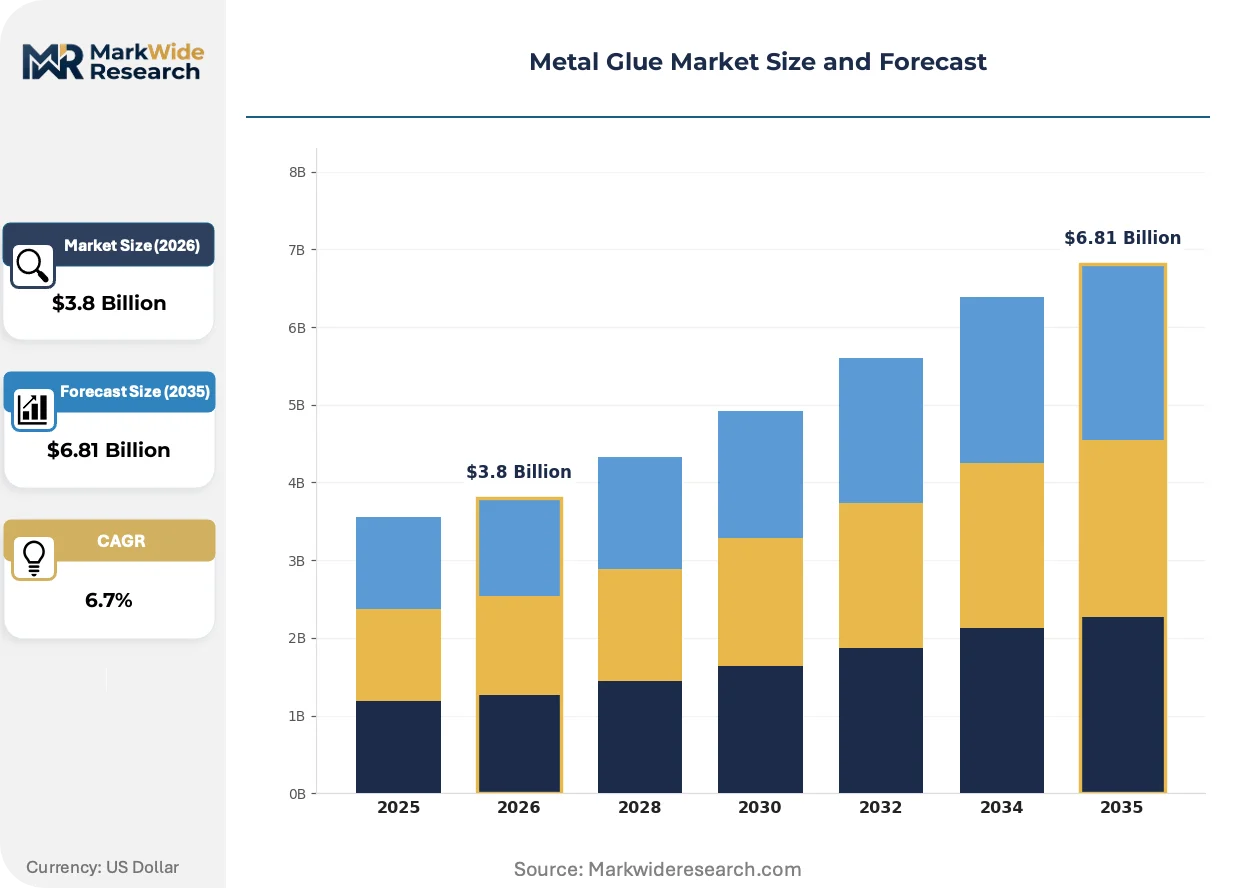
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Acrylic, Polyurethane, Silicone Application: Automotive, Aerospace, Electronics, Construction End User: Manufacturers, DIYers, Contractors, Consumers Packaging Type: Tubes, Jars, Pouches, Cartridges |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, Sika AG, H.B. Fuller Company, Arkema Group, LORD Corporation, BASF SE, Evonik Industries, Permabond LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Glue Market Evolving Landscape
Reactive chemistry advances and digital manufacturing integration are compressing cure cycles while expanding bondable substrate combinations. These developments are redrawing competitive boundaries between formulation specialists and systems integrators.
Two-part structural acrylics with built-in induction-cure accelerators are electrifying assembly line throughput in automotive body-in-white operations. Mercedes-Benz and BMW have adopted these systems for aluminum closure panel bonding, cutting fixture time from 45 minutes to under 90 seconds. This speed differential is electrifying supplier selection criteria toward integrated cure-system providers rather than standalone adhesive vendors.
EPA VOC emission standards under the Clean Air Act are forcing reformulation of solvent-borne primers and cleaners that precede structural adhesive application. Metal fabrication shops in Michigan and Ohio face compliance deadlines that accelerate waterborne and 100-percent-solid system adoption. The construction equipment segment bears the highest switching costs due to field-service compatibility requirements with legacy repair protocols.
Automotive OEMs are consolidating approved supplier lists to single-source structural bonding systems per vehicle platform, displacing multi-vendor qualification strategies. Tier-one integrators like Magna and Gestamp now mandate adhesive-cure equipment packages from qualified system houses. This concentration is most visible in German and Chinese electric vehicle programs where platform scale justifies captive process engineering investment.
Metal Glue Market Segmentation
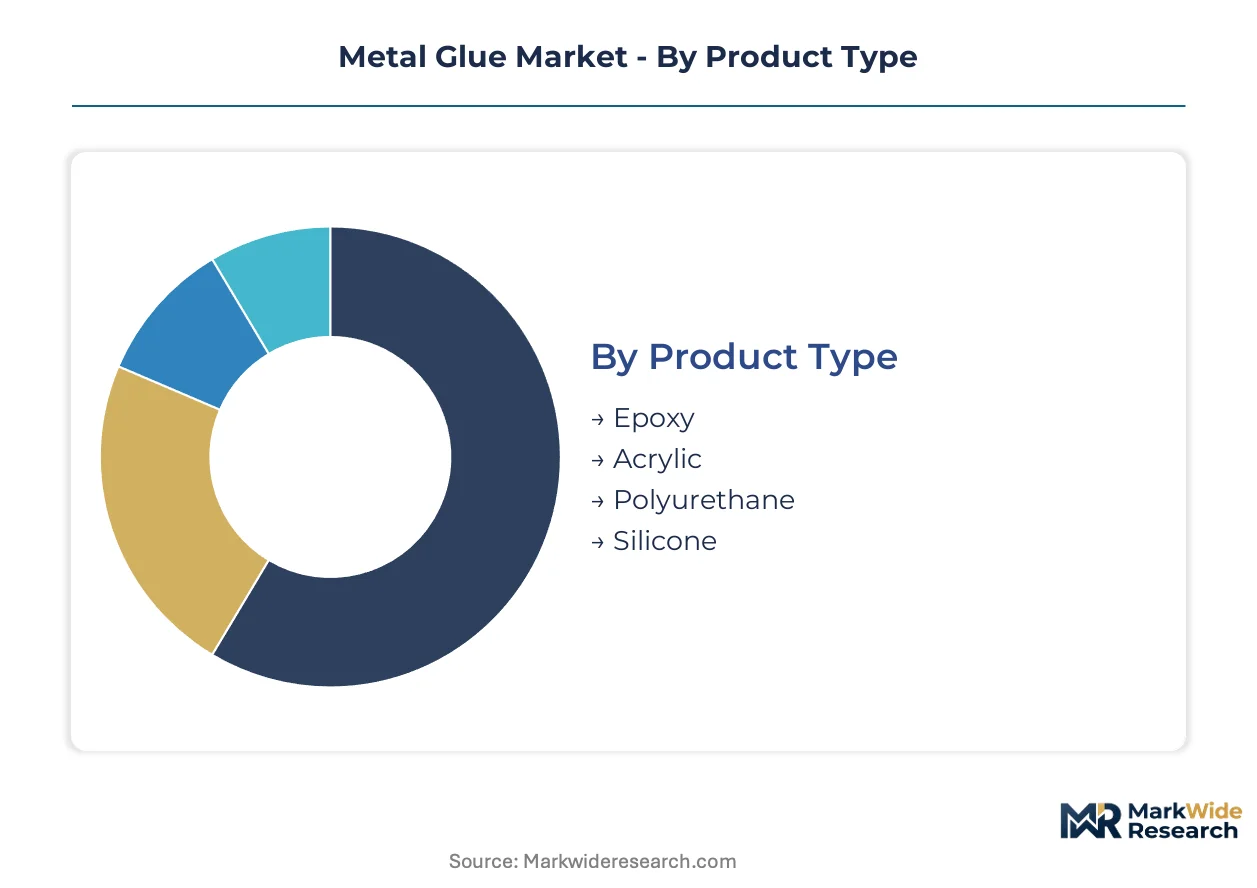
Segmentation in metal adhesives determines qualification pathways, cure equipment requirements, and margin structures across industrial supply chains. Chemistry selection and packaging format directly dictate surface preparation protocols and application throughput in automated assembly environments.
Product Type:
Capital intensity varies sharply across chemistries, with epoxy systems requiring the most substantial curing infrastructure investment.
- Epoxy:Two-part thermosetting formulations achieve shear strengths exceeding 20 MPa on etched aluminum surfaces. Automotive crash-structure bonding in Germany and China consumes the majority of toughened epoxy volume as OEMs phase out spot-welding in aluminum-intensive platforms.
- Acrylic:Methyl methacrylate systems cure rapidly through ambient moisture or induction acceleration. Wind turbine nacelle assembly in Denmark and marine fabrication yards are pulling acrylic adhesives into high-growth applications where gap-filling tolerance and fixture speed prove critical.
- Polyurethane:Flexible formulations dominate construction and transportation OEM specifications where vibration damping justifies premium positioning. Customized two-part systems require precise metering equipment but operate across wider temperature ranges than rigid alternatives.
- Silicone:RTV formulations serve secondary sealing and gasketing functions rather than primary structural loads. Electronics enclosure assembly and HVAC ductwork represent stable demand pockets with lower qualification barriers.
Epoxy absorbs the bulk of installed capacity; acrylic is expanding most quickly.
Application:
End-use concentration determines specification stringency and supplier consolidation patterns across industrial clusters.
- Automotive:Battery enclosure bonding for electric vehicle skateboard architectures demands crash-resistant formulations with 18-24 month qualification cycles. OEM captive supply agreements now mandate integrated adhesive-cure equipment packages from single-source qualified vendors.
- Aerospace:FAA and EASA certification requirements for structural adhesive systems create near-insurmountable barriers to new entrants. Boeing and Airbus specification lock-ins sustain multi-decade supplier relationships with specialized formulators.
- Electronics:Miniaturization trends favor low-viscosity dispensing systems for circuit board component attachment. Thermal management requirements in power electronics are driving ceramic-filled conductive adhesive adoption.
- Construction:Field-service compatibility with legacy repair protocols constrains formulation switching in structural steel and curtain wall applications. Infrastructure retrofit programs are opening specification windows for qualified structural bonding systems.
Automotive commands the greatest absolute volume; aerospace maintains the steepest margin premiums.
End User:
Procurement scale and technical sophistication fragment sharply across customer categories.
- Manufacturers:Tier-one integrators like Magna and Gestamp negotiate multi-year platform supply agreements with embedded process engineering support. Volume commitments justify dedicated formulation development and on-site technical service deployment.
- DIYers:Retail channel distribution favors pre-mixed syringe formats with simplified surface preparation instructions. E-commerce penetration in this segment lags professional channels due to hazmat shipping restrictions.
- Contractors:Construction equipment repair and infrastructure maintenance demand field-compatible packaging with extended working times. Regional distributor relationships determine brand loyalty more than formulation performance differentiation.
- Consumers:General-purpose metal bonding represents a commoditized segment where private-label capture concentrates in mass retail channels. Price sensitivity limits penetration of structural-grade formulations into this category.
Manufacturers anchor revenue concentration; contractors represent the most fragmented expansion opportunity.
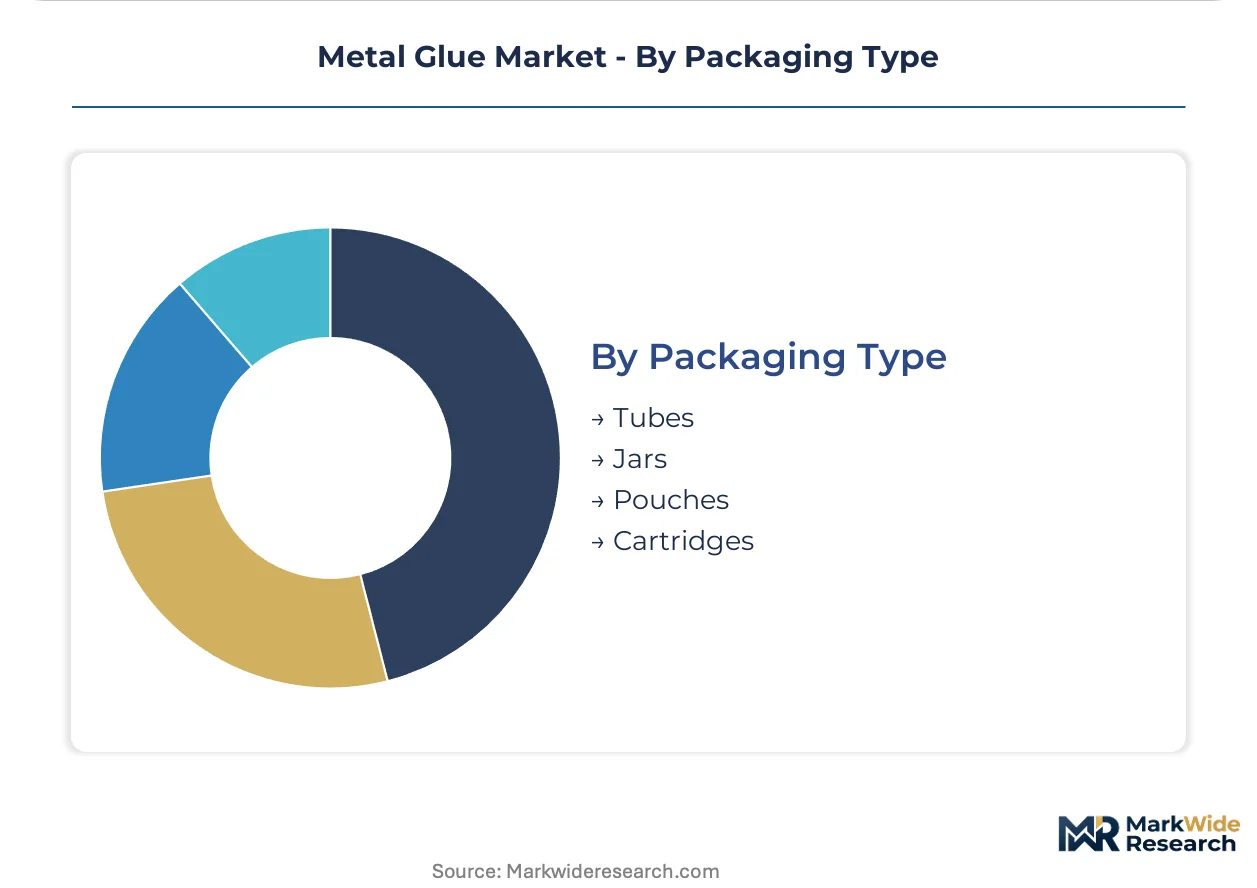
Packaging Type:
Format selection directly interfaces with automation compatibility and inventory carrying cost structures.
- Tubes:Collapsible aluminum or plastic tubes serve low-volume repair applications and field service kits. Squeeze-dispensing limitations restrict use to non-critical joints without precise bead control requirements.
- Jars:Bulk containers support brush or spatula application in maintenance workshops and small fabrication operations. Pot life management challenges limit jar formats to slow-cure systems with extended working windows.
- Pouches:Side-by-side barrier pouches enable precise ratio mixing for two-part systems without dedicated metering equipment. Wind turbine blade repair crews and marine technicians favor this format for remote site portability.
- Cartridges:Standardized coaxial and side-by-side cartridges integrate with pneumatic and battery-powered dispensing guns in automated assembly lines. Automotive body-in-white operations have standardized on 400ml and 600ml cartridge formats for robotic application.
Cartridges dominate industrial automation uptake; pouches are gaining share fastest in field-service segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene and benzene derivative production clusters in the US Gulf Coast, Germany's Rhine-Ruhr corridor, and China's Yangtze River Delta supply the epoxy and polyurethane precursors that dominate metal adhesive formulations. These feedstock localities anchor regional formulation capacity and dictate cross-border supply reliability for industrial bonding systems.
Germany
Automotive OEMs in Stuttgart and Munich are phasing out spot-welding in aluminum-intensive electric vehicle platforms, pulling structural epoxy volumes into crash-structure applications. ECHA's tightening REACH thresholds on isocyanates and heavy-metal catalysts are accelerating solvent-to-reactive adhesive conversions across Baden-Württemberg fabrication clusters. The Rhine-Ruhr industrial corridor hosts specialized induction curing equipment suppliers that bottleneck new adhesive line installations for tier-one integrators.
China
Wind turbine nacelle assembly in Jiangsu and Guangdong fabrication yards is consuming toughened epoxy systems for steel-to-composite load transfer joints in offshore installations. SAMR product safety frameworks and GB standards impose additional testing protocols for imported metal bonding systems entering industrial supply chains. The Yangtze River Delta concentration of battery enclosure manufacturers is qualifying crash-resistant methyl methacrylate formulations for aluminum-intensive skateboard architectures.
United States
EPA VOC emission standards under the Clean Air Act are forcing reformulation of solvent-borne primers and cleaners that precede structural adhesive application in Michigan and Ohio metal fabrication shops. Aerospace-grade adhesive qualification through FAA certification sustains multi-decade supplier relationships with specialized formulators in the Pacific Northwest and Southern California. The Southeast automotive corridor is consolidating approved supplier lists to single-source structural bonding systems per electric vehicle platform.
India
PLI scheme incentives for domestic manufacturing are opening specification windows for qualified adhesive suppliers in Tamil Nadu and Maharashtra railway and construction equipment sectors. BIS standards and DGFT import protocols create compliance layers for foreign formulation entrants targeting infrastructure retrofit programs. The Delhi-Mumbai Industrial Corridor is deepening metal bonding adoption in structural steel assembly for commercial and residential construction.
Japan
Industrial-scale induction and infrared curing system suppliers cluster in Nagoya and Osaka, creating equipment procurement bottlenecks for new adhesive line installations across Asia-Pacific. METI industrial standards and JIS certification requirements constrain formulation switching in precision machinery and electronics enclosure assembly. The Kanto region's concentration of tier-one automotive suppliers is mandating adhesive-cure equipment packages from qualified system houses for platform-scale programs.
Metal Glue Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty certification and regional qualification pathways to wedge into supply chains. The vendor base stratifies across three maturity tiers: multinational chemical conglomerates with captive raw material positions, mid-cap formulation specialists with OEM specification lock-ins, and regional distributors with field-service technical capabilities. Dominant competitive moves include backward integration into epoxy resin and polyurethane precursor production, plus strategic partnerships with induction curing equipment manufacturers to offer integrated bonding systems rather than standalone adhesives.
Within the multinational tier, Henkel AG & Co. KGaA and 3M Company exemplify archetypes of platform-scale suppliers with extensive OEM specification relationships. Sika AG occupies a position among European-focused specialists with construction and transportation OEM concentration. These three anchors represent distinct geographic and segment positioning strategies that shape competitive dynamics for qualification-dependent industrial bonding applications.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| Sika AG |
| H.B. Fuller Company |
| Arkema Group |
| LORD Corporation |
| BASF SE |
| Evonik Industries |
| Permabond LLC |
| Others |
Value Network & Pricing Analysis
Induction-cure accelerator integration in two-part structural acrylics is compressing fixture economics while concentrating procurement power among integrated system houses that bundle adhesive formulations with specialized curing equipment. This technology shift simultaneously elevates upfront capital requirements and locks in long-term supply relationships, reshaping how tier-one automotive suppliers negotiate total cost of ownership across aluminum-intensive vehicle platforms.
Pricing Analysis
Warranty and technical service bundling separates premium structural adhesive suppliers from commodity competitors in this market. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments, with automotive OEM captive agreements commanding the steepest discounts. Price differentiation hinges on crash-structure qualification status and embedded process engineering support. Pricing pressure stems from petrochemical feedstock volatility in epoxy resin precursors. DIY retail channels exhibit highest price sensitivity; aerospace-qualified suppliers maintain lowest.
Supply Chain Analysis
Qualification gating through OEM specification lock-ins restricts supply base concentration to Germany, China, and the United States for high-volume structural bonding systems. Raw material dependencies center on propylene and benzene derivatives for epoxy and polyurethane formulations, plus methyl methacrylate monomer for acrylic systems. Supply chain risk manifests in single-source vulnerability for industrial-scale induction curing equipment clustered in Germany and Japan. Distribution runs through qualified system houses that bundle adhesive-cure equipment packages for automotive body-in-white operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over epoxy resin and polyurethane precursor production determines margin defense capability against feedstock volatility.
For Market Incumbents: Acquire captive epoxy resin production capacity in the US Gulf Coast or Rhine-Ruhr corridor to hedge against propylene derivative cost swings. Lock in long-term supply agreements with induction curing equipment manufacturers in Nagoya and Osaka to secure bottlenecked production line components. Defend specification position by accelerating crash-structure qualification cycles ahead of emerging methyl methacrylate competitors. For New Entrants and Emerging Players: Begin with aftermarket structural bonding kits for collision repair and infrastructure maintenance, where OEM captive agreements do not block channel access. Target India's PLI scheme beneficiaries in Tamil Nadu railway equipment manufacturing, where qualified supplier lists remain open. Pursue field-service technical partnerships with regional construction distributors rather than direct OEM qualification. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by multinational chemical conglomerates seeking OEM specification lock-ins. Long-term viability favors mid-cap formulation specialists with established automotive platform relationships and backward integration into specialty resin production. Watch for inflection in SAMR enforcement intensity on imported metal bonding systems entering Chinese industrial supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Production | Captive precursor supply insulates Henkel and Sika from benzene derivative cost volatility in European automotive programs. |
| Induction Cure Equipment Partnership | Integrated system bundling locks tier-one suppliers into multi-year adhesive-cure equipment packages per vehicle platform. |
| Crash-Structure Qualification Acceleration | Compressed 18-24 month validation cycles strain supplier cash conversion but defend against acrylic adhesive substitution. |
| Aftermarket Channel Development | Collision repair and infrastructure retrofit kits bypass OEM captive supply agreements for volume expansion. |
| Regional Qualification in India | PLI scheme incentives in Tamil Nadu and Maharashtra open specification windows outside saturated German and Chinese clusters. |
Research Methodology
Trade databases, chemical industry association publications, and regulatory filing repositories formed the secondary backbone for demand modeling and competitive positioning assessment. Primary interviews with automotive platform engineers, Tier 1 supplier procurement leads, adhesive formulation R&D directors, and induction curing equipment manufacturers validated volume assumptions and qualification timeline estimates. Bottom-up and top-down triangulation reconciled plant-level production data with end-use consumption patterns across automotive, aerospace, and wind turbine fabrication clusters.
Bottom-up modeling anchored volume projections to qualified adhesive consumption per vehicle platform, turbine nacelle, and aircraft assembly program across the projection horizon. Segmentation dimensions included chemistry type, application end-use, packaging format, and regional production hub concentration. CAGRs were derived from fitted growth curves calibrated to historical qualification cycle compression and electric vehicle platform rollout trajectories. Feedstock cost indices and OEM specification consolidation patterns served as industry-specific forecast inputs.
Feedstock price volatility, regulatory threshold tightening on isocyanates and heavy-metal catalysts, and OEM single-source consolidation decisions are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding qualification timeline stability and equipment supplier capacity expansion. A model refresh is warranted upon material change in ECHA REACH enforcement intensity or SAMR product safety framework implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Urethane Adhesives Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
Hot Glue Guns Market
Adhesives & Sealants
Die Cut Adhesive Market
Adhesives & Sealants
Co-Polymer Sealants Market
Adhesives & Sealants
Brazil Adhesives Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market
Adhesives & Sealants
American Epoxy Adhesives Market
Adhesives & Sealants
Marine Adhesives Market
Adhesives & Sealants
Soft Skin Adhesives Market
Adhesives & Sealants
Europe Adhesives Market
Adhesives & Sealants
De-Seamable Adhesives Market
Adhesives & Sealants
Central Reinforced Tape Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
United Kingdom Hot-Melt Adhesives Market